
 MRI Compatible Patient Monitoring Systems Market | 2026-2036
MRI Compatible Patient Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
MRI Compatible Patient Monitoring Systems Market Foresight
The capital-intensity gap between established imaging OEMs and specialized monitoring firms is collapsing. GE Healthcare leverages its installed base of MRI scanners to bundle compatible monitoring ecosystems. iRadimed Corporation sustains its niche through dedicated non-magnetic infusion and monitoring systems purpose-built for high-field environments. Philips Healthcare competes by integrating patient monitoring with its broader diagnostic imaging portfolio.
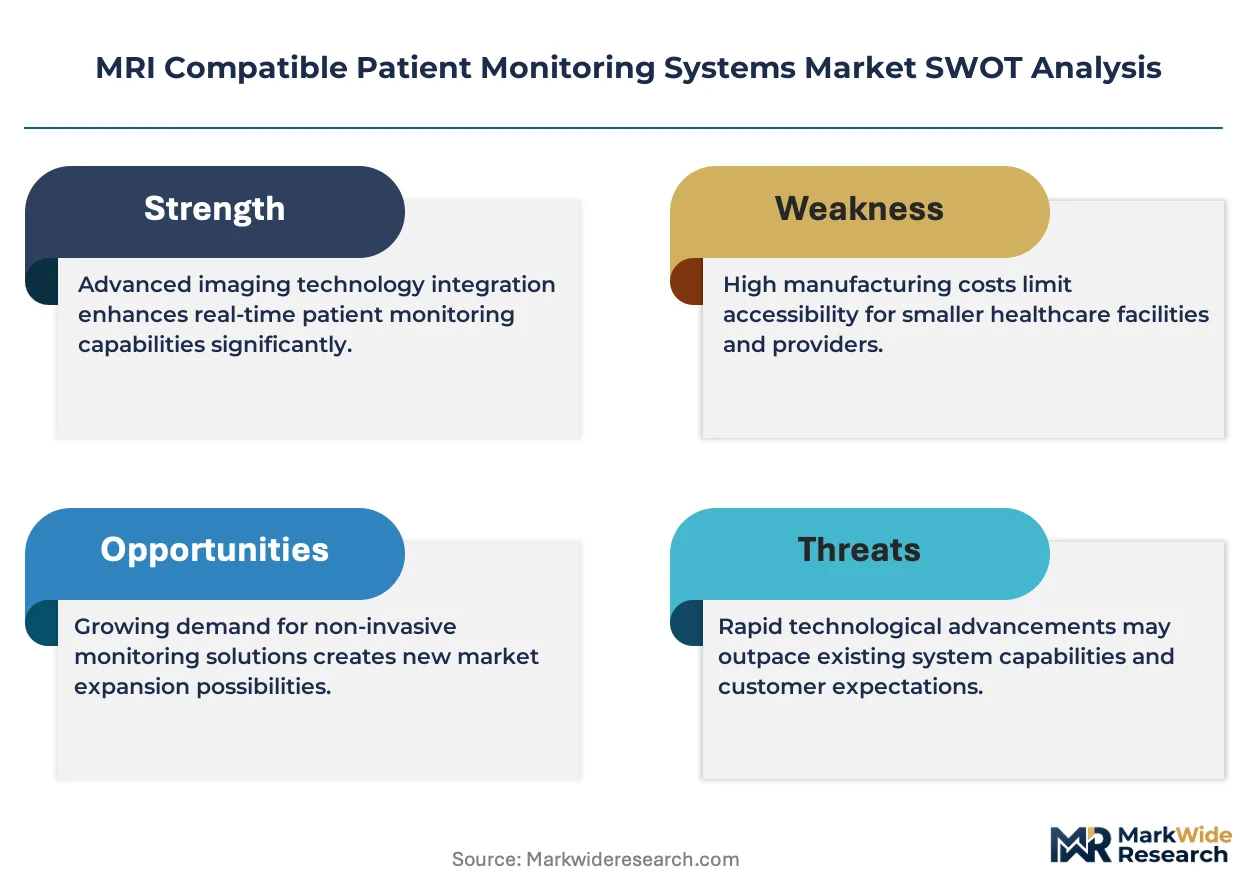
MRI compatible patient monitoring systems incorporate non-ferromagnetic components, fiber-optic signal transmission, and radiofrequency shielding to operate safely within static magnetic fields exceeding 1.5 Tesla and 3 Tesla configurations; these systems enable continuous vital sign tracking during interventional and diagnostic MRI procedures without image artifact generation. Monitors dominate product-level revenue due to replacement cycles tied to MRI suite upgrades, while wireless technology segments attract capital as hospitals pursue cable-free workflows that reduce patient setup time and improve throughput in busy radiology departments. Sensors represent a concentrated margin pool where specialized pressure transducers and pulse oximetry probes command premium pricing for MRI-conditional certification.
The FDA enforces 510(k) premarket notification for MRI-conditional devices under electromagnetic compatibility standards, while the EU Medical Device Regulation requires notified body review for active implantable and monitoring equipment marketed in Europe. ISO 13485 quality management and IEC 60601-1-2 electromagnetic compatibility standards shape design verification protocols for manufacturers seeking multi-region approval. Stakeholders must weigh the pace of ultra-high-field MRI adoption against the certification burden of proving conditional safety at 7 Tesla and above.
Market Dynamics
The convergence of ultra-high-field MRI adoption above 7 Tesla with wireless monitoring architectures is compressing product refresh cycles and forcing incumbent suppliers to recertify entire device portfolios under stricter electromagnetic compatibility protocols.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:The streamlined premarket notification process for MRI-conditional devices under electromagnetic compatibility standards reduces time-to-market for monitoring manufacturers targeting neurosurgical navigation suites.
- Intraoperative MRI Expansion:Academic medical centers in the United States are retrofitting surgical theaters with real-time imaging capabilities, creating pull-through demand for compatible vital sign tracking systems.
- Fiber-Optic Signal Transmission:This non-magnetic data architecture eliminates radiofrequency interference artifacts, enabling continuous patient surveillance during high-field diagnostic procedures without image degradation.
Market Restraints
- Non-Ferromagnetic Material Costs:Specialized alloys and composite housings required for 3 Tesla+ safety certification carry 40-60% premiums over standard monitoring enclosures, compressing gross margins for mid-tier suppliers.
- Notified Body Bottlenecks:EU Medical Device Regulation review timelines for active implantable monitoring equipment extend 18-24 months, delaying European market entry for new product generations.
- Electromagnetic Shielding Complexity:Radiofrequency enclosure engineering for 7 Tesla environments demands specialized simulation capabilities scarce outside established imaging OEMs.
Strategic Opportunities
- 7 Tesla Safety Certification:First-movers proving conditional device safety at ultra-high-field strengths capture premium positioning in research-focused university hospital networks.
- India Diagnostic Imaging Expansion:Private hospital chains in Mumbai and Delhi are installing 1.5 Tesla suites faster than regulatory frameworks mature, creating early-mover advantage for compliant monitoring suppliers.
- Wireless Workflow Integration:Cable-free patient setup architectures reduce radiology department throughput bottlenecks, aligning with hospital operational efficiency mandates.
Industry Challenges
- ISO 13485 Quality Management Talent:Medical device quality engineering expertise for multi-region approval pathways concentrates in Boston, Minneapolis, and Stuttgart, creating recruitment competition.
- IEC 60601-1-2 Verification Timelines:Electromagnetic immunity testing for simultaneous 1.5 Tesla and 3 Tesla compatibility extends design validation phases by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRI Compatible Patient Monitoring Systems Market |
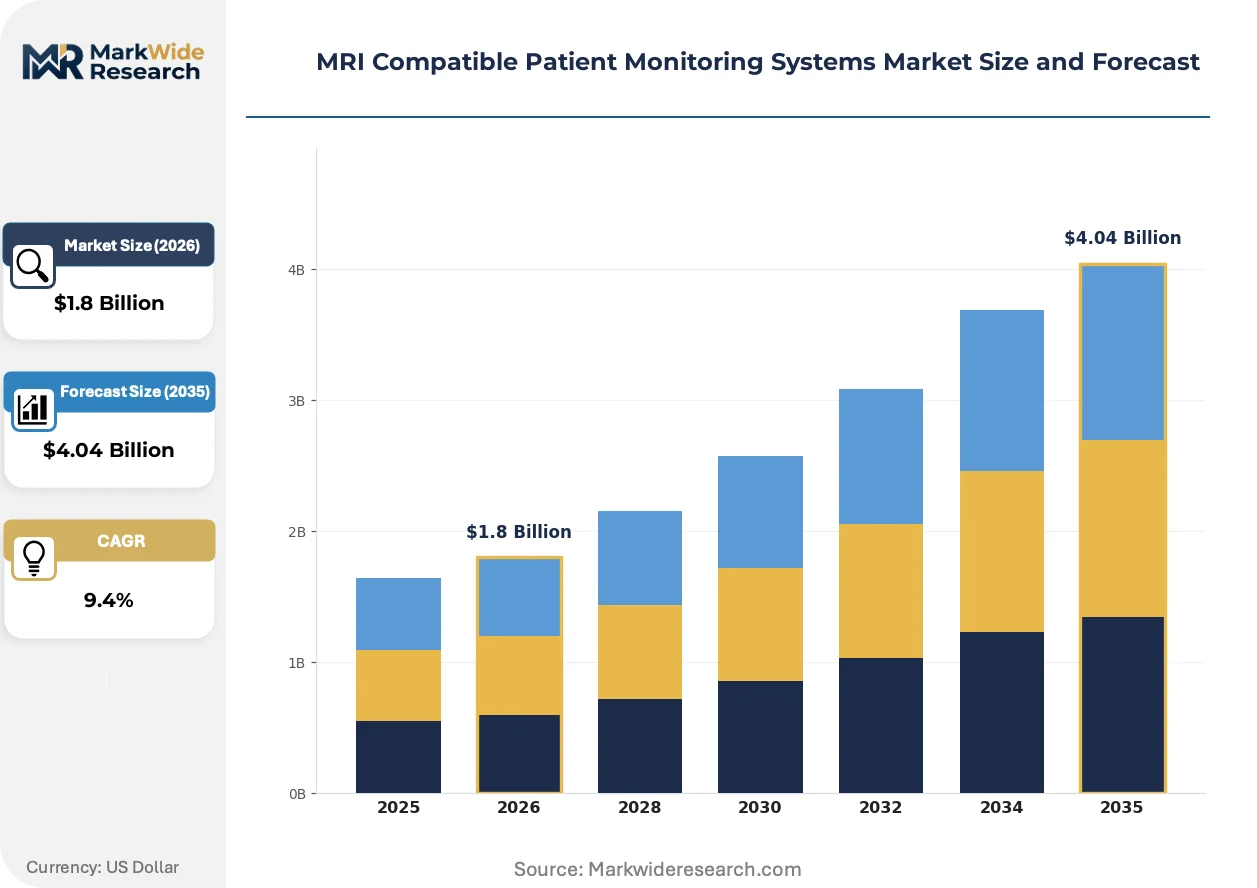
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitors, Sensors, Alarm Systems, Software End User: Hospitals, Imaging Centers, Clinics, Emergency Services Technology: Wireless, Real-time, Portable, Fixed Application: Neurosurgery, Cardiology, Emergency Care, Radiology |
| Companies Covered | GE Healthcare, iRadimed Corporation, Philips Healthcare, Siemens Healthineers, Drägerwerk AG & Co. KGaA, B. Braun Melsungen AG, Fresenius SE & Co. KGaA, Schwarzer Cardiotek GmbH, Arcomed AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRI Compatible Patient Monitoring Systems Market Shifts & Advancements
Wireless patient monitoring architectures are displacing fiber-tethered systems as the dominant connectivity paradigm, while regulatory convergence between FDA electromagnetic compatibility standards and EU MDR technical documentation requirements is reshaping certification economics.
Photoplethysmography sensors with integrated motion artifact rejection are displacing traditional pulse oximetry probes in high-field environments. Academic medical centers in Germany and Japan are deploying these solid-state devices during cardiac MRI procedures. The technology is displacing legacy fiber-optic transducers by eliminating cable management constraints and reducing patient setup time.
The EU Medical Device Regulation's enhanced technical documentation requirements for active implantable equipment are compressing product lifecycle planning. Manufacturers must now submit clinical evaluation reports and post-market surveillance protocols that exceed FDA 510(k) stringency. European notified bodies are prioritizing MRI-conditional monitoring submissions, creating queue advantages for early filers.
Hospital procurement committees are unbundling monitoring hardware from scanner OEM service contracts. Independent radiology groups in Texas and Florida are sourcing third-party compatible devices through group purchasing organizations. This pattern concentrates in outpatient imaging centers seeking operational flexibility outside manufacturer-captive ecosystems.
MRI Compatible Patient Monitoring Systems Market Segmentation
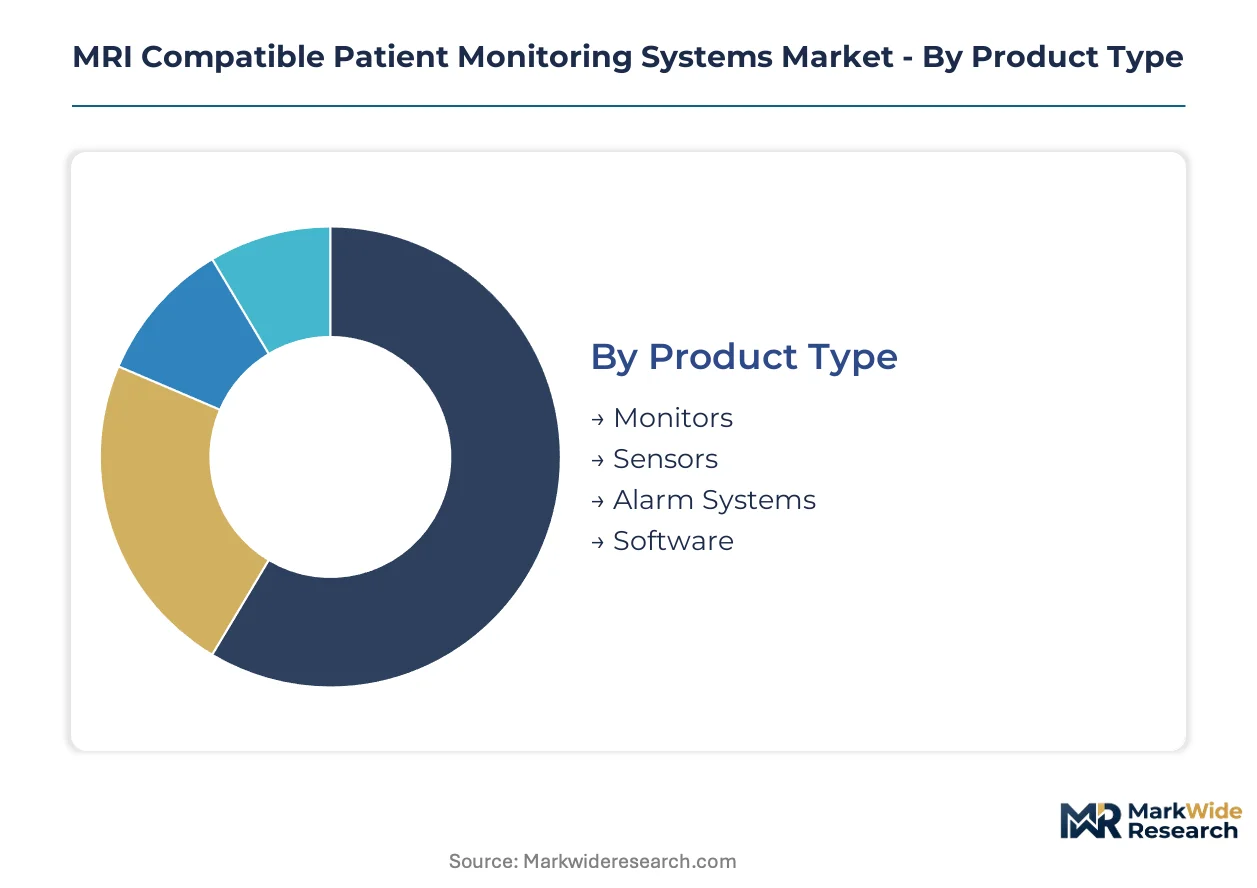
Segmentation in MRI compatible patient monitoring systems reveals how regulatory certification tiers, magnetic field compatibility ratings, and end-use workflow requirements create distinct commercial battlegrounds. Product-level differentiation concentrates where FDA 510(k) pathways intersect with hospital procurement committee priorities.
Product Type:
FDA electromagnetic compatibility standards stratify product categories by certification burden and replacement cycle velocity, with 510(k) clearance timelines varying substantially across hardware versus software submissions.
- Monitors:Non-ferromagnetic chassis designs incorporating fiber-optic signal transmission and radiofrequency shielding dominate hospital procurement for 1.5 Tesla and 3 Tesla suites. Academic medical centers in the United States drive replacement demand tied to MRI suite upgrade cycles, with procurement committees prioritizing IEC 60601-1-2 verification documentation.
- Sensors:Specialized pressure transducers and pulse oximetry probes command premium positioning through MRI-conditional certification at high-field strengths. Photoplethysmography variants with motion artifact rejection are displacing legacy fiber-optic transducers in German and Japanese cardiac MRI procedures.
- Alarm Systems:Audible and visual alert mechanisms engineered for high-field environments with electromagnetic immunity testing per FDA standards.
- Software:Data aggregation platforms for multi-parameter vital sign visualization with post-market surveillance protocols under EU MDR technical documentation requirements.
Established volume favors Monitors; emerging adoption favors Sensors.
End User:
Capital expenditure thresholds and operational workflow complexity separate institutional buyers, with intraoperative MRI adoption patterns concentrating demand in integrated delivery networks versus independent imaging operators.
- Hospitals:Academic medical centers and tertiary care facilities retrofitting surgical theaters with real-time imaging capabilities generate pull-through demand for compatible vital sign tracking. Intraoperative MRI suite expansion in United States university hospital networks prioritizes 7 Tesla safety certification for research applications.
- Imaging Centers:Independent radiology groups in Texas and Florida source third-party compatible devices through group purchasing organizations, unbundling hardware from scanner OEM service contracts.
- Clinics:Outpatient facilities with limited 1.5 Tesla suite deployments seeking operational flexibility outside manufacturer-captive ecosystems.
- Emergency Services:Mobile MRI units and field-deployable monitoring requiring portable electromagnetic compatibility configurations.
Procurement concentration favors Hospitals; operational flexibility demand favors Imaging Centers.
Technology:
Connectivity architecture determines setup time, throughput capacity, and electromagnetic interference profile, with wireless implementations displacing tethered systems in radiology department efficiency mandates.
- Wireless:Cable-free patient setup architectures reduce radiology department throughput bottlenecks and eliminate radiofrequency interference artifacts. Hospital operational efficiency mandates in busy diagnostic departments accelerate capital allocation toward Bluetooth and proprietary radio protocols with integrated motion artifact rejection.
- Real-time:Continuous vital sign streaming during interventional procedures with latency requirements for neurosurgical navigation.
- Portable:Battery-powered configurations for intraoperative transport and emergency MRI suite deployment.
- Fixed:Hardwired installations in dedicated high-field suites with permanent electromagnetic shielding infrastructure.
Capital deployment favors Wireless; specialized application demand favors Fixed.
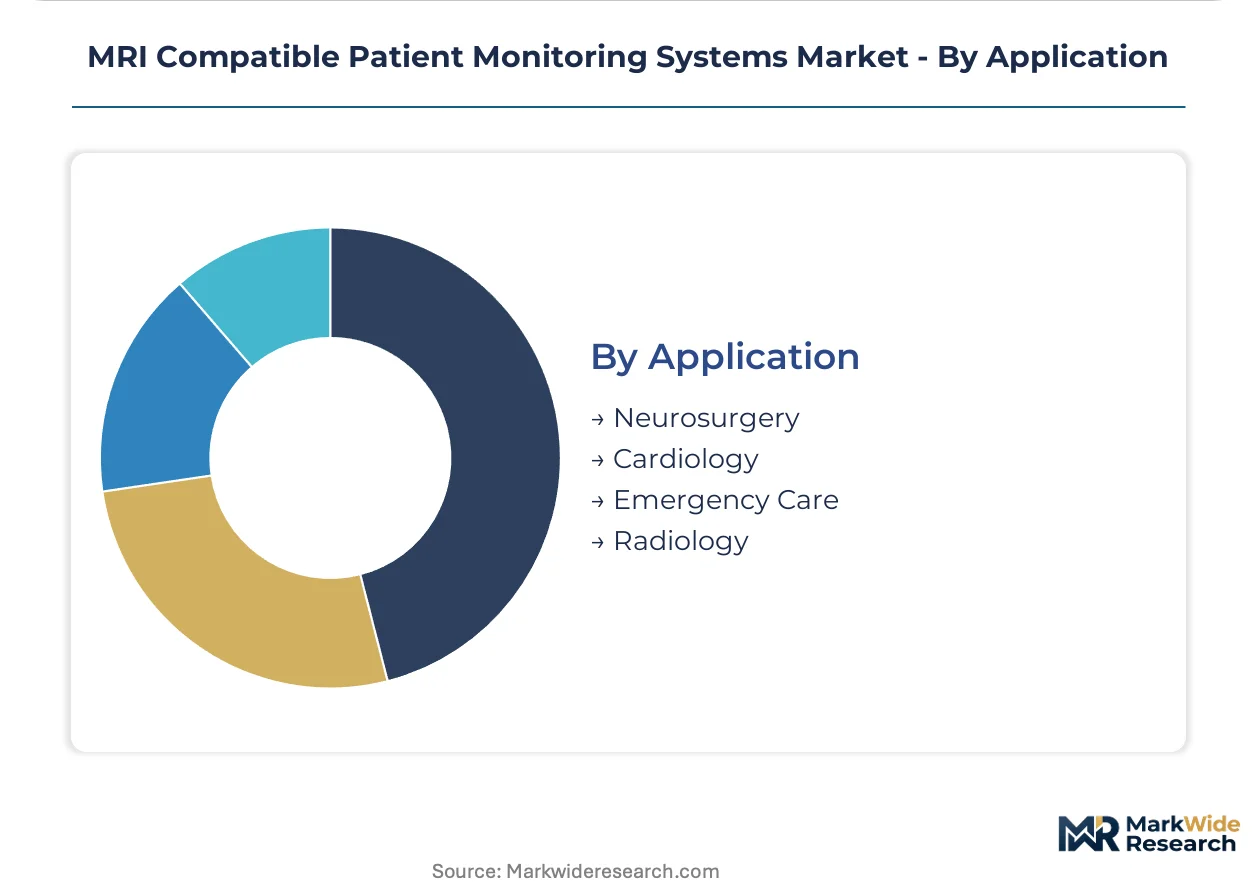
Application:
Clinical use case determines magnetic field strength requirements, patient positioning constraints, and monitoring parameter priority, with neurosurgical navigation demanding the most stringent electromagnetic compatibility verification.
- Neurosurgery:Intraoperative MRI navigation requires continuous vital sign surveillance during awake craniotomy and tumor resection procedures. Real-time imaging capabilities in United States academic medical centers create demand for 7 Tesla conditional safety certification and fiber-optic signal transmission without image degradation.
- Cardiology:Cardiac MRI procedures in Germany and Japan deploy photoplethysmography sensors with solid-state designs eliminating cable management constraints.
- Emergency Care:Trauma and stroke protocol monitoring requiring rapid patient setup in mixed-field environments.
- Radiology:Routine diagnostic imaging with standardized 1.5 Tesla and 3 Tesla compatibility requirements.
Certification stringency concentrates in Neurosurgery; volume throughput concentrates in Radiology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Academic medical centers in the United States absorb premium pricing for 7 Tesla certification, while private hospital chains in India prioritize cost-efficient 1.5 Tesla compatibility. European procurement committees weigh total lifecycle costs against stringent EU MDR compliance timelines.
United States
Academic medical centers in Boston and Minneapolis drive replacement cycles tied to intraoperative MRI suite expansion. FDA 510(k) premarket notification pathways accelerate product entry for electromagnetic compatibility standards. The Mayo Clinic and Cleveland Clinic anchor demand for fiber-optic monitoring architectures in neurosurgical navigation.
Germany
Cardiac MRI procedures in Munich and Heidelberg deploy photoplethysmography sensors with motion artifact rejection. EU Medical Device Regulation notified body review concentrates in Stuttgart and Berlin, extending 18-24 month timelines for active implantable monitoring equipment. Siemens Healthineers anchors the Baden-Württemberg imaging cluster.
Japan
University hospital networks in Tokyo and Osaka pursue 7 Tesla safety certification for research applications. METI industrial standards shape electromagnetic shielding requirements for ultra-high-field environments. The Kanto region concentrates photoplethysmography sensor adoption during cardiac MRI procedures.
India
Private hospital chains in Mumbai and Delhi install 1.5 Tesla suites faster than CDSCO regulatory frameworks mature. BIS certification timelines lag behind capital deployment, creating early-mover advantage for compliant monitoring suppliers. Maharashtra and Karnataka anchor diagnostic imaging expansion.
United Kingdom
NHS procurement committees unbundle monitoring hardware from scanner OEM service contracts. MHRA post-Brexit regulatory pathways diverge from EU MDR, extending technical documentation requirements for active implantable equipment. London and Manchester radiology departments prioritize wireless workflow integration.
MRI Compatible Patient Monitoring Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier. GE Healthcare, Philips Healthcare, and Siemens Healthineers leverage installed MRI scanner bases to bundle compatible monitoring ecosystems. Mid-tier specialists compete on dedicated non-magnetic architectures for high-field environments. Dominant competitive moves include portfolio diversification into wireless connectivity and strategic partnerships with academic medical centers for 7 Tesla certification co-development.
Among imaging OEMs with captive monitoring portfolios, GE Healthcare and Philips Healthcare exemplify the integrated-leader archetype. iRadimed Corporation occupies a distinct position within the specialist tier, representing dedicated non-magnetic infusion and monitoring system fabrication. Drägerwerk AG & Co. KGaA anchors German-engineered life support equipment integration into MRI-conditional workflows.
| Leading Market Players |
|---|
| GE Healthcare |
| iRadimed Corporation |
| Philips Healthcare |
| Siemens Healthineers |
| Drägerwerk AG & Co. KGaA |
| B. Braun Melsungen AG |
| Fresenius SE & Co. KGaA |
| Schwarzer Cardiotek GmbH |
| Arcomed AG |
| Others |
Supply & Pricing Matrix
Long-term service contracts with MRI scanner OEMs lock in both supply access and price visibility for hospital procurement committees, bundling monitoring hardware with multi-year maintenance agreements that smooth capital expenditure recognition across fiscal planning cycles. These arrangements concentrate pricing power with integrated manufacturers while forcing mid-tier specialists to compete on unbundled component sales with compressed margins.
Pricing Analysis
After-sales service revenue drives lifetime value in MRI-compatible monitoring, with preventive maintenance contracts and sensor replacement programs generating recurring income that exceeds initial hardware margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by magnetic field certification, with 7 Tesla conditional devices commanding substantial premiums over 1.5 Tesla baseline configurations. Cost compression in mid-tier sensor categories is intensifying because photoplethysmography solid-state designs are displacing legacy fiber-optic transducers. Academic medical centers in the United States exhibit lowest price sensitivity due to research funding flexibility, while independent imaging centers in Texas and Florida prioritize operational flexibility over premium certification tiers.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time delivery for non-ferromagnetic alloy components sourced from German and Japanese specialty metal suppliers. Manufacturing concentration centers on Baden-Württemberg for electromagnetic shielding enclosures, Massachusetts for fiber-optic signal transmission assemblies, and Osaka for photoplethysmography sensor fabrication. Supply chains draw from rare earth processing facilities in China for specialized magnetic shielding materials, precision optical fiber from Corning's North Carolina operations, and medical-grade silicone for patient interfaces from Wacker Chemie in Bavaria. Single-source vulnerability in 7 Tesla RF coil subassemblies creates procurement risk for research-focused university hospital networks. Distribution runs through group purchasing organizations for hospital systems and direct OEM relationships for academic medical center procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against wireless consumer-grade monitoring devices encroaching on low-acuity diagnostic applications, as Bluetooth-enabled wearables threaten to commoditize basic vital sign tracking outside interventional MRI workflows.
For Market Incumbents: Consolidate certification capabilities by acquiring specialized notified body relationships in Stuttgart and Berlin to compress EU MDR review timelines from 24 months toward 12-month benchmarks. Integrate backward into non-ferromagnetic alloy supply through captive agreements with German specialty metal producers, defending against input cost volatility that compresses gross margins on 3 Tesla+ enclosures. This counters emerging entrants from Asia-Pacific with government-subsidized material costs.
For New Entrants and Emerging Players: Differentiate on 7 Tesla safety certification co-development partnerships with university hospital networks in Tokyo and Boston, where research funding absorbs premium positioning without procurement committee price sensitivity. Target India's private hospital chains in Maharashtra and Karnataka before CDSCO regulatory frameworks mature, establishing installed base ahead of compliance requirements. Deploy direct sales teams to radiology department heads rather than competing through established GPO contracts.
For Investors and Strategic Acquirers: Niche specialists with dedicated non-magnetic architectures and FDA 510(k) clearance velocity represent the most defensible acquisition profile, particularly those with photoplethysmography sensor portfolios displacing legacy fiber-optic designs. Long-term viability hinges on wireless workflow integration capabilities and electromagnetic compatibility testing infrastructure that 7 Tesla adoption renders essential rather than optional. Monitor FDA 510(k) submission volumes for MRI-conditional devices as inflection indicator for competitive intensity and pricing pressure direction.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Streamlined electromagnetic compatibility review reduces time-to-market for neurosurgical navigation suite suppliers. |
| 7 Tesla Safety Certification | First-movers capture premium positioning in research-focused university hospital networks in Boston and Tokyo. |
| Wireless Workflow Integration | Cable-free architectures align with hospital operational efficiency mandates in busy radiology departments. |
| Hospital System Partnership | Unbundling from scanner OEM service contracts creates procurement flexibility for independent imaging centers. |
| Photoplethysmography Sensor Development | Solid-state designs eliminate cable management constraints during cardiac MRI procedures in Germany and Japan. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at MRI-conditional device manufacturers; and secondary validation against FDA 510(k) clearance databases, EU MDR notified body submission records, hospital procurement databases, and CMS Medicare reimbursement filings. Bottom-up triangulation across product-level unit economics and top-down validation against scanner OEM service contract disclosures anchored market sizing.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by magnetic field compatibility rating, end-user procurement archetype, connectivity architecture, and regional regulatory cluster. CAGRs were derived from replacement cycle velocity tied to MRI suite upgrade timelines and penetration assumptions for wireless versus fiber-tethered installations. Forecast inputs incorporated notified body queue lengths for EU MDR compliance, academic medical center capital expenditure cycles, and photoplethysmography sensor adoption curves in cardiac MRI procedures.
Material uncertainties — regulatory timeline delays at European notified bodies, tariff exposure on rare earth magnetic shielding materials, and accelerated 7 Tesla adoption ahead of conditional safety certification — sit outside the modeled envelope. Forecasts reflect assumptions about electromagnetic compatibility standard convergence and hospital procurement unbundling velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Germany Patient Monitoring Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
Patient Monitoring Systems Market
Patient Monitoring
Urine Monitoring Systems Market
Patient Monitoring
Patient Monitoring Devices Market
Patient Monitoring
Europe Biomedical Sensors Market
Patient Monitoring
South America Remote Patient Monitoring Systems Market
Patient Monitoring
Transcutaneous Monitors Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market
Patient Monitoring
France Patient Monitoring Market
Patient Monitoring
Patient Scales Market
Patient Monitoring
Patient Monitoring Pods Market
Patient Monitoring
China ICU Patient Monitor Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
United States Patient Monitoring Market