
 Global Blood Pressure Monitoring Devices Market | 2026-2036
Global Blood Pressure Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Pressure Monitoring Devices Market Foresight
Connected sensor integration and cloud-based data architecture is reshaping how blood pressure monitoring devices are designed, manufactured, and distributed across care pathways. Omron Healthcare leverages its deep vertical integration in oscillometric sensor production to sustain manufacturing scale across Asian and North American assembly networks. Philips Healthcare anchors its competitive stance through hospital-grade telemetry systems that extend into remote patient monitoring workflows.
Blood pressure monitoring devices are electromechanical instruments that measure arterial pressure through inflatable cuff systems coupled with pressure transducers, typically operating within measurement ranges of 0-300 mmHg and accuracy tolerances of ±3 mmHg per international standards. Their primary commercial purpose spans chronic disease management, acute care surveillance, and preventive cardiovascular screening across clinical and non-clinical environments. The automatic product category dominates unit shipments due to ease of use among elderly populations and untrained home users, while ambulatory systems command premium positioning in diagnostic laboratories where 24-hour circadian profiling drives clinical reimbursement. Remote patient monitoring applications are expanding fastest as telehealth providers integrate oscillometric and photoplethysmography-based wearables into subscription care models.
The FDA regulates these devices as Class II medical products under 510(k) premarket notification pathways, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for software-enabled connected monitors seeking CE marking. China's NMPA has accelerated review timelines for home-use automatic devices aligned with national hypertension screening initiatives. Stakeholders must monitor how divergent cybersecurity standards across FDA, EMA, and NMPA jurisdictions reshape development roadmaps for cloud-connected devices.
Market Dynamics
The convergence of photoplethysmography with oscillometric sensing is compressing form factors and enabling cuffless measurement architectures that bypass traditional inflatable systems entirely. This sensor fusion is redrawing competitive boundaries between consumer electronics and medical device manufacturers.
Growth Catalysts
- Hypertension screening mandates:China's NMPA has streamlined approval pathways for home-use automatic monitors aligned with national cardiovascular prevention programs, accelerating household penetration in tier-1 and tier-2 cities.
- Telehealth reimbursement expansion:Remote patient monitoring codes in the United States now cover oscillometric data transmission for chronic care management, pulling device procurement into subscription-based care models.
- MEMS pressure transducer miniaturization:Advances in microelectromechanical fabrication are reducing bill-of-materials costs for wearable form factors, enabling sub-$50 retail price points in direct-to-consumer channels.
Market Restraints
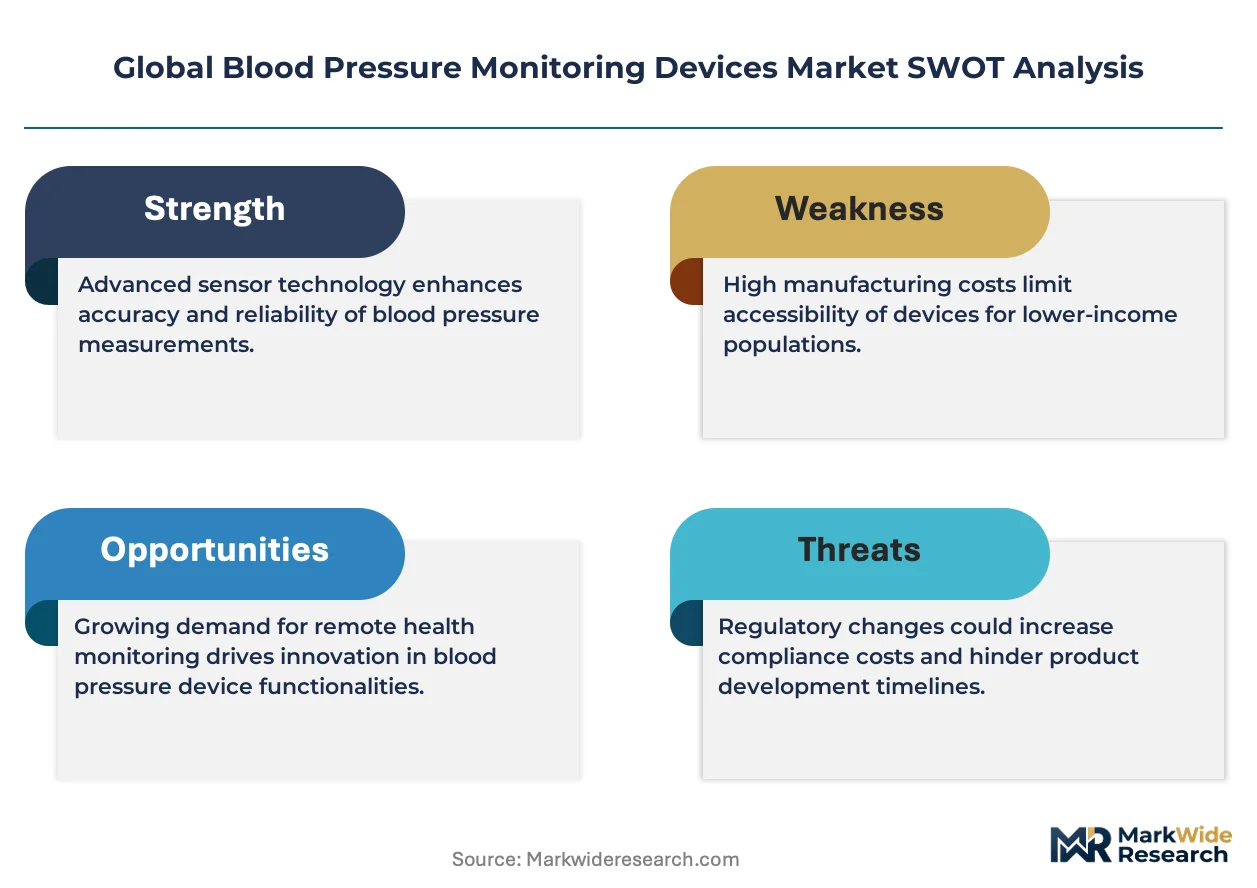
- Sensor calibration drift:Photoplethysmography-based wearables require frequent recalibration against oscillometric baselines, limiting clinical acceptance in diagnostic workflows where traceability to ISO 81060-2 standards is mandatory.
- Semiconductor supply concentration:Analog front-end integrated circuits for pressure signal conditioning concentrate in Taiwanese and South Korean foundry capacity, exposing manufacturers to geopolitical disruption risks.
- Regulatory fragmentation:Divergent cybersecurity requirements between FDA 510(k) pathways and EU MDR Annex I technical documentation are extending development timelines by 8-14 months for cloud-connected devices.
Strategic Opportunities
- Rural India penetration:Community health worker programs under India's National Health Mission create demand for sub-$20 automatic upper-arm units with Hindi-language interfaces and solar charging compatibility.
- AI-enabled arrhythmia detection:Integration of atrial fibrillation screening algorithms into oscillometric cycles opens reimbursement pathways in German statutory health insurance preventive care frameworks.
- Pharmacy channel integration:CVS Health and Walgreens in the United States are deploying connected monitor kiosks with automatic data transmission to electronic health records, capturing medication-adherence touchpoints.
Industry Challenges
- Firmware validation bottlenecks:FDA's evolving software-as-a-medical-device guidance requires exhaustive verification of over-the-air update mechanisms, stretching quality engineering headcount at mid-tier manufacturers.
- Legacy hospital telemetry incompatibility:Proprietary data protocols from 1990s-era bedside monitors resist integration with cloud-native remote monitoring platforms, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Pressure Monitoring Devices Market |
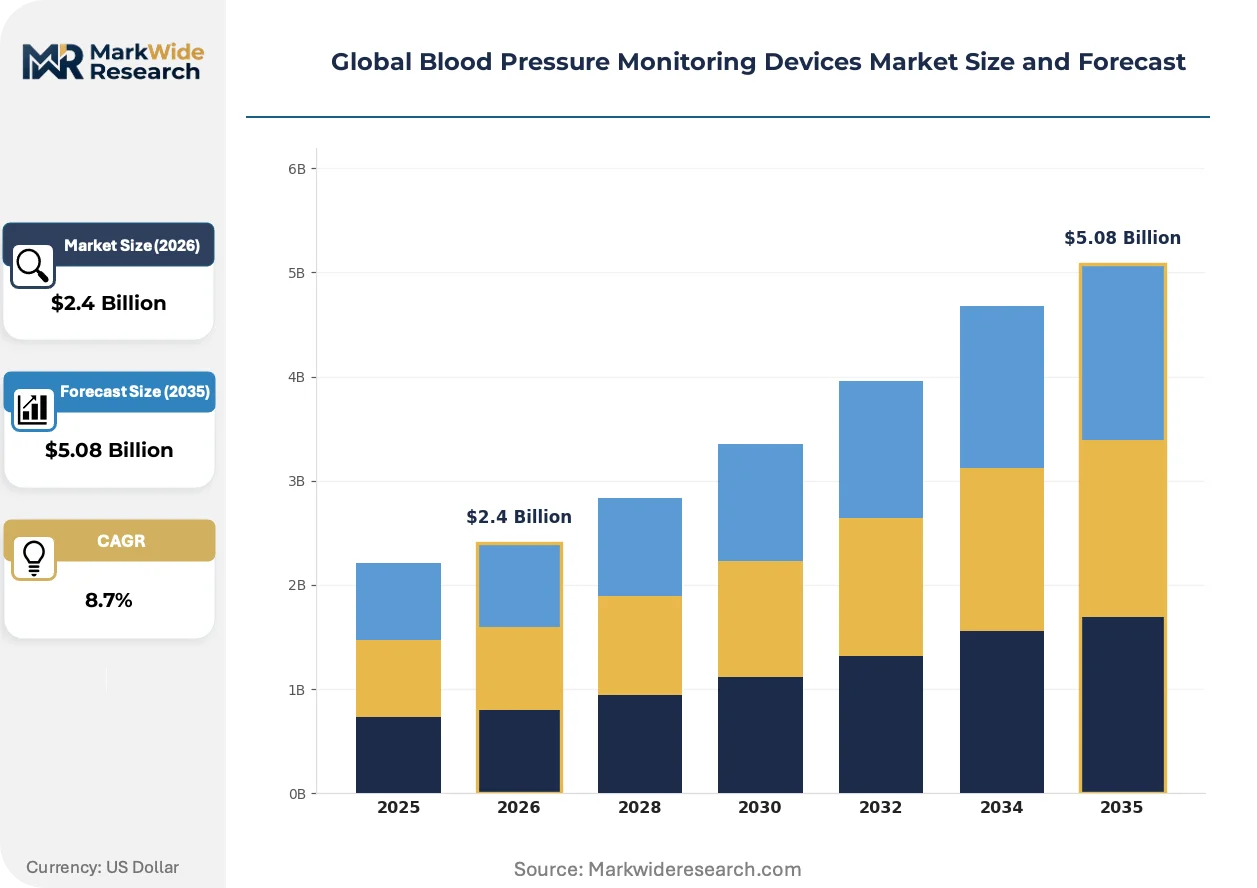
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Ambulatory, Wrist, Finger Technology: Oscillometric, Auscultatory, Volume Clamp, Tonometry, Photoplethysmography Application: Home Care, Clinical Diagnostics, Remote Patient Monitoring, Sports Medicine, Occupational Health End User: Primary Care Physicians, Diagnostic Laboratories, Nursing Homes, Pharmacies, Telehealth Providers |
| Companies Covered | Omron Healthcare, GE Healthcare, Philips Healthcare, Welch Allyn, A&D Medical, Withings, SunTech Medical, Spacelabs Healthcare, Rossmax International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Pressure Monitoring Devices Market Shifts & Advancements
Measurement modalities are fragmenting as cuff-based oscillometry faces displacement from optical and acoustic alternatives, while data architectures shift from episodic capture to continuous streaming models.
Photoplethysmography is migrating from fitness-tracking accessories into clinically validated blood pressure estimation systems. Consumer electronics manufacturers in Shenzhen and Cupertino are embedding multi-wavelength LED arrays into wrist-worn form factors. This technology is migrating from wellness positioning toward FDA-cleared medical claims by adding accelerometer-based motion artifact rejection and machine learning calibration against oscillometric baselines.
EU MDR clinical evidence requirements for software-enabled devices are tightening post-market surveillance obligations for connected monitors. Manufacturers must now submit periodic safety update reports with real-world performance data from cloud-connected installed bases. Ambulatory blood pressure monitoring systems seeking CE marking face expanded clinical investigation requirements that favor established players with European notified body relationships.
Pharmacy retailers are unbundling device procurement from clinical interpretation services. Walgreens and CVS in the United States now offer subscription models where hardware is subsidized in exchange for monthly data analytics fees. This restructuring concentrates buyer power among three national pharmacy chains while fragmenting end-user relationships across thousands of independent primary care practices.
Global Blood Pressure Monitoring Devices Market Segmentation
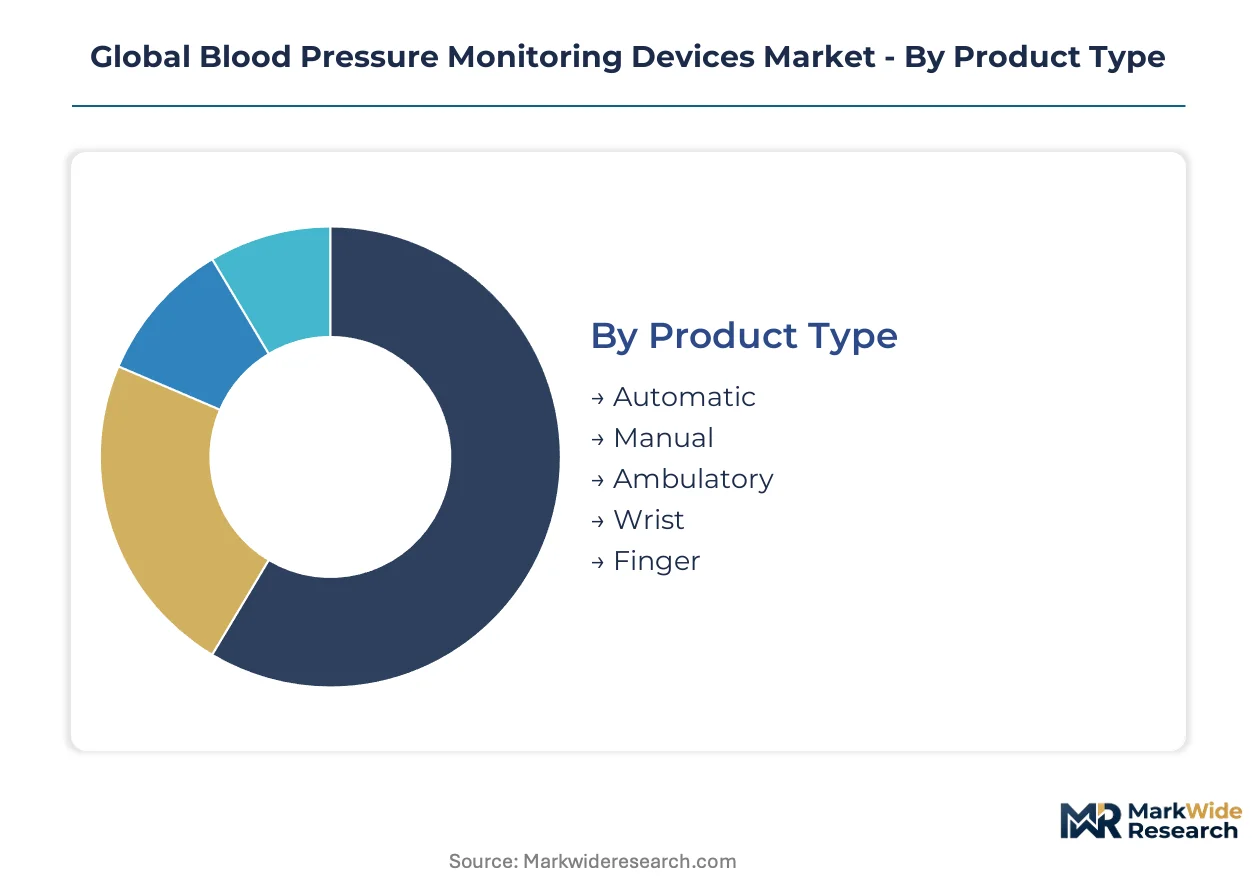
Segmentation in blood pressure monitoring devices reveals how technical specifications, care settings, and procurement channels fragment demand. Understanding these divisions exposes where sensor innovation concentrates and which customer relationships command pricing power.
Product Type:
Replacement cycles vary dramatically across form factors, with ambulatory systems lasting five to seven years while wrist-worn units turn over every eighteen to twenty-four months as consumers chase feature upgrades.
- Automatic:These devices employ oscillometric algorithms with microprocessor-controlled inflation and deflation sequences. Household penetration in China's tier-1 cities accelerates under NMPA streamlining for home-use approvals tied to national hypertension screening mandates.
- Ambulatory:Twenty-four hour circadian profiling systems integrate programmable timers with proprietary cuff designs for sleep-period measurement. German statutory health insurance reimbursement for diagnostic hypertension workups sustains premium positioning in European clinical laboratories.
- Manual:Auscultatory sphygmomanometers requiring trained operator interpretation persist in resource-constrained settings and medical education. Demand concentrates in India's community health worker programs under the National Health Mission.
- Wrist:Compact oscillometric units with position sensors compete on portability against upper-arm accuracy trade-offs. Direct-to-consumer channels in the United States absorb volume through pharmacy chain promotional placement.
- Finger:Photoplethysmography-based cuffless architectures target wellness positioning with limited clinical validation. Early adopters in sports medicine applications tolerate accuracy variance for convenience gains.
Automatic monitors anchor the volume base while wrist devices gain share at the steepest rate.
Technology:
Cost tiers separate validated clinical methods from emerging optical alternatives, with oscillometric systems commanding three to five times the bill-of-materials outlay of photoplethysmography chipsets.
- Oscillometric:Pressure transducer arrays detect arterial wall oscillations during cuff deflation, processed through proprietary algorithms tuned to population-specific pulse wave characteristics. FDA 510(k) clearance requirements for accuracy validation per ISO 81060-2 standards protect incumbent manufacturers from consumer electronics entrants.
- Photoplethysmography:Multi-wavelength LED arrays measure blood volume changes in peripheral vessels, with machine learning calibration against oscillometric baselines enabling cuffless estimation. Shenzhen-based sensor module suppliers are driving unit economics below fifty dollars for wearable integration.
- Auscultatory:Korotkoff sound detection through mercury or aneroid manometers remains the reference standard for clinical validation studies. Medical education institutions in Germany and Japan sustain residual demand despite environmental restrictions on mercury devices.
- Volume Clamp:Finger cuff systems with servo-controlled pressure maintenance enable beat-to-beat continuous monitoring. Cardiac catheterization laboratories in the United States deploy these for hemodynamic monitoring during interventional procedures.
- Tonometry:Applanation sensors at peripheral artery sites measure pulse wave velocity for central blood pressure estimation. Research applications at academic medical centers dominate current utilization pending regulatory validation for diagnostic claims.
Oscillometric platforms dominate revenue concentration while photoplethysmography expands most quickly through consumer electronics integration.
Application:
Customer procurement patterns diverge sharply between institutional tender processes and direct-to-consumer retail, with telehealth providers introducing subscription-based hardware economics that blur traditional ownership models.
- Home Care:Self-measurement protocols with automated data logging support chronic disease management outside clinical facilities. China's national cardiovascular prevention programs subsidize device procurement in tier-2 and tier-3 cities.
- Remote Patient Monitoring:Cloud-connected oscillometric devices transmit readings to telehealth platforms with automated alert thresholds. United States reimbursement codes for chronic care management now cover device data transmission, pulling procurement into subscription models.
- Clinical Diagnostics:Hospital-grade systems with wired telemetry integration support acute care surveillance and perioperative monitoring. EU MDR post-market surveillance requirements for connected devices favor established European notified body relationships.
- Sports Medicine:Ambulatory profiling during exercise stress testing evaluates hypertensive response to physical activity. Professional sports franchises in Germany contract with specialized cardiology practices for athlete screening protocols.
- Occupational Health:Workplace screening programs for commercial drivers and safety-sensitive positions mandate periodic blood pressure assessment. United States Department of Transportation medical examiner requirements sustain fleet procurement cycles.
Home care settings generate the largest unit volumes while remote patient monitoring climbs the fastest on telehealth reimbursement expansion.
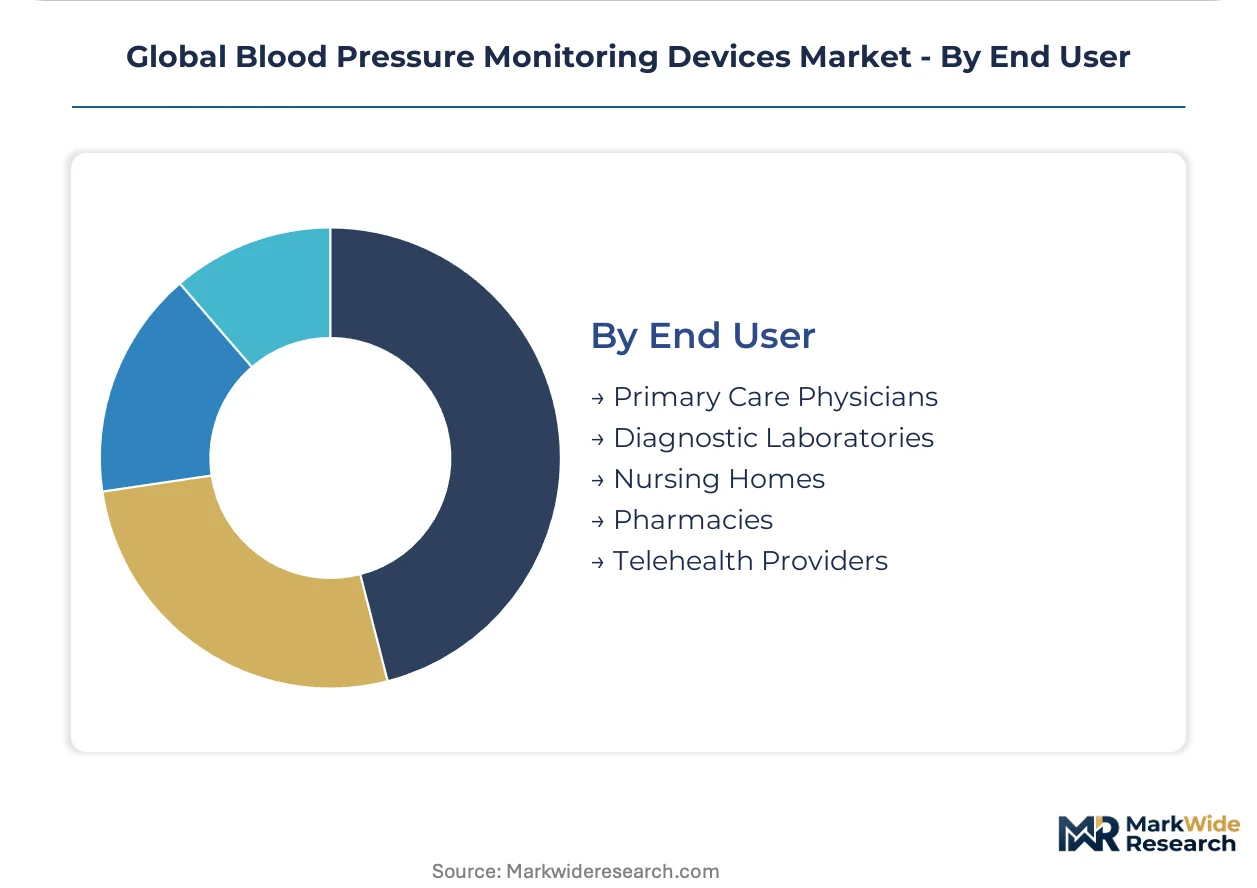
End User:
Channel concentration varies from fragmented primary care practices to consolidated pharmacy chains, with telehealth providers consolidating device procurement decisions across thousands of virtual clinicians.
- Telehealth Providers:Virtual care platforms standardize on specific device models to ensure data interoperability with electronic health record systems. CVS Health and Walgreens in the United States deploy connected monitor kiosks with automatic transmission to capture medication adherence touchpoints.
- Diagnostic Laboratories:Reference laboratories contract for ambulatory monitoring services with twenty-four hour turnaround on report generation. German statutory health insurance preventive care frameworks reimburse atrial fibrillation screening add-ons to standard hypertension protocols.
- Primary Care Physicians:Office-based oscillometric devices support point-of-care screening during routine encounters. India's National Health Mission distributes automatic upper-arm units to community health workers for rural hypertension detection.
- Nursing Homes:Long-term care facilities prioritize automated measurement to reduce staff training requirements and documentation burden. State-level Medicaid reimbursement variations in the United States create procurement patchworks across facilities.
- Pharmacies:Retail chains subsidize hardware costs through data analytics subscription fees, concentrating buyer power among three national United States operators. Independent pharmacies struggle to match procurement scale and cloud infrastructure investments.
Telehealth providers anchor the fastest-expanding demand channel while diagnostic laboratories sustain premium pricing for validated clinical systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports oscillometric sensor modules to assembly networks in the United States and Germany, while finished devices flow through pharmacy retail channels across North America and Europe. Trade corridors concentrate component sourcing in Shenzhen and Suzhou industrial clusters, with final distribution anchored by CVS Health and Walgreens procurement consolidation.
United States
Telehealth reimbursement expansion through CMS chronic care management codes pulls device procurement into subscription-based care models. FDA 510(k) clearance pathways for connected monitors require exhaustive firmware validation of over-the-air update mechanisms. Greater Boston hosts specialized cardiology practices contracting with professional sports franchises for athlete screening protocols.
China
National hypertension screening mandates accelerate household penetration of automatic upper-arm units in tier-1 and tier-2 cities. NMPA streamlined approval pathways align with cardiovascular prevention program subsidies. Suzhou industrial clusters sustain vertical integration in pressure transducer fabrication for Asian and North American assembly networks.
Germany
Statutory health insurance reimbursement for ambulatory 24-hour circadian profiling sustains premium positioning in diagnostic laboratories. EU MDR post-market surveillance requirements with real-world performance data submissions favor established notified body relationships. Bavaria anchors reference laboratory contracting for preventive care frameworks covering atrial fibrillation screening add-ons.
India
Community health worker programs under the National Health Mission create demand for sub-$20 automatic upper-arm units with Hindi-language interfaces. The country's national pharmaceutical regulator maintains quality standards for distributed screening equipment. Maharashtra and Gujarat industrial corridors concentrate assembly operations for solar-charging-compatible rural deployment models.
Japan
Medical education institutions sustain residual demand for auscultatory sphygmomanometers despite environmental restrictions on mercury devices. PMDA clinical evidence requirements for software-enabled devices tighten post-market obligations for connected monitor manufacturers. Kanto region academic medical centers dominate tonometry research applications pending regulatory validation for diagnostic claims.
Global Blood Pressure Monitoring Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. Pharmacy chains and telehealth platforms concentrate buyer power while oscillometric sensor fabricators and ambulatory system specialists defend margin positions through clinical validation. Three archetypes dominate: vertically integrated healthcare conglomerates with hospital-grade telemetry extensions, consumer electronics manufacturers leveraging photoplethysmography miniaturization, and mid-tier automatic monitor specialists serving price-sensitive emerging markets. Competitive moves concentrate on M&A for regulatory clearance capabilities and strategic partnerships for cloud infrastructure integration.
Among diversified healthcare conglomerates, Omron Healthcare and GE Healthcare exemplify channel-spanning positions across clinical and home care settings. Philips Healthcare occupies a position within the hospital-telemetry-to-remote-monitoring extension archetype. These three companies represent the scale-driven tier where manufacturing depth and regulatory relationships create defensive moats against consumer electronics entrants.
| Leading Market Players |
|---|
| Omron Healthcare |
| GE Healthcare |
| Philips Healthcare |
| Welch Allyn |
| A&D Medical |
| Withings |
| SunTech Medical |
| Spacelabs Healthcare |
| Rossmax International |
| Others |
Supply & Pricing Matrix
Shanghai-Shenzhen rail freight corridors carry pressure transducer modules and MEMS sensor arrays to North American and European assembly plants, with container rates directly feeding into tiered hardware pricing. Oscillometric component concentration in Suzhou industrial clusters enables volume discounts that compress retail price points for automatic monitors, while cuffless photoplethysmography chipsets from Shenzhen foundries unlock sub-fifty-dollar direct-to-consumer positioning.
Pricing Analysis
Prior-generation oscillometric upper-arm units trade at commodity margins against current-generation connected monitors with cloud subscriptions, while next-generation cuffless optical systems command wellness premiums pending clinical validation. Three-tier pricing structure across premium, standard, and economy levels separates hospital-grade telemetry with FDA 510(k) clearance from home-use automatic monitors and unvalidated finger-worn wellness devices. Pricing pressure stems from MEMS miniaturization and Taiwanese foundry capacity expansion, with telehealth providers and pharmacy chains exhibiting highest price sensitivity due to subscription-model procurement, while diagnostic laboratories show lowest sensitivity given statutory reimbursement protection.
Supply Chain Analysis
Foxconn, Jabil, and select Shenzhen-based EMS providers hold contract manufacturing capacity for oscillometric device assembly, with tier-1 CMs dominating FDA-regulated production lines. China, Taiwan, and South Korea anchor supply for pressure transducers, analog front-end ICs, and LED sensor arrays, drawing from silicon wafer feedstock and rare-earth phosphor dependencies. Single-source vulnerability concentrates in Taiwanese foundry capacity for signal conditioning chips, exposing manufacturers to geopolitical disruption. Distribution runs through pharmacy retail consolidation in the United States, hospital procurement networks in Germany, and community health worker programs in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins are compressing toward single-digit percentages while data analytics subscriptions and remote monitoring service fees expand at multiples of device revenue growth. The shift from ownership to recurring-revenue models restructures buyer relationships and capital allocation priorities across the value chain.
For Market Incumbents: Build regulatory clearance moats through accelerated FDA 510(k) submissions for AI-enabled arrhythmia detection features before consumer electronics entrants achieve clinical validation. Deepen backward integration into oscillometric sensor fabrication to defend margin positions against photoplethysmography displacement, while capturing pharmacy chain kiosk deployments through exclusive data interoperability agreements with CVS Health and Walgreens. For New Entrants and Emerging Players: Pursue rural India penetration through sub-twenty-dollar automatic upper-arm units with Hindi-language interfaces and solar charging compatibility, targeting community health worker programs under the National Health Mission. White-space opportunity concentrates in cuffless wearable form factors for sports medicine applications where accuracy tolerance permits wellness positioning, with go-to-market traction through direct-to-consumer channels and fitness platform partnerships. For Investors and Strategic Acquirers: Ambulatory monitoring specialists with established European notified body relationships represent priority acquisition targets given EU MDR post-market surveillance requirements that favor incumbents. Long-term viability hinges on recurring revenue attachment rates exceeding hardware replacement cycles, with signal to watch being telehealth provider consolidation into three national pharmacy chains that concentrate procurement decision-making.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements favor established notified body relationships for software-enabled devices. |
| Hospital System Partnership | Proprietary telemetry protocol integration with cloud-native platforms forces expensive middleware development at mid-tier manufacturers. |
| Software Companion Development | FDA software-as-a-medical-device guidance requires exhaustive verification of over-the-air update mechanisms. |
| Reimbursement Strategy | CMS chronic care management codes now cover oscillometric data transmission for remote patient monitoring subscription models. |
| Regulatory Clearance Acceleration | NMPA streamlined pathways for home-use automatic monitors align with China's national hypertension screening mandates. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EU MDR technical documentation filings, and CMS reimbursement code updates preceded structured interviews with hospital purchasing committee members, biomedical engineers, telehealth platform operators, and GPO contracts managers. Primary fieldwork combined with secondary validation against NMPA approval timelines, ISO 81060-2 standard evolution, and customs records for pressure transducer trade flows. Bottom-up unit shipment modeling triangulated against top-down healthcare expenditure allocation across chronic disease management programs.
Assumptions held fixed include regulatory pathway stability across FDA, EMA, and NMPA jurisdictions, while reimbursement expansion rates and semiconductor foundry capacity utilization were varied across sensitivity scenarios. Segmentation dimensions encompassed product type, measurement technology, care setting application, and procurement channel concentration, with CAGRs derived from installed base replacement cycles and penetration rate trajectories across tiered city classifications in China and insurance coverage expansion in the United States.
Sensitivities concentrate around cybersecurity standard divergence extending development timelines, telehealth reimbursement retrenchment, and Taiwanese foundry disruption affecting analog front-end IC supply. Forecasts reflect documented assumptions regarding NMPA streamlining continuity and EU MDR post-market surveillance enforcement intensity. Quarterly review of FDA software guidance updates, CMS chronic care management code utilization, and NMPA approval velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Wearable Ambulatory Monitoring Device Market
Patient Monitoring
Remote Patient Monitoring Devices Market
Patient Monitoring
MRI Compatible Patient Monitoring Systems Market
Patient Monitoring
MR Vital Sign Monitors Market
Patient Monitoring
Germany Blood Glucose Monitoring Market
Patient Monitoring
Mobile Heart Monitoring Market
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
Cardiac Rhythm Remote Monitoring Devices Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
North America Respiratory Monitoring Market
Patient Monitoring
Respiratory Monitoring Devices Market
Patient Monitoring
Heart Failure Monitoring Systems Market
Patient Monitoring
Pain Monitoring Devices Market