
 Transcutaneous Monitors Market | 2026-2036
Transcutaneous Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Transcutaneous Monitors Market Outlook
Software-defined calibration and remote diagnostic subscriptions are decoupling hardware revenue from lifetime value in transcutaneous monitoring. Koninklijke Philips N.V. leverages integrated enterprise informatics to anchor hospital system contracts across North America and Western Europe. Medtronic sustains R&D intensity in sensor miniaturization for wearable and portable formats. Radiometer Medical ApS dominates benchtop critical care installations through direct channel control in high-acuity settings.
Transcutaneous monitors measure blood gases and perfusion parameters through skin-mounted sensors without arterial puncture, typically employing heated electrochemical or optical transducers at controlled temperatures to accelerate gas diffusion through the stratum corneum. Portable monitors and handheld devices lead unit volume as point-of-care expansion shifts monitoring from centralized labs to bedside and transport environments. Infrared and hybrid sensor technologies capture the fastest growth trajectory, displacing legacy thermodynamic designs in neonatal and sleep-lab applications where response time and motion artifact rejection determine clinical utility.
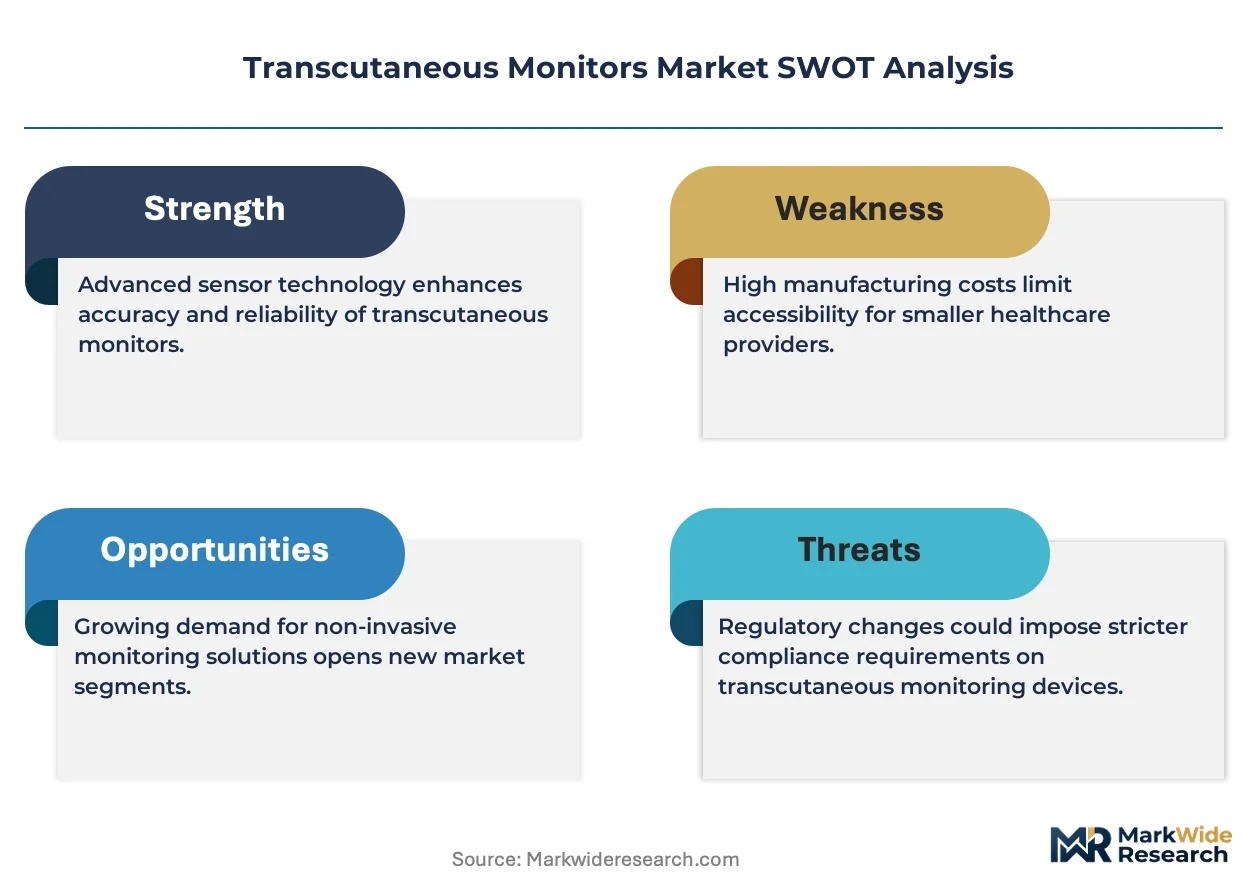
FDA 510(k) clearance requirements and the EU MDR's clinical evidence mandates shape product development timelines and market access costs for manufacturers seeking dual-territory approval. ISO 80601-2-56 standards for body-worn physiologic monitors enforce electromagnetic compatibility and measurement accuracy thresholds that filter subscale competitors from institutional procurement channels. Stakeholders must monitor reimbursement code consolidation for non-invasive monitoring procedures and sensor consumables, as payment policy shifts will determine whether hospital capital budgets or per-patient operational spending funds the next replacement cycle.
Market Dynamics
Non-invasive gas monitoring is displacing arterial blood draws in neonatal intensive care, creating replacement demand cycles that favor sensor miniaturization and heated electrochemical platforms over legacy benchtop systems.
Growth Catalysts
- EU MDR clinical evidence mandates:Tighter validation requirements for Class II medical devices are filtering subscale competitors and consolidating procurement around validated sensor platforms in German and French hospital systems.
- Premature infant monitoring protocols:NICU adoption of continuous tcPO2 and tcPCO2 tracking eliminates invasive sampling trauma, driving hardware replacement in United States academic medical centers.
- Infrared sensor diffusion:Optical transducers with faster response times are capturing sleep-lab and transport monitoring applications where motion artifact rejection determines clinical utility.
Market Restraints
- Palladium electrode cost volatility:Electrochemical sensor production depends on precious metal inputs whose price swings compress margin stability for disposable consumable manufacturers.
- ISO 80601-2-56 compliance burden:Electromagnetic compatibility and measurement accuracy certification timelines extend product development cycles by 12-18 months for body-worn monitor entrants.
- Pulse oximetry substitution threat:Widespread SpO2 monitoring infrastructure in lower-acuity settings limits transcutaneous penetration outside critical care and neonatal specialties.
Strategic Opportunities
- Home-based respiratory monitoring:Japan's aging population and expanded long-term care insurance reimbursement create first-time installations for portable tcPCO2 devices in chronic respiratory disease management.
- Software-defined calibration subscriptions:Remote diagnostic platforms decouple hardware revenue from lifetime value, enabling recurring revenue models that anchor hospital system contracts.
- Wearable form factor convergence:Miniaturized heated sensors combined with wireless telemetry open ambulatory monitoring applications in post-surgical recovery and sleep medicine.
Industry Challenges
- Biomedical sensor engineering talent scarcity:Specialized expertise in electrochemical transducer design and thermal control systems concentrates in Radiometer Medical's Denmark operations and select German sensor houses.
- Legacy device integration complexity:Enterprise informatics deployment requires API development and data normalization across heterogeneous EMR systems that fragment hospital IT procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcutaneous Monitors Market |
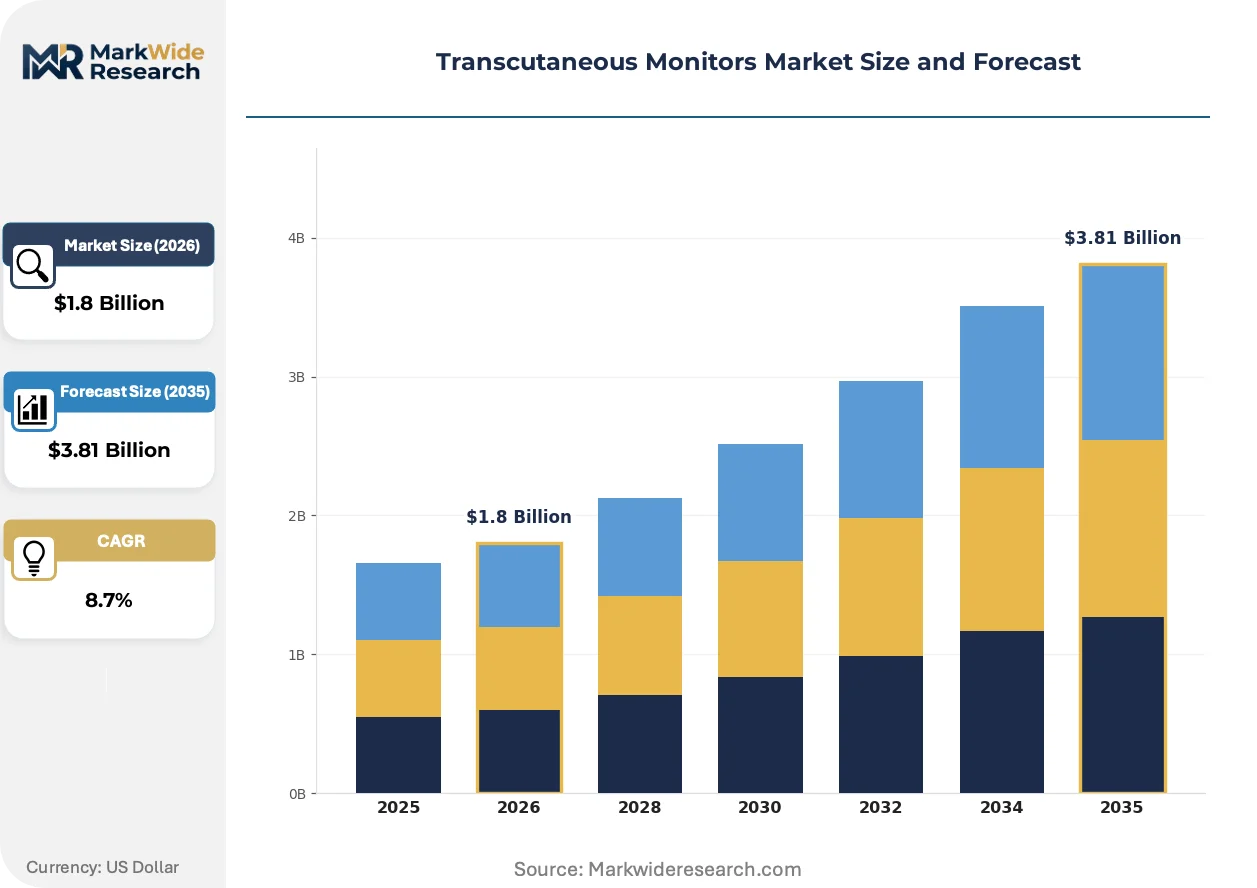
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Handheld Devices, Desktop Systems, Wearable Devices End User: Hospitals, Home Care, Outpatient Clinics, Emergency Services Technology: Infrared Sensors, Optical Sensors, Thermodynamic Sensors, Hybrid Systems Application: Pediatric Monitoring, Pain Management, Anesthesia Monitoring, Critical Care |
| Companies Covered | Koninklijke Philips N.V., Medtronic, Radiometer Medical ApS, Mindray Medical International Limited, Nihon Kohden Corporation, SenTec AG, Drägerwerk AG & Co. KGaA, Humares GmbH, Perimed AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcutaneous Monitors Market Strategic Shifts
Sensor architecture is bifurcating between high-precision benchtop systems for critical care and miniaturized wearable platforms for ambulatory monitoring, with software calibration layers becoming the primary differentiation vector.
Hybrid optical-electrochemical sensors are integrating infrared transducers with heated electrochemical cells to achieve sub-30-second response times in neonatal applications. Level III NICUs in the United States and Germany are adopting these platforms for ventilator weaning protocols. This convergence is integrating real-time perfusion mapping with gas exchange metrics, compressing the functional gap between transcutaneous and invasive arterial monitoring.
FDA 510(k) clearance pathways for Class II medical devices are tightening predicate device equivalence requirements, forcing manufacturers to generate new clinical performance data rather than relying on established device comparisons. The industrial consequence is extended regulatory timelines and elevated legal costs for dual-territory approval seekers. Neonatal monitor categories face the most pronounced compliance burden, with FDA demanding expanded biocompatibility testing for skin-contact sensors in low-birth-weight populations.
Hospital procurement departments are consolidating vendor relationships through enterprise informatics contracts that bundle hardware, consumables, and remote diagnostics into multi-year agreements. United States health system buying cooperatives are displacing individual hospital purchasing autonomy, concentrating negotiation leverage with integrated platform vendors. Academic medical centers in Boston and Cleveland have pioneered these consolidated sourcing frameworks, with standardized sensor consumable contracts now propagating through regional hospital networks.
Transcutaneous Monitors Market Segmentation
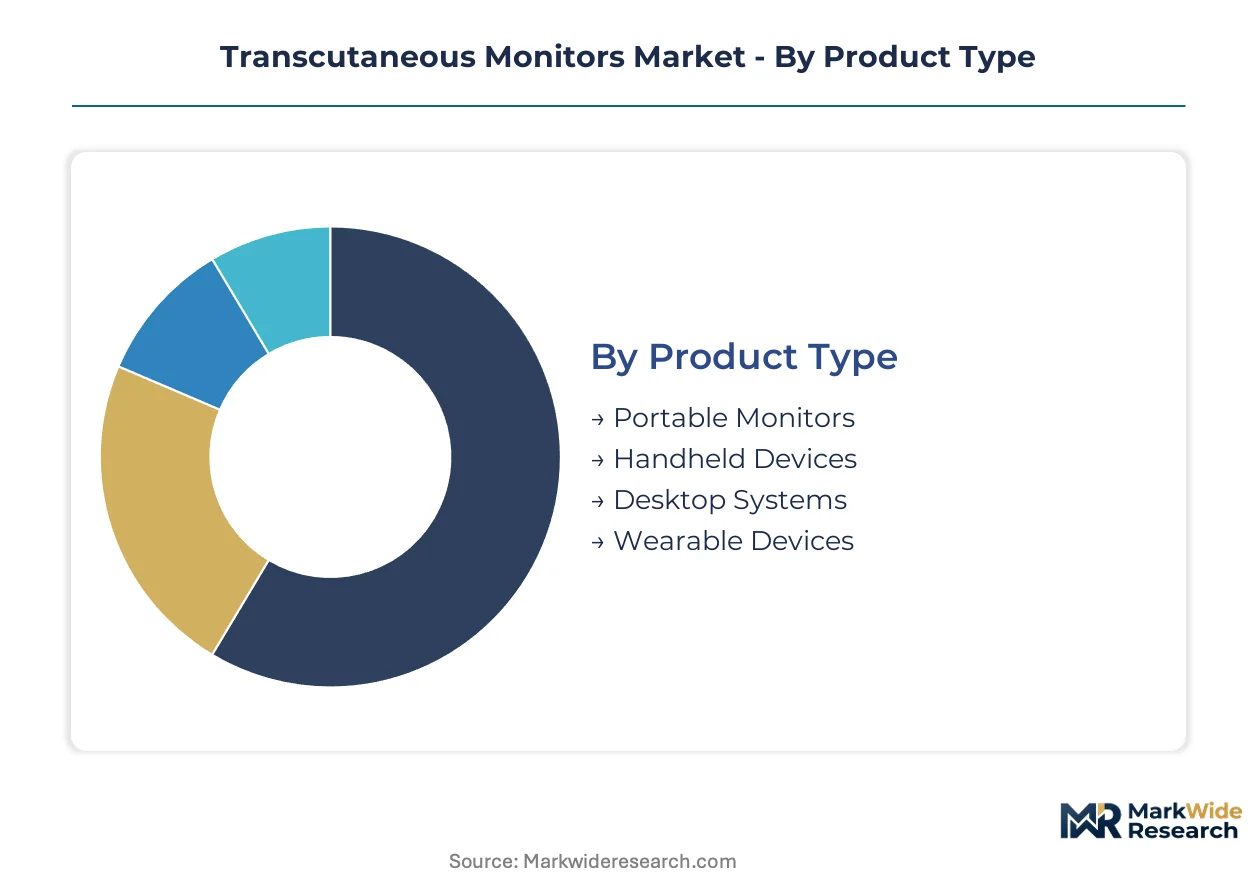
Product architecture in transcutaneous monitoring fragments across stationary critical care platforms, transportable bedside units, and emerging ambulatory formats. Procurement decisions hinge on acuity level, patient mobility requirements, and integration depth with enterprise informatics systems.
Product Type:
Hospital capital budgets prioritize device portability against EMR connectivity requirements, with procurement committees weighing total cost of ownership against clinical workflow flexibility.
- Portable Monitors:Battery-powered units with wireless telemetry enable intra-hospital transport and step-down unit deployment. Demand concentrates in United States academic medical centers replacing fixed bedside installations with flexible monitoring infrastructure.
- Handheld Devices:Compact form factors with simplified interfaces target rapid assessment protocols in emergency departments and outpatient settings. German hospital systems are standardizing these for pre-operative screening workflows to reduce anesthesia consultation bottlenecks.
- Desktop Systems:High-precision benchtop platforms with heated electrochemical sensors serve Level III NICU ventilator weaning protocols.
- Wearable Devices:Skin-adhesive patches with continuous telemetry target post-surgical recovery and sleep medicine applications in Japan's expanding home care reimbursement framework.
Volume sits with portable monitors; growth tilts toward wearable devices.
End User:
Site-of-care economics reshape equipment specifications, with reimbursement codes determining whether capital budgets or per-patient operational spending fund device acquisition.
- Hospitals:Integrated enterprise informatics contracts bundle hardware, consumables, and remote diagnostics across multi-year agreements. United States health system buying cooperatives concentrate negotiation leverage with platform vendors serving neonatal intensive care and critical care units.
- Home Care:Portable tcPCO2 devices gain reimbursement traction under Japan's long-term care insurance expansion for chronic respiratory disease management. Patient and caregiver training requirements shape interface design priorities for this segment.
- Outpatient Clinics:Handheld formats with rapid calibration support pre-surgical assessment and procedural sedation monitoring in ambulatory surgery centers.
- Emergency Services:Ruggedized portable units with extended battery life target pre-hospital trauma and respiratory distress protocols.
Revenue concentrates in hospitals; expansion accelerates in home care.
Technology:
Sensor selection determines response time, motion artifact rejection, and consumable economics, with heated electrochemical platforms facing displacement from optical alternatives in time-sensitive applications.
- Infrared Sensors:Non-contact optical transducers measure perfusion and gas exchange through spectral analysis without skin heating. Sleep-lab adoption in the United States and Germany favors these for motion-tolerant monitoring during nocturnal studies.
- Optical Sensors:LED-based photoplethysmography variants integrate with wearable form factors for continuous ambulatory monitoring. Japanese device manufacturers are advancing miniaturization for skin-adhesive patch formats in post-discharge respiratory surveillance.
- Thermodynamic Sensors:Heated electrochemical cells remain the reference standard for neonatal tcPO2 and tcPCO2 measurement in critical care.
- Hybrid Systems:Combined infrared and electrochemical architectures achieve sub-30-second response times for ventilator weaning protocols.
Installed base rests with thermodynamic sensors; technology investment flows toward hybrid systems.
Application:
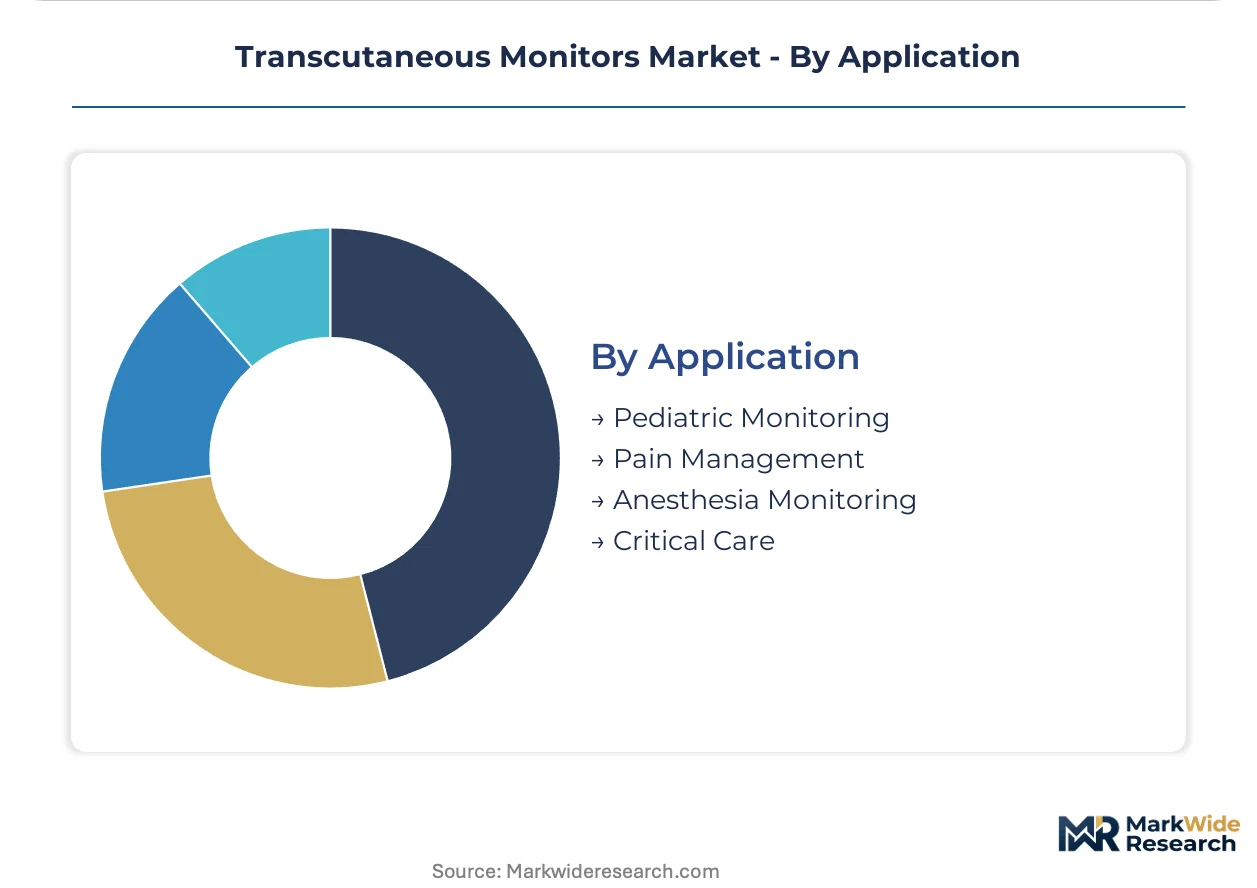
Clinical use case dictates performance specifications, with neonatal and critical care applications demanding highest precision while pain management and anesthesia monitoring prioritize rapid deployment.
- Pediatric Monitoring:Continuous tcPO2 and tcPCO2 tracking eliminates invasive blood draws in premature infant populations. FDA clearance pathways for neonatal indications impose expanded biocompatibility testing for skin-contact sensors in low-birth-weight patients.
- Critical Care:Multi-parameter integration with ventilator systems and EMR platforms anchors hospital procurement decisions. United States and German Level III NICUs drive replacement cycles toward hybrid sensor platforms with real-time perfusion mapping.
- Pain Management:Portable monitors support procedural sedation and patient-controlled analgesia safety protocols in outpatient settings.
- Anesthesia Monitoring:Handheld devices enable rapid pre-operative respiratory assessment and intraoperative ventilation optimization.
Revenue intensity peaks in critical care; pediatric monitoring commands premium pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copenhagen's Medicon Valley anchors European transcutaneous monitor engineering, with sensor foundries and electrochemical research clusters feeding supply chains into German hospital systems and United States academic medical centers.
United States
Level III NICU replacement cycles in Boston and Cleveland drive hybrid sensor platform adoption for ventilator weaning protocols. FDA 510(k) clearance pathways for Class II devices impose expanded biocompatibility testing requirements on skin-contact sensors. Academic medical centers in these clusters pioneer enterprise informatics contracts that bundle hardware, consumables, and remote diagnostics across multi-year agreements.
Germany
Hospital procurement consolidation in North Rhine-Westphalia and Bavaria filters subscale competitors through tightened EU MDR clinical evidence mandates. The country's national pharmaceutical regulator enforces performance validation requirements for sensor accuracy in neonatal applications. Medical device clusters around Munich and Düsseldorf concentrate electrochemical sensor engineering talent and heated transducer manufacturing.
Japan
Expanded long-term care insurance reimbursement creates first-time installations for portable tcPCO2 devices in chronic respiratory disease management. METI coordinates domestic device approval pathways with post-market surveillance requirements for home-use monitors. Osaka-based manufacturers advance miniaturized heated sensors for skin-adhesive patch formats in post-discharge respiratory surveillance.
Denmark
Radiometer Medical's Brønshøj operations concentrate biomedical sensor engineering expertise in electrochemical transducer design and thermal control systems. The Danish Medicines Agency aligns national device regulation with EU MDR implementation timelines for Class II critical care monitors. Copenhagen's Medicon Valley corridor integrates sensor foundry capacity with clinical validation partnerships at Rigshospitalet.
Transcutaneous Monitors Market Competitive Environment
Capital-heavy producers compete with asset-light designers across sensor architecture and software calibration layers. The vendor base consolidates around three strategic tiers: integrated platform vendors anchoring hospital system contracts, specialized sensor houses controlling critical care niches, and emerging wearable format developers. Dominant competitive moves include enterprise informatics bundling to lock multi-year procurement agreements and sensor miniaturization R&D to capture ambulatory monitoring expansion.
Within the integrated platform tier, Koninklijke Philips N.V. and Medtronic occupy positions shaped by North American and Western European hospital system penetration. Radiometer Medical ApS exemplifies the specialized sensor house archetype, with its Denmark-based operations anchoring high-acuity critical care installations. These three entities represent divergent strategic postures: enterprise informatics integration, wearable format development, and benchtop precision engineering respectively.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Medtronic |
| Radiometer Medical ApS |
| Mindray Medical International Limited |
| Nihon Kohden Corporation |
| SenTec AG |
| Drägerwerk AG & Co. KGaA |
| Humares GmbH |
| Perimed AB |
| Others |
Value Chain & Pricing Dynamics
United States health system buying cooperatives concentrate procurement leverage around integrated platform vendors, locking in multi-year enterprise informatics contracts that bundle hardware, consumables, and remote diagnostics into subscription-based pricing models. This buyer concentration shifts negotiation power toward vendors with FDA-cleared sensor platforms and established GPO relationships, compressing margins for standalone device manufacturers lacking software calibration layers.
Pricing Analysis
Value-based pricing anchors on clinical throughput and ventilator weaning protocol efficiency in Level III NICU deployments. Three-tier pricing structure across premium hybrid-sensor platforms, standard heated-electrochemical systems, and economy infrared-only devices differentiates by FDA clearance tier and EMR integration depth. Cost compression in the economy tier intensifies because pulse oximetry substitution limits addressable demand outside critical care. Academic medical centers exhibit lowest price sensitivity due to bundled informatics contracts; outpatient clinics and ambulatory surgery centers face highest budget constraints.
Supply Chain Analysis
Regional distribution centers in Copenhagen, Munich, and Osaka operate hub-and-spoke patterns serving hospital systems and home care networks. Sensor foundry capacity concentrates in Denmark, Germany, and Japan, drawing from palladium electrode suppliers and optical transducer component manufacturers. Single-source vulnerability in precious metal inputs for electrochemical cells creates margin instability during commodity price swings. Distribution runs through direct hospital channel control for benchtop critical care systems, with third-party medical device distributors handling portable and wearable formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transcutaneous monitors market operates as a cost-of-compliance story where EU MDR clinical evidence mandates and FDA 510(k) biocompatibility requirements erect barrier-to-entry moats favoring validated sensor platform vendors with established regulatory affairs infrastructure.
For Market Incumbents: Hedge against pulse oximetry substitution by deepening software-defined calibration subscriptions that anchor hospital system contracts beyond hardware replacement cycles. Prioritize backward integration into palladium electrode supply chains to buffer margin compression from precious metal volatility. Defensive patent filings around hybrid optical-electrochemical architectures protect NICU ventilator weaning protocol market share from emerging wearable format developers. For New Entrants and Emerging Players: Enter via Japan's home care reimbursement expansion under long-term care insurance, where portable tcPCO2 devices face limited incumbent saturation and patient training requirements favor simplified interface designs. Target sleep-lab and post-surgical ambulatory monitoring applications where infrared sensor response time advantages displace legacy thermodynamic platforms. Pursue white-label partnerships with Osaka-based miniaturization specialists to accelerate skin-adhesive patch format development without captive sensor foundry investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized sensor houses with Denmark-based electrochemical engineering talent and existing FDA neonatal clearance pathways. Long-term viability over the analysis window hinges on software calibration layer recurring revenue conversion and hybrid sensor platform adoption in ventilator weaning protocols. Monitor reimbursement code consolidation for non-invasive monitoring procedures as the primary inflection signal determining whether capital budgets or per-patient operational spending fund replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerated predicate device equivalence reviews compress market access timelines for neonatal sensor platforms. |
| CE Marking Pathway | EU MDR clinical evidence mandates filter subscale competitors from German and French hospital procurement channels. |
| Hospital System Partnership | Enterprise informatics bundling with United States academic medical centers locks multi-year consumable contracts. |
| Software Companion Development | Remote diagnostic platforms decouple hardware revenue from lifetime value in subscription-based pricing models. |
| Reimbursement Strategy | Japan METI coordination on long-term care insurance codes enables first-time home care installations for portable monitors. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract repositories, complemented by interviews with neonatologists, biomedical engineers, hospital purchasing committee members, and regulatory affairs specialists at sensor platform vendors. Secondary validation drew from ISO 80601-2-56 standards documentation, CMS Medicare reimbursement code databases, and Japan METI device approval records. Bottom-up unit economics and top-down market sizing triangulated across primary fieldwork and secondary data synthesis.
Segment-level outputs across product type, end user, technology, and application dimensions were generated through structured modeling over the projection horizon. CAGRs derived from regression analysis against neonatal intensive care admission trends, critical care infrastructure replacement cycles, and home care reimbursement expansion trajectories. Forecast inputs incorporated sensor miniaturization R&D intensity, palladium price volatility indices, and health system buying cooperative consolidation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR implementation delays or FDA biocompatibility testing requirement expansions for low-birth-weight populations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Europe Respiratory Monitoring Market
Patient Monitoring
Remote Patient Monitoring Software Market
Patient Monitoring
North America Remote Patient Monitoring Systems Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Brain Monitoring Systems Market
Patient Monitoring
Asia-Pacific Patient Monitoring Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
Continuous Cardiac Monitoring Devices Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market
Patient Monitoring
Global Patient Monitoring Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
Wearable Ambulatory Monitoring Device Market