
 United States Cardiac Holter Monitor Market | 2026-2036
United States Cardiac Holter Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
United States Cardiac Holter Monitor Market Intelligence
Domestic device manufacturing capacity is restructuring around digital-first production lines in Minnesota and Massachusetts. Medtronic leverages its deep implantable cardiac portfolio to cross-sell Holter systems into integrated cath lab networks. Abbott Laboratories anchors its position through diagnostic ecosystem bundling with vascular and diabetes platforms. iRhythm Technologies, Inc. competes aggressively on AI-enabled ECG interpretation that reduces clinician reading burden.
The United States Cardiac Holter Monitor is a portable electrocardiographic device that continuously records heart rhythm over 24–48 hours via 3–12 lead configurations, storing data for retrospective arrhythmia analysis. Its primary purpose is to capture transient cardiac electrical abnormalities outside clinical settings where standard 12-lead ECGs miss episodic events. Wireless Holter and mobile cardiac telemetry segments are capturing the fastest expansion as reimbursement codes validate remote monitoring economics. Traditional Holter maintains volume dominance in hospital-based preoperative assessment workflows where cost sensitivity and established protocols limit technology switching. Cloud-based solutions and smartphone integration within the technology dimension are concentrating margin pools through recurring software licensing rather than hardware depreciation cycles.
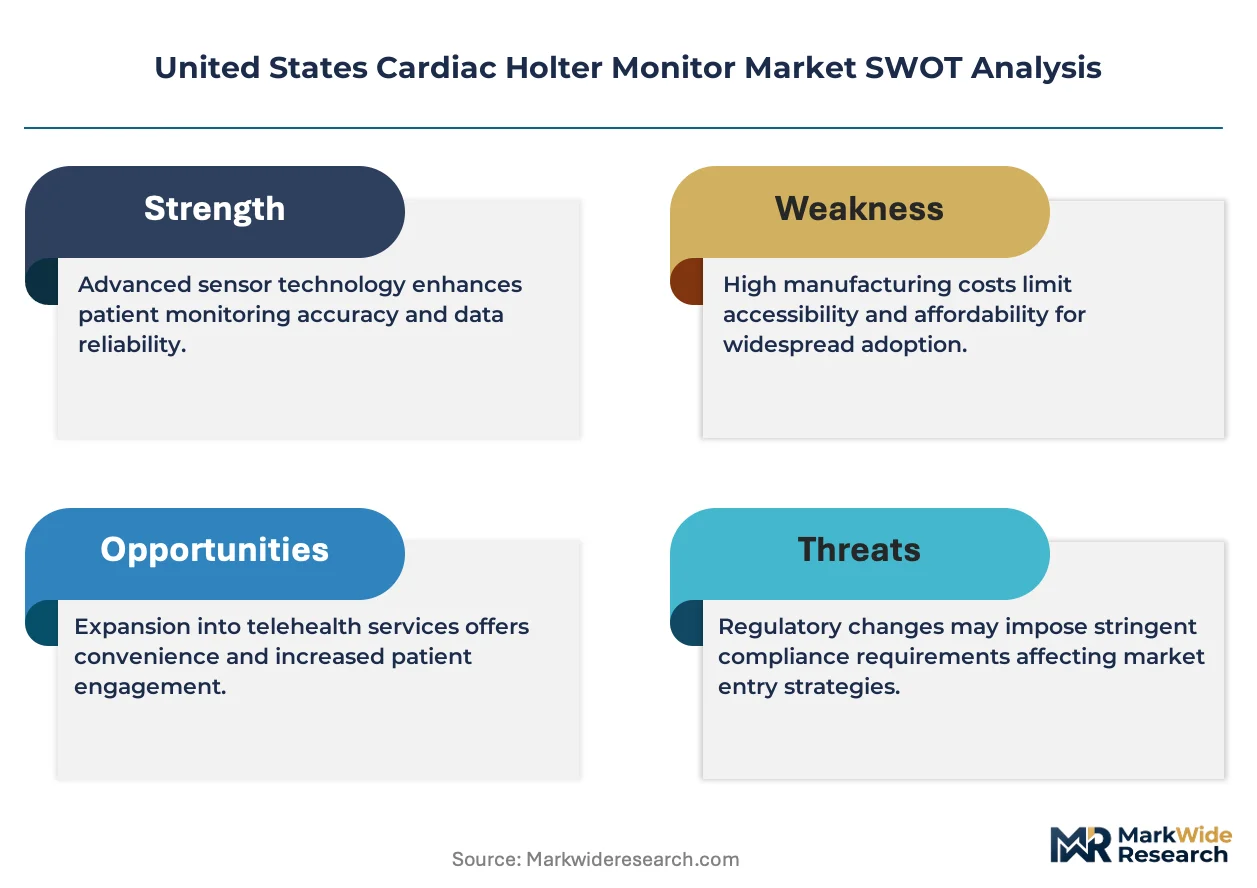
FDA 510(k) clearance pathways and CMS National Coverage Determinations shape product development timelines and commercial launch sequencing for manufacturers seeking immediate reimbursement eligibility. HIPAA data security requirements and FDA cybersecurity guidance for connected devices impose compliance costs that favor established players with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving CPT code valuations for extended external electrocardiographic monitoring as payer consolidation redefines profitable service line configurations.
Market Dynamics
CMS reimbursement code expansions for remote patient monitoring are restructuring provider economics, forcing cardiovascular service lines to consolidate ambulatory monitoring programs around digital-first platforms rather than legacy hardware depreciation models.
Growth Catalysts
- Medicaid RPM coverage expansion:State-level Medicaid programs in Texas and Florida now reimburse extended external electrocardiographic monitoring, expanding addressable patient populations beyond Medicare beneficiaries.
- Integrated delivery network consolidation:Midwest hospital systems are bundling Holter procurement with cath lab capital equipment purchases, creating single-vendor relationships that reduce switching costs.
- AI-enabled ECG interpretation:Machine learning algorithms trained on arrhythmia datasets are reducing cardiologist reading time by flagging priority cases, improving clinical workflow efficiency in high-volume practices.
Market Restraints
- Semiconductor component concentration:Analog front-end chips and low-power microcontrollers for wearable ECG devices concentrate in Taiwan and South Korean foundries, exposing manufacturers to geopolitical supply disruptions.
- FDA 510(k) cybersecurity requirements:Connected device guidance issued in 2023 imposes pre-market documentation burdens that extend clearance timelines by 4-6 months for software-integrated systems.
- Mobile cardiac telemetry substitution:Real-time cellular-connected monitors are capturing diagnostic cases previously assigned to traditional Holter studies, compressing volume in hospital-based preoperative workflows.
Strategic Opportunities
- Ohio Medicaid managed care penetration:Underserved rural counties in Appalachian Ohio present whitespace for remote monitoring programs targeting heart failure readmission reduction.
- Smartphone-native ECG convergence:Integration of single-lead consumer devices with clinical-grade Holter systems creates hybrid diagnostic pathways for episodic symptom capture.
- Accountable care organization risk contracts:Medicare ACOs in Florida are incentivizing ambulatory arrhythmia detection to reduce emergency department utilization, aligning reimbursement with monitoring intensity.
Industry Challenges
- Cardiac electrophysiologist workforce constraints:Fellowship training programs produce insufficient specialists to interpret escalating Holter study volumes, creating diagnostic backlogs in community hospital settings.
- EHR interoperability fragmentation:Proprietary data formats from competing device manufacturers require costly interface engine development for health system IT departments managing multi-vendor environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Cardiac Holter Monitor Market |
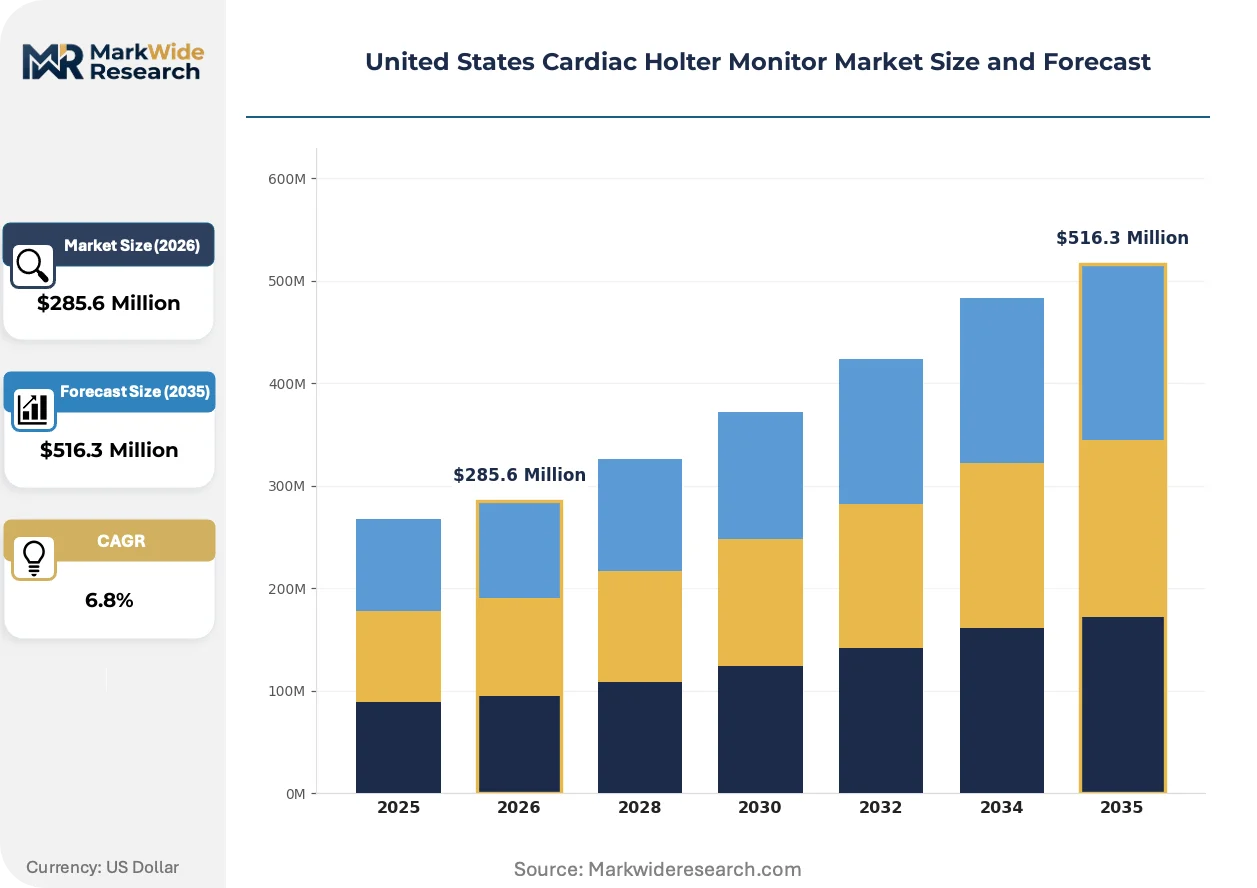
| Market Size in 2026 | $285.6 Million |
| Market Size in 2035 | $516.3 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Holter, Wireless Holter, Event Monitor, Mobile Cardiac Telemetry End User: Hospitals, Outpatient Clinics, Home Healthcare, Research Institutions Technology: Continuous Monitoring, Smartphone Integration, Cloud-Based Solutions, ECG Analysis Software Application: Arrhythmia Detection, Post-Myocardial Infarction, Syncope Evaluation, Preoperative Assessment |
| Companies Covered | Koninklijke Philips N.V., Boston Scientific, Medtronic, Hillrom Holdings, Inc., Nihon Kohden Corporation, Abbott Laboratories, iRhythm Technologies, Inc., Schiller AG, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Cardiac Holter Monitor Market Strategic Shifts & Innovations
Artificial intelligence is penetrating every layer of cardiac monitoring value chains, from signal acquisition through clinical decision support, compressing traditional service models that relied on human interpretation labor.
Patch-based ambulatory monitors are overtaking conventional wired Holter systems in outpatient cardiology practices. These adhesive single-use devices eliminate electrode placement variability and patient compliance failures. Health systems in Texas and Florida are deploying patch platforms for 7-14 day monitoring windows that exceed traditional Holter duration limits.
FDA cybersecurity guidance for connected medical devices is mandating software bill of materials disclosure and vulnerability management protocols. Manufacturers must demonstrate continuous monitoring capabilities for cloud-connected Holter systems throughout product lifecycles. This regulatory friction disproportionately burdens mid-tier device companies lacking dedicated security engineering infrastructure.
Cardiovascular service line administrators are unbundling device procurement from professional interpretation services. Third-party diagnostic reading groups staffed by board-certified cardiologists are capturing Holter interpretation contracts from hospital-employed physicians. This channel disintermediation concentrates in Southeastern integrated delivery networks seeking labor cost arbitrage.
United States Cardiac Holter Monitor Market Segmentation
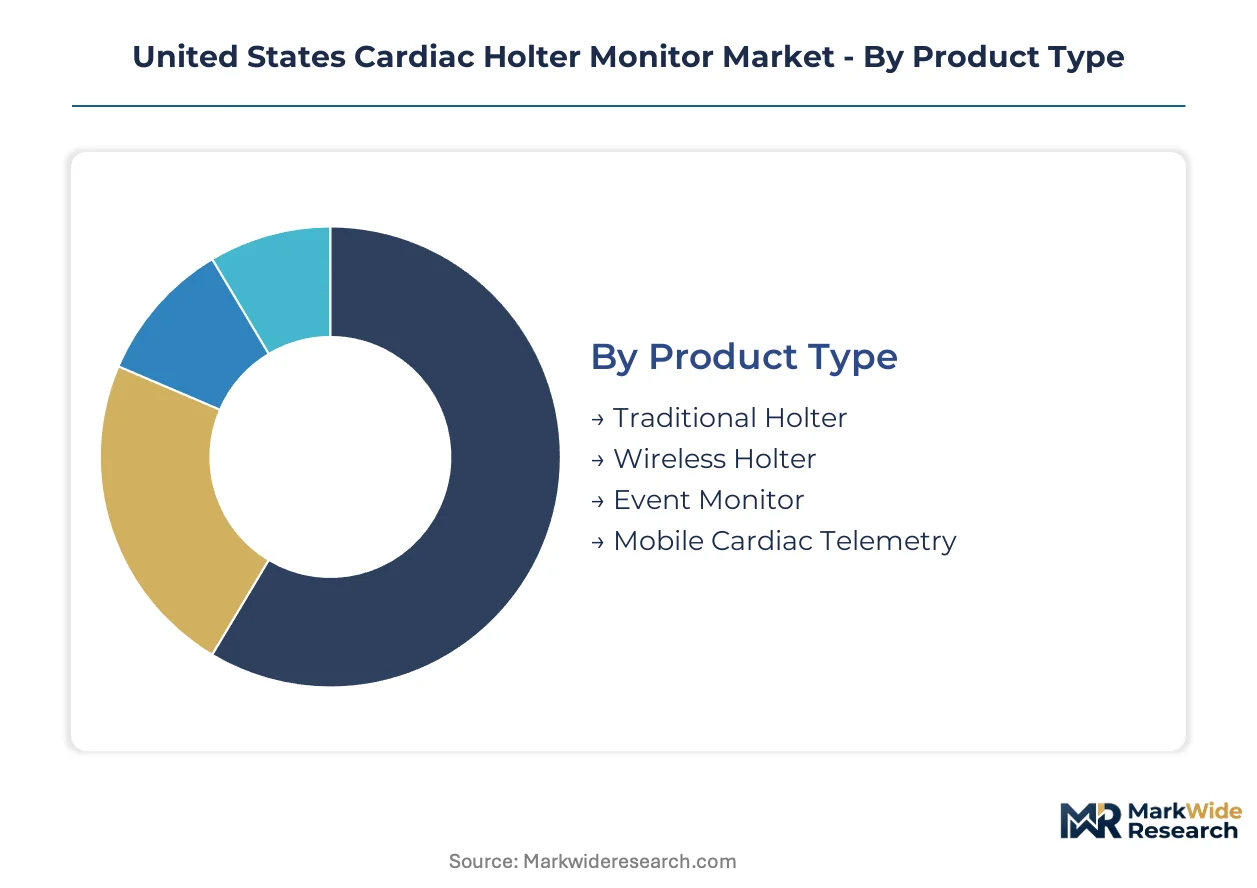
Segmentation in the United States cardiac Holter monitor market reveals how FDA clearance pathways and CMS reimbursement codes differentially shape commercial viability across product configurations. Each dimension carries distinct regulatory burdens that determine go-to-market economics and provider adoption velocity.
Product Type:
FDA 510(k) clearance complexity varies substantially across form factors, with wireless and patch-based systems facing heightened cybersecurity documentation requirements under 2023 guidance.
- Traditional Holter:Wired 3-12 lead configurations with 24-48 hour recording duration dominate hospital preoperative workflows in Texas and Florida where established protocols limit technology switching. Cost sensitivity and depreciation accounting favor this segment in integrated delivery network procurement bundles.
- Wireless Holter:Bluetooth-enabled devices eliminate electrode wire constraints while maintaining diagnostic-grade signal fidelity. Demand concentrates in Midwest hospital systems expanding ambulatory monitoring programs where patient mobility compliance drives clinical utility.
- Event Monitor:Patient-activated or auto-triggered devices capture episodic symptoms over 30-day windows. Appalachian Ohio rural counties present whitespace deployment opportunities for heart failure readmission reduction programs.
- Mobile Cardiac Telemetry:Real-time cellular-connected monitors transmit ECG data continuously to monitoring centers. Southeastern integrated delivery networks substitute these for traditional Holter in diagnostic pathways.
Traditional Holter sits at the top of the volume ranking, with Mobile Cardiac Telemetry climbing the fastest.
End User:
Procurement authority and reimbursement capture mechanics differ sharply across care settings, with hospital systems leveraging capital equipment bundling while home healthcare depends on remote patient monitoring code valuations.
- Hospitals:Cardiovascular service lines in Midwest and Southeast regions anchor volume through cath lab integration and preoperative assessment protocols. CMS reimbursement shifts accelerate consolidation around digital-first platforms.
- Outpatient Clinics:Community cardiology practices in Texas and Florida deploy patch-based monitors for 7-14 day monitoring windows exceeding traditional Holter limits. Third-party diagnostic reading groups capture interpretation contracts from clinic-employed physicians.
- Home Healthcare:Medicare ACOs incentivize ambulatory arrhythmia detection to reduce emergency department utilization. State-level Medicaid programs in Texas and Florida now reimburse extended external electrocardiographic monitoring.
- Research Institutions:Academic medical centers in Minnesota and Massachusetts drive AI-enabled ECG algorithm development through large-scale arrhythmia dataset curation.
Hospitals retain the dominant procurement position, though home healthcare gains share fastest as RPM coverage expands.
Technology:
Margin pools concentrate in software layers where recurring licensing replaces hardware depreciation, while semiconductor component concentration in Asian foundries exposes device manufacturers to supply disruption.
- Continuous Monitoring:Uninterrupted ECG signal acquisition across 24-hour to 30-day durations remains the clinical standard for arrhythmia burden quantification. FDA cybersecurity guidance imposes software bill of materials disclosure for these connected systems.
- Smartphone Integration:Single-lead consumer devices converge with clinical-grade systems for hybrid diagnostic pathways. Smartphone-native ECG platforms enable episodic symptom capture outside traditional clinical workflows.
- Cloud-Based Solutions:Data storage and remote access infrastructure concentrate margin through recurring software licensing rather than capital equipment sales. HIPAA data security requirements impose compliance costs favoring established players.
- ECG Analysis Software:Machine learning algorithms trained on proprietary arrhythmia datasets reduce cardiologist reading time by flagging priority cases. AI-enabled interpretation creates diagnostic workflow efficiency in high-volume practices.
Continuous Monitoring holds the largest installed base, with ECG Analysis Software expanding most quickly as labor arbitrage drives adoption.
Application:
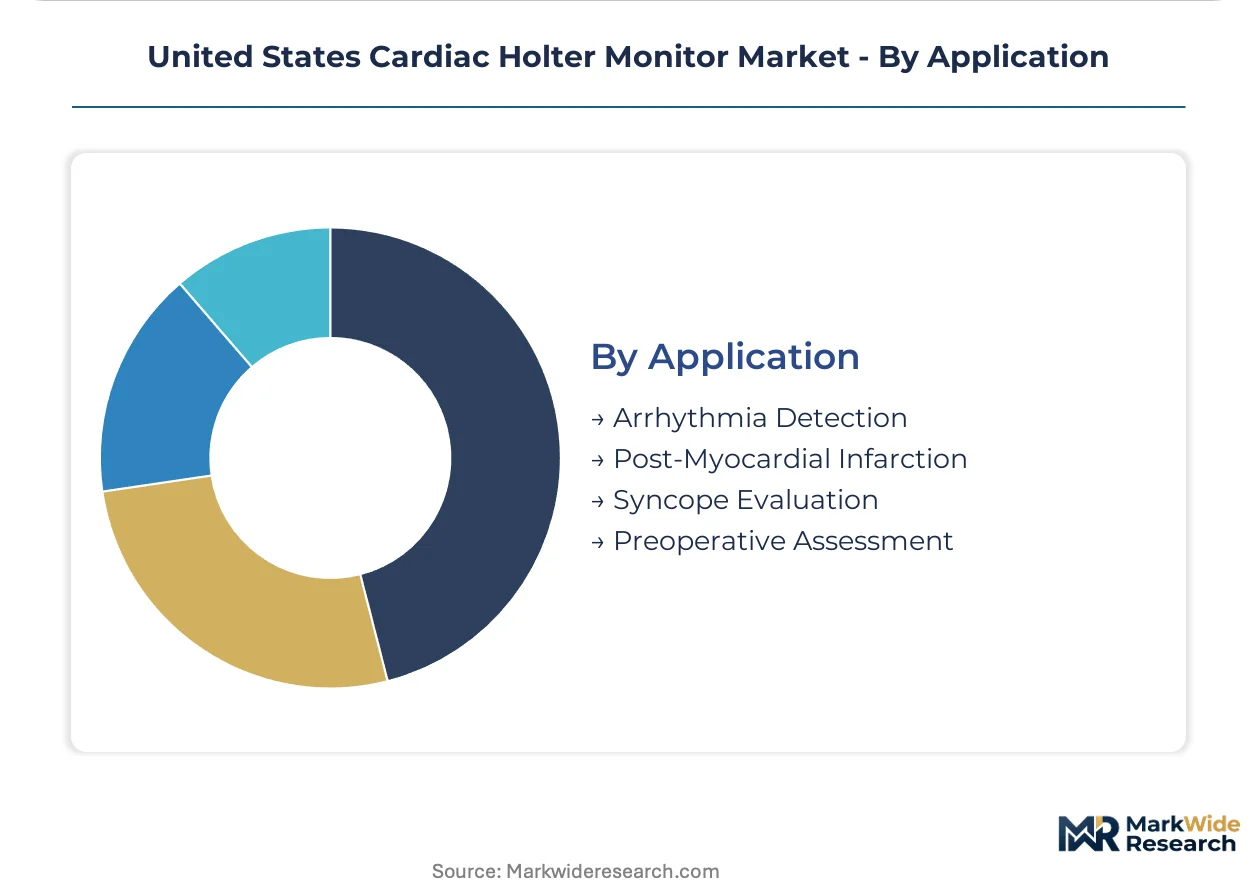
Clinical indication determines monitoring duration requirements and reimbursement code selection, with syncope evaluation and post-MI surveillance commanding distinct CPT valuations.
- Arrhythmia Detection:Primary indication for ambulatory ECG monitoring encompassing atrial fibrillation burden assessment and ventricular ectopy quantification. Cardiac electrophysiologist workforce constraints create diagnostic backlogs in community hospital settings.
- Post-Myocardial Infarction:Surveillance for silent ischemia and ventricular arrhythmia risk stratification following acute coronary events. Ohio Medicaid managed care penetration targets underserved rural counties for readmission reduction.
- Syncope Evaluation:Correlation of symptoms with cardiac rhythm disturbances in unexplained loss-of-consciousness cases. Event monitors and mobile cardiac telemetry capture cases where traditional Holter duration proves insufficient.
- Preoperative Assessment:Risk stratification for non-cardiac surgery patients with cardiovascular comorbidities. Traditional Holter maintains dominance where established protocols and cost sensitivity limit technology switching.
Arrhythmia Detection anchors diagnostic volume, with Syncope Evaluation showing the steepest expansion trajectory as monitoring duration requirements lengthen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cybersecurity guidance and CMS reimbursement code valuations create compliance-cost arbitrage that favors established manufacturers with dedicated regulatory infrastructure over emerging entrants lacking comparable resources.
Texas
Integrated delivery networks in Houston and Dallas consolidate cardiovascular service lines around digital-first ambulatory monitoring platforms. State Medicaid expansion now reimburses extended external electrocardiographic monitoring, widening addressable populations beyond Medicare. Medical device distribution clusters in the Texas Medical Center anchor procurement relationships for hospital system bundles.
Florida
Medicare ACO risk contracts incentivize ambulatory arrhythmia detection to reduce emergency department utilization across the Southeast. Tampa and Miami metropolitan areas concentrate outpatient cardiology practices deploying patch-based monitors for 7-14 day windows. CMS National Coverage Determinations validate remote patient monitoring economics for physician adoption.
Ohio
Appalachian rural counties present whitespace for heart failure readmission reduction programs targeting underserved populations. Medicaid managed care penetration in Cleveland and Columbus markets drives demand for cost-effective diagnostic pathways. The Midwest hospital system expansion of ambulatory cardiac monitoring programs concentrates procurement authority in integrated networks.
Minnesota
Domestic device manufacturing capacity restructures around digital-first production lines in the Minneapolis-St. Paul corridor. Medtronic leverages its deep implantable cardiac portfolio to cross-sell Holter systems into integrated cath lab networks. HIPAA data security requirements favor established players with dedicated compliance infrastructure.
Massachusetts
Academic medical centers in Boston drive AI-enabled ECG algorithm development through large-scale arrhythmia dataset curation. Abbott Laboratories anchors diagnostic ecosystem bundling with vascular and diabetes platforms from its regional headquarters. FDA 510(k) clearance pathways shape product development timelines for manufacturers seeking immediate reimbursement eligibility.
United States Cardiac Holter Monitor Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue AI-enabled interpretation and patch-based form factors to differentiate from legacy hardware depreciation models. The vendor base stratifies across implantable cardiac device incumbents, diagnostic platform conglomerates, and digital-native monitoring specialists. Three archetypes dominate: diversified medtech conglomerates with cath lab integration capabilities, pure-play ambulatory monitoring specialists with algorithmic differentiation, and hospital supply distributors with procurement bundling leverage. Competitive moves concentrate on diagnostic ecosystem bundling and third-party interpretation service disintermediation.
Within the diversified medtech tier, Medtronic and Abbott Laboratories exemplify archetypes leveraging implantable device portfolios to cross-sell external monitoring systems. iRhythm Technologies, Inc. occupies a position representing pure-play digital-native competitors competing on AI-enabled ECG interpretation that reduces clinician reading burden. These three anchors illustrate how regulatory infrastructure scale, algorithmic differentiation, and integrated service line penetration define competitive positioning in CMS reimbursement-dependent markets.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Boston Scientific |
| Medtronic |
| Hillrom Holdings, Inc. |
| Nihon Kohden Corporation |
| Abbott Laboratories |
| iRhythm Technologies, Inc. |
| Schiller AG |
| GE Healthcare |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up diagnostic reading groups in the Southeastern United States are consolidating Holter interpretation contracts and compressing margins for device manufacturers, forcing pricing discipline upstream while semiconductor component sourcing concentrates procurement leverage among established players with dedicated supply chain teams.
Pricing Analysis
Distributor margins on traditional wired Holter systems range from 15-25% in hospital procurement bundles, while direct-to-clinic sales of patch-based monitors command premium positioning through AI-enabled interpretation subscriptions. Three-tier pricing structure across premium AI-integrated, standard wireless, and economy traditional wired configurations reflects FDA cybersecurity compliance costs and algorithm development investment. Pricing pressure stems from third-party diagnostic reading groups capturing interpretation services and unbundling professional fees from device revenue. Hospital systems in Texas and Florida exhibit highest price sensitivity due to integrated delivery network volume consolidation, while academic medical centers in Massachusetts and Minnesota prioritize AI-enabled workflow efficiency over unit cost.
Supply Chain Analysis
Reverse-logistics flows for refurbished Holter recorders and warranty replacement units concentrate in Minnesota and Massachusetts manufacturing facilities, creating secondary supply channels for cost-sensitive Midwest hospital systems. Analog front-end chips and low-power microcontrollers draw from Taiwan and South Korean foundries, while adhesive patch substrates and medical-grade electrodes source from domestic converters in Ohio and Texas. Single-source vulnerability in semiconductor fabrication exposes manufacturers to geopolitical disruption, particularly for Bluetooth-enabled wireless systems requiring specialized RF components. Distribution runs through GPO contracts with hospital systems, direct sales to outpatient cardiology practices, and third-party diagnostic service providers capturing interpretation revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ohio Medicaid expansion into rural Appalachian counties creates a geographic-arbitrage opportunity where reimbursement rate differentials between Medicare and state managed care programs enable margin capture unavailable in saturated Florida and Texas metropolitan markets.
For Market Incumbents: Hedge against mobile cardiac telemetry substitution by deepening AI-enabled ECG interpretation capabilities and securing exclusive GPO contracts with expanding Midwest integrated delivery networks. Acquire patch-based monitor specialists to fill form-factor gaps before pure-play digital entrants capture outpatient clinic volume in Texas and Florida. FDA cybersecurity documentation burdens favor consolidation around players with dedicated regulatory affairs infrastructure. For New Entrants and Emerging Players: The premium-economy price-point gap in traditional wired Holter systems for hospital preoperative workflows presents white-space entry through cost-optimized manufacturing and simplified FDA 510(k) pathways targeting cost-sensitive community hospitals. Target Ohio Medicaid managed care penetration in underserved rural counties with remote patient monitoring bundles addressing heart failure readmission reduction. Go-to-market through third-party diagnostic reading group partnerships to bypass direct hospital sales force requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier device manufacturers lacking AI-enabled interpretation software and cloud infrastructure, creating acquisition targets for diagnostic platform conglomerates seeking ambulatory monitoring capabilities. Long-term viability hinges on recurring software licensing revenue displacing hardware depreciation models over the projection horizon. Watch CMS National Coverage Determination revisions for extended external electrocardiographic monitoring codes as the inflection signal for reimbursement-driven demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled ECG Algorithm Development | Machine learning training on arrhythmia datasets reduces cardiologist reading burden and creates subscription revenue. |
| FDA 510(k) Cybersecurity Compliance Investment | Pre-market documentation for connected devices extends clearance timelines and favors established regulatory infrastructure. |
| Hospital System GPO Contract Consolidation | Integrated delivery network bundling with cath lab equipment reduces vendor switching costs and locks procurement relationships. |
| Patch-Based Monitor Platform Launch | Adhesive single-use devices eliminate electrode placement variability and capture 7-14 day monitoring windows. |
| Third-Party Interpretation Service Integration | Diagnostic reading groups staffed by board-certified cardiologists disintermediate hospital-employed physician labor costs. |
Research Approach
Direct dialogue with cardiovascular service line administrators, biomedical engineers at integrated delivery networks, GPO contracts managers, and cardiac electrophysiologists grounded qualitative findings in procurement workflow realities and clinical interpretation bottlenecks. Secondary validation drew from FDA 510(k) clearance databases, CMS National Coverage Determinations, hospital procurement records, and GPO contract disclosures. Bottom-up triangulation across device shipment estimates and top-down reconciliation against CMS reimbursement claims data ensured cross-verified market sizing.
Segment-level projections across product type, end user, technology, and application dimensions produced volume and value estimates across the analysis window. CAGRs derived from regression analysis of historical reimbursement code valuations, hospital capital expenditure cycles, and ambulatory monitoring program expansion rates. Forecast inputs incorporated semiconductor supply lead times, FDA cybersecurity guidance implementation timelines, and state-level Medicaid RPM coverage expansion trajectories.
Caveats apply where FDA cybersecurity requirement modifications, CMS CPT code valuation resets, or Taiwan semiconductor supply disruptions could materially shift the outlook. Practitioners should monitor state Medicaid managed care penetration rates and Medicare ACO risk contract adoption for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Coronary Pressure Monitors Market
Patient Monitoring
Home Care Monitoring and Diagnostics Market
Patient Monitoring
Bedside Monitors Market
Patient Monitoring
Respiratory Monitoring Market
Patient Monitoring
United Kingdom Remote Patient Monitoring Market
Patient Monitoring
UAE Patient Monitoring Equipment Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
Digital Patient Monitoring Systems Market
Patient Monitoring
Gas Exchange Monitor Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
South Africa Patient Monitoring Market
Patient Monitoring
ECG Monitoring System Market