
 Real Time Health Monitoring Devices Market | 2026-2036
Real Time Health Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Real Time Health Monitoring Devices Market Outlook
Buyer concentration across hospital procurement networks is rebalancing toward integrated delivery networks that negotiate enterprise-wide device contracts. Medtronic plc anchors its position through deep clinical channel relationships with these consolidated buyers. Abbott Laboratories differentiates via continuous glucose monitoring platforms that leverage in-house sensor production. Philips Healthcare sustains geographic dominance across European hospital systems with regulatory-compliant monitoring infrastructure.
Real time health monitoring devices comprise sensor-enabled systems that capture physiological parameters—heart rate, blood oxygen saturation, glucose levels, respiratory rate—at intervals ranging from seconds to minutes and transmit data via Bluetooth, Wi-Fi, or cellular protocols to clinical or consumer interfaces. Their primary commercial purpose is to enable early intervention, reduce acute care utilization, and shift care delivery toward outpatient and home settings. Wearable monitors occupy the largest volume position due to consumer familiarity and declining unit costs, while implantable devices capture concentrated margin pools in chronic disease management where reimbursement supports premium pricing. Remote patient monitoring represents the fastest-growing application segment as CMS reimbursement codes and similar mechanisms in other countries expand provider willingness to prescribe connected care.
FDA premarket notification pathways and EU MDR conformity assessment procedures shape product development timelines, testing requirements, and market access costs for manufacturers targeting the United States and European Union. Japan's PMDA and METI standards add a third regulatory layer that influences sensor accuracy specifications and software validation protocols for Asia-Pacific entry. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market surveillance obligations under MDR Article 83 as connected device liability frameworks mature.
Market Dynamics
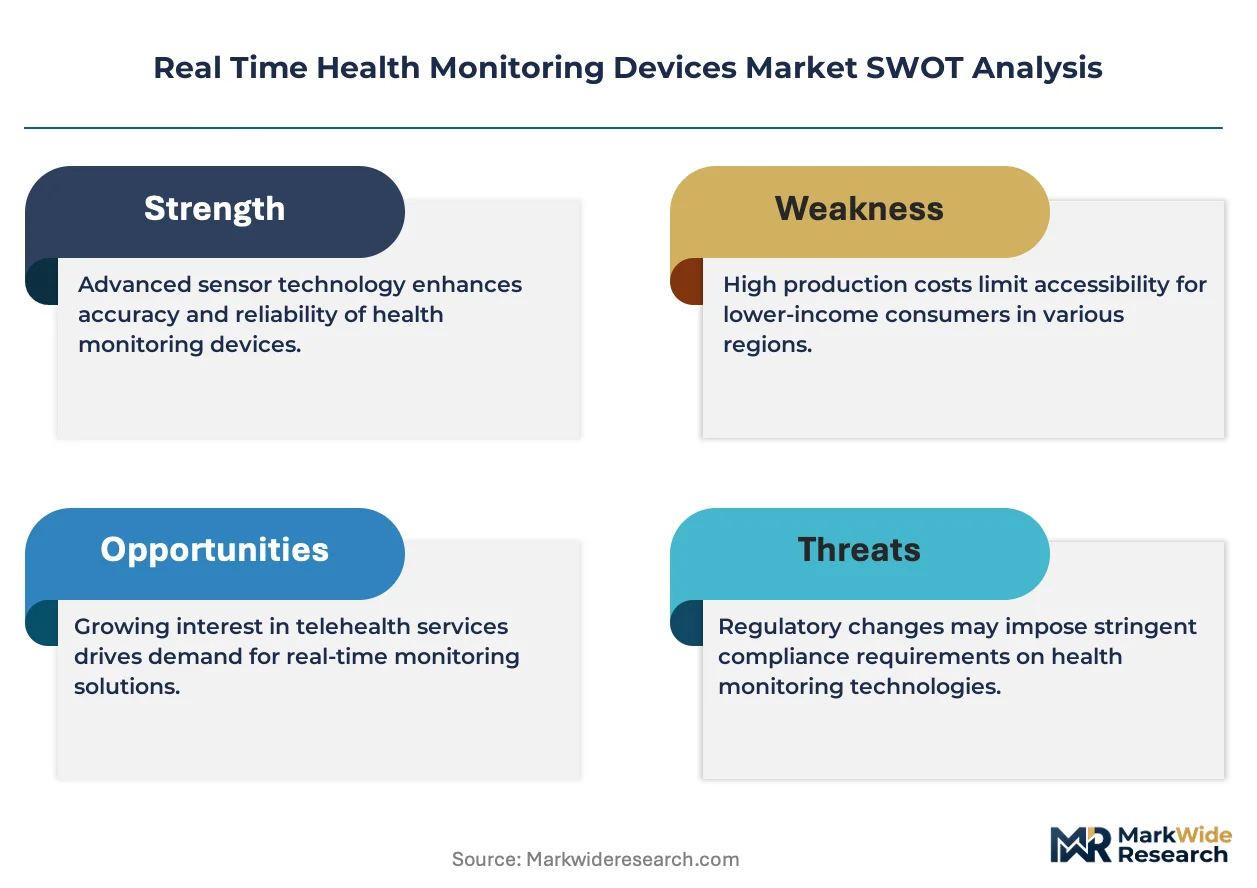
Hospital procurement consolidation is compressing vendor margins and forcing device manufacturers to restructure commercial organizations around integrated delivery networks rather than individual facility sales.
Growth Catalysts
- CMS reimbursement expansion:New remote patient monitoring billing codes in the United States are accelerating provider adoption of connected care systems for chronic disease populations.
- Wearable sensor miniaturization:Advances in microelectromechanical systems are enabling continuous multi-parameter monitoring from consumer-form-factor devices.
- Japan's super-aging society:METI incentives for home-based care infrastructure are driving institutional procurement of cellular-enabled monitoring platforms.
Market Restraints
- Semiconductor supply concentration:Dependence on Taiwan-based foundries for application-specific integrated circuits creates vulnerability in sensor module production.
- EU MDR conformity costs:Expanded clinical evidence requirements and notified body capacity constraints are extending time-to-market for European launches.
- Data interoperability limitations:Proprietary communication protocols between competing platforms prevent seamless electronic health record integration.
Strategic Opportunities
- India's tier-2 hospital networks:Underpenetrated secondary care facilities present whitespace for affordable Bluetooth-enabled vital sign monitors.
- AI-driven predictive analytics:Machine learning integration with continuous glucose monitoring data streams is opening reimbursement pathways for automated insulin delivery.
- Direct-to-consumer channels:Pharmacy retail partnerships and telehealth platforms are bypassing traditional durable medical equipment distributors.
Industry Challenges
- Cybersecurity engineering talent scarcity:FDA's evolving guidance on connected device security is outpacing available firmware development expertise.
- Legacy health information system integration:HL7 FHIR standard adoption gaps are forcing costly custom interface development for hospital deployments.
- Post-market surveillance capacity:EU MDR Article 83 mandates for systematic data collection are straining quality management resources at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real Time Health Monitoring Devices Market |
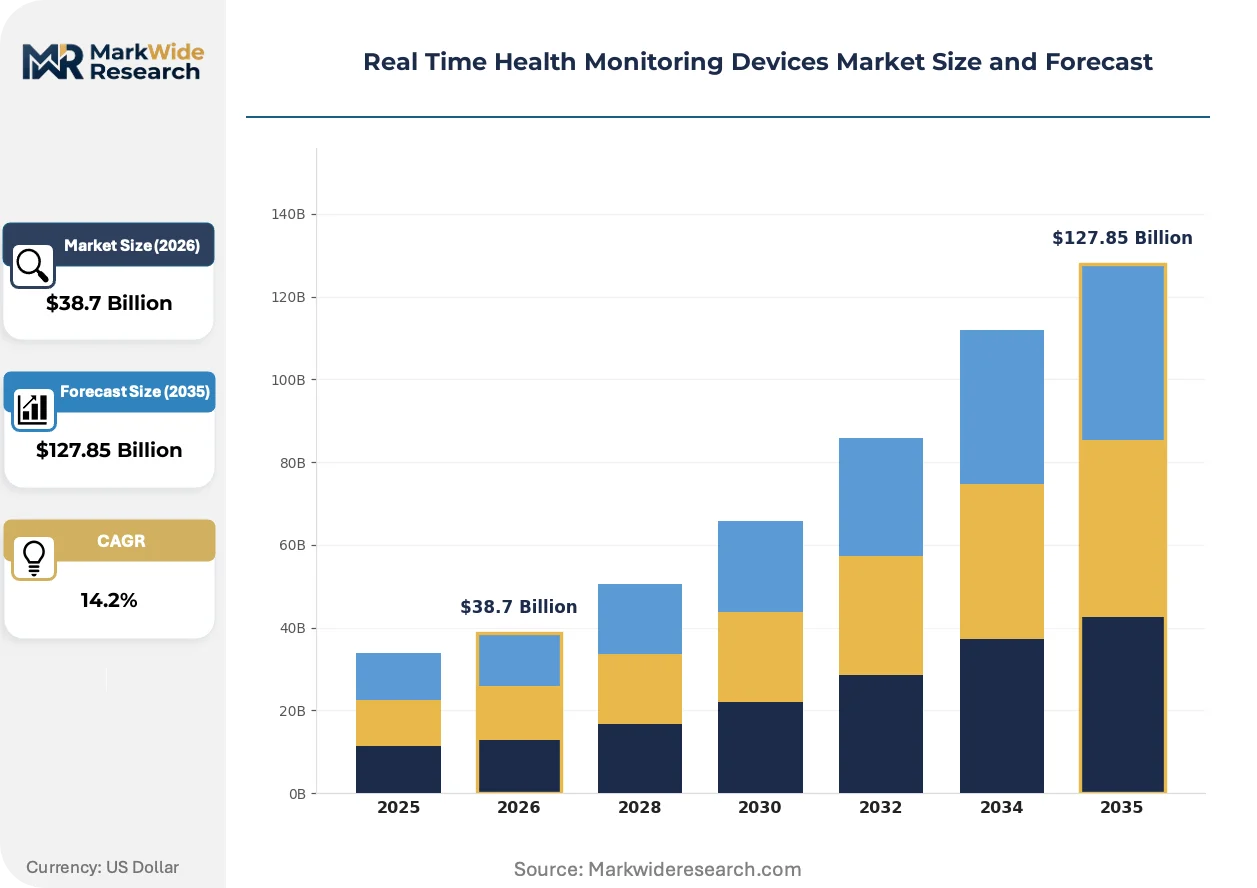
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wearable Monitors, Implantable Devices, Handheld Monitors, Smart Health Equipment Application: Chronic Disease Management, Fitness Tracking, Emergency Monitoring, Remote Patient Monitoring Technology: Bluetooth, Wi-Fi, Cellular, NFC End User: Patients, Healthcare Providers, Caregivers, Fitness Enthusiasts |
| Companies Covered | Apple Inc., Medtronic plc, Garmin Ltd., Samsung Electronics Co. Ltd., Fitbit Inc., Abbott Laboratories, GE Healthcare, Philips Healthcare, Dexcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real Time Health Monitoring Devices Market Strategic Shifts
Continuous biosensor platforms are displacing episodic point-of-care testing across multiple chronic conditions. This shift is compressing diagnostic cycles and redefining the boundary between consumer wellness and regulated medical devices.
Photoplethysmography is expanding into blood pressure estimation and atrial fibrillation detection from wrist-worn form factors. Cardiology departments in German hospital systems are piloting these optical sensors for post-discharge arrhythmia surveillance. The technology is expanding into applications previously requiring dedicated Holter monitors or invasive catheters.
FDA's 2023 cybersecurity guidance for premarket submissions is mandating software bill of materials and vulnerability management plans for all connected devices. Manufacturers are restructuring quality systems to incorporate threat modeling into design controls. The regulation is reshaping development timelines most acutely for startups lacking established regulatory affairs infrastructure.
Accountable care organizations are consolidating device procurement through single-source contracts spanning multiple hospital campuses. This concentration is displacing fragmented purchasing by individual departments and forcing vendors to restructure pricing and service models. The pattern is most visible in United States markets where Medicare Shared Savings Program participation drives standardization imperatives.
Real Time Health Monitoring Devices Market Segmentation
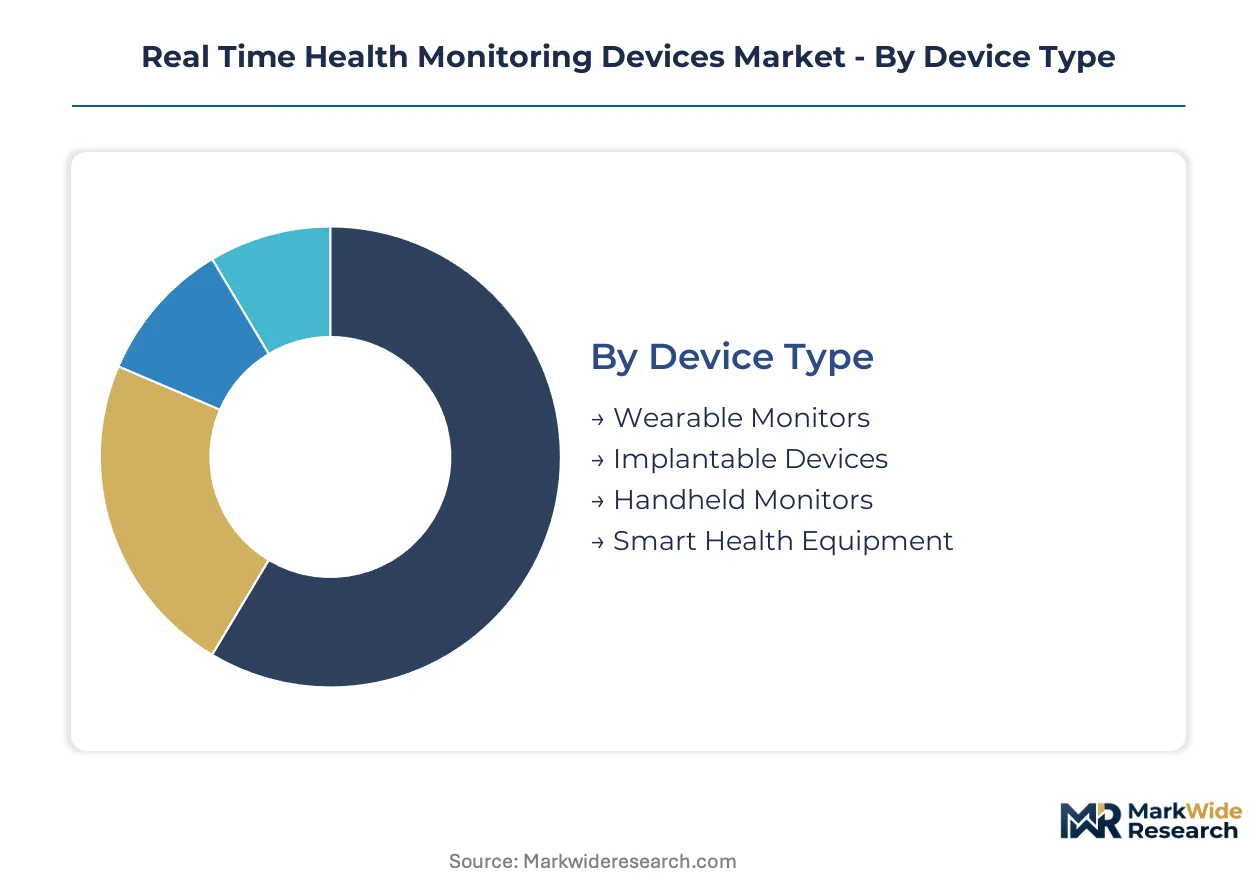
Segmentation reveals how procurement priorities diverge across clinical versus consumer use cases. Device specifications, connectivity protocols, and reimbursement pathways create distinct commercial theaters with non-overlapping buyer expectations.
Device Type:
Hospital procurement teams weight durability, regulatory clearance, and integration capacity against unit economics when selecting form factors for enterprise deployment.
- Wearable Monitors:Wrist-worn and patch-based sensors employing photoplethysmography and accelerometry capture heart rate, SpO2, and activity metrics continuously. Demand concentrates in United States accountable care organizations seeking CMS-reimbursable remote patient monitoring for heart failure and COPD populations where outpatient visibility reduces readmission penalties.
- Implantable Devices:Subcutaneous glucose sensors and cardiac monitors deliver multi-year continuous data streams through sealed biocompatible housings. German hospital systems prioritize these for diabetes and arrhythmia management where reimbursement supports premium pricing and long-term therapeutic relationships justify surgical placement costs.
- Handheld Monitors:Portable pulse oximeters, blood pressure cuffs, and single-lead ECG devices enable point-of-care measurement without continuous wear. India's tier-2 hospital networks drive procurement of affordable Bluetooth-enabled units for resource-constrained settings.
- Smart Health Equipment:Connected scales, blood pressure monitors, and sleep mats integrate with consumer mobile applications and clinical dashboards. Japanese METI incentives for home-based care infrastructure accelerate adoption of cellular-enabled platforms in super-aging municipalities.
Wearable monitors lead on scale; implantable devices lead on momentum.
Application:
Reimbursement code availability determines provider willingness to prescribe connected care across clinical scenarios.
- Chronic Disease Management:Continuous glucose monitoring for diabetes, remote cardiac monitoring for heart failure, and respiratory tracking for COPD require FDA-cleared or CE-marked devices with clinical workflow integration. United States Medicare Advantage plans expand coverage for these applications as risk-adjusted payment models reward outcome improvement.
- Remote Patient Monitoring:Multi-parameter vital sign surveillance with automated alerts to clinical teams enables early intervention before acute decompensation. This segment expands most quickly as CMS billing codes and similar mechanisms in Germany and Japan reduce provider financial risk for connected care deployment.
- Fitness Tracking:Consumer-oriented heart rate, sleep, and activity monitoring operates outside medical device regulation in most jurisdictions. Direct-to-consumer channels through pharmacy retail and telehealth platforms bypass traditional durable medical equipment distribution.
- Emergency Monitoring:Fall detection, panic buttons, and acute event alerting systems serve aging-in-place populations and institutional care facilities. Japanese municipal governments subsidize deployment in rural districts with limited acute care access.
Chronic disease management leads on scale; remote patient monitoring leads on momentum.
Technology:
Connectivity protocol selection balances power consumption, range, infrastructure requirements, and security architecture.
- Bluetooth:Low-energy protocols dominate wearable and handheld devices for personal area network transmission to smartphones or bedside hubs. United States hospital procurement prioritizes Bluetooth 5.0 and later for encrypted pairing and reduced interference in dense RF environments.
- Cellular:LTE-M and NB-IoT modules enable standalone operation without patient-managed intermediary devices. Japan's METI-specified home care platforms require cellular backhaul for reliable connectivity in elderly households lacking broadband.
- Wi-Fi:Higher bandwidth supports continuous multi-parameter streaming and firmware updates in institutional settings. German hospital systems standardize on WPA3-Enterprise security for Wi-Fi-connected bedside monitors.
- NFC:Near-field communication enables rapid device pairing, authentication, and localized data transfer. Fitness enthusiast applications leverage NFC for tap-to-sync with gym equipment and wellness kiosks.
Bluetooth leads on scale; cellular leads on momentum.
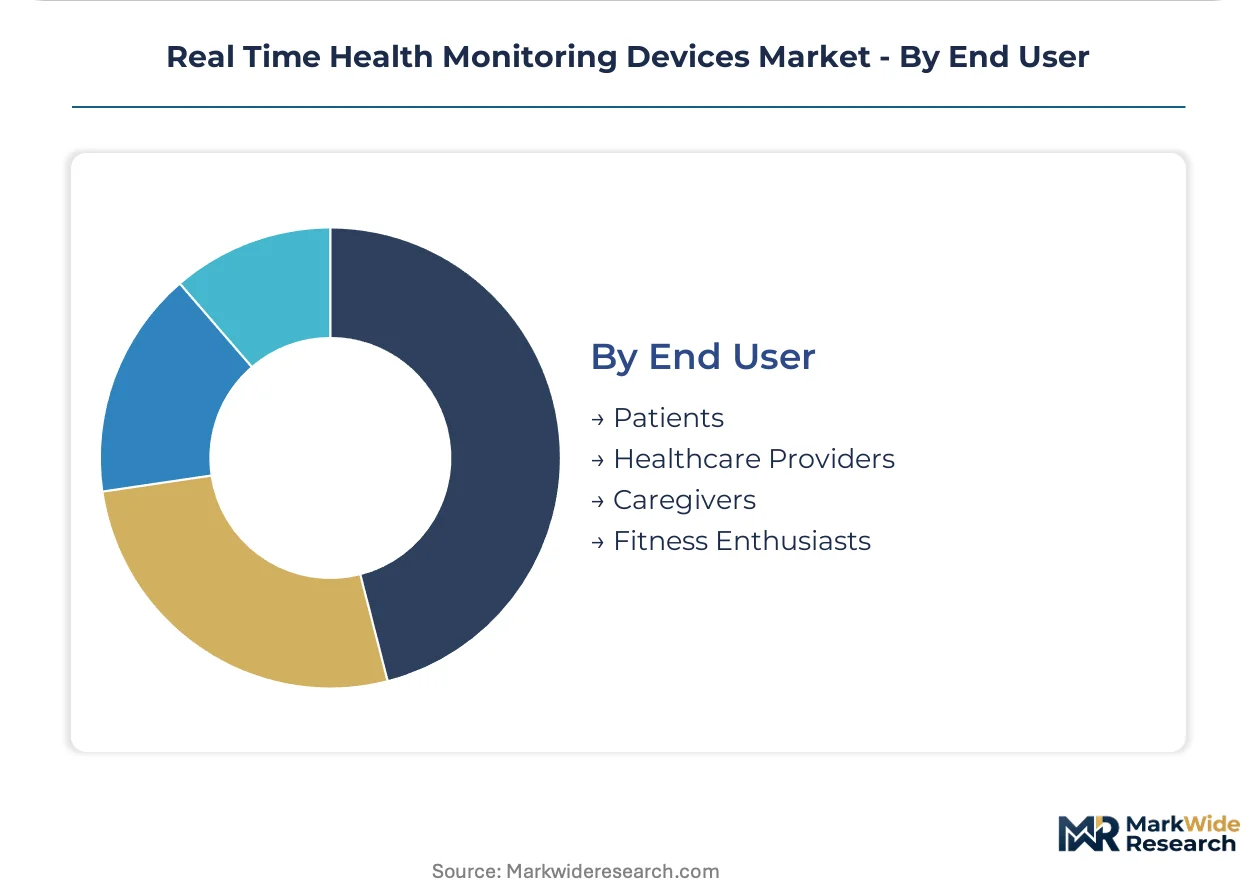
End User:
User technical sophistication, clinical oversight requirements, and payment responsibility shape device design and distribution strategy.
- Healthcare Providers:Hospitals, physician practices, and home health agencies require FDA-cleared or CE-marked devices with EHR integration, clinical decision support, and systematic data review workflows. United States integrated delivery networks negotiate enterprise contracts spanning multiple campuses.
- Patients:Individuals managing diagnosed conditions use prescribed devices with remote clinical oversight. Reimbursement eligibility and out-of-pocket cost sensitivity drive selection between premium and economy tiers.
- Caregivers:Family members and professional aides rely on simplified interfaces and alert systems for dependent populations. Japan's municipal home care programs distribute cellular-enabled monitors to informal caregivers in super-aging communities.
- Fitness Enthusiasts:Wellness-focused consumers purchase unregulated devices through retail and direct-to-consumer channels. These users prioritize aesthetic design, app ecosystem quality, and social sharing features over clinical accuracy.
Healthcare providers lead on scale; patients lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in Boston, Basel, and Singapore anchor device development pipelines. Regulatory science expertise concentrates near FDA headquarters in Maryland and EMA offices in Amsterdam. Manufacturing scale sits with contract electronics producers in Shenzhen and Penang.
United States
CMS reimbursement codes for remote patient monitoring drive hospital procurement of connected cardiac and respiratory devices. FDA's 2023 cybersecurity guidance mandates software bills of materials for all premarket submissions. The Minneapolis-St. Paul corridor hosts concentrated medical device design and regulatory affairs capabilities serving integrated delivery networks.
Germany
EU MDR conformity assessment requirements accelerate notified body specialization in clinical evidence evaluation. CE marking timelines extend as Article 83 post-market surveillance obligations strain quality management systems. The Baden-Württemberg region clusters precision sensor manufacturing and hospital system procurement headquarters for European distribution.
Japan
METI incentives for home-based care infrastructure target super-aging municipalities with limited acute care access. PMDA software validation protocols influence sensor accuracy specifications for Asia-Pacific market entry. The Kansai region around Osaka concentrates domestic device manufacturing and municipal procurement decision-making for elderly care programs.
India
Tier-2 hospital networks in Maharashtra and Gujarat present whitespace for affordable Bluetooth-enabled vital sign monitors. CDSCO medical device rules create registration pathways for imported sensor platforms with local assembly requirements. The Bengaluru electronics corridor hosts contract manufacturing for wearable form factors targeting price-sensitive clinical segments.
South Korea
MFDS fast-track approval pathways for AI-integrated diagnostic devices attract software developers from Seoul's digital health cluster. Government-funded smart hospital pilots in the capital region validate continuous monitoring platforms for export certification. The Pangyo Techno Valley concentrates health data analytics firms serving domestic chaebol medical device divisions.
Real Time Health Monitoring Devices Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct margin tiers. Hospital procurement consolidation favors vendors with enterprise-wide service capabilities and regulatory compliance infrastructure. Three archetypes dominate: integrated technology conglomerates with consumer electronics scale, dedicated medical device manufacturers with deep clinical channel relationships, and sensor technology specialists with proprietary hardware platforms. Competitive moves center on strategic partnerships with telehealth platforms and backward integration into MEMS fabrication.
Among diversified technology conglomerates, Apple Inc. and Samsung Electronics Co. Ltd. occupy positions leveraging consumer brand recognition and app ecosystem integration for wellness-adjacent monitoring. Medtronic plc anchors the dedicated medical device archetype through hospital system relationships and regulatory clearance depth. Abbott Laboratories exemplifies the sensor technology specialist model with in-house continuous glucose monitoring production. These three represent divergent strategic paths: consumer scale, clinical integration, and component control.
| Leading Market Players |
|---|
| Apple Inc. |
| Medtronic plc |
| Garmin Ltd. |
| Samsung Electronics Co. Ltd. |
| Fitbit Inc. |
| Abbott Laboratories |
| GE Healthcare |
| Philips Healthcare |
| Dexcom Inc. |
| Others |
Value Chain & Pricing Dynamics
United States integrated delivery networks concentrate procurement power through enterprise-wide device contracts, imposing subscription-plus-hardware bundling as the dominant pricing model across remote patient monitoring categories.
Pricing Analysis
Bundled service contracts encompassing hardware, connectivity, and clinical workflow integration command premium positioning against unbundled per-unit transactions. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared implantable sensors from Bluetooth-enabled wellness peripherals and unregulated fitness trackers. Cost compression in the standard tier intensifies because Taiwanese foundry capacity constraints elevate application-specific integrated circuit costs. Hospital procurement committees exhibit highest price sensitivity, while chronic disease patients under Medicare Advantage plans show greater willingness to absorb out-of-pocket costs for continuous glucose monitoring systems.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing and local-assembly requirements under CDSCO medical device rules are reshaping sourcing strategies for multinational vendors seeking price-competitive entry. Sensor module production draws from Taiwan, South Korea, and Malaysia, with MEMS fabrication and biocompatible housing materials feeding from these concentrated nodes. Single-source vulnerability in Taiwan-based foundry capacity for precision analog front-end chips threatens continuity planning. Distribution runs through durable medical equipment distributors in developed markets and direct-to-consumer pharmacy retail partnerships in wellness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA's 2023 cybersecurity guidance for premarket submissions and CMS reimbursement code expansions create sustained demand tailwinds for compliant device manufacturers.
For Market Incumbents: Anticipate margin compression from accountable care organization procurement consolidation by deepening clinical channel relationships with integrated delivery networks. Prioritize backward integration into MEMS sensor fabrication to defend against semiconductor supply concentration risks. Accelerate EU MDR Article 83 post-market surveillance infrastructure investments before notified body capacity constraints worsen.
For New Entrants and Emerging Players: India's tier-2 hospital procurement managers represent the most penetrable buyer archetype for affordable Bluetooth-enabled vital sign monitors with localized assembly partnerships. Direct-to-consumer telehealth platform integrations bypass entrenched durable medical equipment distribution. Target cellular-enabled home care platforms for Japan's super-aging municipalities where METI subsidies reduce customer acquisition costs.
For Investors and Strategic Acquirers: Hospital systems with captive risk-bearing entities are the most active acquirer in this space, seeking vertical integration into remote patient monitoring capabilities. Five-to-ten year viability hinges on regulatory clearance depth rather than consumer scale. Watch FDA cybersecurity enforcement actions as the inflection indicator for quality management system valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Compliance Pathway | Mandates software bill of materials for all connected device premarket submissions. |
| CE Marking Under EU MDR | Accelerates notified body specialization but extends time-to-market for European launches. |
| Hospital System Partnership | Secures enterprise-wide procurement contracts across integrated delivery network campuses. |
| Software Companion Development | Enables automated clinical decision support integration with EHR systems. |
| Reimbursement Strategy | Aligns device features with CMS billing codes for remote patient monitoring. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down sensor production tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists combined with secondary validation from FDA 510(k) filings, CMS Medicare claims data, EU MDR notified body registers, and hospital procurement databases. Cross-referencing shipment data from contract electronics manufacturers against reimbursement code utilization rates enables triangulation of installed base estimates.
Historical trendline analysis of device adoption curves across chronic disease populations informs projection modeling across the analysis window. Segmentation dimensions include device form factor, connectivity protocol, clinical application, and end-user technical sophistication. CAGRs derive from regression analysis of reimbursement expansion trajectories and sensor cost decline curves, with semiconductor foundry capacity utilization and regulatory approval velocity serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; FDA-cleared implantable devices carry tighter precision than unregulated fitness trackers due to mandatory adverse event reporting. Forecasts reflect assumptions about reimbursement code stability and foundry capacity expansion that regulatory shifts or geopolitical disruptions could revise. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Remote Home Monitoring Systems Market
Patient Monitoring
Respiratory Monitoring Market
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
Multi-Channel Remote ECG Monitors Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market
Patient Monitoring
AI in Remote Patient Monitoring Market
Patient Monitoring
Clinical Alarm Management Market
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
B-Ketone Monitoring System Market
Patient Monitoring
North America Patient Monitoring Market
Patient Monitoring
Italy Patient Monitoring Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market