
 Blood Group Typing Market | 2026-2036
Blood Group Typing Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Group Typing Market Analysis
Synthetic polymer-based microarray substrates are expanding their share in blood group typing consumables, displacing traditional glass-slide formats in high-throughput laboratories. Danaher Corporation leverages its diagnostics platform breadth to sustain instrument placement cycles across hospital transfusion services. Bio-Rad Laboratories, Inc. anchors its position through specialized reagent portfolios for extended antigen phenotyping. Grifols, S.A. dominates plasma-derived diagnostic supply chains in European blood banking networks.
Blood group typing encompasses serological and molecular methods for determining ABO, Rh, and extended red cell antigen profiles, typically employing hemagglutination reactions, gel card systems, or PCR-based allele-specific amplification with turnaround targets under four hours for emergency transfusion decisions. Reagent and kit segments capture recurring revenue from high-volume hospital blood banks, while instrument placements concentrate in centralized reference laboratories pursuing automated batch processing. Polymerase chain reaction technology leads growth in pre-transfusion genotyping, displacing manual serology for complex antibody investigations and alloimmunized patient cohorts.
The FDA governs blood grouping reagents as biologics under 21 CFR 660, while the EMA's In Vitro Diagnostic Regulation imposes clinical evidence requirements on serological test kits sold in European markets. WHO guidance on global blood safety standards shapes procurement specifications for developing-country blood bank infrastructure. Stakeholders must monitor regulatory divergence between FDA biologics pathways and EU IVDR conformity assessment timelines when planning multi-region product registrations.
Market Dynamics
Hospital transfusion services are consolidating reference laboratory contracts into integrated health networks, compressing procurement cycles and favoring vendors with full-platform diagnostics capabilities over specialized reagent suppliers.
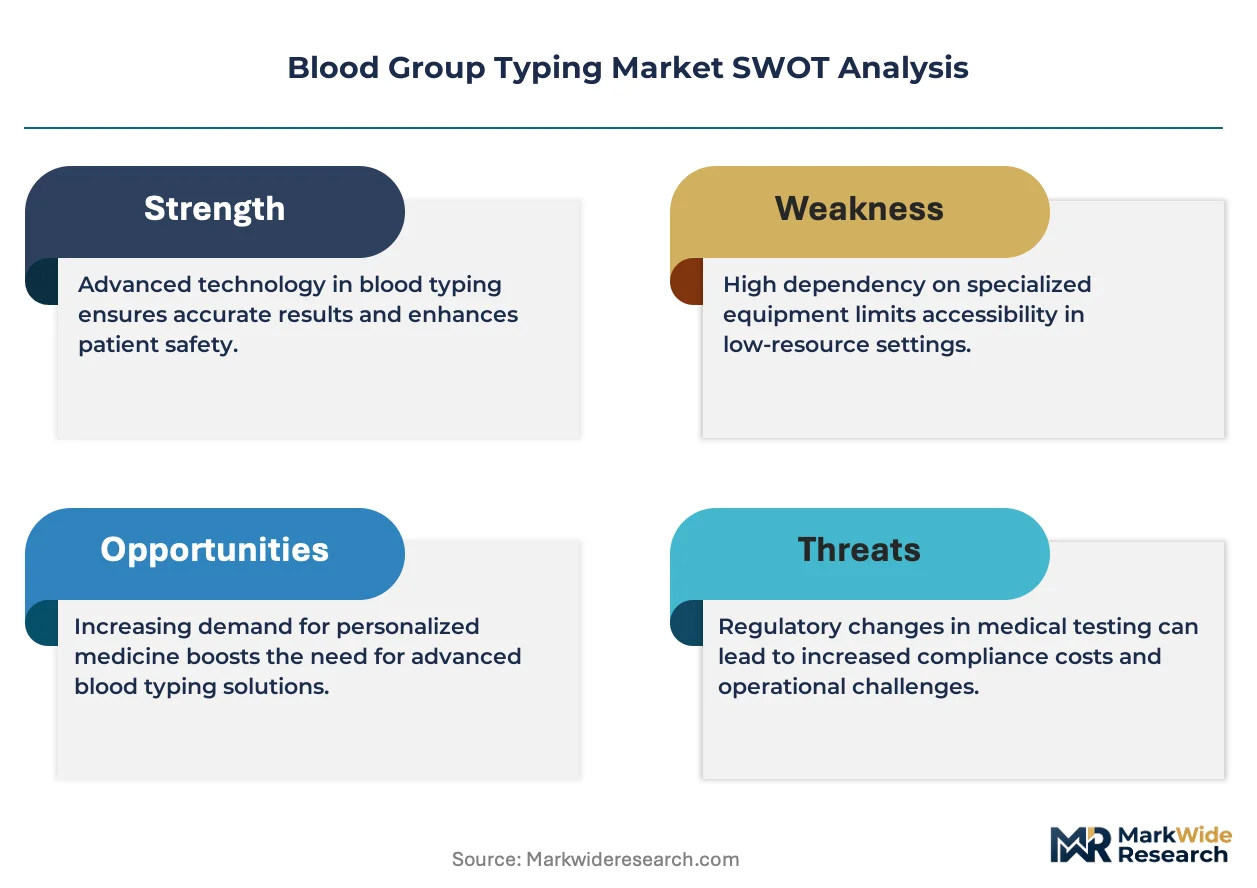
Growth Catalysts
- FDA Biologics Oversight:The FDA's blood banking safety mandates under 21 CFR 660 are tightening quality requirements for serological reagents, accelerating replacement of legacy testing platforms in hospital blood banks.
- Molecular Genotyping:PCR-based allele-specific amplification is displacing manual serology for complex antibody investigations, reducing turnaround times for emergency transfusion decisions.
- Integrated Health Networks:United States hospital systems are consolidating reference laboratory contracts, creating pull-through demand for automated batch processing instruments.
Market Restraints
- Reagent Supply Concentration:Plasma-derived diagnostic supply chains concentrate in European blood banking networks, creating vulnerability to raw material sourcing disruptions.
- EMA IVDR Compliance Costs:The EMA's In Vitro Diagnostic Regulation imposes clinical evidence requirements that extend conformity assessment timelines and raise registration expenses for serological test kits.
- Glass-Substrate Obsolescence:Traditional glass-slide microarray formats face displacement by synthetic polymer substrates, stranding capital investments in legacy high-throughput laboratory equipment.
Strategic Opportunities
- Extended Antigen Phenotyping:Specialized reagent portfolios for rare blood type identification represent underpenetrated white space in alloimmunized patient cohorts.
- Pre-Transfusion Genotyping:Molecular typing platforms offer expansion potential in emergency medicine workflows where four-hour turnaround targets create premium pricing power.
- WHO Procurement Standards:Developing-country blood bank infrastructure projects aligned with WHO global blood safety guidance create tender opportunities for instrument-reagent bundled offerings.
Industry Challenges
- Molecular Diagnostics Talent Gap:PCR-based allele-specific amplification requires specialized laboratory personnel that hospital transfusion services struggle to recruit and retain.
- Multi-Region Registration Divergence:Stakeholders must navigate asynchronous FDA biologics pathways and EU IVDR conformity assessment timelines when planning product registrations.
- Automated Batch Integration Complexity:Centralized reference laboratories face technical friction connecting new molecular typing platforms to legacy laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Group Typing Market |
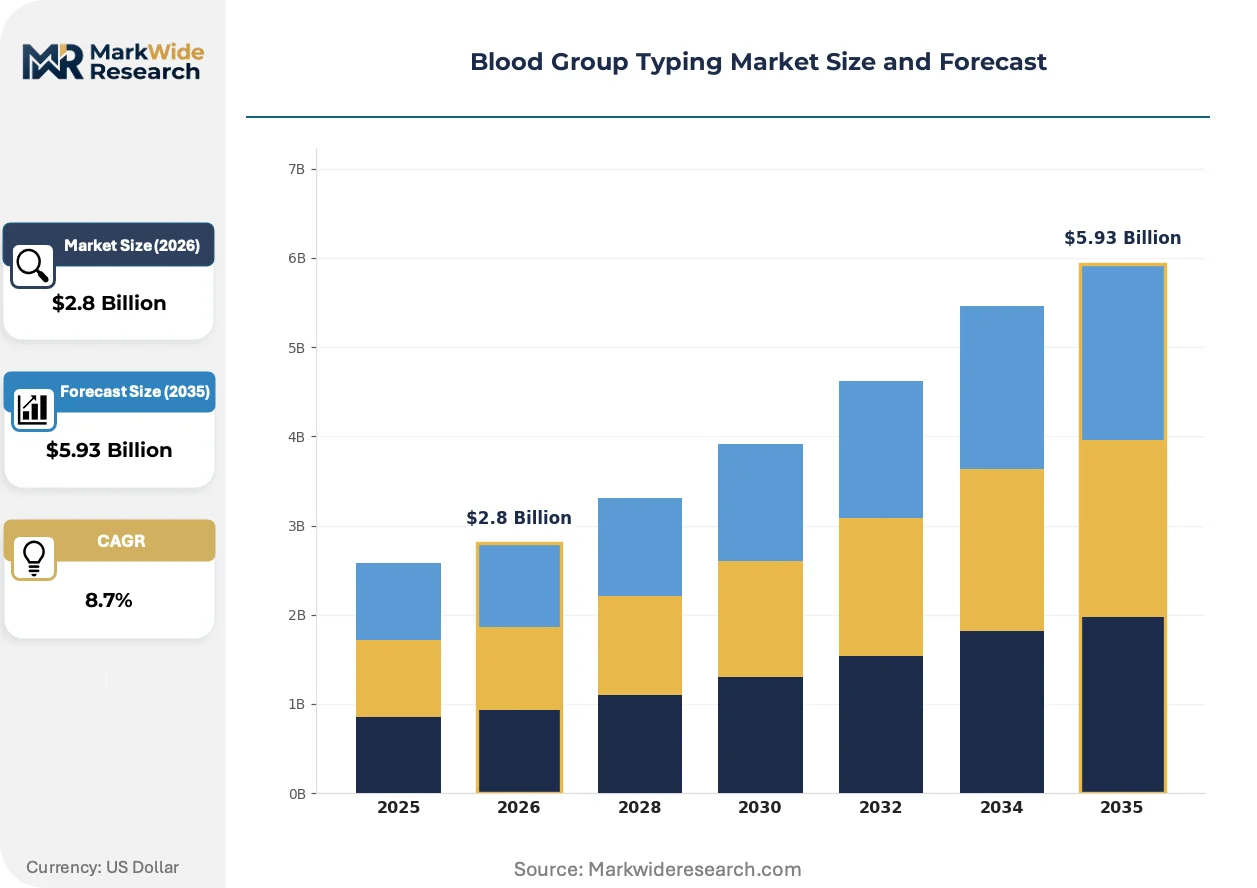
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Software Technology: Polymerase Chain Reaction, Microscopy, Flow Cytometry, Enzyme-Linked Immunosorbent Assay End User: Hospitals, Blood Banks, Diagnostic Laboratories, Research Institutions Application: Transfusion, Antenatal Testing, Organ Transplantation, Paternity Testing |
| Companies Covered | Ortho Clinical Diagnostics, Danaher Corporation, Bio-Rad Laboratories, Inc., Merck KGaA, Thermo Fisher Scientific, Grifols, S.A., Immucor, Inc., Quotient Limited, QuidelOrtho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Group Typing Market Emerging Trajectories
Synthetic polymer-based microarray substrates are actively reshaping consumable specifications in high-throughput blood typing laboratories, while regulatory divergence between FDA biologics and EU IVDR frameworks is compressing product development timelines.
PCR-based pre-transfusion genotyping is unifying serological and molecular workflows into single-platform diagnostics. Hospital transfusion services in integrated United States health networks are adopting these systems at accelerated replacement cycles. This convergence is unifying instrument procurement decisions, favoring vendors with comprehensive reagent portfolios over point-solution specialists.
The EMA's In Vitro Diagnostic Regulation is imposing clinical evidence requirements on serological test kits sold in European markets. Manufacturers must now generate performance data comparable to medical device standards, extending time-to-market for new reagent introductions. Extended antigen phenotyping kits face the steepest compliance burden, prompting some suppliers to prioritize United States FDA biologics pathways first.
Reference laboratory procurement is consolidating toward multi-year sole-source agreements with full-platform vendors. Hospital blood banks are unbundling after-sales service contracts from instrument purchases, creating standalone revenue streams for technical support specialists. This pattern is most visible in United States metropolitan health networks where integrated delivery systems command pricing leverage through volume commitments.
Blood Group Typing Market Segmentation
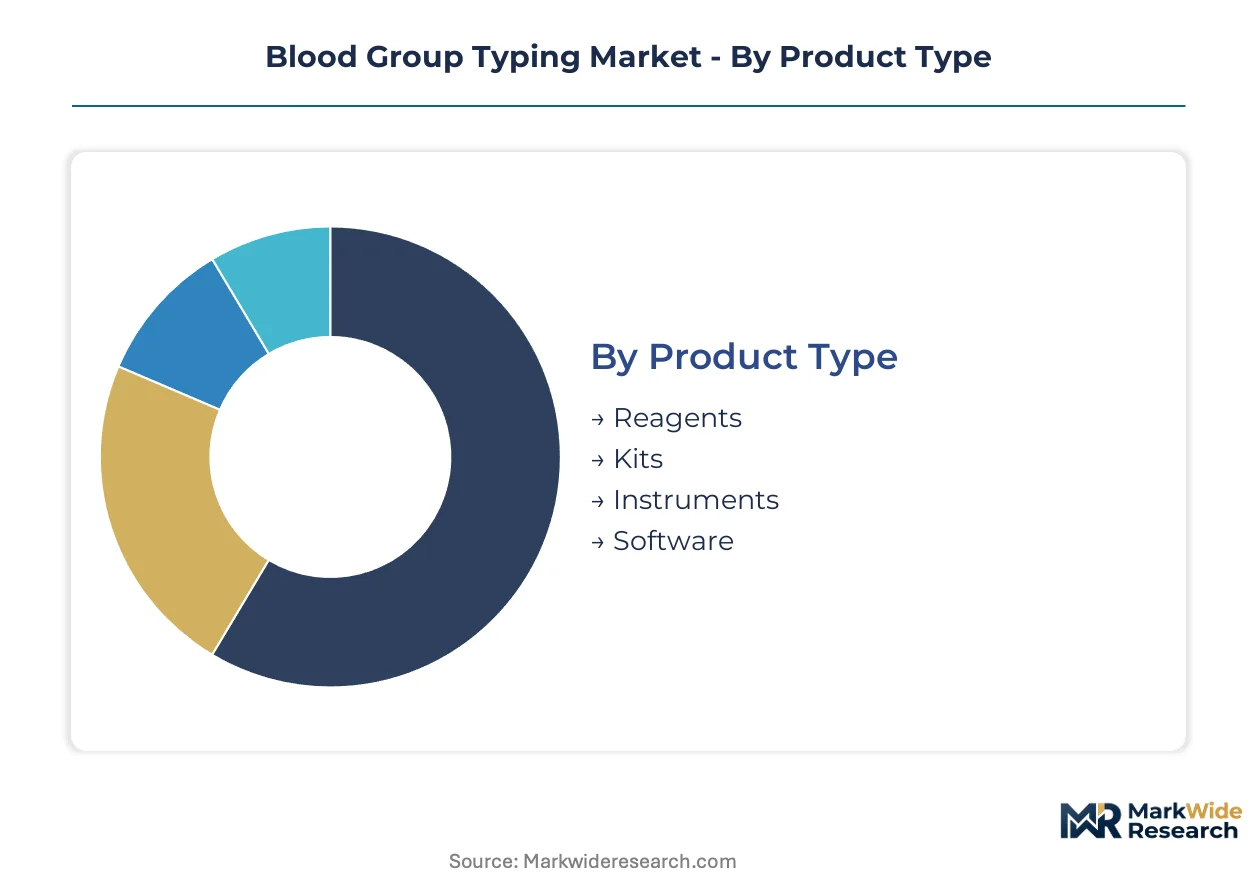
Blood group typing markets fragment across consumable replenishment cycles, capital equipment refresh timelines, and service-intensive software implementations. Each segment carries distinct procurement rhythms and margin structures that shape vendor positioning strategies.
Product Type:
Volume-driven consumables dominate transaction frequency while instrument placements concentrate capital deployment in centralized laboratories.
- Reagents:Plasma-derived serological reagents and synthetic polymer-based formulations constitute the recurring revenue backbone. Hospital blood banks in the United States consume these at weekly replenishment intervals under sole-source agreements with reference laboratories.
- Kits:Extended antigen phenotyping kits and emergency transfusion panels command premium pricing in alloimmunized patient cohorts. European networks under EMA IVDR compliance requirements face extended conformity assessments for new kit introductions.
- Instruments:Automated batch processing platforms serve consolidated health network contracts.
- Software:Laboratory information management system integrations enable workflow unification.
Mature deployment sits with Reagents. Newer deployment is concentrated in Software.
Technology:
Diagnostic modality selection hinges on turnaround time requirements and personnel specialization availability across end-use settings.
- Polymerase Chain Reaction:Allele-specific amplification protocols displace manual serology for complex antibody investigations. United States emergency medicine workflows leverage PCR platforms to meet four-hour transfusion decision targets.
- Microscopy:Traditional hemagglutination observation persists in resource-constrained settings.
- Flow Cytometry:High-throughput antigen profiling serves reference laboratory batch processing.
- Enzyme-Linked Immunosorbent Assay:Solid-phase antibody detection supports extended phenotyping panels.
Established infrastructure favors Microscopy. Capability expansion is climbing the fastest in Polymerase Chain Reaction.
End User:
Procurement authority consolidation is compressing vendor access channels toward integrated delivery systems.
- Hospitals:Transfusion services within United States metropolitan health networks command pricing leverage through multi-year volume commitments. These facilities unbundle after-sales service contracts from instrument purchases.
- Blood Banks:European plasma-derived diagnostic supply chains concentrate procurement in Grifols-dominated networks.
- Diagnostic Laboratories:Centralized reference sites pursue automated platform standardization.
- Research Institutions:Extended antigen discovery programs drive specialized reagent demand.
Contract consolidation centers on Hospitals. Technical capability building is gaining share fastest in Diagnostic Laboratories.
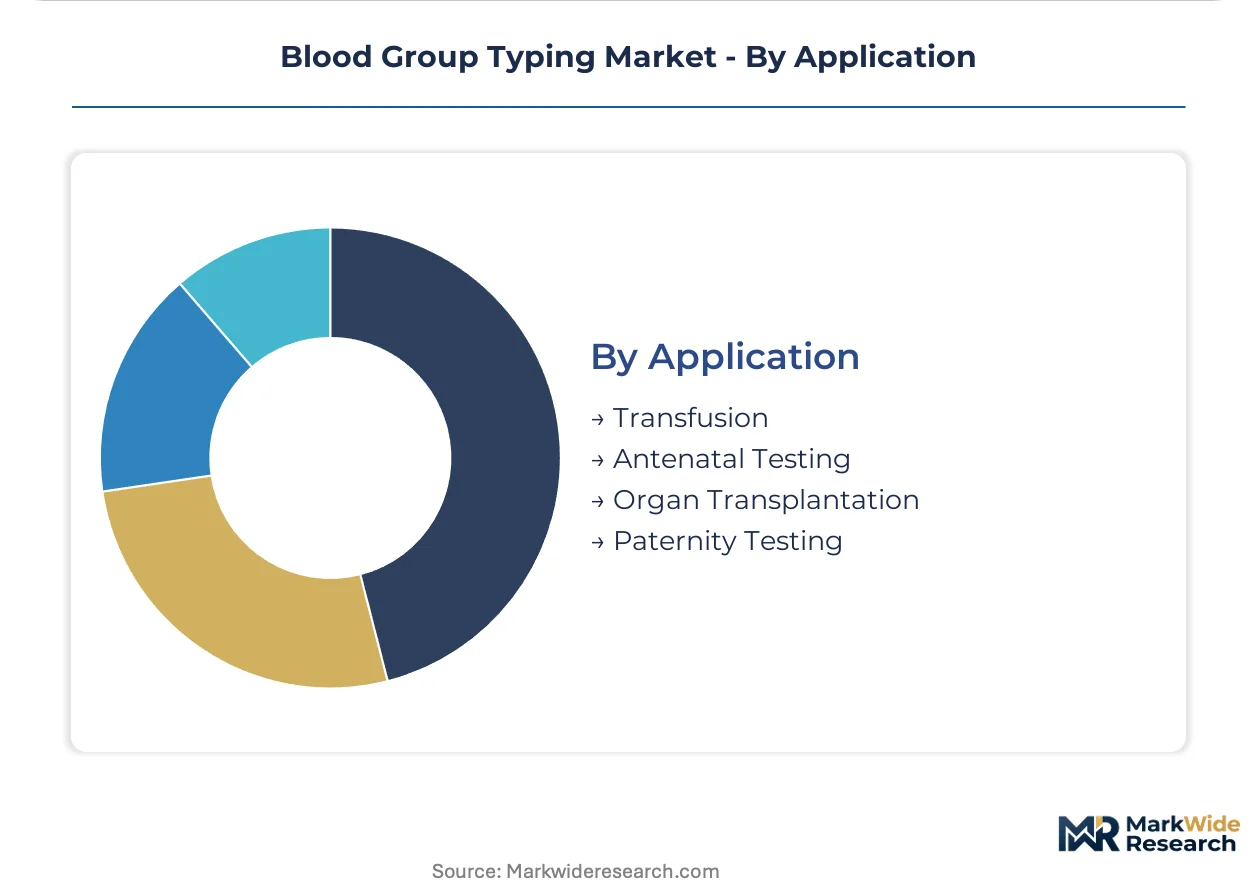
Application:
Clinical urgency gradients create pricing power differentiation across use cases.
- Transfusion:Pre-transfusion compatibility testing represents the highest-volume application with stringent turnaround requirements. FDA biologics oversight under 21 CFR 660 governs reagent quality for emergency transfusion decisions.
- Antenatal Testing:Rh and extended antigen screening prevents hemolytic disease of the newborn.
- Organ Transplantation:Histocompatibility matching integrates blood typing with tissue cross-matching protocols.
- Paternity Testing:ABO and Rh profiling supports forensic and legal use cases.
Regulatory stringency peaks in Transfusion. Service expansion is expanding most quickly in Organ Transplantation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated health networks in the United States concentrate procurement authority for blood group typing systems, while European plasma-derived reagent supply chains and Asian molecular diagnostics expansion create distinct regional competitive dynamics.
United States
Metropolitan health networks in the United States consolidate reference laboratory contracts into multi-year sole-source agreements. FDA biologics oversight under 21 CFR 660 mandates quality standards for serological reagents used in emergency transfusion decisions. Hospital transfusion services in cities like Houston, Boston, and Los Angeles unbundle after-sales service contracts from instrument purchases.
Germany
German hospital systems prioritize automated batch processing platforms for centralized blood bank operations. EMA In Vitro Diagnostic Regulation compliance extends conformity assessment timelines for serological test kit introductions. The Rhine-Ruhr metropolitan region hosts reference laboratories pursuing PCR-based allele-specific amplification for complex antibody investigations.
Japan
Japanese medical institutions adopt molecular typing platforms for extended antigen phenotyping in alloimmunized patient cohorts. PMDA regulatory frameworks govern in vitro diagnostic reagent approvals with clinical evidence requirements. Tokyo-Osaka medical corridors concentrate demand for four-hour turnaround emergency transfusion genotyping systems.
China
Chinese tertiary hospitals expand molecular diagnostics capabilities for pre-transfusion compatibility testing. NMPA oversight of in vitro diagnostic reagents imposes registration requirements on serological test kit manufacturers. The Yangtze River Delta cluster around Shanghai drives adoption of automated blood typing instruments in consolidated health systems.
United Kingdom
UK National Health Service blood and transplant services standardize procurement across regional transfusion centers. MHRA regulations align with EMA IVDR frameworks for serological reagent quality assurance. London and Birmingham host reference laboratories integrating PCR-based workflows with legacy laboratory information management systems.
Blood Group Typing Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-platform vendors capturing consolidated health network contracts while reagent specialists defend niche phenotyping portfolios. The vendor base organizes around three strategic archetypes: diversified diagnostics conglomerates with instrument-reagent bundling capabilities, pure-play blood banking specialists with plasma-derived supply chain control, and molecular diagnostics entrants displacing manual serology. Competitive moves concentrate on multi-year sole-source agreement pursuit and synthetic polymer substrate substitution for legacy glass-slide formats.
Among diversified diagnostics conglomerates, Danaher Corporation and Thermo Fisher Scientific occupy positions enabling instrument placement cycles across hospital transfusion services. Grifols, S.A. exemplifies the plasma-derived supply chain specialist archetype dominating European blood banking networks. Bio-Rad Laboratories, Inc. represents the extended antigen phenotyping specialist tier anchoring reagent portfolio positions in reference laboratory markets.
| Leading Market Players |
|---|
| Ortho Clinical Diagnostics |
| Danaher Corporation |
| Bio-Rad Laboratories, Inc. |
| Merck KGaA |
| Thermo Fisher Scientific |
| Grifols, S.A. |
| Immucor, Inc. |
| Quotient Limited |
| QuidelOrtho Corporation |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up diagnostics specialists control instrument placement cycles across United States hospital networks, translating capital deployment discipline into pricing power over reagent replenishment contracts and service unbundling strategies.
Pricing Analysis
Volume-driven consumables trade at thin margins while extended antigen phenotyping kits capture premium pricing in alloimmunized cohorts. Three-tier pricing structure across emergency-transfusion premium, standard hospital blood bank, and research-economy levels reflects FDA biologics certification grade and after-sales service bundling. Cost compression in standard serological reagents is intensifying because synthetic polymer substrates displace legacy glass formats. Reference laboratories show lowest price sensitivity due to sole-source agreement lock-in, while developing-country blood banks face acute budget constraints.
Supply Chain Analysis
EMA IVDR and FDA 21 CFR 660 qualification gating concentrates plasma-derived reagent supply in Spain, Germany, and the United States. Manufacturing draws from donor plasma networks, synthetic polymer substrate foundries, and PCR enzyme suppliers. Single-source vulnerability runs through European plasma collection networks dominated by Grifols-dominated supply chains. Distribution runs through integrated health network procurement committees and WHO-aligned tender processes for developing-country infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over plasma-derived reagent supply chains and molecular diagnostics talent pools determines pricing power across consolidated hospital contracts.
For Market Incumbents: Acquire specialized PCR-based genotyping platforms to anchor sole-source agreements before molecular entrants displace serology in emergency transfusion workflows. Deepen backward integration into synthetic polymer substrate manufacturing to offset glass-substrate obsolescence risk. Secure captive supply of donor plasma networks in European markets where EMA IVDR compliance extends competitor time-to-market. For New Entrants and Emerging Players: Begin with extended antigen phenotyping kits for alloimmunized patient cohorts where specialized reagent portfolios face lower regulatory burden than transfusion-critical applications. Target developing-country blood bank infrastructure tenders aligned with WHO procurement standards. Pursue instrument-reagent bundled offerings to bypass entrenched sole-source relationships in United States metropolitan health networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor molecular diagnostics entrants with PCR platform capabilities in Japanese and Chinese markets where PMDA and NMPA pathways offer faster approval than EMA IVDR conformity assessments. Long-term viability hinges on automation integration with legacy laboratory information management systems. Watch FDA guidance updates on biologics oversight as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Supply Network Acquisition | Secures raw material access for European reagent manufacturing under EMA traceability requirements. |
| PCR Platform Integration | Unifies serological and molecular workflows into single-instrument procurement decisions for hospital networks. |
| Synthetic Polymer Substrate Manufacturing | Displaces glass-slide formats and captures consumable margin expansion in high-throughput laboratories. |
| WHO-Aligned Tender Participation | Opens developing-country blood bank infrastructure contracts outside consolidated health network procurement. |
| After-Sales Service Unbundling | Creates standalone revenue streams as United States hospitals separate technical support from instrument purchases. |
Methodological Framework
Multi-period observation of instrument placement cycles, reagent replenishment intervals, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with blood bank directors, transfusion service chiefs, reference laboratory managers, and diagnostics procurement officers at integrated health networks. Secondary validation drew from FDA 21 CFR 660 filings, EMA IVDR conformity assessment databases, WHO blood safety guidance documents, and hospital GPO contract disclosures. Bottom-up transaction modeling triangulated against top-down market sizing across product type, technology modality, and end-user concentration dimensions.
Input-output matrix architecture mapped consumable replenishment velocity to instrument installed base expansion, segmenting projections across serological reagent, molecular kit, automated platform, and software integration categories. CAGRs derived from weighted average of historical placement cycle compression and replacement acceleration assumptions. Forecast inputs incorporated EMA IVDR compliance timeline uncertainty, FDA biologics oversight stringency indices, and integrated health network contract consolidation patterns.
Regulatory divergence between FDA and EMA pathways, plasma supply network disruptions, and molecular diagnostics talent scarcity are the dominant revision risks warranting model reassessment. Forecasts reflect documented assumptions on procurement consolidation velocity and technology substitution elasticities. A model refresh is warranted upon material change in FDA biologics enforcement posture or EMA IVDR transitional period extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Immune Response Testing Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
Clinical Microbiology Market
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market
Clinical Diagnostics
Europe Colorectal Cancer Screening Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Food Allergy Diagnosis and Treatment Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market
Clinical Diagnostics
Global Cardiac Marker Testing Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Clinical Diagnostic Equipment Market
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
Bacterial and Viral Specimen Collection Market