
 Global Respiratory Disease Testing Market | 2026-2036
Global Respiratory Disease Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Respiratory Disease Testing Market Foresight
Asset-light leasing models for PCR and molecular diagnostic platforms is reconfiguring capital deployment across the respiratory testing value chain. Thermo Fisher Scientific leverages its installed base of thermal cyclers to sustain recurring consumable revenue streams. Siemens Healthineers anchors hospital lab automation through integrated sample-to-answer workflows. Qiagen competes in nucleic acid extraction chemistry, a segment where reagent pull-through determines profitability.
Respiratory disease testing encompasses laboratory and point-of-care methods for detecting bacterial, viral, and fungal pathogens affecting the pulmonary system, with PCR-based molecular assays achieving analytical sensitivity below 10 copies per reaction for targets such as influenza A/B and respiratory syncytial virus. The primary commercial purpose centers on enabling clinicians to differentiate infectious etiologies, guide antimicrobial stewardship, and satisfy public health surveillance mandates. Molecular test types command premium pricing due to multiplexing capabilities and rapid turnaround requirements during respiratory virus season. Point of care clinics represent the fastest-expanding testing setting as decentralized diagnosis reduces emergency department burden. Lateral flow assay technology occupies the economy tier for screening applications where sensitivity trade-offs are clinically acceptable.
FDA premarket notification pathways under 21 CFR Part 820 shape quality system requirements for US manufacturers, while the EU In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for CE-marked devices entering European markets. Japan's PMDA enforces post-market surveillance protocols that extend validation obligations well beyond initial approval. ISO 15189 accreditation for clinical laboratories creates downstream demand for standardized control materials and external quality assessment programs. Stakeholders must weigh regulatory capital requirements against the margin compression risk as automated platforms commoditize basic respiratory panel testing.
Market Dynamics
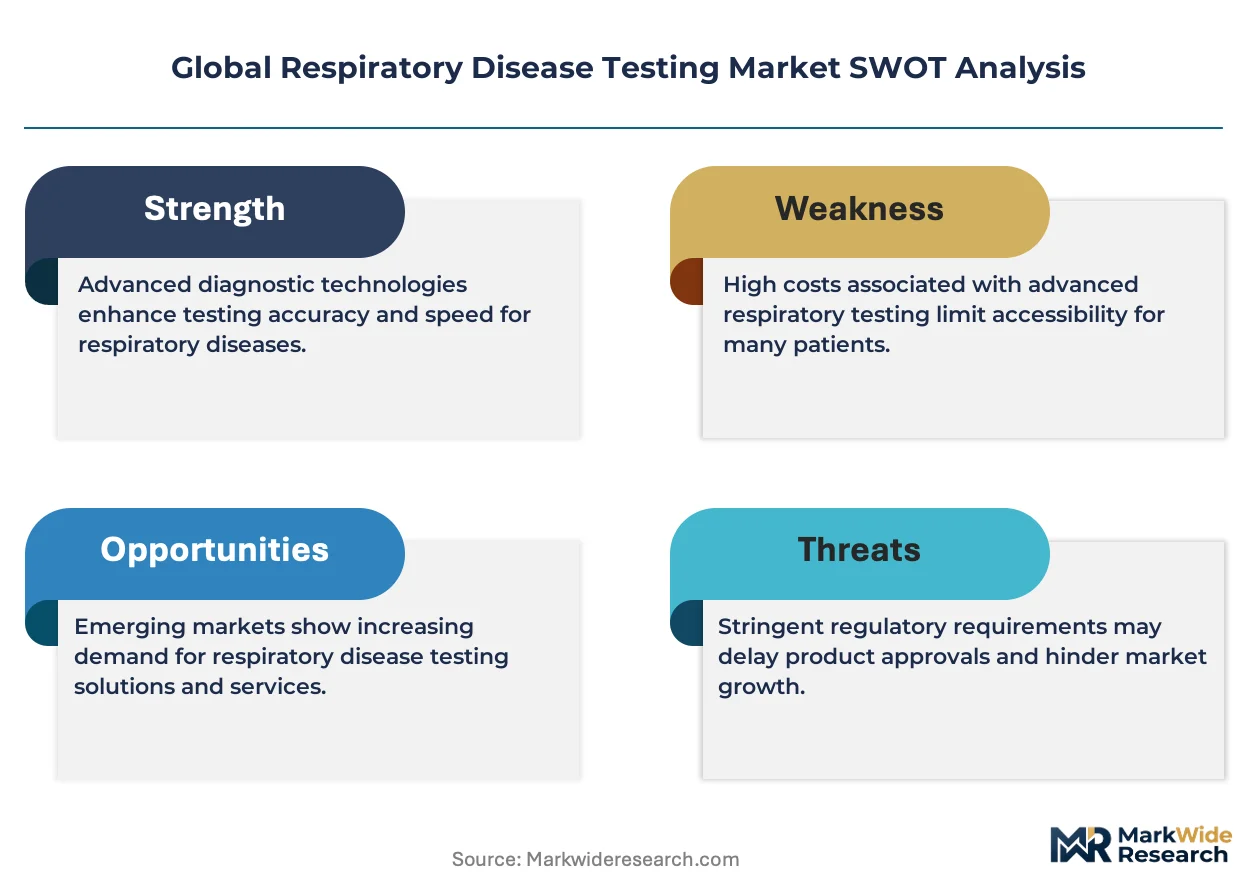
Decentralized diagnostic networks are fragmenting testing volumes away from centralized hospital laboratories toward point-of-care settings and retail clinics, compressing reimbursement rates while demanding faster turnaround times.
Growth Catalysts
- FDA Emergency Use Authorization Framework:Accelerated approval pathways for multiplex respiratory panels during viral surges compress commercialization timelines from years to months.
- Antimicrobial Stewardship Mandates:Hospital systems in the United States and Germany deploy rapid molecular diagnostics to reduce inappropriate antibiotic prescribing and satisfy Joint Commission metrics.
- PCR Platform Miniaturization:Benchtop thermal cycler footprints below 0.25 cubic meters enable placement in urgent care clinics previously excluded from molecular testing.
Market Restraints
- Reagent Supply Concentration:Nucleic acid extraction chemistry production clusters in German and Swiss contract manufacturers, creating single-source vulnerability for panel producers.
- Reimbursement Compression:Medicare's Clinical Laboratory Fee Schedule cuts molecular respiratory panel rates below the cost of goods for mid-complexity assays.
- Lateral Flow Substitution:Low-sensitivity rapid antigen tests capture screening volumes during low-prevalence periods, displacing molecular confirmation testing.
Strategic Opportunities
- Home-Based Collection Infrastructure:Self-administered nasal swab programs with mail-back PCR processing penetrate underinsured populations in Brazil and Mexico.
- AI-Assisted Interpretation:Machine learning algorithms integrated with digital PCR platforms automate cycle threshold analysis and reduce technician training burdens.
- EU IVDR Transition Window:Stricter clinical evidence requirements for CE-marked devices create first-mover advantage for manufacturers with pre-2027 validated dossiers.
Industry Challenges
- Multiplex Assay Validation Burden:Clinical laboratories must verify 15-22 pathogen targets per respiratory panel under CAP checklist requirements, extending implementation timelines.
- Legacy LIS Integration Friction:Point-of-care molecular instruments require HL7 interface development with hospital information systems that lack modern API architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Respiratory Disease Testing Market |
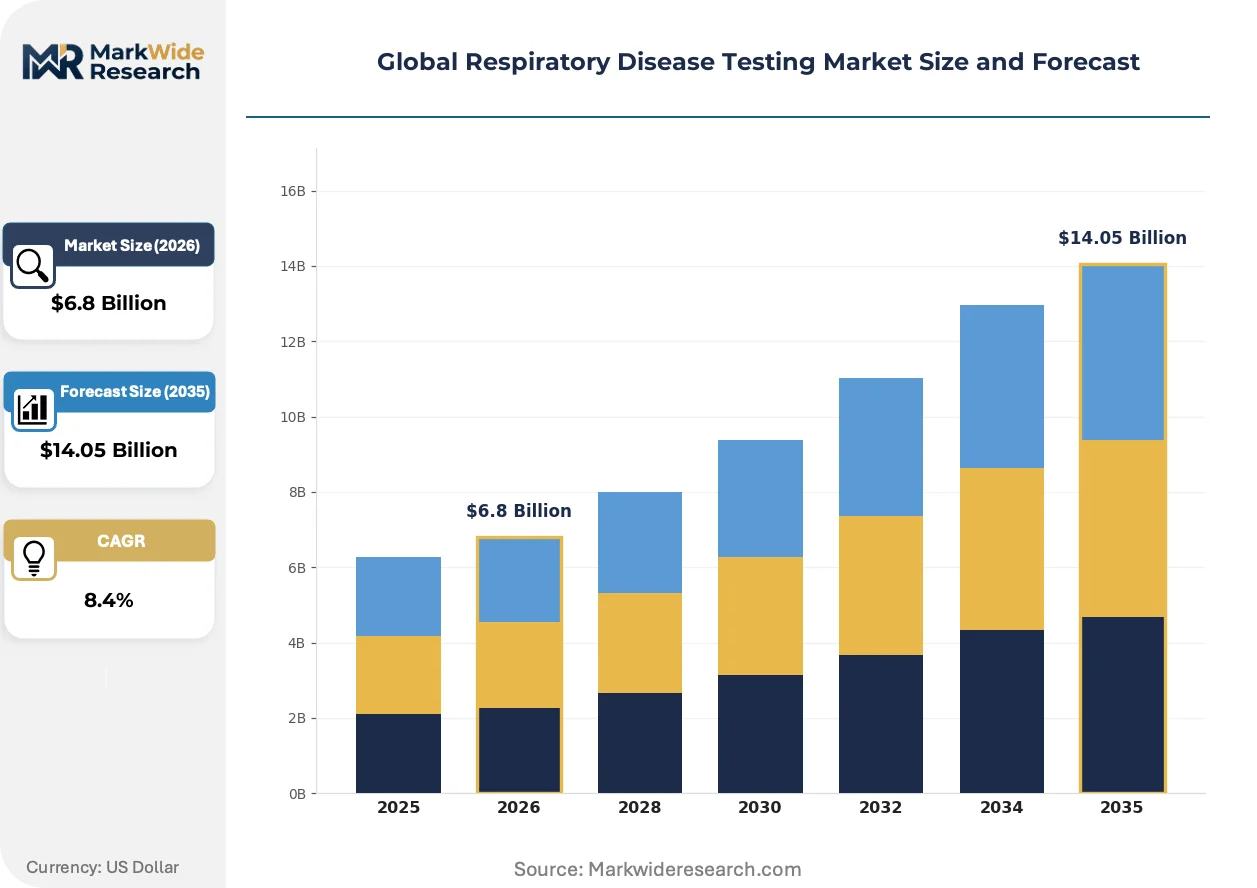
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Molecular, Serological, Antigen, Culture, Imaging Technology: PCR, ELISA, Lateral Flow Assay, Immunofluorescence, Microarray Testing Setting: Hospital Labs, Diagnostic Centers, Home Care, Point of Care Clinics, Mobile Labs End User: Clinical Laboratories, Research Institutes, Diagnostic Companies, Public Health Agencies, Blood Banks |
| Companies Covered | Abbott Laboratories, Thermo Fisher Scientific, Siemens Healthineers, Becton Dickinson and Company, Koninklijke Philips, ResMed, Qiagen, GE Healthcare, bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Respiratory Disease Testing Market Shifts & Advancements
Cloud-connected diagnostic instruments are collapsing the distance between sample acquisition and specialist interpretation, enabling remote quality control and real-time epidemiological surveillance without physical infrastructure expansion.
Digital PCR technology is virtualizing the quantification workflow for respiratory viral loads, replacing endpoint fluorescence with droplet partitioning that eliminates standard curve dependencies. Reference laboratories in the United States and Japan are adopting these platforms for immunocompromised patient monitoring where precise copy number detection guides antiviral therapy decisions. This shift is virtualizing the role of centralized quantitative testing, allowing satellite labs to perform reference-grade assays without capital-intensive real estate.
The EU In Vitro Diagnostic Regulation imposes post-market performance monitoring obligations that extend beyond device approval into continuous real-world evidence collection. Manufacturers must maintain periodic safety update reports and trend analysis of analytical failures, increasing regulatory affairs headcount by 40-60% for mid-sized firms. Multiplex respiratory panel suppliers targeting European hospital networks are restructuring quality management systems to satisfy Annex XIV clinical evidence requirements.
Hospital procurement departments are consolidating respiratory testing contracts under single-source agreements that bundle instruments, reagents, and service across three-to-five-year terms. This behavior concentrates purchasing power among integrated delivery networks in the United States and Germany, squeezing independent reference laboratories from preferred vendor lists. The shift is most visible in metropolitan health systems where laboratory directors report directly to supply chain executives rather than clinical chiefs.
Global Respiratory Disease Testing Market Segmentation
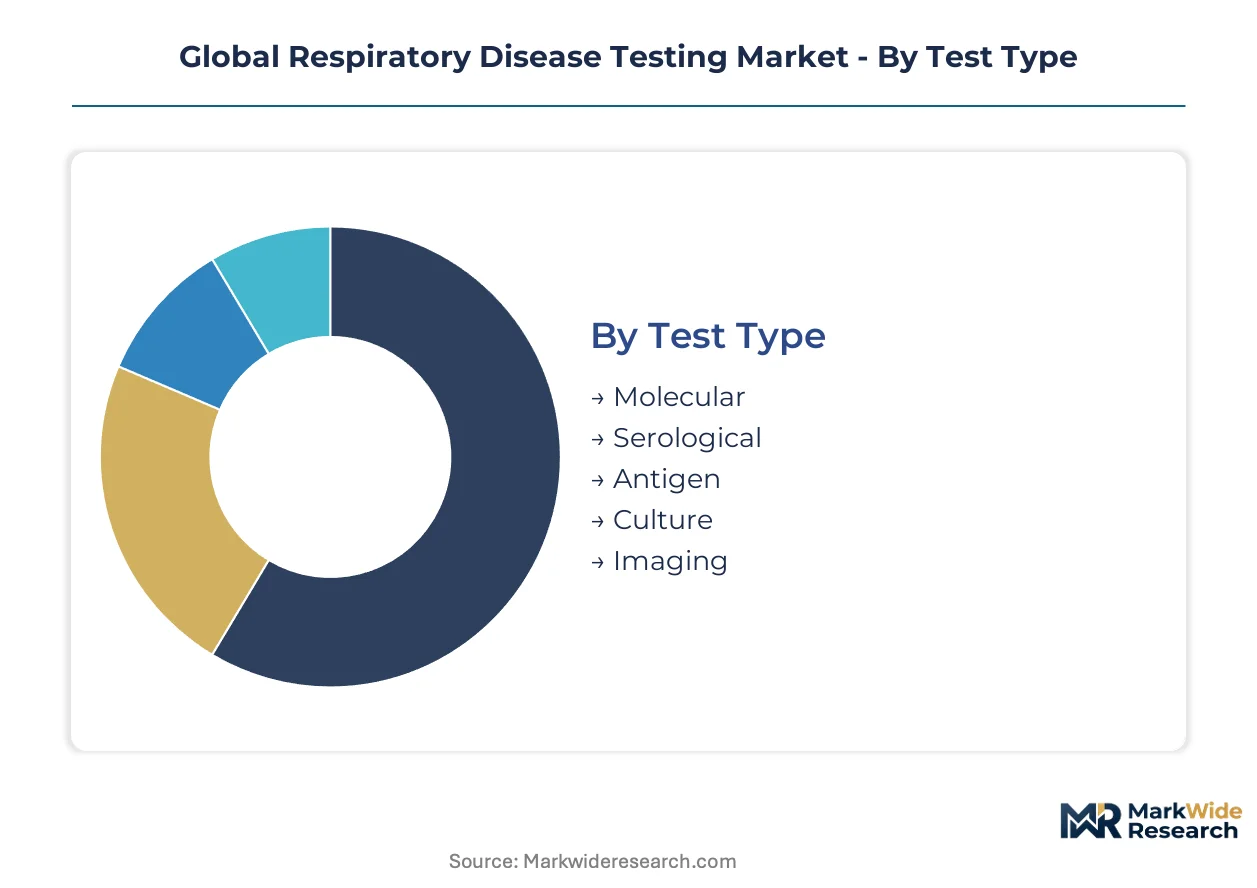
Respiratory disease testing segments fragment along technical sophistication and care setting axes. Test type determines reimbursement tiers while technology choices lock in consumable economics across multi-year instrument leases.
Test Type:
Mature molecular platforms anchor hospital laboratory revenue while emerging antigen formats penetrate retail channels.
- Molecular:PCR and nucleic acid amplification methods detect viral RNA with analytical sensitivity below 10 copies per reaction. United States hospital systems deploy multiplex respiratory panels to satisfy Joint Commission antimicrobial stewardship metrics and reduce empirical antibiotic prescribing.
- Antigen:Lateral flow immunoassays deliver results in 15 minutes without thermal cycler infrastructure. Point of care clinics in Germany and Japan stock these for influenza season screening where sensitivity trade-offs are clinically acceptable.
- Serological:Antibody detection methods support epidemiological surveillance and convalescent screening protocols.
- Culture:Traditional bacterial isolation remains essential for antimicrobial susceptibility testing in severe pneumonia cases.
- Imaging:Chest radiography and CT complement laboratory diagnostics for lower respiratory tract infection assessment.
Molecular retains volume leadership; antigen holds the steepest expansion curve.
Technology:
Cost tiers separate capital-intensive automated platforms from disposable rapid tests.
- PCR:Thermal cycling amplification achieves gold-standard sensitivity for influenza A/B and respiratory syncytial virus detection. Siemens Healthineers and Thermo Fisher Scientific compete through integrated sample-to-answer workflows that minimize technician hands-on time.
- Lateral Flow Assay:Nitrocellulose membrane immunoassays occupy the economy tier for screening applications. Brazilian and Mexican public health programs distribute these for decentralized surveillance.
- ELISA:Enzyme-linked immunosorbent assays support high-throughput serological screening in reference laboratories.
- Immunofluorescence:Direct fluorescent antibody testing provides rapid viral identification with microscopy infrastructure.
- Microarray:Multiplexed nucleic acid detection enables comprehensive respiratory pathogen panels on single cartridges.
PCR dominates hospital procurement; lateral flow assays are expanding most quickly into retail clinics.
Testing Setting:
Patient volume migrates from centralized laboratories toward distributed acquisition points.
- Hospital Labs:Integrated delivery networks consolidate respiratory testing under single-source contracts spanning instruments, reagents, and service. Laboratory directors in United States metropolitan health systems report to supply chain executives rather than clinical chiefs.
- Point of Care Clinics:Urgent care and retail health locations deploy benchtop thermal cyclers with footprints below 0.25 cubic meters. Japan's decentralized testing network expansion drives placement in previously excluded settings.
- Diagnostic Centers:Independent reference laboratories face exclusion from preferred vendor lists as procurement consolidates.
- Home Care:Self-administered nasal swab programs with mail-back PCR processing reach underinsured populations.
- Mobile Labs:Containerized diagnostic units support outbreak response and rural access initiatives.
Hospital labs retain volume leadership; point of care clinics show the steepest expansion trajectory.
End User:
Customer type determines validation burden and purchasing authority structures.
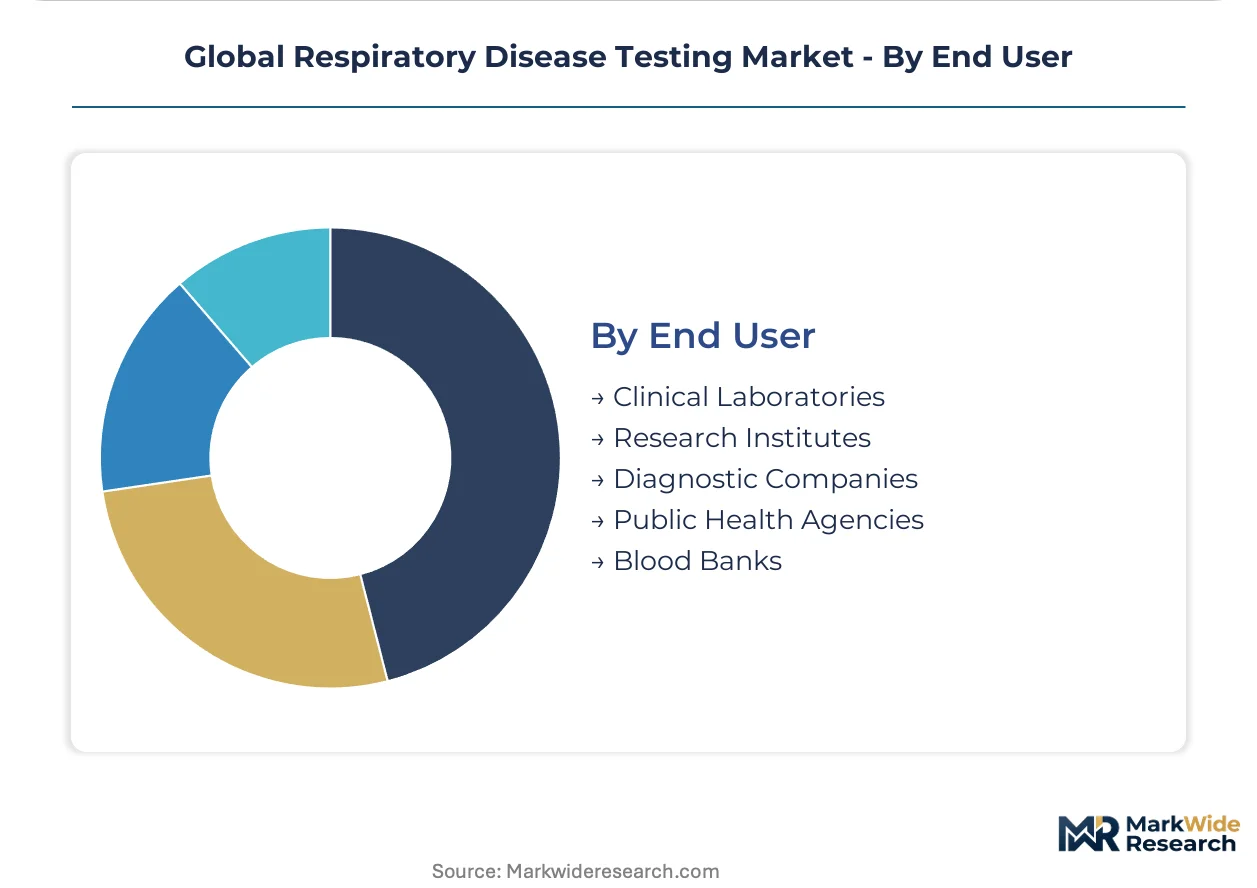
- Clinical Laboratories:CAP checklist requirements mandate verification of 15-22 pathogen targets per respiratory panel. ISO 15189 accreditation creates downstream demand for standardized control materials.
- Public Health Agencies:Surveillance mandates drive procurement of multiplex panels for epidemiological monitoring. Germany's national health agency coordinates regional laboratory networks for respiratory pathogen tracking.
- Research Institutes:Academic medical centers validate novel biomarkers and assay formats.
- Diagnostic Companies:Contract manufacturers and OEM suppliers purchase reagents and control materials.
- Blood Banks:Donor screening protocols incorporate respiratory pathogen detection for cellular therapy safety.
Clinical laboratories retain volume leadership; public health agencies are gaining share fastest through pandemic preparedness investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and decentralized testing networks concentrate demand across five national markets. Each geography exhibits distinct regulatory pathways, reimbursement structures, and infrastructure deployment patterns that shape competitive positioning.
United States
Integrated delivery networks consolidate respiratory testing under single-source contracts spanning instruments, reagents, and service. FDA emergency use authorization frameworks accelerate commercialization timelines for multiplex panels during viral surges. Laboratory directors in metropolitan health systems report to supply chain executives rather than clinical chiefs.
Germany
Hospital systems deploy rapid molecular diagnostics to reduce inappropriate antibiotic prescribing and satisfy Joint Commission metrics. The EU In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for CE-marked devices entering European markets. Regional laboratory networks in Bavaria and North Rhine-Westphalia coordinate respiratory pathogen tracking under national health agency oversight.
Japan
PMDA enforces post-market surveillance protocols that extend validation obligations well beyond initial approval. Benchtop thermal cyclers with footprints below 0.25 cubic meters enable placement in urgent care clinics previously excluded from molecular testing. The Kanto region around Tokyo anchors decentralized testing network expansion.
Brazil
Self-administered nasal swab programs with mail-back PCR processing penetrate underinsured populations. ANVISA regulates diagnostic device registration with timelines that favor pre-validated platform submissions. São Paulo's public health programs distribute lateral flow assays for decentralized surveillance during respiratory virus season.
India
CDSCO pathways for in vitro diagnostics create compliance complexity for multinational platform suppliers. Point-of-care clinics in Maharashtra and Karnataka deploy economy-tier screening formats where sensitivity trade-offs are clinically acceptable. Diagnostic centers in Delhi-NCR face exclusion from preferred vendor lists as procurement consolidates under hospital networks.
Global Respiratory Disease Testing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across instrument, reagent, and service bundles. The market exhibits tiered concentration: diversified life science conglomerates anchor hospital laboratory contracts, while mid-sized molecular specialists capture point-of-care placements. Two strategic archetypes dominate—integrated platform providers leveraging installed bases for consumable pull-through, and reagent-focused suppliers competing on extraction chemistry performance. Competitive moves center on multi-year instrument leasing arrangements and exclusive reagent supply agreements that lock in customer switching costs.
Among diversified platform providers, Thermo Fisher Scientific and Siemens Healthineers occupy positions defined by sample-to-answer workflow integration. Qiagen represents the reagent-specialist archetype, competing in nucleic acid extraction chemistry where standardized control materials create downstream demand. Abbott Laboratories anchors the point-of-care vector through rapid testing formats. These three companies exemplify how competitive positioning fragments across capital deployment models—asset-heavy versus asset-light—and regulatory dossier depth under EU IVDR transition timelines.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Becton Dickinson and Company |
| Koninklijke Philips |
| ResMed |
| Qiagen |
| GE Healthcare |
| bioMérieux |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and Swiss nucleic acid extraction chemistry manufacturers determines both pricing tier spreads and supply chain shape, forcing panel producers to absorb reagent cost volatility or pass through to hospital procurement departments.
Pricing Analysis
Cost-plus contracts with annual indexation to polymer and enzyme commodity benchmarks dominate reagent supply agreements between extraction chemistry specialists and multiplex panel manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared sample-to-answer systems from laboratory-developed test protocols and lateral flow screening formats. Cost compression in mid-complexity molecular assays intensifies because Medicare's Clinical Laboratory Fee Schedule cuts have pushed reimbursement below cost of goods. Point-of-care clinics exhibit highest price sensitivity due to capital constraints, while integrated delivery networks leverage volume consolidation for least-sensitive procurement positions.
Supply Chain Analysis
Contract manufacturing concentration in German and Swiss specialty chemical producers holds capacity for nucleic acid extraction kits and purified polymerases essential to respiratory panel production. Supply draws from concentrated production in Germany, Switzerland, and the United States for thermal cycler instruments, reagent chemistry, and control materials respectively. Raw material dependencies include optical-grade plastics for cartridge molding, thermostable polymerases, and fluorophore-labeled probes. Single-source vulnerability in extraction chemistry creates supply chain risk. Distribution runs through direct sales forces to hospital networks and diagnostic distributors to point-of-care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Respiratory disease testing sits in early-cycle expansion as decentralized diagnostic networks penetrate urgent care clinics previously excluded from molecular testing capacity.
For Market Incumbents: Insulate installed base positions through exclusive reagent supply agreements that lock in multi-year instrument leases and raise switching costs for hospital laboratory customers. Deepen backward integration into nucleic acid extraction chemistry production to reduce dependency on German and Swiss contract manufacturers. Counter lateral flow substitution threats by bundling rapid antigen screening with confirmatory molecular workflows. For New Entrants and Emerging Players: Establish a beachhead in Brazil and Mexico home-based collection infrastructure where self-administered nasal swab programs with mail-back PCR processing penetrate underinsured populations. Target point-of-care clinics in Japan's Kanto region where benchtop thermal cycler miniaturization enables new placement opportunities. Pursue go-to-market partnerships with regional diagnostic distributors rather than direct hospital sales forces. For Investors and Strategic Acquirers: EU IVDR transition timelines reshape the acquisition landscape by favoring targets with pre-validated clinical evidence dossiers that satisfy Annex XIV requirements. Five-to-ten year viability hinges on regulatory dossier depth rather than near-term revenue scale. Prioritize acquisition of mid-sized molecular specialists with ISO 15189-aligned quality management systems. Watch FDA emergency use authorization filing velocity as inflection indicator for platform commercialization readiness.| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Dossier Completion | First-mover advantage for CE-marked multiplex panels under stricter clinical evidence standards accelerates European hospital procurement access. |
| Benchtop Thermal Cycler Miniaturization | Footprint reduction below 0.25 cubic meters enables urgent care clinic placements previously excluded from molecular testing infrastructure. |
| Exclusive Reagent Supply Agreements | Multi-year contracts lock in consumable pull-through economics and raise customer switching costs across integrated delivery networks. |
| Home-Based Collection Infrastructure | Self-administered nasal swab programs with mail-back PCR processing extend reach into underinsured populations in Brazil and Mexico. |
| AI-Assisted Interpretation Integration | Machine learning algorithms automate cycle threshold analysis and reduce technician training burdens for digital PCR platforms. |
Research Methodology
Cross-validation between primary interviews with laboratory directors, hospital procurement executives, diagnostic platform engineers, and regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU IVDR technical documentation, CMS Clinical Laboratory Fee Schedule updates, and hospital GPO contract databases. Bottom-up and top-down triangulation reconciles instrument placement data with reagent consumption patterns.
Calibration against historical instrument lease volumes and reagent pull-through rates shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include test type, technology platform, testing setting, and end-user category. CAGRs were derived from regression analysis of adoption curves and reimbursement trajectory assumptions. Forecast inputs incorporate antimicrobial stewardship mandate penetration rates and point-of-care clinic expansion timelines.
Stress conditions across Medicare reimbursement cuts, EU IVDR compliance cost inflation, and reagent supply disruption scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about decentralized testing network expansion and molecular platform miniaturization adoption. Quarterly review of FDA emergency use authorization filings and hospital procurement contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Kidney Function Tests Market
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Global Breast Cancer Screening Test Market
Clinical Diagnostics
Osteoporosis Testing Market
Clinical Diagnostics
Nitric Oxide Asthma Testing Market
Clinical Diagnostics
Blood Group Typing Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
Bone Metabolism Test Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Angiogenesis Assays Market