
 Europe Colorectal Cancer Screening Market | 2026-2036
Europe Colorectal Cancer Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Colorectal Cancer Screening Market Foresight
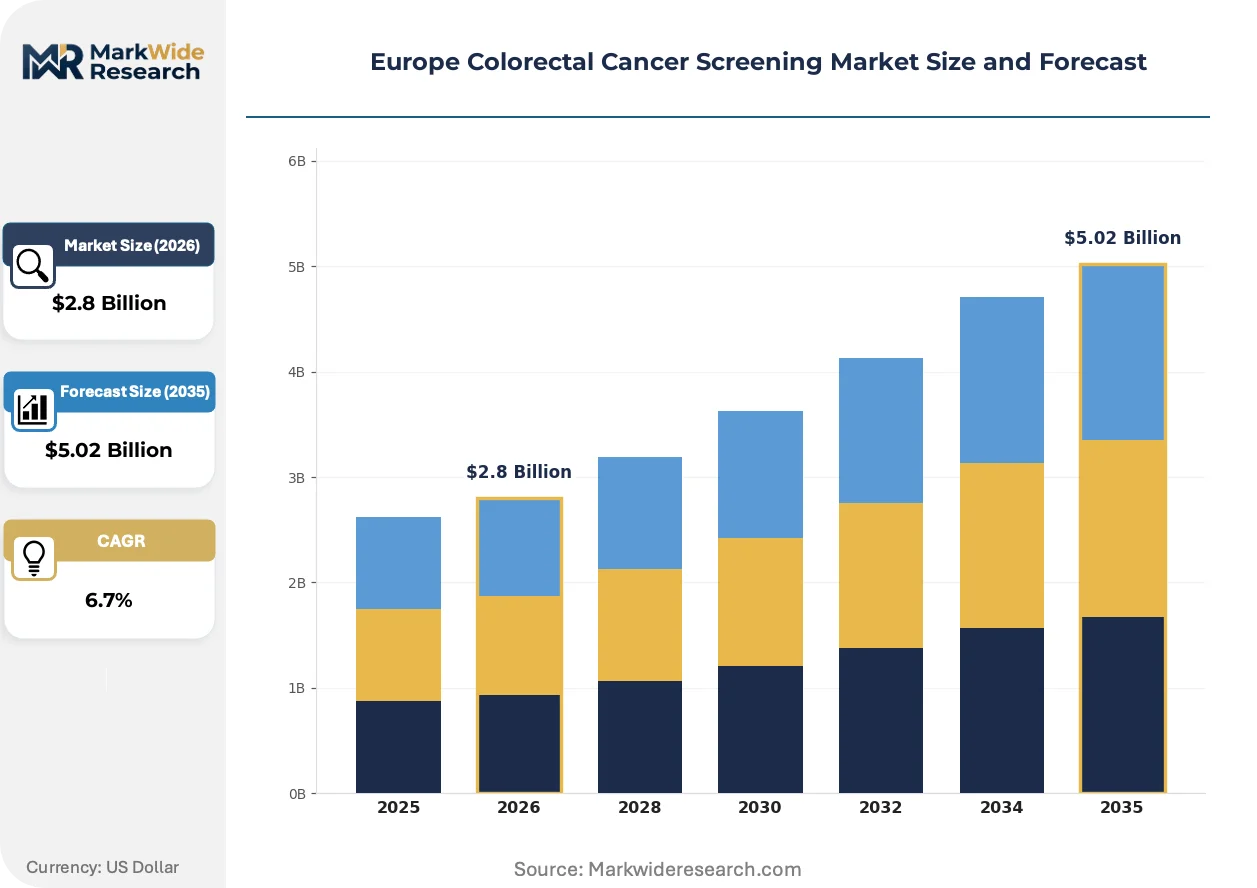
The EU Green Deal is decoupling colorectal screening procurement from resource-intensive endoscopic workflows across European hospital systems. Roche Diagnostics leverages its pan-European distribution infrastructure to sustain centralized laboratory testing volumes. Exact Sciences Corporation anchors its competitive position through specialized DNA-based stool assay platforms designed for compliance with evolving EU IVD regulations.
Europe Colorectal Cancer Screening encompasses diagnostic modalities that detect neoplastic lesions or occult blood in the colorectal tract, employing immunochemical reagents, DNA biomarker panels, or optical imaging systems with defined sensitivity thresholds for advanced adenoma detection. These technologies serve the primary purpose of enabling early-stage intervention before metastatic progression. Fecal immunochemical tests dominate routine population screening due to lower per-test costs and scalable mail-based distribution, while DNA-based assays capture expanding margin pools in risk-stratified screening protocols. Optical imaging retains structural importance for diagnostic confirmation and therapeutic intervention despite higher procedural complexity.
The Medical Device Regulation and In Vitro Diagnostic Regulation frameworks reshape market access through tightened clinical evidence requirements and post-market surveillance obligations across EU member states. National reimbursement authorities in France, Germany, and Italy calibrate screening program eligibility criteria, directly influencing test volume allocation between hospital laboratories and home-based collection models. Stakeholders must monitor pending EU HTA coordination procedures that will standardize cost-effectiveness thresholds across member states.
Market Dynamics
The EU Green Deal is forcing hospital procurement departments across France, Germany, and Italy to abandon resource-intensive endoscopic screening workflows in favor of mail-distributed fecal immunochemical tests that reduce carbon footprints per screening episode.
Growth Catalysts
- MDR compliance deadlines:The Medical Device Regulation is accelerating manufacturer consolidation toward CE-marked, high-sensitivity immunochemical platforms that satisfy post-market surveillance obligations.
- Population aging demographics:Adults aged 50-74 now represent the largest insured cohort in Western European health systems, expanding addressable screening volumes in centralized diagnostic laboratories.
- Biomarker panel advancement:Multi-target DNA stool assays are capturing expanded reimbursement codes in risk-stratified protocols across French and German national health programs.
Market Restraints
- IVD clinical evidence requirements:The In Vitro Diagnostic Regulation mandates prospective validation studies that extend time-to-market for novel biomarker platforms by 18-24 months.
- Centralized laboratory concentration:High-throughput processing capacity clusters in Paris, Munich, and Milan hospital networks, creating geographic access disparities for peripheral regions.
- Endoscopic confirmation dependency:Positive non-invasive screening results still require optical colonoscopy for histological confirmation, limiting complete workflow substitution.
Strategic Opportunities
- Eastern European program expansion:Poland and Romania health ministries are piloting population-based screening initiatives with EU structural fund support, opening greenfield procurement channels.
- At-home collection logistics:Specialized cold-chain distributors are building direct-to-patient specimen transport networks that bypass traditional hospital laboratory gatekeepers.
- EU HTA coordination:Pending health technology assessment harmonization will standardize cost-effectiveness thresholds across member states, simplifying multi-country market access.
Industry Challenges
- Biostatistician talent scarcity:Clinical trial design for multi-cohort screening studies requires specialized epidemiological expertise that commands premium compensation in Basel and Cambridge biotech clusters.
- Legacy LIS integration:Hospital laboratory information systems in Turin and Lyon operate on incompatible data standards that complicate automated result reporting for decentralized screening programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Colorectal Cancer Screening Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Colonoscopy, Fecal Occult Blood Test, Sigmoidoscopy, Virtual Colonoscopy Age Group: 40-49 Years, 50-59 Years, 60-69 Years, 70 Years & Above Technology: Immunochemical Test, DNA-Based Test, Optical Imaging, Fluid-Based Test End User: Hospitals, Diagnostic Centers, Home Care, Research Institutions |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Exact Sciences Corporation, Sysmex Corporation, Epigenomics AG, Quest Diagnostics, Siemens Healthineers AG, Olympus Corporation, Novigenix SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Colorectal Cancer Screening Market Shifts & Advancements
Digital pathology platforms and artificial intelligence-assisted polyp detection are compressing diagnostic timelines while biomarker multiplexing expands the information yield from single stool specimens.
Liquid biopsy technologies for circulating tumor DNA detection are decentralizing confirmatory testing away from hospital endoscopy suites toward community phlebotomy centers. Regional health authorities in Bavaria and Catalonia are piloting blood-based screening protocols that reduce patient travel burdens. This shift is compressing the addressable market for optical imaging equipment while expanding reagent consumption in molecular diagnostic laboratories.
The EU AI Act classification rules are imposing conformity assessment obligations on machine-learning algorithms used for polyp detection during colonoscopy. German notified bodies are developing specialized review pathways for computer-aided detection software. Manufacturers of optical imaging systems are restructuring quality management systems to accommodate algorithm version control and post-deployment performance monitoring.
Hospital purchasing consortia in the Netherlands and Belgium are consolidating fecal immunochemical test procurement into multi-year framework agreements that specify minimum sensitivity thresholds for advanced adenoma detection. This concentration is displacing spot purchasing from individual pathology departments. Diagnostic manufacturers are responding with performance-guarantee contracts that tie pricing to documented detection rates in screened populations.
Europe Colorectal Cancer Screening Market Segmentation
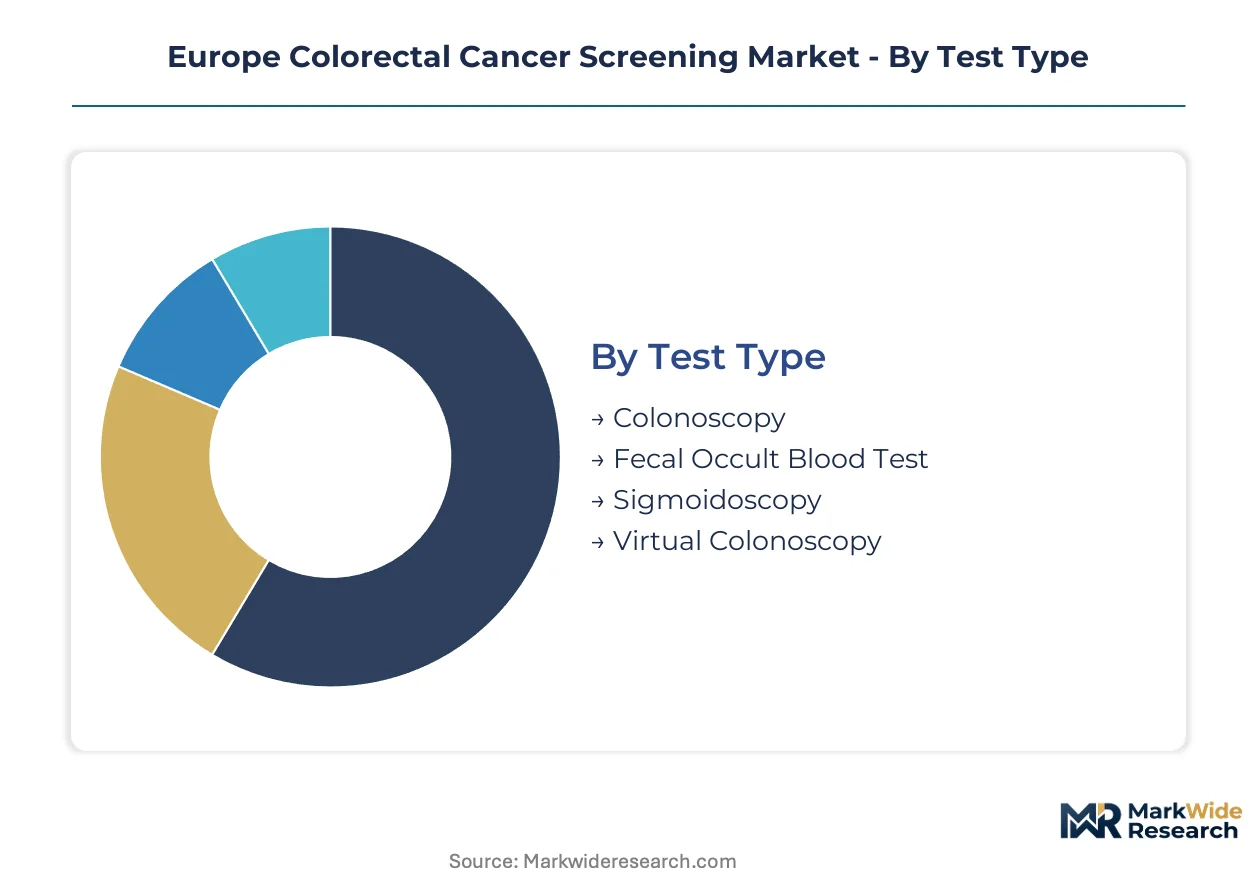
Segmentation reveals how procurement priorities diverge across European health systems. National reimbursement frameworks and the EU MDR reshape demand concentration by test modality and care setting.
Test Type:
Procurement departments in Paris and Munich hospital networks prioritize workflow efficiency and per-episode carbon footprint when selecting screening modalities.
- Fecal Occult Blood Test:Immunochemical reagent platforms process high-throughput stool specimens in centralized laboratories. Demand clusters in German and French national screening programs seeking mail-distribution scalability with reduced patient travel burdens.
- Colonoscopy:Optical examination with histological sampling remains the diagnostic confirmation standard for positive non-invasive screens. Volume concentrates in tertiary hospital endoscopy suites across Italy and Spain despite higher procedural resource intensity.
- Sigmoidoscopy:Distal colorectal examination targets left-sided lesion detection with lower sedation requirements.
- Virtual Colonoscopy:CT-based luminal imaging offers non-invasive structural assessment without sedation.
Volume sits with Fecal Occult Blood Test; growth tilts toward Colonoscopy efficiency improvements.
Age Group:
Eligibility criteria in national health programs determine addressable cohort size and screening frequency intervals.
- 50-59 Years:Preventive intervention window where early-stage adenoma detection yields highest lifetime cost-effectiveness. French and German authorities are expanding invitation coverage to this bracket under EU cancer plan targets.
- 60-69 Years:Peak incidence period with established screening adherence patterns. Italian regional health systems concentrate reminder campaigns and follow-up coordination resources here.
- 40-49 Years:Risk-stratified protocols for familial history or hereditary syndromes.
- 70 Years & Above:Comorbidity-adjusted screening decisions balance life expectancy against procedural risks.
Volume concentrates in 60-69 Years; eligibility expansion is climbing fastest in 50-59 Years.
Technology:
Regulatory evidence requirements under EU IVDR differentiate market access timelines and reimbursement confidence.
- Immunochemical Test:Quantitative fecal hemoglobin detection with established CE-marking pathways. Bavarian and Catalan laboratories process the highest European volumes through automated analyzer platforms.
- DNA-Based Test:Multi-target stool assays detect methylated gene markers and mutated DNA fragments. Pilot reimbursement codes in French national programs are expanding addressable use beyond high-risk stratification.
- Optical Imaging:White-light and narrow-band colonoscopy systems with AI-assisted polyp detection.
- Fluid-Based Test:Blood-based circulating tumor DNA approaches in early validation.
Installed base favors Immunochemical Test; DNA-Based Test holds the steepest expansion trajectory.
End User:
Specimen collection logistics and result reporting integration shape channel selection across member states.
- Hospitals:Integrated endoscopy and pathology departments manage diagnostic confirmation and therapeutic intervention. German hospital purchasing consortia consolidate multi-year framework agreements specifying sensitivity thresholds.
- Diagnostic Centers:Independent laboratories compete on turnaround time and digital result delivery. Dutch and Belgian networks are capturing decentralized screening volume through direct-to-patient specimen logistics.
- Home Care:Mail-distributed collection kits with prepaid return packaging.
- Research Institutions:Longitudinal cohort studies and biomarker validation trials.
Processing volume clusters in Hospitals; patient convenience is driving fastest share gain in Diagnostic Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of immunochemical reagents and DNA assay platforms concentrates in German and Swiss manufacturing clusters, while consumption spreads across Western European hospital networks and emerging Eastern European screening programs. France and Italy absorb the highest per-capita testing volumes through centralized laboratory infrastructure.
Germany
Bavarian diagnostic manufacturers supply automated fecal immunochemical analyzers to hospital purchasing consortia across the Länder. The Federal Joint Committee (G-BA) mandates minimum sensitivity thresholds for population-based screening reimbursement. Munich and Berlin hospital networks process the highest European specimen volumes through integrated laboratory information systems.
France
National health insurance expansion targets adults aged 50-74 with biennial FIT invitations through regional health agencies. ANSM oversees CE-marking compliance for multi-target DNA stool assays entering pilot reimbursement protocols. The Paris hospital network anchors centralized processing capacity while Lyon laboratories pioneer digital pathology integration.
Italy
Regional health systems in Lombardy and Emilia-Romagna operate decentralized screening registries with varying adherence rates. The Ministry of Health harmonizes quality standards across autonomous regional programs under EU cancer plan alignment. Turin and Milan endoscopy suites retain high colonoscopy confirmation volumes despite FIT scale-up.
United Kingdom
NHS England's bowel cancer screening programme distributes quantitative FIT kits through GP-registered populations with automated result tracking. NICE evaluates cost-effectiveness thresholds for blood-based circulating tumor DNA alternatives. London diagnostic hubs and Manchester reference laboratories compete on turnaround time for decentralized specimen logistics.
Poland
EU structural funds finance pilot population-based screening initiatives in Mazovia and Silesian Voivodeships with mail-distribution infrastructure. The national health ministry calibrates eligibility criteria against centralized laboratory capacity constraints. Warsaw hospital networks build high-throughput processing capabilities while Krakow academic centers validate biomarker protocols.
Europe Colorectal Cancer Screening Market Competitive Landscape
The competitive structure tilts toward diversified diagnostics conglomerates with pan-European distribution infrastructure. Manufacturer consolidation accelerates as MDR compliance deadlines eliminate smaller players lacking post-market surveillance capabilities. Three archetypes dominate: pan-European reagent suppliers, specialized DNA assay developers, and optical imaging system integrators. Strategic moves concentrate on multi-year framework agreements with hospital purchasing consortia and biomarker panel licensing partnerships.
Among diversified diagnostics conglomerates, Roche Diagnostics and Abbott Laboratories occupy positions spanning immunochemistry and molecular platforms. Exact Sciences Corporation exemplifies the specialized DNA assay archetype with regulatory focus on EU IVD compliance. Siemens Healthineers AG represents the imaging-integrated diagnostics tier with endoscopy and pathology workflow offerings.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Exact Sciences Corporation |
| Sysmex Corporation |
| Epigenomics AG |
| Quest Diagnostics |
| Siemens Healthineers AG |
| Olympus Corporation |
| Novigenix SA |
| Others |
Supply & Pricing Matrix
Polymerase chain reaction reagent spot prices on the S&P Global Commodity Insights index cascade through European diagnostic supply chains into three-tier pricing structures that separate high-sensitivity immunochemical platforms from standard-grade alternatives and economy-tier imports. This cost transmission concentrates pricing power among German and Swiss manufacturers with captive raw material sourcing while compressing margins for distributors dependent on spot-market biochemical inputs.
Pricing Analysis
Outcome-linked pricing anchors hospital procurement contracts across French and German screening programs, with per-test fees tied to documented advanced adenoma detection rates in screened populations. Price differentiation separates CE-IVDR certified platforms from legacy devices facing reimbursement exclusion, with volume-scale discounts commanding steepest reductions in multi-year framework agreements. Pricing pressure stems from EU Green Deal carbon-accounting requirements that favor mail-distributed specimen collection over hospital-based workflows. Diagnostic centers in the Netherlands and Belgium exhibit highest price sensitivity due to competitive tendering, while centralized Paris and Munich hospital networks prioritize sensitivity thresholds over unit cost.
Supply Chain Analysis
Direct-to-laboratory distribution channels handle high-throughput reagent demand from Bavarian and Catalan diagnostic hubs, bypassing traditional wholesale intermediaries. Manufacturing concentration rests in Germany, Switzerland, and the Netherlands for immunochemical analyzer production and reagent formulation. Raw material dependencies draw from specialized enzyme suppliers in Denmark, fluorescent dye producers in Belgium, and precision-molded plastic consumables from Austrian manufacturers. Single-source vulnerability concentrates in cold-chain specimen transport networks serving decentralized screening programs. Distribution runs through hospital purchasing consortia in the Netherlands and Belgium that consolidate multi-year procurement into framework agreements specifying minimum performance thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR and IVDR frameworks erect compliance moats that favor manufacturers with post-market surveillance infrastructure, transforming market access into a cost-of-compliance contest where smaller players face elimination. National reimbursement authorities in France, Germany, and Italy calibrate screening eligibility criteria that directly allocate volume between compliant and non-compliant test platforms.
For Market Incumbents: Extend performance-guarantee contract structures into Eastern European pilot programs before EU HTA harmonization standardizes procurement criteria. Consolidate backward integration into specialized enzyme supply chains to insulate margin structures from Danish and Belgian raw material price volatility. Defensive capacity expansion in Warsaw and Krakow laboratory networks captures emerging Polish screening volumes before local competitors achieve IVDR certification.
For New Entrants and Emerging Players: Independent diagnostic laboratories in Romania and Bulgaria represent the most penetrable channel archetype, with EU structural fund financing creating procurement windows for novel biomarker platforms. White-space concentration sits in at-home collection logistics that bypass traditional hospital laboratory gatekeepers through direct-to-patient cold-chain networks. Go-to-market positioning should emphasize AI-assisted result interpretation that satisfies pending EU AI Act conformity assessment pathways for machine-learning diagnostic algorithms.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap DNA assay developers in Cambridge and Basel biotech clusters facing IVDR validation cost overruns but holding proprietary methylation marker intellectual property. Long-term viability frames around five-to-ten year reimbursement expansion for blood-based circulating tumor DNA alternatives that displace optical colonoscopy confirmation volumes. The inflection signal to monitor is NICE cost-effectiveness evaluation timing for liquid biopsy screening protocols in NHS England's bowel cancer programme.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Certification Pathway | CE marking under EU IVDR unlocks French and German national reimbursement codes for DNA stool assays. |
| Hospital System Partnership | Munich and Berlin hospital network agreements anchor high-throughput analyzer placement in Europe's largest screening volumes. |
| Biomarker Panel Licensing | Multi-target methylation marker partnerships expand addressable use from high-risk stratification to population-based protocols. |
| Software Companion Development | AI-assisted polyp detection algorithms satisfy EU AI Act conformity assessment for computer-aided colonoscopy systems. |
| Reimbursement Strategy | Federal Joint Committee sensitivity threshold compliance secures G-BA reimbursement for German population screening. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with diagnostic laboratory directors, hospital procurement committee members, biomedical engineers, and GPO contracts managers. EMA submission databases, ANSM device registration records, hospital procurement databases, and GPO contract repositories provided secondary validation. Bottom-up test volume modeling triangulated against top-down national screening program expenditure data.
Granularity-level modeling captured test type, age group eligibility, technology platform, and end-user channel dimensions at the country level across the analysis window. CAGRs derived from logistic diffusion curves fitted to screening program penetration rates and biomarker adoption trajectories. Forecast inputs incorporated EU HTA coordination timeline assumptions and MDR compliance deadline impacts on manufacturer consolidation.
Several conditions sit outside the modeled scope, including pending blood-based screening protocol validation outcomes and AI Act algorithm classification determinations. Forecasts reflect assumptions about reimbursement expansion timelines and laboratory capacity buildout rates. Periodic stress-testing of base assumptions is recommended against regulatory delay scenarios and biomarker panel clinical evidence requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Blood Group Typing Market
Clinical Diagnostics
Antenatal Screening Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market
Clinical Diagnostics
Renal Function Test Market
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
Artificial Intelligence in Cancer Diagnostics Market
Clinical Diagnostics
Cardiology Genomic Testing Market
Clinical Diagnostics
Chronic Hepatitis B Virus Testing Market
Clinical Diagnostics
Angiogenesis Assays Market
Clinical Diagnostics
Kidney Function Tests Market
Clinical Diagnostics
Cell-Free Fetal DNA Testing Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market
Clinical Diagnostics
Nitric Oxide Asthma Testing Market