
 Adult Hemoglobinopathy Testing Market | 2026-2036
Adult Hemoglobinopathy Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Adult Hemoglobinopathy Testing Market Outlook
High-sensitivity next-generation sequencing panels is redrawing competitive boundaries in adult hemoglobinopathy testing. Bio-Rad Laboratories leverages its electrophoresis heritage to sustain dominance in reference laboratory workflows. Thermo Fisher Scientific anchors its position through integrated PCR-to-sequencing platforms that span research and clinical applications. Siemens Healthineers competes on automation density, embedding hemoglobinopathy assays into high-throughput hematology lines.
Adult hemoglobinopathy testing encompasses laboratory and point-of-care methods for detecting variant hemoglobins—quantifying HbS, HbC, HbE, and thalassemia mutations through protein separation, DNA amplification, or nucleotide sequencing—to enable diagnosis, carrier identification, and transfusion management in individuals beyond infancy. Genetic tests capture the deepest margin pools as laboratories bill for mutation-specific panels rather than screening-only workflows. Blood tests retain volume leadership in routine clinical settings where capillary electrophoresis and HPLC chromatography deliver rapid phenotypic confirmation. Diagnostic laboratories represent the fastest-growing end user segment as hospital outsourcing and centralized regional networks expand molecular capacity.
FDA oversight of in vitro diagnostic devices and WHO prequalification programs shape product registration pathways and international procurement eligibility for hemoglobinopathy assays. EMA's In Vitro Diagnostic Regulation intensifies conformity requirements for CE-marked testing kits entering European diagnostic laboratories. Stakeholders must monitor evolving reimbursement codes for molecular versus protein-based testing as payers recalibrate coverage policies across public and private systems.
Market Dynamics
Centralization of molecular diagnostics capacity into regional reference laboratories is compressing point-of-care margins while expanding high-complexity testing volumes. WHO prequalification pathways and EMA's In Vitro Diagnostic Regulation are accelerating consolidation among assay manufacturers capable of multi-jurisdictional compliance.
Growth Catalysts
- Brazil's national screening expansion:The maturation of newborn programs into adult carrier testing services is creating sustained demand for HPLC and capillary electrophoresis workflows in public health laboratories.
- WHO hemoglobinopathy control guidelines:Standardization mandates across member states are forcing procurement alignment toward prequalified assay platforms, benefiting centralized diagnostic networks.
- Next-generation sequencing panel adoption:Diagnostic laboratories are upgrading from protein-based screening to mutation-specific genetic panels that capture higher reimbursement per test.
Market Restraints
- Reagent supply concentration:Critical electrophoresis buffers and polymerase chain reaction master mixes depend on concentrated manufacturing in Germany and the United States, exposing laboratories to import delays.
- EMA MDR compliance costs:Technical documentation and notified body review requirements for CE-marked hemoglobinopathy kits have extended registration timelines by eighteen to twenty-four months.
- Limited substitute technologies:Mass spectrometry remains prohibitively capital-intensive for mid-tier laboratories, trapping facilities in electrophoresis-dependent workflows without viable upgrade paths.
Strategic Opportunities
- Underpenetrated sub-Saharan Africa:Nigeria and the Democratic Republic of Congo present white space for portable capillary electrophoresis units where laboratory infrastructure remains sparse.
- Integrated PCR-to-sequencing platforms:Convergence of real-time amplification and semiconductor sequencing is enabling same-day diagnostic confirmation previously requiring send-out workflows.
- India's PLI scheme for diagnostics:Production-linked incentives for medical device manufacturing are attracting contract manufacturers to establish local kit assembly capacity.
Industry Challenges
- Molecular cytogenetics skill scarcity:Interpretation of complex variant calls from sequencing panels requires specialized bioinformatics expertise that academic training programs have failed to scale.
- Legacy hematology analyzer integration:Hospital laboratories face middleware compatibility failures when attempting to embed hemoglobinopathy assays into existing Beckman Coulter or Sysmex workflow management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adult Hemoglobinopathy Testing Market |
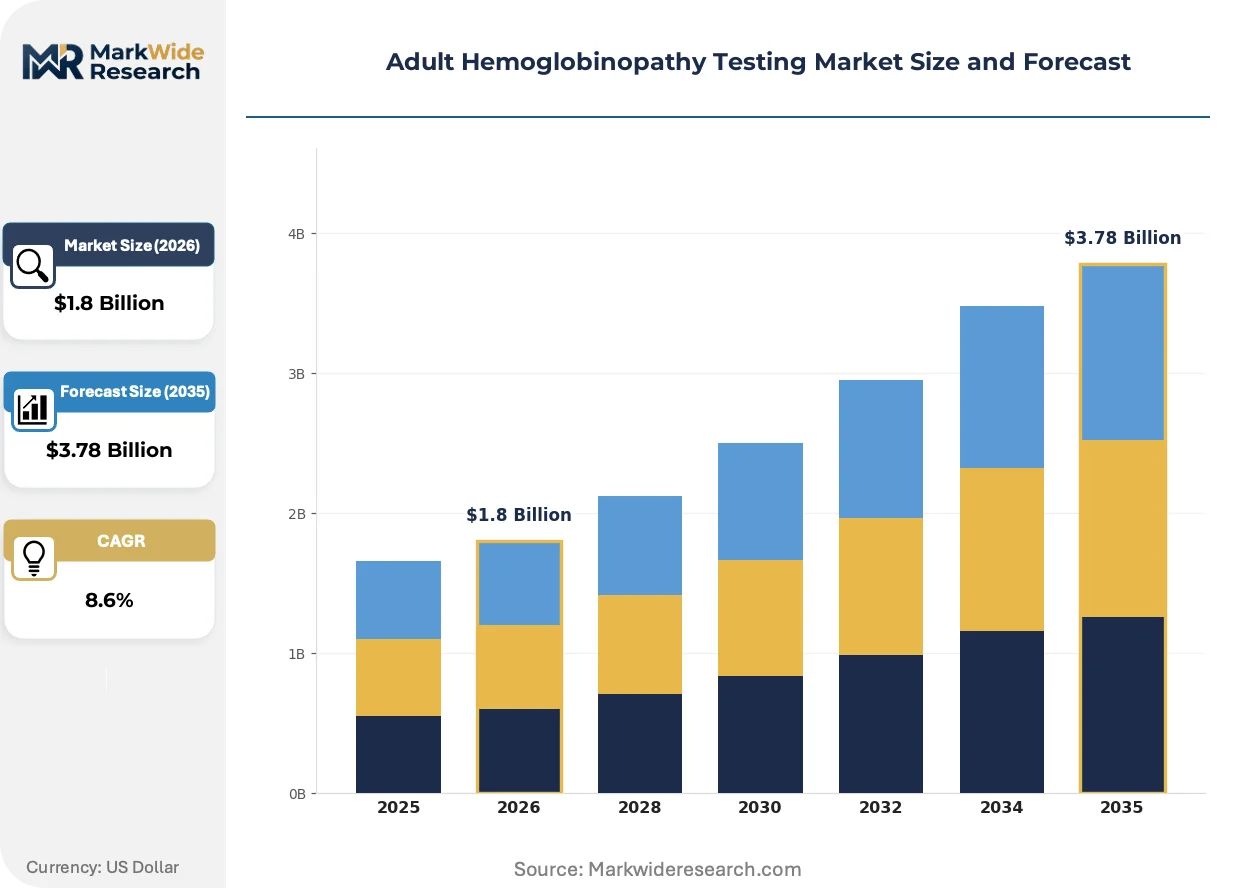
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetic Tests, Blood Tests, Screening Kits, Diagnostic Reagents Application: Research, Clinical Diagnosis, Newborn Screening, Carrier Testing End User: Hospitals, Diagnostic Laboratories, Research Institutions, Clinics Technology: PCR, Electrophoresis, Sequencing, Chromatography |
| Companies Covered | Bio-Rad Laboratories, Inc., Thermo Fisher Scientific Inc., Siemens Healthineers, Revvity, Trinity Biotech, PerkinElmer Inc., Roche Diagnostics, Abbott Laboratories, Sysmex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adult Hemoglobinopathy Testing Market Strategic Shifts
Portable diagnostic platforms and automated interpretation software are compressing the time from sample collection to clinical decision. Regulatory convergence around WHO prequalification is reshaping product development priorities for assay manufacturers.
Capillary electrophoresis instrumentation is miniaturizing from benchtop systems to handheld cartridge-based devices suitable for rural clinic deployment. Community health centers in Brazil and India are piloting these platforms for same-day sickle cell trait screening. The technology is miniaturizing capital requirements, enabling diagnostic access outside centralized laboratory networks previously necessary for hemoglobin variant separation.
EMA's In Vitro Diagnostic Regulation is eliminating self-certified CE-marked assays from European procurement channels. Manufacturers must now submit to notified body oversight for hemoglobinopathy testing kits, raising compliance barriers for smaller reagent suppliers. Diagnostic laboratories in France and Germany are consolidating purchasing around vendors with dedicated regulatory affairs teams capable of sustaining MDR technical documentation.
Hospital systems are unbundling after-sales service contracts from instrument procurement, opting for third-party maintenance or in-house biomedical engineering support. This purchasing behavior shift is pressuring original equipment manufacturers to reduce service attach rates or risk competitive displacement. The trend is most visible in United States academic medical centers where capital committees prioritize lower total cost of ownership over bundled warranty terms.
Adult Hemoglobinopathy Testing Market Segmentation
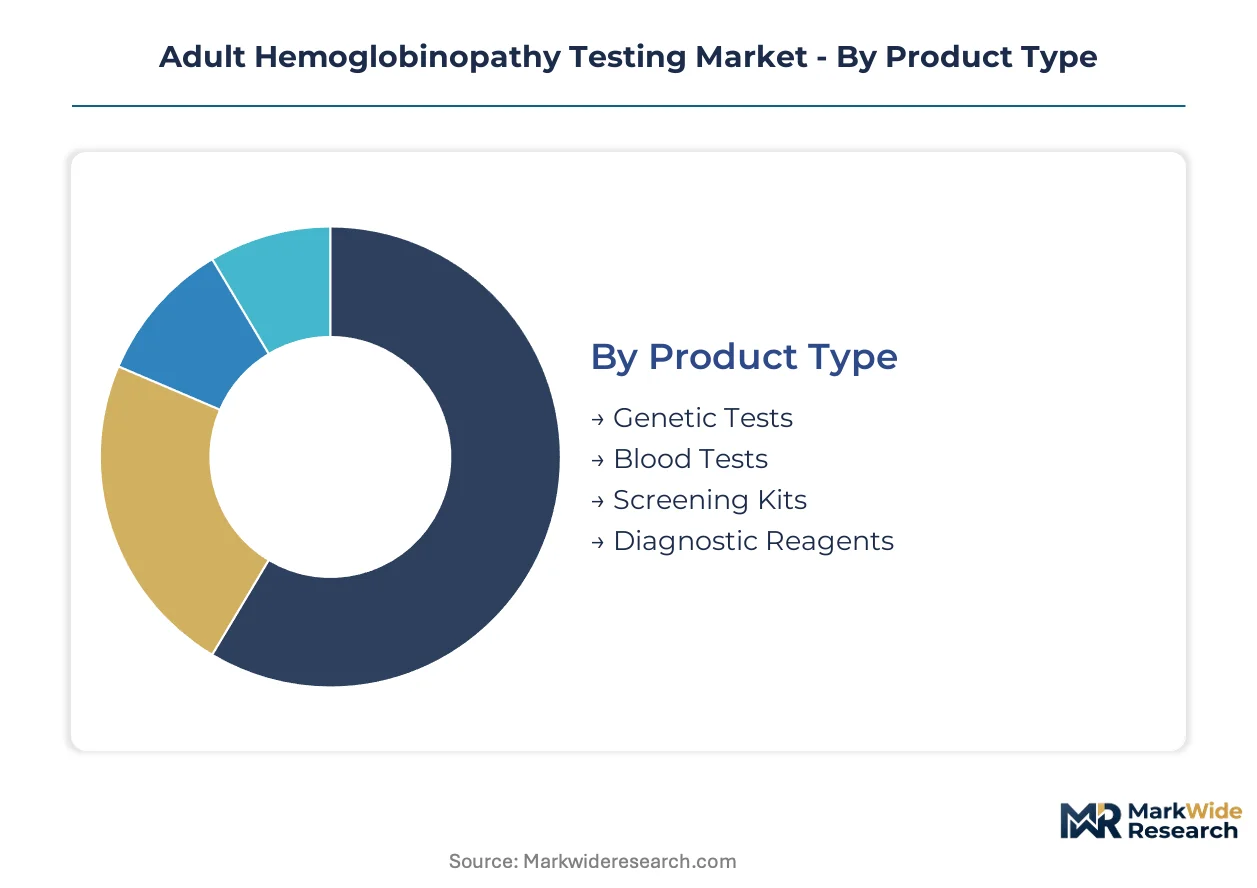
Segmentation in adult hemoglobinopathy testing reveals how substitution pressures and reimbursement tiers reshape purchasing decisions across laboratories and clinical settings. Laboratories prioritize technologies that balance analytical sensitivity with throughput economics, while point-of-care deployments favor portability over comprehensive mutation profiling.
Product Type:
Substitution pressure concentrates most intensely on blood tests, where protein-based methods face displacement by genetic panels that command superior reimbursement rates and diagnostic specificity.
- Genetic Tests:Mutation-specific panels employing next-generation sequencing or targeted PCR detect beta-globin gene variants with single-nucleotide resolution. Academic medical centers in the United States and regional reference laboratories in Brazil are consolidating send-out volumes around these higher-complexity workflows as payers expand coverage for definitive genotyping.
- Blood Tests:Capillary electrophoresis and high-performance liquid chromatography separate hemoglobin variants based on charge and molecular weight. Public health laboratories in Brazil and India retain heavy dependence on these methods for population-scale carrier screening where capital constraints limit molecular infrastructure deployment.
- Screening Kits:Rapid lateral flow devices enable point-of-care sickle cell trait detection in community health settings with minimal equipment requirements.
- Diagnostic Reagents:Specialized buffers, primers, and control materials constitute recurring consumable demand across electrophoresis and amplification workflows.
Blood tests anchor the volume base while genetic tests gain share at the steepest rate.
Application:
Cost tier stratification separates research-grade sequencing from clinical screening workflows, with reimbursement codes driving divergence between definitive diagnosis and carrier identification markets.
- Research:Academic institutions employ whole-exome sequencing and CRISPR-edited cellular models to investigate modifier genes affecting sickle cell severity. NIH-funded centers in the United States and the Wellcome Trust Sanger Institute in the United Kingdom concentrate demand for exploratory genotyping platforms that precede clinical assay validation.
- Clinical Diagnosis:Hospital laboratories perform confirmatory testing for symptomatic adults presenting with anemia, vaso-occlusive crisis, or transfusion-dependent thalassemia. Workflow integration with existing hematology analyzers determines platform selection in mid-tier facilities.
- Newborn Screening:State public health programs deploy dried blood spot analysis with tandem mass spectrometry or isoelectric focusing for presymptomatic detection.
- Carrier Testing:Preconception screening programs in Mediterranean and Middle Eastern populations drive demand for targeted mutation panels.
Clinical diagnosis anchors the volume base while carrier testing expands most quickly as preconception screening programs proliferate.
End User:
Customer type determines purchasing authority complexity, with hospital systems negotiating enterprise contracts while independent laboratories face capital constraints that favor reagent rental arrangements.
- Diagnostic Laboratories:Regional reference networks in Brazil and India are consolidating molecular capacity to capture outsourced hospital volumes. These facilities prioritize automation density and LIS integration to process high-throughput sample flows from multiple clinical sites.
- Hospitals:Academic medical centers maintain in-house electrophoresis for urgent transfusion management while referring complex genotyping to external specialists. Middleware compatibility with Beckman Coulter or Sysmex hematology lines constrains assay platform selection.
- Research Institutions:University-affiliated centers drive early adoption of emerging sequencing chemistries before clinical translation.
- Clinics:Community health centers in sub-Saharan Africa and rural India pilot portable capillary electrophoresis units for same-day screening.
Hospitals anchor the volume base while diagnostic laboratories climb the fastest as outsourcing accelerates.
Technology:
Supply concentration in electrophoresis instrumentation creates vendor lock-in effects that complicate migration to sequencing platforms despite superior analytical performance.
- Sequencing:Semiconductor and nanopore chemistries enable same-day turnaround for mutation-specific confirmation previously requiring batch processing. Thermo Fisher Scientific's integrated PCR-to-sequencing platforms span research and clinical applications, capturing upgrade cycles from protein-dependent laboratories.
- Electrophoresis:Capillary systems from Bio-Rad Laboratories dominate reference laboratory workflows through established service networks and regulatory prequalification. The technology's miniaturization into handheld cartridge devices is extending reach to point-of-care settings in Brazil and India.
- PCR:Real-time amplification remains the workhorse for targeted mutation detection in resource-limited settings.
- Chromatography:HPLC systems provide quantitative hemoglobin variant profiling with established reimbursement pathways.
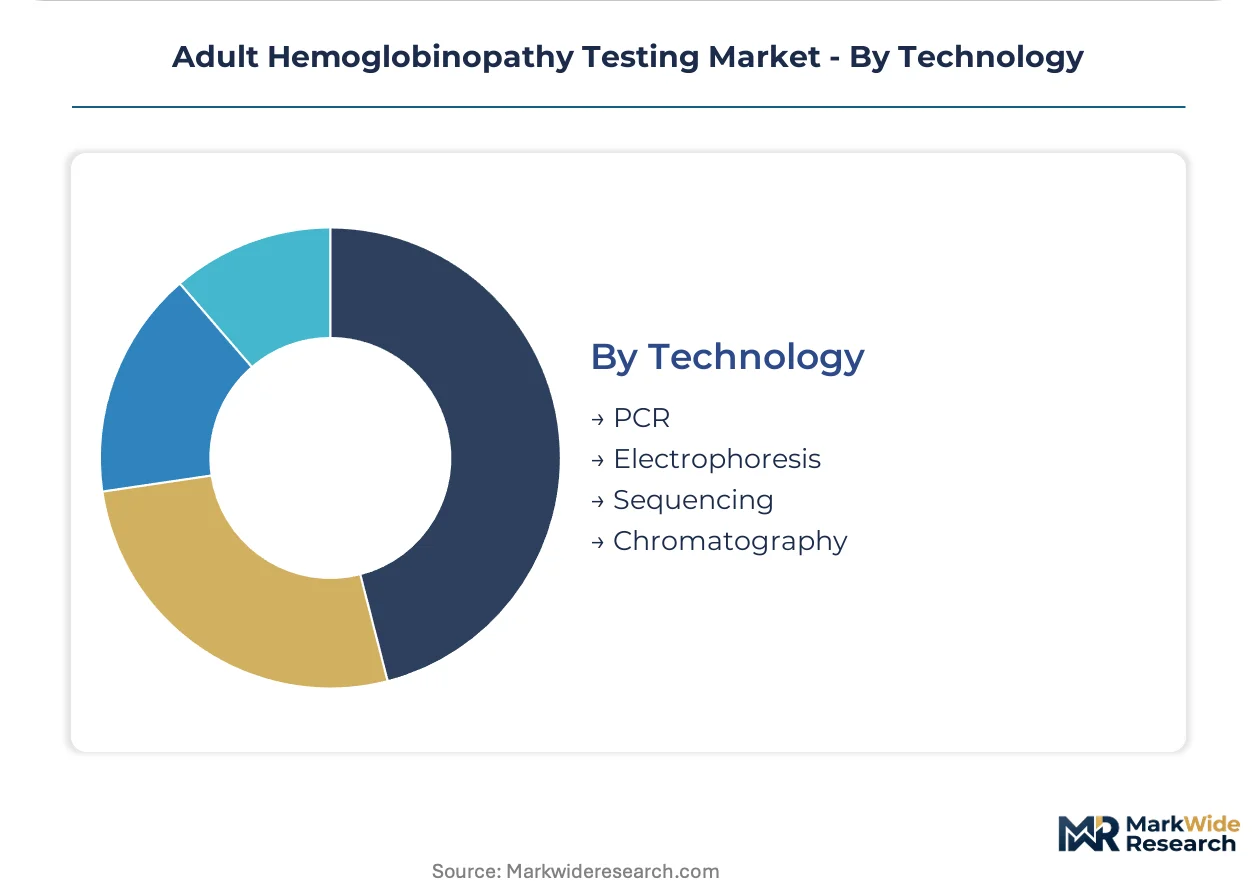
Electrophoresis anchors the volume base while sequencing follows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports electrophoresis instrumentation and PCR master mixes to diagnostic laboratories across Brazil, India, and the United States. These reagent supply corridors concentrate manufacturing capacity in Baden-Württemberg and North Rhine-Westphalia before distribution to high-volume testing markets.
United States
Academic medical centers in Boston and the San Francisco Bay Area drive adoption of next-generation sequencing panels for definitive genotyping. FDA oversight of in vitro diagnostic devices shapes product registration pathways for assay manufacturers seeking clinical laboratory access. NIH-funded research institutions concentrate exploratory genotyping demand that precedes commercial assay validation.
Brazil
Public health laboratories in São Paulo and Rio de Janeiro process population-scale carrier screening through HPLC and capillary electrophoresis workflows. ANVISA regulates medical device registration for diagnostic kits entering the national health system. The national newborn screening program's maturation into adult testing services sustains reagent demand in southeastern state laboratories.
Germany
Reference laboratories in Munich and Hamburg consolidate molecular diagnostics capacity for outsourced hospital volumes across Central Europe. EMA's In Vitro Diagnostic Regulation extends registration timelines for CE-marked hemoglobinopathy kits through notified body oversight. Manufacturing clusters in Mannheim and Freiburg produce electrophoresis buffers and PCR reagents for export to Brazil and India.
India
Regional diagnostic networks in Maharashtra and Karnataka expand molecular capacity to capture outsourced hospital testing from tier-2 cities. CDSCO regulates import and local assembly of diagnostic reagents under production-linked incentive schemes. Mumbai and Bangalore laboratories pilot portable capillary electrophoresis units for same-day rural screening.
United Kingdom
The Wellcome Trust Sanger Institute near Cambridge concentrates exploratory sequencing demand for modifier gene research in sickle cell disease. MHRA post-Brexit regulatory pathways diverge from EU MDR requirements for hemoglobinopathy assay registration. London hospital systems unbundle after-sales service contracts from instrument procurement to reduce total cost of ownership.
Adult Hemoglobinopathy Testing Market Competitive Environment
Listed leaders compete with private specialists across regulatory compliance capabilities and service network density. The vendor base stratifies into three tiers: multinational conglomerates with dedicated regulatory affairs teams, mid-cap instrument specialists with regional service presence, and emerging point-of-care device developers. Strategic archetypes include electrophoresis heritage players defending reference laboratory relationships, integrated platform providers spanning PCR-to-sequencing workflows, and automation-focused hematology line embedders. Dominant competitive moves center on M&A consolidation to acquire molecular assay portfolios and capacity expansion into India's PLI-subsidized manufacturing zones.
Within the integrated platform tier, Thermo Fisher Scientific Inc. and PerkinElmer Inc. occupy positions spanning research and clinical applications. Siemens Healthineers anchors the automation-focused archetype through hematology line integration. Bio-Rad Laboratories, Inc. exemplifies the electrophoresis heritage specialist defending reference laboratory workflows. These three listed entities represent distinct strategic postures without overlapping core competencies.
| Leading Market Players |
|---|
| Bio-Rad Laboratories, Inc. |
| Thermo Fisher Scientific Inc. |
| Siemens Healthineers |
| Revvity |
| Trinity Biotech |
| PerkinElmer Inc. |
| Roche Diagnostics |
| Abbott Laboratories |
| Sysmex Corporation |
| Others |
Value Chain & Pricing Dynamics
Regional reference laboratory consolidation in Brazil and India generates throughput scale that compresses per-test reagent costs while elevating price floors for specialized genetic panels. This concentration dynamic simultaneously concentrates procurement leverage among diagnostic networks and fragments price-setting power for consumable suppliers serving smaller hospital laboratories.
Pricing Analysis
Next-generation sequencing platforms command premium positioning against legacy capillary electrophoresis systems and emerging point-of-care cartridge devices. Three-tier pricing structure across premium, standard, and economy levels separates integrated PCR-to-sequencing workflows from modular electrophoresis instruments and rapid screening kits. Cost compression in protein-based testing intensifies as Brazilian public health laboratories consolidate purchasing around prequalified vendors. Academic medical centers in the United States exhibit lowest price sensitivity due to NIH-funded research budgets, while community health centers in sub-Saharan Africa face acute budget constraints that favor rental and reagent-only arrangements.
Supply Chain Analysis
Rhine River logistics corridors through Mannheim and Basel concentrate electrophoresis buffer and PCR master mix manufacturing for export to Brazil, India, and the United States. Critical inputs include high-purity acrylamide polymers, fluorophore-labeled primers, and semiconductor sequencing chips that draw from specialized chemical and electronics supply bases. Single-source vulnerability persists for capillary array consumables where Bio-Rad Laboratories maintains dominant production capacity. Distribution runs through regional diagnostic distributors in São Paulo and Mumbai before final-mile delivery to state public health laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through WHO prequalification and EMA MDR compliance creates durable defensive moats for assay manufacturers with dedicated technical documentation teams. Switching costs for diagnostic laboratories are elevated by LIS integration complexity and reagent validation timelines.
For Market Incumbents: Shield reference laboratory relationships in Brazil by embedding service engineers within state public health systems and securing multi-year reagent supply contracts. Accelerate backward integration into capillary array manufacturing to reduce dependence on German polymer suppliers. Next-generation sequencing substitution threatens electrophoresis volume retention; counter by bundling interpretive software licenses that lock in workflow continuity. For New Entrants and Emerging Players: Portable diagnostic service layers in Nigerian and Democratic Republic of Congo health districts present immediate white-space opportunity where centralized laboratory infrastructure remains underdeveloped. Target same-day screening workflows in rural Indian clinics through cartridge-based capillary electrophoresis partnerships with Maharashtra state distributors. Pursue ANVISA fast-track registration for prequalified platforms to bypass incumbent procurement lock-in. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated platform providers spanning PCR amplification to semiconductor sequencing over pure-play electrophoresis specialists facing substitution pressure. Long-term viability over the projection horizon rests on regulatory affairs scalability and installed base service attach rates. Monitor WHO prequalification pipeline velocity as inflection indicator for procurement momentum shifts in member state health systems.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR notified body submission secures European diagnostic laboratory procurement eligibility. |
| Hospital System Partnership | Beckman Coulter middleware integration contracts embed assays into existing hematology workflows. |
| Software Companion Development | Automated variant interpretation tools address molecular cytogenetics skill scarcity in mid-tier laboratories. |
| Reimbursement Strategy | Molecular panel coding expansion captures superior margins versus protein-based screening workflows. |
| Geographic Expansion | India PLI scheme manufacturing foothold reduces import duty exposure for reagent kit assembly. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with diagnostic laboratory directors, regulatory affairs managers at assay manufacturers, and hospital biomedical engineers; and secondary validation through FDA 510(k) filings, ANVISA registration databases, EMA MDR technical documentation, and WHO prequalification listings. Bottom-up triangulation against top-down macroeconomic indicators calibrated market sizing across technology generations and end-user segments.
Across the analysis window, forecasts model technology substitution rates, reimbursement code evolution, and regional laboratory consolidation patterns. Segmentation dimensions include product type, application, end user, and technology platform. CAGRs derive from installed base expansion, reagent consumption curves, and pricing trajectory assumptions. Industry-specific inputs capture EMA MDR compliance timeline delays and Brazilian national screening program maturation.
Forecasts assume regulatory continuity in EMA MDR implementation and WHO prequalification pathways; material policy shifts in either regime would require re-modeling. Practitioners should keep alternative scenarios live as India's PLI scheme localization requirements and sub-Saharan Africa infrastructure investment flows evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Global Biomarkers Market
Clinical Diagnostics
Blood Group Typing Market
Clinical Diagnostics
Nitric Oxide Asthma Testing Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Cardiology Genomic Testing Market
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
Global Hepatitis C Testing Market
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
Global Apoptosis Assays Market
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Chromosomal Aberration Test Market