
 Clinical Refractometer Market | 2026-2036
Clinical Refractometer Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Refractometer Market Analysis
The EU In Vitro Diagnostic Regulation is shifting the cost-of-entry calculus for clinical refractometer manufacturers seeking CE-marked placement in European healthcare systems. Anton Paar GmbH leverages its precision optics heritage to sustain premium positioning in laboratory-grade instrumentation. Reichert Technologies anchors its competitive stance through deep specialization in clinical refractometry for ophthalmic and urinalysis applications. ATAGO competes aggressively in handheld segments where portability commands channel preference.
A clinical refractometer measures refractive index of biological fluids—principally urine, serum, and plasma—using optical or digital detection systems with temperature compensation typically specified to 0.1 °C precision for diagnostic accuracy. The device serves primary commercial purpose in standardized urinalysis screening, where specific gravity readings inform renal function assessment and hydration monitoring protocols. Digital refractometers now dominate hospital procurement budgets given automated readout integration with laboratory information systems, while handheld refractometers occupy growing share in veterinary clinics and decentralized testing environments where capital constraints limit full laboratory infrastructure. Optical technology retains installed-base dominance though microfluidic technology represents the fastest-expanding margin pool as miniaturization enables cartridge-based consumable economics.
FDA 510(k) clearance pathways shape US market access timelines for novel refractometer submissions, while EMA-aligned IVDR technical documentation requirements in Europe extend conformity assessment durations for non-notified-body-ready manufacturers. ISO 13485 quality management certification functions as baseline qualification for supply contracts with integrated health networks across both jurisdictions. Stakeholders must monitor regulatory divergence between FDA's predicate-based framework and IVDR's stricter clinical evidence expectations when prioritizing geographic launch sequencing.
Market Dynamics
Digital refractometer adoption in centralized laboratory networks is compressing replacement cycles while forcing handheld manufacturers to defend channel position through veterinary and point-of-care specialization.
Growth Catalysts
- IVDR Conformity Pressure:The EU In Vitro Diagnostic Regulation mandates enhanced clinical evidence documentation, accelerating hospital procurement of pre-certified digital systems that streamline compliance workflows.
- Microfluidic Cartridge Economics:Miniaturized consumable architectures enable recurring revenue models that attract private equity backing for point-of-care device commercialization.
- German Laboratory Consolidation:Centralized networks in Baden-Württemberg and Bavaria standardize specifications across multi-site contracts, creating volume concentration for qualified suppliers.
Market Restraints
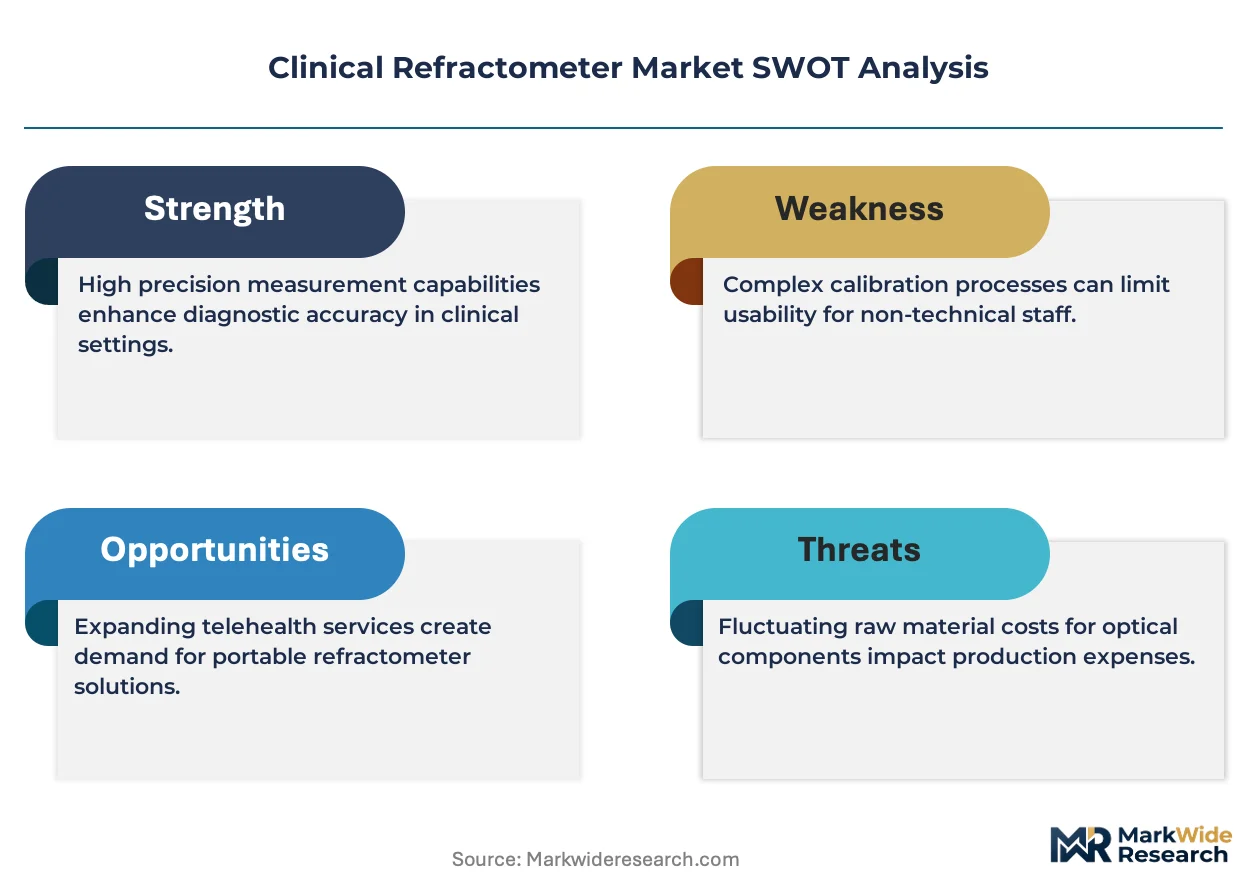
- Optical Component Supply Concentration:Precision prism manufacturing concentrates among German and Japanese specialty glass suppliers, exposing procurement timelines to single-source risk.
- Temperature Compensation Cost Structure:Platinum resistance thermometers and thermoelectric stabilization modules constitute disproportionate bill-of-materials share in mid-tier instruments.
- Predicate Device Pathway Friction:FDA 510(k) clearance requires substantial equivalence demonstrations that delay novel detection algorithm introductions by 12-18 months versus European technical file routes.
Strategic Opportunities
- Veterinary Practice Decentralization:Companion animal diagnostic spending in US metropolitan clusters creates demand for sub-$500 handheld units with species-specific calibration matrices.
- AI-Assisted Readout Convergence:Machine vision algorithms paired with smartphone-connected refractometers enable cloud-based quality control that differentiates emerging players.
- Indian Diagnostic Lab Expansion:NABL-accredited chains in Mumbai and Hyderabad seek automated urinalysis modules that integrate with existing hematology workflows.
Industry Challenges
- ISO 13485 Auditor Capacity Bottlenecks:Notified body queue times for quality management certification extend supplier qualification schedules beyond contract award windows.
- LIS Integration Legacy Protocols:HL7 v2.x middleware requirements consume engineering resources that compress differentiation budgets for mid-size manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Refractometer Market |
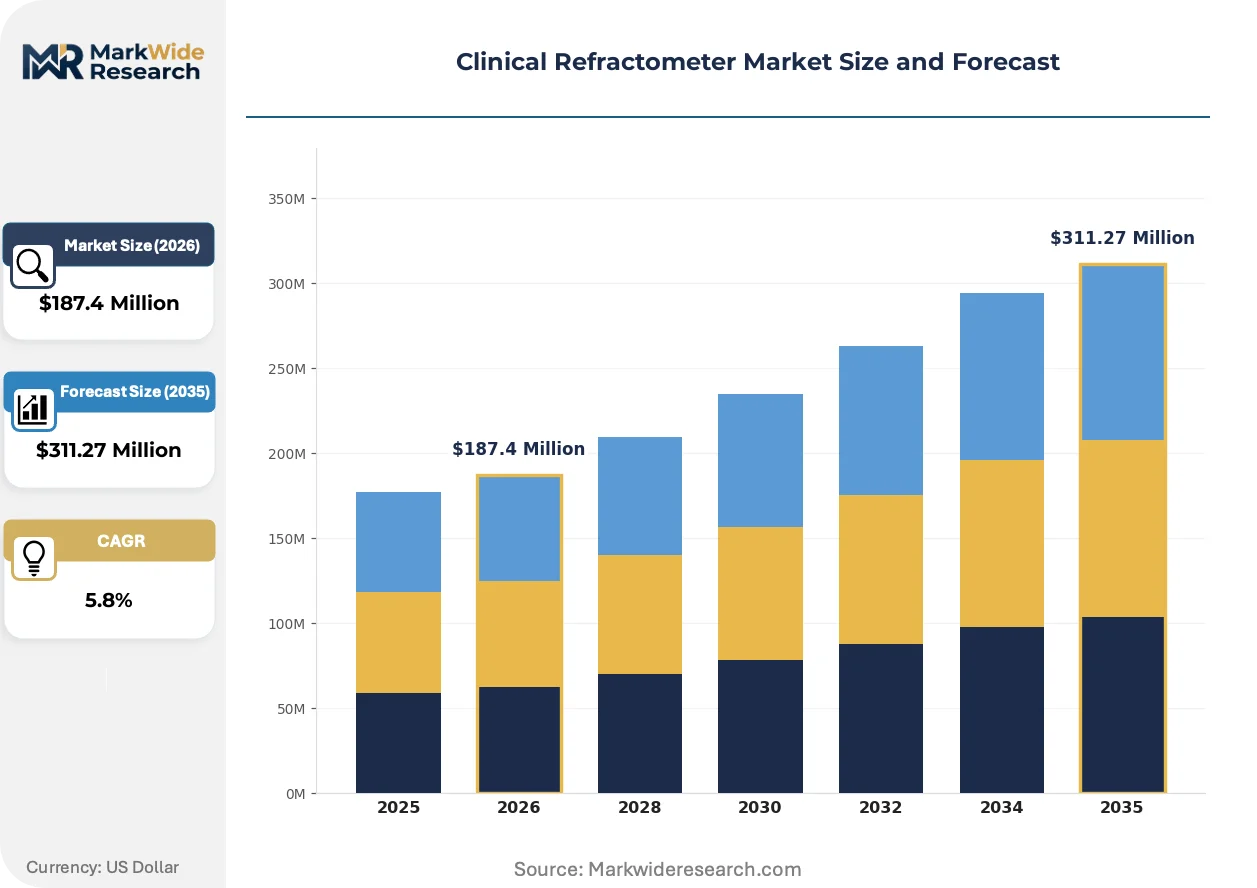
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Refractometers, Analog Refractometers, Handheld Refractometers, Laboratory Refractometers End User: Hospitals, Clinical Laboratories, Research Institutions, Veterinary Clinics Technology: Optical Technology, Laser Technology, Ultrasonic Technology, Microfluidic Technology Application: Urinalysis, Blood Analysis, Quality Control, Fluid Assessment |
| Companies Covered | Anton Paar GmbH, Reichert Technologies, ATAGO, AMETEK, Rudolph Research Analytical, METTLER TOLEDO, Xylem Analytics, Krüss Optronic, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Refractometer Market Emerging Trajectories
Refractometer architecture is bifurcating between laboratory systems pursuing full automation integration and handheld devices exploiting connectivity and consumable economics for distributed testing environments.
Digital refractometry with CMOS sensor arrays and LED illumination sources is unifying refractive index measurement with automated specific gravity conversion, eliminating operator interpretation variance. Hospital laboratories in Germany and Switzerland adopt these systems at replacement-cycle acceleration, compressing the installed base of optical Abbe-type instruments into veterinary and educational segments. This unification enables direct LIS data transmission that removes transcription error liability from clinical workflow documentation.
EMA-aligned IVDR technical documentation requirements are extending conformity assessment durations for manufacturers lacking prior MDD experience, favoring incumbent notified body relationships. The regulation's clinical evidence expectations for Class B devices now demand performance studies that previously sufficed with literature reviews. Point-of-care refractometer developers respond by prioritizing US FDA 510(k) submissions for revenue timing certainty.
Diagnostic procurement through group purchasing organizations is consolidating vendor panels at integrated delivery networks, compressing approved supplier lists from twelve to three refractometer sources. Hospital systems in Texas and California leverage volume commitments for extended warranty and service bundling that displaces independent distributor relationships. This concentration is most visible in US academic medical centers where capital equipment committees mandate interoperability certifications.
Clinical Refractometer Market Segmentation
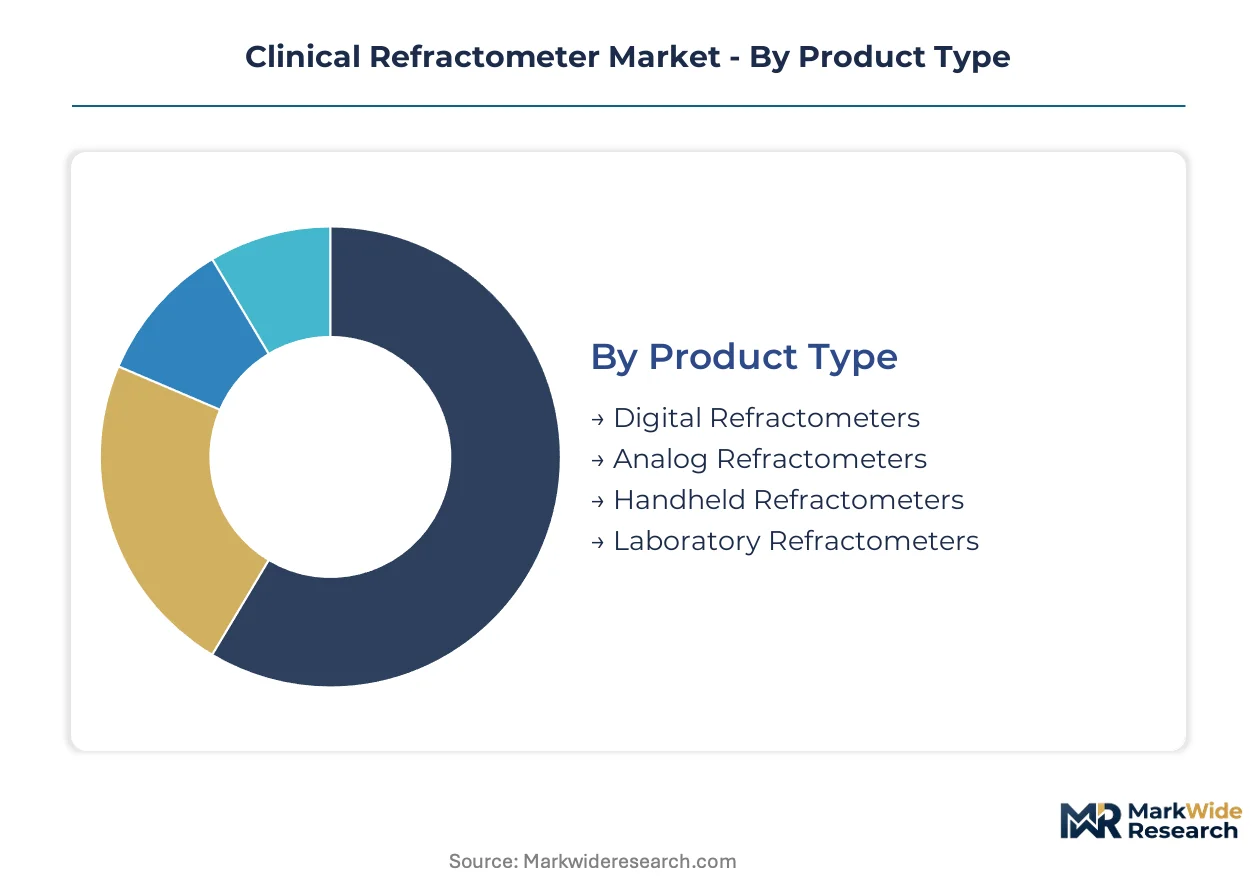
Clinical refractometer purchasing patterns diverge sharply between integrated laboratory systems and standalone point-of-care deployments. Understanding these structural splits reveals where procurement budgets concentrate and which technology transitions command capital allocation priority.
Product Type:
Standalone instruments dominate centralized laboratory procurement, while embedded modules capture point-of-care and veterinary workflows where space constraints and capital budgets limit full infrastructure investment.
- Digital Refractometers:CMOS sensor arrays with LED illumination and automated temperature compensation deliver direct LIS integration. Hospital systems in Germany and Switzerland accelerate replacement cycles to capture error-reduction benefits in high-throughput urinalysis workflows.
- Handheld Refractometers:Battery-powered units with refractive index readouts suit decentralized testing environments. Veterinary clinics in US metropolitan clusters drive procurement of sub-$500 calibrated units for companion animal diagnostics.
- Analog Refractometers:Optical Abbe-type instruments with manual prism adjustment retain installed-base presence in educational settings and budget-constrained facilities.
- Laboratory Refractometers:Benchtop systems with thermoelectric stabilization and multi-sample handling anchor centralized diagnostic infrastructure.
Digital refractometers lead volumes today; handheld units are gaining share fastest in decentralized care settings.
End User:
Procurement authority concentrates in integrated delivery networks that standardize specifications across multi-site contracts, compressing vendor panels and favoring suppliers with established service infrastructure.
- Hospitals:Acute care facilities with automated urinalysis lines demand IVDR-compliant digital systems with HL7 middleware compatibility. Centralized networks in Baden-Württemberg and Bavaria consolidate purchasing to capture volume discounts.
- Clinical Laboratories:Independent and hospital-affiliated labs prioritize throughput metrics and regulatory pre-certification. NABL-accredited chains in Mumbai and Hyderabad seek modules that integrate with hematology workflows.
- Veterinary Clinics:Companion animal practices value portability and species-specific calibration matrices over laboratory-grade precision.
- Research Institutions:Academic medical centers require interoperability certifications and extended warranty bundling for capital equipment committees.
Clinical laboratories lead volumes today; veterinary clinics are climbing the fastest as pet diagnostic spending expands.
Technology:
Detection methodology determines margin structure, with consumable-enabled architectures attracting private equity backing and optical systems defending installed-base revenue through service contracts.
- Optical Technology:Prism-based refractive index measurement with visible light sources commands legacy installed-base dominance. Precision glass manufacturing concentrates among German and Japanese specialty suppliers.
- Microfluidic Technology:Cartridge-based miniaturization enables recurring revenue models and point-of-care deployment. This segment is expanding most quickly as consumable economics reshape commercialization strategies.
- Laser Technology:Coherent light sources improve precision for specialized serum and plasma applications in reference laboratories.
- Ultrasonic Technology:Acoustic velocity measurement offers alternative refractive index detection for industrial-quality fluid assessment crossover applications.
Optical technology leads volumes today; microfluidic systems are gaining share fastest through cartridge-based economics.
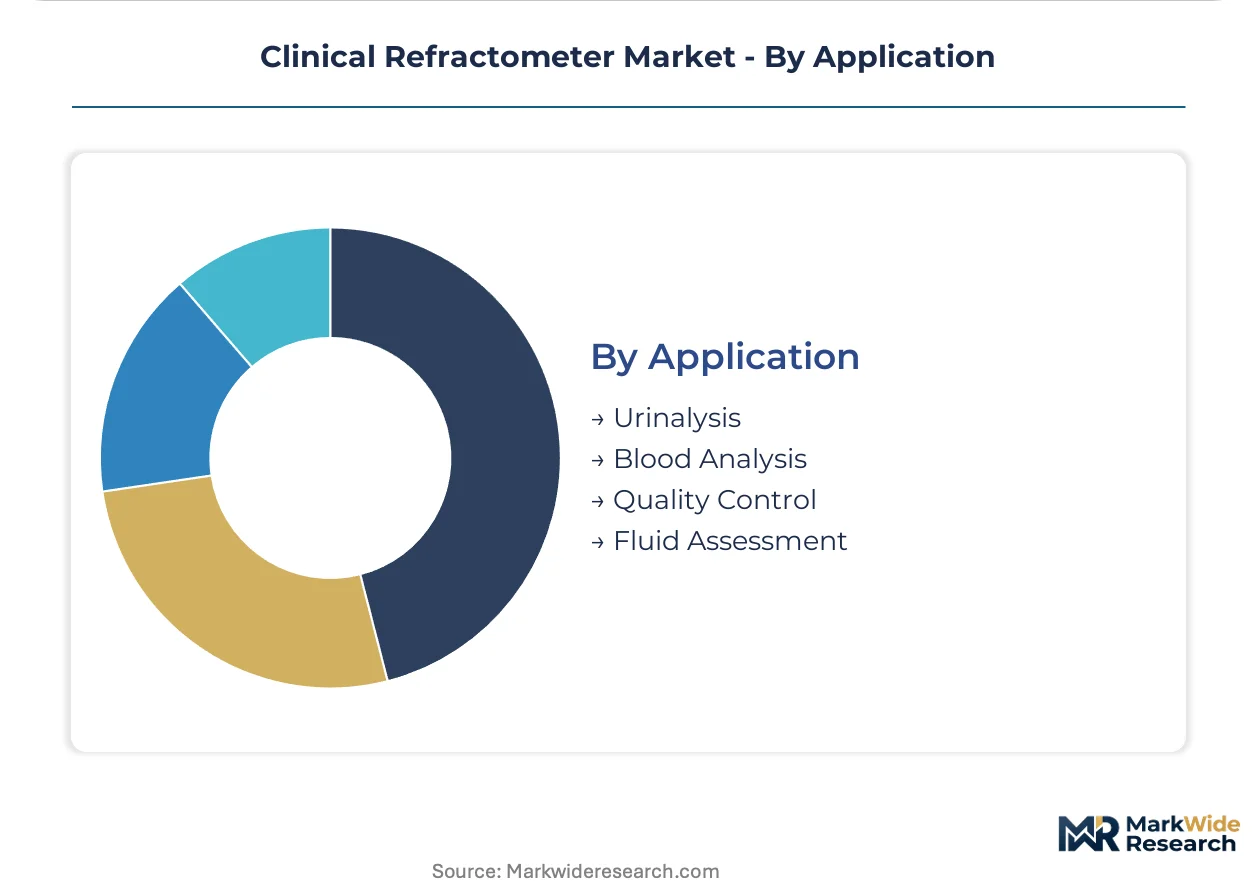
Application:
Workflow integration requirements vary by clinical purpose, with urinalysis demanding highest throughput automation and blood analysis requiring superior precision for therapeutic monitoring.
- Urinalysis:Specific gravity screening for renal function and hydration status drives highest unit volume. Digital refractometers with automated readout capture standardization mandates from EU IVDR clinical evidence requirements.
- Blood Analysis:Serum and plasma refractive index measurement for protein concentration and therapeutic drug monitoring commands premium pricing in reference laboratory segments.
- Quality Control:Process validation in pharmaceutical manufacturing and clinical laboratory accreditation protocols sustains replacement demand for calibrated instrumentation.
- Fluid Assessment:Cerebrospinal fluid and other biological specimen analysis occupies niche applications with specialized precision requirements.
Urinalysis leads volumes today; blood analysis is climbing the fastest as precision therapeutics expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision optics manufacturing originated in German university workshops during the 19th century, establishing Central Europe as the foundational geography for clinical refractometer engineering standards and quality protocols that persist today.
Germany
Centralized laboratory networks in Baden-Württemberg and Bavaria drive standardization of refractometer specifications across multi-site procurement contracts. EMA-aligned IVDR technical documentation requirements extend conformity assessment durations for new market entrants. Stuttgart and Munich host precision optics clusters where specialty glass suppliers maintain single-source positions for critical prism components.
United States
Hospital systems in Texas and California leverage group purchasing organization volume commitments for extended warranty bundling on digital refractometer deployments. FDA 510(k) clearance pathways shape market access timelines for novel detection algorithm introductions. Academic medical centers in Boston and Houston mandate interoperability certifications that compress approved vendor panels.
Switzerland
Swissmedic regulations enforce clinical evidence standards that favor pre-certified digital systems from established laboratory instrumentation suppliers. Basel and Zurich anchor pharmaceutical-quality diagnostic equipment manufacturing clusters. Private hospital networks standardize on thermoelectric-stabilized benchtop systems for therapeutic drug monitoring workflows.
India
NABL-accredited diagnostic chains in Mumbai and Hyderabad seek automated urinalysis modules that integrate with hematology analyzer workflows. CDSCO import licensing requirements shape procurement timelines for foreign-manufactured point-of-care devices. Bangalore and Chennai emerging as veterinary diagnostic equipment distribution hubs for South Asian markets.
Japan
PMDA quality system regulations maintain stringent post-market surveillance requirements that sustain premium pricing for precision optical instruments. Tokyo and Osaka metropolitan laboratory networks accelerate replacement cycles for CMOS sensor-based digital refractometers. METI industrial standards support domestic manufacturers in handheld device segments for decentralized testing environments.
Clinical Refractometer Market Vendor Landscape
The competitive structure tilts toward precision optics heritage players with established notified body relationships. Laboratory-grade instrumentation concentrates among Central European and North American suppliers with ISO 13485 certification depth, while handheld segments attract Asian manufacturers competing on portability and capital cost. Two strategic archetypes dominate: integrated conglomerates leveraging cross-divisional service infrastructure, and specialized refractometry houses defending position through application-specific calibration expertise. Competitive moves center on M&A for regulatory certification assets and strategic partnerships for LIS middleware integration.
Among precision optics specialists, Anton Paar GmbH and Reichert Technologies exemplify the heritage-driven archetype with deep specialization in laboratory-grade refractometry, while ATAGO occupies a position within the handheld segment where portability commands channel preference in veterinary and point-of-care environments. These three anchors represent distinct competitive vectors—European precision engineering, North American clinical application focus, and Asian manufacturing scale—without overlapping positioning in procurement budget tiers.
| Leading Market Players |
|---|
| Anton Paar GmbH |
| Reichert Technologies |
| ATAGO |
| AMETEK |
| Rudolph Research Analytical |
| METTLER TOLEDO |
| Xylem Analytics |
| Krüss Optronic |
| Thermo Fisher Scientific |
| Others |
Supply Flow & Price Mechanics
Platinum resistance thermometers and thermoelectric stabilization modules anchor the mid-tier instrument cost structure, flowing from Japanese and German precision component suppliers through three distinct pricing tiers that separate laboratory-grade digital systems from handheld veterinary units and budget optical instruments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IVDR-certified laboratory systems from mid-tier hospital instruments and sub-$500 handheld veterinary devices. Price differentiation hinges on certification grade—EMA-aligned technical documentation versus basic CE marking—and after-sales service bundling through GPO contracts. Cost compression in the handheld tier is intensifying because Asian manufacturers exploit CMOS sensor commoditization. Veterinary clinics exhibit highest price sensitivity; Swiss private hospital networks show lowest.
Supply Chain Analysis
Precision optics technician shortages in Stuttgart and Tokyo constrain prism manufacturing throughput for critical refractive index components. Supply concentrates in Germany, Japan, and Switzerland for specialty glass, platinum sensors, and thermoelectric modules. Raw material dependencies include borosilicate crown glass, platinum wire, and rare-earth phosphors for LED illumination. Single-source vulnerability pervades the German prism supplier base. Distribution runs through integrated delivery network procurement committees and veterinary distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical refractometer commercialization rewards geographic arbitrage between FDA 510(k) predicate pathways in the United States and extended IVDR conformity timelines in Europe, with regulatory cost differentials exceeding twelve months in market access velocity.
For Market Incumbents: Lock in multi-site service contracts with Baden-Württemberg and Bavaria laboratory networks before replacement cycle peaks. Deepen backward integration into precision prism manufacturing to offset single-source exposure from Stuttgart-area glass suppliers. Prioritize AI-assisted readout R&D to preempt smartphone-connected refractometer entrants. For New Entrants and Emerging Players: Capture veterinary clinic procurement in US metropolitan clusters through sub-$500 handheld units with species-specific calibration matrices. Exploit microfluidic cartridge economics to establish recurring revenue models that attract private equity backing. Lead with cloud-based quality control differentiation against legacy optical instruments. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 auditor capacity bottlenecks extend supplier qualification timelines beyond contract windows. Five-to-ten year viability favors specialized refractometry houses with established notified body relationships over undifferentiated optical instrument assemblers. Watch CDSCO import licensing velocity in Mumbai and Hyderabad as inflection indicator for Indian diagnostic lab expansion.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Pre-Certification Investment | EMA-aligned technical documentation accelerates hospital procurement in German laboratory networks. |
| Microfluidic Cartridge Development | Consumable economics enable recurring revenue models for point-of-care commercialization. |
| LIS Middleware Partnership | HL7 v2.x integration removes transcription error liability from urinalysis workflows. |
| Veterinary Distribution Channel Expansion | Companion animal diagnostic spending in US metropolitan clusters drives handheld volume. |
| Precision Optics Backward Integration | In-house prism manufacturing mitigates single-source risk from Stuttgart glass suppliers. |
Methodological Framework
Multiple input streams — primary interviews with biomedical engineers, hospital purchasing committees, and GPO contracts managers; secondary validation against FDA 510(k) filings, EMA IVDR technical documentation, and hospital procurement databases; plus customs records for precision optics trade flows — were reconciled through bottom-up instrument shipment tracking and top-down diagnostic equipment expenditure analysis.
Historical replacement cycle patterns were cross-referenced against panel input from laboratory instrumentation specialists to model adoption curves across the projection horizon. Segmentation dimensions included product architecture, end-user procurement authority, detection methodology, and application workflow. CAGRs were derived from unit volume trajectories weighted by average selling price evolution, with IVDR implementation timelines and veterinary diagnostic spending curves as industry-specific forecast inputs.
Regulatory pathway delays, precision component supply disruptions, and diagnostic procurement budget freezes are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on replacement cycle acceleration and GPO vendor panel consolidation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Cervical Cancer Screening Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Artificial Intelligence in Cancer Diagnostics Market
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market
Clinical Diagnostics
Herpes Marker Testing Market
Clinical Diagnostics
Blood Urea Nitrogen Testing Market
Clinical Diagnostics
Global Cervical Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Clinical Microbiology Market
Clinical Diagnostics
Global Breast Cancer Screening Test Market
Clinical Diagnostics
Bone Metabolism Test Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Cardiology Genomic Testing Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market
Clinical Diagnostics
Global Monocyte Activation Tests Market