
 Food Allergy Diagnosis and Treatment Market | 2026-2036
Food Allergy Diagnosis and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Food Allergy Diagnosis and Treatment Market Analysis
The EU MDR is broadening compliance costs for diagnostic kit manufacturers entering European markets. Aimmune Therapeutics leverages its peanut allergy therapeutic specialization to anchor US market presence. Thermo Fisher Scientific sustains laboratory channel dominance through allergen detection assay breadth.
Food allergy diagnosis and treatment encompasses clinical identification of IgE-mediated hypersensitivity reactions through skin prick testing, serum specific-IgE immunoassays, and oral food challenges, followed by therapeutic intervention via allergen immunotherapy desensitization protocols, biologic monoclonal antibodies, and emergency epinephrine administration. Epinephrine injectors occupy the largest revenue pool due to mandatory patient carry requirements and replacement cycles, while allergen immunotherapy represents the fastest-expanding segment as sublingual tablet formulations displace injection-based protocols in clinic and homecare settings.
FDA, EMA, and ISO 13485 collectively govern device safety, biologic efficacy thresholds, and quality management systems across this market. These frameworks elevate R&D expenditure floors and extend validation timelines, particularly for novel delivery modes seeking pediatric indications. Stakeholders must monitor evolving biosimilar pathways and real-world evidence requirements that will determine competitive positioning in next-generation immunotherapy.
Market Dynamics
The FDA's accelerated approval pathways for biologics are compressing development timelines while simultaneously elevating validation expenditure floors, creating a bifurcation between well-capitalized developers and mid-tier diagnostic manufacturers.
Growth Catalysts
- Sublingual immunotherapy tablets:These formulations are displacing injection-based protocols in pediatric and homecare settings across Germany and France, expanding addressable patient populations beyond clinic-dependent administration.
- EU MDR compliance frameworks:Diagnostic kit manufacturers investing early in ISO 13485-aligned quality systems are capturing shelf space as smaller competitors withdraw from European market entry.
- Peanut allergy prevalence clusters:Concentrated patient populations in the United States sustain epinephrine injector replacement cycles and drive volume commitments through mandatory carry requirements.
Market Restraints
- Specialized allergen extract supply:Production of standardized peanut, tree nut, and shellfish extracts concentrates among a limited supplier base in North America, creating input vulnerability for immunotherapy developers.
- Pediatric indication timelines:FDA requirements for extended safety databases in patients under 12 years extend validation periods and defer revenue recognition for novel biologic modalities.
- Epinephrine pricing compression:Pharmacy benefit managers in the United States are narrowing reimbursement bands for auto-injector devices, squeezing margin structures across the category.
Strategic Opportunities
- Real-world evidence pathways:FDA's evolving framework for post-market surveillance data is enabling label expansion for approved biologics without redundant Phase III replication.
- Home-based oral food challenge protocols:Telemedicine-integrated supervision models are opening rural and exurban patient access points previously excluded by specialist geography.
- Biosimilar immunotherapy development:EMA's clarified comparability guidelines for allergen extracts create entry corridors for European manufacturers with established GMP infrastructure.
Industry Challenges
- Pediatric allergist workforce density:Fellowship-trained specialists concentrate in metropolitan corridors, creating access bottlenecks for immunotherapy administration in secondary markets.
- Cross-reactive allergen characterization:Definitive molecular diagnostic protocols for legume and seafood homology remain inconsistently deployed, generating diagnostic uncertainty and treatment delay.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Allergy Diagnosis and Treatment Market |
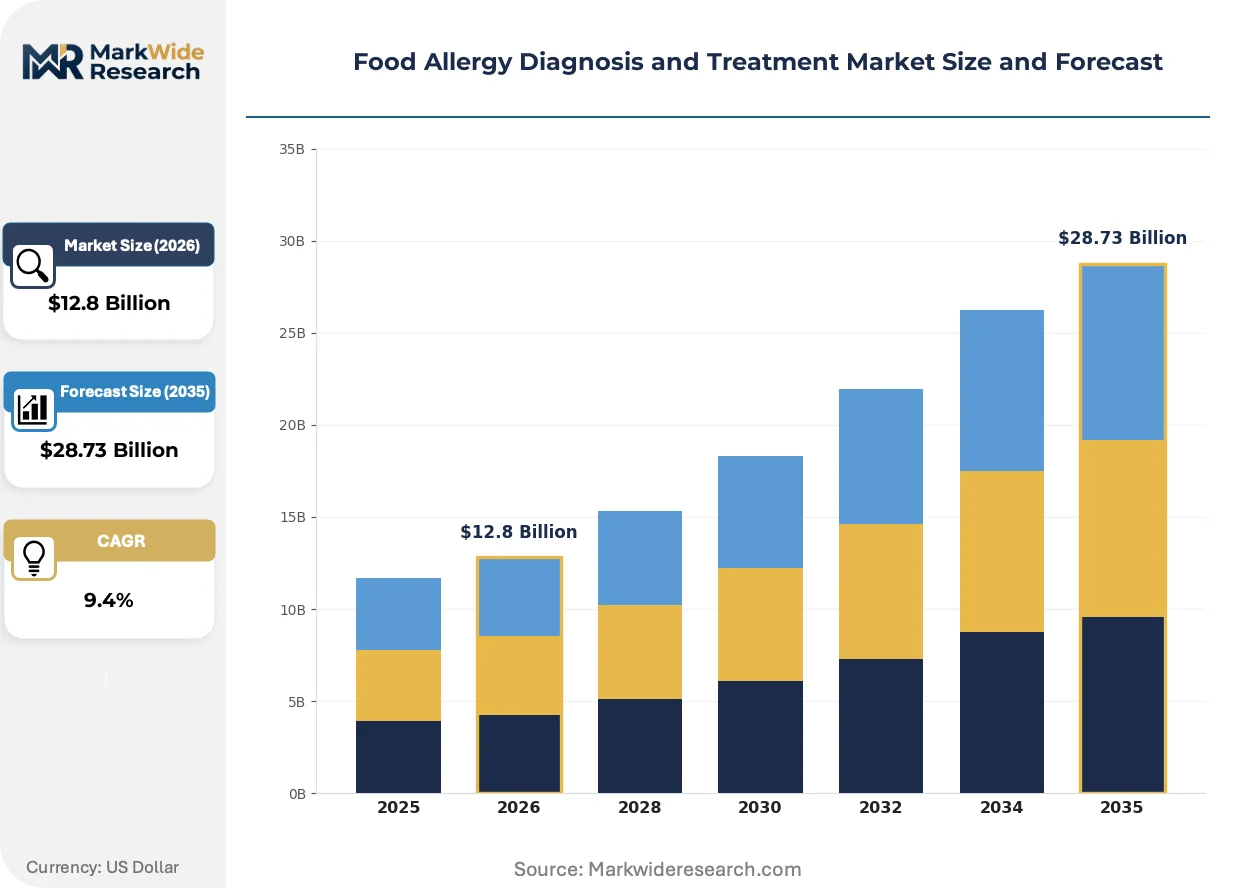
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Allergen Immunotherapy, Antihistamines, Epinephrine Injectors, Diagnostic Kits End User: Clinics, Hospitals, Homecare Settings, Laboratories Delivery Mode: Injectable, Oral, Sublingual, Intranasal Application: Pediatric Care, Adult Care, Emergency Care, Research |
| Companies Covered | DBV Technologies, Vedanta Biosciences, Alladapt Immunotherapeutics, Aimmune Therapeutics, Sanofi, Novartis, Thermo Fisher Scientific, Danaher, Regeneron Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Allergy Diagnosis and Treatment Market Emerging Trajectories
Biologic monoclonal antibodies are absorbing development priority as allergen immunotherapy delivery modalities fragment across clinical and home settings, reshaping competitive positioning between pharmaceutical and device manufacturers.
Component-resolved diagnostics is absorbing investment from reference laboratories seeking to differentiate serum IgE testing beyond whole-allergen panels. Thermo Fisher Scientific and Quest Diagnostics are expanding assay menus for individual allergen proteins. This precision is compressing false-positive rates and enabling targeted immunotherapy selection.
EMA's implementation of the In Vitro Diagnostic Regulation is absorbing compliance resources from European diagnostic kit entrants, extending registration timelines for novel allergen detection platforms. Manufacturers with legacy CE-marked portfolios are defending position through transitional provision exploitation. German and French notified bodies are experiencing backlog concentration.
Patient self-administration preferences are absorbing channel configuration decisions, with sublingual tablet formulations capturing share from physician-administered injections. Allergy clinics in the United States are unbundling supervision from product provision. Retail pharmacy networks in California and Texas are capturing dispensing volume previously held by specialty infusion centers.
Food Allergy Diagnosis and Treatment Market Segmentation
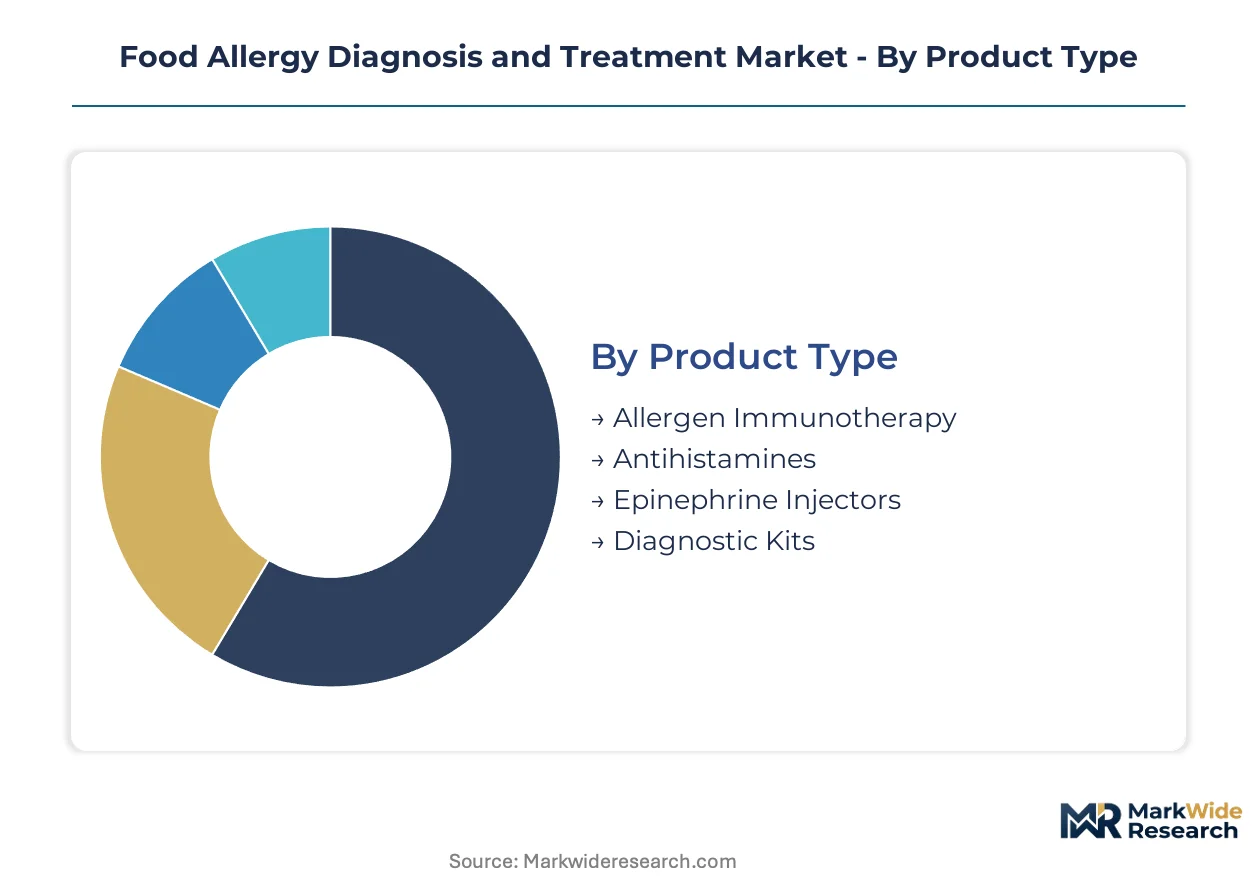
Segmentation in food allergy care separates high-volume commodity products from premium biologic interventions, with reimbursement pathways and patient acuity determining profitability across each slice. Manufacturers configure R&D portfolios differently depending on whether they target institutional procurement or direct-to-patient dispensing channels.
Product Type:
Epinephrine injectors command the largest revenue pool due to mandatory carry requirements and replacement cycles, while allergen immunotherapy represents the fastest-expanding segment as sublingual tablet formulations displace injection-based protocols.
- Epinephrine Injectors:Auto-injector devices deliver standardized epinephrine doses during anaphylactic events. Demand concentrates in the United States where peanut allergy prevalence drives volume through pharmacy benefit manager formularies and school district procurement mandates.
- Allergen Immunotherapy:Desensitization protocols using standardized allergen extracts or biologic monoclonal antibodies reduce hypersensitivity over time. Pediatric clinics in Germany are expanding adoption as sublingual tablets enable home administration beyond specialist-dependent injection models.
- Diagnostic Kits:Serum specific-IgE immunoassays and component-resolved diagnostic platforms identify trigger allergens. Thermo Fisher Scientific sustains laboratory channel dominance through assay menu breadth.
- Antihistamines:H1-receptor antagonists manage mild allergic symptoms without interrupting daily activity. Over-the-counter distribution through retail pharmacy networks in California and Texas captures volume.
Mature deployment sits with Epinephrine Injectors. Newer deployment is concentrated in Allergen Immunotherapy.
End User:
Institutional procurement through hospital systems favors bundled diagnostic-therapeutic contracts, while homecare channels reward patient self-administration products with simpler storage and handling requirements.
- Homecare Settings:Patient-directed administration of sublingual immunotherapy tablets and epinephrine auto-injectors reduces specialist visit burden. Pharmacy benefit managers in the United States are narrowing reimbursement bands for devices dispensed through retail networks.
- Clinics:Fellowship-trained allergists supervise oral food challenges and injection-based immunotherapy protocols. Access bottlenecks persist in secondary markets where pediatric allergist workforce density concentrates in metropolitan corridors.
- Hospitals:Emergency departments manage acute anaphylaxis presentations requiring immediate epinephrine intervention. FDA requirements for extended safety databases in patients under 12 years extend validation periods for novel biologics seeking pediatric indications.
- Laboratories:Reference laboratories process serum specific-IgE testing and component-resolved diagnostic panels. Quest Diagnostics is expanding assay menus for individual allergen proteins to compress false-positive rates.
Volume leadership belongs to Clinics. Margin expansion is climbing the fastest in Homecare Settings.
Delivery Mode:
Route selection determines regulatory pathway complexity, with parenteral formulations requiring stricter sterility validation than mucosal or enteral alternatives.
- Sublingual:Orally dissolving tablets deliver standardized allergen doses beneath the tongue. Formulations are displacing injection-based protocols in pediatric and homecare settings across Germany and France.
- Injectable:Subcutaneous or intramuscular administration of epinephrine or allergen extracts requires clinical supervision. Production of standardized peanut, tree nut, and shellfish extracts concentrates among a limited supplier base in North America.
- Oral:Entire allergen exposure protocols conducted under medical supervision desensitize patients through controlled ingestion. Telemedicine-integrated supervision models are opening rural and exurban patient access points.
- Intranasal:Mucosal delivery of antihistamines or corticosteroids manages rhinitis symptoms associated with food-triggered respiratory responses. Limited penetration reflects narrower indication scope.
Injectable routes retain the largest installed base. Sublingual deployment is gaining share fastest among new patient starts.
Application:
Pediatric indications command premium pricing and extended exclusivity, though FDA safety database requirements lengthen development timelines compared to adult-only approvals.
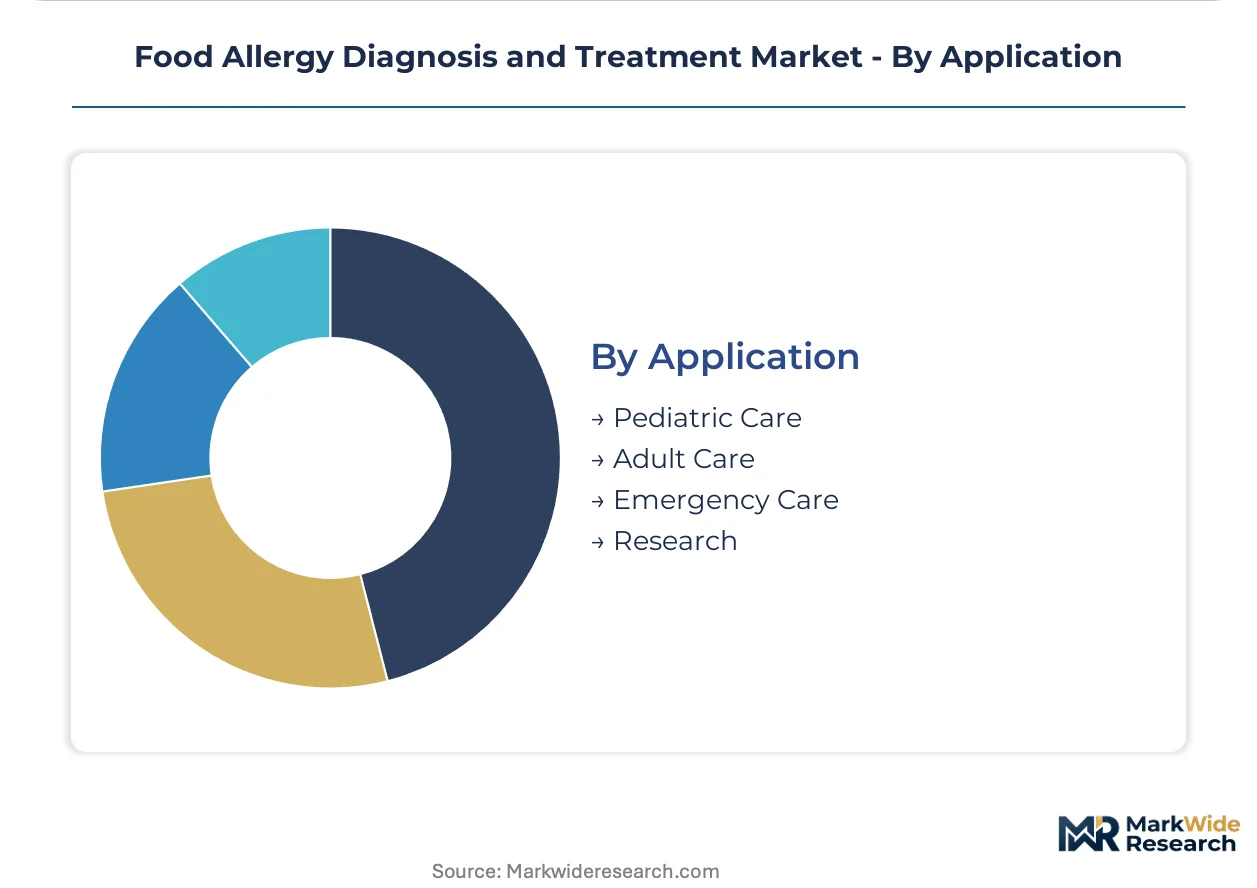
- Pediatric Care:Early intervention protocols target immune system plasticity in patients under 18 years. Aimmune Therapeutics leverages peanut allergy therapeutic specialization to anchor US market presence.
- Emergency Care:Acute anaphylaxis management requires immediate epinephrine access and airway stabilization. Concentrated patient populations in the United States sustain auto-injector replacement cycles.
- Adult Care:Late-onset allergy identification and maintenance therapy address acquired sensitivities in patients over 18 years. Component-resolved diagnostics enable targeted immunotherapy selection.
- Research:Clinical trial infrastructure supports novel biologic development and real-world evidence generation. FDA's evolving framework for post-market surveillance data enables label expansion without redundant Phase III replication.
Adult Care represents the largest treated population. Pediatric Care shows the steepest expansion trajectory as early intervention protocols prove durable efficacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for food allergy diagnostics and therapeutics concentrates in high-prevalence clusters across North America and Western Europe, with regulatory frameworks and reimbursement policies shaping adoption velocity in each national market.
United States
Peanut allergy prevalence drives epinephrine auto-injector volumes through pharmacy benefit manager formularies and school district procurement mandates. FDA accelerated approval pathways for biologics compress development timelines while elevating validation expenditure floors. The Boston-Cambridge corridor anchors biologic development clusters where Aimmune Therapeutics maintains therapeutic specialization.
Germany
Pediatric clinics expand sublingual immunotherapy tablet adoption as home administration protocols displace injection-dependent models. EMA oversight through the EU MDR broadens compliance costs for diagnostic kit manufacturers entering European markets. Munich and Heidelberg concentrate reference laboratory capacity where allergen detection assay deployment accelerates.
France
Sublingual tablet formulations capture share from physician-administered injections in allergy clinic networks across Paris and Lyon. ANSM notification requirements extend registration timelines for novel allergen detection platforms. The Île-de-France region hosts concentration of pediatric allergist specialists driving immunotherapy protocol adoption.
United Kingdom
NHS procurement frameworks favor bundled diagnostic-therapeutic contracts through hospital system purchasing. MHRA alignment with EMA standards streamlines biologic approval pathways post-Brexit transition. London and Manchester metropolitan corridors concentrate fellowship-trained allergist workforce density.
Japan
PMDA pediatric indication requirements extend safety database validation periods for novel biologic modalities seeking approval. Component-resolved diagnostics investment flows from reference laboratories in Tokyo and Osaka seeking serum IgE testing differentiation. METI funding channels support allergen extract standardization infrastructure development.
Food Allergy Diagnosis and Treatment Market Vendor Landscape
United States producers anchor the biologic development tier; European diagnostic specialists hold laboratory channel dominance. Market structure bifurcates between well-capitalized pharmaceutical developers pursuing monoclonal antibody platforms and mid-tier diagnostic manufacturers navigating ISO 13485 compliance burdens. Three archetypes predominate: peanut allergy therapeutic specialists, reference laboratory assay providers, and emergency epinephrine device manufacturers. Competitive moves concentrate on real-world evidence generation for label expansion and sublingual formulation portfolio diversification.
Among biologic developers, Aimmune Therapeutics and Regeneron Pharmaceuticals occupy positions exemplifying the peanut allergy therapeutic specialization archetype, while Thermo Fisher Scientific anchors the reference laboratory channel through allergen detection assay breadth. DBV Technologies and Vedanta Biosciences represent emerging modality approaches within the immunotherapy segment, with Sanofi and Novartis sitting within diversified pharmaceutical portfolios that span emergency care and maintenance therapy vectors.
| Leading Market Players |
|---|
| DBV Technologies |
| Vedanta Biosciences |
| Alladapt Immunotherapeutics |
| Aimmune Therapeutics |
| Sanofi |
| Novartis |
| Thermo Fisher Scientific |
| Danaher |
| Regeneron Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Peanut extract commodity pricing volatility cascades through immunotherapy manufacturing tiers, compressing margins for sublingual tablet producers while amplifying cost pass-through leverage for vertically integrated epinephrine device manufacturers serving pharmacy benefit manager formularies.
Pricing Analysis
Volume leadership sits with epinephrine auto-injectors, where mandatory replacement cycles and school district procurement mandates sustain throughput despite narrowing pharmacy benefit manager reimbursement bands. Premium-mid-economy pricing differentiation separates FDA-approved biologics from compounded allergen extracts, with certification tier and pediatric indication status determining formulary placement. Cost compression in the generic auto-injector tier is intensifying because pharmacy benefit managers are consolidating vendor panels. Hospital systems demonstrate lowest price sensitivity due to bundled emergency care contracts, while retail pharmacy networks face acute margin pressure from narrow reimbursement bands.
Supply Chain Analysis
Single-source vulnerability sits with North American suppliers of standardized peanut, tree nut, and shellfish extracts, where production concentrates among limited GMP-certified facilities. Manufacturing draws from specialized allergen extract producers in the United States, Germany, and France, with raw material dependencies spanning pharmaceutical-grade glycerin, histamine diluents, and precision-milled allergen proteins. Regulatory restriction risk elevates as EMA's In Vitro Diagnostic Regulation extends registration timelines for diagnostic kit entrants. Distribution runs through hospital system purchasing cooperatives, specialty allergy clinic networks, and retail pharmacy chains with cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food allergy market occupies a technology-transition phase where sublingual immunotherapy tablets systematically displace injection-based protocols, rewarding developers with home administration capabilities and penalizing clinic-dependent service models.
For Market Incumbents: Cement laboratory channel dominance through component-resolved diagnostic assay menu expansion, defending against reference laboratory competitors by securing exclusive GPO contracts with hospital systems. Backward integration into allergen extract production mitigates input vulnerability from the concentrated North American supplier base. For New Entrants and Emerging Players: Enter via telemedicine-integrated oral food challenge supervision, capturing rural and exurban patient populations excluded by metropolitan allergist concentration. Home-based pediatric immunotherapy administration represents the most penetrable application segment, with direct-to-patient subscription models offering the strongest go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors biologic developers with FDA-accelerated approval pathways and real-world evidence generation capabilities, positioning for label expansion without redundant Phase III replication. Watch FDA pediatric indication timeline compression as the inflection signal distinguishing viable acquisition targets from stranded development assets.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Generation | FDA's evolving post-market surveillance framework enables biologic label expansion without Phase III replication. |
| Sublingual Formulation Portfolio Diversification | Home administration protocols displace clinic-dependent injection models in German and French pediatric networks. |
| Component-Resolved Diagnostic Assay Expansion | Thermo Fisher Scientific and Quest Diagnostics differentiate serum IgE testing beyond whole-allergen panels. |
| EU MDR Compliance Investment | ISO 13485-aligned quality systems capture shelf space as smaller diagnostic competitors withdraw from European entry. |
| Pediatric Indication Safety Database Buildout | Extended FDA requirements for patients under 12 years extend validation periods but secure premium pricing tiers. |
Methodological Framework
Independent corroboration across regulatory filings, hospital procurement databases, and pharmaceutical pipeline disclosures underwrites the qualitative findings in this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Rate-of-change decomposition across product type, delivery mode, end user, application, and regional regulatory cluster dimensions structured the analytical framework. CAGRs derived from fitted growth curves applied to base-year sizing, with allergen immunotherapy tablet adoption velocity and epinephrine auto-injector replacement cycle frequency serving as key forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA pediatric indication timeline extensions or EMA diagnostic kit registration backlogs. Forecasts reflect documented assumptions about sublingual tablet displacement rates and biologic accelerated approval pathway utilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Lab Automation in Clinical Diagnostics Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Kidney Function Tests Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Blood Group Typing Market
Clinical Diagnostics
Heart Failure Testing Market
Clinical Diagnostics
Global Cervical Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
Genetic Disease Diagnostic Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Global Hepatitis C Testing Market