
 Urinary Collection Device Market | 2026-2036
Urinary Collection Device Market Size, Share, and Industry Trends Forecast 2026-2036
Urinary Collection Device Market Outlook
Market Context
Buyer fragmentation across home care settings is expanding as patients transition from institutional facilities to self-managed environments. Becton Dickinson and Company leverages its hospital supply chain to reach decentralized purchasers. Coloplast A/S specializes in hydrophilic-coated intermittent catheters for independent users. Medtronic anchors its position through urological navigation systems that integrate with collection workflows.
Technical Definition and Segments
A urinary collection device comprises catheters, drainage bags, external sheaths, or collection funnels manufactured from silicone, PVC, or latex with hydrophobic surface treatments, designed to channel urine from the bladder or external genitalia into a closed receptacle for measurement, disposal, or analysis. Catheters command the largest product segment due to indwelling and intermittent procedural volumes, while sheaths gain traction in male ambulatory populations seeking non-invasive alternatives. Among end users, home care represents the fastest-expanding channel as reimbursement shifts favor community-based chronic management over nursing facility stays.
Regulatory Outlook
FDA 510(k) pathways and EU MDR Class IIa/IIb designation govern device biocompatibility, sterility assurance, and latex labeling for urinary collection products. ISO 10993 biological evaluation standards and Japan's PMDA quality management requirements further constrain material selection and manufacturing validation. Stakeholders must monitor evolving reimbursement coding for remote patient monitoring attachments that track output volume and infection markers outside clinical settings.
Market Dynamics
Reimbursement migration from institutional to community-based care is restructuring procurement authority toward patients and family caregivers, fragmenting traditional hospital-centric supply relationships and forcing manufacturers to build direct-to-consumer logistics.
Growth Catalysts
- Japan's PMDA fast-track pathway for home-use devices:Expedited approval timelines for hydrophilic-coated intermittent catheters accelerate patient transitions from acute facilities to self-managed environments.
- Silicone elastomer biocompatibility advances:Reduced protein adhesion and encrustation rates extend indwelling catheter dwell times, lowering replacement frequency for spinal cord injury patients.
- Germany's Diagnosis-Related Group bundling reforms:Financial incentives for shorter hospital stays push discharge planning teams to prescribe external collection sheaths for ambulatory male patients.
Market Restraints
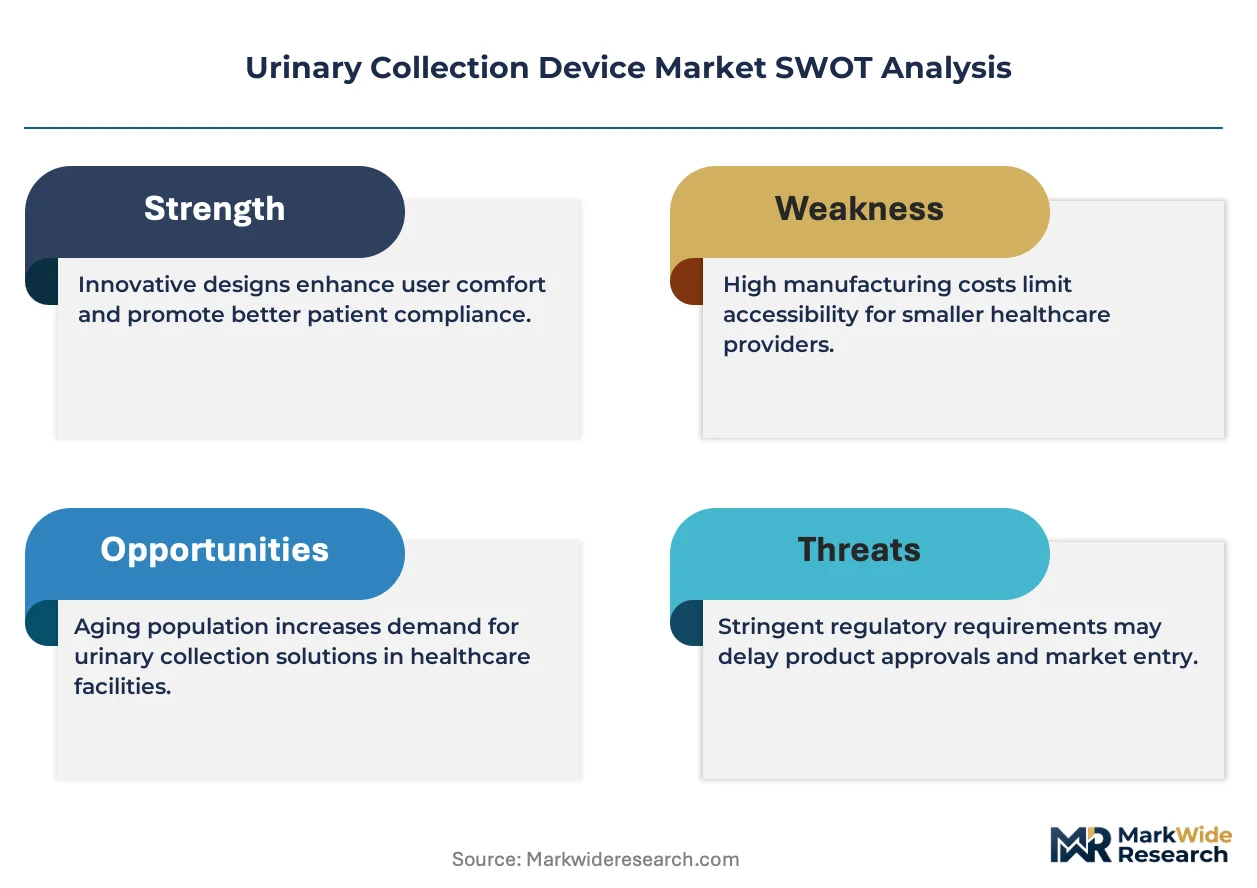
- Medical-grade silicone supply concentration:Three specialty chemical producers in Germany and Japan control feedstock for high-purity elastomers, exposing device makers to input cost volatility.
- EU MDR technical documentation burdens:Extended conformity assessment timelines for Class IIb drainage bags delay product launches by 18-24 months versus previous Medical Device Directive pathways.
- Antibiotic-impregnated catheter substitution:Silver-alloy and nitrofurazone-releasing alternatives from urological pharmaceutical divisions compete on infection-prevention claims.
Strategic Opportunities
- Remote patient monitoring integration:Bluetooth-enabled drainage bags with volume sensors and cloud connectivity create subscription revenue streams for home health agencies tracking post-surgical recovery.
- India's PLI scheme for medical devices:Production-linked incentives for domestic manufacturing of hydrophilic coatings attract contract manufacturers serving Southeast Asian export markets.
- Pediatric neurogenic bladder segmentation:Miniaturized catheter French sizes and gamified insertion training address an underserved cohort transitioning from parental to self-catheterization.
Industry Challenges
- Cleanroom manufacturing capacity constraints:ISO 14644 Class 7 validation for hydrophilic coating lines requires capital deployment that mid-tier producers struggle to finance.
- Latex labeling compliance complexity:FDA natural rubber latex caution statements and EU MDR Annex I allergen disclosures demand reformulation of legacy PVC blends and packaging artwork synchronization across markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Collection Device Market |
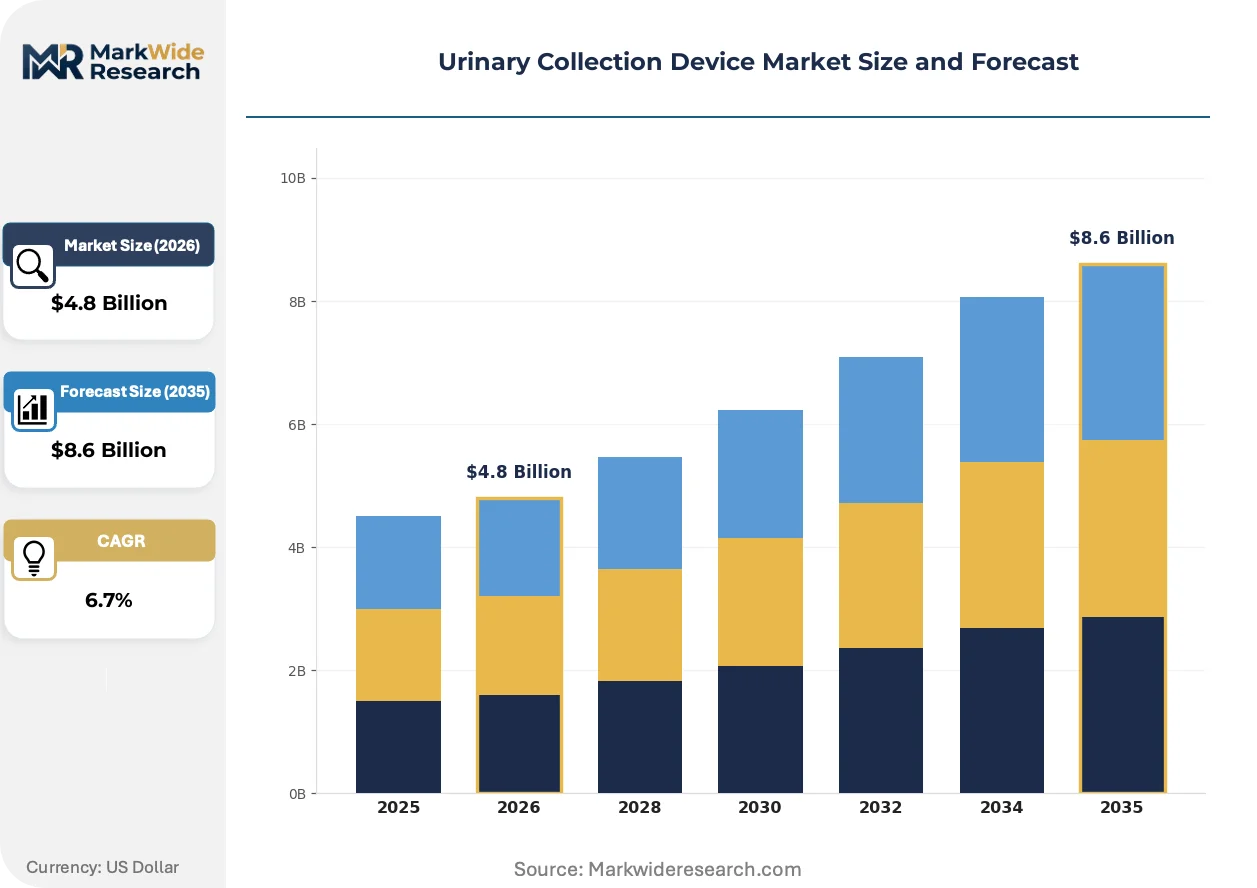
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Bags, Sheaths, Funnels End User: Hospitals, Clinics, Home Care, Nursing Facilities Material: Silicone, PVC, Latex, Hydrophobic Coatings Application: Postoperative Care, Chronic Care, Urinary Incontinence, Pediatric Care |
| Companies Covered | Becton Dickinson and Company, Coloplast A/S, Medtronic, B. Braun Melsungen AG, Teleflex Incorporated, Boston Scientific Corporation, ConvaTec Group plc, Hollister Incorporated, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Collection Device Market Strategic Shifts
Digital connectivity and surface chemistry advances are converging to transform urinary collection from passive containment to active therapeutic monitoring, while regulatory pressure on single-use plastics accelerates material substitution roadmaps.
Antimicrobial peptide-bonded catheter surfaces are absorbing market share from traditional silver-ion coatings by demonstrating superior biofilm inhibition against multidrug-resistant organisms. Long-term care facilities in the Netherlands and Denmark are piloting these surfaces for residents with recurrent catheter-associated urinary tract infections. The technology is absorbing premium positioning previously held by antibiotic-impregnated alternatives as resistance surveillance data accumulates.
EU MDR Annex XVI expansion to include products without intended medical purpose is capturing external male sheaths marketed for sports or travel use under medical device surveillance. Manufacturers must now maintain post-market clinical follow-up systems for consumer-grade products previously exempt from technical documentation. German notified bodies are processing the first conformity assessments for these reclassified products, establishing precedent for borderline device regulation.
Subscription replenishment models are displacing acute-care bulk purchasing for home-dwelling catheter users. Direct-to-patient platforms in the United States bypass durable medical equipment distributors by integrating insurance pre-authorization with scheduled delivery. This channel rotation concentrates in Medicare Advantage plans with supplemental home health benefits, where care coordinators manage chronic condition bundles.
Urinary Collection Device Market Segmentation
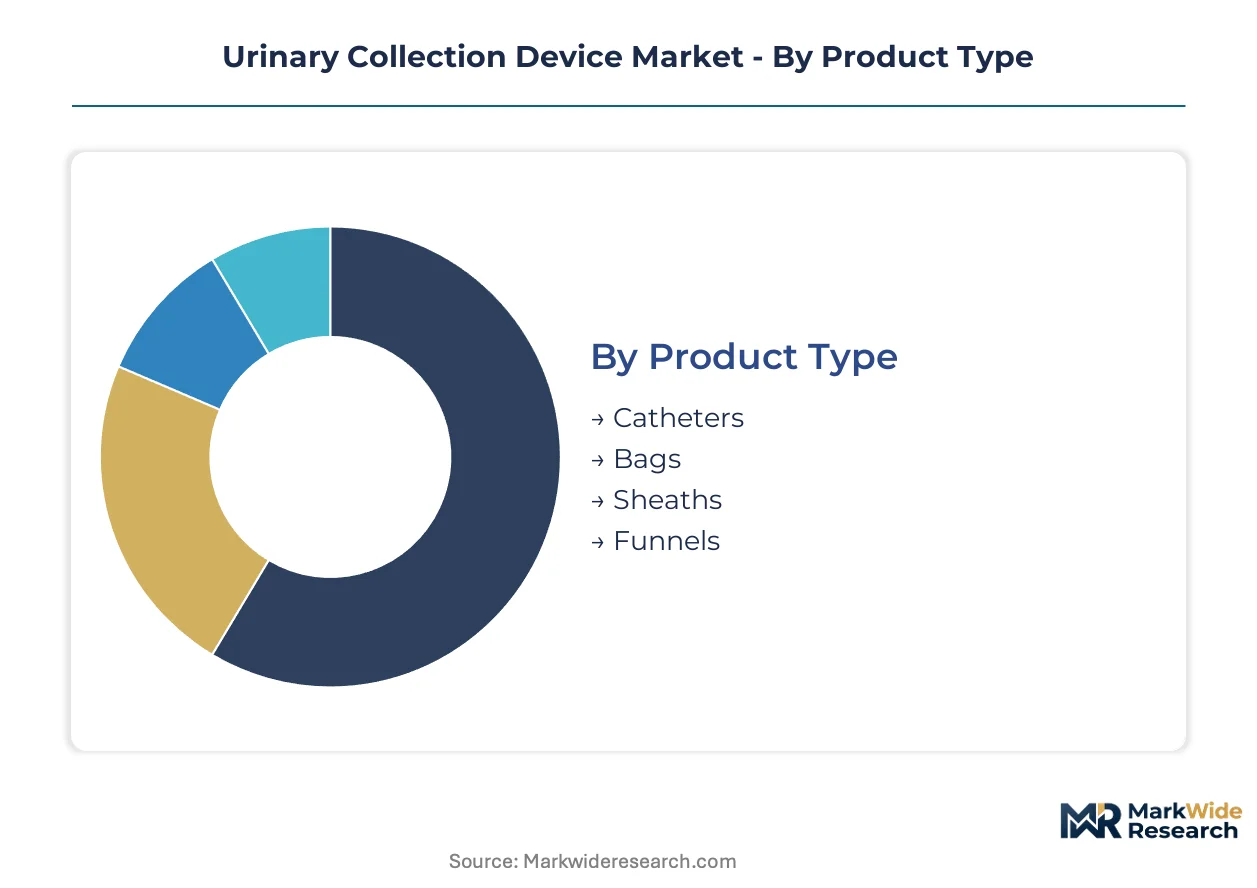
Segmentation in the urinary collection device market reveals distinct procurement patterns between acute-care bulk purchasing and patient-directed home replenishment. Material specifications and coating technologies further stratify margins across reimbursement tiers.
Product Type:
Standalone drainage systems dominate institutional procurement, while embedded sensor-enabled devices reshape home monitoring workflows.
- Catheters:Indwelling Foley and intermittent straight catheters manufactured from silicone or hydrophilic-coated PVC constitute the procedural backbone of urological intervention. Demand concentrates in United States Medicare-reimbursed spinal cord injury programs where extended dwell times reduce replacement frequency.
- Bags:Closed-system drainage receptacles with anti-reflux valves and graduated volume markings attach to catheters or leg straps for ambulatory containment. German hospital procurement consortiums favor large-capacity overnight models that minimize nursing interruption.
- Sheaths:External male collection devices with adhesive or compression-fit seals offer non-invasive alternatives for ambulatory incontinence management.
- Funnels:Portable urination aids for standing or seated positioning serve travel and disability access applications.
Volume placements concentrate in catheters; the faster expansion belongs to sheaths as male ambulatory populations seek catheter-sparing alternatives.
End User:
Procurement authority fragments as reimbursement migrates from facility administrators to patients and family caregivers managing chronic conditions.
- Hospitals:Acute-care facilities purchase sterilized single-use catheters through group purchasing organizations with stringent infection prevention protocols. Japan's PMDA fast-track pathway accelerates hydrophilic-coated product adoption for early discharge planning.
- Clinics:Outpatient urology and rehabilitation centers stock intermittent catheter supplies for procedure-based dispensing. United States Medicare Advantage plans increasingly bundle these products into episode-based payments.
- Home Care:Self-managed environments drive subscription replenishment models bypassing traditional durable medical equipment distributors.
- Nursing Facilities:Long-term care institutions balance cost containment against CAUTI reduction through silver-alloy and antimicrobial peptide surface selections.
Revenue concentration sits with hospitals; home care is climbing the fastest as aging demographics prefer community-based management.
Material:
Biocompatibility standards and allergen labeling requirements constrain formulation choices across regulated markets.
- Silicone:High-purity elastomers with reduced protein adhesion extend indwelling dwell times for neurogenic bladder patients. Supply concentrates among German and Japanese specialty chemical producers, exposing device makers to feedstock volatility.
- PVC:Plasticized polyvinyl chloride remains the cost-optimized standard for intermittent catheters despite environmental scrutiny. EU MDR Annex I allergen disclosures demand reformulation of legacy blends containing natural rubber latex additives.
- Latex:Natural rubber formulations persist in price-sensitive markets despite FDA caution statement requirements.
- Hydrophobic Coatings:Surface treatments reduce friction coefficients for patient self-catheterization.
Silicone commands premium positioning; hydrophobic coatings are gaining share fastest as hydrophilic alternatives displace uncoated PVC in reimbursement-preferred tiers.
Application:
Clinical indication determines product specification complexity and reimbursement coding eligibility.
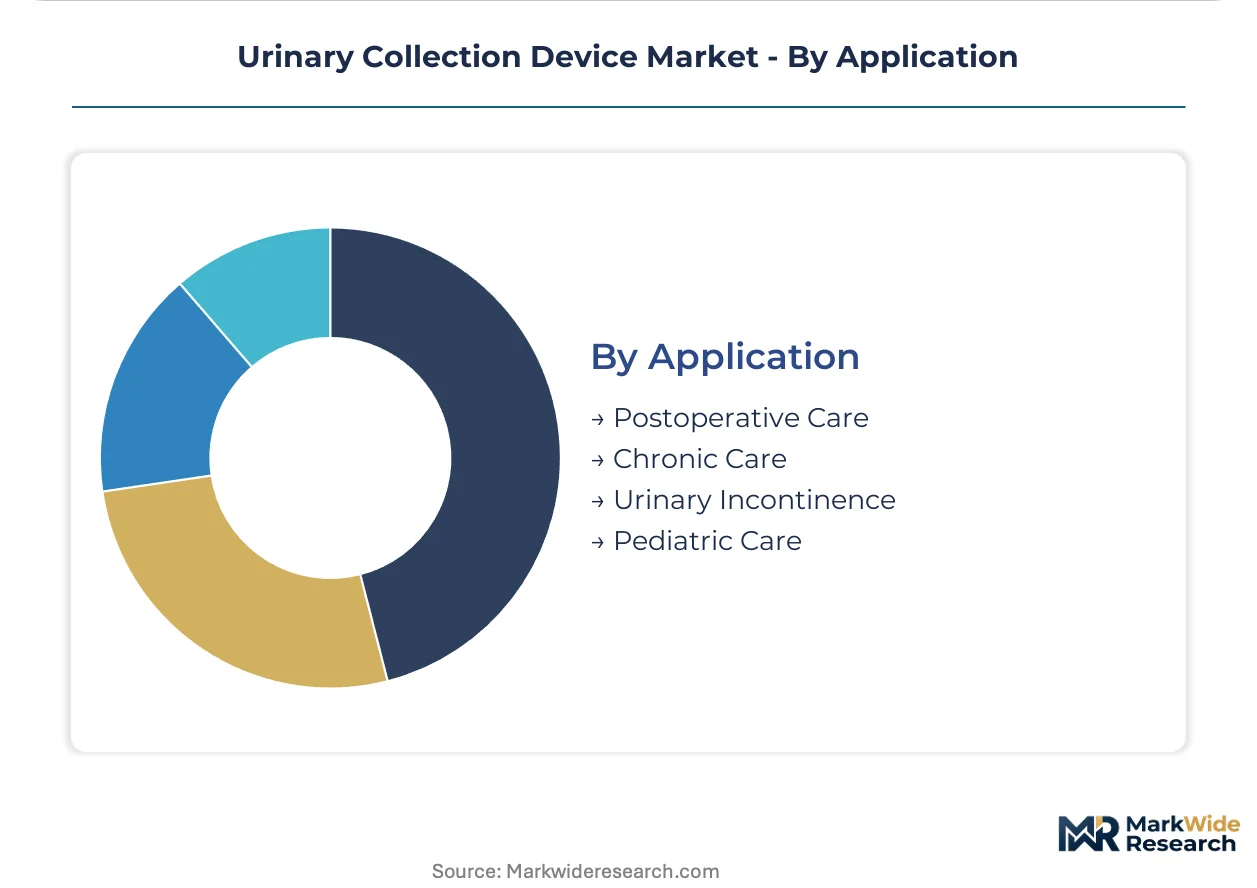
- Postoperative Care:Short-term catheterization following abdominal or pelvic surgery requires sterile closed-system drainage with volume monitoring. United States hospitals track these placements against surgical site infection bundles.
- Chronic Care:Long-term indwelling or intermittent catheterization for spinal cord injury and multiple sclerosis patients demands material durability and patient training resources. Germany's Diagnosis-Related Group bundling reforms favor external sheath prescriptions for male ambulatory cases.
- Urinary Incontinence:Containment-focused solutions prioritize discretion and skin integrity over sterile insertion protocols.
- Pediatric Care:Miniaturized French sizes and developmentally appropriate insertion training address neurogenic bladder management in transitioning adolescents.
Postoperative applications generate the highest procedural volumes; pediatric care shows the steepest expansion trajectory as early intervention programs extend to congenital anomalies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan where reimbursement frameworks support advanced catheter systems and long-term care infrastructure. Aging demographics across these markets accelerate transitions from institutional to home-based management. Regulatory compliance requirements in each jurisdiction reshape material specifications and approval timelines.
United States
Medicare Advantage plans with supplemental home health benefits drive subscription replenishment models for intermittent catheter users. FDA 510(k) pathways govern biocompatibility and sterility assurance for hydrophilic-coated devices. Minneapolis and Boston anchor urological navigation system development that integrates with collection workflows.
Germany
Diagnosis-Related Group bundling reforms create financial incentives for shorter hospital stays and external sheath prescriptions. EU MDR Class IIa/IIb designation and ISO 10993 biological evaluation standards constrain material selection. Specialty chemical producers in the Rhine-Ruhr region control high-purity silicone elastomer feedstock for extended-dwell catheters.
Japan
PMDA fast-track pathways for home-use devices accelerate patient transitions from acute facilities to self-managed environments. METI quality management requirements and JIS standards further validate manufacturing processes. Tokyo and Osaka clusters concentrate urological device distribution networks serving aging rural populations.
United Kingdom
NHS long-term care procurement frameworks favor silver-alloy and antimicrobial peptide surfaces for CAUTI reduction in nursing facilities. MHRA post-market surveillance aligns with EU MDR technical documentation burdens for drainage bag conformity assessments. London and Manchester medical technology corridors host hydrophilic coating validation laboratories.
India
Production-linked incentive schemes for domestic medical device manufacturing attract contract manufacturers for Southeast Asian export markets. CDSCO quality management requirements govern import substitution for hydrophilic-coated intermittent catheters. Gujarat and Karnataka industrial clusters expand cleanroom capacity for ISO 14644 Class 7 coating line validation.
Urinary Collection Device Market Competitive Environment
United States producers anchor the premium-tier supply chain; European specialists hold compliance-intensive segments. The vendor base fragments across hospital-centric distributors and direct-to-consumer platforms. Three archetypes dominate: diversified medical technology conglomerates with urological divisions, pure-play continence management specialists, and contract manufacturers serving private-label brands. M&A activity concentrates on hydrophilic coating capabilities and remote monitoring sensor integration.
Among diversified medical technology conglomerates, Becton Dickinson and Company exemplifies the hospital supply chain reach model, while Medtronic occupies a position in urological navigation system integration. Coloplast A/S represents the pure-play specialist archetype focused on hydrophilic-coated intermittent catheters for independent users. These three anchors illustrate the strategic tension between acute-care volume leverage and home-care subscription economics.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Coloplast A/S |
| Medtronic |
| B. Braun Melsungen AG |
| Teleflex Incorporated |
| Boston Scientific Corporation |
| ConvaTec Group plc |
| Hollister Incorporated |
| Cardinal Health |
| Others |
Value Chain & Pricing Dynamics
Medical-grade silicone feedstock originating from German and Japanese specialty chemical producers flows through three distinct pricing tiers before reaching end users. Procurement managers at device manufacturers negotiate long-term offtake agreements to hedge against raw material volatility that compresses margins on standard PVC catheter lines.
Pricing Analysis
Volume placements concentrate in economy-tier PVC catheters while margin capture sits with premium silicone and hydrophilic-coated alternatives. Three-tier pricing structure across premium, standard, and economy levels differentiates by biocompatibility certification grade and coating technology sophistication. Pricing pressure stems from EU MDR conformity assessment delays that extend product launch timelines and inflate compliance costs. Home care patients and family caregivers exhibit highest price sensitivity; hospital purchasing committees through group purchasing organizations demonstrate lowest sensitivity due to bundled reimbursement.
Supply Chain Analysis
Dual-sourcing requirements mandated by FDA quality system regulations and EU MDR technical documentation standards compel manufacturers to qualify multiple silicone elastomer suppliers. Geographic supply concentration centers on Germany, Japan, and the United States for high-purity elastomer feedstock. Raw material dependencies include medical-grade silicone, hydrophilic coating polymers, and sterilization packaging films. Single-source vulnerability from three dominant specialty chemical producers exposes device makers to input cost volatility. Distribution runs through hospital group purchasing organizations and direct-to-consumer platforms serving home care subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive supply of hydrophilic coating polymers to defend margin structure against raw material volatility.
For Market Incumbents: Acquire hydrophilic coating technology assets and cleanroom manufacturing facilities to secure ISO 14644 Class 7 validation capacity. Consolidate position through backward integration into silicone elastomer feedstock partnerships with German and Japanese specialty chemical producers. Antimicrobial peptide-bonded catheter surfaces from emerging competitors threaten silver-alloy premium positioning; defend through accelerated clinical validation investments. For New Entrants and Emerging Players: The gap between premium silicone catheters and economy PVC alternatives offers entry opportunity for mid-tier hydrophilic-coated intermittent catheter offerings. Target India's PLI scheme for domestic manufacturing to serve Southeast Asian export markets with cost-optimized production. Pediatric neurogenic bladder segmentation remains underpenetrated; pursue gamified insertion training platform development as differentiated go-to-market angle. For Investors and Strategic Acquirers: PMDA fast-track pathway approvals for home-use devices are the leading indicator that Japanese market transitions to self-managed environments are accelerating. Long-term viability favors manufacturers with integrated coating capabilities and remote patient monitoring sensor platforms. Acquisition target archetype: mid-tier contract manufacturers with validated cleanroom capacity and private-label relationships. Watch for FDA 510(k) clearance timelines for Bluetooth-enabled drainage bags as inflection signal for digital health integration viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrophilic Coatings | Captive polymer supply secures margin against German and Japanese feedstock volatility. |
| Hospital System Partnership | GPO contract penetration anchors volume placement in Medicare-reimbursed spinal cord injury programs. |
| Reimbursement Strategy | Medicare Advantage supplemental home health benefit alignment enables subscription replenishment economics. |
| Software Companion Development | Bluetooth-enabled drainage bag volume sensors create recurring revenue streams for home health agencies. |
| CE Marking Pathway | EU MDR Class IIb conformity assessment completion unlocks German Diagnosis-Related Group bundling participation. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and home health agency care coordinators combined with FDA 510(k) databases, EU MDR notified body assessments, and PMDA approval records. Bottom-up product-level modeling triangulated against top-down reimbursement expenditure analysis.
Granularity-level modeling operated at product type, material specification, end-user channel, and geographic regulatory cluster dimensions across the analysis window. CAGRs were derived from procedure volume trajectories, reimbursement code evolution, and patient demographic projections. Forecast inputs included spinal cord injury prevalence data, nursing facility discharge planning patterns, and antimicrobial resistance surveillance trends.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time home care subscription transaction data introduce uncertainty bands around direct-to-consumer channel projections. Deviation in Medicare Advantage benefit design or EU MDR notified body processing timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Prefillable Inhalers Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market
Medical Devices
Meniscus Repair Systems Market
Medical Devices
UHD Surgical Display Market
Medical Devices
Dual Balloon Angioplasty Catheter Market
Medical Devices
Sphincterotomes Market
Medical Devices
Electronic Skin Patch Market
Medical Devices
Global Neurology Ultrasonic Aspirators Market
Medical Devices
Pannus Retraction Device Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Mexico Spinal Surgery Devices Market
Medical Devices
Europe Cardiac Rhythm Management Devices Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
Pharmacy Automation Devices Market
Medical Devices
Ultra-Large Volume Wearable Injectors Market