
 Global Stereotaxic Instrument Market | 2026-2036
Global Stereotaxic Instrument Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stereotaxic Instrument Market Foresight
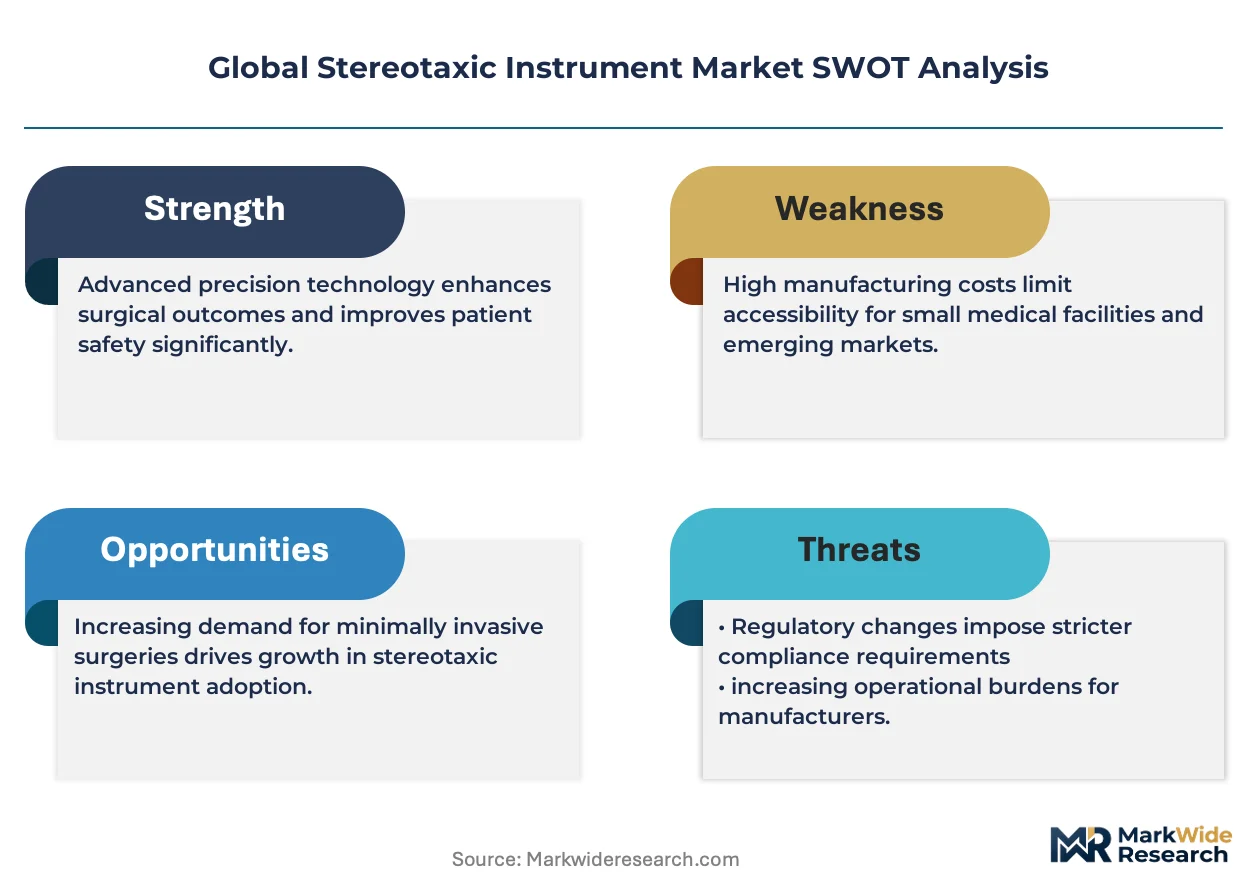
Frameless stereotaxic precision is collapsing the historical trade-off between surgical accuracy and operative time. Medtronic leverages its installed base in deep brain stimulation to sustain recurring revenue from navigation software upgrades. Brainlab differentiates through optical tracking tools that integrate with existing operating room imaging suites. David Kopf Instruments anchors the manual frame-based segment where research institutions prioritize cost control over automation.
A stereotaxic instrument is a three-dimensional mechanical or robotic positioning device that guides probes, electrodes, or cannulae to targeted coordinates within the brain or spinal tissue using Cartesian coordinate systems with sub-millimeter accuracy, typically manufactured from anodized aluminum or titanium alloys with micrometer-scale drive screws. Its primary purpose is to enable minimally invasive neurosurgical interventions including biopsy, lesioning, and electrode placement without direct visualization of deep structures. Frameless systems now lead volume growth as hospitals replace legacy frame-based installations that require skull fixation and extended setup protocols. Robotic-assisted systems command the strongest margin pools due to capital intensity and proprietary software ecosystems, while imaging-guided equipment serves as the interoperability layer connecting stereotaxic hardware to intraoperative MRI and CT workflows. Research institutions represent a stable but lower-margin demand channel compared to neurosurgical centers where procedure reimbursement supports premium platform adoption.
FDA 510(k) clearance pathways and CE marking under the EU MDR govern commercial access for stereotaxic platforms in the United States and European Union, with both frameworks intensifying scrutiny of electromagnetic navigation safety and software validation. ISO 13485 quality management certification operates as a baseline requirement for supply contracts with academic medical facilities and hospital purchasing consortia. Japan's PMDA maintains distinct documentation standards for robotic-assisted surgical devices that delay market entry relative to Western regulators. Stakeholders must monitor how FDA pre-submission meetings and MDR technical file reviews are adapting to artificial intelligence-enabled trajectory planning modules that blur traditional hardware-software classification boundaries.
Market Dynamics
Robotic-assisted trajectory planning is compressing the skill gap between academic medical centers and community hospitals, redistributing surgical volume toward mid-tier facilities previously excluded from deep brain stimulation programs.
Growth Catalysts
- EU MDR calibration mandates:Tightened electromagnetic navigation safety standards under the Medical Device Regulation are accelerating replacement of legacy frame-based systems across German and French neurosurgical centers.
- Deep brain stimulation expansion:Movement disorder clinics in Japan are procuring frameless platforms to reduce patient setup time and expand daily procedure throughput.
- Titanium alloy micromachining:Advances in sub-millimeter drive screw precision are enabling lighter instrument frames that reduce intraoperative fatigue without sacrificing coordinate accuracy.
Market Restraints
- Capital intensity barriers:Robotic-assisted stereotaxic platforms require seven-figure installation commitments that constrain procurement to reimbursed neurosurgical centers, excluding standalone research institutes.
- Supply concentration in optical tracking:Infrared camera subsystems rely on a narrow supplier base concentrated in German precision optics clusters, creating vulnerability to component allocation delays.
- Frame-based substitution persistence:Manual stereotaxic frames retain cost advantage for rodent research protocols, slowing the technology transition in preclinical contract research organizations.
Strategic Opportunities
- Indian neurosurgical infrastructure:Greenfield hospital construction in Mumbai and Delhi is creating first-mover advantage for frameless platform vendors establishing service networks.
- AI-enabled trajectory planning:Convergence of convolutional neural networks with intraoperative imaging is opening software-as-a-service revenue streams independent of hardware sales cycles.
- US IRA procedural incentives:Medicare reimbursement adjustments for outpatient deep brain stimulation are redirecting capital budgets toward same-day surgical platforms.
Industry Challenges
- Electromagnetic interference certification:FDA 510(k) reviewers are demanding expanded safety documentation for navigation systems operating near implanted cardiac devices, extending clearance timelines.
- Legacy imaging integration:Frameless platforms require custom DICOM conformance testing with site-specific MRI and CT suites, inflating deployment costs and delaying go-live dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stereotaxic Instrument Market |
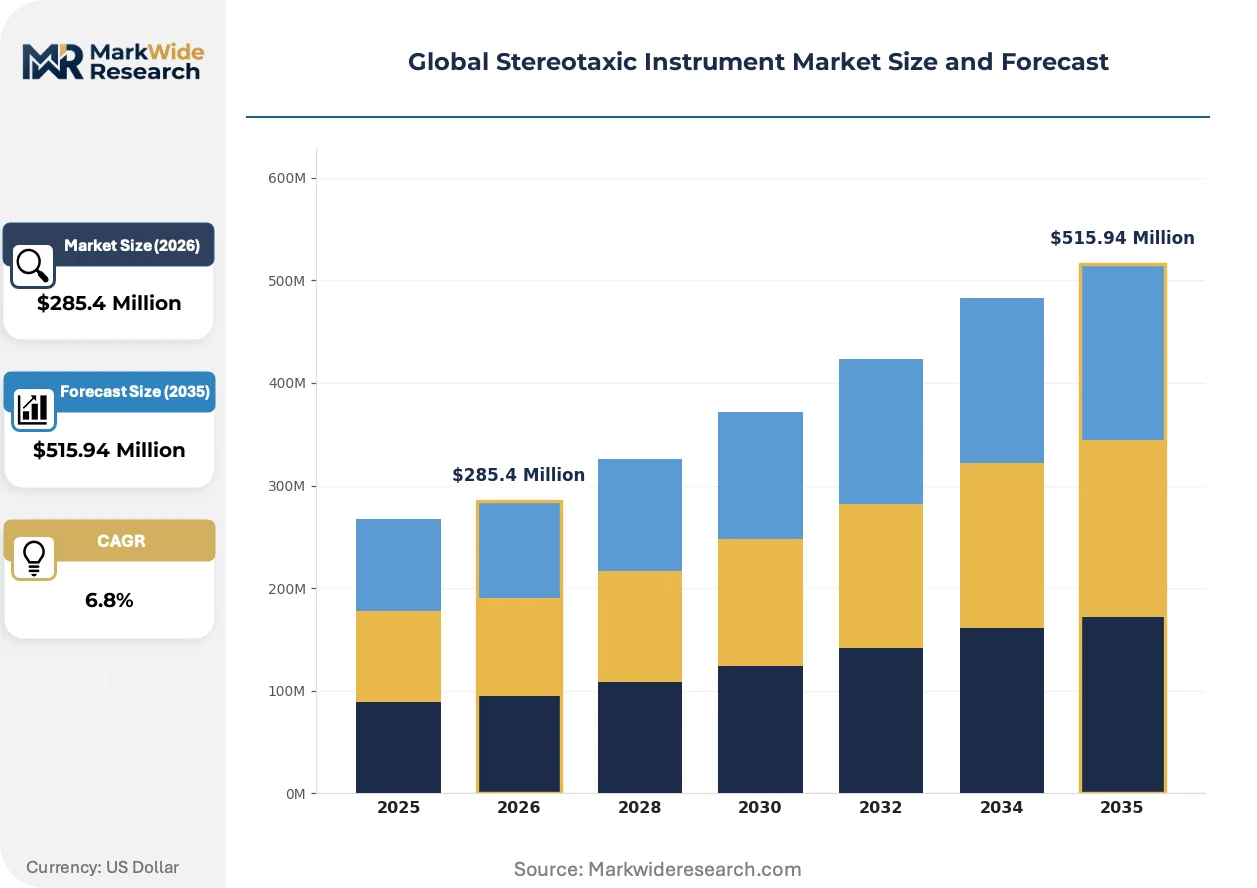
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frame-Based Systems, Frameless Systems, Robotic-Assisted Systems, Imaging-Guided Equipment, Optical Tracking Tools Technology: CT-Guided, MRI-Guided, Ultrasound-Guided, Electromagnetic Navigation, Intraoperative Imaging Application: Neurosurgery, Radiosurgery, Biopsy, Deep Brain Stimulation, Functional Brain Mapping End User: Neurosurgical Centers, Research Institutions, Diagnostic Clinics, Academic Medical Facilities |
| Companies Covered | Brainlab, RWD Life Science, Stoelting Co., Braintree Scientific Inc., Integra LifeSciences, Elekta AB, David Kopf Instruments, Neurostar, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stereotaxic Instrument Market Shifts & Advancements
Electromagnetic navigation architectures are displacing optical tracking as the default interoperability layer, while software ecosystems increasingly determine hardware procurement decisions rather than mechanical precision specifications alone.
Optical stereotaxic tracking is fragmenting into modular subsystems that separate infrared camera arrays from proprietary software licenses. University medical centers in Germany and Switzerland are piloting open-source trajectory planning tools that interface with third-party hardware, compressing vendor lock-in premiums. This fragmentation is enabling research institutions to source cameras from machine vision suppliers and navigation algorithms from specialized software houses, eroding the integrated platform model.
Japan's PMDA has introduced distinct documentation pathways for robotic-assisted surgical devices that mandate real-time error logging and predictive maintenance algorithms. Manufacturers must submit trajectory accuracy validation across temperature and humidity ranges that exceed ISO 13485 baseline requirements. European vendors entering the Japanese market are responding by establishing localized clinical engineering teams to manage PMDA pre-submission consultations.
Hospital procurement committees are unbundling after-sales service contracts from initial capital purchases, forcing vendors to compete on annual maintenance pricing separate from platform hardware. Neurosurgical centers in the United States are consolidating vendor relationships through multi-year enterprise agreements that span imaging, navigation, and stereotaxic hardware. This concentration is most visible in academic medical facilities in Boston and San Francisco, where purchasing consortia negotiate standardized service level agreements across device categories.
Global Stereotaxic Instrument Market Segmentation
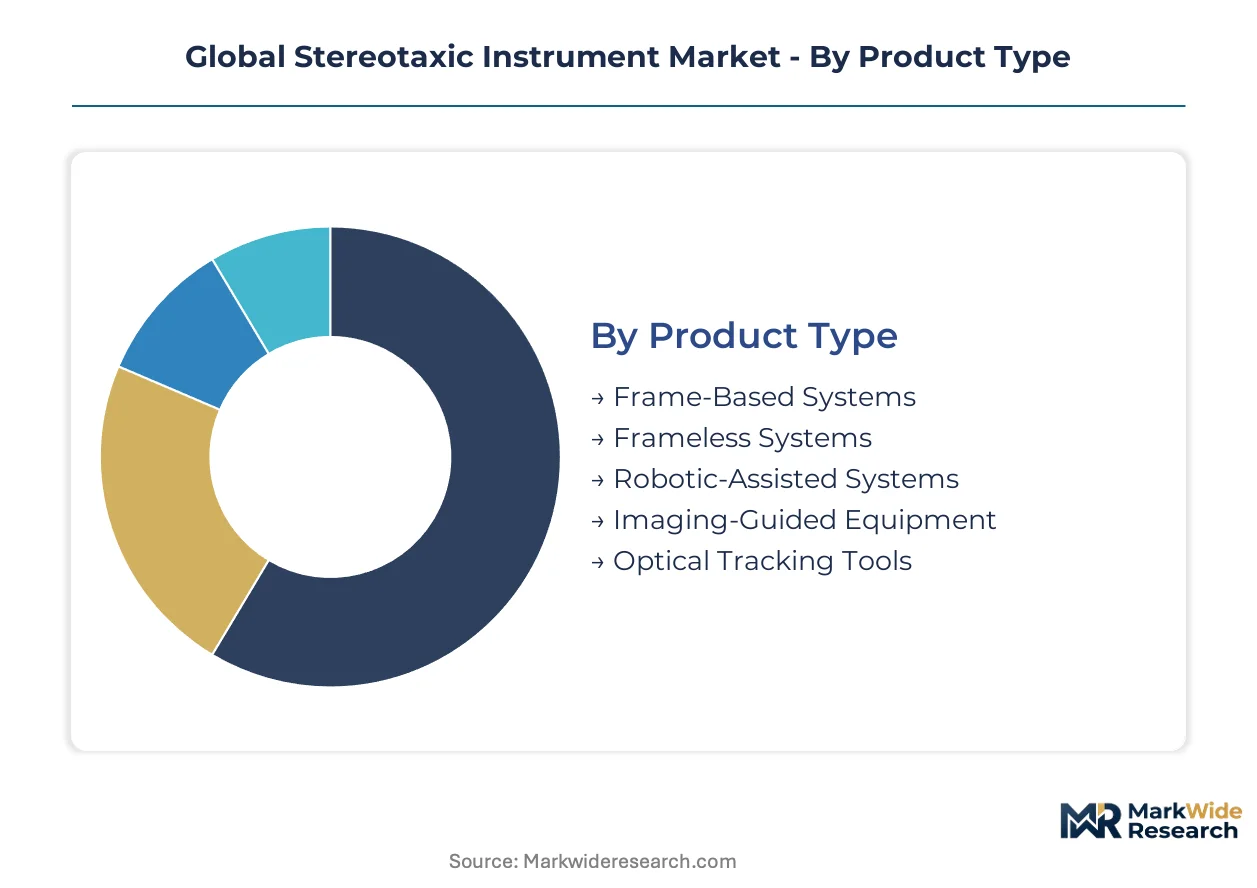
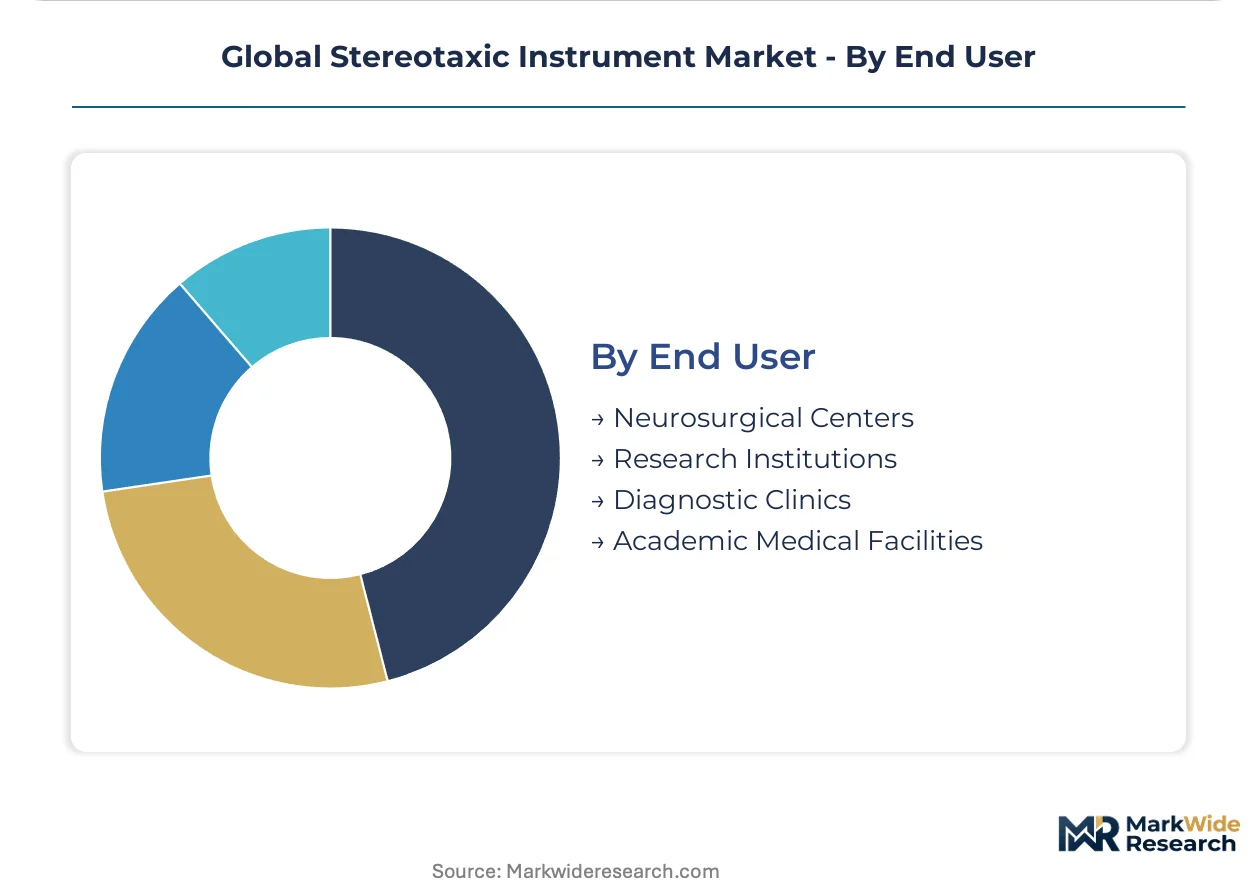
Surgical precision requirements vary dramatically across research protocols versus reimbursed clinical procedures, creating distinct demand profiles for mechanical versus robotic platforms. Procurement committees evaluate stereotaxic instruments through divergent lenses: capital efficiency dominates research purchasing, while operative throughput and reimbursement compatibility drive neurosurgical center decisions.
Product Type:
Frame-based systems anchor domestic manufacturing in Germany and Japan where precision machining clusters serve regional research markets. Frameless and robotic platforms flow through export-led supply chains concentrated in US and Swiss medical technology corridors.
- Frame-Based Systems:Manual aluminum or titanium frames with micrometer-scale drive screws deliver sub-millimeter accuracy for rodent protocols and cost-constrained research. Demand clusters in German university laboratories and Japanese preclinical contract research organizations where capital budgets prioritize precision over automation.
- Robotic-Assisted Systems:Electromechanical positioning arms integrated with proprietary navigation software enable trajectory planning without skull fixation. US neurosurgical centers in Boston and San Francisco anchor procurement, driven by Medicare reimbursement for outpatient deep brain stimulation procedures.
- Frameless Systems:Optical or electromagnetic tracking eliminates frame attachment, reducing patient setup time. German and French hospitals are replacing legacy installations under EU MDR calibration mandates.
- Imaging-Guided Equipment:DICOM-conformant interfaces connecting stereotaxic hardware to intraoperative MRI and CT workflows. Supply concentrates in Swiss and US vendors with established imaging partnerships.
- Optical Tracking Tools:Infrared camera arrays and fiducial markers for real-time position verification. German precision optics clusters dominate component supply, creating allocation vulnerability.
Frame-based systems command the established base. The steepest expansion runs through robotic-assisted platforms.
Technology:
Navigation architectures sort into cost tiers: electromagnetic and optical systems carry premium pricing, while ultrasound-guided approaches serve budget-constrained diagnostic applications.
- Electromagnetic Navigation:Sensor-based tracking without line-of-sight constraints enables flexible surgical workflows. FDA reviewers are demanding expanded safety documentation for systems operating near implanted cardiac devices, extending clearance timelines for US market entry.
- MRI-Guided:Real-time intraoperative imaging with magnetic field-compatible instrumentation. Japanese movement disorder clinics in Tokyo and Osaka are procuring these platforms to expand daily procedure throughput.
- CT-Guided:Bone-registered coordinate mapping for cranial and spinal targeting. Research institutions favor this mature technology for its cost predictability.
- Ultrasound-Guided:Portable navigation for bedside procedures and resource-limited settings. Indian greenfield hospitals in Mumbai are piloting deployment.
- Intraoperative Imaging:Integrated MRI/CT suites with stereotaxic compatibility. Academic medical facilities negotiate multi-year enterprise agreements spanning imaging and navigation hardware.
MRI-guided platforms anchor the premium tier. The steepest volume climb tracks through electromagnetic navigation.
Application:
Procedure reimbursement status determines customer type: reimbursed interventions concentrate in neurosurgical centers, while research-funded applications flow through academic facilities.
- Deep Brain Stimulation:Electrode placement for Parkinson's disease and essential tremor with awake patient monitoring. US Medicare reimbursement adjustments under the IRA are redirecting capital budgets toward same-day surgical platforms.
- Neurosurgery:Biopsy, lesioning, and catheter placement for tumor and vascular indications. German neurosurgical centers are expanding procurement of robotic-assisted platforms under tightened EU MDR precision standards.
- Radiosurgery:Stereotactic radiosurgery coordination with linear accelerator systems. Academic medical facilities anchor demand for integrated planning software.
- Biopsy:Tissue sampling for histopathological diagnosis. Diagnostic clinics favor frameless systems for reduced setup complexity.
- Functional Brain Mapping:Cortical stimulation for epilepsy and language localization. Research institutions in Switzerland are piloting open-source trajectory planning tools.
Neurosurgery commands the established base. The steepest expansion runs through deep brain stimulation.
End User:
Customer concentration patterns diverge: neurosurgical centers purchase through hospital procurement consortia, while research institutions maintain direct vendor relationships.
- Neurosurgical Centers:Reimbursed procedure volume supports seven-figure capital commitments for robotic platforms. US purchasing consortia in Boston and San Francisco negotiate standardized service level agreements.
- Research Institutions:Preclinical and clinical trial applications prioritize cost control over automation. German university laboratories sustain demand for manual frame-based systems.
- Academic Medical Facilities:Hybrid clinical-research environments requiring flexible platform configurations. These facilities are consolidating vendor relationships through multi-year enterprise agreements.
- Diagnostic Clinics:Biopsy and staging procedures with limited neurosurgical backup. Frameless platforms are gaining traction for reduced staffing requirements.
Neurosurgical centers command the established base. The steepest expansion runs through academic medical facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics clusters export infrared camera subsystems to US neurosurgical centers, while Swiss imaging-equipment vendors supply frameless navigation platforms to Japanese movement disorder clinics.
United States
Medicare reimbursement adjustments under the IRA are redirecting capital budgets toward same-day surgical platforms. FDA 510(k) reviewers demand expanded safety documentation for electromagnetic navigation systems operating near implanted cardiac devices. Academic medical facilities in Boston and San Francisco negotiate multi-year enterprise agreements spanning imaging, navigation, and stereotaxic hardware.
Germany
Neurosurgical centers in Munich and Heidelberg are expanding procurement of robotic-assisted platforms under tightened EU MDR calibration mandates. German precision optics clusters in Jena and Oberkochen anchor infrared camera subsystem supply for optical tracking tools. University laboratories in Tübingen sustain demand for manual frame-based systems where capital budgets prioritize precision over automation.
Japan
Movement disorder clinics in Tokyo and Osaka are procuring frameless platforms to reduce patient setup time and expand daily procedure throughput. PMDA maintains distinct documentation standards for robotic-assisted surgical devices that mandate real-time error logging and predictive maintenance algorithms. Japanese preclinical contract research organizations retain cost advantage for manual stereotaxic frames in rodent research protocols.
Switzerland
Research institutions in Basel and Zurich are piloting open-source trajectory planning tools that interface with third-party hardware, compressing vendor lock-in premiums. Swissmedic certification requirements for intraoperative imaging integration exceed ISO 13485 baseline standards. Vendors in the Lake Geneva corridor supply DICOM-conformant interfaces connecting stereotaxic hardware to intraoperative MRI and CT workflows.
India
Greenfield hospital construction in Mumbai and Delhi is creating first-mover advantage for frameless platform vendors establishing service networks. CDSCO regulatory pathways for electromagnetic navigation devices are adapting to software-as-a-service revenue models independent of hardware sales cycles. Diagnostic clinics in Bangalore favor ultrasound-guided platforms for bedside procedures and resource-limited settings.
Global Stereotaxic Instrument Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and software ecosystem dimensions. The vendor base stratifies into three tiers: integrated platform providers commanding premium pricing, modular subsystem suppliers enabling research institution customization, and manual frame fabricators serving cost-constrained preclinical markets. Strategic moves concentrate on multi-year enterprise agreements with academic medical facilities and unbundling of after-sales service contracts from initial capital purchases.
Within the integrated platform tier, Medtronic and Brainlab exemplify divergent approaches to sustaining recurring revenue. Medtronic leverages its installed base in deep brain stimulation to anchor navigation software upgrade cycles, while Brainlab differentiates through optical tracking tools that integrate with existing operating room imaging suites. David Kopf Instruments occupies a position within the manual frame-based segment where research institutions prioritize cost control over automation. These three anchors illustrate how competitive positioning separates hardware-centric from software-centric value capture models.
| Leading Market Players |
|---|
| Brainlab |
| RWD Life Science |
| Stoelting Co. |
| Braintree Scientific Inc. |
| Integra LifeSciences |
| Elekta AB |
| David Kopf Instruments |
| Neurostar |
| Medtronic |
| Others |
Supply & Pricing Matrix
Titanium alloy substitution for anodized aluminum in frame-based instruments is redistributing manufacturing from German precision machining clusters to Japanese metallurgy corridors, compressing per-unit material costs while elevating quality certification premiums for electromagnetic navigation platforms.
Pricing Analysis
Current-generation robotic-assisted systems command fivefold premiums over prior-generation manual frames, while next-generation AI-enabled platforms are entering at subscription-tier SaaS pricing. Three-tier pricing structure across premium robotic, standard frameless, and economy manual systems separates academic medical facilities from research institutions. Cost compression in the manual frame segment is intensifying because Indian contract manufacturers are entering component supply. Research institutions exhibit highest price sensitivity; neurosurgical centers demonstrate lowest sensitivity due to reimbursement coverage.
Supply Chain Analysis
Just-in-time inventory strategies dominate optical tracking subsystem procurement, though electromagnetic sensor manufacturers are shifting toward strategic stockpiles of rare-earth magnet components. Supply concentrates in Germany for infrared camera arrays, Switzerland for DICOM-conformant interface modules, and Japan for titanium micromachining. Component dependencies include precision drive screws, electromagnetic field generators, and MRI-compatible alloys. Single-source vulnerability in German precision optics clusters creates allocation risk. Distribution runs through hospital procurement consortia and direct academic contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-as-a-service revenue from navigation algorithm licensing is expanding faster than capital hardware sales, converting one-time purchases into recurring service-attach relationships.
For Market Incumbents: Compound platform stickiness through backward integration into predictive maintenance algorithms and localized clinical engineering teams for PMDA compliance. Electromagnetic interference certification delays represent a regulatory threat requiring expanded safety documentation investment. Vertical control over optical tracking subsystems anchors margin defense against modular subsystem competitors. For New Entrants and Emerging Players: After-sales service contract unbundling presents a service-layer gap where incumbents under-serve price-sensitive research institutions. Indian greenfield hospital construction offers the most penetrable geography for frameless platform entry. Partner with machine vision suppliers for camera sourcing to bypass integrated vendor premiums. For Investors and Strategic Acquirers: The market sits at a replacement-cycle acceleration phase that favors software-centric acquisition targets over hardware fabricators. Long-term viability centers on recurring revenue multiples from navigation ecosystems rather than capital equipment depreciation schedules. Watch FDA pre-submission meeting outcomes for AI-enabled trajectory planning modules as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Navigation algorithm licensing creates recurring revenue independent of hardware replacement cycles. |
| Hospital System Partnership | Multi-year enterprise agreements with Boston and San Francisco academic consortia consolidate vendor relationships. |
| CE Marking Pathway | EU MDR calibration mandates accelerate replacement demand across German and French neurosurgical centers. |
| Reimbursement Strategy | Medicare IRA outpatient procedure incentives redirect capital budgets toward same-day surgical platforms. |
| Geographic Expansion | Localized service networks in Mumbai and Delhi capture first-mover advantage in Indian greenfield construction. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR technical file repositories, and hospital procurement contract disclosures preceded structured interviews with neurosurgeons, biomedical engineers, GPO contracts managers, and navigation software developers. Bottom-up triangulation across installed base estimates and top-down validation through capital expenditure surveys anchored volume and value projections. Secondary sources included CMS Medicare reimbursement schedules, PMDA pre-submission consultation records, and ISO 13485 certification registries.
Variance decomposition across product type, navigation technology, application procedure, and end-user facility tier structured the analytical framework across the analysis window. CAGRs derived from segment-level growth rate blending weighted by reimbursement status and replacement cycle maturity. Forecast inputs incorporated EU MDR compliance deadlines, IRA procedural incentive timelines, and PMDA documentation pathway revisions.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR enforcement, and PMDA robotic device standards; material policy shifts would require re-modeling. Electromagnetic interference certification timeline extensions and optical component allocation disruptions represent specific revision triggers. Revision becomes warranted when hospital capital expenditure contraction crosses institutional procurement committee threshold delays.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Wheelchair Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Oxygen Conserving Devices Market
Medical Devices
United Kingdom Aesthetic Devices Market
Medical Devices
Intravascular Warming Systems Market
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
Microdebrider Market
Medical Devices
Sinus Dilation Devices Market
Medical Devices
Deep Brain Stimulator Market
Medical Devices
Ear Tube Devices Market
Medical Devices
Middle East and Africa Aligner Sheet Market
Medical Devices
Medical Cyclotron Market
Medical Devices
Feeding Tubes Market
Medical Devices
Transabdominal Retrieval Kits Market
Medical Devices
Lung Preservation Systems Market
Medical Devices
Global Pressure Relief Devices Market