
 Clinical Microbiology Market | 2026-2036
Clinical Microbiology Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Microbiology Market Intelligence
The EU Green Deal's healthcare sustainability criteria is broadening procurement mandates for European diagnostic laboratories. Becton, Dickinson and Company leverages its automated culture systems to sustain market presence across hospital networks. Thermo Fisher Scientific Inc. anchors its competitive position through molecular diagnostics platforms that span pathogen detection and resistance profiling. bioMérieux SA differentiates through mass spectrometry-based microbial identification systems that reduce turnaround times in clinical settings.
Clinical microbiology encompasses the detection, identification, and characterization of pathogenic microorganisms using culture-based, immunological, molecular, and spectrometric methods, with diagnostic sensitivity thresholds typically reaching colony-forming unit counts of 10² to 10⁴ per milliliter depending on the target pathogen and specimen matrix. Its primary commercial purpose is to enable accurate infectious disease diagnosis, guide antimicrobial therapy selection, and support infection control surveillance in patient care and public health contexts. Molecular diagnostics commands the fastest expansion trajectory as hospitals transition from phenotypic to genotypic resistance detection, while mass spectrometry applications are maturing in large reference laboratories where capital equipment amortization aligns with high specimen volumes. Diagnostic kits represent the most concentrated margin pool due to recurring consumable demand and regulatory barriers that protect validated assay formats.
The FDA oversees in vitro diagnostic kit approvals and antimicrobial susceptibility testing standards in the United States, while the EMA coordinates clinical microbiology device conformity across European member states through the In Vitro Diagnostic Regulation framework. These regulators shape demand by mandating performance validation thresholds that determine which technologies achieve market access in their respective jurisdictions. China's NMPA is accelerating local diagnostic kit approvals as part of broader healthcare self-sufficiency initiatives. Stakeholders must monitor evolving resistance gene databases and regulatory harmonization efforts between FDA and EMA to anticipate assay obsolescence risks and platform investment timelines.
Market Dynamics
Hospital laboratories are abandoning phenotypic susceptibility testing in favor of genotypic resistance detection, compressing turnaround times from days to hours while forcing capital reallocation toward molecular platforms and mass spectrometry infrastructure.
Growth Catalysts
- EU Green Deal healthcare procurement mandates:European diagnostic laboratories now face binding sustainability criteria in public tenders, redirecting volume toward energy-efficient automated systems and consumables with reduced environmental footprints.
- Molecular diagnostics platform expansion:United States hospital networks are replacing culture-based workflows with PCR and next-generation sequencing systems, creating pull-through demand for companion resistance gene panels.
- Japan's hospital-based molecular infrastructure:METI-coordinated investments in tertiary care facilities are standardizing rapid pathogen identification protocols, elevating specimen throughput requirements.
Market Restraints
- Capital equipment amortization thresholds:Mass spectrometry systems require specimen volumes exceeding 50,000 isolates annually to achieve unit economics, excluding mid-sized hospital laboratories from MALDI-TOF adoption.
- Consumable supply concentration:Reagent manufacturing for antimicrobial susceptibility testing concentrates among three specialized chemical suppliers, creating input vulnerability during geopolitical disruptions.
- IVDR compliance timeline friction:Europe's In Vitro Diagnostic Regulation extended certification periods to 18-24 months, freezing product launches and forcing inventory buildups of legacy assays.
Strategic Opportunities
- China's NMPA accelerated approval pathway:Local diagnostic kit manufacturers benefit from streamlined review timelines for resistance detection assays, opening procurement opportunities in tier-two city hospital networks.
- Point-of-care molecular convergence:Integration of microfluidic sample preparation with isothermal amplification technologies enables near-patient testing in emergency departments and intensive care units.
- Subscription-based reagent supply contracts:Diagnostic laboratories in Germany are shifting from transactional purchasing to multi-year consumable agreements with embedded platform upgrades.
Industry Challenges
- Bioinformatics specialist scarcity:Clinical laboratories lack personnel trained in resistance gene variant interpretation, creating bottlenecks in next-generation sequencing report generation.
- Legacy LIS integration complexity:Molecular diagnostics platforms require middleware development to communicate with decades-old laboratory information systems, extending implementation timelines.
- Proficiency testing standardization delays:Cross-platform comparability studies for carbapenemase detection remain incomplete, undermining clinician confidence in genotypic results.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Microbiology Market |
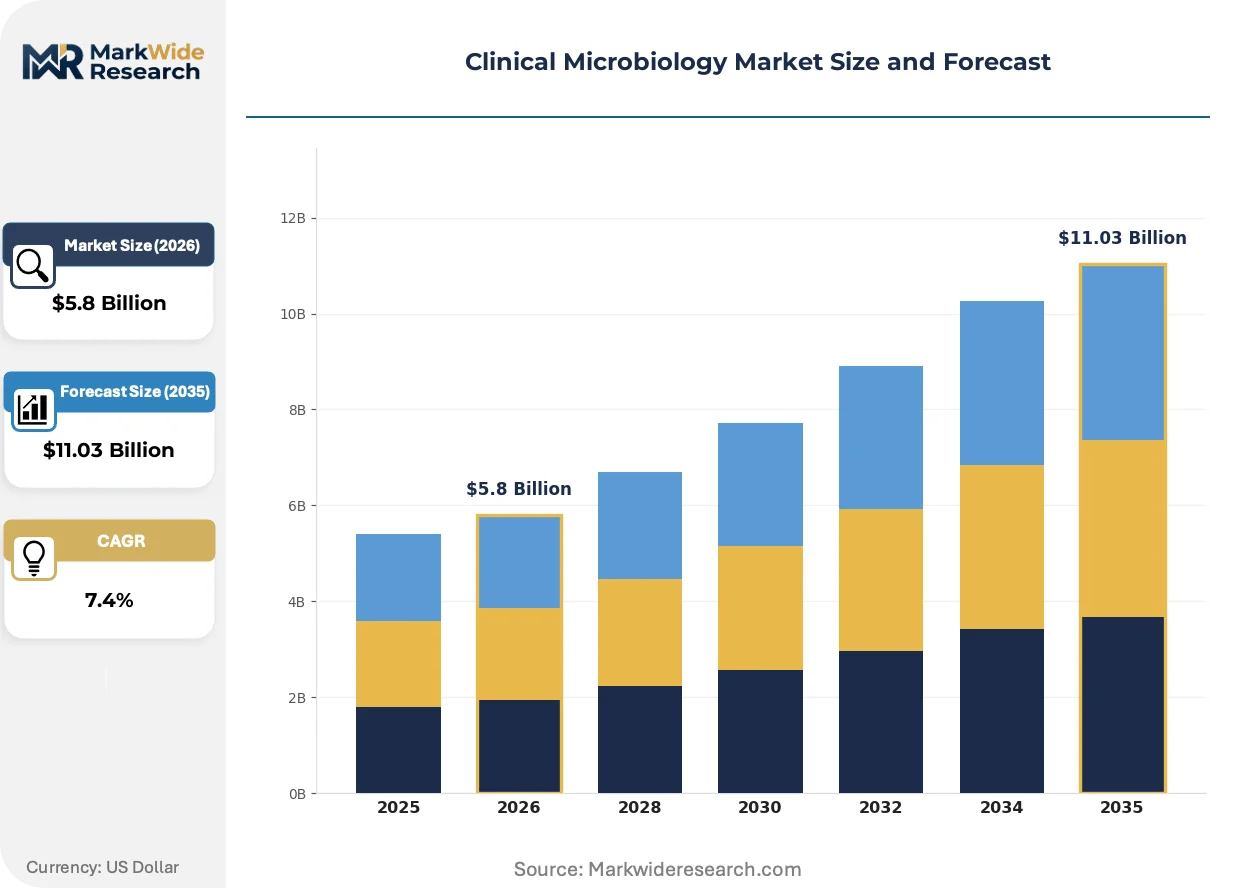
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.03 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Culture Media, Reagents, Diagnostic Kits, Consumables Technology: Molecular Diagnostics, Immunodiagnostics, Microbial Culture, Mass Spectrometry Application: Pathogen Detection, Drug Resistance Testing, Blood Screening, Environmental Testing End User: Hospitals, Diagnostic Laboratories, Research Institutions, Public Health Organizations |
| Companies Covered | Becton, Dickinson and Company, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., Bio-Rad Laboratories, Bruker Corporation, bioMérieux SA, Abbott Laboratories, Hologic Inc., Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Microbiology Market Strategic Shifts & Innovations
Automation, regulatory harmonization pressures, and procurement model restructuring are converging to reshape how diagnostic technologies achieve scale and margin capture in clinical settings.
Matrix-assisted laser desorption ionization time-of-flight mass spectrometry is electrifying microbial identification workflows by replacing biochemical panel testing with protein fingerprint matching. Large reference laboratories in the United States and Germany are deploying these systems at throughput levels exceeding 1,000 isolates daily. The technology is electrifying competitive positioning by compressing identification turnaround to minutes while reducing consumable costs per test.
EMA-FDA regulatory harmonization initiatives are narrowing performance validation thresholds for antimicrobial susceptibility testing kits, creating unified submission pathways. Device manufacturers now design single assay formats satisfying both jurisdictions, reducing development duplication. European diagnostic laboratories benefit first from this convergence, as notified bodies align interpretation criteria with FDA recognition standards.
Diagnostic purchasing coalitions are consolidating procurement authority across multi-hospital health systems, displacing decentralized laboratory autonomy. United States integrated delivery networks now negotiate enterprise-wide reagent contracts covering 50-150 affiliated facilities. Germany's hospital procurement associations apply similar concentration, extracting volume discounts that independent laboratories cannot match.
Clinical Microbiology Market Segmentation
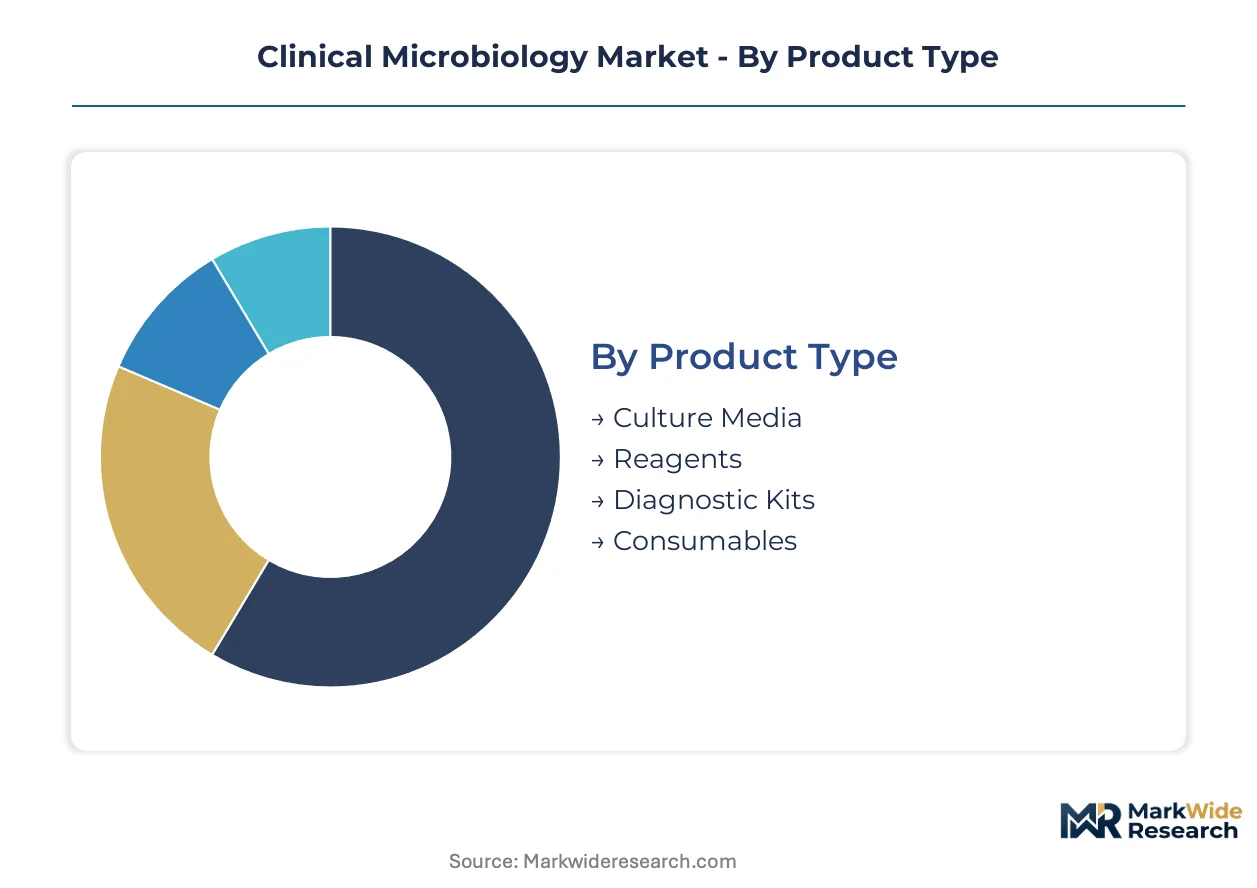
Segmentation in clinical microbiology reveals how capital intensity, regulatory validation requirements, and workflow automation priorities fragment purchasing decisions across laboratory tiers. Technology choices cascade through product procurement, application prioritization, and end-user capability constraints.
Product Type:
Product differentiation tracks directly to recurring revenue potential and regulatory burden intensity.
- Diagnostic Kits:Pre-validated assay formats for specific pathogen-resistance combinations carry the highest margin profiles due to FDA and EMA certification barriers protecting approved suppliers. Hospital networks in the United States concentrate procurement here to reduce in-house validation costs.
- Reagents:Antimicrobial susceptibility testing requires specialized chemical formulations with narrow temperature stability windows, concentrating manufacturing among specialized suppliers in Germany and Japan. Supply disruptions here propagate directly to laboratory throughput constraints.
- Culture Media:Standardized formulations for bacterial isolation.
- Consumables:Pipette tips, collection devices, and transfer systems.
Mature deployment sits with Reagents. Newer deployment is concentrated in Diagnostic Kits.
Technology:
Technology selection divides laboratories by capital access and specimen volume thresholds.
- Molecular Diagnostics:PCR and next-generation sequencing platforms detect resistance genes directly from clinical specimens without culture steps. United States hospital laboratories are displacing phenotypic workflows fastest here, compressing turnaround from days to hours.
- Mass Spectrometry:MALDI-TOF systems identify microorganisms through protein fingerprint matching in minutes. Deployment concentrates in large reference laboratories in Germany and the United States where annual isolate volumes exceed 50,000, amortizing equipment costs effectively.
- Microbial Culture:Conventional isolation and biochemical identification methods.
- Immunodiagnostics:Antigen and antibody detection assays for rapid screening.
Established infrastructure dominates Microbial Culture. Capacity expansion is concentrating in Molecular Diagnostics.
Application:
Application prioritization reflects antimicrobial stewardship pressures and transfusion safety mandates.
- Drug Resistance Testing:Carbapenemase and extended-spectrum beta-lactamase detection commands premium pricing due to infection control urgency and regulatory reporting requirements. Demand concentrates in tertiary care hospitals in Japan and the United States facing multidrug-resistant organism outbreaks.
- Pathogen Detection:Bloodstream and respiratory infection identification.
- Blood Screening:Transfusion-transmissible pathogen testing for donor safety.
- Environmental Testing:Healthcare facility surveillance for contamination sources.
Regulatory-mandated volume sits with Blood Screening. Investment flow is targeting Drug Resistance Testing.
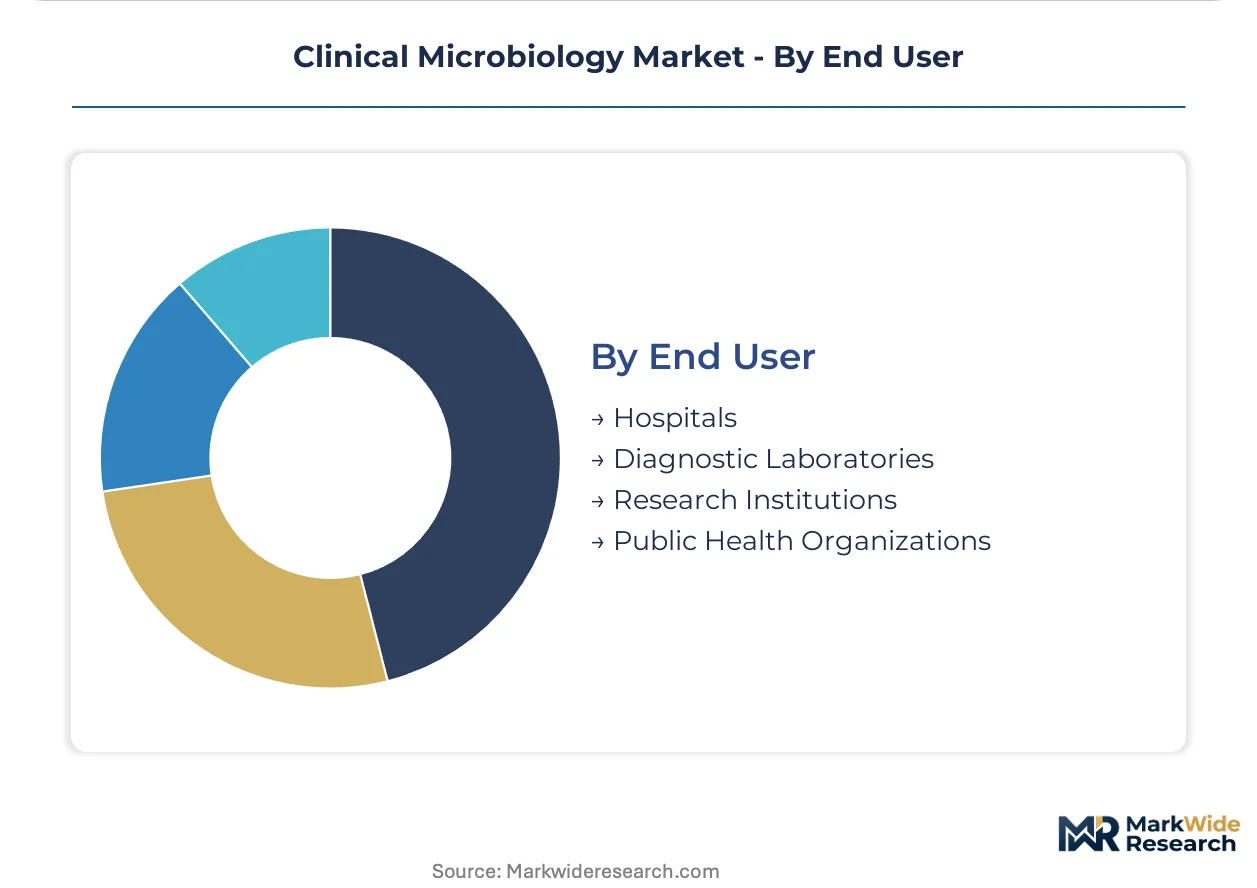
End User:
End-user segmentation captures divergence between integrated health systems and independent operators.
- Hospitals:Inpatient laboratories prioritize rapid turnaround for sepsis and pneumonia protocols, driving molecular platform adoption. United States integrated delivery networks negotiate enterprise contracts covering 50-150 affiliated facilities, concentrating purchasing power.
- Diagnostic Laboratories:Reference and commercial laboratories process high specimen volumes across multiple health systems. Germany's hospital procurement associations apply similar volume concentration, extracting discounts independent laboratories cannot match.
- Research Institutions:Academic medical centers developing novel resistance detection methods.
- Public Health Organizations:Surveillance laboratories tracking population-level resistance patterns.
Consolidated procurement sits with Diagnostic Laboratories. Platform refresh cycles are accelerating in Hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor anchors North American clinical microbiology infrastructure, with hospital networks and reference laboratories clustering along the Route 128 technology belt. This geographic concentration shapes procurement patterns and regulatory engagement strategies across the sector.
United States
Hospital networks in Massachusetts and California are replacing phenotypic workflows with PCR-based resistance detection systems. The FDA's updated antimicrobial susceptibility testing guidance is compressing kit validation timelines for domestic manufacturers. The Research Triangle Park corridor in North Carolina hosts contract research organizations supporting clinical trial endpoints for diagnostic platforms.
Germany
Tertiary care hospitals in Bavaria and North Rhine-Westphalia are standardizing MALDI-TOF mass spectrometry platforms for rapid pathogen identification. The EU Green Deal's healthcare sustainability criteria is redirecting public procurement toward energy-efficient automated culture systems. The Munich metropolitan region concentrates reagent manufacturing for antimicrobial susceptibility testing.
Japan
METI-coordinated investments are expanding molecular diagnostics infrastructure across Tokyo and Osaka tertiary care facilities. The PMDA is streamlining approval pathways for next-generation sequencing-based resistance panels. The Kansai region hosts specialized suppliers of culture media formulations for rapid mycobacterial detection.
China
Tier-two city hospital networks in Jiangsu and Zhejiang provinces are adopting localized diagnostic kits for carbapenemase detection. The NMPA's accelerated approval pathway is benefiting domestic manufacturers of resistance gene assays. The Yangtze River Delta cluster concentrates automated platform assembly operations.
United Kingdom
NHS England's antimicrobial stewardship mandates are elevating demand for rapid turnaround pathogen identification in London and Manchester hospital laboratories. The MHRA is aligning post-Brexit device conformity requirements with EMA recognition standards. The Cambridge biotech cluster supports development of novel spectrometric detection methods.
Clinical Microbiology Market Key Industry Players
The competitive structure tilts toward diversified life science conglomerates with diagnostics divisions. Three to five integrated technology holding companies control platform development and distribution networks. Two archetypes dominate: automated instrument specialists with recurring consumable revenue streams, and molecular assay developers with resistance gene database dependencies. Consolidation through strategic acquisitions and technology licensing agreements is compressing vendor options for hospital procurement officers.
Among diversified laboratory technology providers, Becton, Dickinson and Company and Thermo Fisher Scientific Inc. occupy positions spanning culture-based and molecular workflows. BioMérieux SA exemplifies the mass spectrometry-focused archetype with protein fingerprint identification systems. These three entities represent the tier where platform breadth and regulatory validation depth determine competitive standing in hospital network tenders.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories |
| Bruker Corporation |
| bioMérieux SA |
| Abbott Laboratories |
| Hologic Inc. |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
Hospital procurement coalitions in the United States are consolidating purchasing authority across 50-150 affiliated facilities, forcing reagent suppliers to absorb volume discounts or lose enterprise contracts entirely. This buyer concentration is compressing margins on antimicrobial susceptibility testing consumables while privileging automated platform vendors with embedded recurring revenue streams.
Pricing Analysis
Turnaround-time guarantees anchor value-based pricing for molecular diagnostics platforms, with United States hospital networks paying premium rates for resistance gene panels delivering results within four hours. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated assay kits from CE-marked equivalents and unvalidated research-use-only reagents. Cost compression in standard-tier consumables is intensifying because German hospital procurement associations extract volume commitments exceeding 100,000 tests annually. Reference laboratories with amortized mass spectrometry infrastructure exhibit lowest price sensitivity, while mid-sized hospital laboratories in tier-two Chinese cities face acute budget constraints.
Supply Chain Analysis
Direct-to-hospital channels handle molecular platform installations and consumable replenishment for integrated delivery networks in the United States and Germany. Specialized chemical manufacturing for antimicrobial susceptibility testing concentrates in Germany, Japan, and the United States, with these countries hosting the three dominant reagent formulators. Production draws from refined petrochemical feedstocks, lyophilized enzyme preparations, and precision-molded plastic consumables. Single-source vulnerability pervades the MALDI-TOF matrix crystal supply, where one Japanese specialty chemical producer controls global output. Distribution runs through regional distribution centers co-located with major hospital clusters in Boston, Munich, and Tokyo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clinical microbiology market is consolidating around platform-integrated conglomerates with regulatory validation depth, as IVDR compliance costs and FDA submission timelines extinguish standalone assay developers lacking capital reserves.
For Market Incumbents: Acquire resistance gene database assets to secure interpretive algorithm advantages against emerging bioinformatics specialists. Becton Dickinson and Thermo Fisher should deepen backward integration into reagent chemical manufacturing to insulate margins from supply disruptions. BioMérieux must defend its mass spectrometry installed base through embedded software subscriptions that raise switching costs for reference laboratories. For New Entrants and Emerging Players: The price-point gap between premium MALDI-TOF systems and economy-grade culture-based workflows opens entry space for point-of-care molecular devices in emergency departments. Target tier-two city hospital networks in China's Jiangsu and Zhejiang provinces, where NMPA accelerated approvals favor domestic kit manufacturers. Pursue white-label partnerships with German procurement associations to bypass direct selling infrastructure. For Investors and Strategic Acquirers: The window for entry favors vertically integrated diagnostic conglomerates with FDA and EMA dual-approval capabilities over pure-play assay developers. Long-term viability hinges on resistance surveillance database ownership as antimicrobial stewardship mandates expand. Monitor EMA-FDA harmonization announcements as inflection signals for unified submission pathway advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Resistance Gene Database Acquisition | Interpretive algorithm ownership secures recurring subscription revenue from hospital laboratories. |
| IVDR Dual-Certification Investment | EMA-FDA harmonization creates unified market access for assay kit manufacturers. |
| Point-of-Care Platform Development | Microfluidic integration enables emergency department specimen testing without culture steps. |
| Reagent Chemical Backward Integration | In-house production of susceptibility testing inputs insulates margins from supply disruptions. |
| Hospital System Partnership Expansion | Enterprise contracts covering 50-150 facilities concentrate procurement authority and volume. |
Research Approach
Independent corroboration across hospital laboratory directors, diagnostic platform engineers, and antimicrobial stewardship officers underwrites the qualitative findings on workflow transition patterns. Primary interviews with GPO contracts managers, reagent procurement leads, and FDA regulatory consultants were combined with secondary validation from FDA 510(k) filings, EMA IVDR technical documentation, and hospital procurement database extracts. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across the analysis window.
Rate-of-change decomposition separates technology displacement effects from antimicrobial resistance prevalence trends and regulatory compliance cost escalations. Segmentation dimensions span product type, technology platform, application urgency, and end-user procurement concentration, with regional regulatory cluster as an additional modeling layer. CAGRs were derived from installed base expansion curves and consumable pull-through coefficients, incorporating METI infrastructure investment disclosures and NHS England stewardship mandate timelines as industry-specific forecast inputs.
Inputs from FDA pre-submission meetings and EMA notified body guidance were available through the study window; gaps in tier-two Chinese hospital procurement data introduce uncertainty bands for domestic manufacturer share estimates. Forecasts reflect assumptions regarding IVDR certification timeline stabilization and resistance gene panel reimbursement expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
Renal Function Test Market
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
Colorectal Cancer Molecular Diagnostics Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
Lactate Dehydrogenase Test Market
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
Heart Failure Testing Market
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market
Clinical Diagnostics
Europe Colorectal Cancer Screening Market
Clinical Diagnostics
Global Cardiac Marker Testing Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market