
 Cytomegalovirus Assay Market | 2026-2036
Cytomegalovirus Assay Market Size, Share, and Industry Trends Forecast 2026-2036
Cytomegalovirus Assay Market Analytics
Buyer concentration in the Cytomegalovirus Assay Market is pivoting toward large reference laboratories and hospital networks consolidating infectious disease testing under centralized procurement. Abbott leverages its installed base of immunoassay analyzers to sustain recurring revenue streams across transplant centers. Bio-Rad Laboratories Inc. anchors its position through specialized quality control panels that laboratories require for PCR assay validation. F. Hoffmann-La Roche Ltd competes by extending its cobas platform into virology menus that integrate CMV quantitation with broader transplant pathogen surveillance.
Cytomegalovirus assays comprise diagnostic systems that detect viral DNA, proteins, or antibodies in clinical specimens, typically employing nucleic acid amplification with limits of detection below 50 IU/mL to guide antiviral therapy decisions in immunocompromised patients. Real-Time PCR technology leads the technology segment due to its quantitative precision in transplant monitoring, while Next-Generation Sequencing represents the fastest-growing category as laboratories adopt genotypic resistance profiling. The application segment shows margin concentration in transplantation monitoring, where longitudinal viral load testing generates higher per-patient revenue than one-time infectious disease diagnosis.
FDA nucleic acid test premarket notification requirements shape product development timelines for US manufacturers, while the EU In Vitro Diagnostic Regulation mandates clinical evidence standards that affect CE marking pathways for PCR-based CMV assays. The European Medicines Agency coordinates pharmacovigilance expectations that link diagnostic viral load thresholds to antiviral drug labeling. Stakeholders must monitor evolving CMS reimbursement determinations for multiplex transplant pathogen panels, as coding decisions will influence whether laboratories consolidate CMV testing within broader molecular infectious disease menus or retain standalone assay configurations.
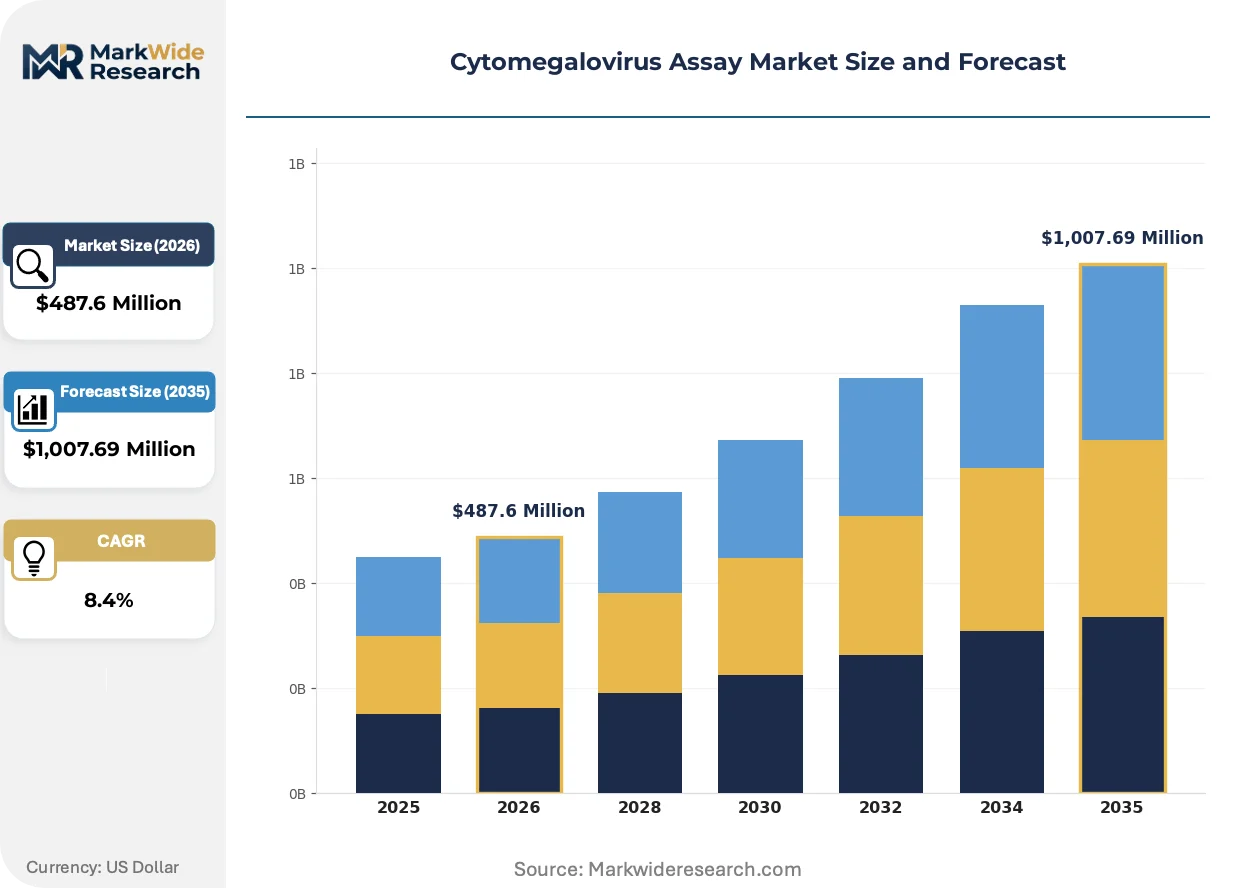
Market Dynamics
Automated nucleic acid amplification platforms are compressing turnaround times for CMV viral load quantitation, forcing diagnostic laboratories to consolidate testing workflows around integrated molecular systems or risk losing transplant center contracts to reference laboratories with higher throughput capacity.
Growth Catalysts
- Solid-organ transplant volume expansion:Rising kidney and liver transplant procedures in the United States generate recurring demand for longitudinal viral load monitoring, creating predictable assay consumption patterns.
- FDA nucleic acid test pathway acceleration:Shortened premarket notification review timelines for transplant monitoring applications enable faster commercialization of quantitative PCR assays.
- Next-Generation Sequencing adoption:Clinical laboratories are integrating genotypic resistance profiling into CMV management protocols, opening new service revenue streams beyond standard viral load reporting.
Market Restraints
- CE marking clinical evidence requirements:The EU In Vitro Diagnostic Regulation mandates expanded performance studies for PCR-based CMV assays, extending development timelines and validation costs for manufacturers seeking European market access.
- Reimbursement coding uncertainty:Evolving CMS determinations for multiplex transplant pathogen panels create revenue visibility risks for laboratories deciding between standalone CMV configurations or consolidated molecular menus.
- Specialized technician scarcity:Molecular diagnostics laboratories face persistent recruitment challenges for certified clinical laboratory scientists capable of validating and operating quantitative PCR systems.
Strategic Opportunities
- Hematopoietic stem cell transplant expansion:Cord blood and haploidentical transplant protocols in US academic medical centers require more frequent CMV surveillance than solid-organ protocols, supporting premium pricing for high-sensitivity assays.
- Antiviral therapeutic drug monitoring convergence:Integration of viral load quantitation with pharmacokinetic testing creates bundled service opportunities for diagnostic providers with both capabilities.
- Quality control panel standardization:External quality assessment programs for molecular CMV testing generate recurring revenue for suppliers of validated reference materials and proficiency testing specimens.
Industry Challenges
- PCR assay harmonization delays:Lack of standardized international reference materials complicates result comparability across different quantitative platforms, frustrating clinicians managing patients across transplant centers.
- Laboratory information system integration complexity:Middleware connectivity between automated molecular platforms and electronic health record systems requires substantial informatics investment, particularly for mid-sized hospital laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cytomegalovirus Assay Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,007.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR, Serological Tests, Antigen Detection, Viral Culture Technology: Real-Time PCR, ELISA, Nucleic Acid Hybridization, Next-Generation Sequencing End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutions Application: Infectious Disease Diagnosis, Blood Screening, Transplantation Monitoring, Prenatal Screening |
| Companies Covered | Thermo Fisher Scientific Inc., Abbott, Becton Dickinson and Company, Bio-Rad Laboratories Inc., Merck & Co. Inc., F. Hoffmann-La Roche Ltd, Qiagen, Roche Diagnostics, Sysmex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cytomegalovirus Assay Market Evolving Landscape
Digital PCR platforms are gaining traction for absolute viral load quantitation without calibration curves, while artificial intelligence-assisted result interpretation tools are entering validation studies at major transplant centers.
Sample-to-answer molecular systems is automating nucleic acid extraction, amplification, and detection within closed cartridge formats, reducing hands-on time for clinical laboratory scientists. Large reference laboratories in the United States are deploying these platforms across multiple satellite locations to standardize turnaround times. This automation is compressing the competitive advantage of centralized high-complexity testing facilities by enabling hospital laboratories to retain CMV testing in-house.
The EU In Vitro Diagnostic Regulation's clinical evidence requirements are forcing manufacturers to conduct larger prospective studies for CE marking of quantitative CMV assays. European notified bodies are demanding head-to-head performance comparisons against predicate devices, extending submission preparation timelines. Smaller diagnostic companies are responding by partnering with academic transplant centers to generate real-world evidence rather than funding standalone clinical trials.
Consolidated procurement by hospital network parent organizations is displacing individual transplant center purchasing autonomy for CMV assays. Health system supply chain departments are mandating sole-source agreements for molecular infectious disease testing across all affiliated hospitals. This concentration is most visible in the United States, where integrated delivery networks now control assay selection for over half of solid-organ transplant volumes.
Cytomegalovirus Assay Market Segmentation
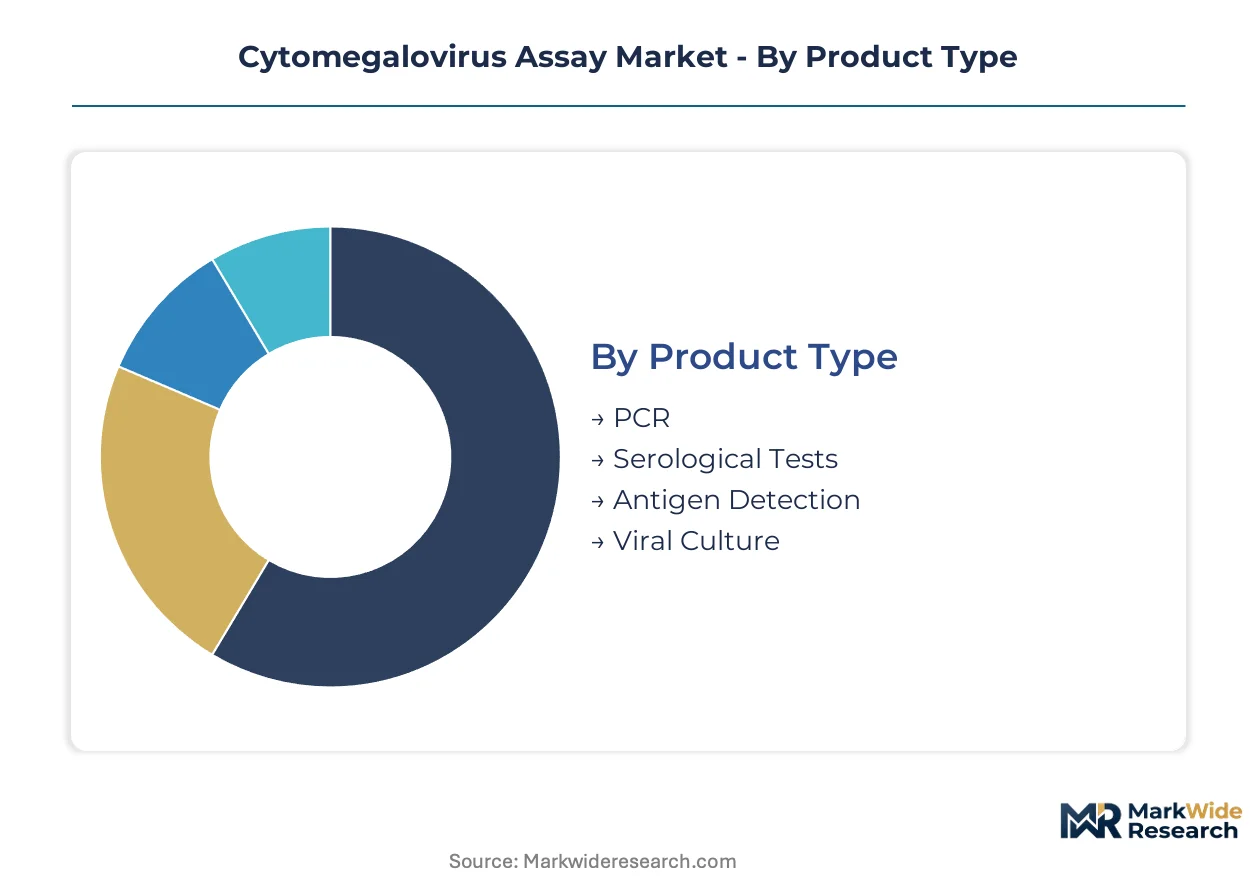
CMV assay segmentation reveals how technology choices and procurement concentration reshape competitive positioning. Supply-side specialization in molecular platforms versus serological alternatives determines margin capture across transplant centers and reference laboratories.
Product Type:
Supply concentrates around nucleic acid amplification platforms that command premium positioning in high-volume transplant monitoring contracts.
- PCR:Quantitative nucleic acid amplification delivers viral load precision below 50 IU/mL for therapeutic decision-making in immunocompromised patients. Demand clusters at US academic medical centers with solid-organ and stem cell transplant programs, where longitudinal monitoring generates recurring revenue.
- Serological Tests:Antibody-based detection platforms identify prior CMV exposure through IgG/IgM differentiation, serving initial screening protocols. Procurement concentrates in hospital networks standardizing pre-transplant patient workups under centralized laboratory contracts.
- Antigen Detection:pp65 antigenemia assays offer rapid viral protein identification without nucleic acid extraction infrastructure.
- Viral Culture:Traditional cell-based isolation methods retain niche utility for phenotypic resistance testing in specialized reference settings.
Today's leader: PCR. Tomorrow's challenger: Serological Tests bundled into multiplex infectious disease panels.
Technology:
Cost tiers separate automated high-throughput platforms from manual laboratory-developed tests, with reimbursement coding favoring FDA-cleared systems.
- Real-Time PCR:Fluorescence-based quantitation provides the clinical standard for transplant viral load surveillance with established calibration traceability. US transplant centers with high procedure volumes drive platform standardization decisions that ripple through affiliated hospital networks.
- Next-Generation Sequencing:Massively parallel sequencing enables genotypic resistance profiling and viral strain differentiation beyond quantitative reporting. Clinical laboratories at US academic medical centers are integrating this capability into CMV management protocols, expanding service revenue per specimen.
- ELISA:Enzyme-linked immunosorbent assays deliver cost-effective antibody screening for large-scale blood donor testing.
- Nucleic Acid Hybridization:Probe-based detection methods offer alternative amplification chemistries for resource-limited settings.
Real-Time PCR commands current volume. Next-Generation Sequencing shows the steepest expansion trajectory as resistance testing protocols mature.
End User:
Customer type determines procurement complexity, with integrated delivery networks consolidating purchasing authority away from individual laboratory directors.
- Diagnostic Laboratories:High-complexity molecular facilities process the majority of quantitative CMV testing under exclusive contracts with transplant programs. Large US reference laboratories are deploying automated sample-to-answer systems across satellite locations to standardize turnaround times.
- Hospitals:In-house clinical laboratories retain lower-complexity serological screening while outsourcing quantitative viral load testing. Mid-sized US hospital systems face middleware integration investments to connect automated molecular platforms with electronic health records.
- Clinics:Outpatient settings rely on send-out arrangements for CMV diagnostics given molecular complexity requirements.
- Research Institutions:Academic centers generate real-world evidence for assay validation under EU In Vitro Diagnostic Regulation clinical evidence mandates.
Diagnostic Laboratories dominate assay consumption. Hospital in-house testing represents the emerging competitive battleground as automation democratizes molecular capability.
Application:
Margin concentration varies sharply across use cases, with longitudinal monitoring outpacing one-time diagnostic events in per-patient revenue generation.
- Transplantation Monitoring:Serial viral load quantitation guides preemptive antiviral therapy throughout immunosuppression periods. US solid-organ transplant volume expansion and stem cell protocol intensification create predictable, high-frequency testing demand.
- Infectious Disease Diagnosis:Acute CMV detection in immunocompetent patients presents episodic demand with lower reimbursement per encounter.
- Blood Screening:Donor testing protocols maintain steady serological assay consumption at blood collection facilities.
- Prenatal Screening:Maternal and neonatal CMV detection supports congenital infection management pathways.
Transplantation Monitoring captures premium economics. Prenatal Screening offers underdeveloped penetration opportunity as maternal-fetal medicine protocols expand molecular testing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates higher per-patient assay revenue through longitudinal transplant monitoring than Germany, where consolidated laboratory networks standardize procurement across hospital systems. National regulatory frameworks and transplant program densities create divergent competitive dynamics across major markets.
United States
Solid-organ transplant volumes at academic medical centers in Houston and Pittsburgh drive recurring viral load testing demand. FDA nucleic acid test premarket notification pathways for transplant monitoring applications compress commercialization timelines for quantitative PCR assays. The Southeast cluster of transplant centers in Florida and Georgia is adopting automated sample-to-answer systems to standardize turnaround times across satellite locations.
Germany
University hospital networks in Berlin and Munich consolidate molecular infectious disease testing under centralized laboratory contracts. The EU In Vitro Diagnostic Regulation mandates expanded clinical evidence studies for CE marking of quantitative CMV assays, extending validation timelines. The Rhine-Ruhr metropolitan laboratory network is deploying harmonized PCR platforms to enable result comparability across affiliated transplant centers.
China
Expanding hematopoietic stem cell transplant programs in Beijing and Shanghai generate demand for high-sensitivity viral load quantitation. The National Medical Products Administration oversees nucleic acid amplification test registration for transplant monitoring applications. The Yangtze River Delta cluster of tertiary hospitals is integrating automated molecular systems to reduce dependence on reference laboratory send-outs.
Japan
Academic medical centers in Tokyo and Osaka advance genotypic resistance profiling through next-generation sequencing adoption. The Pharmaceuticals and Medical Devices Agency coordinates pharmacovigilance expectations linking diagnostic viral load thresholds to antiviral drug labeling. The Kansai region's transplant consortium is standardizing external quality assessment programs for molecular CMV testing across member institutions.
United Kingdom
National Health Service blood and transplant services maintain serological screening protocols for donor testing. The Medicines and Healthcare products Regulatory Agency implements post-market surveillance requirements for IVD performance monitoring. The Greater Manchester laboratory hub is consolidating quantitative viral load testing for multiple transplant centers under exclusive service agreements.
Cytomegalovirus Assay Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Cytomegalovirus Assay Market, creating a tiered structure where platform breadth determines contract access. Large diagnostics manufacturers leverage installed bases of automated analyzers to secure sole-source agreements with integrated delivery networks. Three archetypes dominate: diversified life science conglomerates with molecular platform portfolios, specialized molecular diagnostics firms with transplant-focused menus, and quality control reference material suppliers. Competitive moves concentrate on strategic partnerships with academic transplant centers for real-world evidence generation and automation-enabled workflow consolidation.
Among diversified diagnostics manufacturers, Thermo Fisher Scientific Inc., Abbott, and F. Hoffmann-La Roche Ltd occupy positions defined by platform scale and integrated system offerings. These conglomerates exemplify the archetype of breadth-driven competitors seeking to anchor laboratory contracts through multi-parameter virology menus. Their market presence reflects the structural advantage of analyzer installed bases in procurement decisions by consolidated hospital networks.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Abbott |
| Becton Dickinson and Company |
| Bio-Rad Laboratories Inc. |
| Merck & Co. Inc. |
| F. Hoffmann-La Roche Ltd |
| Qiagen |
| Roche Diagnostics |
| Sysmex Corporation |
| Others |
Value Network & Pricing Analysis
Certified clinical laboratory scientists in the United States command wage premiums that widen spreads between premium automated platforms and manual assay alternatives. Labor-cost differentials between high-complexity molecular facilities and mid-sized hospital laboratories stratify pricing tiers across transplant monitoring contracts.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for CE-marked quantitative PCR assays as manufacturers absorb expanded clinical evidence study costs under EU In Vitro Diagnostic Regulation mandates. Pricing stratifies across premium, standard, and economy tiers based on FDA clearance status and automation integration depth. Cost compression in the standard tier is intensifying because consolidated hospital networks are mandating sole-source agreements that favor bundled molecular menus. Reference laboratories exhibit the least price sensitivity due to recurring transplant center contract structures, while mid-sized hospital systems face acute budget constraints for middleware integration investments.
Supply Chain Analysis
Thermostable polymerase supply rests on specialized enzyme producers in the United States, Germany, and Japan with proprietary formulation expertise. Raw material dependencies include fluorescence-labeled probes, calibrated reference standards, and nucleic acid extraction reagents. Single-source vulnerability concentrates in certified reference material suppliers for viral load quantitation traceability. Distribution runs through authorized distributor networks serving integrated delivery networks and academic medical center procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FDA nucleic acid test pathway acceleration in the United States contrasts against extended CE marking timelines in Europe, creating divergent capital deployment windows.
For Market Incumbents: Extend platform integration capabilities to capture consolidated procurement decisions by integrated delivery networks controlling over half of US solid-organ transplant volumes. Anchor laboratory contracts through multi-parameter virology menus that bundle CMV quantitation with broader transplant pathogen surveillance. Counter next-generation sequencing entrants by embedding resistance profiling alerts within existing real-time PCR workflows.
For New Entrants and Emerging Players: Begin with prenatal screening applications where maternal-fetal medicine protocols are expanding molecular testing adoption faster than saturated transplant monitoring segments. Target cord blood and haploidentical stem cell transplant programs requiring more frequent surveillance than solid-organ protocols. Pursue academic medical center partnerships for real-world evidence generation under EU clinical evidence mandates rather than funding standalone trials.
For Investors and Strategic Acquirers: Diversified diagnostics conglomerates are the most active acquirer in this space, seeking transplant-focused menu specialists to fill virology portfolio gaps. Over the medium-term horizon, assess targets with automated sample-to-answer platforms that democratize molecular capability for mid-sized hospital laboratories. Watch CMS reimbursement determinations for multiplex transplant pathogen panels as the inflection signal for laboratory consolidation versus standalone assay retention.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sample-to-Answer Platform Deployment | Reduces hands-on time requirements at hospital laboratories competing with reference laboratory send-outs. |
| Academic Transplant Center Partnership | Generates real-world evidence for EU In Vitro Diagnostic Regulation clinical evidence mandates without standalone trial costs. |
| Multiplex Transplant Pathogen Panel Development | Captures CMS reimbursement coding advantages as consolidated procurement favors bundled molecular menus. |
| Next-Generation Sequencing Resistance Profiling Integration | Opens service revenue streams beyond standard viral load reporting at US academic medical centers. |
| External Quality Assessment Program Participation | Generates recurring revenue through validated reference materials and proficiency testing specimen supply. |
Research Methodology
Direct dialogue with transplant center laboratory directors, clinical virologists, hospital procurement managers, GPO contracts specialists, and IVD regulatory affairs leads grounded the qualitative foundation. Secondary validation drew from FDA 510(k) premarket notification databases, EMA pharmacovigilance guidance documents, CMS Medicare reimbursement determinations, and hospital procurement contract filings. Bottom-up assay volume modeling and top-down market sizing triangulated through transplant procedure volume correlations and per-patient testing frequency assumptions.
Bottom-up segmentations modeled technology adoption curves, end-user procurement concentration, and application-specific margin structures across the projection horizon. Analytical dimensions included product type, technology platform, end-user facility scale, and geographic regulatory cluster. CAGRs derived from fitted adoption curves calibrated to transplant volume expansion rates and automation penetration trajectories. Forecast inputs incorporated FDA review timeline trends, EU IVDR implementation pacing, and integrated delivery network consolidation patterns.
Several conditions sit outside the modeled scope, including unforeseen regulatory pathway reversals, novel antiviral therapeutic mechanisms that alter surveillance protocols, and macroeconomic disruptions to hospital capital expenditure cycles. Forecasts reflect assumptions about sustained transplant volume growth and stable reimbursement coding structures. A small set of named triggers warrants ongoing watch: CMS determinations for multiplex panel coding, EU notified body capacity constraints for IVDR submissions, and digital PCR platform commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Europe Colorectal Cancer Screening Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
Pediatric Cardiac Tumor Diagnostics Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Blood Urea Nitrogen Testing Market
Clinical Diagnostics
Global Nasopharyngeal Swab Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Blood Group Typing Market
Clinical Diagnostics
Bone Metabolism Test Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
Antenatal Screening Market
Clinical Diagnostics
Cystatin C Testing Market