
 Bacterial and Viral Specimen Collection Market | 2026-2036
Bacterial and Viral Specimen Collection Market Size, Share, and Industry Trends Forecast 2026-2036
Bacterial and Viral Specimen Collection Market Intelligence
Hospital and laboratory procurement is restructuring around integrated collection-to-sequencing workflows rather than standalone consumable purchasing. Thermo Fisher Scientific Inc. leverages its life sciences platform to bundle specimen devices with downstream analytical instruments. Becton, Dickinson and Company anchors hospital supply chains through automated dispenser systems and direct distribution contracts. Quidel Corporation specializes in point-of-care collection formats that bypass centralized lab routing.
Bacterial and viral specimen collection encompasses the engineered devices and transport media used to harvest, stabilize, and preserve microbial and viral nucleic acid or protein targets prior to laboratory analysis, typically incorporating flocked nylon or sterile cotton tips with universal or viral transport media maintaining viability across temperature ranges from refrigerated to ambient conditions for diagnostic, research, and surveillance purposes. Collection kits dominate unit volume as health systems consolidate ordering across swabs, vials, and transport media into standardized protocols that reduce procurement complexity and shelf-space requirements. Nylon materials displace traditional cotton in respiratory viral applications due to superior elution efficiency for molecular amplification methods, while glass vials retain share in reference laboratories requiring thermal stability for extended transport chains. Diagnostic testing applications generate the largest revenue pool, though epidemiological surveillance represents the fastest-expanding segment as national health agencies rebuild pandemic-era monitoring infrastructure.
FDA enforces quality system regulation under 21 CFR Part 820 for device manufacturers, while EMA's In Vitro Diagnostic Medical Devices Regulation tightens clinical evidence requirements for specimen collection devices marketed in Europe. ISO 13485 certification shapes supplier qualification decisions for multinational laboratory networks seeking harmonized quality documentation across jurisdictions. Stakeholders must monitor evolving transport media stability claims as regulatory bodies scrutinize shelf-life validation data against real-world temperature excursion profiles.
Market Dynamics
Hospital procurement teams are consolidating specimen collection purchasing into integrated diagnostic system contracts, compressing standalone consumable margins while favoring vendors with full workflow capabilities from collection through molecular analysis.
Growth Catalysts
- IVDR Compliance Deadlines:EMA's In Vitro Diagnostic Medical Devices Regulation mandates upgraded clinical evidence for collection devices, accelerating replacement cycles as laboratories retire legacy inventory ahead of certification deadlines.
- Flocked Nylon Elution Efficiency:Respiratory viral testing protocols now specify nylon-tipped swabs for superior nucleic acid release, driving material substitution across European and North American reference networks.
- India Molecular Infrastructure:CDSCO fast-track approvals for transport media and the country's expanding network of molecular diagnostic hubs generate concentrated demand for temperature-stable collection formats.
Market Restraints
- Polymer Supply Concentration:Flocked swab manufacturing depends on specialized nylon 6,6 fiber suppliers concentrated in Germany and China, exposing procurement to input volatility and geographic risk.
- Glass Vial Thermal Mass:Reference laboratories requiring extended cold-chain transport face higher shipping costs and breakage rates compared to plastic alternatives, limiting format flexibility.
- ISO 13485 Certification Burden:Multinational laboratory networks now require harmonized quality documentation, disqualifying smaller regional manufacturers lacking certification resources.
Strategic Opportunities
- Ambient Temperature Formulations:Transport media chemistries eliminating cold-chain requirements open surveillance networks in sub-Saharan Africa and Southeast Asia where refrigeration infrastructure remains limited.
- Point-of-Care Integration:Collection devices pre-loaded into cartridge-based molecular platforms bypass centralized laboratory routing, capturing value from urgent care and retail clinic expansion.
- PLI Scheme Alignment:India's Production Linked Incentive scheme for medical devices offers cost advantages for domestic manufacturing of viral transport media and sterile packaging.
Industry Challenges
- Stability Validation Timelines:FDA and EMA now require real-world temperature excursion data rather than accelerated aging models, extending shelf-life claim substantiation by 18-24 months.
- Automated Dispenser Integration:Hospital systems deploying Becton Dickinson and Roche automated collection platforms demand proprietary consumable geometries, fragmenting standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bacterial and Viral Specimen Collection Market |
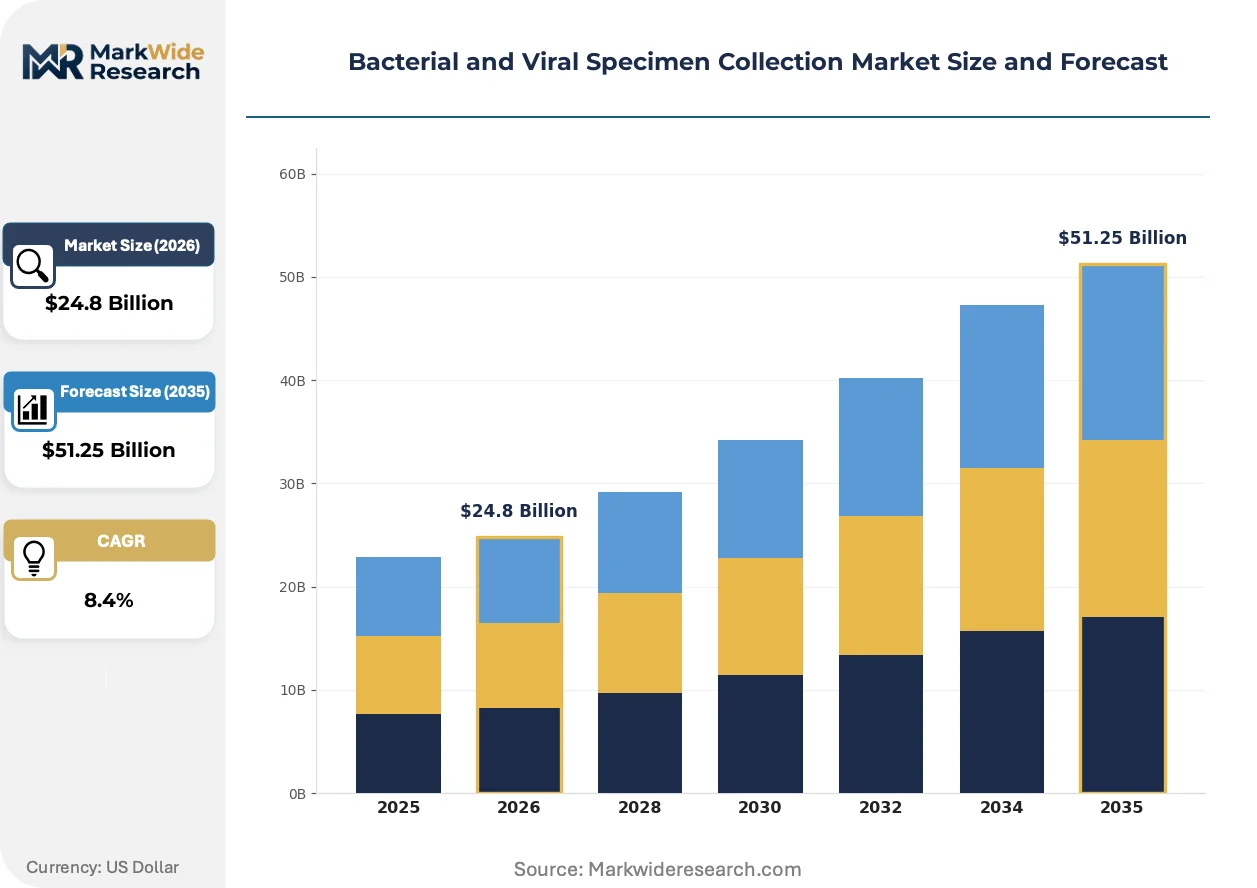
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swabs, Vials, Tubes, Collection Kits Material: Plastic, Glass, Sterile Cotton, Nylon End User: Hospitals, Laboratories, Clinics, Research Centers Application: Diagnostic Testing, Research Studies, Epidemiological Surveillance, Clinical Trials |
| Companies Covered | Thermo Fisher Scientific Inc., Becton, Dickinson and Company, Quidel Corporation, Puritan Medical Products, COPAN Diagnostics Inc., bioMérieux SA, Roche Diagnostics International AG, QIAGEN N.V., Longhorn Vaccines and Diagnostics LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bacterial and Viral Specimen Collection Market Strategic Shifts & Innovations
Specimen collection technology is converging with downstream analytical instrumentation, blurring historical boundaries between consumable and device categories while compressing the vendor landscape toward integrated platform providers.
Flocked nylon swab technology is absorbing market share from traditional cotton and synthetic alternatives by delivering superior nucleic acid elution efficiency for RT-PCR workflows. Large reference laboratories in Germany and the United States have completed material transitions, while mid-tier hospital systems are following with protocol standardization mandates. This material shift is absorbing margin from standalone swab manufacturers lacking downstream platform integration.
EMA's In Vitro Diagnostic Medical Devices Regulation (IVDR) has tightened clinical evidence requirements for specimen collection devices marketed in Europe, eliminating self-certification pathways that existed under the previous directive. Manufacturers must now submit technical documentation including performance studies and post-market surveillance plans, raising compliance costs disproportionately for single-product vendors. The regulation is forcing consolidation as smaller European suppliers seek acquisition by larger diagnostic platforms or exit the market entirely.
Health system procurement teams are bundling collection consumables with multi-year service contracts for molecular diagnostic instruments, unbundling the standalone consumable purchasing that dominated pre-pandemic procurement. Integrated device vendors capture recurring revenue through locked consumable geometries, while independent swab and transport media manufacturers face margin compression. This contract restructuring is most visible in United States academic medical centers and German hospital networks where procurement centralization has advanced furthest.
Bacterial and Viral Specimen Collection Market Segmentation
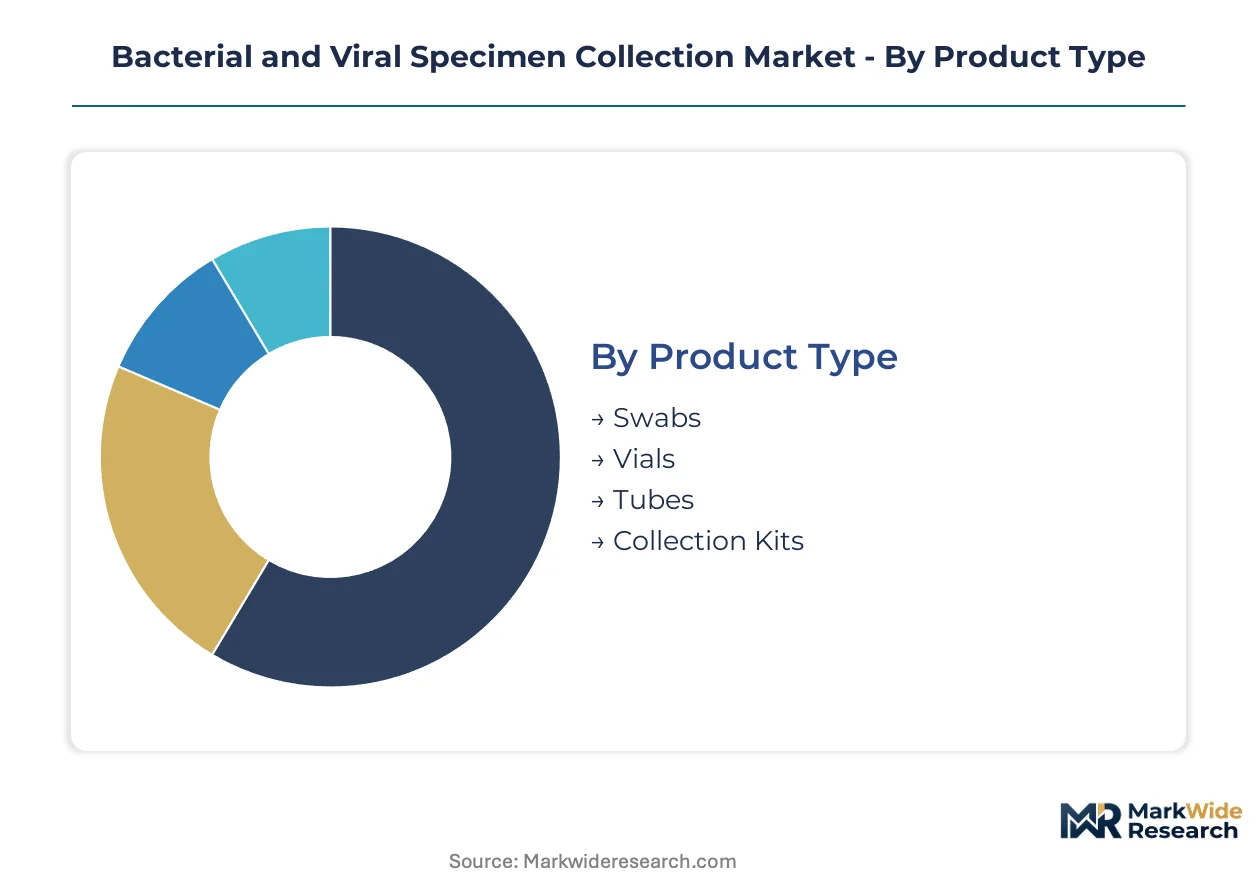
Specimen collection procurement patterns diverge sharply across product formats, material specifications, and end-use settings. Understanding these segment boundaries reveals where standardization pressures concentrate versus where customization commands premium positioning.
Product Type:
Supply concentration in automated dispensing systems favors vendors with integrated kit configurations over standalone component suppliers.
- Collection Kits:Bundled configurations combining swabs, transport media, and vials into single-SKU protocols dominate hospital procurement consolidation. United States academic medical centers now mandate kit standardization to reduce inventory complexity and protocol variation.
- Swabs:Flocked nylon-tipped designs with engineered fiber density for nucleic acid elution have displaced cotton in respiratory viral applications across German and North American reference networks.
- Vials:Sterile containers with pre-filled transport media serve high-throughput laboratory workflows requiring batch processing efficiency.
- Tubes:Conical and round-bottom formats accommodate centrifugation requirements in clinical chemistry and serology workflows.
Collection kits absorb the bulk of installed capacity; diagnostic testing applications are expanding most quickly.
Material:
Cost tier stratification separates premium synthetic formulations from commodity alternatives based on molecular diagnostic compatibility requirements.
- Nylon:Flocked 6,6 polymer fibers deliver superior nucleic acid release efficiency for RT-PCR workflows, commanding price premiums in respiratory viral testing protocols. Supply dependency on German and Chinese fiber manufacturers creates procurement vulnerability.
- Plastic:Polypropylene and polystyrene vials reduce shipping weight and breakage rates compared to glass, dominating point-of-care and ambulatory settings where cold-chain logistics are constrained.
- Sterile Cotton:Traditional fiber swabs retain share in bacterial culture applications where fiber shedding risks are minimal and cost sensitivity dominates.
- Glass:Borosilicate vials maintain thermal stability for extended transport chains in reference laboratory networks, though higher mass increases freight costs.
Nylon captures the steepest expansion trajectory as molecular protocols displace culture-based methods; glass retains defensive positions in thermal-critical applications.
End User:
Volume concentration in integrated health systems is compressing margins for standalone consumable vendors while rewarding full-workflow platform providers.
- Hospitals:Inpatient and emergency departments drive high-frequency collection for infectious disease panels, with procurement teams bundling consumables into multi-year instrument service contracts.
- Laboratories:Reference and clinical laboratories specify material performance for downstream analytical compatibility, particularly for molecular amplification workflows.
- Clinics:Outpatient and urgent care settings prioritize point-of-care formats with ambient temperature stability to bypass centralized laboratory routing.
- Research Centers:Academic and commercial research operations demand lot-to-lot consistency and documentation for regulatory submission support.
Hospitals command the largest volume commitments; clinics are gaining share fastest as retail healthcare expansion decentralizes collection infrastructure.
Application:
Maturity gradients separate established diagnostic testing from emerging surveillance mandates reshaping procurement specifications.
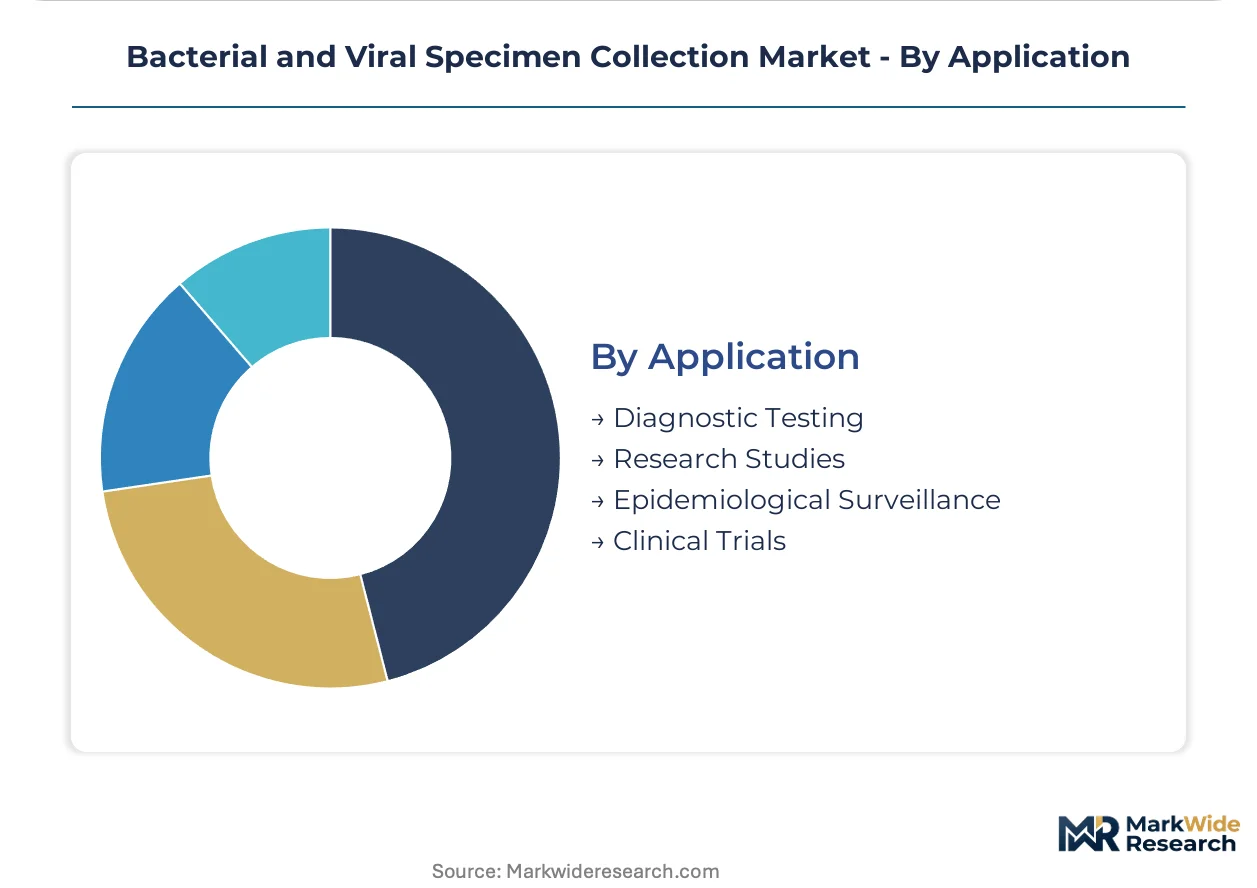
- Diagnostic Testing:Patient-level infectious disease identification generates recurring demand from hospital and laboratory networks, with reimbursement frameworks stabilizing purchase cycles.
- Epidemiological Surveillance:Population-level pathogen monitoring infrastructure rebuilt after pandemic-era investments is driving demand for temperature-stable formats suitable for decentralized collection networks.
- Research Studies:Academic and commercial investigations require customizable collection protocols with extensive documentation for publication and regulatory purposes.
- Clinical Trials:Pharmaceutical development programs demand chain-of-custody documentation and validated stability claims for regulatory submission packages.
Diagnostic testing anchors current revenue; epidemiological surveillance is climbing the fastest as national health agencies expand monitoring scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive scheme for medical devices has concentrated manufacturing investment in Gujarat and Karnataka special economic zones, reshaping procurement patterns across South Asian diagnostic networks.
United States
FDA's 21 CFR Part 820 quality system regulation drives hospital procurement consolidation toward integrated collection-to-sequencing vendors. The Inflation Reduction Act's diagnostic infrastructure investments accelerate molecular hub deployment. Greater Boston's biotech corridor anchors reference laboratory demand for temperature-validated transport formats.
Germany
EMA's IVDR compliance deadlines force retirement of legacy collection devices lacking clinical evidence documentation. Nylon 6,6 fiber manufacturing concentrates in Baden-Württemberg chemical clusters, creating input dependency for flocked swab producers. Munich's university hospital networks pioneer automated dispenser integration.
India
CDSCO fast-track approvals for viral transport media align with the country's expanding molecular diagnostic infrastructure under the National Health Mission. Production Linked Incentive scheme benefits concentrate in Gujarat's medical device parks and Karnataka's Bengaluru-Tumkur corridor. Domestic manufacturing of sterile packaging scales to serve Southeast Asian export markets.
China
NMPA's tightened medical device registration requirements elevate quality documentation burdens for transport media manufacturers. Yangtze River Delta chemical producers supply specialized polymer fibers for flocked swab production. Shanghai's clinical laboratory networks drive standardization toward automated collection workflows.
Switzerland
Swissmedic's harmonized quality standards with EU IVDR facilitate seamless market access for collection device manufacturers serving continental reference laboratories. Precision manufacturing capabilities in Basel's pharmaceutical cluster support high-consistency transport media production. Geneva's international health agency procurement channels demand validated cold-chain stability for surveillance network deployment.
Bacterial and Viral Specimen Collection Market Key Industry Players
Top-tier vendors anchor integrated diagnostic platforms, while mid-tier specialists concentrate on material innovations or regional distribution density. The vendor base stratifies across three archetypes: full-workflow platform providers, component specialists with certified manufacturing, and regional distributors with logistics advantages. Consolidation pressures intensify as procurement teams bundle multi-year service contracts. M&A activity targets transport media formulators with validated stability claims.
Among platform-integrated conglomerates, Thermo Fisher Scientific Inc. and Becton, Dickinson and Company occupy positions exemplifying the full-workflow archetype, while Quidel Corporation represents the point-of-care specialization tier. These three entities illustrate competitive positioning strategies ranging from life sciences bundling to automated dispenser lock-in to decentralized testing formats.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Becton, Dickinson and Company |
| Quidel Corporation |
| Puritan Medical Products |
| COPAN Diagnostics Inc. |
| bioMérieux SA |
| Roche Diagnostics International AG |
| QIAGEN N.V. |
| Longhorn Vaccines and Diagnostics LLC |
| Others |
Cost & Logistics Intelligence
Hospital procurement consolidation into multi-year diagnostic system contracts is forcing standalone consumable vendors to absorb margin compression while integrated platform providers capture pricing power through locked geometries.
Pricing Analysis
Short lead-time premiums command price advantages for ISO 13485-certified manufacturers capable of fulfilling rush orders from reference laboratories facing IVDR compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels separates validated transport media with real-world stability data from commodity alternatives lacking excursion documentation. Cost compression in the standard tier is intensifying as German and United States hospital networks consolidate purchasing volumes. Research centers exhibit the lowest price sensitivity due to grant-funded procurement and regulatory submission requirements, while ambulatory clinics prioritize economy tiers where ambient-temperature formats reduce cold-chain logistics costs.
Supply Chain Analysis
Workforce availability constraints in Baden-Württemberg's chemical clusters and Yangtze River Delta manufacturing zones limit flocked nylon 6,6 fiber production scaling. Supply concentrates in Germany and China for specialized polymer inputs, with Gujarat's medical device parks emerging as an alternative under India's PLI scheme. Raw material dependencies span nylon 6,6 fibers, borosilicate glass, and viral transport media formulations. Single-source vulnerability in German fiber manufacturing exposes procurement to geographic disruption. Distribution runs through hospital GPO contracts, reference laboratory direct agreements, and government tenders for surveillance network deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's IVDR compliance deadlines have erected a cost-of-compliance barrier that favors manufacturers with pre-existing clinical evidence dossiers and quality system investments, effectively moating integrated platform providers against undercapitalized regional competitors.
For Market Incumbents: Hedge against margin erosion in standalone consumables by deepening backward integration into nylon 6,6 fiber production or acquiring transport media formulators with validated stability claims. Automated dispenser lock-in through proprietary geometries with Becton Dickinson and Roche platforms defends recurring revenue streams against independent swab manufacturers. Certification investment in CDSCO fast-track pathways secures positioning in India's expanding molecular diagnostic infrastructure. For New Entrants and Emerging Players: Begin with ambient-temperature transport media formulations targeting sub-Saharan African and Southeast Asian surveillance networks where cold-chain infrastructure gaps create white-space demand. India's PLI-aligned manufacturing in Gujarat offers the most penetrable geography for cost-competitive sterile packaging and viral transport media production. Hospital system partnership through GPO contract participation provides the essential go-to-market angle for volume scaling. For Investors and Strategic Acquirers: The window for entry favors transport media specialists with validated real-world stability data rather than undifferentiated swab manufacturers facing nylon supply concentration risks. Mid-tier formulators holding FDA master files and EMA technical documentation represent prime acquisition targets as IVDR deadlines force retirement of legacy inventory. Watch for CDSCO approval acceleration signals as inflection indicators for Indian manufacturing capacity absorption.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Investment | EMA's tightened clinical evidence requirements eliminate self-certification pathways and force competitor exits. |
| Backward Integration into Nylon 6,6 Fiber | Baden-Württemberg and Yangtze Delta supply concentration creates input vulnerability for non-integrated swab producers. |
| Ambient Temperature Formulation Development | Surveillance network expansion in sub-Saharan Africa and Southeast Asia rewards cold-chain elimination. |
| Automated Dispenser Geometry Lock-in | Becton Dickinson and Roche platform integration captures recurring consumable revenue through proprietary specifications. |
| CDSCO Fast-Track Manufacturing Scale-Up | India's PLI scheme in Gujarat and Karnataka special economic zones offers cost advantages for export markets. |
Research Approach
Document review covered FDA 21 CFR Part 820 filings, EMA IVDR technical documentation databases, CDSCO approval records, and ISO 13485 certification registries, complemented by interviews with hospital procurement managers, reference laboratory directors, GPO contracts specialists, and transport media formulation scientists. Secondary validation drew from customs trade data for nylon 6,6 fiber imports, hospital supply chain disclosures, and national health agency surveillance procurement tenders. Bottom-up demand modeling across collection kit configurations triangulated with top-down molecular diagnostic infrastructure investment forecasts.
Segment-level value outputs were derived through product-format, material-specification, end-user setting, and application-type dimensions across the analysis window. CAGRs were computed from installed base expansion, protocol standardization mandates, and replacement cycle acceleration tied to regulatory deadlines. Forecast inputs incorporated IVDR compliance timeline phasing, PLI scheme manufacturing capacity buildout, and ambient-temperature formulation adoption curves in surveillance networks.
Underlying measurement precision varies by segment; diagnostic testing applications carry tighter precision than epidemiological surveillance given established reimbursement frameworks and procurement visibility. Forecasts reflect assumptions regarding regulatory deadline adherence, fiber supply continuity, and cold-chain infrastructure investment trajectories. Material deviation in IVDR enforcement intensity, CDSCO approval velocity, or nylon 6,6 supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Herpes Marker Testing Market
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
Osteoporosis Testing Market
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Clinical Trial Kits Market
Clinical Diagnostics
Clinical Diagnosis Automation Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Global Cardiac Marker Testing Market
Clinical Diagnostics
Cardiology Genomic Testing Market
Clinical Diagnostics
Europe Colorectal Cancer Screening Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Global Apoptosis Assays Market
Clinical Diagnostics
Blood Urea Nitrogen Testing Market
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
Renal Function Test Market