
 Next-Generation Cancer Diagnostics Market | 2026-2036
Next-Generation Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Cancer Diagnostics Market Outlook
A shift from single-source reference lab contracts toward multi-source in-house testing platforms is repositioning procurement strategies across health systems. Illumina, Inc. leverages its installed base of sequencing instruments to anchor clinical laboratory partnerships. Thermo Fisher Scientific Inc. competes through integrated workflow solutions spanning sample preparation to data analysis. QIAGEN sustains its position with companion diagnostic content libraries that lock in recurring assay consumption.
Next-generation cancer diagnostics encompasses molecular profiling technologies that detect genomic, proteomic, or cellular alterations in tumor tissue or biofluids, operating at analytical sensitivities below one percent variant allele frequency to guide therapeutic decisions. Liquid biopsy products command premium positioning due to non-invasive serial monitoring capabilities, while genomic sequencing remains the largest revenue pool anchored by comprehensive tumor profiling contracts. Early detection applications represent the fastest-expanding segment as pharmaceutical sponsors fund screening trials to expand addressable patient populations ahead of therapy launches.
FDA breakthrough device designations and EMA companion diagnostic pathways shape product development priorities, compressing validation timelines for sponsors that align with regulator-predefined endpoints. HIPAA data governance requirements and GDPR biometric protections constrain cross-border biobank utilization, forcing vendors to architect region-specific cloud infrastructure. Stakeholders must weigh capital deployment between decentralized point-of-care platforms and centralized mega-laboratory networks as reimbursement pathways diverge across payor categories.
Market Dynamics
Oncology clinics are consolidating testing workflows around liquid biopsy platforms as serial monitoring replaces single-point tissue sampling, compressing turnaround times from weeks to days while expanding reimbursable test menus.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited validation pathways compress commercialization timelines for sponsors targeting predefined companion diagnostic endpoints, accelerating patient access to biomarker-guided therapies.
- Germany's Precision Oncology Infrastructure:The country's statutory health insurance system now reimburses comprehensive genomic profiling for metastatic cancers, creating predictable demand for next-generation sequencing workflows.
- Pharmaceutical Sponsor Investment:Therapy developers fund prospective screening trials to expand addressable populations ahead of drug launches, directly underwriting early detection assay development.
Market Restraints
- Input Cost Volatility:Reagent-grade enzymes and synthetic oligonucleotides face supply concentration among contract manufacturers in Switzerland and Singapore, exposing assay producers to price shocks.
- Technical Sensitivity Floors:Current droplet digital PCR platforms struggle to reliably detect variant allele frequencies below 0.1% in cell-free DNA, limiting utility for minimal residual disease monitoring.
- GDPR Biometric Protections:Cross-border biobank utilization between EU member states and third countries requires region-specific cloud architecture, fragmenting data economies of scale.
Strategic Opportunities
- China's Hospital-Grade Laboratory Network:Tier-3 oncology centers in Shanghai and Beijing are building captive NGS capacity, creating demand for localized instrument partnerships and assay content libraries.
- Regulatory Tailwind from EMA Companion Diagnostic Pathways:Parallel scientific advice procedures allow sponsors to align clinical trial designs with pre-defined analytical validation requirements, reducing regulatory risk.
- Technology Convergence:Methylation-sensitive sequencing is converging with fragmentomic analysis to enable multi-cancer early detection from single blood draws, opening screening applications beyond tissue-of-origin identification.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical laboratories lack sufficient variant interpretation specialists to handle rising volumes of complex genomic reports, creating bottlenecks in report turnaround.
- Legacy LIS Integration Complexity:Hospital information systems built on HL7 v2 standards require costly middleware development to ingest structured genomic data from cloud-based analysis platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Cancer Diagnostics Market |
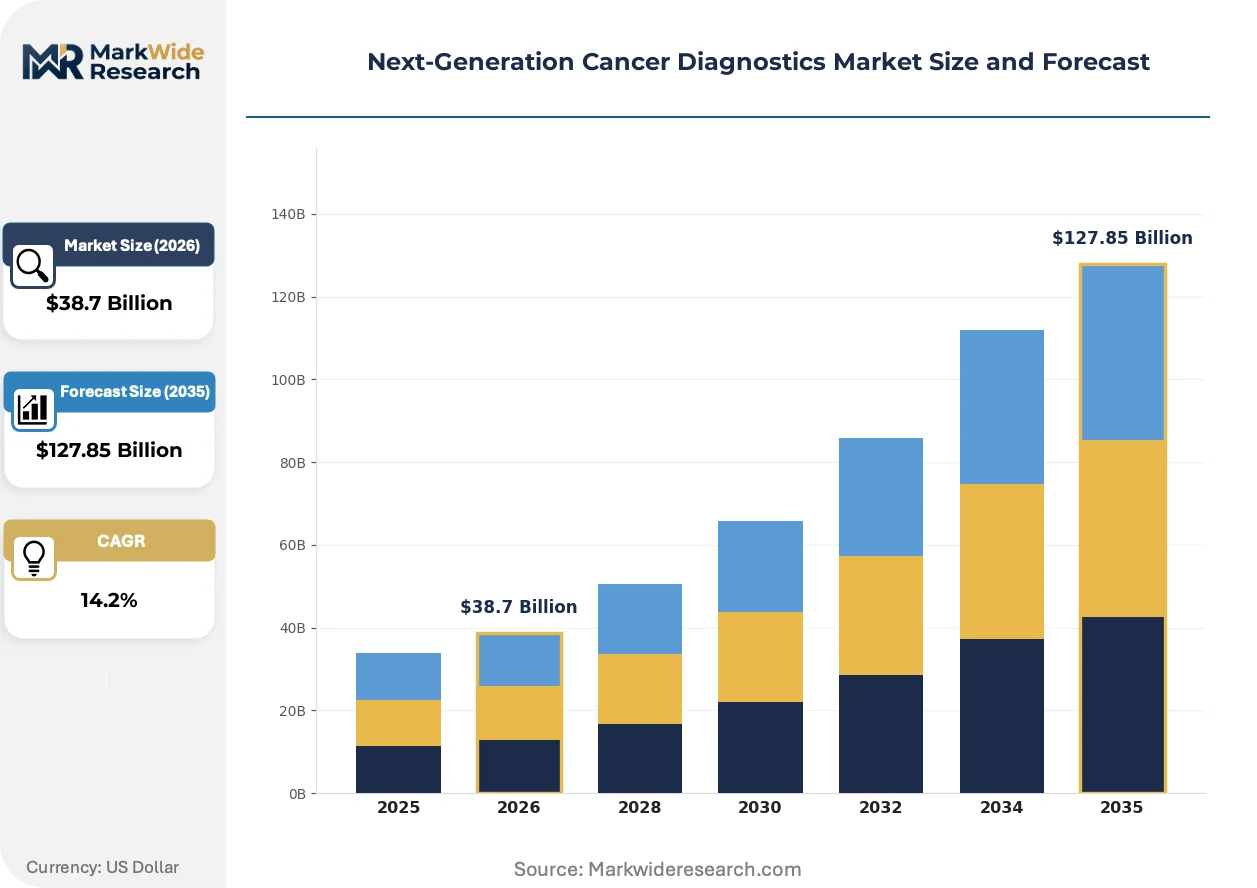
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Biopsy, Genomic Sequencing, Imaging Biomarkers, Proteomics End User: Oncology Clinics, Research Laboratories, Hospitals, Diagnostic Centers Technology: Next-Generation Sequencing, PCR, Mass Spectrometry, Microarrays Application: Early Detection, Disease Monitoring, Treatment Selection, Prognostic Assessment |
| Companies Covered | F. Hoffmann-La Roche Ltd, Illumina, Inc., QIAGEN, Agilent Technologies, Inc., Abbott, Thermo Fisher Scientific Inc., GE HealthCare, Koninklijke Philips N.V., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Cancer Diagnostics Market Strategic Shifts
Diagnostic workflows are fragmenting across point-of-care decentralization and centralized mega-laboratory consolidation, with reimbursement divergence determining which configuration dominates in each payor category.
Multi-omics profiling is converging with artificial intelligence-driven variant classification to automate report generation for complex genomic alterations. Community oncology practices lacking in-house bioinformatics capacity are adopting cloud-based interpretation services at accelerating rates. This convergence is compressing the competitive advantage of vertically integrated reference laboratories that historically bundled sequencing with proprietary analysis.
EMA's In Vitro Diagnostic Regulation (IVDR) is reclassifying companion diagnostic devices into higher risk categories, demanding expanded clinical evidence packages from manufacturers. Sponsors are responding by front-loading analytical validation studies to secure notified body opinions ahead of therapy approval deadlines. High-complexity molecular assays face the steepest compliance cost increases, favoring larger content libraries with amortized regulatory investments.
Hospital procurement committees are unbundling after-sales service contracts from instrument purchase agreements, treating maintenance and training as separately negotiable line items. This pattern is most visible in United States health systems where capital equipment committees now require three-year total cost of ownership analyses. Independent service organizations are capturing calibration and preventive maintenance volumes previously captive to original equipment manufacturers.
Next-Generation Cancer Diagnostics Market Segmentation
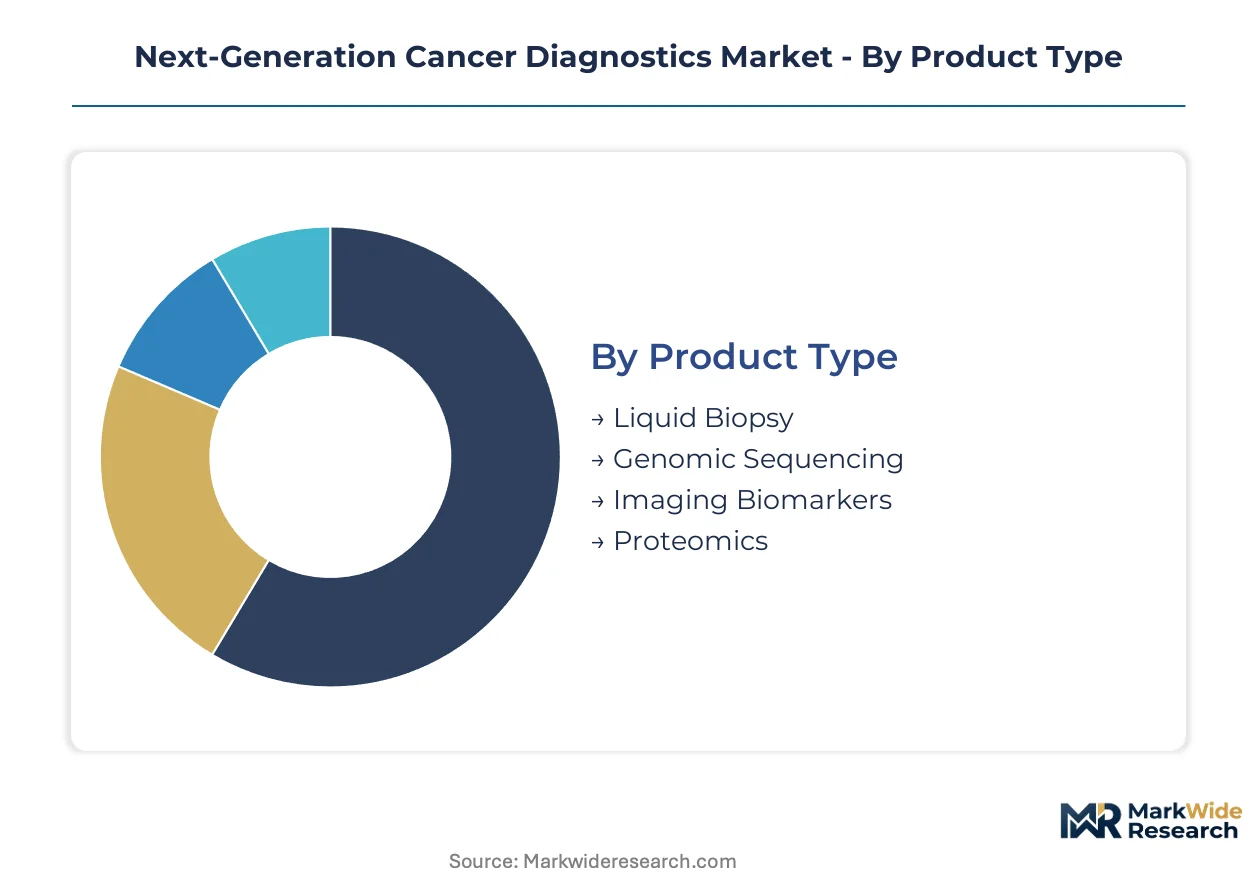
Segmentation in next-generation cancer diagnostics reveals distinct procurement patterns across technology tiers and care settings. Product architecture determines whether vendors capture revenue through instrument placements or recurring consumable streams.
Product Type:
Liquid biopsy platforms function as standalone decentralized systems, while genomic sequencing and proteomics often embed into integrated laboratory workflows.
- Liquid Biopsy:Cell-free DNA and circulating tumor cell isolation technologies enable non-invasive serial monitoring from peripheral blood draws. Demand clusters in United States oncology clinics pursuing real-time therapy response tracking, constrained by sensitivity floors below 0.1% variant allele frequency.
- Genomic Sequencing:Comprehensive tumor profiling spans targeted gene panels to whole-exome approaches, anchoring companion diagnostic contracts with pharmaceutical sponsors. Germany's statutory reimbursement for metastatic profiling sustains predictable instrument placement volumes.
- Imaging Biomarkers:Radiomics and quantitative imaging analytics extract molecular signatures from standard radiology workflows.
- Proteomics:Mass spectrometry-based protein quantification and antibody arrays profile circulating biomarker panels.
Volume placements concentrate in Genomic Sequencing; the faster expansion belongs to Liquid Biopsy.
End User:
Procurement authority shifts from centralized hospital committees toward specialized oncology units with dedicated molecular pathology budgets.
- Oncology Clinics:Community and academic cancer centers build captive testing capacity to retain specimen control and accelerate turnaround times. China's tier-3 hospital networks in Shanghai and Beijing are scaling in-house NGS laboratories to reduce reference lab dependency.
- Hospitals:Integrated health systems negotiate enterprise sequencing contracts spanning multiple sites, amortizing capital across high test volumes.
- Research Laboratories:Academic medical centers and contract research organizations drive analytical validation studies for novel biomarker discovery.
- Diagnostic Centers:Independent reference laboratories compete on turnaround time and payer contract breadth.
Instrument purchasing authority rests with Hospitals; oncology clinics are gaining the fastest share of test volume migration.
Technology:
Platform selection hinges on analytical sensitivity requirements and regulatory validation status rather than raw throughput specifications.
- Next-Generation Sequencing:Short-read and emerging long-read architectures detect single nucleotide variants, indels, and copy number alterations across hundreds of genes simultaneously. FDA breakthrough device designations for NGS-based companion diagnostics compress validation timelines for aligned sponsors.
- PCR:Quantitative and droplet digital PCR deliver rapid turnaround for hotspot mutation detection at lower per-sample cost. Germany's precision oncology infrastructure reimburses PCR-based profiling for targeted therapy selection in metastatic settings.
- Mass Spectrometry:High-resolution proteomic and metabolomic profiling identifies post-translational modifications and small molecule biomarkers.
- Microarrays:Comparative genomic hybridization and methylation arrays support copy number and epigenetic analysis.
Revenue concentration favors Next-Generation Sequencing; PCR retains the steepest expansion trajectory in point-of-care configurations.
Application:
Clinical utility validation progresses from late-stage disease monitoring toward earlier intervention points, expanding reimbursable indications.
- Early Detection:Multi-cancer screening assays from single blood draws target asymptomatic populations, requiring massive prospective validation cohorts. Pharmaceutical sponsors fund these trials to expand addressable patient populations ahead of therapy launches.
- Disease Monitoring:Serial liquid biopsy tracking of minimal residual disease guides therapy escalation or de-escalation decisions.
- Treatment Selection:Companion diagnostic matching links specific genomic alterations to approved targeted therapies.
- Prognostic Assessment:Molecular risk stratification predicts recurrence probability and overall survival independent of therapy choice.
Test volume currently centers on Treatment Selection; Early Detection applications are climbing the fastest as screening trials mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reagent-grade enzyme manufacturing clusters in Switzerland and Singapore anchor regional supply security for assay producers worldwide. These input material hubs feed diagnostic workflows across three dominant demand centers.
United States
FDA breakthrough device designations compress validation timelines for liquid biopsy sponsors targeting companion diagnostic endpoints. HIPAA data governance requirements constrain cross-border biobank utilization, forcing vendors to architect domestic cloud infrastructure. Community oncology practices in Texas and Florida are consolidating testing workflows around decentralized platforms.
Germany
The statutory health insurance system reimburses comprehensive genomic profiling for metastatic cancers, creating predictable demand for next-generation sequencing workflows. EMA companion diagnostic pathways align clinical trial designs with pre-defined analytical validation requirements. Munich and Heidelberg host dense clusters of molecular pathology laboratories scaling in-house NGS capacity.
China
Tier-3 oncology centers in Shanghai and Beijing are building captive NGS capacity to reduce reference lab dependency. NMPA regulatory pathways for innovative medical devices are converging with international standards. The Yangtze River Delta concentration of hospital-grade laboratories is driving localized instrument partnerships.
Japan
PMDA accelerated approval pathways for breakthrough diagnostics are shortening commercialization timelines for biomarker-guided assays. METI funding programs support precision oncology infrastructure development in academic medical centers. The Kanto region around Tokyo anchors the national concentration of high-complexity molecular testing capacity.
Next-Generation Cancer Diagnostics Market Competitive Environment
Strategic partnerships dominate the current landscape as instrument manufacturers anchor clinical laboratory relationships through integrated workflow solutions. The vendor base stratifies across three tiers: vertically integrated life science conglomerates, specialized genomic platform developers, and emerging point-of-care assay specialists. Consolidation pressures favor players with amortized regulatory investments across large content libraries. Technology licensing and geographic expansion represent the two dominant competitive vectors for mid-scale participants seeking defensible positioning.
Within the integrated conglomerate tier, F. Hoffmann-La Roche Ltd and Thermo Fisher Scientific Inc. exemplify archetypes that bundle reagent supply with instrument placements. Illumina, Inc. occupies a position as the dominant sequencing platform anchor, while QIAGEN represents the specialized content library model. These three entities collectively illustrate how competitive advantage in this market derives from locking in recurring consumable streams rather than discrete capital equipment sales.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Illumina, Inc. |
| QIAGEN |
| Agilent Technologies, Inc. |
| Abbott |
| Thermo Fisher Scientific Inc. |
| GE HealthCare |
| Koninklijke Philips N.V. |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committees in United States health systems are unbundling after-sales service contracts from instrument purchase agreements, treating maintenance and training as separately negotiable line items. This shift toward three-year total cost of ownership analyses is compressing margins on capital equipment while elevating recurring consumable streams as the dominant revenue anchor.
Pricing Analysis
Warranty and preventive maintenance bundling now separates original equipment manufacturers from independent service organizations competing on calibration contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by analytical sensitivity and regulatory validation status, with FDA breakthrough device designations commanding material premiums. Cost compression in PCR-based point-of-care configurations is intensifying because hospital capital equipment committees demand amortized per-sample economics. Community oncology practices lacking in-house bioinformatics capacity exhibit the highest price sensitivity, while pharmaceutical sponsors funding companion diagnostic development show minimal elasticity.
Supply Chain Analysis
Specialized workforce availability in Switzerland and Singapore constrains reagent-grade enzyme manufacturing capacity, forcing assay producers to secure multi-year supply commitments. Reagent-grade enzymes and synthetic oligonucleotides draw from contract manufacturers concentrated in these jurisdictions, with logistics chokepoints through pharmaceutical-grade cold chain networks. Single-source vulnerability in synthetic oligonucleotide synthesis exposes producers to input cost volatility. Distribution runs through regional distribution centers serving hospital-grade laboratory networks in Germany, China, and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized bioinformatics talent scarcity props pricing for cloud-based interpretation services, creating durable margin pools for vendors that automate variant classification. Capacity constraints in clinical laboratory report generation sustain premium positioning for workflow-integrated solutions.
For Market Incumbents: Anticipate displacement pressure from cloud-based interpretation services eroding the competitive advantage of vertically integrated reference laboratories. Lock in recurring consumable streams through companion diagnostic content libraries that anchor pharmaceutical sponsor contracts. Defend instrument placement volumes by front-loading analytical validation studies to secure notified body opinions ahead of EMA IVDR deadlines. For New Entrants and Emerging Players: Community oncology practices in Texas and Florida represent the most penetrable buyer archetype, lacking in-house bioinformatics capacity and consolidating around decentralized liquid biopsy platforms. Target early detection assay development funded by pharmaceutical sponsors screening trials to expand addressable patient populations. Pursue localized instrument partnerships with tier-3 hospital networks in Shanghai and Beijing as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors specialized genomic platform developers with amortized regulatory investments across large content libraries. Long-term viability hinges on regulatory convergence between NMPA pathways and international standards enabling geographic expansion. Watch EMA IVDR reclassification enforcement as the inflection indicator for compliance cost escalation favoring consolidated players.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough device designations compress validation timelines for liquid biopsy sponsors targeting companion diagnostic endpoints. |
| Hospital System Partnership | Enterprise sequencing contracts spanning multiple sites amortize capital across high test volumes in integrated United States health systems. |
| Software Companion Development | Artificial intelligence-driven variant classification automates report generation for complex genomic alterations in community oncology practices. |
| Reimbursement Strategy | Germany's statutory health insurance coverage for metastatic profiling creates predictable demand for next-generation sequencing workflows. |
| Geographic Expansion | Localized instrument partnerships with tier-3 oncology centers in Shanghai and Beijing reduce reference lab dependency in China's hospital-grade laboratory network. |
Study Parameters
Independent corroboration across primary interviews with molecular pathologists, regulatory affairs leads at diagnostic manufacturers, hospital procurement managers, and pharmaceutical biomarker strategy executives underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EMA companion diagnostic submissions, ClinicalTrials.gov screening trial registrations, and hospital GPO contract databases. Bottom-up instrument placement and consumable volume estimates triangulate against top-down market sizing derived from statutory reimbursement data in Germany and United States Medicare billing patterns.
Rate-of-change decomposition separates volume expansion from pricing dynamics across the analysis window. Segmentation dimensions modeled include technology platform, application from treatment selection through early detection, end-user category from oncology clinics through research laboratories, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to biomarker-guided therapy penetration rates and liquid biopsy adoption thresholds in metastatic disease monitoring. Forecast inputs incorporate EMA IVDR implementation timelines and NMPA regulatory convergence milestones.
Revisions become necessary when EMA IVDR enforcement intensity exceeds modeled assumptions or when supply concentration in Swiss and Singaporean regrade enzyme manufacturing triggers input cost shocks. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Blood Urea Nitrogen Testing Market
Clinical Diagnostics
Clinical Diagnosis Automation Market
Clinical Diagnostics
Global Nasopharyngeal Swab Market
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market
Clinical Diagnostics
Cervical Cancer Screening Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Bacterial and Viral Specimen Collection Market
Clinical Diagnostics
Lupus Anticoagulant Testing Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Global Cervical Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Global High-Resolution Melting Analysis Market