
 Global Forensic Testing Services Market | 2026-2036
Global Forensic Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Forensic Testing Services Market Foresight
The shift from in-house government laboratories toward outsourced forensic analysis is realigning procurement patterns across public safety budgets. Thermo Fisher Scientific leverages its mass spectrometry portfolio to dominate toxicology and DNA analysis workflows for contract laboratories. Agilent Technologies sustains competitive positioning through chromatography systems that anchor high-throughput drug screening operations. Envista Forensics differentiates by occupying the intersection of engineering failure analysis and forensic investigation for insurance and legal clients.
Forensic testing services encompass the scientific examination of physical, chemical, biological, and digital evidence to establish facts for criminal, civil, and regulatory proceedings, employing techniques such as polymerase chain reaction amplification for DNA profiling, gas chromatography-mass spectrometry for substance identification, and forensic imaging for electronic data recovery. DNA analysis commands the largest revenue share within service types due to its decisive role in criminal exonerations and cold case resolutions, while digital forensics represents the fastest-expanding category as ransomware investigations and corporate insider threat cases multiply. Laboratory testing remains the dominant delivery model because accreditation requirements and chain-of-custody protocols favor fixed-site facilities, though mobile testing units gain traction in mass-casualty incident response and remote crime scene applications.
The FBI's Quality Assurance Standards and ISO 17025 accreditation requirements shape laboratory eligibility for federal evidence processing contracts in the United States, while the United Kingdom's Forensic Science Regulator enforces statutory codes of practice that determine market access for providers serving Crown Prosecution Service needs. Germany's accreditation body DAkkS maintains equivalent standards under EU regulatory alignment for cross-border judicial cooperation in criminal matters. Stakeholders must monitor how artificial intelligence evidence authentication tools challenge established admissibility standards and force recalibration of analyst training curricula and laboratory capital planning.
Market Dynamics
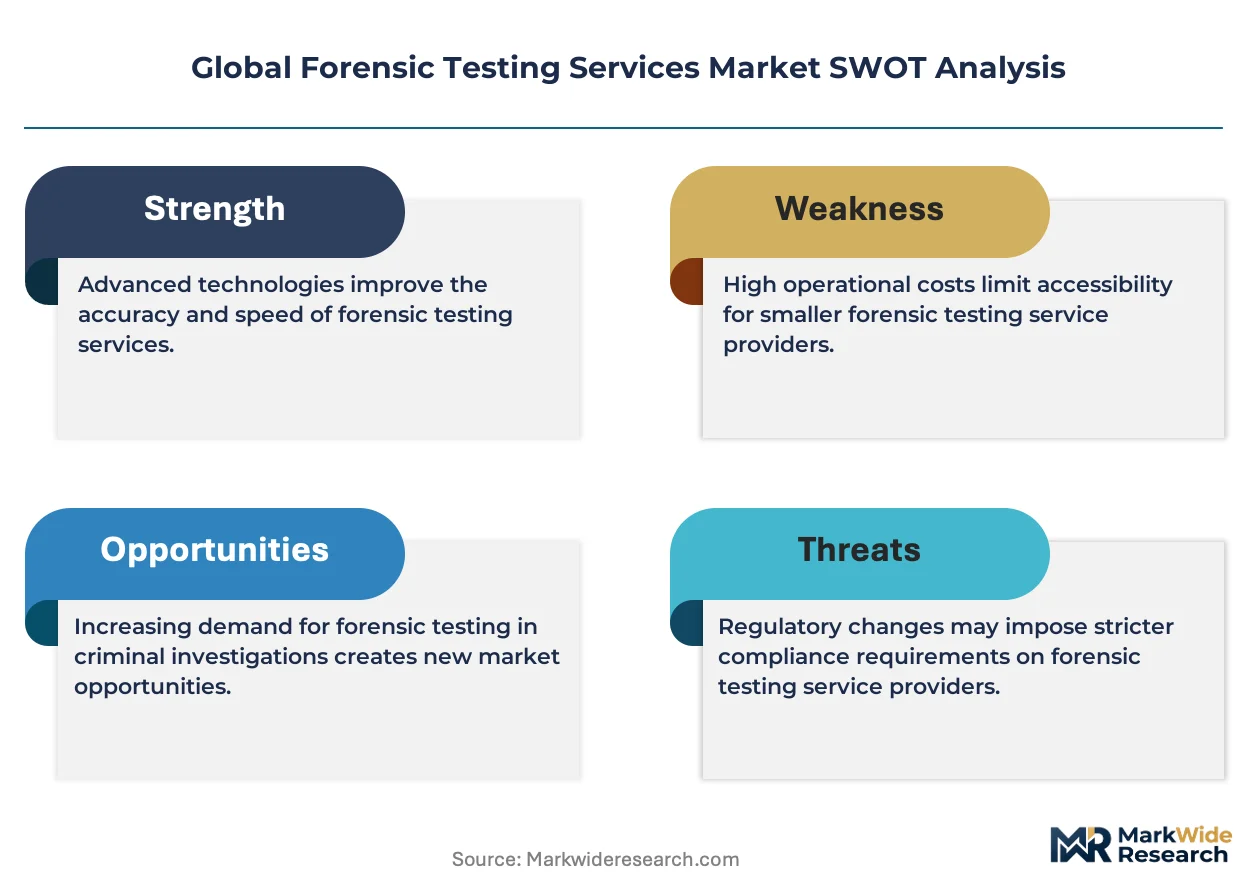
Forensic testing laboratories face mounting pressure from ISO 17025 accreditation mandates that require capital-intensive instrumentation upgrades and documented quality management systems, compressing margins for smaller providers while creating procurement advantages for accredited contractors serving federal agencies.
Growth Catalysts
- FBI CODIS Database Expansion:Federal backlog reduction initiatives in the United States are channeling evidence processing contracts toward private laboratories with DNA analysis capacity and existing accreditation credentials.
- Ransomware Investigation Surge:Corporate cybersecurity incidents are generating digital forensics caseloads that exceed in-house law enforcement technical capabilities, forcing outsourcing to specialized private providers.
- EU Cross-Border Judicial Cooperation:Germany's DAkkS accreditation alignment with EU standards is enabling certified laboratories to bid on multi-national criminal evidence processing contracts.
Market Restraints
- Capital Equipment Concentration:Mass spectrometry and next-generation sequencing platforms require seven-figure investments that concentrate analytical capacity among well-capitalized laboratory networks.
- Analyst Certification Bottlenecks:ISO 17025 technical competency requirements and FBI Quality Assurance Standards create multi-year training pipelines that constrain workforce expansion.
- Chain-of-Custody Infrastructure:Fixed-site laboratory models with documented custody protocols limit operational flexibility compared to portable testing alternatives.
Strategic Opportunities
- Mobile Testing Units:Mass-casualty incident response protocols in the United States are creating demand for deployable forensic capabilities that bypass fixed-laboratory bottlenecks.
- AI Evidence Authentication:Machine learning tools for image and document verification are opening service lines that complement traditional analytical chemistry and DNA workflows.
- Insurance Engineering Forensics:Engineering failure analysis for property and casualty claims represents an adjacent market with lower accreditation barriers and higher fee structures.
Industry Challenges
- Admissibility Standard Recalibration:Artificial intelligence evidence authentication tools are forcing courts to establish new reliability standards that require retraining of analyst testimony protocols.
- Multi-Jurisdictional Compliance:Laboratories serving both United States federal contracts and United Kingdom Crown Prosecution Service requirements must maintain parallel quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Forensic Testing Services Market |
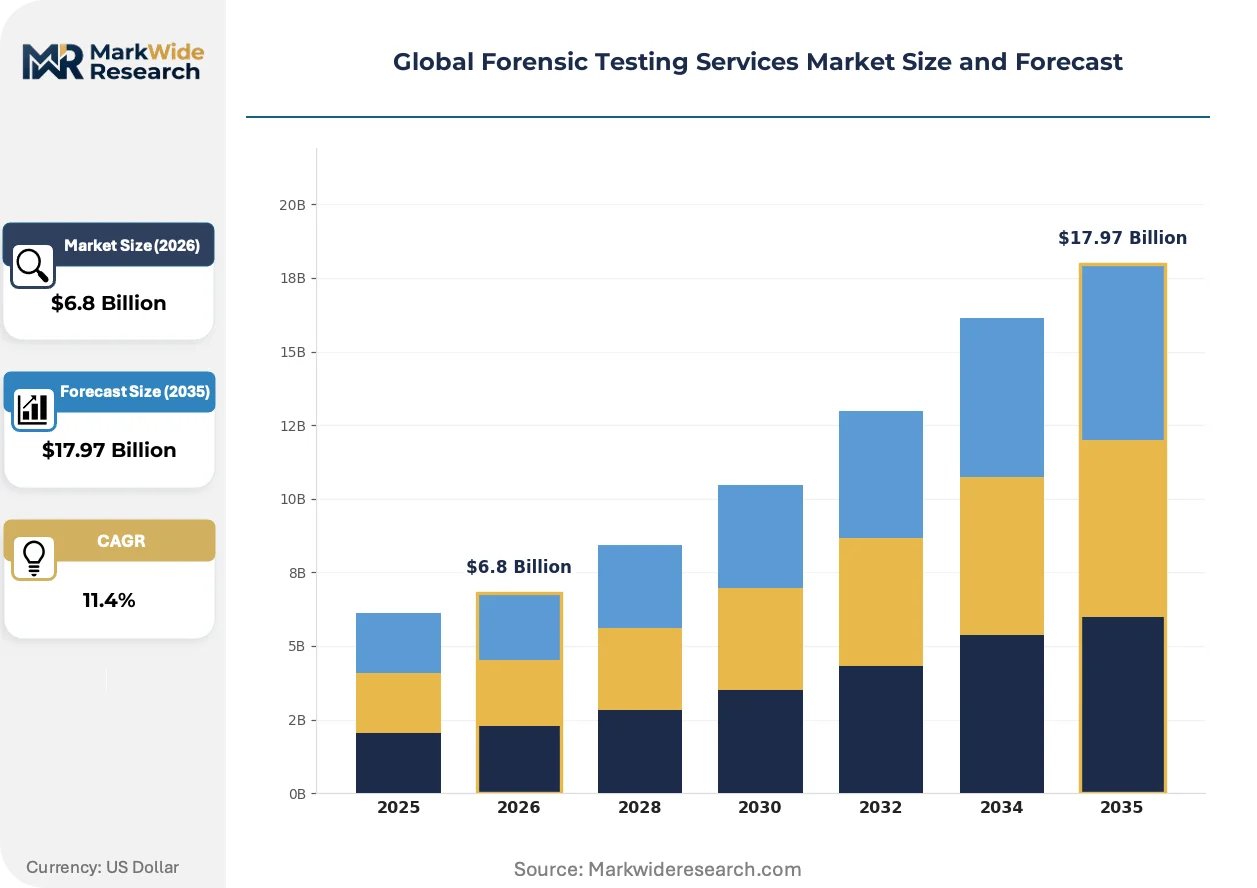
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: DNA Analysis, Toxicology, Fingerprint Examination, Digital Forensics, Ballistics, Trace Evidence Application: Criminal Case Investigation, Civil Litigation, Drug Enforcement, Cybercrime Detection, Fraud Investigation, Accident Reconstruction End User: Law Enforcement Agencies, Legal Firms, Insurance Companies, Private Investigators, Government Laboratories, Research Institutes Delivery Model: Onsite Testing, Laboratory Testing, Mobile Testing Units, Remote Analysis, Third-Party Collaboration, Consultancy Services |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Envista Forensics, Exponent, EFI Global, Intertek, GE Healthcare, NMS Labs, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Forensic Testing Services Market Shifts & Advancements
Next-generation sequencing and rapid DNA analysis platforms are compressing turnaround times for evidence processing while forcing traditional laboratories to reconfigure workflows around automation and data integration capabilities.
Rapid DNA instrumentation is electrifying field-deployable identification capabilities by enabling law enforcement agencies to process buccal swabs at booking stations within two hours. Police departments in the United States are piloting these systems for arrestee screening, bypassing centralized laboratory queues. This compression of analytical timelines is reshaping procurement priorities away from batch-processing efficiency toward point-of-need immediacy.
The European Union's AI Act is establishing risk-classification frameworks for automated evidence analysis tools that determine admissibility standards for machine-generated forensic reports. Laboratory providers serving EU member states must document algorithmic transparency and human oversight protocols. Digital forensics segments face the steepest compliance burden as probabilistic genotyping software and facial recognition systems fall under high-risk categorization.
Law enforcement procurement officers are unbundling analytical services from integrated laboratory contracts, creating spot-market purchasing for specialized capabilities like isotope analysis or advanced toxicology screening. This fragmentation favors niche providers with specific accreditation credentials over full-service laboratories. The United Kingdom's Forensic Science Regulator enforcement actions have accelerated this pattern by disqualifying generalist providers from sensitive casework categories.
Global Forensic Testing Services Market Segmentation
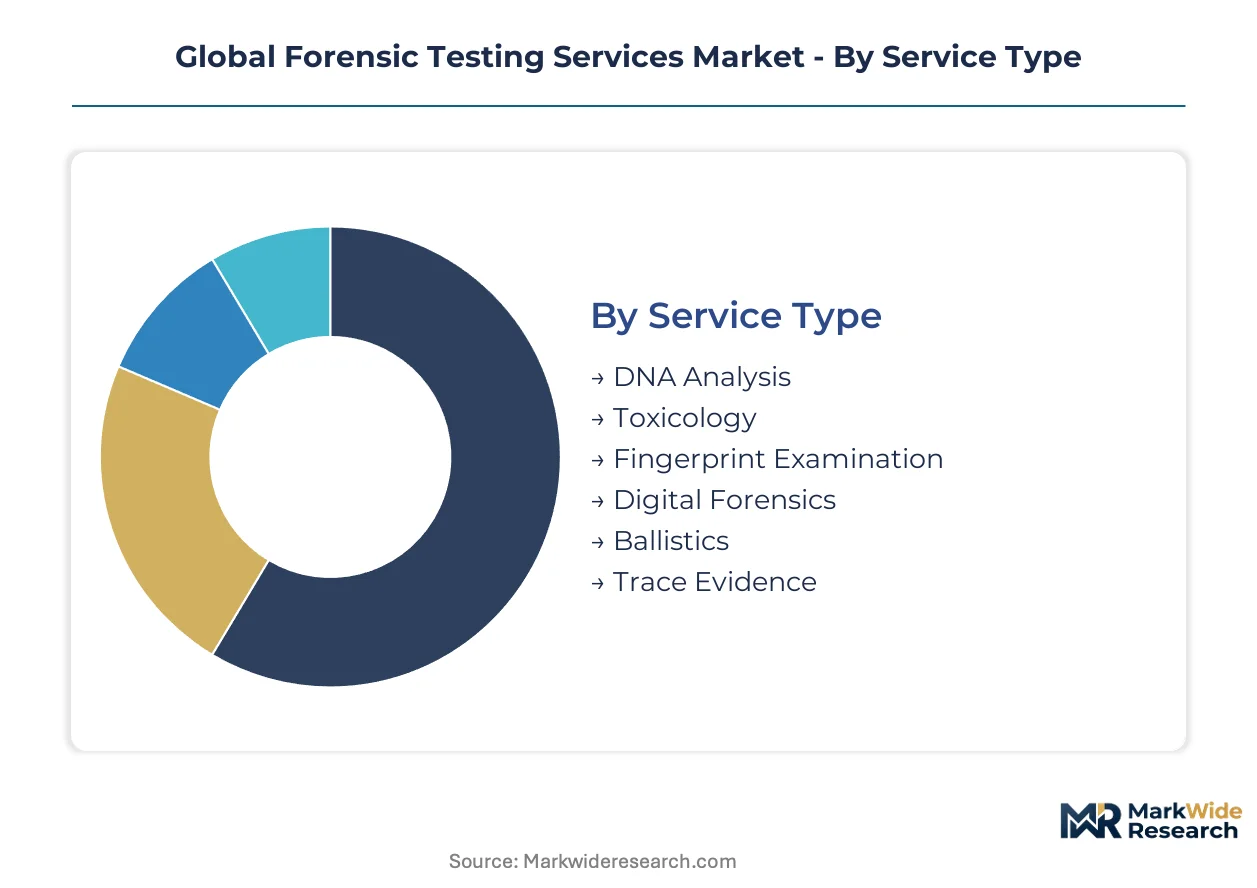
Forensic testing services fragment across multiple dimensions that determine procurement patterns, accreditation requirements, and margin structures. Service type dictates capital intensity and analyst specialization. Application context shapes chain-of-custody protocols and turnaround expectations.
Service Type:
DNA analysis commands premium pricing due to federal backlog reduction contracts, while toxicology and fingerprint examination operate at higher volumes with compressed margins.
- DNA Analysis:Polymerase chain reaction amplification and next-generation sequencing platforms process biological evidence for criminal identification and exoneration. Federal agencies in the United States channel substantial contract volume toward accredited private laboratories with CODIS-compatible workflows, constrained by ISO 17025 mandates that filter out smaller providers.
- Digital Forensics:Electronic data recovery and ransomware investigation protocols extract admissible evidence from compromised systems. Corporate cybersecurity incidents in the United States and Germany generate caseloads exceeding in-house law enforcement capacity, forcing outsourcing to specialized providers with cross-border judicial cooperation credentials.
- Toxicology:Gas chromatography-mass spectrometry identifies controlled substances in biological matrices for drug enforcement and post-mortem investigation.
- Fingerprint Examination:Automated latent print analysis and AFIS database comparison support criminal case investigation workflows.
- Ballistics:Firearm and tool mark comparison examines projectile trajectories and weapon identification for violent crime prosecution.
- Trace Evidence:Microscopic analysis of hair, fiber, and particulate matter links suspects to crime scenes in circumstantial cases.
Mature deployment sits with DNA analysis. Newer deployment is concentrated in digital forensics.
Application:
Criminal case investigation absorbs the majority of accredited laboratory capacity, while cybercrime detection and fraud investigation expand fastest as corporate demand outpaces public sector resourcing.
- Criminal Case Investigation:Homicide, sexual assault, and property crime evidence processing dominates laboratory throughput in the United States and United Kingdom. Crown Prosecution Service procurement standards and FBI Quality Assurance Standards create dual compliance burdens for multi-jurisdictional providers.
- Cybercrime Detection:Ransomware response, insider threat investigation, and network intrusion analysis require specialized digital forensics expertise. Law enforcement technical capabilities lag incident frequency in Germany and the United States, opening procurement to private contractors with EU AI Act documentation protocols.
- Civil Litigation:Discovery support and expert testimony preparation serves legal firms in contract disputes and personal injury claims.
- Drug Enforcement:Controlled substance identification and clandestine laboratory analysis supports interdiction operations.
- Fraud Investigation:Financial document examination and forensic accounting traces asset misappropriation and corporate misconduct.
- Accident Reconstruction:Engineering failure analysis and scene documentation determines liability in vehicular and industrial incidents.
Criminal case investigation anchors established revenue. Cybercrime detection is climbing the fastest as ransomware volumes escalate.
End User:
Law enforcement agencies remain the primary contracting authority, though insurance companies and legal firms represent higher-margin opportunities with less stringent accreditation overhead.
- Law Enforcement Agencies:Municipal police departments, sheriff's offices, and federal bureaus outsource evidence processing to reduce forensic backlogs. The FBI's CODIS expansion and backlog reduction initiatives in the United States concentrate procurement among accredited private laboratories with documented quality management systems.
- Insurance Companies:Property and casualty carriers commission engineering failure analysis and accident reconstruction for claims validation. Lower accreditation barriers and higher fee structures attract providers seeking margin expansion beyond criminal casework.
- Legal Firms:Defense attorneys and civil litigators procure independent expert analysis and testimony preparation.
- Private Investigators:Surveillance documentation and background verification services require limited forensic sophistication.
- Government Laboratories:In-house federal and state facilities maintain capacity for sensitive or classified evidence processing.
- Research Institutes:Academic collaborations advance methodological validation and novel technique development.
Law enforcement agencies dominate transaction volume. Insurance companies are gaining share fastest as engineering forensics expands.
Delivery Model:
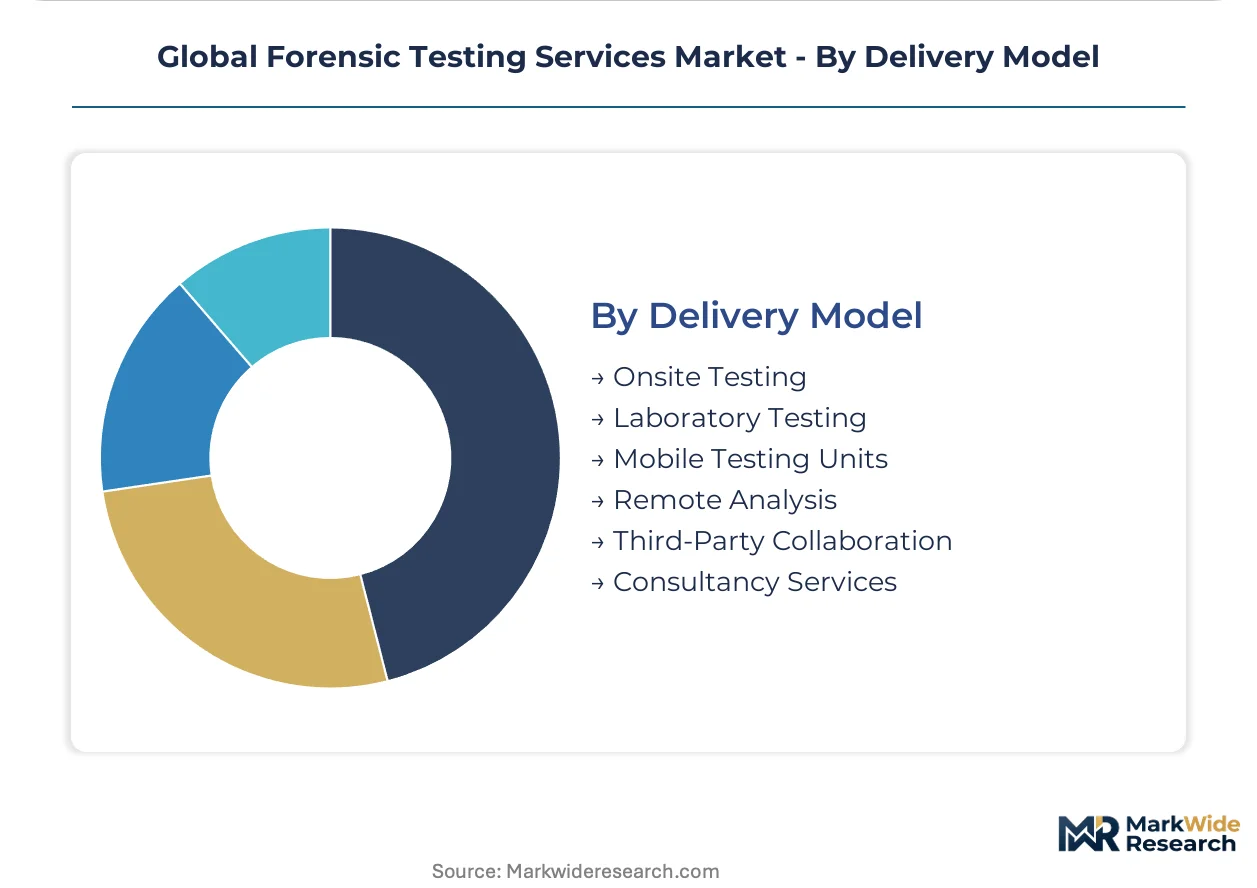
Laboratory testing captures the majority of accredited capacity, while mobile testing units and remote analysis emerge as flexibility differentiators for mass-casualty and distributed incident response.
- Laboratory Testing:Fixed-site facilities with documented chain-of-custody protocols and ISO 17025 accreditation process the majority of DNA and toxicology caseloads. Accreditation requirements and quality management systems favor centralized operations with capital-intensive instrumentation in the United States, United Kingdom, and Germany.
- Mobile Testing Units:Deployable forensic capabilities bypass fixed-laboratory bottlenecks for mass-casualty incident response and remote crime scene applications. United States emergency management protocols are piloting rapid DNA instrumentation at booking stations, compressing analytical timelines from weeks to hours.
- Onsite Testing:Crime scene technicians collect and preserve evidence under chain-of-custody protocols for laboratory transport.
- Remote Analysis:Secure data transmission enables distributed expert consultation and digital evidence review.
- Third-Party Collaboration:Subcontracting arrangements extend specialized capabilities like isotope analysis or advanced toxicology screening.
- Consultancy Services:Expert testimony preparation and case strategy advisory support litigation workflows.
Laboratory testing anchors established accreditation. Mobile testing units are expanding most quickly as point-of-need immediacy reshapes procurement priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Human capital concentrations in forensic science education and federal research funding anchor geographic demand patterns across national jurisdictions. Quality accreditation regimes and criminal justice system structures determine laboratory procurement eligibility and contract terms.
United States
FBI CODIS database expansion and federal backlog reduction initiatives channel evidence processing contracts toward accredited private laboratories. ISO 17025 mandates and FBI Quality Assurance Standards filter market access for providers seeking federal procurement eligibility. Forensic laboratory clusters concentrate in the Washington D.C. metro area, Virginia, and Maryland corridor where proximity to federal agencies shapes contract concentration.
Germany
Cross-border judicial cooperation frameworks under EU regulation generate demand for DAkkS-accredited laboratories serving multi-national criminal evidence processing. The EU AI Act establishes risk-classification requirements for automated forensic analysis tools that determine admissibility standards. Laboratory accreditation activity concentrates in Berlin and Frankfurt metropolitan areas where federal criminal police and international judicial cooperation infrastructure cluster.
United Kingdom
Forensic Science Regulator statutory codes of practice determine market access for providers serving Crown Prosecution Service procurement needs. The regulator's enforcement actions have accelerated disqualification of generalist providers from sensitive casework categories. Commercial forensic laboratory capacity clusters in London, Birmingham, and Manchester where police force procurement concentration and legal services infrastructure overlap.
Canada
Royal Canadian Mounted Police forensic laboratory services and provincial police force outsourcing patterns shape demand for accredited private capacity. Health Canada and provincial health authority toxicology requirements create parallel accreditation pathways for substance identification services. Forensic service providers concentrate in Ontario and Quebec where population density and criminal caseload volume support laboratory economies of scale.
Australia
National Association of Testing Authorities accreditation requirements and state police force procurement frameworks determine laboratory market access across jurisdictions. State-based forensic science institutes maintain in-house capacity while outsourcing specialized capabilities to private accredited providers. Commercial laboratory activity clusters in Sydney, Melbourne, and Brisbane where state police headquarters and legal services infrastructure concentrate demand.
Global Forensic Testing Services Market Competitive Landscape
Global majors compete with regional champions across accreditation credentials and specialized analytical capabilities. Market structure tilts toward consolidated networks among well-capitalized laboratory groups capable of sustaining ISO 17025 compliance investments, while niche specialists occupy segment-specific positions. Three archetypes dominate: diversified analytical instrumentation conglomerates, specialized forensic engineering consultancies, and regional accredited laboratory networks. Competitive moves center on accreditation portfolio expansion and technology platform licensing arrangements.
Within the instrumentation conglomerate tier, Thermo Fisher Scientific and Agilent Technologies occupy positions anchored by mass spectrometry and chromatography platform portfolios. Envista Forensics exemplifies the forensic engineering consultancy archetype, occupying the intersection of failure analysis and insurance claims investigation. These three entities represent distinct strategic positioning vectors across equipment supply, analytical services, and expert testimony delivery.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Envista Forensics |
| Exponent |
| EFI Global |
| Intertek |
| GE Healthcare |
| NMS Labs |
| Promega Corporation |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up laboratory networks dominate forensic testing capacity across the United States, Germany, and the United Kingdom, concentrating ownership among consolidated groups that enforce pricing discipline through ISO 17025 accreditation barriers and federal contract eligibility requirements. This ownership pattern feeds supply behavior toward capital-intensive instrumentation clusters in metropolitan corridors while compressing margins for non-accredited competitors.
Pricing Analysis
Warranty and service bundling separates accredited providers from unbundled spot-market alternatives, with federal contracts typically incorporating multi-year quality assurance commitments while corporate digital forensics often procures discrete project scopes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FBI Quality Assurance Standards commanding substantial premiums over state-level accreditation. Pricing pressure stems from rapid DNA instrumentation reducing centralized laboratory throughput for routine screening. Law enforcement agencies exhibit highest price sensitivity due to fixed public budgets, while insurance carriers tolerate premium fee structures for engineering failure analysis.
Supply Chain Analysis
Mass spectrometry and next-generation sequencing platform supply rests on specialized instrumentation manufacturers concentrated in the United States, Germany, and Japan. Reagent and consumable inputs draw from chemical suppliers in Switzerland and Singapore, with reference standard materials sourced from national metrology institutes. Single-source vulnerability concentrates in proprietary software ecosystems controlling probabilistic genotyping algorithms. Distribution runs through direct manufacturer-laboratory relationships for capital equipment, with consumables flowing through regional scientific supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The forensic testing market sits in a technology-transition phase as rapid DNA platforms and AI evidence authentication displace legacy batch-processing workflows and manual analyst review protocols.
For Market Incumbents: Deploy accreditation portfolio expansion as the primary defensive lever against margin compression from point-of-need instrumentation. Consolidate ISO 17025 credentials across multiple jurisdictions to capture FBI backlog reduction contracts and Crown Prosecution Service procurement simultaneously. Backward integration into rapid DNA platform distribution secures channel control against instrumentation conglomerates. For New Entrants and Emerging Players: EU AI Act risk-classification requirements in Germany open a window for specialized compliance advisory services alongside automated forensic tool deployment. Target mobile testing unit provision for United States mass-casualty incident response protocols, where procurement unbundling creates white-space outside fixed-laboratory contracts. Pursue spot-market positioning for niche capabilities like isotope analysis or advanced toxicology screening. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional accredited laboratory networks in the United Kingdom facing Forensic Science Regulator enforcement pressures. Long-term viability hinges on diversification beyond criminal casework into insurance engineering forensics with lower accreditation barriers. Watch FBI CODIS expansion funding appropriations as inflection indicator for federal contract volume direction.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Portfolio Expansion | Multi-jurisdictional ISO 17025 credentials unlock FBI and Crown Prosecution Service contracts simultaneously. |
| Rapid DNA Platform Integration | Field-deployable instrumentation compresses analytical timelines from weeks to hours at booking stations. |
| AI Evidence Authentication Development | Machine learning tools for image verification address EU AI Act high-risk categorization requirements. |
| Insurance Engineering Forensics Entry | Property and casualty claims investigation offers higher margins with reduced accreditation overhead. |
| Mobile Testing Unit Deployment | Deployable capabilities bypass fixed-laboratory bottlenecks for mass-casualty incident response protocols. |
Research Methodology
Document review covered FBI procurement databases, EU judicial cooperation frameworks, and DAkkS accreditation registries, complemented by interviews with laboratory directors, forensic science regulators, law enforcement procurement officers, and insurance claims executives. Secondary validation drew from ISO 17025 audit reports, federal budget appropriations documentation, and scientific instrumentation trade publications. Bottom-up service-type volume estimates and top-down market sizing triangulated across primary and secondary sources.
Historical capacity utilization patterns were cross-referenced against expert panel inputs on accreditation timeline constraints and instrumentation replacement cycles. Segmentation modeling spanned service type, application context, end-user category, and delivery model dimensions across the projection horizon. CAGRs derived from evidence processing contract award trajectories and rapid DNA platform adoption curves in United States municipal police departments.
The model assumes a particular technology adoption path for rapid DNA instrumentation; alternative pathways for point-of-need molecular analysis would alter the outlook for centralized laboratory throughput. Forecasts reflect assumptions regarding federal backlog reduction funding continuity and EU AI Act implementation timing. A small set of named triggers—FBI CODIS appropriation levels, Forensic Science Regulator enforcement actions, and probabilistic genotyping admissibility rulings—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
Biological Indicator Incubators Market
Testing Services
Fecal Occult Testing Market
Testing Services
Self-Testing Market
Testing Services
Trichomonas Rapid Testing Market
Testing Services
Blood Sugar Tester Market
Testing Services
Creatinine Testing Market
Testing Services
Pancreatic Elastase Testing Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
Service Laboratory Market
Testing Services
Pancreatic Stone Protein Testing Market
Testing Services
Global Extractables and Leachables Testing Services Market
Testing Services
Bimetallic Thermometer Market
Testing Services
Global Metabolic Testing Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Toxicity Testing Outsourcing Market