
 Latin America Melanoma Diagnostics and Therapeutics Market | 2026-2036
Latin America Melanoma Diagnostics and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Melanoma Diagnostics and Therapeutics Market Foresight
Brazilian molecular diagnostics capacity is shifting toward centralized reference laboratories in São Paulo and Minas Gerais. Merck & Co., Inc. leverages its checkpoint inhibitor portfolio to anchor premium positioning in academic medical centers. Roche dominates automated immunohistochemistry platforms across public procurement channels. Novartis specializes in BRAF-targeted therapy combinations, competing directly with Bristol Myers Squibb's regional presence.
Melanoma diagnostics and therapeutics encompass tissue-based pathology confirmation, molecular profiling of driver mutations, and systemic treatment modalities including immune checkpoint blockade and targeted small-molecule inhibition. Immunohistochemistry staining protocols detect S100, HMB-45, and Melan-A expression patterns essential for definitive diagnosis. Immunotherapy segments lead value generation through PD-1 inhibitor utilization, while next-generation sequencing applications grow fastest as companion diagnostic requirements expand. Diagnostic laboratories capture margin pools through bundled molecular testing services, whereas oral targeted therapy delivery modes gain traction in ambulatory settings.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce varying biologic licensing standards that fragment product approval timelines across the region. Brazil's ANVISA alignment with FDA oncology review standards accelerates certain pathway access, while Argentina's ANMAT maintains distinct stability testing requirements. Stakeholders must monitor regulatory convergence initiatives under MERCOSUR pharmaceutical harmonization to anticipate centralized manufacturing qualification demands.
Market Dynamics
ANVISA's oncology fast-track pathways are compressing registration timelines for molecular diagnostics, concentrating investment in São Paulo's reference laboratory infrastructure while fragmenting approval standards across MERCOSUR members.
Growth Catalysts
- Companion diagnostic mandates:Brazil's ANVISA alignment with FDA oncology review standards accelerates PD-1 inhibitor access. Academic medical centers in São Paulo and Rio de Janeiro now require molecular profiling prior to immunotherapy initiation.
- Private insurance penetration:Brazil's supplementary health sector covers next-generation sequencing for metastatic cases. Minas Gerais and Paraná corridors report expanded molecular testing capacity.
- Centralized laboratory networks:Hospital-based oncology departments in Mexico's CDMX-Guadalajara-Monterrey triangle consolidate send-out testing to COFEPRIS-accredited reference sites.
Market Restraints
- Reagent import dependency:Argentina's ANMAT stability testing requirements extend lead times for immunohistochemistry antibodies. Brazilian distributors face foreign exchange volatility on molecular assay kits.
- Specialized pathologist scarcity:Colombia's INVIMA-licensed laboratories compete for dermatopathology expertise. Regional training programs produce insufficient melanoma-specific diagnosticians.
- Public procurement fragmentation:Mexico's federal-state health system splits purchasing authority across COFEPRIS jurisdictions. Pricing disparities emerge between IMSS facilities and state hospitals.
Strategic Opportunities
- Peru's underpenetrated coastal corridor:Lima's oncology centers lack automated immunohistochemistry platforms. DIGEMID regulatory pathways remain less congested than ANVISA or COFEPRIS queues.
- Liquid biopsy integration:Circulating tumor DNA monitoring converges with radiology workflows for treatment response assessment. Chile's ISP framework permits earlier adoption than neighboring jurisdictions.
- Ambulatory oral therapy delivery:BRAF inhibitor dispensing shifts from infusion centers to retail pharmacy networks. Brazil's São Paulo state enables take-home protocols for stable patients.
Industry Challenges
- Molecular tumor board coordination:Multidisciplinary case review requires synchronous pathologist, oncologist, and bioinformatics specialist availability. Brazilian academic centers report scheduling friction.
- Legacy immunohistochemistry platform interoperability:Automated staining systems from different manufacturers generate incompatible digital pathology files. Mexican reference laboratories face integration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Melanoma Diagnostics and Therapeutics Market |
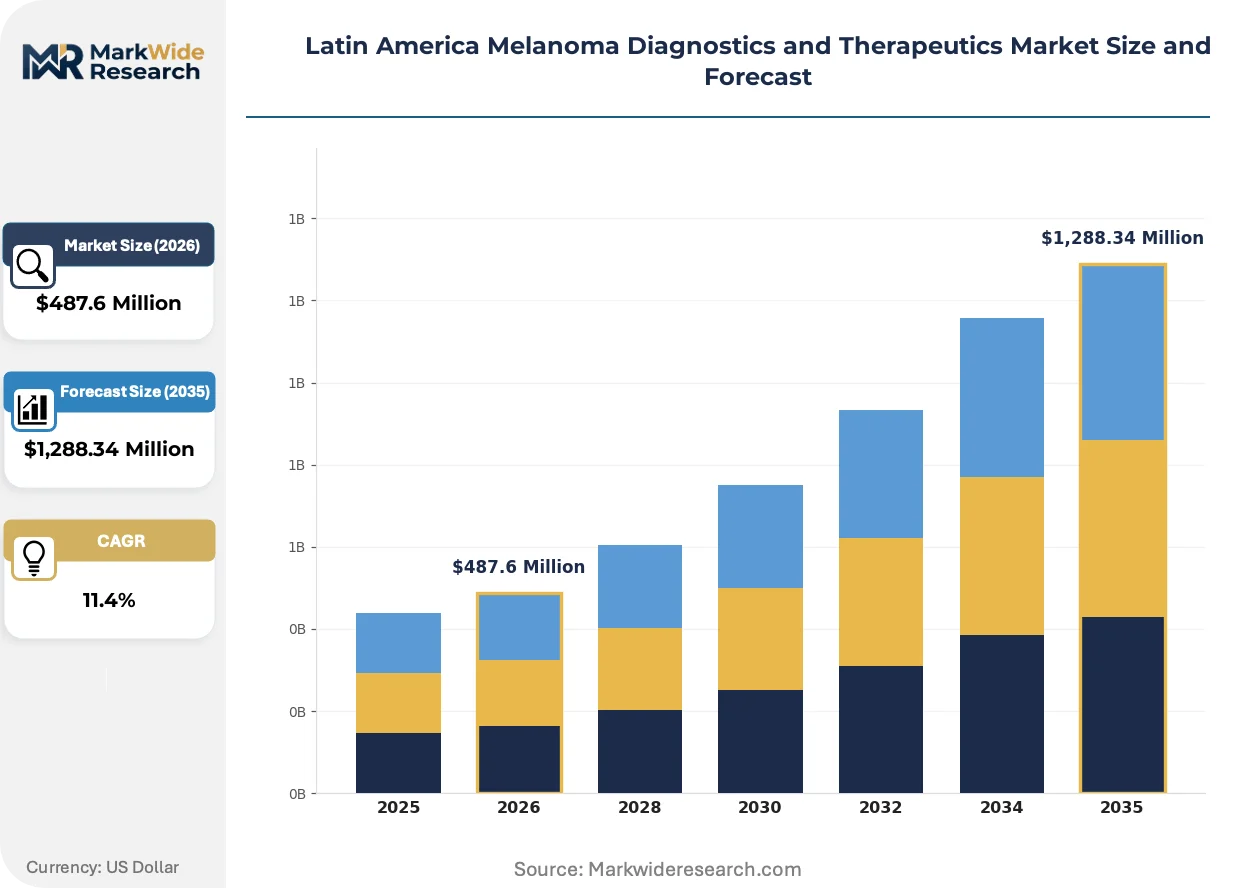
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy, Immunotherapy, Chemotherapy, Targeted Therapy Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Research Institutions Technology: Next-Generation Sequencing, PCR, Immunohistochemistry, Protein Biomarker Analysis |
| Companies Covered | GlaxoSmithKline, Merck & Co., Inc., Abbott Laboratories, bioMerieux SA, Pfizer, Inc., Amgen Inc., Novartis AG, DermTech, Roche, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Melanoma Diagnostics and Therapeutics Market Shifts & Advancements
Next-generation sequencing platforms are compressing diagnostic timelines while reshaping competitive positioning among reference laboratories. Three developments merit particular attention.
Comprehensive genomic profiling is overtaking single-gene hotspot testing as the standard of care for advanced melanoma. São Paulo's private oncology networks now mandate BRAF, NRAS, and c-KIT co-testing prior to systemic therapy selection. This technology is overtaking sequential testing workflows, collapsing the interval between biopsy and treatment initiation from weeks to days.
ANVISA's 2023 biologics licensing convergence with FDA standards eliminates redundant stability studies for oncology products. Brazilian manufacturers gain accelerated access to checkpoint inhibitor formulations previously restricted to import channels. Multinational sponsors now prioritize São Paulo-Rio corridor sites for regional launch sequencing.
Hospital procurement committees in Mexico's public sector consolidate molecular testing contracts under three-year framework agreements. CDMX's Instituto Nacional de Cancerología bundles immunohistochemistry with next-generation sequencing services, displacing transactional per-test purchasing. This concentration is most visible in COFEPRIS-centralized jurisdictions where reference laboratory accreditation limits vendor pools.
Latin America Melanoma Diagnostics and Therapeutics Market Segmentation
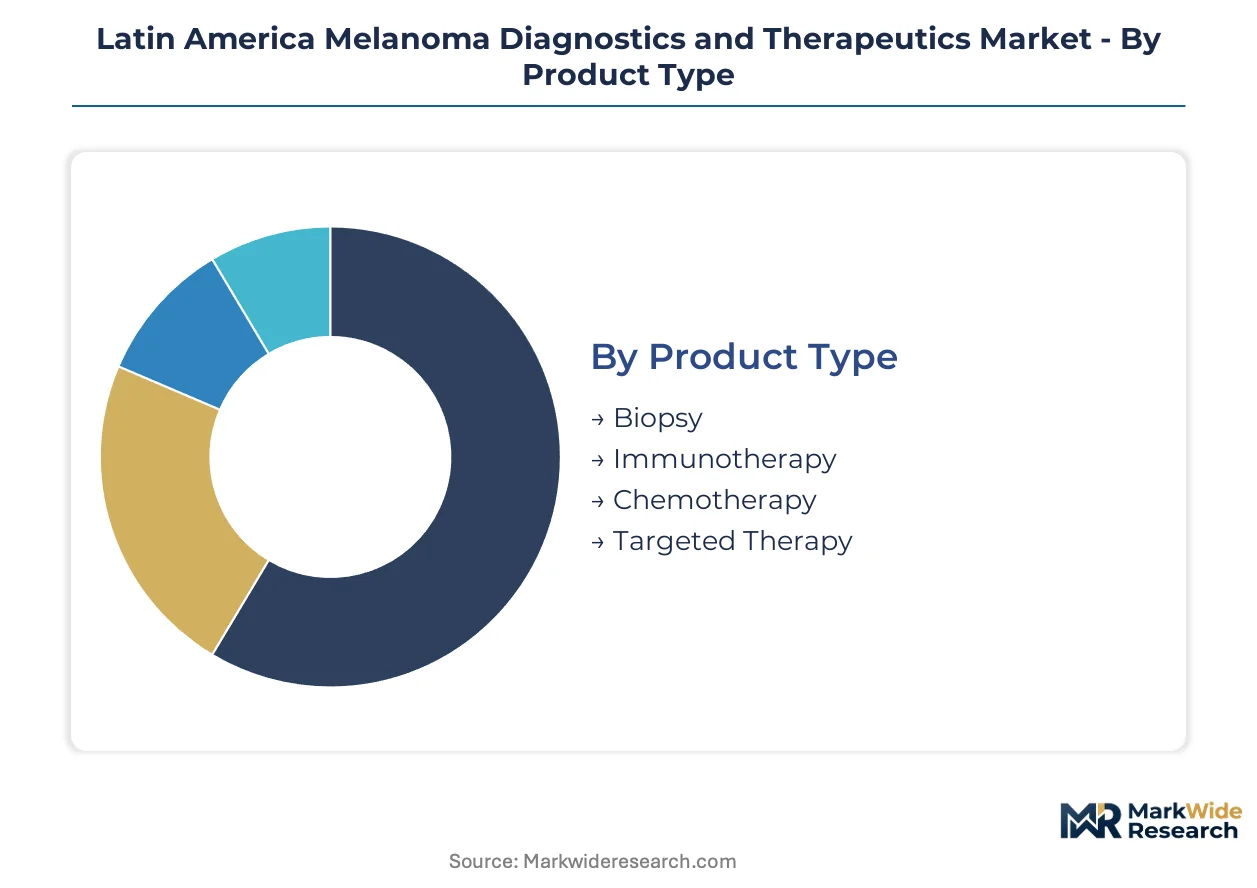
Melanoma care pathways in Latin America fragment across diagnostic confirmation, molecular stratification, and treatment modality selection. Each segmentation axis captures distinct procurement behaviors, reimbursement thresholds, and infrastructure requirements that shape vendor go-to-market strategies.
Product Type:
Buyer sophistication and reimbursement depth separate institutional purchasers across therapeutic categories.
- Biopsy:Tissue acquisition through excisional, incisional, or punch techniques provides definitive histopathological diagnosis. São Paulo's private oncology networks and Mexico City's Instituto Nacional de Cancerología drive demand for image-guided core needle protocols that preserve tissue for molecular downstream testing.
- Immunotherapy:PD-1 and CTLA-4 checkpoint inhibitors command premium positioning through ANVISA fast-track pathways and Brazil's supplementary health coverage. Academic medical centers in Rio de Janeiro and Minas Gais concentrate infusion capacity for nivolumab and pembrolizumab regimens, with companion diagnostic mandates tightening eligibility criteria.
- Chemotherapy:Dacarbazine and temozolomide protocols persist in public sector formularies where immunotherapy access remains restricted. Argentina's ANMAT-licensed facilities maintain dacarbazine stockpiles for BRAF-wildtype cases.
- Targeted Therapy:BRAF and MEK inhibitor combinations address driver-mutation populations. Colombia's INVIMA registration timelines lag ANVISA, concentrating early adoption in Brazilian and Mexican markets.
Volume sits with Immunotherapy; growth tilts toward Targeted Therapy.
Delivery Mode:
Site-of-care economics and patient mobility constraints determine route selection across ambulatory and institutional settings.
- Intravenous:Infusion center dependency concentrates in hospital-based oncology departments with pharmacy compounding capabilities. Brazil's São Paulo-Rio corridor maintains the densest network of ANVISA-licensed infusion suites for checkpoint inhibitor administration.
- Oral:BRAF inhibitor take-home protocols expand through retail pharmacy networks. São Paulo state regulations enable stable patients to receive vemurafenib and dabrafenib outside infusion centers, reducing chair time costs for private insurers.
- Subcutaneous:Limited melanoma applications restrict penetration to investigational settings and combination trials. Chile's ISP framework permits earlier subcutaneous formulation evaluation than neighboring jurisdictions.
- Topical:Imiquimod and other surface agents address superficial lentigo maligna in dermatology clinics. Peru's coastal corridor relies on topical modalities where surgical infrastructure remains underdeveloped.
Intravenous dominates current throughput; oral formulations are climbing the fastest as ambulatory protocols expand.
End User:
Capital intensity and case volume thresholds segment institutional purchasers across public and private reimbursement environments.
- Hospitals:Comprehensive oncology departments integrate surgical, medical, and radiation disciplines under single facility licenses. Brazil's hospital-based networks anchor molecular diagnostic adoption through bundled service contracts.
- Specialty Clinics:Dermatology and surgical oncology practices concentrate excisional biopsy capacity. Mexico's CDMX-Guadalajara-Monterrey triangle hosts COFEPRIS-accredited specialty centers with direct referral pathways to academic medical centers.
- Diagnostic Laboratories:Centralized reference sites capture send-out testing from dispersed clinical practices. São Paulo and Minas Gerais laboratories consolidate immunohistochemistry and next-generation sequencing volumes.
- Research Institutions:Academic medical centers in São Paulo and Rio de Janeiro anchor clinical trial enrollment for novel immunotherapy combinations. ANVISA's alignment with FDA standards accelerates protocol activation timelines.
Hospitals retain the largest case volumes; Diagnostic Laboratories gain share fastest as send-out testing centralizes.
Technology:
Capital expenditure requirements and reimbursement coding sophistication separate technology adopters across public and private payment systems.
- Next-Generation Sequencing:Comprehensive genomic profiling collapses diagnostic timelines from weeks to days through simultaneous BRAF, NRAS, and c-KIT assessment. São Paulo's private networks now mandate NGS prior to systemic therapy initiation, with ANVISA companion diagnostic pathways accelerating platform adoption.
- PCR:Single-gene hotspot testing persists in resource-constrained settings where NGS infrastructure remains unaffordable. Argentine laboratories facing ANMAT reagent import delays maintain PCR workflows for BRAF V600E detection.
- Immunohistochemistry:Automated staining platforms from Roche dominate public procurement channels across Brazil and Mexico. S100, HMB-45, and Melan-A antibody panels provide definitive diagnosis in COFEPRIS-accredited reference sites.
- Protein Biomarker Analysis:Emerging multiplex platforms address immune microenvironment characterization. Chile's ISP regulatory flexibility permits earlier protein biomarker assay validation than ANVISA or COFEPRIS jurisdictions.
Immunohistochemistry anchors current test volumes; Next-Generation Sequencing shows the steepest expansion trajectory as companion diagnostic mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's biomedical corridor anchors molecular diagnostic capacity across the southern cone, while regulatory fragmentation between ANVISA, COFEPRIS, and INVIMA shapes cross-border product flows. Brazil's fast-track oncology pathways concentrate investment in the southeast, with Mexico and Colombia building complementary testing networks.
Brazil
ANVISA's 2023 biologics licensing convergence with FDA standards eliminates redundant stability studies for checkpoint inhibitors. São Paulo and Minas Gerais laboratories consolidate immunohistochemistry and next-generation sequencing volumes through bundled service contracts. The São Paulo-Rio de Janeiro corridor maintains Brazil's densest network of infusion suites for immunotherapy administration.
Mexico
COFEPRIS-accredited reference sites in Mexico City, Guadalajara, and Monterrey capture send-out testing from dispersed clinical practices. Federal-state health system fragmentation splits purchasing authority across jurisdictions, creating pricing disparities between IMSS facilities and state hospitals. CDMX's Instituto Nacional de Cancerología bundles molecular diagnostics under three-year framework agreements.
Argentina
ANMAT maintains distinct stability testing requirements that extend lead times for immunohistochemistry reagents. Buenos Aires academic medical centers anchor clinical trial enrollment for novel combination therapies despite foreign exchange volatility on molecular assay imports. The country's public sector formularies retain dacarbazine stockpiles where immunotherapy access remains restricted.
Colombia
INVIMA-licensed laboratories in Bogotá compete for scarce dermatopathology expertise as regional training programs produce insufficient melanoma-specific diagnosticians. Medellín and Cali oncology centers lack automated immunohistochemistry platforms found in Brazilian and Mexican reference sites. Private insurance penetration in major metros funds next-generation sequencing for metastatic cases.
Chile
ISP regulatory flexibility permits earlier adoption of circulating tumor DNA monitoring and protein biomarker assays than neighboring ANVISA or COFEPRIS jurisdictions. Santiago's oncology networks integrate liquid biopsy workflows with radiology departments for treatment response assessment. The country's smaller market size concentrates specialized expertise in capital-based academic centers.
Latin America Melanoma Diagnostics and Therapeutics Market Competitive Landscape
Global majors compete with regional champions across diagnostic platform installation and therapeutic distribution networks. The vendor base organizes around three tiers: multinational pharmaceutical conglomerates with checkpoint inhibitor portfolios, diversified diagnostics manufacturers with automated staining platforms, and emerging molecular testing specialists. Consolidation pressures favor players with integrated diagnostic-therapeutic offerings. Strategic moves center on reference laboratory partnerships and companion diagnostic co-development agreements.
Among Swiss-based pharmaceutical conglomerates, Roche and Novartis occupy positions spanning automated immunohistochemistry platforms and BRAF-targeted therapy combinations. Merck & Co., Inc. anchors the premium immunotherapy tier through academic medical center relationships. These three exemplify the integrated diagnostic-therapeutic archetype that regulatory convergence increasingly favors across ANVISA and COFEPRIS jurisdictions.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Merck & Co., Inc. |
| Abbott Laboratories |
| bioMerieux SA |
| Pfizer, Inc. |
| Amgen Inc. |
| Novartis AG |
| DermTech |
| Roche |
| Others |
Supply & Pricing Matrix
Reagent import costs for immunohistochemistry antibodies and molecular assay kits flow through foreign exchange volatility into tiered service pricing across Brazilian reference laboratories, concentrating margin pressure on mid-tier diagnostic providers while premium academic centers absorb volatility through bundled oncology contracts.
Pricing Analysis
Service bundling separates comprehensive genomic profiling packages from unbundled per-test transactional models across São Paulo's private oncology networks. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales pathology consultation depth. Cost compression in economy-tier PCR testing is intensifying because Argentine ANMAT import delays force laboratories to maintain redundant reagent inventories. Public sector hospitals exhibit highest price sensitivity due to fragmented procurement authority, while supplementary health-funded academic centers demonstrate lowest sensitivity to per-test pricing.
Supply Chain Analysis
Monoclonal antibody production for diagnostic staining rests on United States, Germany, and Chinese specialty chemical manufacturers, with Brazilian distributors serving as regional consolidation points. Automated platform hardware draws from Swiss and Japanese precision engineering suppliers, while assay kit components hinge on Singaporean and South Korean biotech manufacturing. Single-source vulnerability concentrates in thermocycler reagent supply chains transiting through Miami logistics hubs. Distribution runs through COFEPRIS-accredited reference laboratories in Mexico's CDMX-Guadalajara-Monterrey triangle and ANVISA-licensed São Paulo-Minas Gerais networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated diagnostic-therapeutic capabilities, with regulatory convergence under MERCOSUR pharmaceutical harmonization pressuring standalone testing providers toward acquisition or partnership.
For Market Incumbents: Acquire liquid biopsy platform capabilities to anchor circulating tumor DNA monitoring services ahead of Chilean ISP adoption patterns spreading northward. Consolidate send-out testing contracts through three-year framework agreements with Mexico's Instituto Nacional de Cancerología, displacing transactional competitors. Deepen backward integration into immunohistochemistry reagent manufacturing to offset Argentine ANMAT import volatility and capture margin pools currently flowing to European antibody suppliers. For New Entrants and Emerging Players: Reference laboratory partnerships in Peru's Lima coastal corridor offer lowest competitive density among major Latin American metro oncology centers, with DIGEMID regulatory queues running shorter than ANVISA or COFEPRIS pathways. Target automated immunohistochemistry platform installation in Colombian Bogotá and Medellín centers lacking Roche-dominated infrastructure found in Brazilian and Mexican markets. Pursue companion diagnostic co-development agreements with BRAF-targeted therapy sponsors seeking accelerated ANVISA pathway access. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap molecular testing specialists in Argentina facing foreign exchange-driven reagent cost pressures but possessing ANMAT-licensed facility assets and Buenos Aires academic medical center relationships. Long-term viability centers on diagnostic-therapeutic integration capabilities as ANVISA-FDA convergence eliminates standalone testing margins. Watch MERCOSUR pharmaceutical harmonization implementation timelines as the inflection signal for centralized manufacturing qualification demands reshaping competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | ANVISA fast-track alignment with FDA standards accelerates PD-1 inhibitor market entry timelines. |
| Reference Laboratory Acquisition | São Paulo-Minas Gerais network consolidation captures send-out testing volumes from dispersed clinical practices. |
| Liquid Biopsy Platform Integration | Chilean ISP regulatory flexibility permits earlier circulating tumor DNA adoption than neighboring jurisdictions. |
| Automated Immunohistochemistry Installation | COFEPRIS-accredited sites in Mexico's CDMX-Guadalajara-Monterrey triangle displace manual staining workflows. |
| Ambulatory Oral Therapy Distribution | São Paulo state take-home protocols for BRAF inhibitors reduce infusion center chair time costs. |
Research Methodology
Independent corroboration across ANVISA registration filings, COFEPRIS accreditation databases, and hospital procurement records underwrites the qualitative findings presented herein. Primary interviews with molecular pathology laboratory directors, oncology formulary managers, and diagnostic platform procurement officers combined with secondary validation from ClinicalTrials.gov protocol disclosures, MERCOSUR regulatory harmonization documents, and supplementary health plan coverage policies. Bottom-up testing volume estimates from São Paulo, Rio de Janeiro, and Mexico City reference sites triangulate against top-down pharmaceutical distribution data.
Comparable-period anchoring against historical immunohistochemistry platform installation rates and checkpoint inhibitor patient access program enrollment established the forecast baseline. The analytical framework segments across technology platform, delivery mode, end-user institution type, and regional regulatory cluster throughout the projection horizon. CAGRs derive from weighted average of segment-specific growth trajectories, with companion diagnostic mandate implementation timelines and private insurance reimbursement expansion serving as key melanoma-specific forecast inputs.
Caveats apply where ANVISA biologics licensing convergence delays, Argentine foreign exchange volatility, or Colombian dermatopathologist training pipeline shortfalls could materially shift the outlook. Forecasts reflect assumptions regarding regulatory harmonization progress and reimbursement policy stability. A small set of named triggers—MERCOSUR centralized manufacturing rules, liquid biopsy ISP adoption spillover, and public procurement consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Pediatric Cardiac Tumor Diagnostics Market
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Clinical Trial Kits Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Kidney Function Tests Market
Clinical Diagnostics
Food Allergy Diagnosis and Treatment Market
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
Global Minimal Residual Disease Market
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market