
 Laboratory Fume Hoods Market | 2026-2036
Laboratory Fume Hoods Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Fume Hoods Market Outlook
ASHRAE 110 certification tier is rotating toward the center of procurement decisions for new laboratory builds. NuAire Laboratory Equipment leverages its domestic manufacturing footprint to compete on lead times for certified installations. Labconco anchors the premium segment with deep specialization in custom containment solutions for nuclear and biological applications. Thermo Fisher Scientific extends its channel control through integrated service contracts that bundle hood maintenance with broader laboratory asset management.
Laboratory fume hoods are ventilated enclosures engineered to capture and exhaust hazardous vapors, gases, and particulates through specified face velocity parameters typically ranging from 80 to 100 feet per minute, with primary purpose of protecting personnel and maintaining environmental integrity in controlled research settings. Ductless fume hoods represent a structurally expanding category as facilities seek to avoid building infrastructure costs, while variable air volume hoods command margin concentration through energy recovery value propositions that reduce HVAC operational loads. Walk-in fume hoods occupy a mature niche serving industrial-scale chemical processing with stable replacement cycles but limited new-installation growth.
OSHA laboratory safety standards and EPA emissions regulations in the United States shape mandatory containment performance thresholds, while REACH chemical registration requirements in Europe drive hood specification upgrades for substances of very high concern. ASHRAE and ISO 14644 cleanroom classifications increasingly intersect with fume hood design protocols as multi-use laboratory spaces proliferate. Stakeholders must monitor how evolving energy codes in California and Massachusetts integrate fume hood airflow into whole-building carbon accounting frameworks.
Market Dynamics
The laboratory fume hoods market is restructuring around ASHRAE 110 certification tiers as the primary procurement filter, with energy recovery specifications and ductless alternatives compressing traditional specification hierarchies across pharmaceutical and academic installations.
Growth Catalysts
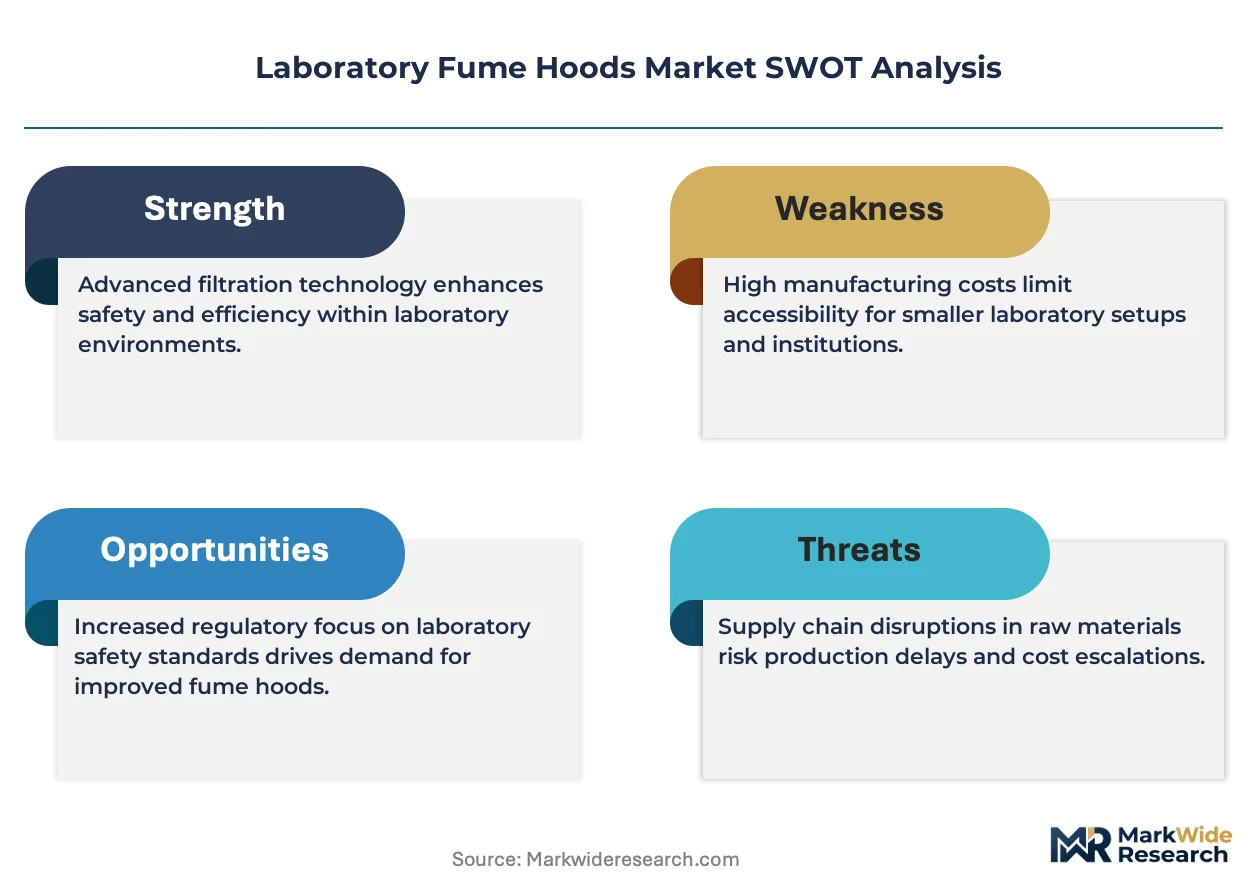
- Biologics manufacturing expansion:Pharmaceutical laboratories in Germany and the United States are scaling containment infrastructure to support monoclonal antibody and cell therapy production lines.
- EPA emissions mandates:Tightening OSHA laboratory safety standards and EPA air quality regulations are forcing replacement cycles for pre-2015 installations.
- University hospital modernization:Chemical research clusters in Heidelberg, Boston, and Singapore are consolidating dispersed laboratory assets into centralized facilities with upgraded ventilation systems.
Market Restraints
- Stainless steel and HEPA filter cost volatility:Input material prices for 316-grade stainless steel and certified filtration media fluctuate with energy-intensive European smelter output.
- Certified installer concentration:ASHRAE 110 testing and commissioning capacity concentrates in North American and Western European metropolitan corridors, extending project timelines elsewhere.
- Ductless hood performance ceilings:Carbon and HEPA filtration saturation limits restrict ductless systems to lower-toxicity applications, capping addressable procedure range.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO regulatory alignment with ICH guidelines is driving contract research organizations in Hyderabad and Bangalore to upgrade analytical chemistry infrastructure.
- Variable air volume retrofits:Integration of VAV controls with building management systems offers energy recovery value propositions for existing laboratory real estate.
- Multi-use cleanroom convergence:ISO 14644-1 classifications intersecting with fume hood specifications create hybrid containment demand in cell and gene therapy facilities.
Industry Challenges
- Commissioning engineer scarcity:Qualified airflow testing technicians for ASHRAE 110-2016 tracer gas protocols remain concentrated in legacy manufacturing regions.
- Legacy building HVAC incompatibility:Variable air volume hood deployment requires static pressure recalibration in aging central ventilation plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Fume Hoods Market |
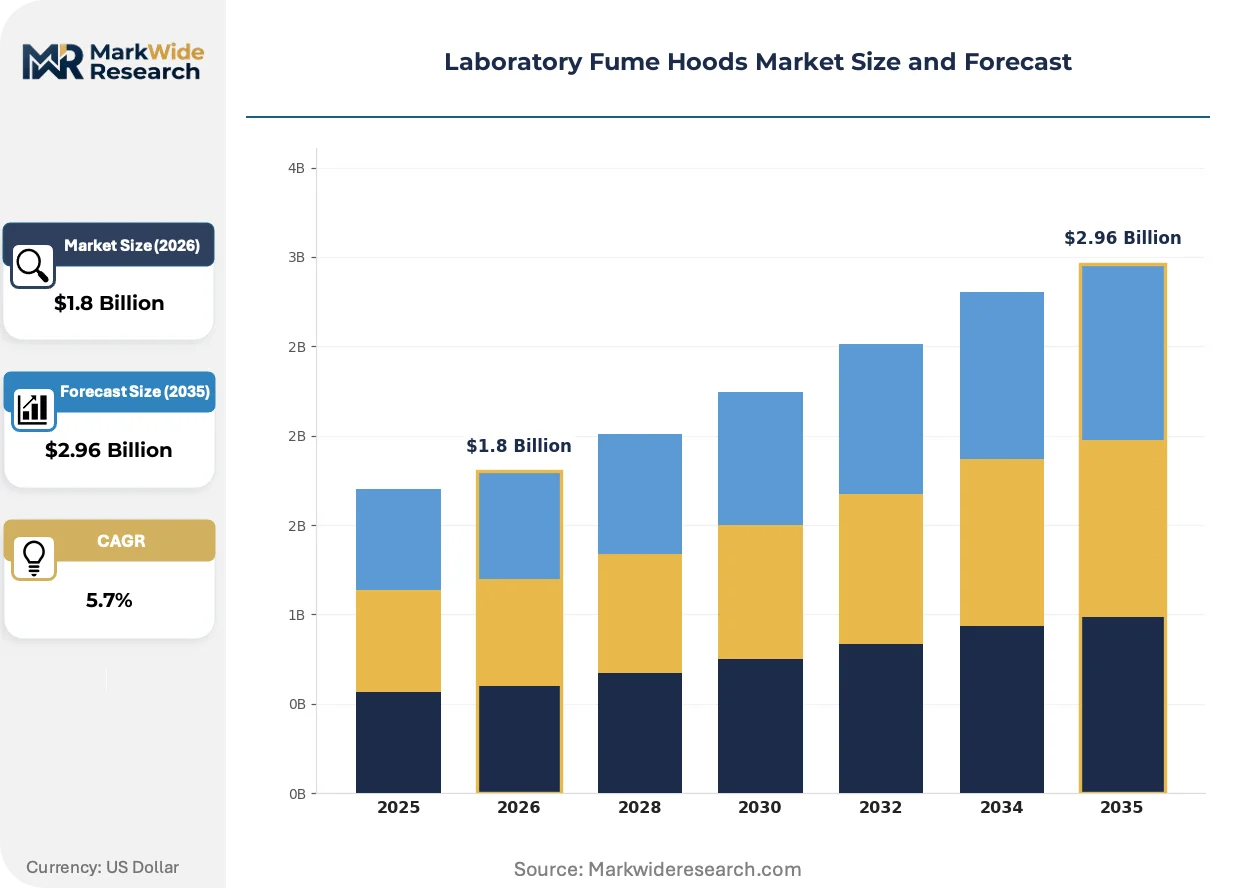
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Fume Hoods, Vertical Fume Hoods, Ductless Fume Hoods, Walk-in Fume Hoods End User: Pharmaceuticals, Educational Institutions, Research Laboratories, Chemical Manufacturing Technology: Smart Fume Hoods, Conventional Fume Hoods, Energy-Efficient Hoods, Variable Air Volume Hoods Installation Type: Bespoke Installations, Standard Configurations, Mobile Options, Bench-mounted Units |
| Companies Covered | NuAire Laboratory Equipment, Tecniplast Group, Labconco, Flow Sciences, MBRAUN, Thermo Fisher Scientific, The Baker Company, Biobase, ESCO Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Fume Hoods Market Strategic Shifts
Active sensor networks and predictive maintenance protocols are displacing scheduled service models, while regulatory carbon accounting integrates fume hood airflow into whole-building energy performance frameworks.
Variable air volume control technology is bifurcating the installed base between legacy constant-volume hoods and intelligent demand-controlled ventilation. Research universities in California and Massachusetts are mandating VAV specifications for new construction. The technology is compressing operational energy intensity by modulating face velocity against sash position, though upfront controls integration extends capital deployment timelines.
REACH chemical registration requirements in Europe are elevating containment specifications for substances of very high concern across pharmaceutical quality control laboratories. ECHA substance evaluation processes now trigger hood replacement cycles independent of equipment age. German chemical research clusters are responding with centralized procurement frameworks that bundle ASHRAE 110 certification with ongoing compliance monitoring.
Service contract unbundling is fragmenting the traditional equipment-plus-maintenance bundle. Academic medical centers are separating hood acquisition from third-party certification and recertification services. This pattern is most visible in United States research hospital networks, where facilities management departments are consolidating vendor relationships across multiple laboratory asset categories.
Laboratory Fume Hoods Market Segmentation
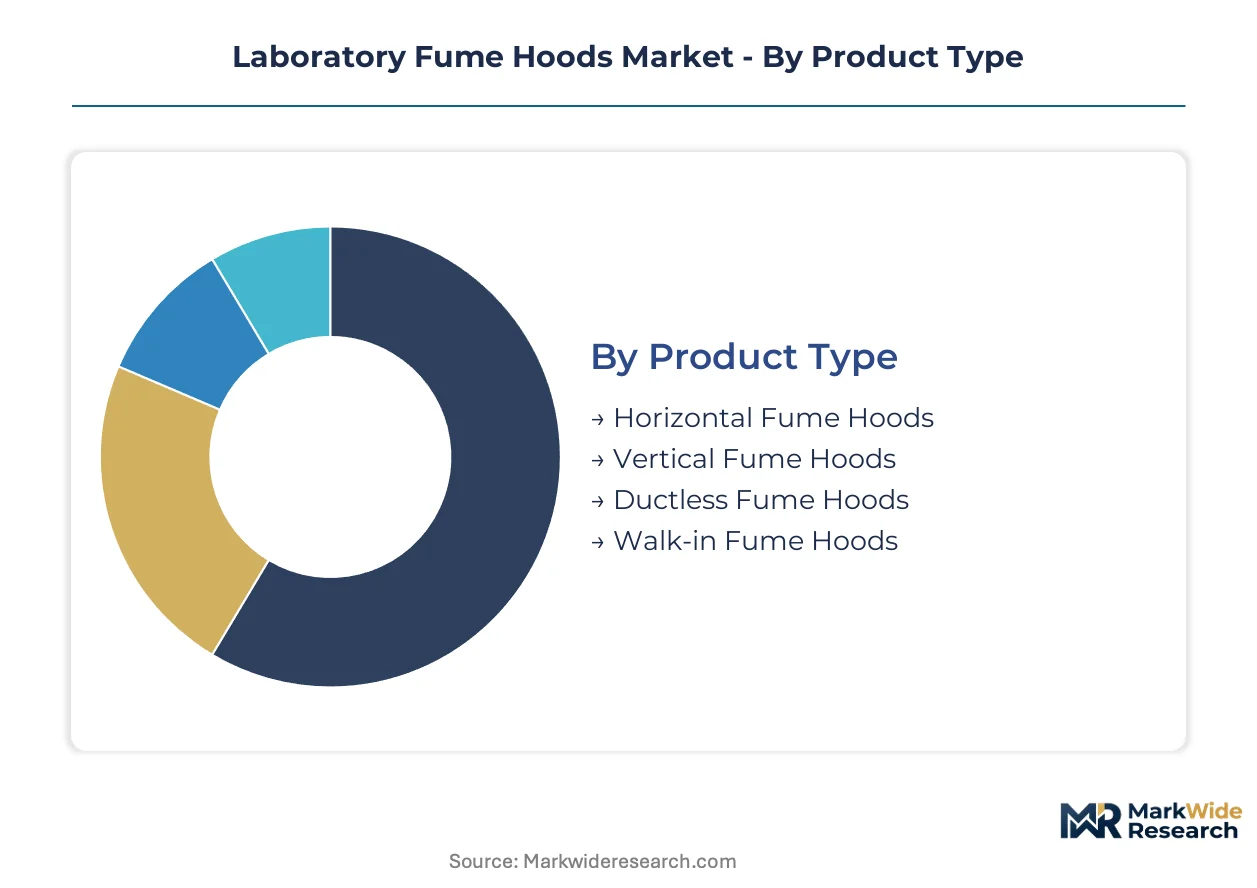
Laboratory fume hood segmentation reveals how procurement decisions split between energy performance mandates and application-specific containment requirements. Distinct margin pools form around certification tiers, installation complexity, and ongoing service attachment rates.
Product Type:
Margin concentration pools in systems that reduce building infrastructure costs and energy recovery specifications that lower HVAC operational loads.
- Horizontal Fume Hoods:These enclosures draw air horizontally across the work surface through rear-wall baffles, optimizing for procedures involving large equipment footprints. Demand concentrates in university hospital networks across Germany where chemical research clusters are modernizing centralized facilities, though replacement cycles remain stable rather than expansionary.
- Vertical Fume Hoods:Airflow descends from top-mounted filters through sash openings, capturing vapors closer to the source. Pharmaceutical laboratories in the United States are specifying vertical configurations for biologics manufacturing lines, driven by OSHA containment mandates for monoclonal antibody production.
- Ductless Fume Hoods:Self-contained carbon and HEPA filtration eliminates external ducting requirements. Facilities in Massachusetts and California are deploying ductless units to avoid building infrastructure costs in leased laboratory real estate.
- Walk-in Fume Hoods:Floor-to-ceiling enclosures accommodate industrial-scale chemical processing equipment. Chemical manufacturing sites in Heidelberg maintain stable replacement cycles for these mature systems with limited new-installation growth.
The dominant share belongs to vertical fume hoods, while ductless alternatives are closing the gap fastest.
End User:
Procurement authority and specification sophistication vary sharply across customer types, with pharmaceutical buyers commanding premium pricing through integrated service contracts.
- Pharmaceuticals:Quality control and manufacturing operations demand ASHRAE 110-certified containment with documented tracer gas testing. CDSCO regulatory alignment in India is driving contract research organizations in Hyderabad to upgrade analytical chemistry infrastructure with certified installations.
- Educational Institutions:University laboratories balance budget constraints against liability exposure in undergraduate teaching environments. Research universities in Singapore are consolidating dispersed assets into centralized facilities with upgraded ventilation systems.
- Research Laboratories:Academic medical centers and government facilities prioritize flexibility for multi-use protocols. These buyers are increasingly unbundling equipment acquisition from third-party certification services.
- Chemical Manufacturing:Industrial-scale production requires walk-in configurations with stable replacement cycles tied to equipment depreciation schedules rather than regulatory triggers.
Pharmaceuticals command the highest specification tier, while educational institutions are expanding volume fastest through modernization programs.
Technology:
Intelligence integration and energy modulation capabilities are bifurcating the installed base between legacy constant-volume systems and demand-controlled ventilation.
- Smart Fume Hoods:Active sensor networks enable predictive maintenance protocols and real-time airflow monitoring. Research hospitals in Boston are mandating smart specifications for new construction to integrate with building management systems.
- Conventional Fume Hoods:Fixed-face velocity systems without modulation capabilities dominate existing real estate. Pre-2015 installations face replacement pressure from tightening EPA emissions mandates.
- Energy-Efficient Hoods:Low-flow designs maintain containment at reduced face velocities through aerodynamic sash and baffle engineering. California energy codes are integrating hood airflow into whole-building carbon accounting frameworks.
- Variable Air Volume Hoods:Demand-controlled ventilation modulates exhaust rates against sash position, compressing operational energy intensity. VAV retrofits offer energy recovery value propositions for aging laboratory real estate in Massachusetts.
Conventional systems retain installed base dominance, while variable air volume technology is climbing the fastest through regulatory energy mandates.
Installation Type:
Project complexity and margin structure correlate directly with customization depth and commissioning requirements for ASHRAE 110 certification.
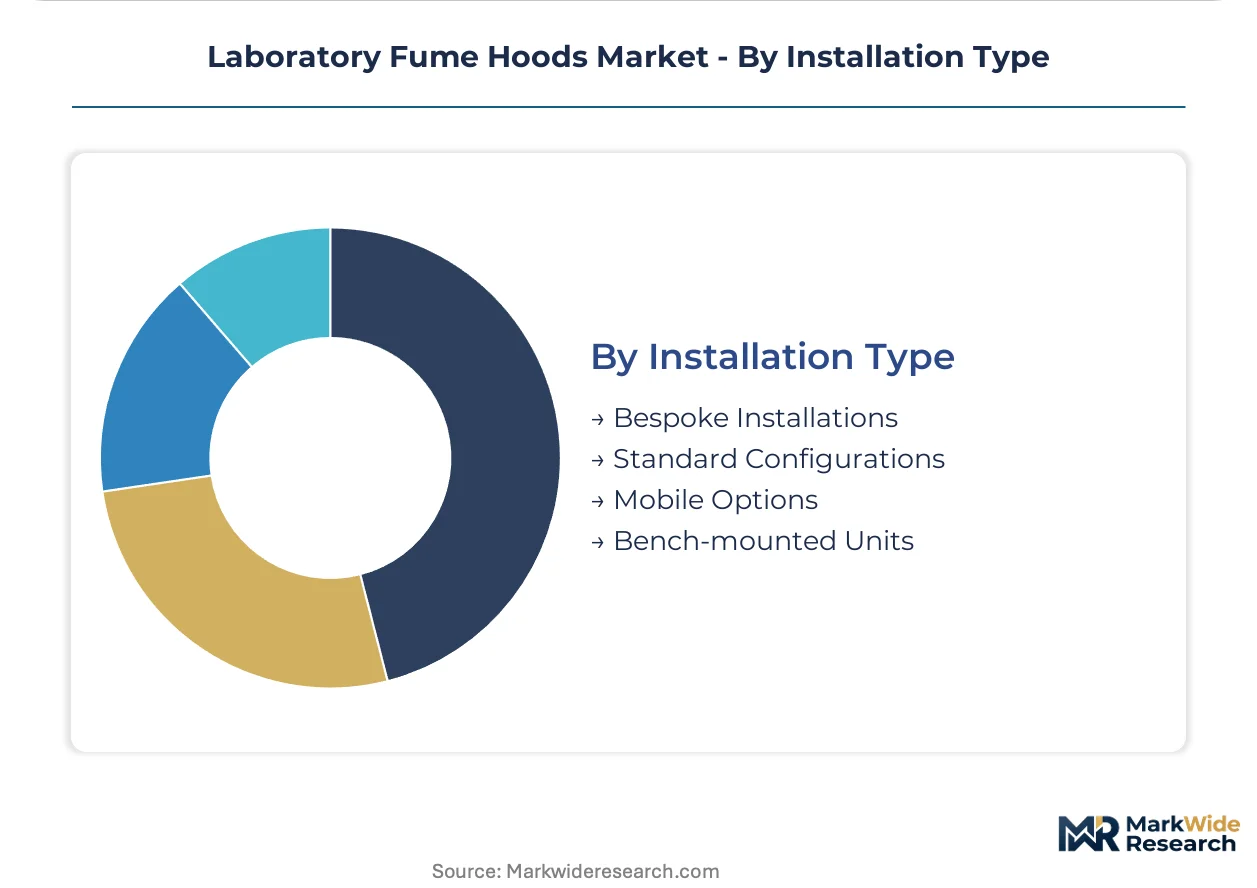
- Bespoke Installations:Custom-engineered containment solutions for nuclear and biological applications require specialized baffle design and materials specification. These projects concentrate in government and defense research facilities with extended capital deployment timelines.
- Standard Configurations:Catalog-specified units with predefined dimensions and airflow parameters serve routine laboratory applications. Standard offerings anchor procurement for educational institutions with predictable facility layouts.
- Mobile Options:Castor-mounted units enable reconfiguration of laboratory workflows without structural modification. Contract research organizations favor mobile deployments for project-based analytical chemistry operations.
- Bench-mounted Units:Compact enclosures integrate directly with existing laboratory furniture systems. These configurations dominate refurbishment projects where infrastructure constraints preclude floor-standing alternatives.
Standard configurations hold volume leadership, while bespoke installations capture margin concentration through engineering complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Educational institutions in India and Southeast Asia demonstrate the highest price elasticity, deferring replacement cycles until regulatory mandates force action, while pharmaceutical manufacturers in Germany and the United States absorb premium pricing for certified installations without volume contraction.
United States
Biologics manufacturing expansion in Massachusetts and California drives containment infrastructure procurement for monoclonal antibody production lines. EPA emissions mandates and OSHA laboratory safety standards force replacement cycles for pre-2015 installations. Research hospitals in Boston mandate smart fume hood specifications with building management system integration for new construction projects.
Germany
Chemical research clusters in Heidelberg and university hospital networks prioritize ASHRAE 110-certified containment with documented tracer gas testing. REACH chemical registration requirements and ECHA substance evaluation processes trigger hood replacement cycles independent of equipment age. Centralized procurement frameworks in Baden-Württemberg bundle certification with ongoing compliance monitoring services.
India
Contract research organizations in Hyderabad and Bangalore upgrade analytical chemistry infrastructure as CDSCO regulatory alignment with ICH guidelines accelerates. The national pharmaceutical regulator mandates containment upgrades for quality control laboratories serving export markets. Educational institutions in Maharashtra defer capital expenditure pending budget allocation cycles, compressing near-term volume.
Singapore
Research universities consolidate dispersed laboratory assets into centralized facilities with upgraded ventilation systems. The national biomedical research agency specifications intersect with ISO 14644-1 cleanroom classifications for cell and gene therapy facilities. Biopolis and one-north research clusters drive demand for variable air volume retrofits in existing laboratory real estate.
China
Pharmaceutical quality control laboratories in Shanghai and Suzhou face containment specification upgrades under evolving national pharmaceutical regulator standards. Dual carbon goals integrate fume hood airflow into whole-building energy performance frameworks for new construction. Yangtze River Delta chemical research institutes modernize infrastructure with energy-efficient low-flow designs.
Laboratory Fume Hoods Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with premium-tier specialists commanding margin concentration through engineering complexity while scale-oriented fabricators compete on lead times for standard configurations. The market structures around three tiers: domestic manufacturers with short delivery windows, multinational conglomerates with integrated service contracts, and niche specialists in custom containment solutions. Consolidation pressure concentrates among mid-scale regional fabricators lacking certification depth or channel breadth. Dominant competitive moves include geographic expansion into Indian pharmaceutical manufacturing corridors and technology licensing partnerships for variable air volume control systems.
Among laboratory equipment specialists, NuAire Laboratory Equipment and Labconco exemplify contrasting strategic positions within the premium tier, while Thermo Fisher Scientific anchors the integrated service contract segment. NuAire leverages its domestic manufacturing footprint to compete on lead times for certified installations. Labconco occupies a position centered on custom containment solutions for nuclear and biological applications. Thermo Fisher Scientific extends channel control through bundled hood maintenance and broader laboratory asset management contracts.
| Leading Market Players |
|---|
| NuAire Laboratory Equipment |
| Tecniplast Group |
| Labconco |
| Flow Sciences |
| MBRAUN |
| Thermo Fisher Scientific |
| The Baker Company |
| Biobase |
| ESCO Global |
| Others |
Value Chain & Pricing Dynamics
Project-based procurement contracts with ASHRAE 110 certification bundling lock in supply access for pharmaceutical buyers while anchoring price visibility across multi-year installation timelines in Germany and the United States.
Pricing Analysis
ASHRAE 110 certification dictates the pricing tier structure across the laboratory fume hoods market, separating premium certified installations from standard catalog offerings and economy-grade teaching laboratory units. Price differentiation hinges on tracer gas testing documentation and stainless steel grade specification, with 316-grade baffle systems commanding substantial premiums over 304-grade alternatives. Cost compression in the educational institution segment is intensifying because university procurement departments are unbundling equipment acquisition from third-party certification services. Pharmaceutical manufacturers exhibit the lowest price sensitivity, absorbing premium pricing for integrated service contracts without volume contraction, while educational institutions in India and Southeast Asia demonstrate the highest price elasticity.
Supply Chain Analysis
Germany and the United States anchor precision fabrication of certified containment systems, while China concentrates production of standard-configured bench-mounted units and carbon filtration media. Manufacturing draws from 316-grade stainless steel sourced through energy-intensive European smelters, certified HEPA filtration media, and variable air volume control modules. Single-source vulnerability concentrates in ASHRAE 110 testing and commissioning capacity, which remains tethered to North American and Western European metropolitan corridors. Distribution runs through laboratory equipment specialists and integrated service contractors serving pharmaceutical and academic research clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laboratory fume hoods market functions as a defensive-moat industry where regulatory entrenchment creates substantial switching costs for installed base customers facing mandatory replacement cycles.
For Market Incumbents: Secure ASHRAE 110 testing and commissioning capacity through exclusive technician certification programs to defend against emerging entrants with limited tracer gas protocol expertise. Deepen backward integration into 316-grade stainless steel fabrication to mitigate raw material cost volatility from European smelter output fluctuations. For New Entrants and Emerging Players: Differentiate on rapid deployment timelines for ductless fume hood configurations targeting contract research organizations in Hyderabad and Bangalore facing CDSCO-mandated containment upgrades. Penetrate the mobile fume hood segment serving project-based analytical chemistry operations with castor-mounted units that avoid infrastructure modification costs. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale regional fabricators possessing ASHRAE 110 certification depth but lacking channel breadth for geographic expansion into Indian pharmaceutical manufacturing corridors. The long-term viability window favors players with integrated service contract capabilities and VAV control technology licensing partnerships. Monitor EPA emissions mandate enforcement intensity as the primary inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ASHRAE 110 Certification Investment | Tracer gas testing capabilities differentiate premium tier positioning against uncertified competitors in German chemical research clusters. |
| Variable Air Volume Technology Licensing | Demand-controlled ventilation partnerships compress energy intensity for Massachusetts and California regulatory compliance mandates. |
| Backward Integration into Filtration Media | Captive HEPA and carbon filter production mitigates supply disruption risk from certified media concentration in legacy manufacturing regions. |
| Geographic Expansion into Indian CRO Corridors | Hyderabad and Bangalore facility upgrades under CDSCO-ICH alignment create addressable procurement volume for certified installations. |
| Service Contract Unbundling Response | Separate certification and recertification offerings capture academic medical center procurement consolidation across laboratory asset categories. |
Study Parameters
Initial hypotheses were tested against primary input from laboratory facilities managers, pharmaceutical quality control directors, university procurement officers, and ASHRAE 110 commissioning engineers, and refined through secondary validation against EPA regulatory filings, OSHA laboratory safety standards documentation, ECHA substance evaluation databases, and university capital expenditure records. Bottom-up triangulation across equipment shipment data and top-down reconciliation against HVAC infrastructure investment flows anchored volume and value estimates.
Variance decomposition across product type, end-user segment, technology tier, and installation complexity dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic drivers and regulatory mandate timelines. Forecast inputs incorporated REACH chemical registration requirement enforcement patterns and university hospital modernization program acceleration in Heidelberg, Boston, and Singapore.
Material uncertainties — stainless steel and HEPA filter cost volatility, ASHRAE 110 technician scarcity, and regulatory carbon accounting integration timelines — sit outside the modeled envelope. Forecasts reflect assumptions about EPA and OSHA mandate enforcement consistency and CDSCO regulatory alignment progression. Recalibration cycles align with material shifts in emissions regulation stringency and energy code adoption patterns in California and Massachusetts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Benchtop Centrifuges Market
Laboratory Equipment
Global Laboratory Plasticware Market
Laboratory Equipment
Global Laboratory Washers Market
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Ion-Selective Clinical Lab Analyzers Market
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
Vacuum Blood Collection Tube Market
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Blood Collection Tubes Market
Laboratory Equipment
United States Pipette Tips Market
Laboratory Equipment
Global Laboratory Grinders Market
Laboratory Equipment
Beaker Market
Laboratory Equipment
Blood Volume Analyzer Market
Laboratory Equipment
Histopathology Laboratory Equipment Market
Laboratory Equipment
UK Pipette Tips Market