
 Immune Response Testing Market | 2026-2036
Immune Response Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Immune Response Testing Market Analytics
Software-defined assay workflows are expanding the addressable value per instrument beyond hardware sales alone. Thermo Fisher Scientific leverages its cloud-connected analytics platform to sustain recurring revenue from installed cytometry bases. Siemens Healthcare GmbH anchors its position through embedded immune monitoring modules within integrated lab automation lines. Abbott Laboratories differentiates via point-of-care immune response platforms that reduce send-out volumes for health systems.
Immune response testing encompasses analytical methods that quantify cellular and humoral immune activity through detection of cytokines, antibodies, lymphocyte subsets, or activation markers, typically requiring sensitivity thresholds in the picogram-per-milliliter range for cytokine quantification. These assays serve critical functions in infectious disease management, autoimmune diagnostics, and cancer immunotherapy patient stratification. Flow cytometry commands premium positioning due to multiparameter single-cell resolution, while ELISA maintains volume leadership in routine clinical settings where cost-per-test drives procurement decisions. Research institutions represent the fastest-growing end-user channel as academic-industrial partnerships for immunotherapy trials multiply.
The FDA regulates immune response assays as in vitro diagnostic devices under 21 CFR Part 820 quality system requirements, while the EMA's IVDR transition imposes new clinical evidence standards on European market entrants. ISO 15189 accreditation shapes laboratory purchasing criteria for clinical-grade immune monitoring platforms. Stakeholders must weigh regulatory pathway complexity against the margin potential of companion diagnostic claims as immunotherapy pipelines mature.
Market Dynamics
Pharmaceutical companies are consolidating immunogenicity screening capabilities in-house as biologics pipelines expand, compressing outsourcing volumes for contract research organizations while elevating technical specifications for analytical instrumentation.
Growth Catalysts
- Companion diagnostic mandates:The FDA's evolving guidance on immunogenicity risk assessment requires validated assays for biologics approval, forcing developers to invest in compliant testing infrastructure.
- Cell therapy manufacturing:Academic medical centers are building dedicated immune monitoring facilities to support CAR-T and TCR trials, creating pull-through demand for multiparameter cytometry platforms.
- Cloud-connected analytics:Software-defined workflows enable recurring revenue from installed instrument bases, shifting vendor economics beyond hardware replacement cycles.
Market Restraints
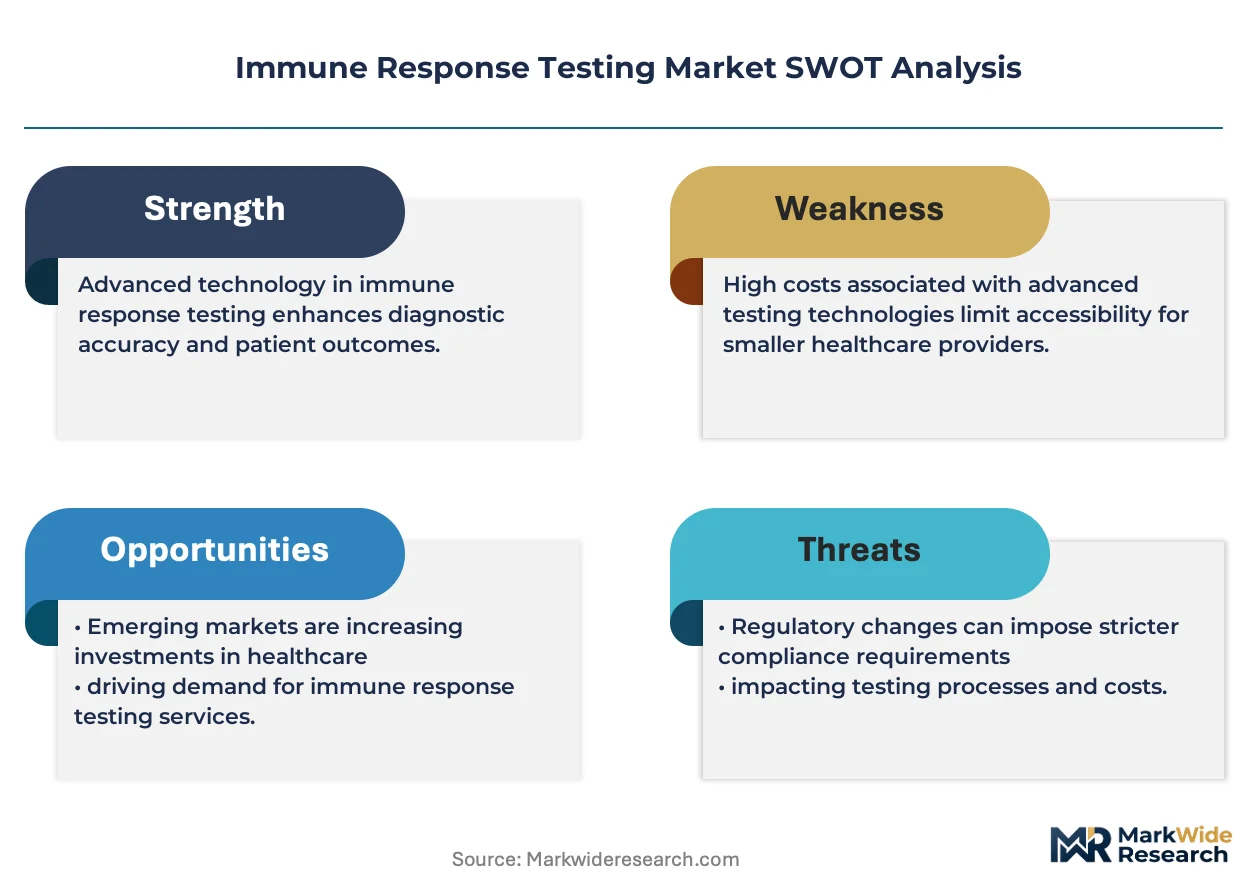
- Reagent supply concentration:Critical fluorophores and cytokine detection antibodies originate from a narrow supplier base in Germany and the United States, exposing assay developers to input volatility.
- IVDR compliance burden:The EMA's In Vitro Diagnostic Regulation imposes clinical evidence requirements that extend European market entry timelines by 18-24 months for novel assay formats.
- Technical sensitivity floors:Picogram-per-milliliter cytokine quantification demands specialized equipment and personnel, limiting test decentralization to community hospital settings.
Strategic Opportunities
- Point-of-care immune monitoring:Health systems in India are piloting decentralized lymphocyte subset analysis to reduce send-out volumes and accelerate infectious disease management decisions.
- ISO 15189 accreditation services:Clinical laboratories in Brazil require external validation support to meet international quality standards, creating service revenue for platform vendors.
- AI-assisted gating algorithms:Machine learning convergence with spectral cytometry is compressing analysis time from hours to minutes for complex immunophenotyping panels.
Industry Challenges
- Flow cytometry specialist scarcity:The technical complexity of 20+ color panel design and compensation requires rare expertise, constraining laboratory expansion plans.
- Legacy LIS integration friction:New immune monitoring platforms face extended deployment timelines due to interoperability requirements with entrenched laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immune Response Testing Market |
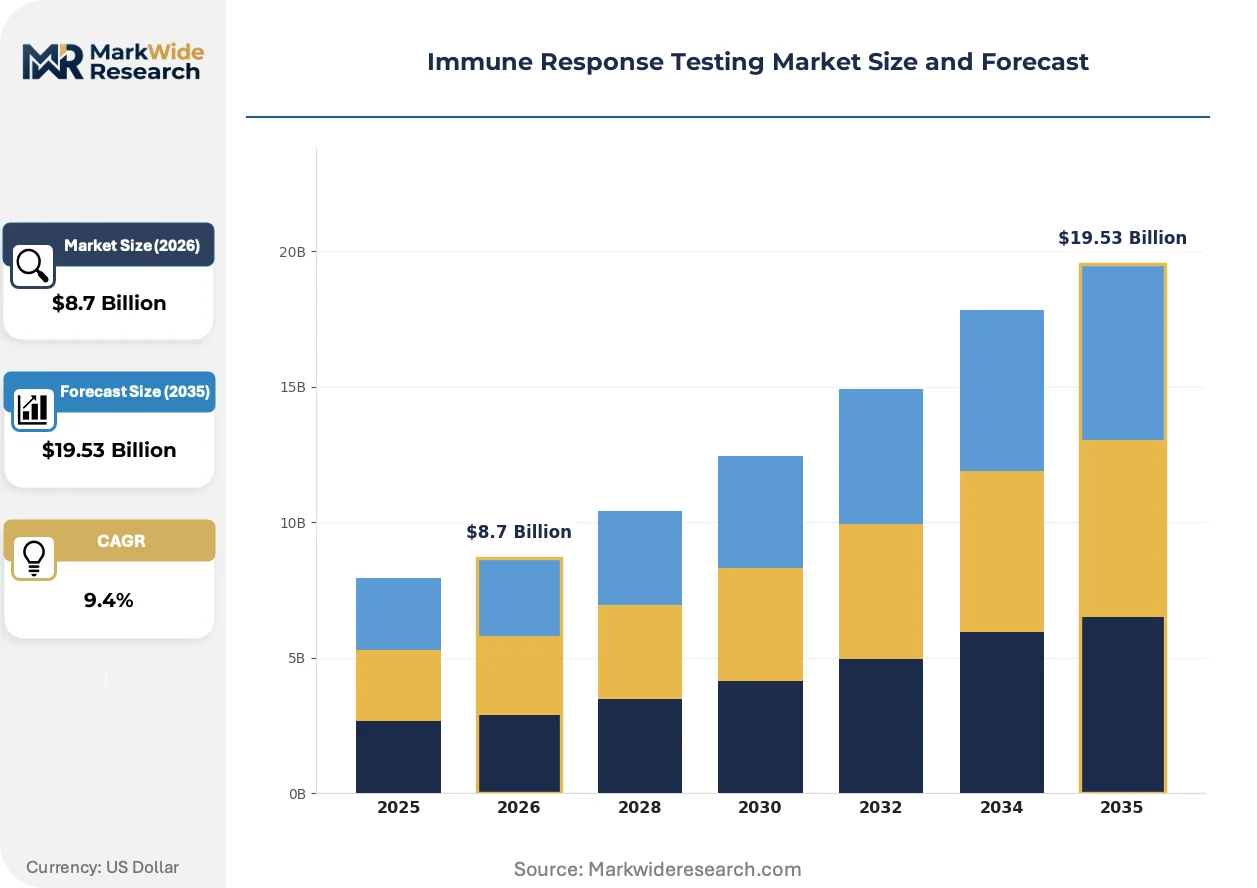
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: ELISA, Flow Cytometry, Immunoassay, Western Blot End User: Clinical Laboratories, Research Institutions, Diagnostic Centers, Pharmaceutical Companies Sample Type: Blood, Serum, Plasma, Saliva Application: Infectious Disease, Autoimmune Disorders, Cancer, Allergy Testing |
| Companies Covered | F. Hoffmann-La Roche AG, Thermo Fisher Scientific Inc., Siemens Healthcare GmbH, Abbott Laboratories, Quest Diagnostics Incorporated, Illumina Inc., QIAGEN N.V., Bio-Rad Laboratories Inc., Becton Dickinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immune Response Testing Market Evolving Landscape
Spectral detection architectures are displacing conventional optical filter systems, enabling deeper immunophenotyping while compressing instrument footprints and reagent consumption rates.
Mass cytometry is electrifying immuno-oncology biomarker discovery by resolving 40+ metal-tagged parameters simultaneously. Pharmaceutical translational medicine groups are adopting this technology for patient stratification in Phase II trials. The approach is electrifying demand for specialized service laboratories capable of handling rare earth metal conjugation and high-dimensional data analysis.
The EMA's IVDR transition is forcing assay developers to generate prospective clinical performance data for existing products. European IVD manufacturers are withdrawing lower-volume SKUs rather than absorbing compliance costs. Multiplex cytokine panels and lymphocyte subset enumeration assays face the steepest evidence requirements under the new classification rules.
Academic-industrial partnerships for immunotherapy trials are reshaping procurement authority. Principal investigators now specify analytical platforms in grant-funded protocols, bypassing traditional hospital supply chain committees. This pattern concentrates in the United States and Germany where National Institutes of Health and German Research Foundation funding streams support dedicated immune monitoring infrastructure.
Immune Response Testing Market Segmentation
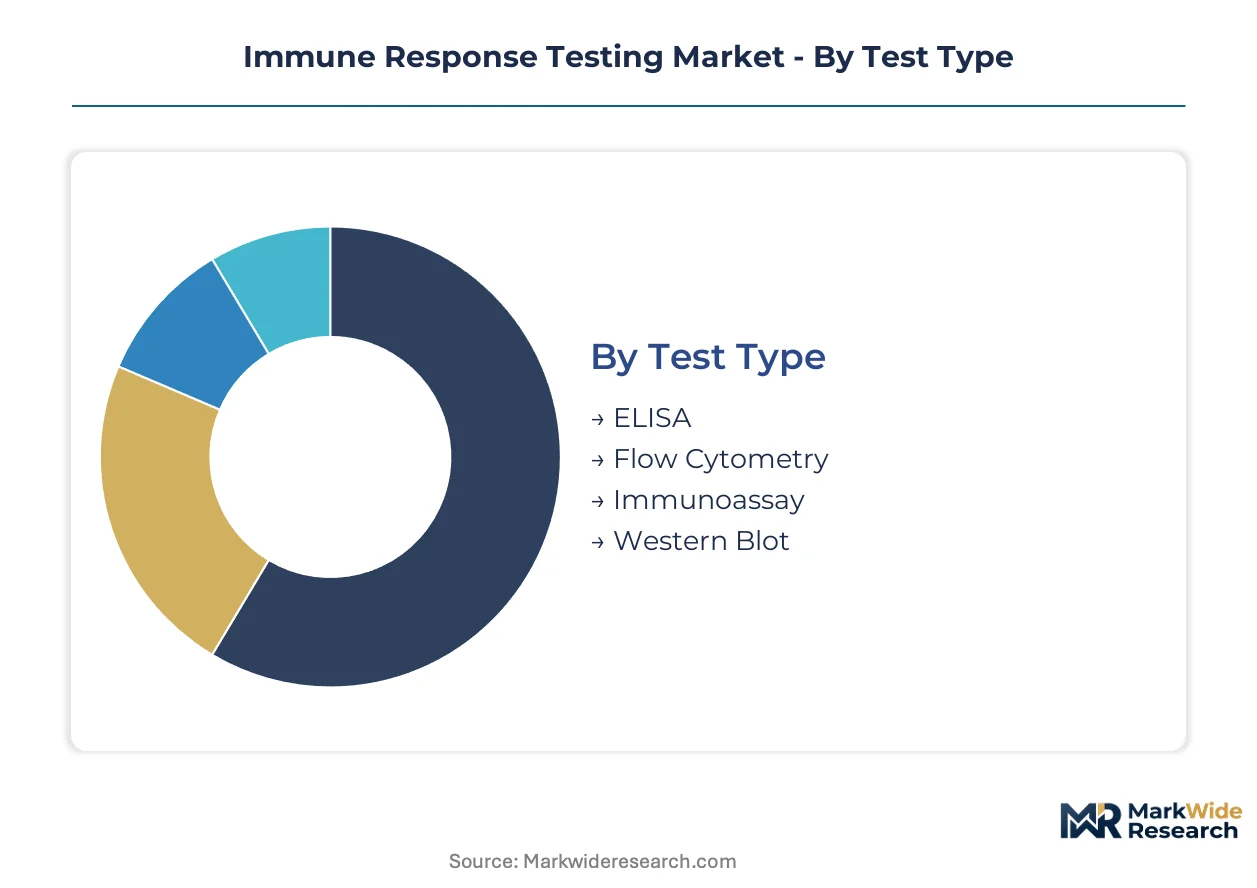
Immune response testing markets fragment across technical methodologies, sample matrices, and institutional purchasing authority. Procurement patterns diverge sharply between high-volume clinical screening and precision-driven translational research applications.
Test Type:
Technical specifications for sensitivity, multiplexing capacity, and throughput define competitive positioning across analytical platforms.
- Flow Cytometry:Multiparameter single-cell resolution enables 20+ color immunophenotyping panels for CAR-T patient stratification. Academic medical centers in the United States concentrate demand here, driven by NIH-funded immuno-oncology trials requiring deep cellular characterization.
- ELISA:Enzyme-linked immunosorbent assays dominate routine cytokine quantification with picogram-per-milliliter sensitivity thresholds. Clinical laboratories in Germany and Japan favor this format for cost-per-test economics in high-volume infectious disease monitoring.
- Immunoassay:Chemiluminescence and electrochemiluminescence platforms serve automated core lab workflows with mid-plex cytokine panels.
- Western Blot:Semi-quantitative antibody detection persists in research settings for novel biomarker validation and regulatory submission support.
Mature deployment sits with ELISA. Newer deployment is concentrated in Flow Cytometry.
End User:
Institutional purchasing authority shapes instrument specifications, service contract terms, and reagent consumption patterns.
- Research Institutions:Principal investigators specify analytical platforms directly in grant-funded protocols, bypassing traditional supply chain committees. German Research Foundation and NIH funding streams support dedicated immune monitoring infrastructure at centers in Heidelberg, Boston, and Houston.
- Pharmaceutical Companies:In-house immunogenicity screening programs compress outsourcing volumes while elevating technical specifications for GMP-compliant cytometry and multiplex cytokine analysis.
- Clinical Laboratories:ISO 15189 accreditation requirements drive procurement of validated, FDA-cleared or IVDR-compliant assay systems with established quality control frameworks.
- Diagnostic Centers:Point-of-care lymphocyte subset analysis pilots in Indian health systems aim to reduce send-out volumes and accelerate infectious disease management decisions.
Volume concentration rests with Clinical Laboratories. Margin expansion is concentrated in Research Institutions.
Sample Type:
Biological matrix characteristics determine pre-analytical handling requirements, stability windows, and assay validation complexity.
- Blood:Whole blood assays preserve cellular integrity for immediate flow cytometry analysis, supporting decentralized testing in resource-limited settings. Brazilian clinical laboratories are expanding cold-chain infrastructure to support same-day processing requirements.
- Plasma:Anticoagulated plasma enables cytokine stability during transport, facilitating centralized reference laboratory models across the United States and European Union.
- Serum:Clotted blood derivatives serve antibody detection applications where cellular components introduce interference.
- Saliva:Non-invasive collection is gaining traction in pediatric allergy testing and large-scale epidemiological surveillance programs.
Standardized workflows center on Plasma. Methodological innovation is concentrated in Saliva.
Application:
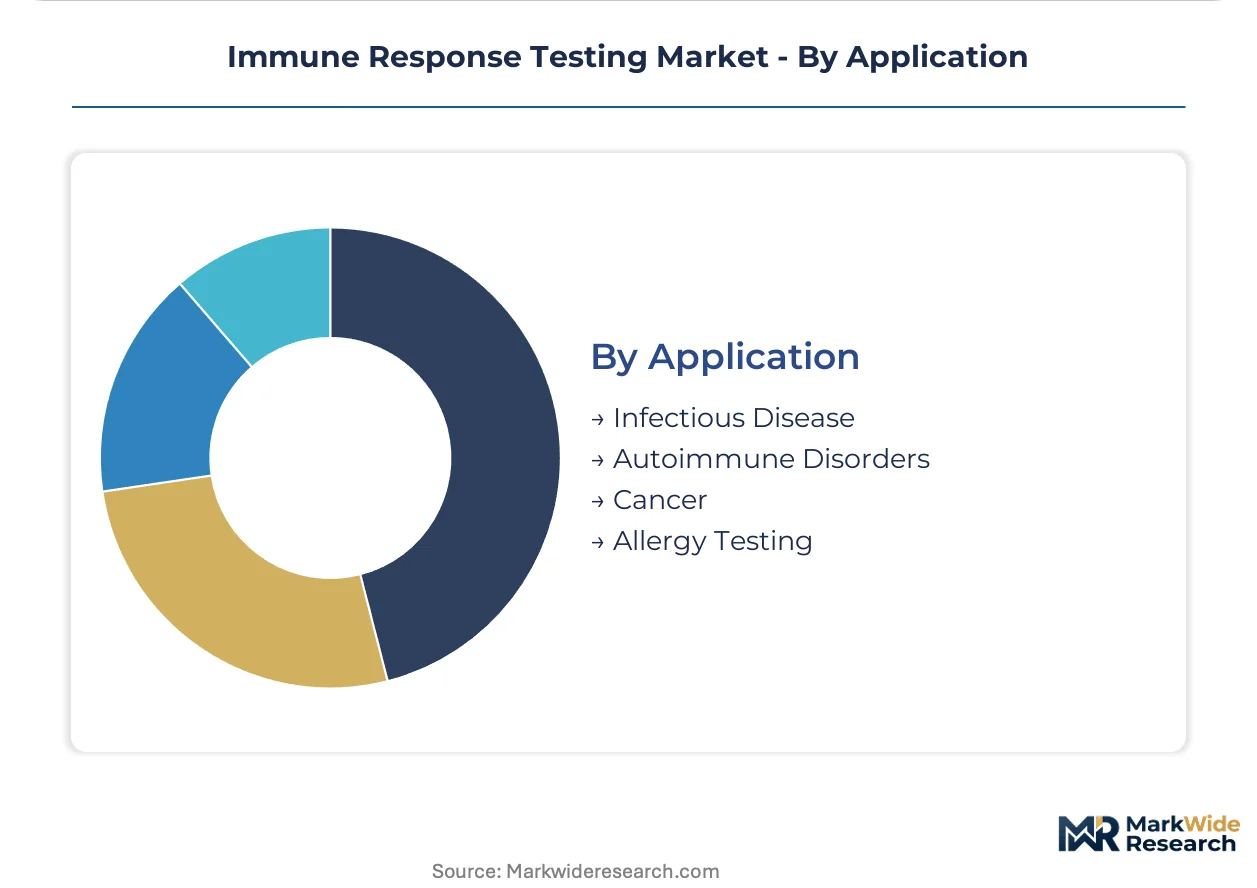
Disease-specific clinical utility drives reimbursement codes, companion diagnostic mandates, and platform investment priorities.
- Cancer:Immuno-oncology patient stratification commands premium pricing for multiparameter cytometry panels supporting PD-1/PD-L1 and CAR-T therapy decisions. FDA companion diagnostic mandates for biologics approval force developers to invest in validated testing infrastructure.
- Infectious Disease:Lymphocyte subset enumeration guides antiretroviral therapy monitoring and transplant recipient immune reconstitution assessment.
- Autoimmune Disorders:Cytokine profiling and autoantibody panels support disease activity monitoring in rheumatoid arthritis and systemic lupus erythematosus.
- Allergy Testing:Specific IgE quantification and basophil activation tests serve diagnostic and therapeutic monitoring applications.
Established reimbursement sits with Infectious Disease. Regulatory momentum is concentrated in Cancer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors the highest concentration of immune response testing infrastructure, with academic medical centers and NIH-funded research hospitals driving procurement of multiparameter cytometry platforms for CAR-T and checkpoint inhibitor trials.
United States
NIH funding streams support dedicated immune monitoring facilities at centers in Boston, Houston, and San Diego. The FDA's evolving guidance on immunogenicity risk assessment mandates validated assays for biologics approval, compelling pharmaceutical developers to invest in compliant testing infrastructure. Principal investigators now specify analytical platforms directly in grant-funded protocols, bypassing traditional hospital supply chains.
Germany
Heidelberg and Munich cluster academic-industrial partnerships for immunotherapy trials, with German Research Foundation funding enabling dedicated immune monitoring infrastructure. The EMA's IVDR transition imposes clinical evidence requirements that extend market entry timelines for novel assay formats. Siemens Healthcare GmbH anchors integrated lab automation lines with embedded immune monitoring modules.
China
NMPA regulatory pathways for in vitro diagnostic devices are accelerating as domestic biologics pipelines expand. Shanghai and Beijing concentrate demand for flow cytometry platforms serving cell therapy manufacturing quality control. Local clinical laboratories are building ISO 15189-accredited immune monitoring capabilities to support indigenous CAR-T programs.
India
Health systems in Maharashtra and Karnataka pilot decentralized lymphocyte subset analysis to reduce send-out volumes and accelerate infectious disease management decisions. CDSCO oversight of diagnostic device quality standards is tightening procurement criteria for imported platforms. Thermo Fisher Scientific leverages cloud-connected analytics to sustain recurring revenue from installed cytometry bases in metropolitan hospital networks.
Brazil
ANVISA regulatory harmonization with international standards is elevating compliance burdens for European and North American assay vendors. São Paulo clinical laboratories require external validation support to meet ISO 15189 accreditation, creating service revenue opportunities for platform manufacturers. Cold-chain infrastructure expansion supports same-day processing requirements for whole blood flow cytometry assays.
Immune Response Testing Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across instrument manufacturing and reagent supply. The market structure concentrates around integrated diagnostics conglomerates with captive distribution networks and specialized cytometry boutiques with proprietary panel design expertise. Three archetypes dominate: full-stack platform vendors bundling hardware, software, and consumables; reagent specialists commanding fluorophore and antibody supply; and service laboratories monetizing high-dimensional data analysis. Consolidation pressures favor M&A-driven portfolio diversification and strategic partnerships for AI-assisted gating algorithm development.
Among Swiss and German pharmaceutical conglomerates, F. Hoffmann-La Roche AG exemplifies the integrated diagnostics archetype spanning reagent manufacturing through clinical laboratory services. Thermo Fisher Scientific Inc., a US-based corporation, occupies a position at the convergence of instrument hardware and cloud-connected analytics platforms. Siemens Healthcare GmbH, a German GmbH, anchors the automation-integrated tier through embedded immune monitoring modules within core lab workflows. These three entities represent distinct strategic vectors: Roche through therapeutic-diagnostic vertical alignment, Thermo Fisher through software-defined recurring revenue, and Siemens through health system automation penetration.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| Thermo Fisher Scientific Inc. |
| Siemens Healthcare GmbH |
| Abbott Laboratories |
| Quest Diagnostics Incorporated |
| Illumina Inc. |
| QIAGEN N.V. |
| Bio-Rad Laboratories Inc. |
| Becton Dickinson |
| Others |
Value Network & Pricing Analysis
ISO 15189 accreditation requirements gate qualified supply access for clinical-grade immune monitoring platforms, segmenting vendors into premium-tier pricing for accredited systems versus economy positioning for research-use-only configurations. This certification divide concentrates pricing power among platform manufacturers with established quality management systems, while squeezing margins for reagent suppliers lacking clinical evidence packages under EMA IVDR rules.
Pricing Analysis
Outcome-linked pricing anchors premium cytometry platforms, with vendors tying instrument leases to patient stratification throughput guarantees in immuno-oncology trials. Three-tier pricing structure across premium, standard, and economy levels reflects GMP compliance grade, multiplexing capacity, and software analytics bundling. Cost compression in economy ELISA segments intensifies because of raw material input volatility from German fluorophore suppliers. Academic medical centers exhibit highest price sensitivity due to grant-funded procurement constraints, while pharmaceutical translational medicine groups prioritize sensitivity specifications over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Singapore anchor hub-and-spoke patterns for temperature-sensitive reagents and rare earth metal conjugates. Critical fluorophores and cytokine detection antibodies draw from concentrated manufacturing bases in Germany and the United States, with single-source vulnerability for specialized spectral detection components. Tariff exposure runs through China-sourced optical filters and Japanese-sourced photomultiplier tubes. Distribution runs through direct field service organizations for high-value cytometry platforms, while consumables feed from authorized distributor networks with cold-chain validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spectral detection architectures are displacing conventional optical filter systems, compressing the technology transition window for legacy platform vendors. This shift rewards manufacturers with embedded software analytics and punishes pure hardware plays lacking recurring revenue attachment.
For Market Incumbents: Extend cloud-connected analytics penetration to sustain recurring revenue from installed cytometry bases, countering margin erosion from hardware commoditization. Deepen backward integration into rare earth metal conjugation capabilities to secure supply for mass cytometry expansion. Prioritize ISO 15189 accreditation support services as a defensive moat against emerging platform vendors lacking clinical quality infrastructure. For New Entrants and Emerging Players: Mid-tier clinical laboratories in Brazil and India represent an underserved buyer archetype requiring external validation support for international quality standards. White-space concentration sits with point-of-care lymphocyte subset analysis in resource-limited health systems. A service-first go-to-market angle—bundling instrument placement with AI-assisted gating algorithm training—bypasses capital procurement barriers. For Investors and Strategic Acquirers: FDA companion diagnostic mandate enforcement is the leading indicator that validated assay infrastructure will command scarcity premiums. Long-term viability favors platform vendors with therapeutic-diagnostic vertical alignment and software-defined recurring revenue models. Acquisition target archetype: specialized cytometry boutiques with proprietary 20+ color panel design expertise and established academic medical center relationships. Watch for EMA IVDR transition completion as signal for European market consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Analytics Platform Expansion | Thermo Fisher Scientific leverages recurring revenue attachment to extend instrument lifecycle economics beyond replacement cycles. |
| ISO 15189 Accreditation Service Launch | Siemens Healthcare GmbH embeds quality validation modules within automation lines to capture Brazilian laboratory compliance demand. |
| Point-of-Care Immune Monitoring Pilot | Abbott Laboratories reduces hospital send-out volumes through decentralized lymphocyte subset analysis in Indian health systems. |
| AI-Assisted Gating Algorithm Development | Machine learning convergence compresses immunophenotyping analysis time from hours to minutes for complex CAR-T patient stratification. |
| Mass Cytometry Service Laboratory Buildout | Specialized facilities handling rare earth metal conjugation capture pharmaceutical translational medicine outsourcing demand. |
Research Methodology
SEC 10-K filings, FDA 510(k) clearance databases, and EMA IVDR technical documentation formed the secondary backbone, cross-referenced against primary interviews with flow cytometry platform directors, clinical laboratory quality managers, pharmaceutical translational medicine leads, and hospital procurement committee members. Bottom-up and top-down triangulation validated segment-level assumptions against instrument installation records and reagent consumption patterns.
Bottom-up modeling anchored volume projections on installed base expansion and utilization rates per platform, while top-down constraints drew from aggregate biologics pipeline investment and immune monitoring infrastructure buildout announcements. Segmentation dimensions included test methodology, end-user institutional type, sample matrix, and application area across the analysis window. CAGRs derived from logistic diffusion curves fitted to technology adoption patterns in academic medical centers and pharmaceutical in-house screening programs.
Revisions become necessary when regulatory enforcement intensity shifts, supply chain disruptions alter reagent availability, or technology substitution accelerates beyond modeled diffusion parameters. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
Global Cardiac Marker Testing Market
Clinical Diagnostics
Food Allergy Diagnosis and Treatment Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market
Clinical Diagnostics
Global Apoptosis Assays Market
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Bacterial and Viral Specimen Collection Market
Clinical Diagnostics
Global Hepatitis C Testing Market
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
Cervical Cancer Screening Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Bone Metabolism Test Market