
 Clinical Diagnostic Equipment Market | 2026-2036
Clinical Diagnostic Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Diagnostic Equipment Market Outlook
Multi-source procurement for critical diagnostic platforms is hardening as hospital systems reduce dependency on single-vendor ecosystems. Siemens Healthineers leverages its imaging-to-laboratory workflow integration to sustain long-term service contracts with major health networks. Danaher anchors its position through disciplined operational excellence across its life sciences diagnostics portfolio. bioMérieux specializes in microbiology and infectious disease testing, occupying a defensible niche where clinical specificity commands premium positioning.
Clinical diagnostic equipment encompasses analyzers, imaging systems, assays, and reagents designed to detect, quantify, and monitor biological markers with specified sensitivity thresholds, typically operating through automated sample processing workflows that reduce human error and turnaround time. Its primary commercial purpose is enabling accurate, repeatable diagnostic outputs that inform treatment decisions across acute care, chronic disease management, and population health screening. Analyzers and reagents together capture the largest margin pools, as consumable attachment rates on installed instrument bases generate recurring revenue streams that outperform capital equipment sales. Molecular technology segments are expanding fastest as nucleic acid amplification platforms displace slower culture-based methods in infectious disease and oncology applications.
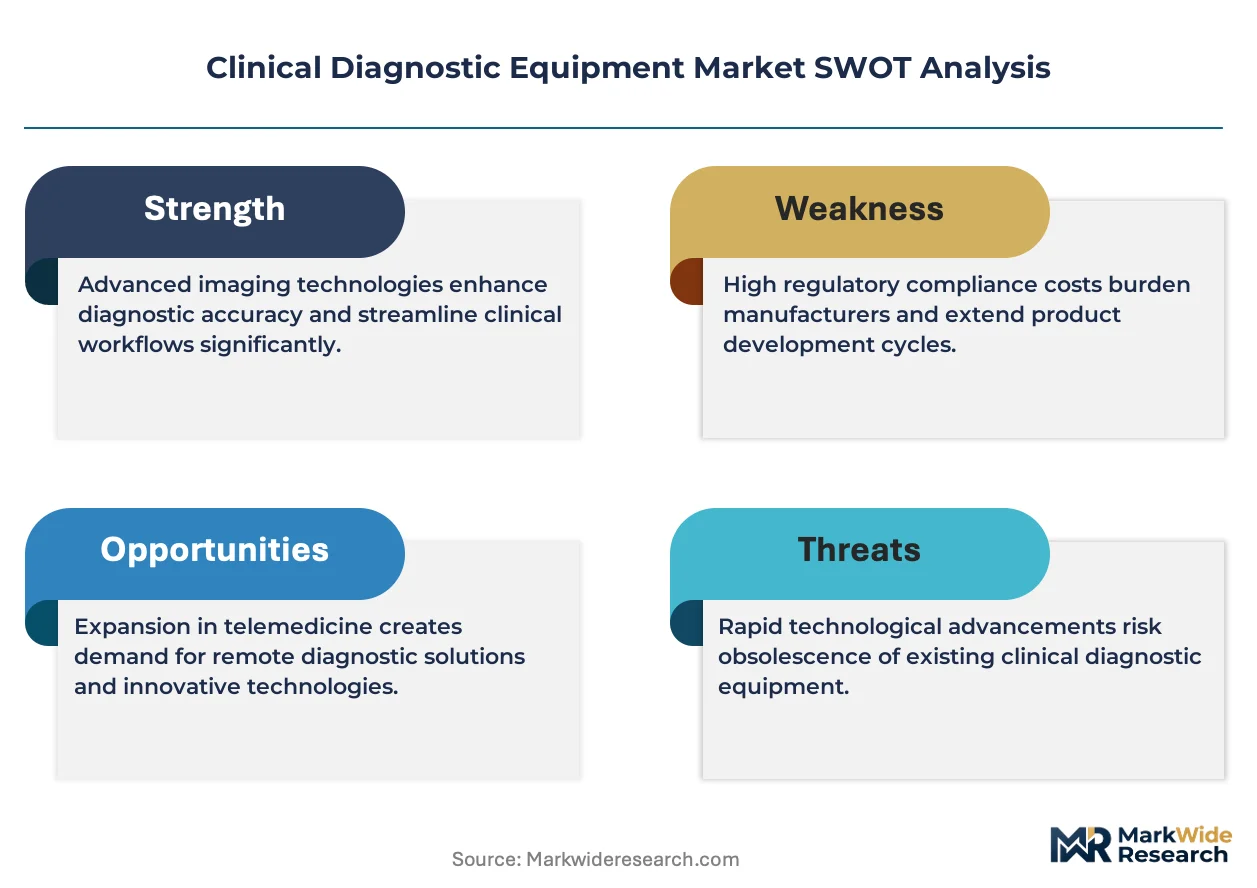
FDA premarket notification and clearance pathways shape product development timelines and market access for US-bound diagnostic platforms, while the EU Medical Device Regulation imposes stricter clinical evidence requirements on in vitro diagnostic manufacturers seeking CE marking. ISO 15189 accreditation standards for medical laboratories create downstream demand for equipment that delivers traceable, reproducible results aligned with quality management systems. Stakeholders must monitor how reimbursement policy shifts toward value-based care models will redirect capital allocation between point-of-care decentralization and centralized laboratory automation.
Market Dynamics
Automated sample-to-answer workflows are compressing turnaround times in hospital laboratories, forcing capital equipment vendors to rearchitect their platforms around throughput metrics rather than standalone analytical sensitivity. This operational imperative is redistributing margin pools toward consumables and service contracts.
Growth Catalysts
- EU MDR implementation:Stricter clinical evidence requirements for in vitro diagnostics are accelerating replacement cycles as laboratories upgrade to compliant platforms ahead of enforcement deadlines.
- Point-of-care decentralization:Integrated delivery networks are deploying nucleic acid amplification systems in satellite clinics to reduce central lab bottlenecks during respiratory virus seasons.
- Reagent rental models:Equipment vendors are bundling instrument placement with minimum volume commitments, lowering upfront capital barriers for mid-sized hospital systems.
Market Restraints
- Optical component supply concentration:Precision photonics subassemblies for fluorescence detection concentrate among German and Japanese specialty suppliers, creating vulnerability to export control disruptions.
- FDA premarket review timelines:Novel assay platforms face extended clearance pathways when predicate devices lack established performance benchmarks, delaying commercialization by 12-18 months.
- Culture-based method persistence:Antimicrobial susceptibility testing retains reimbursement advantages in certain Medicare jurisdictions, slowing molecular platform displacement.
Strategic Opportunities
- India's diagnostic infrastructure expansion:The country's PLI scheme for medical devices is attracting contract manufacturers to establish reagent production hubs serving Southeast Asian export markets.
- Pharmacogenomics integration:Convergence of pharmacogenomic testing with routine chemistry panels is creating demand for multimodal analyzers in oncology and psychiatry clinics.
- Direct-to-employer contracts:Self-insured corporations are contracting on-site diagnostic capabilities as population health benefits, bypassing traditional hospital procurement channels.
Industry Challenges
- Cross-trained technician scarcity:Molecular diagnostics requires hybrid competencies in biochemistry and informatics that traditional medical laboratory science programs inadequately cover.
- LIS integration complexity:Laboratory information system interoperability with third-party analyzers demands custom middleware development, extending deployment timelines and inflating implementation costs.
- IVD-CDx regulatory bifurcation:Companion diagnostic co-development pathways impose divergent evidentiary standards between FDA and EMA, complicating simultaneous market entry strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Diagnostic Equipment Market |
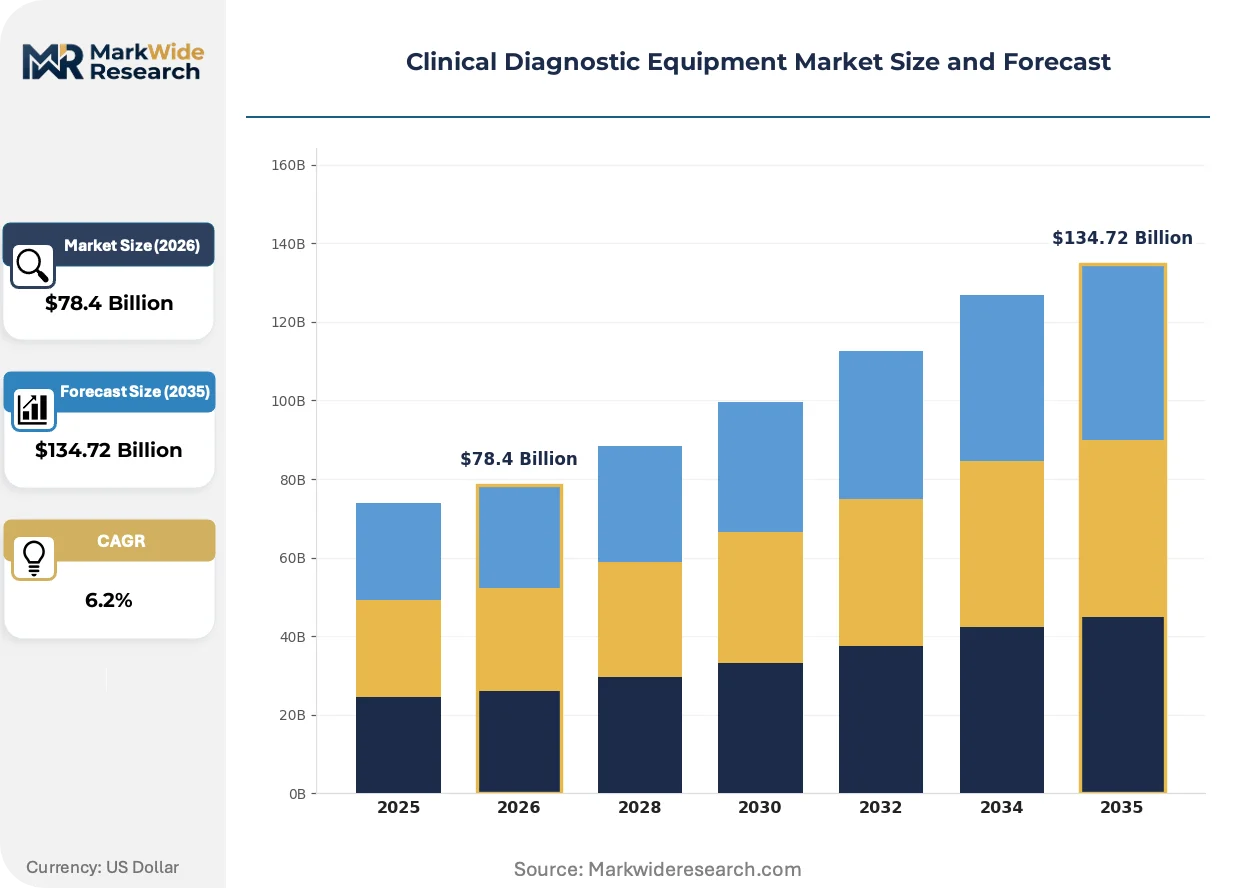
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analyzers, Imaging Systems, Assays, Reagents Technology: Biochemical, Molecular, Imaging, Hematology End User: Hospitals, Laboratories, Diagnostic Centers, Research Institutions Application: Disease Diagnosis, Health Monitoring, Infectious Diseases, Cancer Screening |
| Companies Covered | Abbott, Siemens Healthineers, F. Hoffmann-La Roche, Danaher, GE Healthcare, Thermo Fisher Scientific, BD, bioMérieux, Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Diagnostic Equipment Market Strategic Shifts
Digital pathology and artificial intelligence are converging to automate morphological interpretation, while regulatory frameworks struggle to keep pace with algorithm-based diagnostic determinations. These developments are compressing the traditional boundaries between laboratory disciplines.
Next-generation sequencing is rewriting infectious disease surveillance by enabling same-day outbreak source identification that culture methods require weeks to deliver. Public health laboratories in the United States and Germany are prioritizing platform standardization across state and federal networks. This capability is compressing response timelines for novel pathogen emergence and antimicrobial resistance tracking.
The FDA's enforcement discretion policy for artificial intelligence-based radiological devices is expanding to encompass digital pathology algorithms, creating a regulatory sandbox for computer-aided diagnostic tools. Device manufacturers are submitting real-world performance data through pre-certification pathways rather than traditional 510(k) submissions. Anatomic pathology laboratories with academic medical center affiliations are most aggressively piloting these systems to address subspecialist staffing gaps.
Hospital procurement committees are unbundling service contracts from equipment purchases, soliciting third-party maintenance providers through competitive bidding. This disintermediation pressures OEM service margins while creating openings for independent service organizations with specialized training in multi-vendor environments. The phenomenon is most pronounced in the United States, where integrated delivery networks operate centralized biomed departments across dozens of facility locations.
Clinical Diagnostic Equipment Market Segmentation
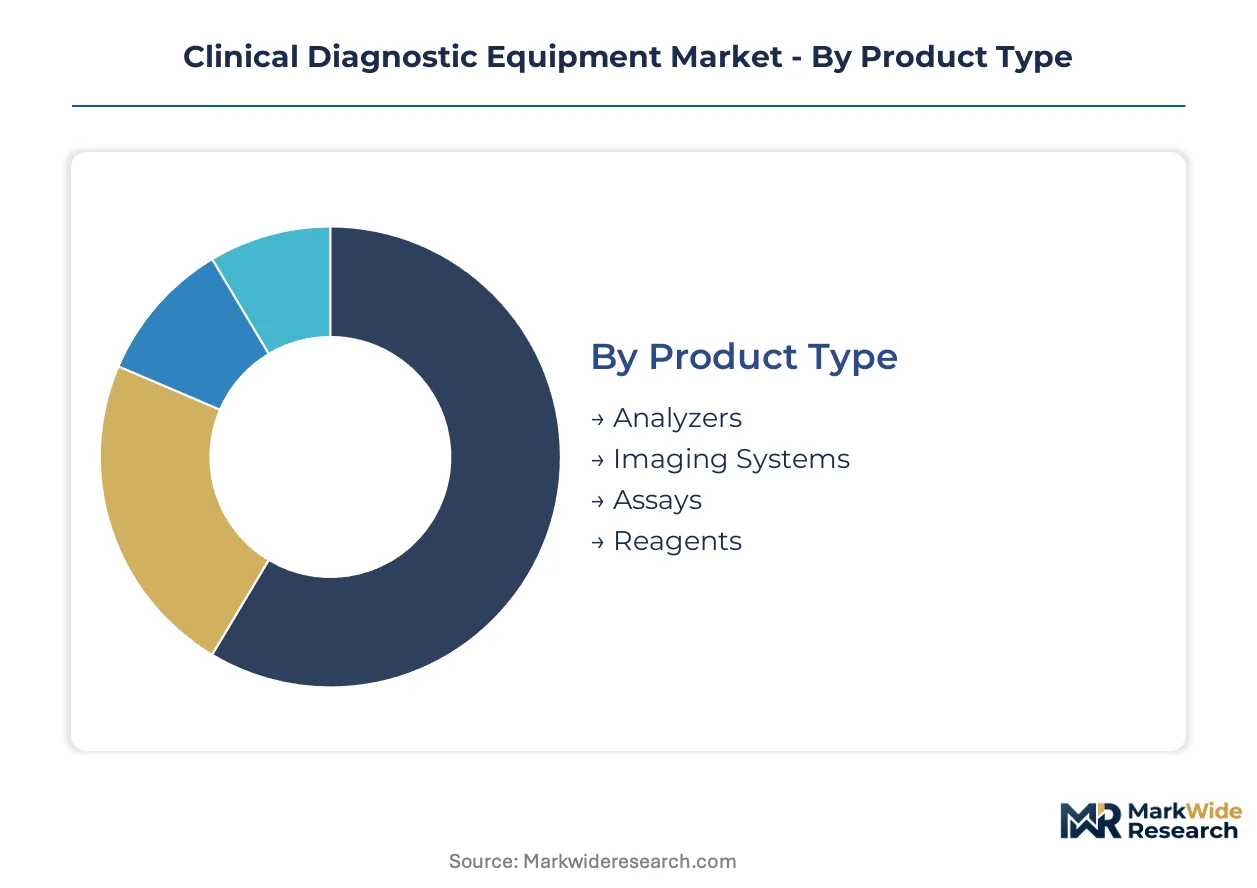
Segmentation in clinical diagnostic equipment reveals how margin pools concentrate around consumable attachment rates and technology maturity. Procurement committees weigh capital intensity against throughput metrics when allocating budgets across product categories.
Product Type:
Volume-driven consumables capture recurring revenue streams, while capital equipment commands premium positioning through service bundling.
- Analyzers:Automated platforms process high-throughput sample workflows with specified sensitivity thresholds. Hospital laboratories in the United States prioritize throughput metrics over standalone analytical performance when selecting chemistry and immunoassay systems.
- Reagents:Consumable inputs with formulation stability requirements and cold-chain logistics dependencies. Integrated delivery networks negotiate multi-year minimum volume commitments to lock in predictable per-test economics.
- Imaging Systems:Digital pathology and radiological hardware with algorithm-assisted interpretation capabilities. Academic medical centers pilot computer-aided diagnostic tools to address subspecialist staffing gaps.
- Assays:Preconfigured test kits with defined performance characteristics for specific biomarker detection. FDA premarket notification pathways shape development timelines for novel assay platforms.
Mature deployment sits with analyzers. Newer deployment is concentrated in imaging systems with embedded artificial intelligence.
Technology:
Speed of result generation separates premium positioning from commodity substitution risk.
- Molecular:Nucleic acid amplification platforms displace culture-based methods through same-day pathogen identification. Public health laboratories in Germany and the United States prioritize platform standardization across federal networks for outbreak response.
- Imaging:Morphological interpretation systems with photonics subassemblies concentrated among German and Japanese specialty suppliers. Digital pathology algorithms face evolving FDA enforcement discretion policies for computer-aided diagnostic determinations.
- Biochemical:Established chemistry panels with reimbursement alignment under Medicare fee schedules. Antimicrobial susceptibility testing retains payment advantages in certain jurisdictions, slowing displacement.
- Hematology:Cell counting and coagulation analysis with mature automation standards. Hospital laboratories expand automated lines to manage higher patient throughput during respiratory virus seasons.
Clinical specificity commands premium positioning in molecular technology. Biochemical methods represent the most mature installed base.
End User:
Procurement authority concentration determines contract structure and service bundling economics.
- Hospitals:Acute care facilities with centralized biomed departments managing multi-vendor environments across dozens of locations. United States integrated delivery networks unbundle service contracts from equipment purchases through competitive bidding.
- Laboratories:Independent and hospital-affiliated testing facilities requiring ISO 15189 accreditation alignment. Quality management systems create downstream demand for traceable, reproducible result platforms.
- Diagnostic Centers:Outpatient facilities with point-of-care deployment of nucleic acid amplification systems. Satellite clinics reduce central lab bottlenecks during seasonal demand surges.
- Research Institutions:Academic centers with companion diagnostic co-development pathways. FDA and EMA evidentiary divergence complicates simultaneous market entry strategies for investigational platforms.
Consolidated procurement sits with hospitals. Decentralized expansion is concentrated in diagnostic centers.
Application:
Reimbursement policy shifts redirect capital allocation between screening volume and precision intervention.
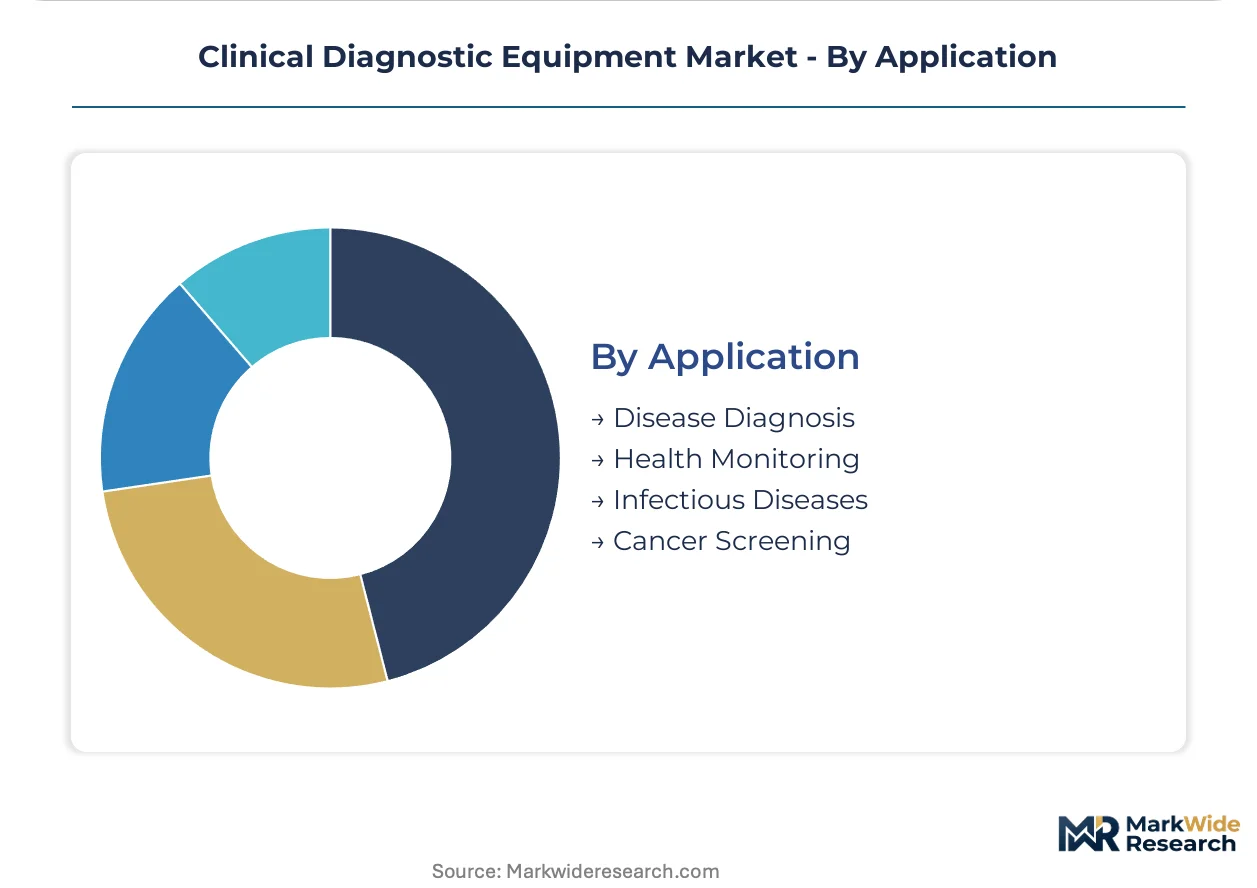
- Disease Diagnosis:Acute and chronic condition identification with treatment decision dependency. Value-based care models reshape capital allocation between point-of-care and centralized automation.
- Cancer Screening:Oncology panels with pharmacogenomic integration creating multimodal analyzer demand. Convergence with routine chemistry testing drives psychiatry and oncology clinic procurement.
- Infectious Diseases:Pathogen detection with antimicrobial resistance tracking requirements. Next-generation sequencing compresses outbreak source identification timelines from weeks to same-day resolution.
- Health Monitoring:Population screening and chronic disease surveillance with employer-contracted on-site capabilities. Self-insured corporations bypass traditional hospital procurement channels for workforce health benefits.
Volume concentration sits with disease diagnosis. Steepest expansion trajectory is concentrated in cancer screening with companion diagnostic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision photonics subassemblies from German and Japanese specialty suppliers anchor the upstream supply chain for fluorescence detection systems. Hospital procurement concentration and regulatory pathway efficiency determine commercial access across major diagnostic equipment markets.
United States
Integrated delivery networks consolidate procurement around multi-year equipment contracts spanning dozens of facility locations. FDA premarket review pathways for in vitro diagnostics shape product development timelines and clearance trajectories for novel assay platforms. Academic medical centers in Boston and the Research Triangle pilot digital pathology algorithms to address subspecialist staffing gaps.
Germany
Public health laboratories prioritize platform standardization across federal and state networks for outbreak response and antimicrobial resistance tracking. EU Medical Device Regulation imposes stricter clinical evidence requirements on in vitro diagnostic manufacturers seeking CE marking. The Munich-Stuttgart corridor concentrates precision photonics suppliers serving fluorescence detection subassemblies.
China
NMPA regulatory pathways govern market access for molecular diagnostic platforms and automated analyzer systems. The country's diagnostic infrastructure expansion attracts contract manufacturers establishing reagent production hubs for Southeast Asian export markets. Shanghai and Suzhou industrial clusters host domestic equipment assembly operations serving hospital laboratory automation demand.
India
The PLI scheme for medical devices incentivizes localized manufacturing of diagnostic reagents and consumables. CDSCO regulatory frameworks govern import and domestic production of in vitro diagnostic equipment. Maharashtra and Gujarat host emerging contract manufacturing facilities targeting regional export markets.
Japan
PMDA consultation pathways influence development timelines for companion diagnostic co-development projects. METI industrial policy supports precision photonics capabilities concentrated among specialty component suppliers. The Osaka-Kobe manufacturing belt maintains diagnostic equipment production serving domestic hospital laboratory demand.
Clinical Diagnostic Equipment Market Competitive Environment
Global majors compete with regional champions across integrated workflow solutions and specialized testing niches. The vendor base organizes around three strategic archetypes: diversified healthcare conglomerates with imaging-to-laboratory integration capabilities, life sciences specialists with disciplined operational excellence across diagnostics portfolios, and microbiology-focused players commanding premium positioning through clinical specificity. Competitive dynamics center on service contract unbundling and reagent rental models that lower upfront capital barriers.
Within the diversified healthcare tier, Siemens Healthineers and GE Healthcare exemplify integrated workflow positioning. Danaher represents the operational excellence archetype across life sciences diagnostics. bioMérieux occupies the specialized niche position in microbiology and infectious disease testing segments.
| Leading Market Players |
|---|
| Abbott |
| Siemens Healthineers |
| F. Hoffmann-La Roche |
| Danaher |
| GE Healthcare |
| Thermo Fisher Scientific |
| BD |
| bioMérieux |
| Philips Healthcare |
| Others |
Value Chain & Pricing Dynamics
Hybrid technician scarcity in the Research Triangle and Boston corridors widens pricing spreads between premium-tier service-bundled systems and economy-tier unbundled placements. Labor-cost differentials between these specialized clusters and mid-sized hospital markets force vendors to stratify contract structures around training intensity and response-time guarantees.
Pricing Analysis
Warranty and service-bundling unbundling is redistributing margin pools across contract structures. Three-tier pricing structure across premium, standard, and economy levels separates Siemens Healthineers' integrated workflow packages from third-party-maintained legacy analyzers. Price differentiation hinges on ISO 15189 accreditation alignment and after-sales service density. Pricing pressure stems from competitive bidding by independent service organizations in United States integrated delivery networks. Mid-sized hospital systems exhibit highest price sensitivity; academic medical centers with subspecialist staffing gaps show lowest.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese precision photonics suppliers serving fluorescence detection subassemblies. Manufacturing concentrates in Germany, Japan, and China for optical components, reagent formulation, and analyzer assembly respectively. Raw material dependencies include rare-earth phosphors, high-purity solvents, and specialized polymer consumables. Tariff exposure on precision optical imports from Germany creates supply chain risk. Distribution runs through hospital procurement committees and group purchasing organizations with multi-year contract lock-ins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR implementation has erected a cost-of-compliance moat that favors incumbents with established clinical evidence dossiers and quality management systems, marginalizing undercapitalized challengers unable to fund retrospective trials.
For Market Incumbents: Deepen backward integration into precision photonics capabilities to reduce dependency on German and Japanese specialty suppliers. Lock in reagent rental contracts with minimum volume commitments before third-party service organizations capture mid-sized hospital maintenance spend. Molecular platform substitution of culture-based methods represents the priority threat requiring defensive patent positioning. For New Entrants and Emerging Players: Enter via India's PLI scheme for medical devices to establish reagent production hubs serving Southeast Asian export markets with lower regulatory barriers than EU or US pathways. Target diagnostic centers deploying point-of-care nucleic acid amplification systems during respiratory virus seasons. Pharmacogenomics integration with routine chemistry panels offers the most penetrable application angle for multimodal analyzer positioning. For Investors and Strategic Acquirers: The window for entry favors microbiology-focused specialists with defensible infectious disease testing niches and premium pricing power in antimicrobial resistance surveillance. Long-term viability rests on companion diagnostic co-development capabilities bridging FDA and EMA evidentiary divergence. Watch for FDA enforcement discretion policy expansion on digital pathology algorithms as inflection signal for computer-aided diagnostic platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance accelerates replacement cycles ahead of enforcement deadlines. |
| Hospital System Partnership | Multi-year equipment contracts with integrated delivery networks secure installed base. |
| Reagent Rental Model | Minimum volume commitments lower upfront capital barriers for mid-sized systems. |
| Software Companion Development | LIS interoperability middleware reduces deployment timeline friction. |
| Reimbursement Strategy | Value-based care alignment redirects capital toward point-of-care decentralization. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this clinical diagnostic equipment analysis. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and laboratory directors combined with FDA 510(k) databases, EU MDR technical documentation, and hospital procurement databases. Bottom-up instrument placement tracking and top-down market sizing triangulated volume estimates across the analysis window.
Segmentation granularity modeled product type at the analyzer-reagent-assay level, technology at molecular-imaging-biochemical-hematology resolution, and end user through hospital-laboratory-diagnostic center-research institution taxonomy. Geographic splits applied country-level regulatory pathway efficiency and procurement concentration metrics. CAGRs derived from installed base expansion rates and consumable attachment velocity across the projection horizon. Pharmacogenomics integration pace and digital pathology algorithm adoption served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA premarket review timeline extensions or EU MDR enforcement acceleration. Forecasts reflect assumptions on reimbursement policy continuity and precision photonics supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Cardiology Genomic Testing Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
Global Hepatitis C Testing Market
Clinical Diagnostics
Pediatric Cardiac Tumor Diagnostics Market
Clinical Diagnostics
Clinical Microbiology Market
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market
Clinical Diagnostics
Clinical Chemistry Market
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Global Biomarkers Market
Clinical Diagnostics
Global Breast Cancer Screening Test Market
Clinical Diagnostics
Lactate Dehydrogenase Test Market
Clinical Diagnostics
Genetic Disease Diagnostic Market
Clinical Diagnostics
Heart Failure Testing Market