
 Illuminating Eye Massagers Market | 2026-2036
Illuminating Eye Massagers Market Size, Share, and Industry Trends Forecast 2026-2036
Illuminating Eye Massagers Market Analytics
Chinese OEM clusters in Shenzhen and Hefei are expanding contract manufacturing capacity for illuminated eye massagers with integrated LED arrays. Foreo Iris leverages Nordic design credentials and premium direct-to-consumer channels to sustain above-average price positioning. Breo anchors its competitive stance through deep specialization in TCM-inspired percussion mechanisms paired with adjustable chromotherapy settings. Panasonic competes on decades of consumer electronics brand equity and dense retail distribution across East Asian markets.
Illuminating eye massagers combine ocular percussion, thermoelectric heating, and narrow-band LED emission—typically red or near-infrared wavelengths between 620 nm and 850 nm—to mitigate periorbital tension and promote localized microcirculation. The devices serve both home-use relaxation routines and professional wellness service menus. Portable rechargeable units dominate unit economics due to lithium-ion miniaturization and cordless convenience expectations. Light therapy technology leads margin pools as wavelength specificity and irradiance calibration require tighter component sourcing. Heat therapy paired with vibration remains the largest volume category across mass-market online retail channels.
FDA classifies many illuminated eye massagers as Class I or II medical devices depending on therapeutic claims, while EU MDR and REACH constrain LED material composition and biocompatibility testing protocols. Japan's PMDA and METI enforce electrical safety and electromagnetic compatibility standards that shape export feasibility for non-domestic manufacturers. Stakeholders must monitor evolving photobiomodulation evidence thresholds that could trigger stricter ophthalmological review requirements in major jurisdictions.
Market Dynamics
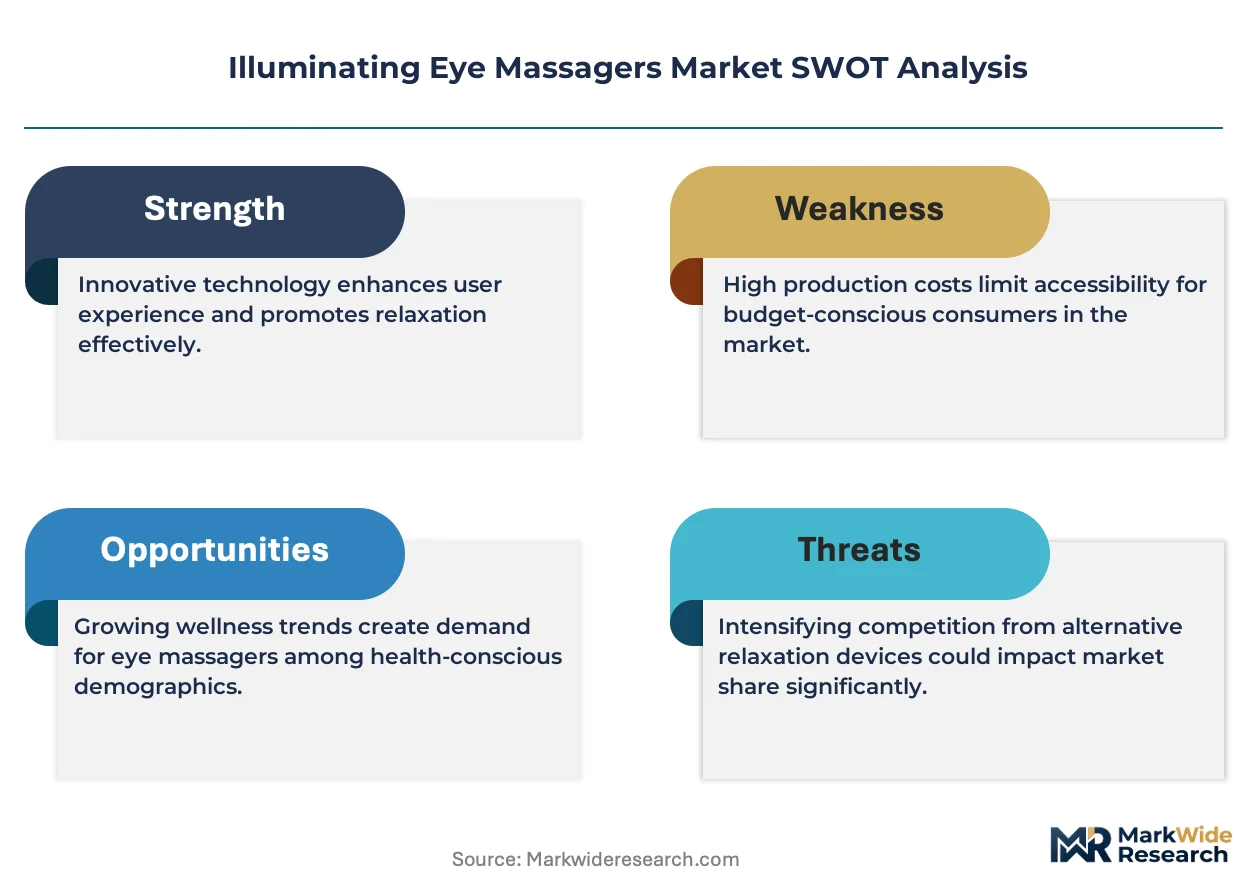
EU MDR wavelength calibration mandates and IEC 60601 electrical safety standards are compressing component sourcing flexibility while simultaneously elevating barriers for non-compliant manufacturers across wellness and medical distribution channels.
Growth Catalysts
- Photobiomodulation evidence thresholds:Accumulating clinical data on near-infrared ocular applications is expanding reimbursable indications under select national health frameworks, widening addressable patient populations.
- Japan METI efficiency standards:Stringent electromagnetic compatibility requirements for home-use electrical devices are accelerating lithium-ion miniaturization investments among contract manufacturers.
- TCM-inspired percussion mechanisms:Traditional Chinese Medicine wellness protocols are penetrating premium spa menus in Germany and South Korea, creating specification demand for adjustable chromotherapy settings.
Market Restraints
- LED die sourcing concentration:Narrow-band emitters between 620 nm and 850 nm depend on specialized foundry capacity concentrated in East Asian semiconductor clusters, exposing supply continuity risk.
- Biocompatibility testing protocols:EU REACH substance restrictions and MDR material composition rules extend certification timelines for skin-contact components by 8-14 months.
- Near-infrared lamp substitutes:Professional clinic-grade photobiomodulation panels offer higher irradiance for periorbital treatments, limiting price ceiling for portable consumer devices.
Strategic Opportunities
- Underpenetrated urban wellness corridors:Premium spa chains in São Paulo and Dubai are expanding light-therapy service menus without established local device suppliers, creating first-mover distribution windows.
- CSRD sustainability reporting:EU corporate sustainability disclosure requirements are incentivizing wellness chains to procure devices with documented circular material flows and repairable architectures.
- Convergence of percussion and transdermal delivery:Integration of microcurrent or iontophoresis functions into existing heat-vibration chassis opens aesthetic dermatology adjacent revenue streams.
Industry Challenges
- Ophthalmological review timelines:FDA Class II medical device reclassification for therapeutic claims requires clinical trial documentation that extends time-to-market by 18-30 months.
- Cross-functional talent scarcity:Engineers capable of integrating thermoelectric heating, vibration mechanics, and optical calibration within miniaturized form factors command premium compensation in Shenzhen and Hefei labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Illuminating Eye Massagers Market |
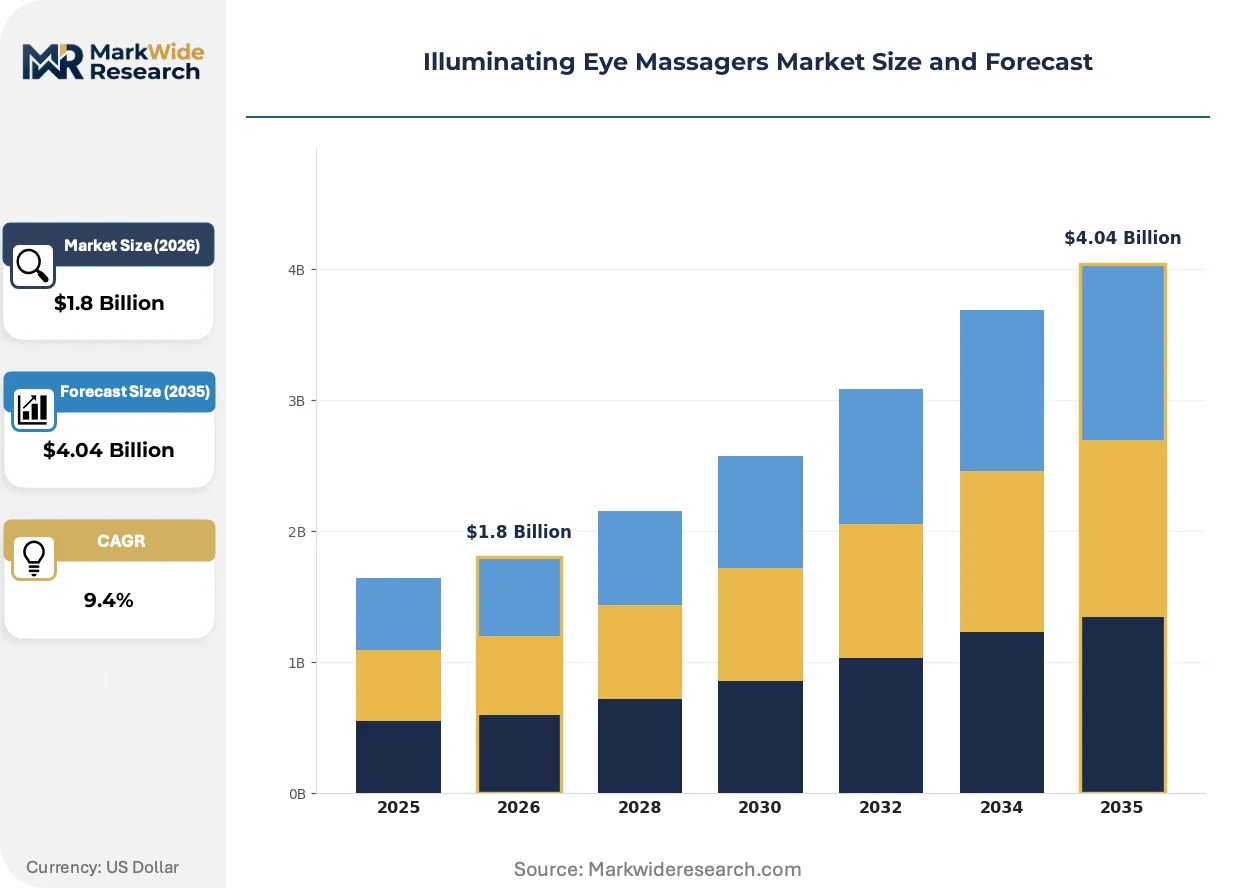
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Rechargeable, Wired, Wireless Technology: Heat Therapy, Vibration, Light Therapy, Air Pressure End User: Consumers, Retailers, Wellness Centers, Spas Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Foreo Iris, Breo, Panasonic, RENPHO, OSIM, TouchBeauty, Hefei Morningstar Healthmate Fitness Co., Ltd, Shenzhen Five Continents Technology Co., Ltd, Dielin Technology Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Illuminating Eye Massagers Market Evolving Landscape
Active reshaping of this market stems from convergence between medical-grade optical specifications and consumer electronics miniaturization trajectories, compressing development cycles while elevating performance baselines.
Multi-wavelength LED arrays with programmable irradiance curves are absorbing capital allocation from single-wavelength legacy designs. Wellness center procurement committees in Germany and South Korea now specify tunable spectral outputs as baseline requirements. This technology compression is forcing smaller OEMs to abandon proprietary optical designs in favor of licensed module integration.
EU MDR Article 10 general safety and performance requirements are tightening post-market surveillance obligations for skin-contact electrical devices. Manufacturers must now maintain technical documentation across entire product lifecycles with systematic vigilance reporting. Portable rechargeable units with therapeutic claims face the steepest compliance cost escalation, favoring larger competitors with dedicated regulatory affairs functions.
Direct-to-consumer channels are displacing traditional medical distributor networks for non-reimbursable wellness applications. Urban millennial buyers in premium corridors research wavelength specifications and irradiance data before purchase, compressing brand loyalty cycles. This behavior shift is most visible in Japan and South Korea, where social commerce platforms now dominate discovery and comparison phases for home-use relaxation devices.
Illuminating Eye Massagers Market Segmentation
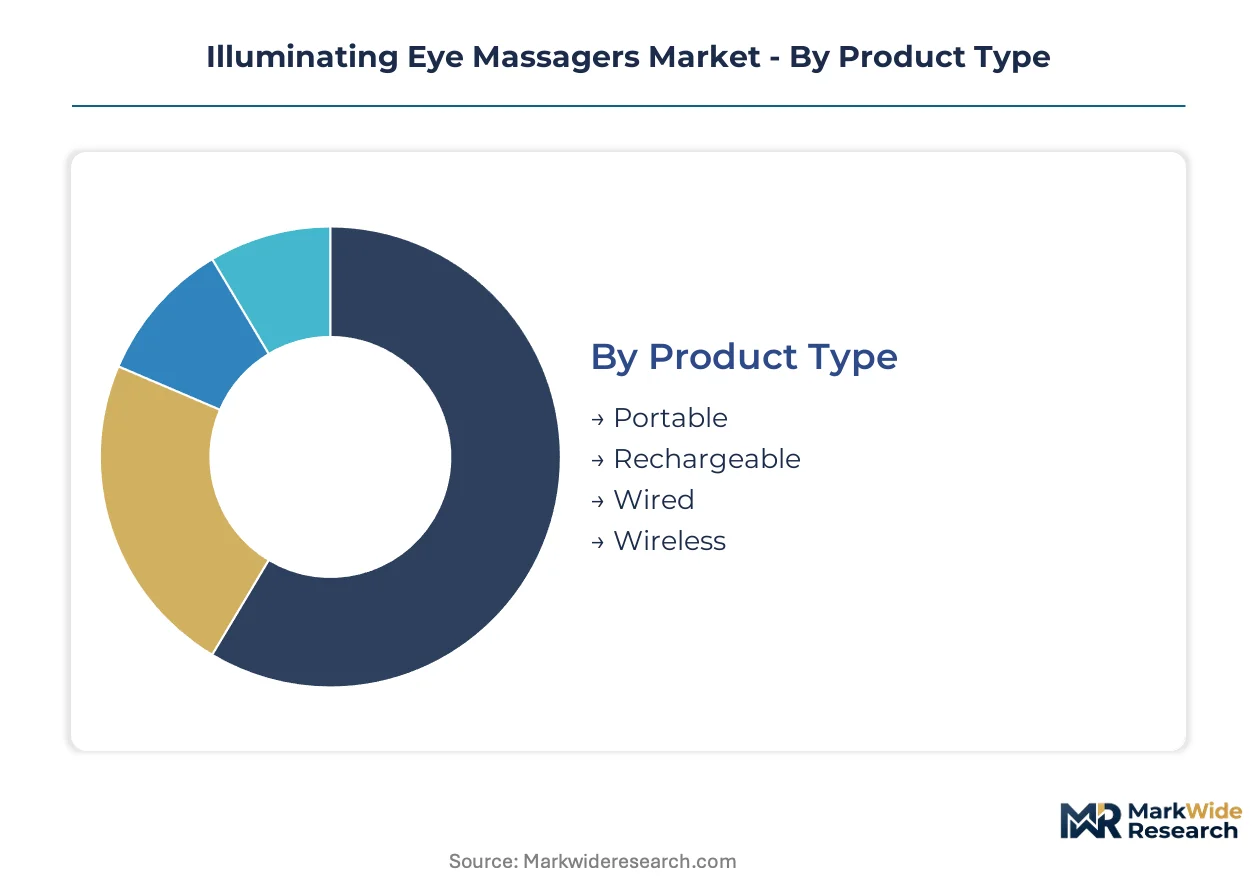
Segmentation in the Illuminating Eye Massagers Market reveals distinct procurement patterns between home-use consumers and institutional wellness operators. Technology integration depth and regulatory compliance tier determine margin architecture across each category.
Product Type:
Portable and rechargeable configurations dominate unit economics, while wired alternatives retain niche positioning in clinical settings.
- Portable:Cordless lithium-ion chassis with collapsible designs serve frequent travelers and urban commuters. Wellness chains in Germany and South Korea specify these for mobile spa menus.
- Rechargeable:Integrated battery systems with USB-C charging ports capture premium home-use demand. METI efficiency standards in Japan are compressing standby power budgets for this segment.
- Wired:AC-powered units with uninterrupted irradiance output serve professional photobiomodulation protocols. IEC 60601 electrical safety compliance is mandatory for clinic deployment.
- Wireless:Bluetooth-enabled devices with app-controlled wavelength programming target tech-forward millennials. Shenzhen OEM clusters are expanding capacity for this integration-heavy format.
Mature deployment sits with Rechargeable. Newer deployment is concentrated in Wireless.
Technology:
Heat-vibration combinations anchor mass-market volume, while light therapy commands premium positioning through wavelength specificity.
- Heat Therapy:Thermoelectric heating elements between 38°C and 42°C target periorbital tension relief. EU MDR biocompatibility testing extends certification timelines for skin-contact thermal components.
- Vibration:Percussion motors with adjustable frequency profiles deliver TCM-inspired acupressure simulation. Spa procurement committees in Dubai now specify this as baseline functionality.
- Light Therapy:Narrow-band LED arrays emitting 620-850 nm wavelengths require specialized foundry sourcing. FDA Class II reclassification risk constrains therapeutic claim language.
- Air Pressure:Pneumatic compression chambers with rhythmic inflation cycles address sinus pressure and lymphatic drainage. This modality is gaining share fastest in premium urban wellness corridors.
Volume leadership belongs to Heat Therapy. Margin expansion concentrates in Light Therapy.
End User:
Consumer self-purchase patterns diverge sharply from institutional procurement specifications for durability and service integration.
- Consumers:Individual buyers researching wavelength specifications through social commerce platforms in Japan and South Korea. Direct-to-consumer channels are displacing traditional medical distributors for this segment.
- Retailers:Electronics and beauty specialty chains negotiating private-label arrangements with Shenzhen contract manufacturers. CSRD sustainability reporting requirements are filtering supplier selection criteria.
- Wellness Centers:Institutional buyers specifying multi-device fleet compatibility and centralized maintenance protocols. São Paulo chains are expanding light-therapy service menus without established local suppliers.
- Spas:Premium hospitality operators integrating devices into branded relaxation rituals. Chromotherapy adjustability is becoming a non-negotiable specification in German spa procurement.
Procurement standardization is most advanced with Wellness Centers. Specification experimentation is most visible with Spas.
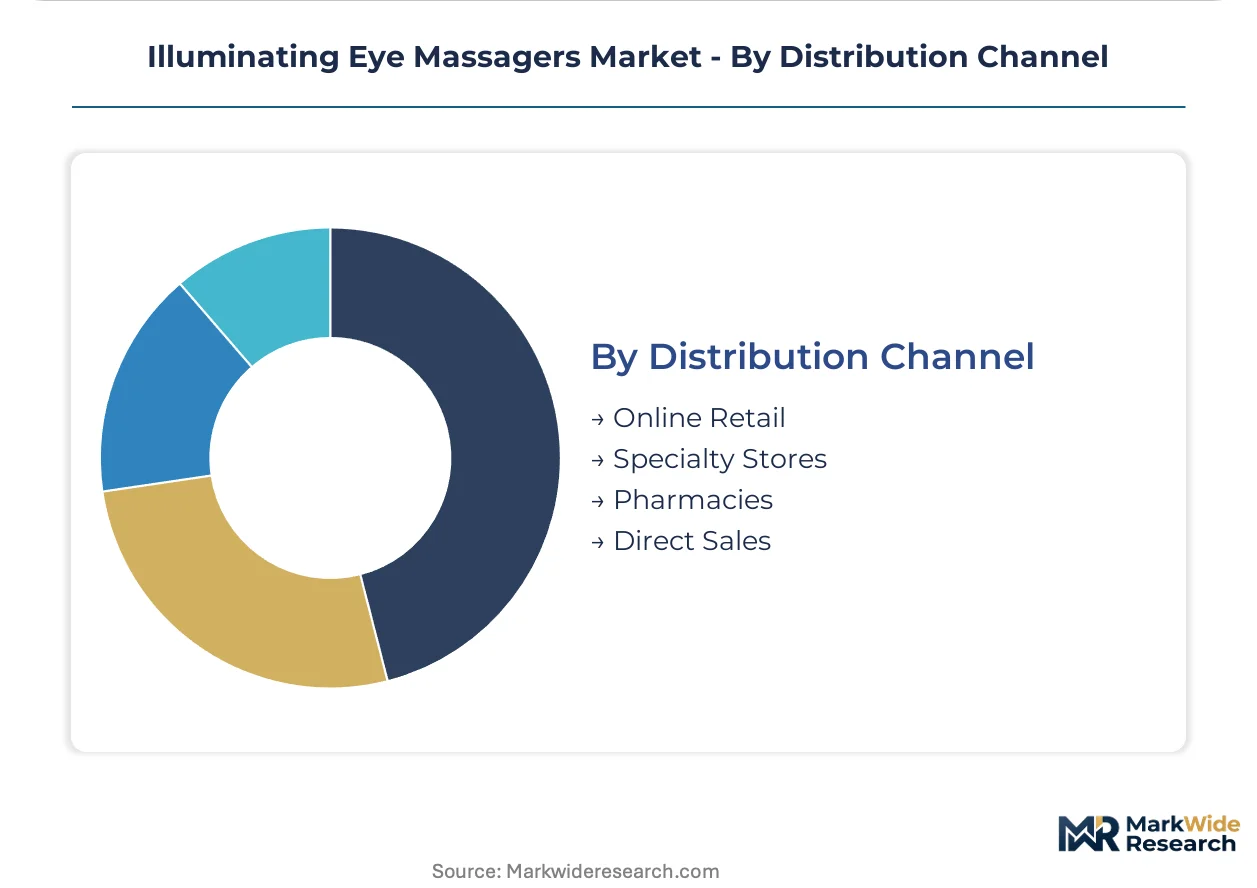
Distribution Channel:
Channel selection determines price realization and post-purchase support obligations, with digital platforms compressing traditional retail margins.
- Online Retail:E-commerce marketplaces and brand-direct storefronts capturing wavelength-literate millennial demand. Irradiance data transparency is becoming a conversion prerequisite.
- Specialty Stores:Beauty and electronics retailers offering tactile evaluation before purchase. Staff training on LED specifications varies significantly by geography.
- Pharmacies:Healthcare-positioned channels requiring FDA or national regulator registration for therapeutic claims. Reimbursement eligibility is expanding under select national health frameworks.
- Direct Sales:Wellness chain bulk procurement and corporate wellness program integrations. Relationship-based contracting favors established OEMs with dedicated regulatory affairs functions.
Channel maturity rests with Specialty Stores. Channel expansion is accelerating through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized LED die foundries in Hefei and Shenzhen anchor component supply for illuminating eye massagers, with downstream assembly clusters radiating across East Asian manufacturing corridors. Distribution networks then fan out through wellness centers in Germany, Japan, and South Korea, where regulatory stringency shapes procurement specifications.
Germany
Wellness centers in Berlin and Munich specify multi-wavelength LED arrays with tunable spectral outputs for premium spa menus. EU MDR Article 10 general safety requirements compress certification timelines for skin-contact electrical devices. Bavarian spa chains now mandate documented circular material flows under CSRD sustainability reporting obligations.
Japan
Urban millennial buyers in Tokyo and Osaka research irradiance data through social commerce platforms before purchase. METI efficiency standards enforce stringent electromagnetic compatibility and standby power budgets for home-use devices. Kanto region electronics retailers negotiate private-label arrangements with Shenzhen contract manufacturers for rechargeable chassis.
South Korea
Seoul-based wellness chains expand light-therapy service menus without established local device suppliers, creating first-mover distribution windows. MFDS and METI-aligned electrical safety protocols shape import feasibility for non-domestic manufacturers. Busan-Ulsan corridor procurement committees specify adjustable chromotherapy settings as baseline functionality.
China
Shenzhen and Hefei OEM clusters expand contract manufacturing capacity for illuminated eye massagers with integrated LED arrays. NMPA medical device classification and GB standards constrain therapeutic claim language for domestic distribution. Yangtze River Delta assembly plants face cross-functional talent scarcity for engineers integrating thermoelectric heating, vibration mechanics, and optical calibration.
United States
Direct-to-consumer channels displace traditional medical distributor networks for non-reimbursable wellness applications among wavelength-literate buyers. FDA Class I and II medical device classification depends on therapeutic claims intensity, with reclassification risk extending time-to-market. California and New York Metro wellness chains drive specification demand for portable rechargeable units with app-controlled programming.
Illuminating Eye Massagers Market Competitive Landscape
Global majors compete with regional champions across wavelength specificity and distribution channel access, producing a tiered structure where premium positioning depends on regulatory compliance depth rather than scale alone. The vendor base separates into three archetypes: Nordic design-credentialed direct-to-consumer specialists, TCM-inspired percussion mechanism fabricators, and consumer electronics conglomerates with dense retail footprints. Dominant competitive moves include strategic partnerships with wellness chains for fleet deployment and technology licensing for multi-wavelength LED module integration.
Within the design-credentialed tier, Foreo Iris occupies a position exemplifying premium direct-to-consumer channel mastery. Among East Asian specialists, Breo and OSIM represent archetypes anchoring competitive stance through deep regional wellness protocol integration. At the scale-driven end, Panasonic sits within consumer electronics brand equity accumulated across decades of retail distribution in East Asian markets. Shenzhen Five Continents Technology Co., Ltd and Hefei Morningstar Healthmate Fitness Co., Ltd exemplify contract manufacturing capacity expansion in Chinese OEM clusters.
| Leading Market Players |
|---|
| Foreo Iris |
| Breo |
| Panasonic |
| RENPHO |
| OSIM |
| TouchBeauty |
| Hefei Morningstar Healthmate Fitness Co., Ltd |
| Shenzhen Five Continents Technology Co., Ltd |
| Dielin Technology Co., Ltd |
| Others |
Value Network & Pricing Analysis
Lithium carbonate price indices cascading from Qinghai and Sichuan extraction hubs transmit directly into rechargeable chassis cost structures, compressing margin pools for mid-tier OEMs while amplifying pricing power among vertically integrated manufacturers with captive cell supply.
Pricing Analysis
Warranty bundling separates premium positioning from unbundled economy tiers, with EU MDR-compliant service documentation commanding substantial markups over bare-device transactional pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales coverage depth. Cost compression in the mid-tier is intensifying because Shenzhen contract manufacturers are absorbing lithium-ion volatility rather than passing through. Wellness center procurement committees exhibit lowest price sensitivity, while individual consumers on social commerce platforms demonstrate highest elasticity.
Supply Chain Analysis
Narrow-band LED die supply rests on specialized foundry capacity concentrated in Taiwan, South Korea, and Japan, with epitaxial wafer sourcing feeding from III-V semiconductor clusters. Thermoelectric heating elements, lithium-ion cells, and precision vibration motors constitute critical component dependencies. Single-source vulnerability in 850 nm near-infrared emitters exposes continuity risk given limited qualified suppliers. Distribution runs through wellness chain direct procurement and e-commerce marketplaces, bypassing traditional medical distributor networks for non-reimbursable applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized LED foundry capacity constraints prop pricing power for compliant manufacturers, as wavelength-specific epitaxial wafer supply fails to match downstream device demand expansion.
For Market Incumbents: Deepen regulatory affairs investment to compress EU MDR certification timelines before Article 10 vigilance obligations escalate compliance costs. Secure multi-year LED die offtake agreements with Hsinchu and Seoul foundries to lock input pricing against foundry concentration risk. Prioritize backward integration into thermoelectric heating element production to defend margin position against component cost volatility. For New Entrants and Emerging Players: Launch via direct-to-consumer social commerce channels targeting wavelength-literate millennials in São Paulo and Dubai wellness corridors where established supplier relationships remain absent. Prioritize app-controlled wireless formats with programmable irradiance curves to differentiate from legacy single-wavelength designs. White-space concentration sits with premium spa chains seeking chromotherapy-adjustable fleet deployments without incumbent vendor lock-in. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap OEMs with dormant EU MDR technical documentation in Germany and South Korea, where certification investment gaps create acquisition discounts against compliant peers. Long-term viability hinges on circular material flow documentation under CSRD sustainability reporting obligations. Watch for FDA Class II reclassification announcements as inflection indicators for therapeutic claim expansion or restriction.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-wavelength LED Module Licensing | Technology compression forces smaller OEMs toward licensed optical designs from Hefei and Shenzhen specialists. |
| EU MDR Technical Documentation Investment | Systematic vigilance reporting obligations favor competitors with dedicated regulatory affairs functions in Berlin and Munich. |
| Wellness Chain Fleet Deployment Partnerships | Bulk procurement relationships with São Paulo and Dubai spa operators secure volume commitments ahead of competitor entry. |
| Circular Material Flow Certification | CSRD sustainability reporting requirements filter supplier selection criteria for Bavarian and Seoul wellness chains. |
| App-Controlled Wavelength Programming | Bluetooth-enabled irradiance customization targets tech-forward millennial demand in Tokyo and Osaka social commerce channels. |
Research Methodology
Multi-period observation of LED die pricing, lithium-ion cell capacity utilization, and EU MDR certification timeline data anchored the trend analysis, supplemented by interviews with wellness center procurement directors, spa operations managers, contract manufacturing executives, and biomedical engineers specializing in photobiomodulation. Primary fieldwork drew from hospital purchasing committees and GPO contracts managers evaluating therapeutic device reimbursement eligibility. Secondary validation incorporated FDA 510(k) filings, EU MDR technical documentation databases, METI efficiency standard disclosures, and customs records tracking component flows through Shenzhen and Hefei export corridors. Bottom-up unit economics modeling triangulated against top-down market sizing from wellness service revenue attribution.
Segment-weighting across product type, technology modality, end-user archetype, and distribution channel dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from fitted growth curves applied to rechargeable and wireless format adoption trajectories, with wavelength-specific irradiance calibration premiums and TCM-inspired percussion mechanism integration rates serving as industry-specific forecast inputs.
Photobiomodulation evidence threshold revisions, LED die foundry capacity expansion delays, and FDA Class II reclassification decisions are the dominant revision risks warranting ongoing watch. Forecasts reflect documented assumptions regarding regulatory stability and component supply continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Viscosupplementation Market
Medical Devices
Wearable Pulse Oximeters Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Facial Implant Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Asia-Pacific Medical Aesthetic Devices Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
Dosage Unit Sampling Apparatus Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Cheek Implants Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
China General Surgical Devices Market