
 Digital Flexible Ureteroscopes Market | 2026-2036
Digital Flexible Ureteroscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Flexible Ureteroscopes Market Insights
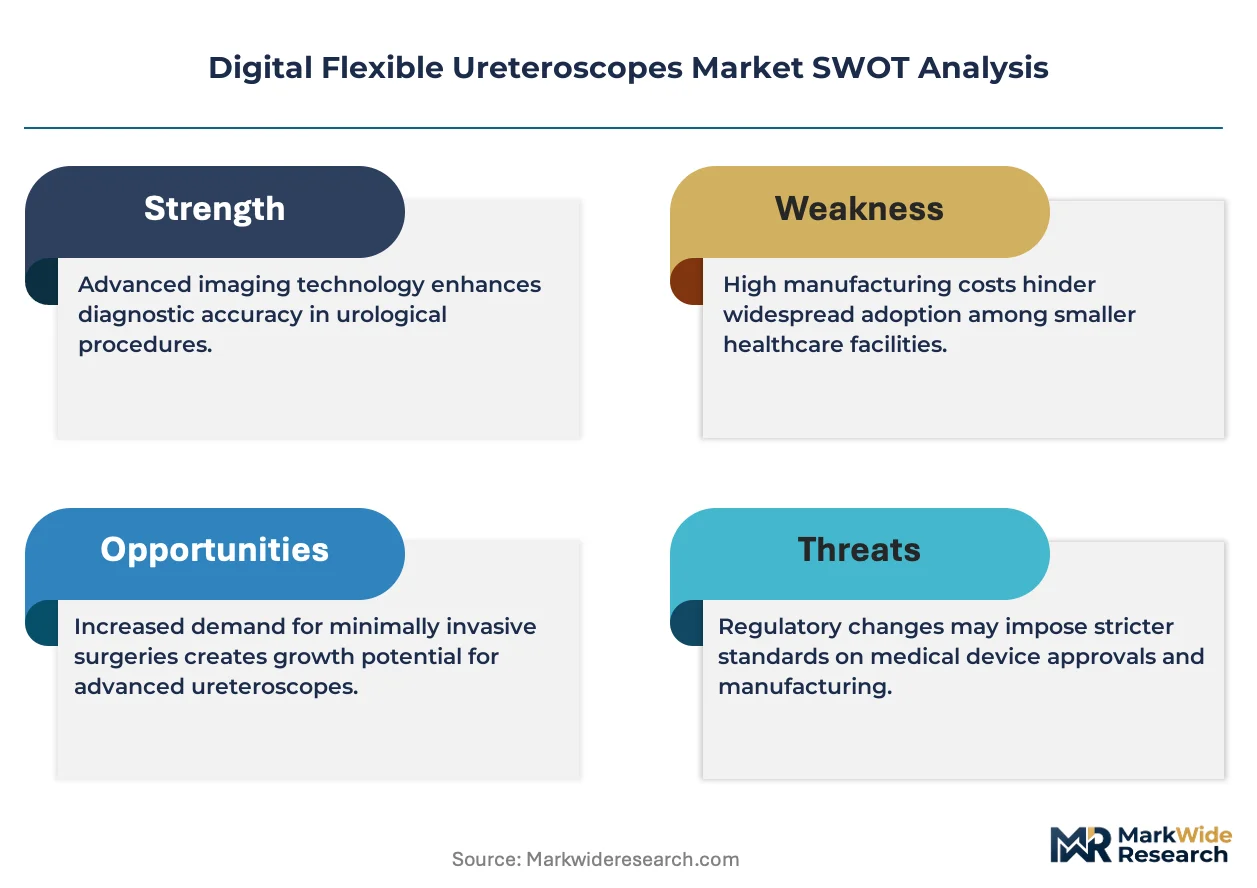
Buyer concentration among hospital procurement networks is repositioning vendor relationships across the digital flexible ureteroscopes landscape. Olympus leverages its integrated imaging ecosystem to sustain service contracts with large health systems. Boston Scientific competes through specialized lithotripsy-compatible scope designs that anchor its presence in high-volume stone centers. Karl Storz dominates the premium manual-flexion segment, where German engineering standards command sustained pricing power.
A digital flexible ureteroscope employs a distal CMOS or CCD sensor mounted on an actively deflectable insertion tube, typically 2.8–3.6 mm in outer diameter, transmitting high-definition video to an external processor for visual navigation of the upper urinary tract during minimally invasive diagnosis and intervention. Digital imaging platforms now lead technology adoption as hospitals retire fiberoptic inventories, while stone removal applications occupy the largest procedure volume share and generate the most recurring instrument demand across installed bases.
FDA 510(k) clearances and EU MDR conformity assessments shape product launch timelines and clinical evidence requirements for digital ureteroscope manufacturers entering Western markets. ISO 13485 quality management standards and Japan's PMDA device registration further govern market access across major economies. Stakeholders must monitor how reimbursement shifts toward outpatient settings reshape capital equipment purchasing cycles and service contract structures.
Market Dynamics
Hospital procurement consolidation into integrated delivery networks is compressing vendor margins and forcing scope manufacturers to bundle imaging processors with service contracts. This structural concentration favors suppliers with full-stack urology platforms over standalone device vendors.
Growth Catalysts
- EU MDR streamlined pathways:The European Medical Device Regulation's enhanced clinical evidence requirements are accelerating post-market surveillance adoption, which drives replacement demand for digitally traceable instrument platforms.
- Ambulatory surgical centers:Freestanding stone centers in Germany and the United States are expanding ureteroscopy service lines, creating pull-through demand for portable digital imaging stacks.
- CMOS sensor miniaturization:Advances in complementary metal-oxide semiconductor fabrication are enabling sub-3mm distal chip assemblies with improved light sensitivity over legacy fiberoptic bundles.
Market Restraints
- Single-use polymer cost volatility:Medical-grade Pebax and polyurethane supply chains concentrate among European chemical processors, exposing manufacturers to input price swings.
- Japanese PMDA registration timelines:Extended technical documentation review periods for novel digital imaging platforms delay market entry by 18-24 months versus FDA 510(k) pathways.
- Reusable scope reprocessing liability:Hospital-acquired infection litigation risk surrounding inadequate sterilization protocols limits penetration into cost-sensitive public health systems.
Strategic Opportunities
- India's underserved tier-2 cities:Urology infrastructure gaps in secondary metropolitan markets create first-mover potential for mobile digital ureteroscopy units.
- Integrated lithotripsy-laser systems:Convergence of holmium laser fiber technology with digital navigation platforms enables single-procedure stone fragmentation and retrieval workflows.
- US Medicare ASC payment expansion:The 2024 outpatient prospective payment system update elevates reimbursement for complex ureteroscopic procedures performed outside hospital settings.
Industry Challenges
- ISO 13485 auditor capacity constraints:Certification body backlogs for quality management system recertification delay product line extensions and geographic expansion timelines.
- Legacy tower integration complexity:Digital ureteroscopes from newer vendors require proprietary video processors incompatible with installed Karl Storz and Olympus light source infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Flexible Ureteroscopes Market |
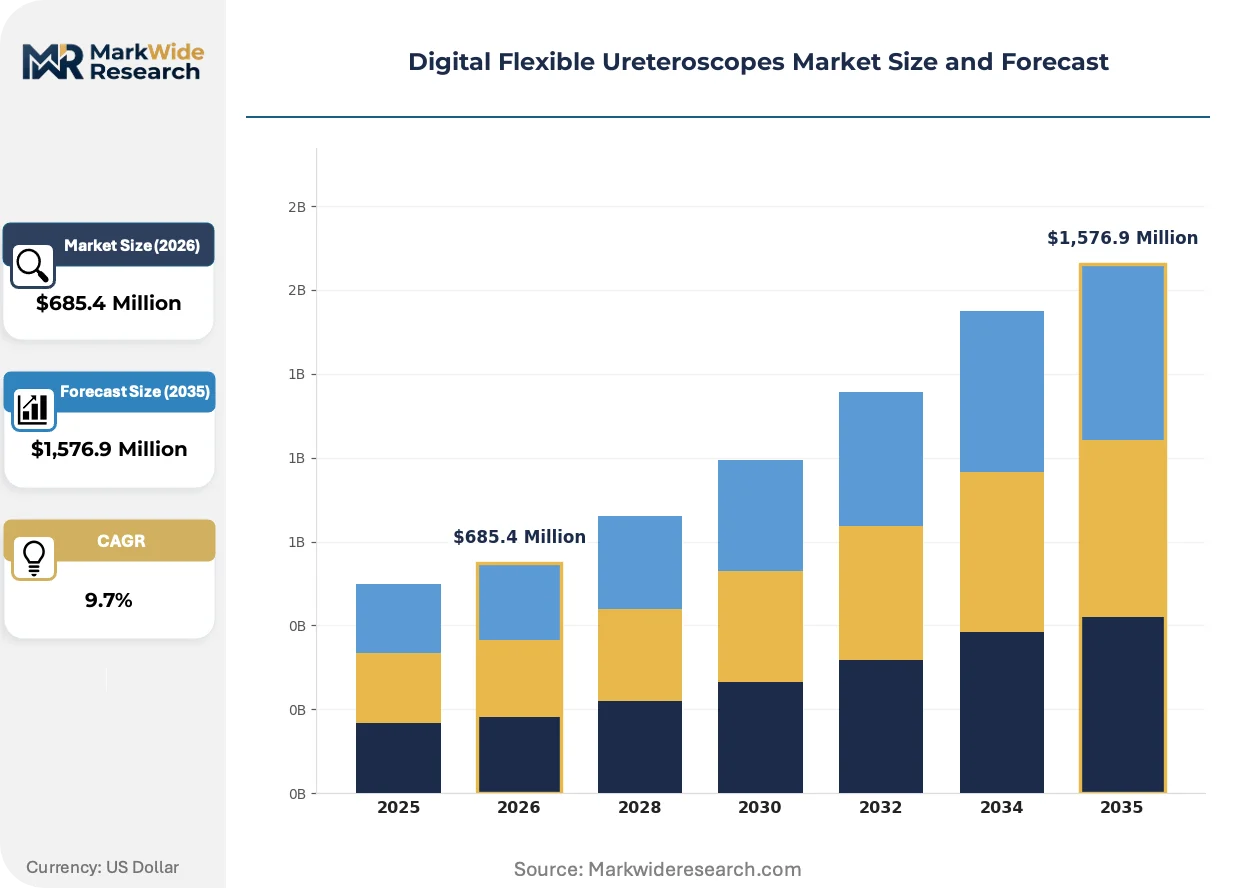
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,576.9 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-rigid Ureteroscopes, Digital Ureteroscopes, Fibreoptic Ureteroscopes, Laser Ureteroscopes End User: Hospitals, Surgical Centers, Clinics, Academic Institutions Technology: Digital Imaging, Fiber Optic Imaging, Video Ureteroscopy, Laser Technology Application: Stone Removal, Tumor Resection, Biopsy, Diagnostic Procedures |
| Companies Covered | Stryker, Vimex Endoscopy, Boston Scientific, NeoScope, Dornier MedTech, Olympus, Richard Wolf, OPCOM Medical, Karl Storz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Flexible Ureteroscopes Market Trends and Innovations
Digital imaging architectures are displacing fiberoptic transmission across the installed base, while regulatory harmonization efforts and procurement centralization reshape how manufacturers commercialize next-generation platforms.
Single-use digital ureteroscopes incorporating disposable CMOS sensor assemblies are automating reprocessing compliance burdens for high-volume stone centers. Academic medical centers in the United States and Germany are piloting these devices to eliminate cross-contamination protocols and reduce turnover time between cases. This automation is compressing the total cost-of-ownership calculus that previously favored capital-intensive reusable platforms.
The FDA's 2023 guidance on computational imaging algorithms for endoscopic devices is creating premarket submission requirements for AI-enhanced visualization features. Manufacturers must now submit algorithm training datasets and performance validation studies alongside traditional biocompatibility and electrical safety documentation. High-volume stone centers seeking competitive differentiation through image enhancement capabilities face extended procurement cycles as vendors navigate these evidentiary thresholds.
Health system procurement committees are consolidating ureteroscope purchasing into multi-year capital equipment agreements that bundle scopes, processors, and maintenance services. Independent urology practices and smaller community hospitals find themselves excluded from these negotiated rate structures, forcing migration toward third-party equipment leasing channels. This concentration is most pronounced in the United States, where hospital network mergers have reduced the number of independent purchasing decision-makers by over one-third since 2019.
Digital Flexible Ureteroscopes Market Segmentation
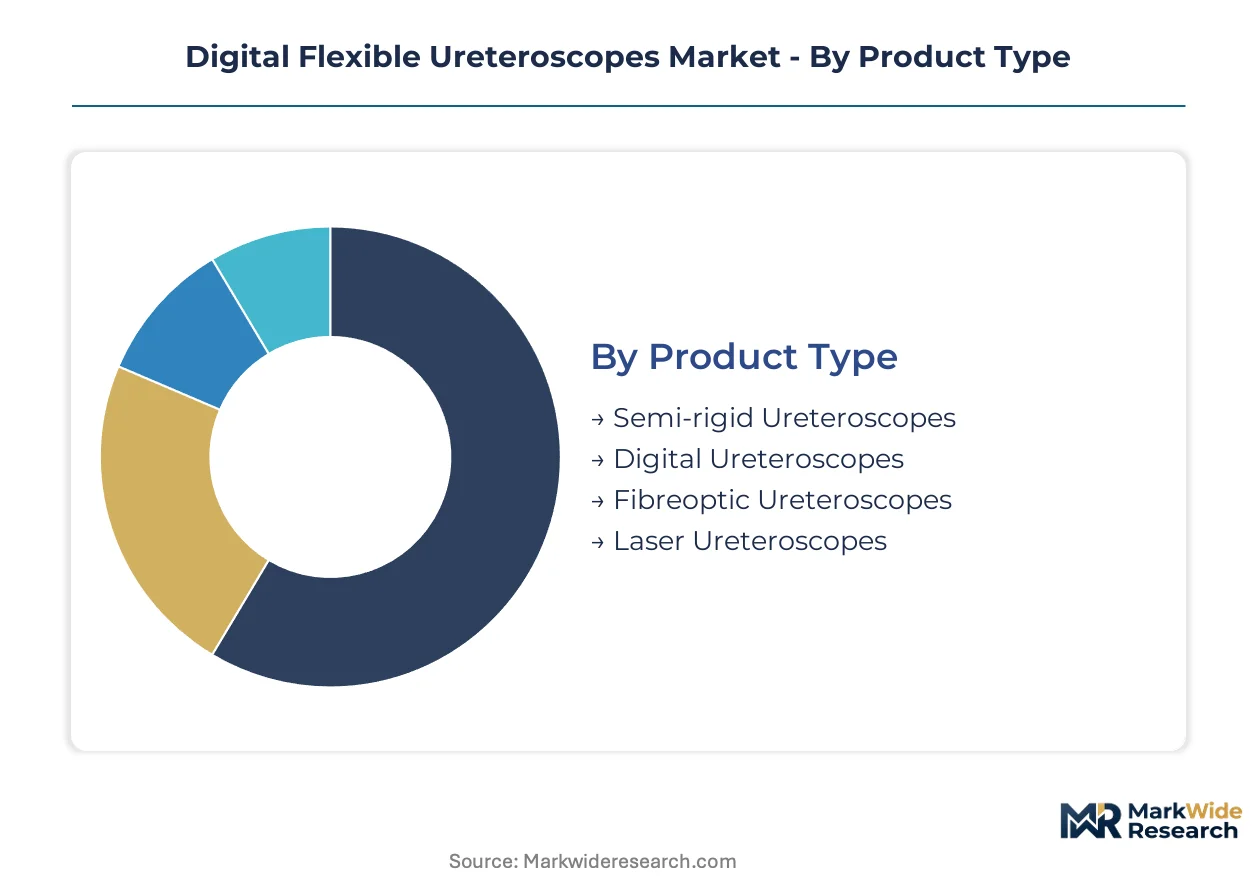
Segmentation in the digital flexible ureteroscopes market reveals how procurement priorities diverge across care settings and procedure types. Buyers select platforms based on reprocessing economics, imaging fidelity requirements, and compatibility with existing surgical infrastructure.
Product Type:
Cost tier differentiation separates capital-intensive reusable platforms from disposable alternatives and legacy fiberoptic systems.
- Digital Ureteroscopes:These devices integrate distal CMOS sensors with active deflection mechanisms, delivering high-definition visualization without fiberoptic degradation. German stone centers and US academic hospitals are retiring fiberoptic inventories fastest, driven by superior image quality and reduced maintenance burden.
- Semi-rigid Ureteroscopes:Constructed with fixed proximal shafts and limited distal articulation, these scopes address distal ureteral pathology where full flexion is unnecessary. Community hospitals in cost-sensitive markets favor them for straightforward diagnostic ureteroscopy, balancing capital constraints against procedural versatility.
- Fibreoptic Ureteroscopes:Legacy bundles of coherent glass fibers transmit images through eyepiece or camera attachment, remaining prevalent in developing markets.
- Laser Ureteroscopes:Specialized platforms with integrated holmium laser fiber channels enable single-instrument fragmentation and retrieval workflows.
Digital ureteroscopes lead volumes today; laser ureteroscopes are gaining share fastest.
End User:
Customer type determines purchasing authority complexity and service contract structures.
- Hospitals:Integrated delivery networks negotiate multi-year capital agreements bundling scopes, processors, and preventive maintenance. These buyers demand ISO 13485-certified vendors with established field service organizations across multiple states or regions.
- Surgical Centers:Freestanding ambulatory facilities prioritize single-use platforms that eliminate reprocessing infrastructure and turnover delays. Germany's reimbursement environment supports premium digital placement in these settings.
- Clinics:Smaller urology practices lease equipment through third-party channels excluded from health system purchasing coalitions.
- Academic Institutions:Teaching hospitals pilot AI-enhanced visualization features and disposable sensor assemblies under research protocols.
Hospitals dominate current installed base; surgical centers are expanding most quickly.
Technology:
Maturity curves separate established fiberoptic transmission from emerging digital architectures.
- Digital Imaging:CMOS and CCD sensor assemblies at the distal tip eliminate image degradation from fiber bundle fracture. FDA 510(k) clearances for next-generation platforms are compressing time-to-market for manufacturers with established quality management systems.
- Fiber Optic Imaging:Coherent fiber bundles remain in service where capital replacement cycles lag, particularly in public health systems with extended depreciation schedules.
- Video Ureteroscopy:External camera systems attached to fiberoptic or rod-lens scopes bridge legacy infrastructure toward full digital adoption.
- Laser Technology:Integrated holmium:YAG delivery systems converge fragmentation capability with navigation platforms.
Digital imaging leads current technology mix; laser integration shows steepest expansion trajectory.
Application:
Procedure volume and reimbursement intensity differentiate clinical use cases.
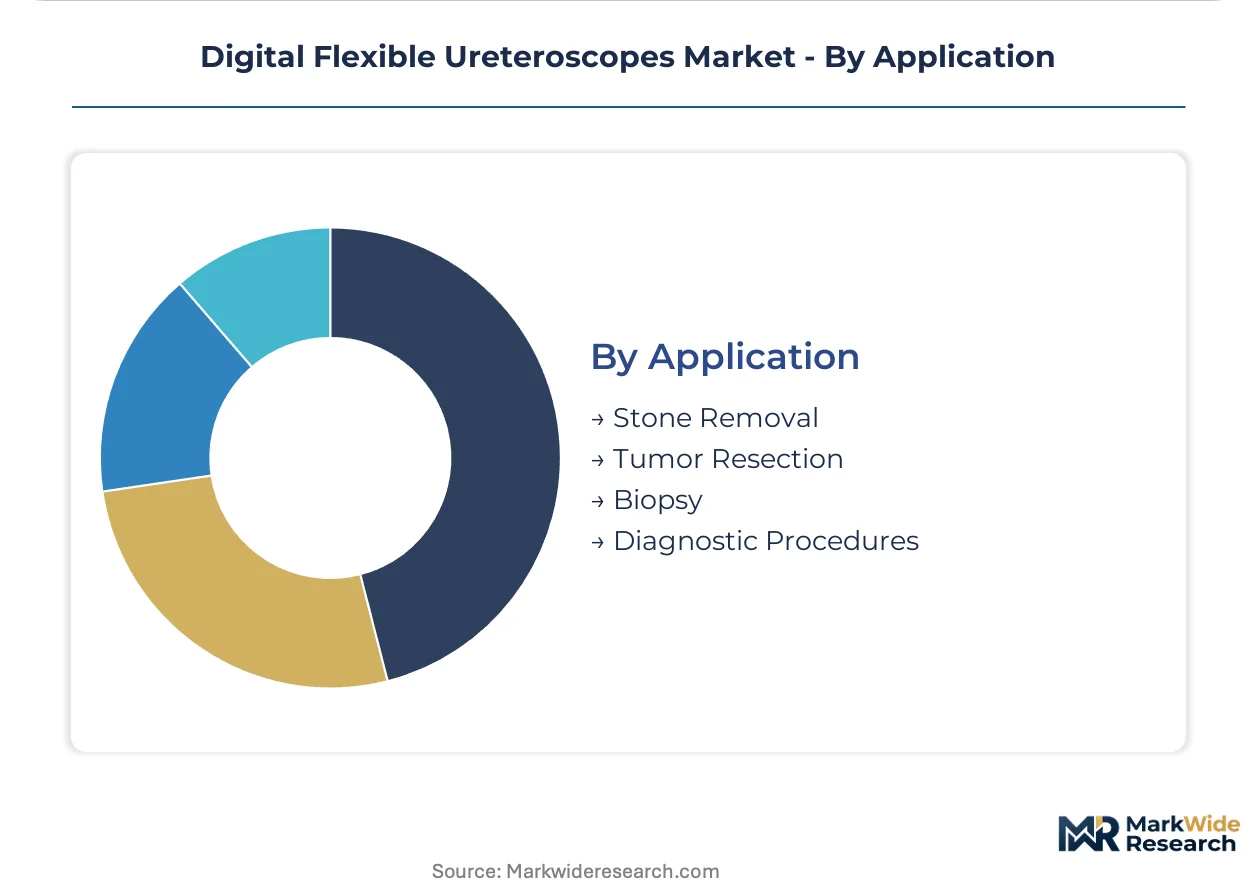
- Stone Removal:Ureteroscopy for nephrolithiasis and ureteral calculi generates the highest procedure volume and instrument utilization rates. High-volume stone centers in Germany and the United States drive recurring demand for durable flexible platforms capable of accessing the lower pole calyx.
- Diagnostic Procedures:Evaluation of hematuria, filling defects, and upper tract surveillance requires reliable visualization without therapeutic intervention. Outpatient migration of these evaluations is reshaping equipment specifications toward portable imaging stacks.
- Tumor Resection:Upper tract urothelial carcinoma management demands high-definition tissue characterization and precise instrument control.
- Biopsy:Targeted tissue acquisition for histopathological diagnosis requires compatible working channels and flexible deflection.
Stone removal leads procedure volumes today; diagnostic applications are climbing fastest as surveillance protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's reimbursement infrastructure supports premium digital ureteroscope placement faster than Japan's extended PMDA registration timelines permit market entry.
United States
Ambulatory surgical centers in Texas and Florida are expanding urology service lines under expanded Medicare ASC payment rules. FDA 510(k) clearances for digital imaging platforms compress time-to-market for next-generation devices. High-volume stone centers in Houston and Miami drive recurring demand for durable flexible platforms.
Germany
Reimbursement for minimally invasive stone procedures supports premium ureteroscope placement in Bavaria and North Rhine-Westphalia. EU MDR conformity assessments shape product launch timelines with enhanced clinical evidence requirements. Karl Storz maintains engineering and manufacturing concentration in Baden-Württemberg.
Japan
Extended PMDA technical documentation review periods delay market entry by 18-24 months versus FDA pathways. METI standards for medical device quality management govern domestic manufacturing. Tokyo and Osaka academic medical centers pilot AI-enhanced visualization features under research protocols.
India
Urology infrastructure gaps in tier-2 cities such as Pune and Jaipur create first-mover potential for mobile digital ureteroscopy units. CDSCO medical device registration requirements are streamlining for Class B and C imports. Maharashtra and Karnataka host emerging procurement networks for hospital equipment.
China
NMPA device registration timelines and GB standards for endoscopic equipment govern market access for imported digital platforms. Yangtze River Delta hospital networks are retiring fiberoptic inventories fastest among domestic markets. Shanghai medical centers demand high-definition CMOS sensor assemblies for upper tract procedures.
Digital Flexible Ureteroscopes Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the digital flexible ureteroscopes landscape. The vendor base organizes into three tiers: integrated imaging ecosystem providers, lithotripsy-compatible scope designers, and premium manual-flexion specialists. Consolidation favors suppliers with full-stack urology platforms over standalone device vendors. Dominant competitive moves include strategic partnerships bundling imaging processors with service contracts and portfolio diversification into single-use disposable platforms.
Among diversified medical technology conglomerates, Stryker and Boston Scientific occupy positions anchoring integrated surgical platform offerings. Olympus exemplifies the imaging ecosystem archetype with established service contract relationships across large health systems. Karl Storz represents the precision engineering specialist tier where German manufacturing standards command sustained pricing power in premium manual-flexion segments.
| Leading Market Players |
|---|
| Stryker |
| Vimex Endoscopy |
| Boston Scientific |
| NeoScope |
| Dornier MedTech |
| Olympus |
| Richard Wolf |
| OPCOM Medical |
| Karl Storz |
| Others |
Pricing and Supply Chain Analysis
Integrated delivery network procurement committees now dominate capital equipment purchasing, compressing vendor margins and forcing bundled service-contract pricing models across the digital flexible ureteroscopes landscape. This buyer concentration shifts pricing power toward health systems with multi-year capital agreements covering scopes, processors, and preventive maintenance.
Pricing Analysis
Capacity additions in China's CMOS sensor fabrication plants are reshaping price floors for distal chip assemblies, enabling cost compression in mid-tier digital ureteroscope offerings. Three-tier pricing structure across premium, standard, and economy levels separates Karl Storz and Olympus flagship platforms from Boston Scientific's lithotripsy-compatible designs and emerging single-use alternatives. Pricing pressure stems from ambulatory surgical center migration toward disposable platforms that eliminate reprocessing infrastructure costs. Public health systems in India and Southeast Asia exhibit highest price sensitivity, while German stone centers demonstrate lowest sensitivity due to procedure-based reimbursement adequacy.
Supply Chain Analysis
Medical-grade Pebax and polyurethane supply rests on German and Belgian specialty chemical producers, with CMOS sensor fabrication concentrated in Taiwan, South Korea, and Japan. Distal chip assemblies, laser fiber channels, and active deflection mechanisms constitute critical component dependencies. Single-source vulnerability in European polymer supply chains exposes manufacturers to input price volatility and regulatory restriction cascades under EU MDR traceability requirements. Distribution runs through health system procurement networks, third-party equipment leasing channels for independent practices, and direct hospital sales organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's extended PMDA registration timelines create a 18-24 month cost and speed-to-market arbitrage versus FDA 510(k) pathways, rewarding manufacturers with established quality management systems and multi-territory regulatory expertise.
For Market Incumbents: Cement service contract relationships with integrated delivery networks by bundling imaging processors with preventive maintenance and software upgrade pathways. Deepen backward integration into CMOS sensor sourcing through strategic partnerships with Taiwanese fabrication facilities. Defend against single-use disposable entrants by emphasizing total cost-of-ownership advantages in high-volume stone centers and leveraging ISO 13485 certification as a procurement barrier. For New Entrants and Emerging Players: The premium-to-economy price gap in India's tier-2 cities offers first-mover positioning for mobile digital ureteroscopy units with simplified imaging stacks. Target ambulatory surgical centers in Texas and Florida seeking to eliminate reprocessing liability under expanded Medicare reimbursement. Pursue CDSCO registration in Maharashtra and Karnataka to establish early procurement network relationships before hospital consolidation accelerates. For Investors and Strategic Acquirers: Diversified medical technology conglomerates are the most active acquirer in this space, seeking full-stack urology platform capabilities. Long-term viability hinges on convergence between digital navigation and holmium laser integration, with single-use sensor technology representing a structural shift rather than cyclical substitution. Watch FDA 510(k) clearance velocity for AI-enhanced visualization features as an inflection indicator for competitive differentiation and extended procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment | Accelerates post-market surveillance adoption and digitally traceable instrument platform replacement demand across German stone centers. |
| CMOS Sensor Miniaturization | Enables sub-3mm distal chip assemblies with improved light sensitivity, displacing legacy fiberoptic bundles in academic medical centers. |
| Single-Use Platform Development | Automates reprocessing compliance burdens for high-volume ASCs, compressing total cost-of-ownership calculus versus reusable platforms. |
| Integrated Lithotripsy-Laser Systems | Converges holmium:YAG fiber technology with digital navigation for single-procedure stone fragmentation and retrieval workflows. |
| Hospital System Partnership | Secures multi-year capital equipment agreements bundling scopes, processors, and maintenance services amid procurement consolidation. |
Research Methodology
Multiple input streams — primary interviews with urologists and hospital purchasing committees, secondary validation through FDA 510(k) filings and CMS Medicare data, and trade analysis of CMOS sensor and polymer supply chains — were reconciled to construct market estimates. Stakeholder interviews encompassed biomedical engineers, GPO contracts managers, ambulatory surgical center administrators, and regulatory affairs leads at device manufacturers. Secondary sources included hospital procurement databases, EU MDR conformity assessment records, and PMDA registration documentation. Bottom-up procedure volume modeling and top-down capital equipment spending analysis were cross-referenced for triangulation.
Historical shipment data was cross-referenced against panel input from procurement executives and service contract managers to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type tier, end-user facility category, technology architecture, and application procedure volume. CAGRs were derived from instrument replacement cycle analysis and installed base expansion patterns. Forecast inputs incorporated reimbursement policy shifts toward outpatient settings and regulatory pathway differential timelines between FDA and PMDA.
Caveats apply where reimbursement code revisions, supply chain disruptions in European polymer processing, or accelerated single-use platform adoption could materially shift the outlook. Forecasts reflect assumptions regarding health system consolidation velocity and ASC payment expansion sustainability. A small set of named triggers — EU MDR auditor capacity constraints, Japanese PMDA documentation review periods, and CMOS sensor fabrication capacity allocation — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Portable OT Light Market
Medical Devices
Leadless Cardiac Pacemaker Market
Medical Devices
Orthodontic Retainers Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Europe Incontinence Devices and Ostomy Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Airway Management Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
Memory Implants Market
Medical Devices
Water Bath Vaporizer Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Syringeless Injector Market
Medical Devices
Insulin Storage Devices Market
Medical Devices
Homecare Medical Devices Market