
 Laryngoscopes Market | 2026-2036
Laryngoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Laryngoscopes Market Analysis
China is tilting toward domestic laryngoscope manufacturing capacity as local medtech clusters scale precision optical and digital imaging capabilities. Medtronic leverages its integrated airway portfolio to sustain hospital system contracts across North America and Western Europe. Ambu A/S anchors the single-use segment through controlled polymer supply chains and sterilization-free value propositions that reduce cross-contamination risk in operating theaters.
A laryngoscope is a medical instrument designed to visualize the larynx and vocal cords, typically incorporating a handle, blade, and light source with specifications ranging from Macintosh curved blades to fiber-optic or CMOS-based video systems for indirect visualization during airway management. Its primary commercial purpose centers on enabling orotracheal intubation, diagnostic laryngoscopy, and emergency airway access across anesthesia, critical care, and prehospital settings. Video laryngoscopes command premium positioning due to superior glottic visualization and reduced failed intubation rates, while flexible platforms grow fastest in outpatient diagnostic assessment where patient comfort drives preference. Conventional direct laryngoscopy retains volume share in cost-constrained clinics and emergency services, though margin pools have shifted toward digital and advanced visualization technologies.
The FDA 510(k) pathway and EU MDR classification rules govern laryngoscope market access, with both frameworks intensifying biocompatibility testing and clinical evidence requirements for reusable device reprocessing validations. ISO 13485 quality management standards and IEC 60601 electrical safety protocols further shape manufacturing compliance for video and digital platforms. Stakeholders must monitor evolving reimbursement codes for single-use versus reusable platforms as payors recalibrate cost-effectiveness thresholds for airway management procedures.
Market Dynamics
Hospital procurement departments are consolidating supplier contracts around single-use video laryngoscope platforms that eliminate reprocessing liability while satisfying tightened infection control protocols in surgical suites.
Growth Catalysts
- EU MDR reprocessing mandates:Reusable device validation requirements under the Medical Device Regulation are accelerating hospital transitions to disposable blades and handles that bypass sterilization documentation burdens.
- CMOS imaging maturation:Cost reductions in complementary metal-oxide semiconductor sensors are democratizing video laryngoscope access across mid-tier emergency departments previously limited to direct visualization.
- Anesthesia workforce expansion:Training program growth in India and Southeast Asia is generating installed base demand for both conventional and video platforms as clinical education scales.
Market Restraints
- Polymer supply concentration:Medical-grade polycarbonate and ABS resin for single-use blades flows through a narrow supplier base concentrated in East Asian petrochemical corridors, exposing molders to feedstock volatility.
- Reusable blade margin compression:Stainless steel blade reconditioning services and third-party repair networks extend product lifecycles beyond OEM revenue models, compressing replacement cycle frequency.
- Direct laryngoscopy substitution ceiling:Fiber-optic bronchoscopes and supraglottic airway devices capture difficult airway scenarios that video laryngoscopes cannot resolve, capping addressable procedure expansion.
Strategic Opportunities
- Brazil outpatient surgery expansion:ANVISA regulatory streamlining for Class II devices is opening ambulatory surgical center channels where portable video platforms replace shared department equipment.
- Artificial intelligence convergence:Machine learning algorithms trained on glottic visualization databases are hybridizing with video laryngoscope outputs to provide real-time intubation guidance for novice operators.
- Subscription distribution models:Blade-and-handle per-procedure leasing arrangements are penetrating United States hospital systems seeking to convert capital equipment into operational expenditures.
Industry Challenges
- ISO 13485 auditor scarcity:Certification body capacity constraints are extending quality management system audit timelines for video platform manufacturers seeking MDR compliance.
- Legacy device interoperability:Proprietary video output formats from incumbent manufacturers resist integration with electronic health record systems and surgical documentation platforms.
- Reprocessing technician certification:Reusable video laryngoscope high-level disinfection protocols require specialized training that outpaces workforce pipeline development in rural health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laryngoscopes Market |
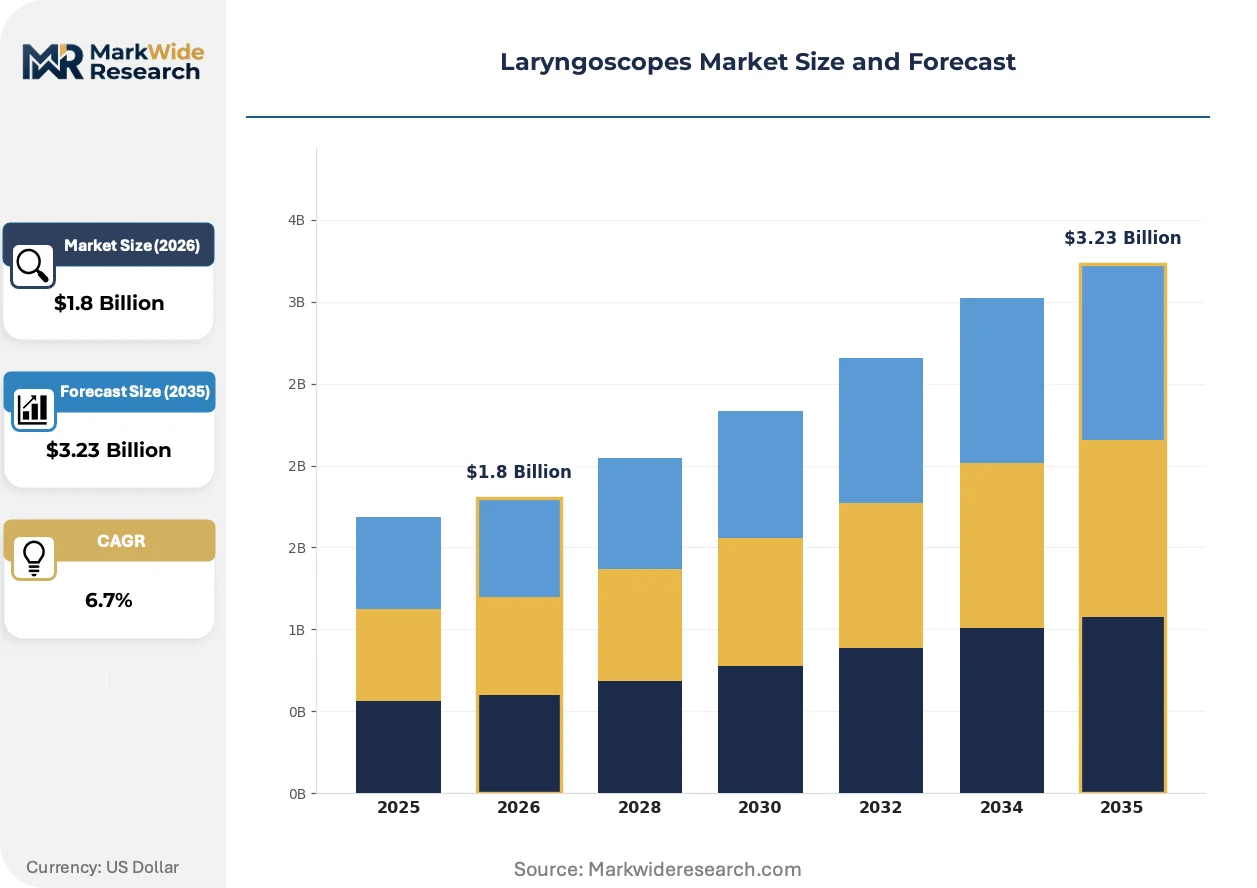
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Laryngoscopes, Flexible Laryngoscopes, Video Laryngoscopes, Optical Laryngoscopes End User: Hospitals, Surgical Centers, Emergency Services, Clinics Technology: Conventional Laryngoscopy, Digital Laryngoscopy, Telemedicine Integration, Advanced Visualization Application: Anesthesia, Emergency Intubation, Surgical Procedures, Diagnostic Assessment |
| Companies Covered | Medtronic, Ambu A/S, KARL STORZ, Olympus Corporation, Teleflex Incorporated, Verathon Inc., Prodol Meditec, Nihon Kohden Corporation, Penlon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laryngoscopes Market Emerging Trajectories
Digital visualization platforms are fragmenting the traditional laryngoscope category into specialized subsystems where imaging performance, disposability economics, and data integration capabilities determine competitive position.
Disposable video laryngoscope blades incorporating CMOS sensors and LED illumination are hybridizing the cost structure of single-use instruments with the visualization quality of reusable video platforms. Community hospitals and emergency medical services in the United States are adopting these devices at replacement rates exceeding conventional blade turnover. The technology is compressing the price-performance gap between premium reusable systems and entry-level direct laryngoscopy.
MDR Article 10 clinical evidence requirements are extending technical documentation timelines for reusable device reprocessing validations. Manufacturers must generate biocompatibility data and sterilization efficacy studies that exceed prior Medical Device Directive standards. Video laryngoscope OEMs with legacy reusable portfolios face the steepest compliance burdens in Germany and France where notified body backlogs concentrate.
Integrated health systems are unbundling airway management procurement from anesthesia machine capital cycles, creating standalone contracting vehicles for laryngoscope platforms. Group purchasing organizations in the United States are consolidating video and single-use blade contracts under single-source agreements that displace multi-vendor purchasing. This consolidation is most visible in California and Texas health systems where standardized protocols reduce training complexity across distributed facilities.
Laryngoscopes Market Segmentation
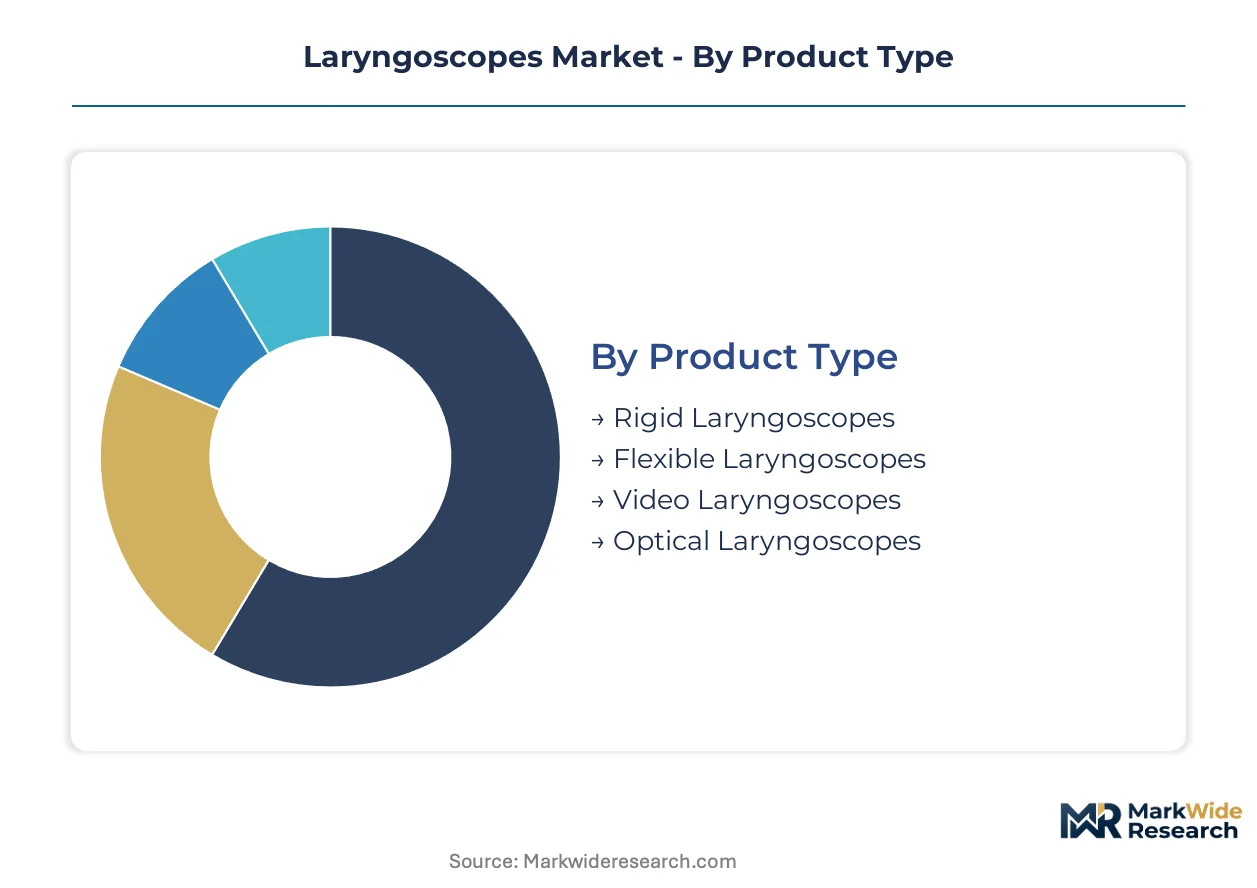
Segmentation in laryngoscopes reveals how visualization technology, procedural setting, and customer economics fragment a market where video platforms now command premium positioning while conventional blades retain volume in cost-constrained channels. Understanding these divides exposes where margin pools concentrate and which technology transitions will reshape competitive boundaries over the forecast window.
Product Type:
Cost tier separates the product landscape, with capital intensity and per-procedure economics determining hospital procurement patterns across reusable and disposable platforms.
- Video Laryngoscopes:CMOS-based systems with integrated LED illumination and high-definition displays deliver superior glottic visualization through indirect laryngoscopy. Demand concentrates in United States academic medical centers and integrated health systems standardizing on single-use blade compatibility to eliminate reprocessing liability under tightened infection control protocols.
- Rigid Laryngoscopes:Stainless steel Macintosh and Miller blades with detachable fiber-optic or bulb light sources remain the foundational platform for direct laryngoscopy training. Volume persists in India and Southeast Asia anesthesia education programs where cost barriers delay video platform adoption despite documented inferior first-pass intubation success rates.
- Flexible Laryngoscopes:Fiber-optic or video-equipped flexible platforms enable awake intubation and diagnostic laryngoscopy in outpatient otolaryngology settings.
- Optical Laryngoscopes:Prism-based indirect visualization systems occupy a narrowing niche between direct and video platforms in mid-tier European hospitals.
Video platforms command the established base. The steepest expansion runs through flexible platforms capturing ambulatory diagnostic volume.
End User:
Customer type dictates purchasing authority, capital allocation cycles, and the trade-off between acquisition cost and total cost of ownership that shapes platform selection.
- Hospitals:Operating theaters, intensive care units, and emergency departments with dedicated anesthesia services generate the highest procedure density and platform standardization potential. United States health systems leverage group purchasing organization contracts to consolidate video and single-use blade procurement under single-source agreements spanning distributed facilities.
- Emergency Services:Prehospital airway management by paramedic and critical care transport teams demands portable, battery-operated platforms with rapid deployment characteristics. CMOS sensor cost reductions are democratizing video laryngoscope access in municipal emergency medical services previously constrained to direct laryngoscopy.
- Surgical Centers:Ambulatory facilities performing short-stay procedures prioritize disposable blades to avoid sterilization infrastructure investment.
- Clinics:Primary care and specialty clinics handle limited intubation scenarios with conventional direct laryngoscopy platforms.
Hospitals anchor procurement volume. Surgical centers represent the fastest-climbing trajectory as outpatient migration accelerates blade-and-handle leasing arrangements.
Technology:
Maturity of underlying imaging and connectivity architectures determines where clinical evidence requirements, regulatory pathways, and reimbursement negotiations concentrate compliance investment.
- Digital Laryngoscopy:CMOS sensor-based video platforms with onboard recording and wireless image transmission enable quality assurance documentation and telemedicine consultation. FDA 510(k) premarket notification pathways and EU MDR technical documentation requirements are extending certification timelines for manufacturers seeking to validate reprocessing protocols or demonstrate single-use equivalency.
- Conventional Laryngoscopy:Direct visualization through Macintosh or Miller blades with incandescent or LED illumination persists where capital constraints outweigh visualization quality demands. Stainless steel blade reconditioning services and third-party repair networks extend product lifecycles beyond original equipment manufacturer replacement revenue models.
- Telemedicine Integration:Real-time video streaming to remote consultants for difficult airway management guidance is penetrating rural United States health systems facing anesthesiologist coverage gaps.
- Advanced Visualization:Augmented reality overlays and artificial intelligence algorithms trained on glottic visualization databases remain in clinical validation phases.
Conventional platforms hold the installed base. Digital systems are gaining share fastest as CMOS economics compress price-performance gaps.
Application:
Procedural urgency and airway complexity determine performance requirements, operator training levels, and the acceptable trade-off between speed of deployment and visualization quality.
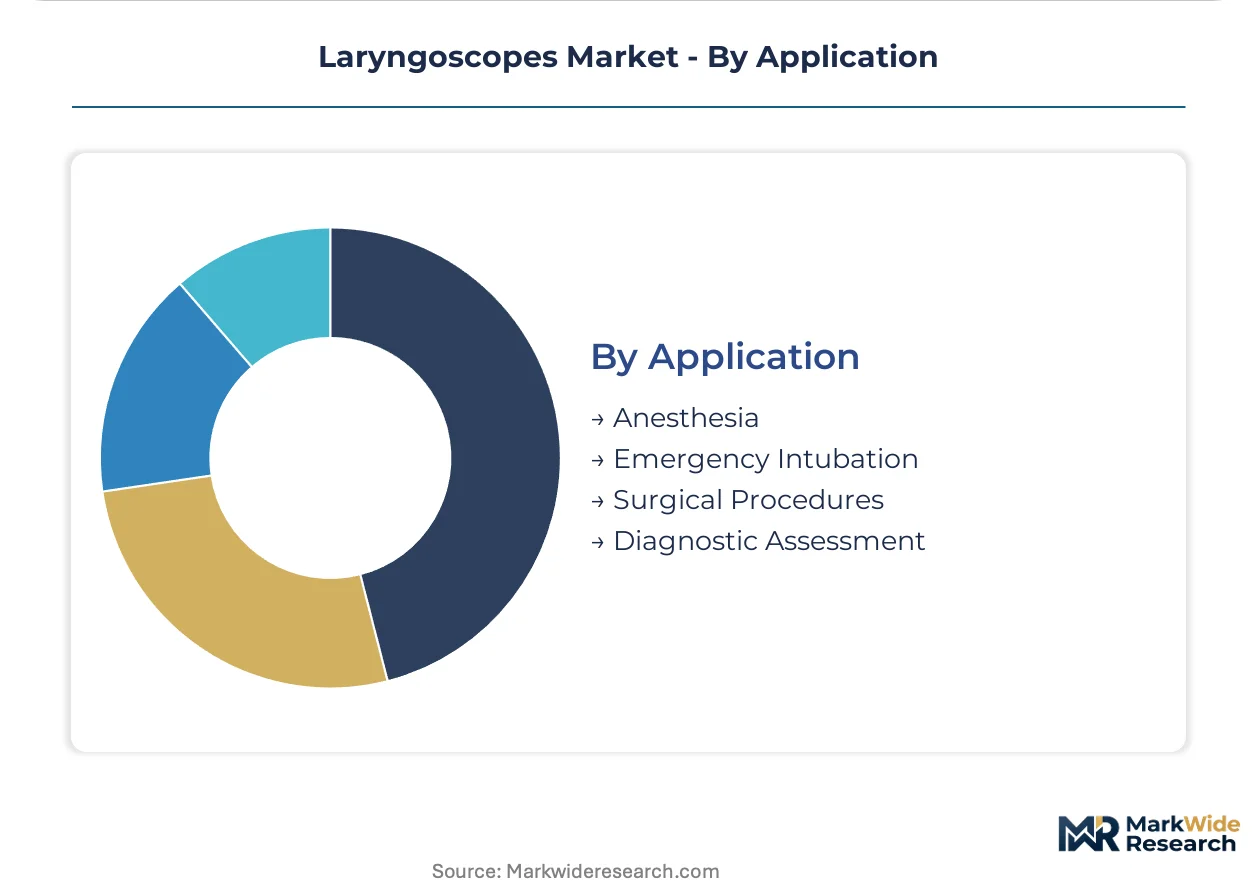
- Anesthesia:Elective surgical intubation in controlled operating theater environments permits platform selection based on anticipated difficulty and operator preference. Integrated health systems in California and Texas are standardizing video platforms across anesthesia departments to reduce training complexity and credentialing variation.
- Emergency Intubation:Time-critical airway access in cardiac arrest, trauma, or respiratory failure scenarios prioritizes first-pass success and rapid sequence intubation compatibility. Single-use video laryngoscope blades are displacing conventional metal blades in United States emergency departments seeking to eliminate cross-contamination risk and sterilization documentation burdens.
- Surgical Procedures:Shared airway cases in head and neck surgery require specialized rigid or flexible platforms with integrated suction capabilities.
- Diagnostic Assessment:Outpatient laryngoscopy for hoarseness, dysphonia, or vocal cord evaluation favors flexible platforms with topical anesthesia tolerance.
Anesthesia commands procedure volume. Emergency intubation is climbing fastest as prehospital video platform deployment expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) premarket notification requirements anchor the United States as the dominant geography, where integrated health systems drive standardization toward video-enabled and single-use platforms across anesthesia and emergency departments.
United States
Hospital procurement consolidation accelerates around blade-and-handle leasing arrangements that convert capital equipment into operational expenditures. FDA premarket notification pathways under 510(k) extend certification timelines for reusable device reprocessing validations. Texas and California health systems standardize video laryngoscope protocols across distributed facilities to reduce training complexity.
Germany
Notified body backlogs under EU MDR Article 10 concentrate compliance burdens for manufacturers with legacy reusable portfolios. The Medical Device Regulation intensifies biocompatibility testing and sterilization efficacy documentation requirements. Bavarian medical device clusters scale precision optical manufacturing for CMOS-based video platforms.
China
Domestic medtech clusters expand precision optical and digital imaging capabilities as local manufacturing capacity scales. NMPA regulatory pathways govern Class II device market access for video laryngoscope platforms. Yangtze River Delta precision manufacturing hubs advance CMOS sensor integration for cost-competitive video systems.
India
Anesthesia training program expansion generates installed base demand for both conventional and video platforms as clinical education scales. CDSCO medical device regulations shape import and domestic manufacturing compliance for airway management equipment. Maharashtra medical device corridors attract contract manufacturing for single-use blade molders.
Brazil
ANVISA regulatory streamlining for Class II devices opens ambulatory surgical center channels where portable video platforms replace shared department equipment. Outpatient surgery expansion drives preference for disposable blades that avoid sterilization infrastructure investment. São Paulo surgical centers lead adoption of subscription-based blade procurement models.
Laryngoscopes Market Vendor Landscape
Diversified medtech conglomerates and specialized airway device manufacturers split the market into distinct capability tiers. Consolidation pressures intensify as integrated health systems demand single-source contracting for video and disposable blade portfolios. Two strategic archetypes dominate: full-spectrum airway platform vendors with anesthesia machine integration capabilities, and focused single-use specialists leveraging polymer supply chain control. Competitive moves center on M&A to acquire CMOS imaging competencies and capacity expansion into East Asian mold tooling partnerships.
Within the diversified medtech tier, Medtronic and Olympus Corporation exemplify full-spectrum platform strategies that bundle laryngoscope offerings with broader anesthesia and surgical portfolios. Ambu A/S occupies a distinct position as a single-use specialist, anchoring the disposable segment through controlled polymer supply chains. KARL STORZ represents the precision optical manufacturing archetype, with German engineering heritage informing rigid endoscopy competencies that extend into video laryngoscope platforms.
| Leading Market Players |
|---|
| Medtronic |
| Ambu A/S |
| KARL STORZ |
| Olympus Corporation |
| Teleflex Incorporated |
| Verathon Inc. |
| Prodol Meditec |
| Nihon Kohden Corporation |
| Penlon |
| Others |
Supply Flow & Price Mechanics
Shanghai-Ningbo port freight corridors transmit polymer feedstock cost volatility directly into single-use blade pricing, concentrating margin pressure on molders dependent on medical-grade polycarbonate while enabling differentiated positioning for manufacturers with captive resin sourcing or integrated sterilization-free value propositions.
Pricing Analysis
Price spreads between German-engineered reusable video systems and Chinese-manufactured disposable blades exceed three-to-one ratios across European procurement channels. Three-tier pricing structure across premium CMOS-integrated platforms, standard fiber-optic systems, and economy direct laryngoscopy blades reflects certification grade differentiation and after-sales service bundling. Cost compression in mid-tier emergency departments is intensifying because CMOS sensor commoditization erodes video platform premiums. Surgical centers exhibit highest price sensitivity due to capital constraint structures, while academic medical centers prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Export control regimes restricting CMOS sensor and precision optical component flows from specific jurisdictions constrain video platform manufacturers dependent on Taiwanese semiconductor foundries and Japanese optical glass suppliers. Component sourcing concentrates in China for polymer resin and mold tooling, Germany for rigid endoscopy optics, and South Korea for CMOS wafer fabrication. Raw material dependencies include medical-grade polycarbonate, stainless steel alloys for reusable blades, and rare-earth elements in LED illumination modules. Single-source vulnerability in East Asian petrochemical corridors exposes molders to feedstock disruption. Distribution runs through group purchasing organization contracts dominating United States hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across anesthesia training programs, ambulatory surgical migration, and prehospital deployment models creates specialized niches where focused capabilities outperform broad portfolios.
For Market Incumbents: Insulate reusable platform revenue through backward integration into reprocessing service networks that extend product lifecycles beyond third-party repair competition. Deepen polymer supply partnerships in Yangtze River Delta corridors to secure medical-grade polycarbonate allocation against single-use blade demand surges. CMOS sensor commoditization threatens premium positioning; counter through software companion development integrating AI-guided intubation assistance. For New Entrants and Emerging Players: Establish a beachhead in Brazilian ambulatory surgical centers where ANVISA regulatory streamlining reduces entry barriers and subscription blade procurement models displace capital equipment purchasing. Target municipal emergency medical services in the United States Southeast where CMOS cost reductions enable video platform displacement of direct laryngoscopy without health system GPO contract complexity. Pursue telemedicine integration partnerships with rural health systems facing anesthesiologist coverage gaps. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors single-use specialists with controlled polymer supply chains and sterilization-free regulatory dossiers over capital equipment vendors facing MDR reprocessing validation burdens. Long-term viability rests on ambulatory procedural volume expansion and infection control protocol tightening rather than operating theater capital cycles. Acquisition target archetype: disposable blade molders with ISO 13485 certification and East Asian manufacturing footprints. Signal to watch: FDA 510(k) clearance timelines for AI-integrated video platforms as inflection indicator for next-generation competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 clinical evidence requirements extend certification timelines for reusable reprocessing validations. |
| Hospital System Partnership | Integrated health systems in California and Texas consolidate video and single-use blade procurement under single-source agreements. |
| Software Companion Development | Machine learning algorithms trained on glottic visualization databases hybridize with video outputs for novice operator guidance. |
| Reimbursement Strategy | Payor recalibration of cost-effectiveness thresholds for single-use versus reusable airway management procedures shapes procurement economics. |
| Backward Integration into Polymer Supply | Captive medical-grade polycarbonate sourcing insulates molders from East Asian petrochemical corridor volatility. |
Methodological Framework
Cross-validation between primary interviews with anesthesia department heads, hospital procurement committee members, biomedical engineers, and GPO contracts managers and secondary sources including FDA 510(k) premarket notification databases, EU MDR technical documentation filings, and hospital procurement contract registries anchors the qualitative findings. Bottom-up installed base modeling triangulates against top-down procedure volume estimates from anesthesia society membership data and surgical volume statistics.
Calibration against historical CMOS sensor cost curves, polymer resin price indices, and regulatory approval timeline databases informs the analytical framework across the projection horizon. Segmentation dimensions include product type, end user facility class, imaging technology architecture, and procedural application urgency. CAGRs derive from elasticity-adjusted demand projections incorporating anesthesia workforce expansion rates and outpatient surgery migration patterns.
Stress conditions across polymer feedstock price bands, notified body audit queue lengths, and CMOS sensor supply allocation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MDR implementation consistency and health system capital expenditure recovery trajectories. Material shifts in EU MDR enforcement intensity or FDA premarket notification pathway restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Invisible Orthodontics Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Mandibular Advancement Devices Market
Medical Devices
Gamma Knife Market
Medical Devices
Global Electrophysiology Devices Market
Medical Devices
Global Foley Catheters Market
Medical Devices
Global Semiconductor in Healthcare Market
Medical Devices
Ultra-Large Volume Wearable Injectors Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Sharps Destruction Device Market
Medical Devices
Intracranial Stents Total Addressable Market
Medical Devices
Global Metal Implants and Medical Alloys Market
Medical Devices
Artificial Disc Replacement Market
Medical Devices
Global PC-Based Audiometer Market
Medical Devices
Knee Braces Market
Medical Devices
Global Transcranial Magnetic Stimulators Market