
 Global Blood Collection Tubes Market | 2026-2036
Global Blood Collection Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Collection Tubes Market Foresight
Chinese polymer converters is decoupling from European PET resin dependency by building dedicated extrusion lines for blood-contact medical grades. Becton, Dickinson and Company anchors North American supply through backward integration into plastic resin compounding. Greiner Bio-One International GmbH specializes in additive-free tube formulations for coagulation-sensitive assays. Terumo Corporation extends its footprint across Asia-Pacific through automated tube production facilities.
Blood collection tubes are cylindrical containers manufactured from borosilicate glass or medical-grade polyethylene terephthalate, engineered with internal vacuum pressure or additive coatings to preserve sample integrity during transport and centrifugation. Vacuum tubes dominate clinical throughput due to standardized fill volumes and reduced hemolysis rates, while microtainers capture pediatric and point-of-care segments where low-volume draws limit standard tube utility. Plastic materials displace glass in mass phlebotomy settings because of shatter resistance and lighter logistics costs.
FDA 510(k) clearance pathways and EU MDR conformity assessments govern tube biocompatibility, shelf-life validation, and additive concentration tolerances, raising compliance costs for new entrants. China's NMPA enforces GB standard equivalency for imported tubes, creating registration bottlenecks for Western manufacturers. ISO 6710 specifications for capillary blood collection devices shape product design benchmarks across export markets. Stakeholders must weigh regulatory reciprocity agreements against localized manufacturing investments when prioritizing geographic expansion.
Market Dynamics
Plastic resin compounding capabilities are consolidating among tube manufacturers as vacuum-draw precision requirements tighten and CDSCO mandates in India force quality infrastructure investments across diagnostic networks.
Growth Catalysts
- CDSCO quality mandates:Diagnostic laboratories in India are expanding phlebotomy infrastructure to meet centralized drug standard enforcement, creating standardized equipment procurement pipelines.
- Polymer extrusion localization:Chinese converters are building dedicated lines for blood-contact medical grades, reducing import dependency for PET resin and shortening supply lead times.
- ISO 6710 harmonization:Capillary collection device specifications are shaping export market design benchmarks, enabling single-SKU strategies across multiple regulatory jurisdictions.
Market Restraints
- EU MDR conformity costs:Biocompatibility and shelf-life validation requirements for tube additives have raised compliance expenditures, squeezing margin structures for mid-tier suppliers.
- GB standard equivalency barriers:China's NMPA enforces domestic standard alignment for imported tubes, creating registration bottlenecks that delay Western manufacturer market entry.
- Glass-to-plastic conversion limits:Coagulation-sensitive assays still require borosilicate formulations where additive-free specifications resist full polymer substitution.
Strategic Opportunities
- Tier-one hospital networks in China:Vacuum tube demand concentrates in urban medical centers where throughput volumes justify automated handling infrastructure investments.
- Pediatric microtainers:Low-volume draw requirements in neonatal and point-of-care settings remain underpenetrated by standard tube formats, opening specialty formulation development.
- Backward integration into resin:Captive supply of medical-grade PET compounds enables quality control over additive migration and surface properties.
Industry Challenges
- FDA 510(k) clearance timelines:Additive concentration tolerance documentation requires extensive stability testing, extending product launch cycles for new tube formulations.
- Legacy glass handling infrastructure:Hospital phlebotomy departments maintain centrifugation and transport systems optimized for borosilicate weights, complicating plastic conversion logistics.
- Cross-border registration reciprocity gaps:Absence of mutual recognition between FDA, EMA, and NMPA pathways forces redundant testing expenditures for multi-territory launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Collection Tubes Market |
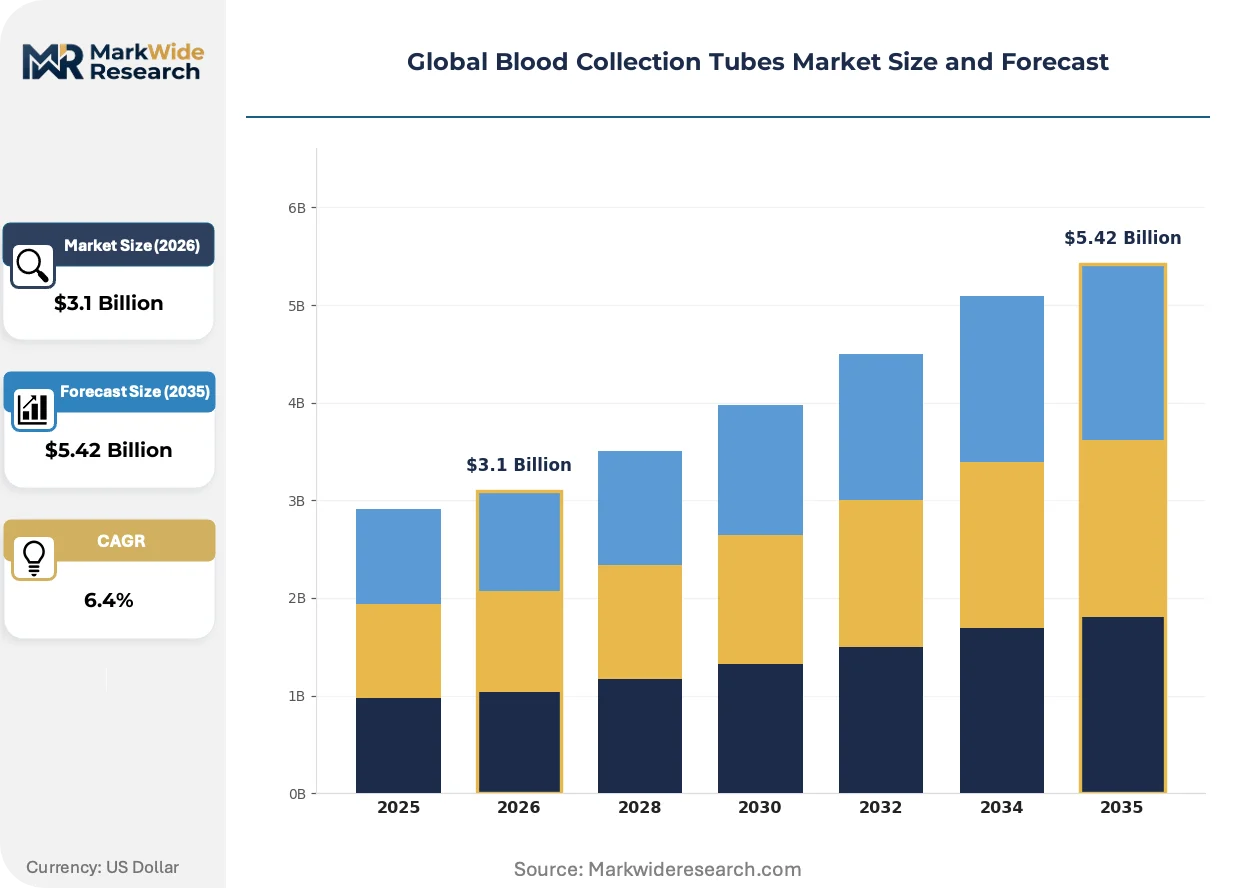
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Tubes, Non-Vacuum Tubes, Capillary Tubes, Pediatric Tubes, Microtainers Material: Glass, Plastic, Polypropylene, Polystyrene, Polyethylene Terephthalate Application: Diagnostic Testing, Blood Banking, Therapeutic Phlebotomy, Research, Quality Control End User: Diagnostic Labs, Blood Banks, Pharmaceutical Companies, Research Institutes, Pathology Centers |
| Companies Covered | Becton, Dickinson and Company, Greiner Bio-One International GmbH, Terumo Corporation, SARSTEDT AG & Co. KG, Fresenius Kabi AG, Nipro Medical Corporation, Cardinal Health, Haematonics, Grifols, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Collection Tubes Market Shifts & Advancements
Automation and precision manufacturing are compressing production economics while regulatory convergence pressures force standardization investments across tube specifications and additive formulations.
Robotic tube handling systems are automating fill-volume consistency and capping operations in high-throughput diagnostic centers. Large hospital networks in Germany and Japan are deploying these systems to reduce hemolysis rates from manual processing errors. This automation is compressing labor cost structures while tightening quality variance bands that previously accommodated human handling tolerances.
The EU MDR's enhanced biocompatibility documentation requirements are forcing additive reformulation investments across European supply chains. Manufacturers must now submit extended shelf-life validation data and leachable substance profiles that exceed previous CE-marking thresholds. Blood coagulation testing tubes face the steepest compliance gradient, as citrate concentration tolerances now require batch-level analytical certification.
Consolidated procurement by multi-site diagnostic chains is displacing fragmented hospital-level purchasing across North American markets. Large laboratory networks in Texas and Florida are negotiating multi-year supply agreements that bundle tube volumes with maintenance and inventory management services. This concentration is visible most acutely in metabolic and chemistry testing segments where standardized consumable specifications dominate.
Global Blood Collection Tubes Market Segmentation
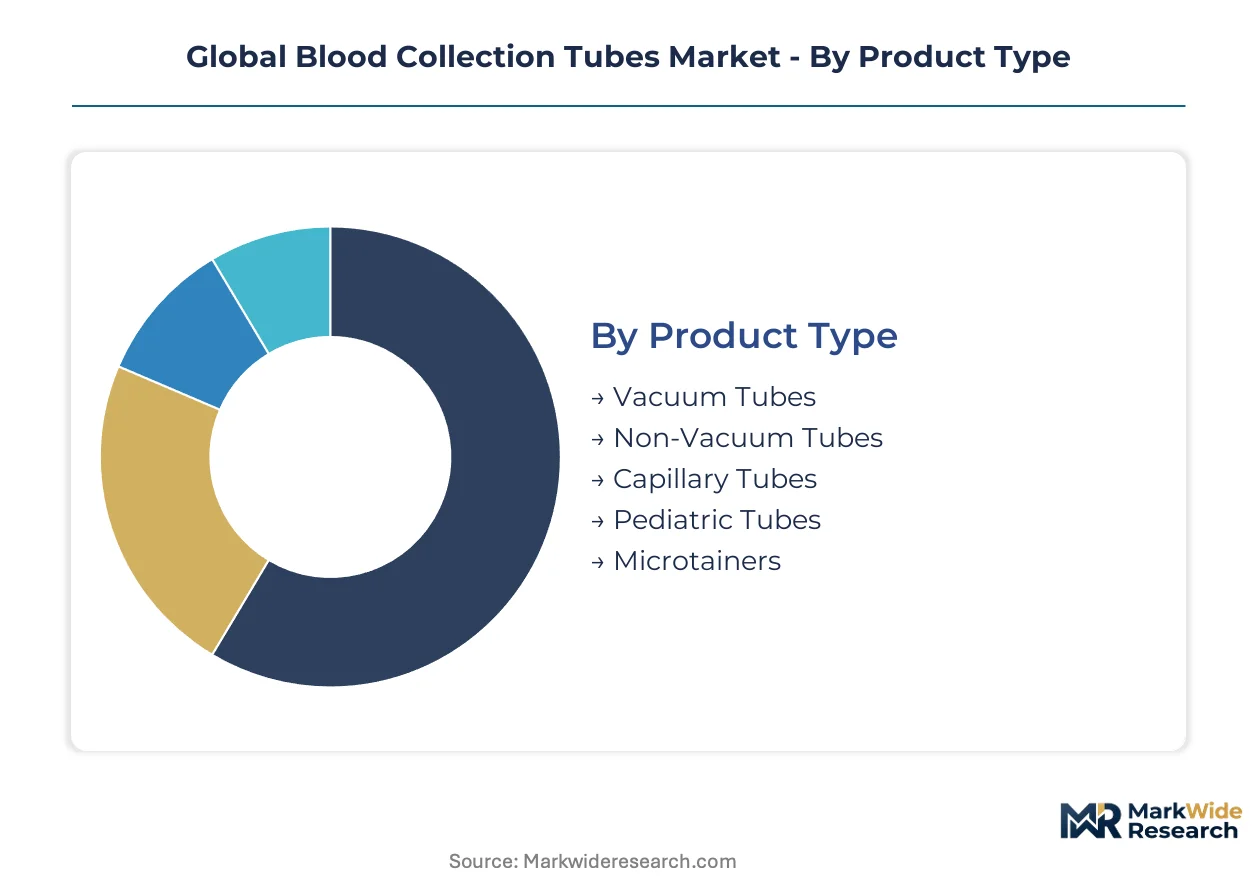
Blood collection tube manufacturers face divergent regulatory pathways across product formats, with vacuum systems requiring FDA 510(k) clearance for additive tolerances while capillary devices fall under ISO 6710 harmonization. Material selection and end-use specifications further stratify compliance burdens, shaping portfolio prioritization strategies.
Product Type:
Vacuum tubes carry the heaviest certification load through FDA additive concentration documentation and EU MDR shelf-life validation, while capillary formats navigate lighter ISO pathway harmonization.
- Vacuum Tubes:Engineered with internal negative pressure and standardized fill volumes for automated phlebotomy systems. Demand concentrates in China's tier-one hospital networks where throughput volumes justify robotic handling infrastructure investments. FDA 510(k) clearance requires extensive stability testing for additive migration profiles.
- Capillary Tubes:Designed for micro-volume collection through skin puncture rather than venipuncture. Pediatric departments in Germany and Japan deploy these formats to reduce hemolysis rates from low-volume draws. ISO 6710 specifications enable single-SKU export strategies across multiple regulatory jurisdictions.
- Non-Vacuum Tubes:Open-system containers requiring manual fill control, common in resource-limited settings with inconsistent vacuum supply chains.
- Pediatric Tubes:Reduced-diameter formats calibrated for neonatal blood draws, capturing point-of-care segments where standard tube utility faces volume constraints.
- Microtainers:Miniature collection vessels for fingerstick sampling, penetrating retail clinic networks and home diagnostic kits.
Vacuum tubes sit at the top of the volume ranking, with capillary tubes climbing the fastest.
Material:
Material selection drives cost tier stratification, with glass commanding premium pricing for coagulation-sensitive assays and plastic resins enabling mass-market penetration through lighter logistics economics.
- Glass:Borosilicate formulations maintain inert surfaces for additive-free coagulation testing where polymer substitution risks assay interference. Blood banks in Switzerland and Australia specify glass for platelet function testing protocols. Shatter resistance limitations constrain adoption in high-throughput automated handling environments.
- Polyethylene Terephthalate:Medical-grade PET dominates mass phlebotomy through shatter resistance and weight reduction in transport logistics. Chinese converters are building dedicated extrusion lines to decouple from European resin dependency. Surface properties require precise compounding control to prevent additive migration.
- Plastic:Broad category encompassing polymer alternatives to glass, capturing standard chemistry and metabolic testing segments where assay sensitivity permits non-glass contact.
- Polypropylene:Crystalline polymer selected for thermal stability in centrifugation cycles, common in research institute protocols requiring repeated temperature cycling.
- Polystyrene:Amorphous polymer with optical clarity for visual sample inspection, penetrating pathology centers with legacy manual processing workflows.
PET commands the largest production volumes, with polypropylene expanding most quickly in research applications.
Application:
Application segmentation maps directly to customer procurement sophistication, with diagnostic testing requiring ISO-standardized specifications and blood banking demanding additive-free certifications.
- Diagnostic Testing:Routine chemistry, hematology, and immunoassay workflows consuming standardized tube formats at highest volumes. Diagnostic laboratory networks in Texas and Florida negotiate multi-year supply agreements bundling tubes with inventory management services. CDSCO quality mandates in India are forcing infrastructure standardization across fragmented lab networks.
- Blood Banking:Collection, processing, and storage for transfusion services requiring stringent donor sample integrity. Blood banks in France and Canada specify citrate concentration tolerances with batch-level analytical certification under EU MDR enhanced documentation. Coagulation-sensitive assays resist full polymer substitution.
- Therapeutic Phlebotomy:Treatment-driven blood removal for conditions like hemochromatosis, utilizing standard vacuum formats with therapeutic labeling distinctions.
- Research:Academic and commercial R&D protocols with specialized additive requirements and non-standard fill volumes.
- Quality Control:Laboratory proficiency testing and assay validation workflows requiring traceable reference materials.
Diagnostic testing anchors procurement volumes, with blood banking gaining share fastest through enhanced regulatory documentation requirements.
End User:
End-user concentration determines channel strategy, with diagnostic labs consolidating procurement through multi-site networks and blood banks maintaining specialized technical specifications.
- Diagnostic Labs:High-throughput processing centers standardizing on vacuum tube automation to reduce manual handling errors. Large networks in Germany deploy robotic handling systems compressing labor cost structures while tightening quality variance bands. Consolidated procurement is displacing fragmented hospital-level purchasing across North American markets.
- Blood Banks:Transfusion service providers with additive-free specifications for donor sample integrity. Blood banks in Japan maintain centrifugation systems optimized for borosilicate weights, complicating plastic conversion logistics. NMPA GB standard equivalency creates registration bottlenecks for Western manufacturer supply agreements.
- Pharmaceutical Companies:Clinical trial sample collection and bioanalytical testing requiring chain-of-custody documentation.
- Research Institutes:Academic and government laboratories with flexible procurement and specialized protocol requirements.
- Pathology Centers:Tissue diagnostic workflows with manual processing preferences and optical clarity specifications.
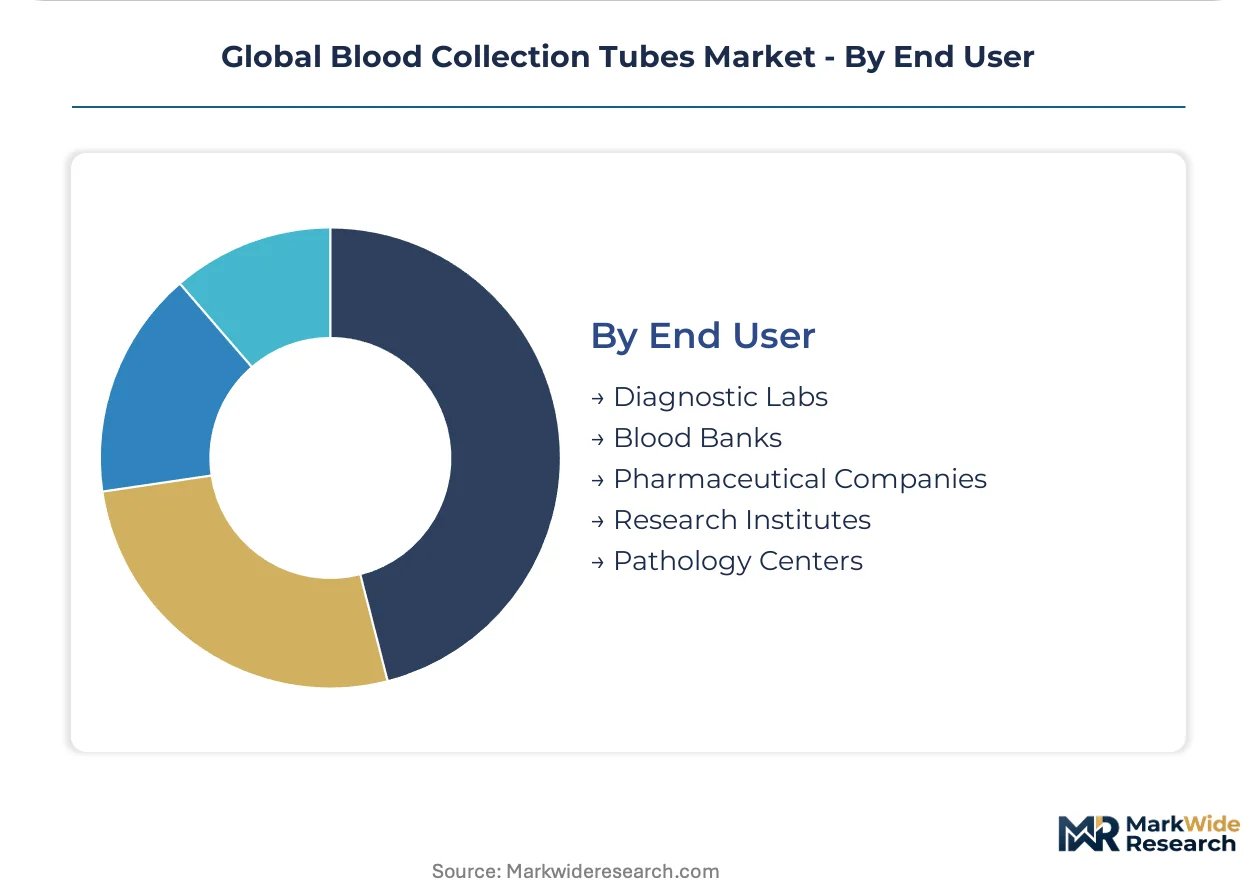
Diagnostic labs represent the dominant procurement channel, with blood banks showing the steepest compliance-driven specification tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing production maps as manufacturers relocate extrusion and compounding capacity to jurisdictions with streamlined medical-device registration pathways. Cost-of-compliance gaps between FDA 510(k) timelines and NMPA GB-standard equivalency procedures are accelerating facility investments in Asian manufacturing clusters.
United States
Diagnostic laboratory consolidation in Texas and Florida is bundling multi-year tube procurement with inventory management services. FDA 510(k) clearance pathways enforce additive concentration tolerance documentation that extends product launch cycles. Large hospital networks in the Southeast are deploying robotic handling systems to compress labor cost structures.
Germany
EU MDR enhanced biocompatibility documentation is forcing additive reformulation investments across domestic supply chains. Blood banks in Bavaria maintain centrifugation systems optimized for borosilicate weights. Robotic tube handling systems in Baden-Württemberg are tightening quality variance bands that previously accommodated manual processing tolerances.
China
NMPA GB standard equivalency for imported tubes is creating registration bottlenecks that delay Western manufacturer market entry. Polymer converters in the Yangtze River Delta are building dedicated extrusion lines for blood-contact medical grades. Tier-one hospital networks in Beijing and Shanghai concentrate vacuum tube demand where throughput volumes justify automated handling infrastructure.
India
CDSCO quality mandates are forcing diagnostic laboratories to expand phlebotomy infrastructure across fragmented networks in Maharashtra and Karnataka. Centralized drug standard enforcement is creating standardized equipment procurement pipelines. Diagnostic chains in Delhi-NCR are consolidating previously hospital-level purchasing into multi-site supply agreements.
Japan
METI industrial policy is supporting automated tube production facility investments to serve Asia-Pacific export markets. Blood banks in the Kanto region specify borosilicate formulations for platelet function testing protocols. PMDA regulatory pathways for capillary collection devices align with ISO 6710 specifications that enable single-SKU export strategies.
Global Blood Collection Tubes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty formulation niches and regional manufacturing localization. The competitive structure stratifies around three archetypes: vertically integrated resin compounders controlling additive migration specifications, additive-free formulation specialists serving coagulation-sensitive assay segments, and automated production scale operators capturing tier-one hospital network contracts. Dominant competitive moves include backward integration into medical-grade PET compounding and strategic partnerships with multi-site diagnostic chains for bundled procurement agreements.
Among North American supply anchors, Becton, Dickinson and Company exemplifies the vertically integrated archetype through captive resin compounding capabilities. Greiner Bio-One International GmbH occupies a position within the additive-free formulation tier, reflecting German precision manufacturing heritage. Terumo Corporation represents the Asia-Pacific automation scale vector, anchoring regional production capacity expansion. These three entities collectively illustrate how geographic origin and corporate structure map to distinct competitive positioning strategies in tube manufacturing.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Greiner Bio-One International GmbH |
| Terumo Corporation |
| SARSTEDT AG & Co. KG |
| Fresenius Kabi AG |
| Nipro Medical Corporation |
| Cardinal Health |
| Haematonics |
| Grifols |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FDA-cleared additive formulations and commodity ISO-standard tubes creates parallel pricing ladders that map directly to resin sourcing depth and compounding control. Premium tiers draw from captive PET compounding operations in North America and Western Europe, while price-competitive volumes flow through distributed converter networks in Asia-Pacific that rely on spot resin markets.
Pricing Analysis
Distributor margins absorb the steepest compression in emerging market channels where diagnostic laboratory consolidation forces volume-based contracting. Three-tier pricing structure across premium, standard, and economy levels separates additive-certified coagulation tubes from chemistry-grade PET formats and unbranded glass alternatives. Pricing pressure stems from EU MDR documentation costs that squeeze mid-tier supplier margins without full premium pricing power. Hospital purchasing committees exhibit lowest price sensitivity for blood banking applications where assay integrity failures carry catastrophic liability, while retail clinic networks drive aggressive commoditization of standard vacuum formats.
Supply Chain Analysis
Workforce availability for precision extrusion and cleanroom molding concentrates manufacturing gravity in China's Yangtze River Delta, India's Maharashtra corridor, and Germany's Baden-Württemberg cluster. Medical-grade PET resin, borosilicate glass tubing, and silicone cap liners constitute the critical input trinity that draws from European chemical producers, Chinese state-owned glassworks, and Japanese specialty polymer houses. Single-source vulnerability pervades the blood-contact additive segment where citrate and heparin formulations rely on concentrated pharmaceutical chemical suppliers. Distribution runs through regional diagnostic equipment distributors that bundle tube procurement with phlebotomy automation service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Blood Collection Tubes Market functions as a stable compounder anchored by irreplaceable consumable demand in diagnostic workflows that resist digital substitution.
For Market Incumbents: Hedge margin erosion from EU MDR compliance cost inflation by deepening backward integration into medical-grade PET compounding and locking multi-year supply agreements with tier-one hospital networks in China and Germany. Prioritize automation capex in Asia-Pacific facilities to offset labor cost divergence from Western manufacturing bases. For New Entrants and Emerging Players: CDSCO quality mandates in India open a window for regional manufacturing investments that bypass NMPA registration bottlenecks blocking Western import channels. Target pediatric microtainer segments where low-volume draw requirements resist standardization by incumbent volume players. Pursue white-label partnerships with diagnostic chains in Delhi-NCR and Mumbai that consolidate fragmented procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier suppliers face simultaneous FDA 510(k) timeline extensions and EU MDR shelf-life validation cost spikes without scale economies to absorb compliance investments. Acquisition target archetype: regional converters with established NMPA registration and dormant capacity for ISO 6710-certified capillary device production. Watch for inflection when CDSCO enforcement triggers mandatory equipment replacement cycles across Indian diagnostic networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive PET supply locks additive migration control for coagulation-sensitive assay tubes. |
| Automated Production Facility Deployment | Robotic handling infrastructure in Japan and Germany compresses fill-volume variance bands below manual tolerances. |
| ISO 6710 Harmonization Investment | Single-SKU capillary device strategies reduce redundant testing for multi-territory launches. |
| Multi-Site Diagnostic Chain Partnership | Bundled procurement agreements in Texas and Florida displace fragmented hospital-level purchasing. |
| Pediatric Microtainer Formulation Development | Neonatal low-volume segments remain underpenetrated by standard vacuum tube formats. |
Research Methodology
Multiple input streams — procurement manager interviews, regulatory filing analysis, and trade flow databases — were reconciled to construct demand estimates. Conversations with hospital purchasing committees, GPO contracts managers, biomedical engineers, and CDSCO inspection officials supplied primary intelligence on infrastructure investment trajectories. Secondary validation drew from FDA 510(k) clearance databases, NMPA registration records, EU MDR notified body certificates, and ISO 6710 certification registries. Bottom-up tube volume modeling by hospital tier and diagnostic lab network scale was cross-checked against top-down resin consumption data from medical-grade PET producers.
Data-stream reconciliation across the projection horizon applied segment-specific growth coefficients to vacuum, capillary, and microtainer formats by material type and end-use application. The analytical framework modeled product type, material grade, application workflow, and end-user procurement sophistication dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical phlebotomy procedure volumes against tube consumption intensity ratios, with explicit incorporation of CDSCO mandate enforcement timelines and NMPA registration queue lengths as policy-sensitive inputs.
Revisions become necessary when regulatory reciprocity agreements emerge between FDA, EMA, and NMPA pathways, or when polymer substitution breakthroughs eliminate glass dependency in coagulation assays. Forecasts reflect assumptions about sustained diagnostic test volume growth and stable resin supply chain configurations. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Blood Processing and Storage Equipment Market
Laboratory Equipment
Automated Blood Processing Equipment Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Test Tube Market
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Electronic Multichannel Pipettes Market
Laboratory Equipment
Global Laboratory Washers Market
Laboratory Equipment
Laboratory Vacuum Drying Oven Market
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
US Cath Labs Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Laboratory Pulverizer Market
Laboratory Equipment
Laboratory Furnaces Market
Laboratory Equipment
ASEAN Laboratory Equipment Market