
 Global Breast Biopsy Devices Market | 2026-2036
Global Breast Biopsy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Breast Biopsy Devices Market Analysis
China is rewriting capacity dynamics for breast biopsy device manufacturing as domestic producers scale precision instrument fabrication. Hologic, Inc. leverages its integrated imaging-to-biopsy platform to sustain leadership across North American hospital networks. Danaher Corporation anchors its position through diagnostic workflow automation that extends from sample acquisition to pathology analysis. Merit Medical Systems competes on interventional radiology channel control, particularly in outpatient settings where procedural throughput determines purchasing decisions.
Breast biopsy devices are precision instruments designed to extract tissue specimens from suspicious breast lesions, typically operating with gauge ranges from 7 to 14 and incorporating vacuum-assisted or core needle mechanisms for adequate histological sampling. Vacuum-assisted biopsy systems command premium positioning due to larger tissue volumes per insertion, while ultrasound-guided technology dominates procedure volume because of real-time visualization and lower capital requirements compared to MRI-guided alternatives. The end-user base fragments across hospitals, diagnostic centers, and outpatient clinics, with cancer research institutes representing a concentrated but lower-volume segment driven by protocol standardization needs.
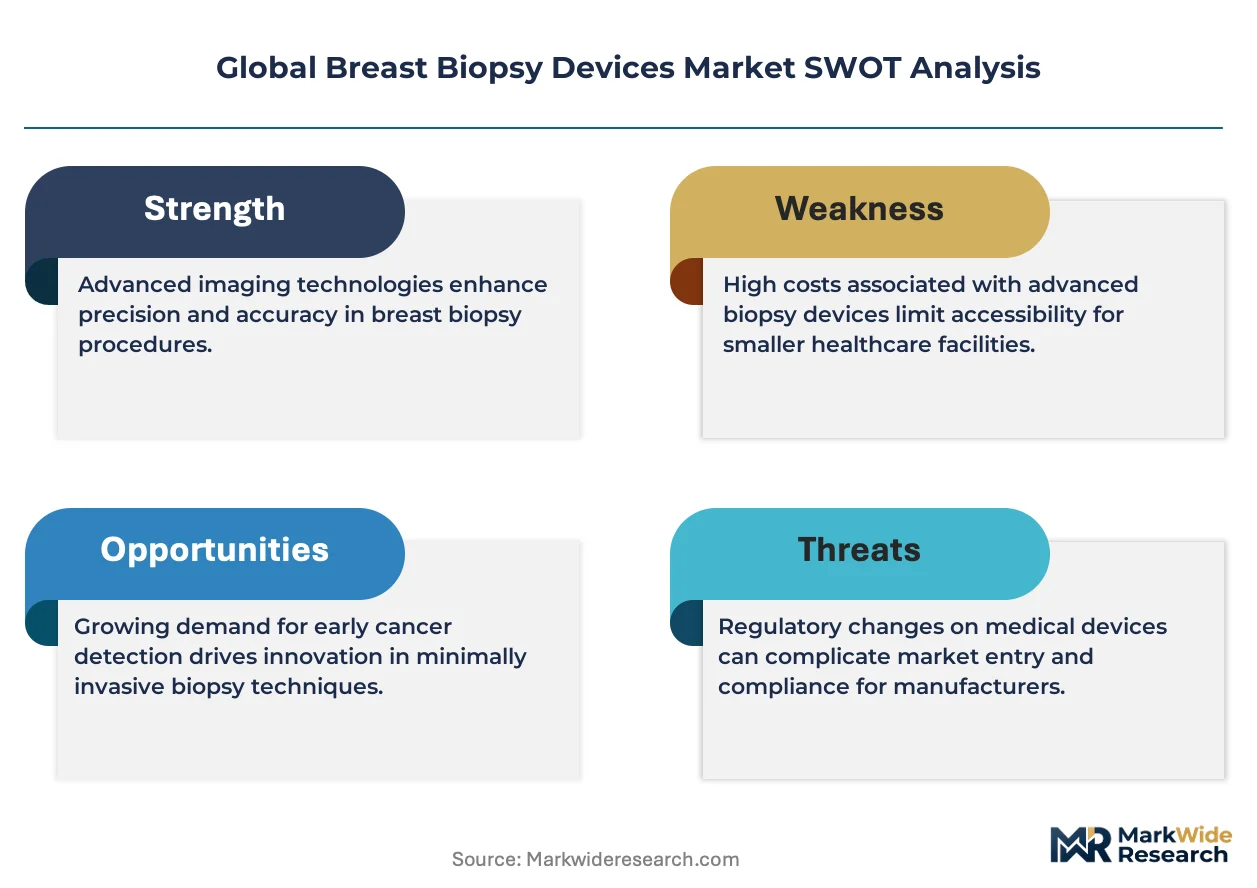
FDA 510(k) clearance pathways shape product development timelines and predicate device selection for manufacturers seeking US market access, while the EU MDR transition imposes stricter clinical evidence requirements on legacy products. Japan's PMDA maintains distinct pharmacovigilance reporting standards that influence post-market surveillance investments by device sponsors. Stakeholders must monitor reimbursement code consolidation trends and AI-assisted imaging integration requirements that will determine next-generation product specifications and capital deployment priorities.
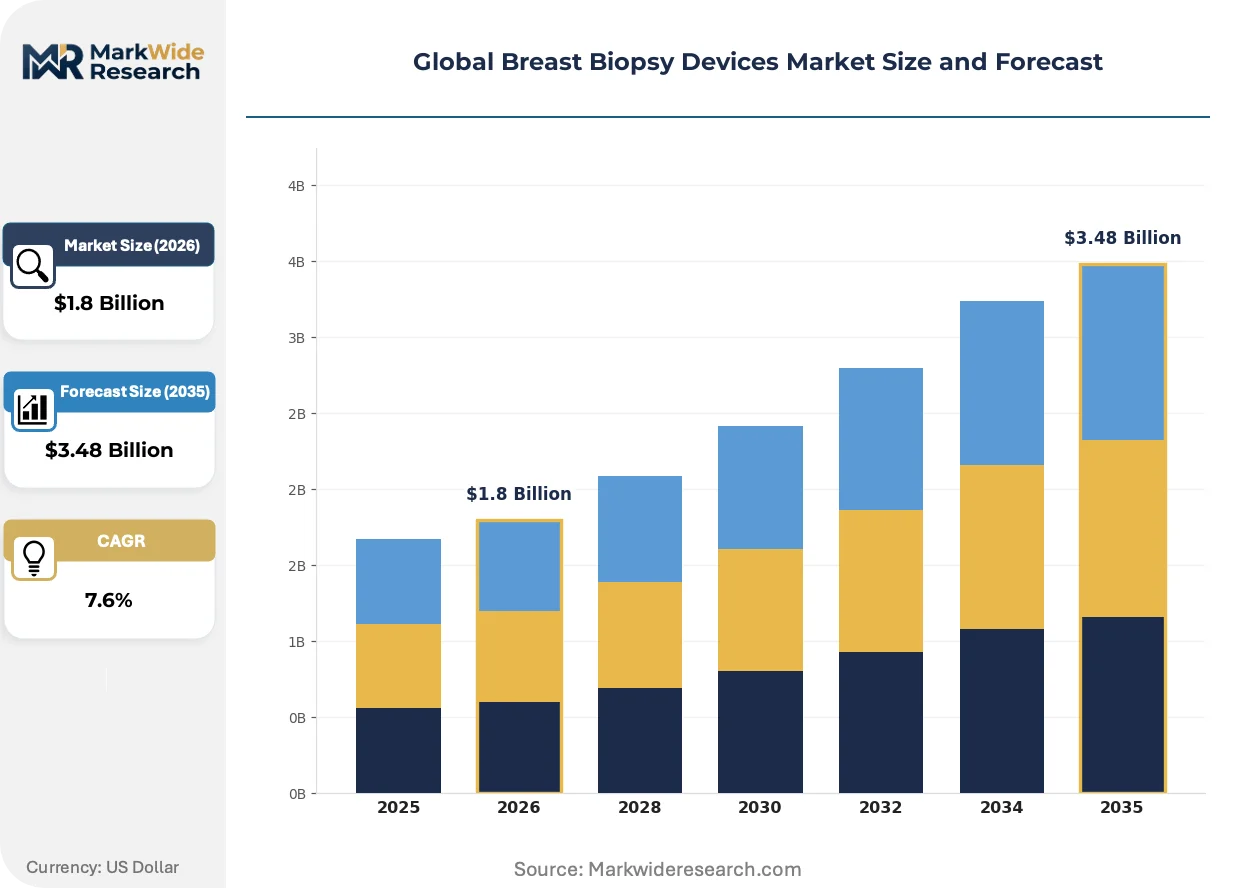
Market Dynamics
Minimally invasive diagnostic protocols are displacing open surgical biopsy as the standard of care across hospital-based oncology departments, compressing procedure times and capital recovery cycles for device manufacturers.
Growth Catalysts
- EU MDR Clinical Evidence Mandates:Stricter post-market surveillance requirements under the Medical Device Regulation are accelerating device quality upgrades and predicate device replacements across European diagnostic networks.
- Vacuum-Assisted Tissue Acquisition:Larger specimen volumes per insertion reduce sampling error rates and repeat procedures, driving preference among interventional radiologists in high-throughput outpatient settings.
- Japan:Dense mammography screening infrastructure and aging demographics sustain procedural volume expansion in hospital-based breast centers.
Market Restraints
- Stainless Steel and Polymer Input Costs:Gauge-specific needle fabrication depends on medical-grade alloys and precision-molded components vulnerable to commodity price swings and specialty polymer supply tightness.
- Single-Source Component Dependencies:Precision drive mechanisms and vacuum pump subassemblies concentrate among German and Japanese precision engineering suppliers, creating geographic chokepoints.
- MRI-Guided System Capital Barriers:High magnetic compatibility requirements and dedicated coil investments limit deployment to tertiary academic centers, capping addressable volume.
Strategic Opportunities
- India:Underpenetrated screening penetration and expanding private diagnostic chains create whitespace for ultrasound-guided disposable biopsy systems.
- AI-Assisted Imaging Convergence:Integration of real-time lesion characterization algorithms with biopsy navigation is compressing procedure variability and expanding operator pools beyond specialized radiologists.
- Same-Day Diagnostic Pathways:Outpatient clinic networks in Germany are unbundling acquisition and pathology services, creating direct procurement channels bypassing traditional hospital supply agreements.
Industry Challenges
- FDA 510(k) Predicate Device Pathways:Evolving substantial equivalence standards and software-as-medical-device guidance are extending clearance timelines for next-generation navigation systems.
- Cross-Training Requirements:Vacuum-assisted and stereotactic systems demand specialized interventional radiology competencies that outpace fellowship program output in several markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Breast Biopsy Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Needle Biopsy, Vacuum-Assisted Biopsy, Stereotactic Biopsy, MRI-Guided Biopsy End User: Hospitals, Diagnostic Centers, Cancer Research Institutes, Outpatient Clinics Technology: Ultrasound, MRI, X-ray, Tomosynthesis Procedure Type: Core Needle Biopsy, Fine Needle Aspiration, Excisional Biopsy, Incisional Biopsy |
| Companies Covered | Danaher Corporation, Merit Medical Systems, Hologic, Inc., Medtronic, Stryker, Mammotome, Argon Medical Devices, Cook Medical, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Breast Biopsy Devices Market Emerging Trajectories
Digital pathology workflows and disposable instrument architectures are compressing capital deployment models and redefining service revenue structures across the biopsy device value chain.
Cloud-based specimen tracking and remote slide review platforms are virtualizing the traditional pathology laboratory footprint. Community hospital networks in the United States are adopting these systems fastest, outsourcing complex case reads to centralized academic pathologists. This architecture is virtualizing equipment utilization patterns and collapsing the geographic radius required for diagnostic coverage.
Japan's PMDA has tightened pharmacovigilance reporting intervals for class II and III biopsy devices, mandating quarterly adverse event submissions versus annual cycles. Device sponsors must restructure post-market surveillance budgets and expand Japanese regulatory affairs headcount. Smaller manufacturers without established Tokyo-based quality infrastructure face disproportionate compliance burden.
Diagnostic centers are unbundling device procurement from consumable supply contracts, fragmenting purchasing authority across capital committees and clinical department budgets. This shift is compressing vendor lock-in duration and elevating total cost-of-ownership transparency in supplier selection. The pattern is most pronounced in German outpatient clinic networks where procurement autonomy has devolved from hospital holding companies to individual practice partnerships.
Global Breast Biopsy Devices Market Segmentation
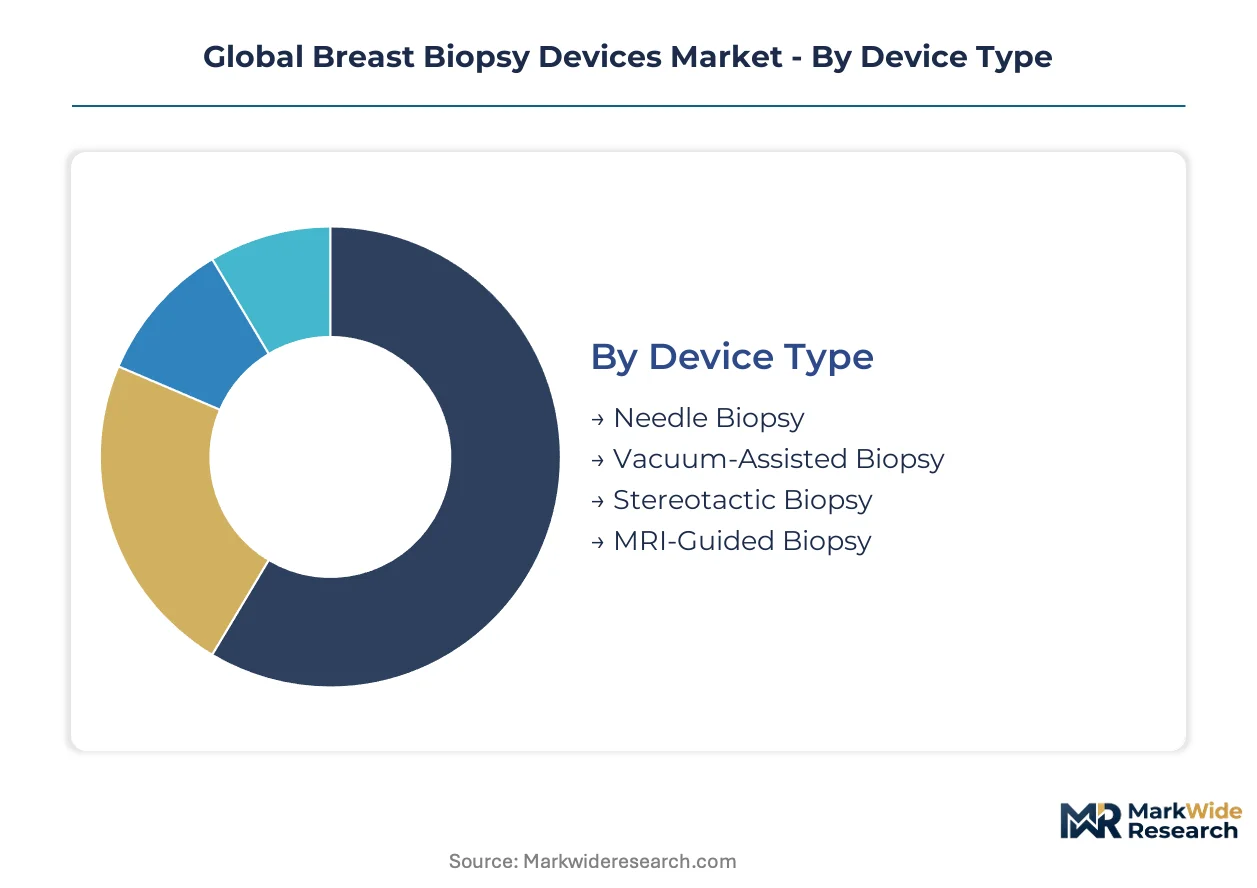
Segmentation in breast biopsy devices reveals how clinical workflow requirements, capital availability, and imaging infrastructure shape procurement patterns across healthcare delivery settings. Manufacturers must align product specifications with the technical capabilities and volume economics of distinct end-use environments.
Device Type:
Mature vacuum-assisted systems dominate revenue concentration while emerging MRI-guided platforms reshape tertiary center capabilities.
- Vacuum-Assisted Biopsy:These systems deploy continuous suction mechanisms to extract larger tissue volumes through single needle insertions, typically utilizing 7-10 gauge probes. Demand concentrates in high-throughput outpatient clinics across the United States and Germany where procedural efficiency directly determines capital recovery timelines.
- Needle Biopsy:Conventional core needle devices represent the foundational technology with 14-18 gauge ranges and manual cutting mechanisms. Community hospital networks in Japan and France favor these systems for their lower capital thresholds and compatibility with existing ultrasound infrastructure.
- Stereotactic Biopsy:X-ray guided coordinate targeting enables precise lesion localization in mammographically detected abnormalities. Breast imaging centers in academic medical centers deploy these for calcification sampling.
- MRI-Guided Biopsy:Magnetic resonance compatibility demands specialized non-ferromagnetic instruments and dedicated breast coils. Tertiary oncology centers in Switzerland and the Netherlands utilize these for occult lesions invisible to conventional imaging.
Vacuum-assisted biopsy retains volume leadership; MRI-guided biopsy holds the steepest expansion curve.
End User:
Customer type segmentation tracks the unbundling of diagnostic services from traditional hospital supply chains toward decentralized procurement.
- Hospitals:Integrated oncology departments command the largest installed base of multi-modality biopsy platforms. University hospitals in the United States and Germany consolidate capital budgets for stereotactic and MRI-guided systems.
- Diagnostic Centers:Standalone imaging facilities prioritize disposable needle architectures and rapid turnaround protocols. Private chains in India and Brazil are expanding ultrasound-guided capacity.
- Outpatient Clinics:These settings favor portable ultrasound-guided systems with same-day pathology pathways. German clinic networks increasingly bypass hospital procurement through direct vendor relationships.
- Cancer Research Institutes:Protocol standardization requirements drive demand for precision instruments with specimen integrity features. National institutes in Japan and France maintain dedicated research-grade installations.
Hospitals retain volume leadership; outpatient clinics hold the steepest expansion curve.
Technology:
Imaging modality segmentation reflects the capital-labor tradeoffs between real-time visualization and diagnostic specificity.
- Ultrasound:Real-time guidance with portable probe systems dominates procedure volume through lower equipment costs and immediate lesion visualization. Diagnostic centers across India, Brazil, and community US markets standardize on this modality.
- MRI:Superior soft-tissue contrast enables targeting of radiographically occult lesions. Academic medical centers in the Netherlands and Switzerland deploy these for high-risk patient surveillance.
- X-ray:Mammography-integrated stereotactic targeting remains essential for calcification-based indications. Screening-dense markets including Japan and Germany maintain significant installed bases.
- Tomosynthesis:Three-dimensional mammographic reconstruction reduces tissue overlap artifacts in lesion localization. Early adoption concentrates in US academic breast centers with 3D mammography infrastructure.
Ultrasound retains volume leadership; tomosynthesis holds the steepest expansion curve.
Procedure Type:
Clinical indication segmentation tracks the displacement of open surgical approaches by percutaneous sampling methods.
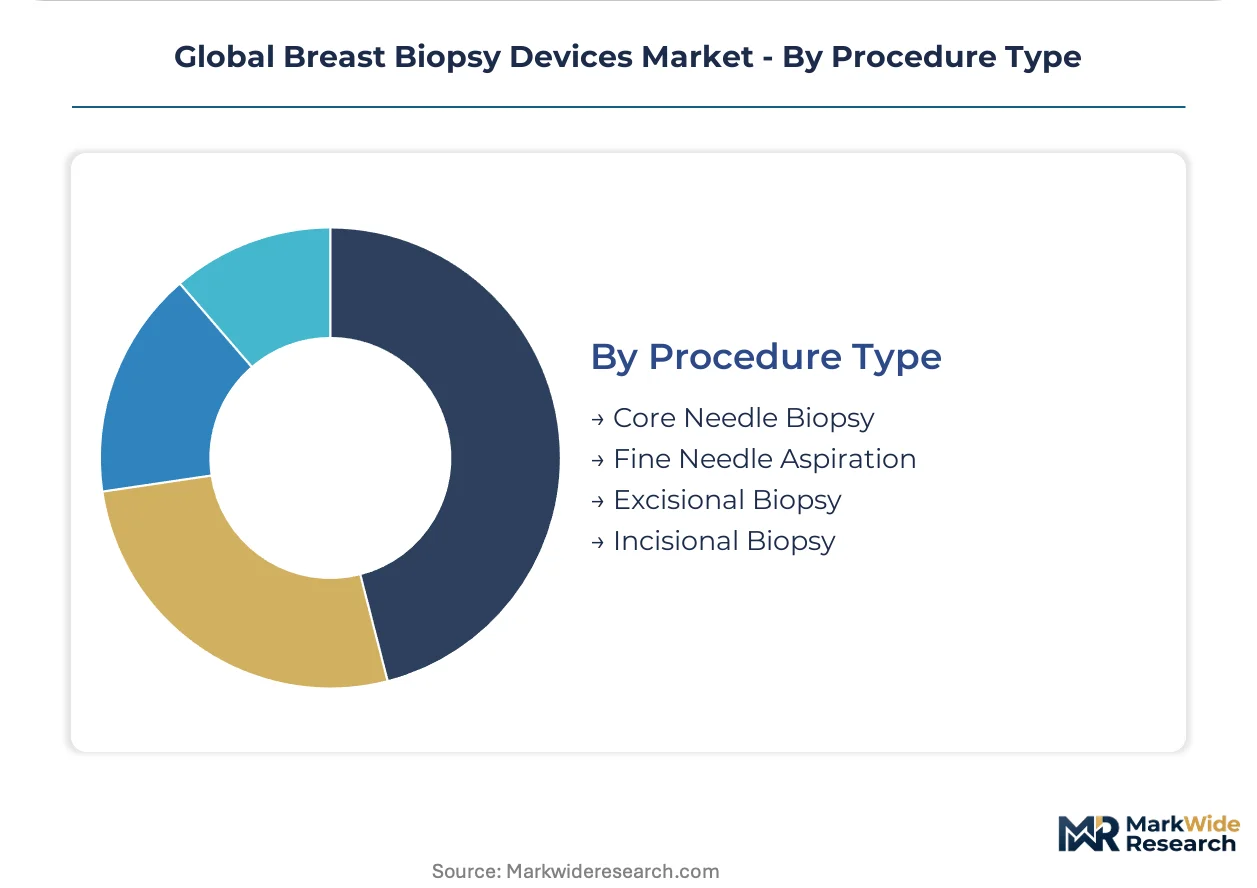
- Core Needle Biopsy:Automated cutting mechanisms extract cylindrical tissue samples adequate for histological diagnosis. Hospital-based breast centers in the United States and Germany perform these as standard-of-care for palpable and image-detected lesions.
- Fine Needle Aspiration:Cytological sampling through 21-25 gauge needles serves rapid on-site assessment. Resource-constrained settings in India and Brazil utilize these for triage before definitive core sampling.
- Excisional Biopsy:Complete lesion removal with surrounding tissue margins persists for indeterminate radiographic-pathological discordance. Japanese breast centers reserve these for selected high-risk lesions.
- Incisional Biopsy:Partial tissue excision for large lesions remains limited to cases where core sampling proves technically inadequate. Tertiary referral centers in France maintain capability for complex presentations.
Core needle biopsy retains volume leadership; fine needle aspiration holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the dominant geography, while Japan's PMDA and the EU MDR create divergent compliance architectures that reshape procurement patterns across hospital networks and outpatient clinic chains.
United States
Dense mammography screening infrastructure and expanding minimally invasive diagnostic programs drive procedural volume concentration. FDA premarket notification pathways tighten quality benchmarks for device clearance, extending development timelines for navigation-integrated systems. Hospital-based oncology departments in the Northeast and California consolidate capital budgets for multi-modality biopsy platforms.
Germany
Outpatient clinic networks unbundle acquisition and pathology services, creating direct procurement channels that bypass traditional hospital supply agreements. EU MDR clinical evidence mandates accelerate device quality upgrades across European diagnostic networks. The Baden-Württemberg and Bavaria regions concentrate precision engineering suppliers for vacuum pump subassemblies.
Japan
Aging demographics and dense screening program densities sustain procedural volume expansion in hospital-based breast centers. PMDA pharmacovigilance reporting standards mandate quarterly adverse event submissions for class II and III devices, restructuring post-market surveillance budgets. Tokyo and Osaka metropolitan areas anchor diagnostic center infrastructure.
China
Domestic producers scale precision instrument fabrication, rewriting capacity dynamics for breast biopsy device manufacturing. NMPA regulatory pathways evolve alongside GB standards adoption for medical device quality. The Yangtze River Delta and Pearl River Delta clusters concentrate manufacturing investment for gauge-specific needle fabrication.
India
Underpenetrated screening penetration and expanding private diagnostic chains create whitespace for ultrasound-guided disposable biopsy systems. CDSCO device registration requirements shape import substitution strategies for multinational sponsors. Maharashtra and Karnataka states lead private hospital network expansion.
Global Breast Biopsy Devices Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where integrated imaging-to-biopsy platforms coexist with specialized disposable instrument fabricators. The vendor base spans multinational conglomerates with diagnostic workflow automation portfolios and mid-cap interventional radiology specialists. Three archetypes dominate: imaging-integrated platform providers, channel-controlled disposable specialists, and precision component subassembly suppliers. Competitive moves concentrate on M&A for navigation technology access and capacity expansion in German and Japanese precision engineering clusters.
Among imaging-integrated platform providers, Hologic, Inc. and Danaher Corporation exemplify archetype leaders that anchor hospital network relationships through capital-intensive system deployments. Merit Medical Systems occupies a position within the interventional radiology channel control tier, particularly in outpatient settings where procedural throughput determines purchasing decisions. These three entities represent distinct strategic postures without overlapping capability claims.
| Leading Market Players |
|---|
| Danaher Corporation |
| Merit Medical Systems |
| Hologic, Inc. |
| Medtronic |
| Stryker |
| Mammotome |
| Argon Medical Devices |
| Cook Medical |
| Becton, Dickinson and Company |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor carries medical-grade stainless steel and precision-molded polymers from Chinese fabrication clusters to German vacuum pump subassembly plants, with container cost volatility feeding directly into downstream price differentiation between premium vacuum-assisted systems and standard core needle devices.
Pricing Analysis
Geographic price spreads separate Japanese hospital procurement at premium tiers from Indian diagnostic center purchasing at economy levels. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, CE marking grade, and after-sales service bundling. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers scale gauge-specific needle fabrication. Price sensitivity concentrates among outpatient clinic networks in Germany and India, while academic medical centers in Switzerland and Japan exhibit lowest sensitivity due to protocol standardization requirements.
Supply Chain Analysis
Contract manufacturing for precision drive mechanisms concentrates among German and Japanese precision engineering suppliers, with Foxconn Medical and Jabil Healthcare holding significant electronics assembly capacity for navigation-integrated systems. Raw material sourcing draws from Swedish medical-grade stainless steel producers, German specialty polymer compounders, and Japanese precision bearing manufacturers. Single-source vulnerability runs through vacuum pump subassembly suppliers in Baden-Württemberg. Distribution runs through hospital GPO contracts in the United States, direct procurement channels in German outpatient networks, and distributor-mediated sales in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward outpatient clinic networks as German diagnostic chains unbundle from hospital holding companies, fragmenting purchasing authority and compressing vendor lock-in duration.
For Market Incumbents: Entrench hospital network relationships through integrated imaging-to-biopsy platform deployments that embed switching costs. Deepen backward integration into precision drive mechanism production to offset single-source dependencies from German and Japanese suppliers. Prioritize CE marking pathway investments under EU MDR clinical evidence mandates to accelerate predicate device replacements. For New Entrants and Emerging Players: Pursue whitespace in Indian private diagnostic chains where underpenetrated screening penetration and expanding ultrasound-guided capacity create entry points. Target disposable needle architectures for resource-constrained settings where capital thresholds exclude multi-modality platform competition. Deploy direct vendor relationships with German outpatient clinic networks bypassing traditional hospital supply agreements. For Investors and Strategic Acquirers: Navigation-software specialists with FDA 510(k) predicate device clearance represent the most attractive acquisition archetype for platform integration plays. Long-term viability hinges on AI-assisted imaging convergence capabilities that expand operator pools beyond specialized radiologists. Watch for quarterly PMDA pharmacovigilance submission patterns as an inflection indicator for Japanese regulatory affairs burden distribution.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathways anchor US market access timelines for navigation-integrated biopsy systems. |
| CE Marking Pathway | EU MDR clinical evidence mandates accelerate quality upgrades across European diagnostic networks. |
| Hospital System Partnership | GPO contract consolidation in the United States embeds switching costs for platform providers. |
| Software Companion Development | AI-assisted lesion characterization algorithms compress procedure variability and expand operator pools. |
| Reimbursement Strategy | Code consolidation trends determine capital deployment priorities for next-generation specifications. |
Methodological Framework
A standing panel of interventional radiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation, PMDA adverse event databases, and hospital procurement records. Bottom-up procedure volume estimates triangulated against top-down device manufacturer revenue disclosures.
Scenario-bracketing framed sensitivity analysis around regulatory pathway delays, commodity input volatility, and reimbursement code consolidation timing. Segmentation modeling spanned device type, imaging modality, end-user setting, and geographic regulatory cluster. CAGRs derived from fitted growth curves applied to procedural volume projections and average selling price trajectories. Forecast inputs incorporated screening program density metrics, fellowship program output rates, and precision engineering capacity utilization.
Sensitivities concentrate around EU MDR transition timelines, PMDA pharmacovigilance interval changes, and vacuum pump subassembly supply disruptions. Forecasts reflect assumptions about minimally invasive diagnostic protocol adoption rates and AI imaging integration penetration. Quarterly review of FDA 510(k) clearance backlogs, German outpatient clinic procurement autonomy indices, and Chinese domestic manufacturer capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Scleral Lens Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
Bovine Pericardial Valve Market
Medical Devices
Implant Handpiece Market
Medical Devices
Software As a Medical Device Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Medical Coatings for Implants Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Japan Electric Wheelchair Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
Global Neurology Ultrasonic Aspirators Market