
 Nigeria Clinical Laboratory Services Market | 2026-2036
Nigeria Clinical Laboratory Services Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Clinical Laboratory Services Market Foresight
Aftermarket service revenue from equipment maintenance contracts is narrowing toward molecular diagnostics platforms as labs upgrade from basic biochemistry analyzers. Synlab Bondco PLC leverages its West African hub infrastructure to sustain multi-city sample logistics. PathCare Nigeria anchors premium pathology services in Lagos while Lancet Laboratories competes through specialized oncology testing panels.
Clinical laboratory services encompass the collection, processing, analysis, and reporting of biological specimens using standardized analytical methods, with typical throughput ranging from 100 to 10,000 tests per day depending on automation level and facility scale. These services enable disease diagnosis, treatment monitoring, and preventive health screening across Nigeria's fragmented healthcare system. Biochemistry and hematology segments dominate current test volumes due to routine demand for renal, liver, and complete blood count panels. Molecular diagnostics represents the fastest-expanding service category as tuberculosis and HIV viral load testing protocols shift toward PCR-based methods. Point-of-care testing delivery mode captures growing margin pools through reduced turnaround time for emergency and rural deployments.
The Medical Laboratory Science Council of Nigeria enforces practitioner licensing and facility accreditation standards that determine market access for new entrants. Nigeria's national health insurance scheme expansion and NAFDAC in-vitro diagnostic registration requirements shape procurement patterns for imported reagents and equipment. Stakeholders must monitor accreditation cost trajectories and import duty structures for automated analyzers to calibrate capital deployment timelines against reimbursement rate negotiations.
Market Dynamics
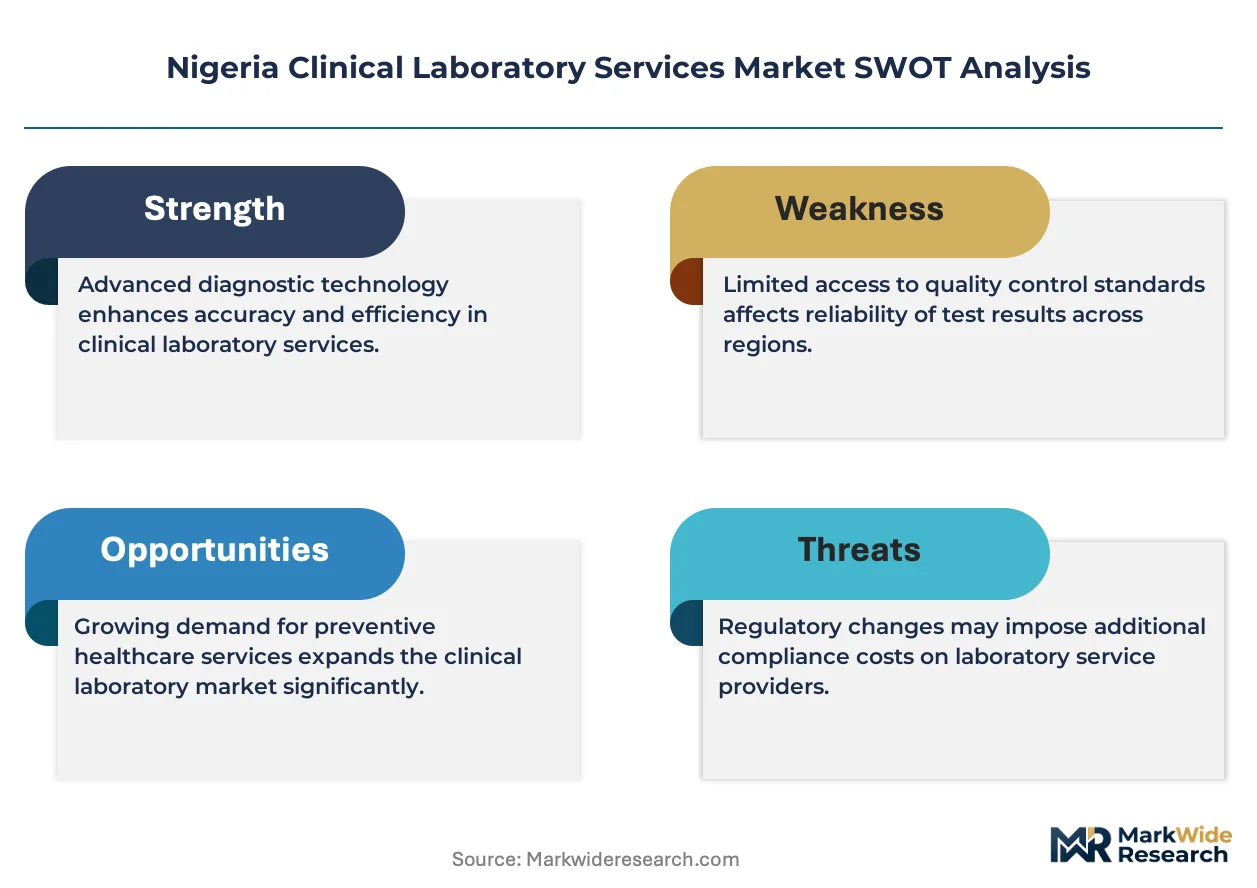
Molecular diagnostics platforms are compressing turnaround times for tuberculosis and HIV viral load testing, forcing capital reallocation from biochemistry analyzers toward PCR infrastructure. The Medical Laboratory Science Council of Nigeria's accreditation tightening is simultaneously raising facility compliance costs while filtering substandard operators.
Growth Catalysts
- MLSCN Facility Accreditation Mandate:The Medical Laboratory Science Council of Nigeria's quality benchmarks are consolidating market access around accredited operators, concentrating test volumes toward compliant networks.
- PCR-Based Viral Load Testing:Tuberculosis and HIV treatment monitoring protocols are mandating molecular methods, expanding reagent throughput requirements for equipped laboratories.
- Lagos-Abuja Urban Corridor Expansion:Private diagnostic networks are clustering in these high-density zones where insurance penetration and disposable income support premium service pricing.
Market Restraints
- Import Duty Burden on Analyzers:Automated equipment faces elevated tariff structures that inflate capital deployment timelines for laboratory upgrades.
- Reagent Supply Concentration:Specialized molecular diagnostics consumables depend on limited offshore manufacturers, exposing procurement to currency volatility and shipping disruptions.
- Power Infrastructure Deficits:Cold chain requirements for PCR reagents and sample integrity face reliability gaps outside major urban centers.
Strategic Opportunities
- Northern Nigeria Penetration Gap:Kano and Kaduna corridors present underdeveloped laboratory density relative to disease burden, offering first-mover positioning for accredited chains.
- Point-of-Care Testing Channel Innovation:Mobile diagnostic units and pharmacy-based sample collection are extending reach into rural settlements beyond fixed facility networks.
- National Health Insurance Scheme Expansion:NHIS enrollment growth is creating reimbursable demand pools that reduce out-of-pocket payment friction for routine panels.
Industry Challenges
- Molecular Diagnostics Specialist Shortage:PCR platform operation and quality control require trained personnel that current educational pipelines supply inadequately.
- Accreditation Timeline Compression:MLSCN facility approval processes create operational gaps between application and permit issuance, delaying revenue commencement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Clinical Laboratory Services Market |
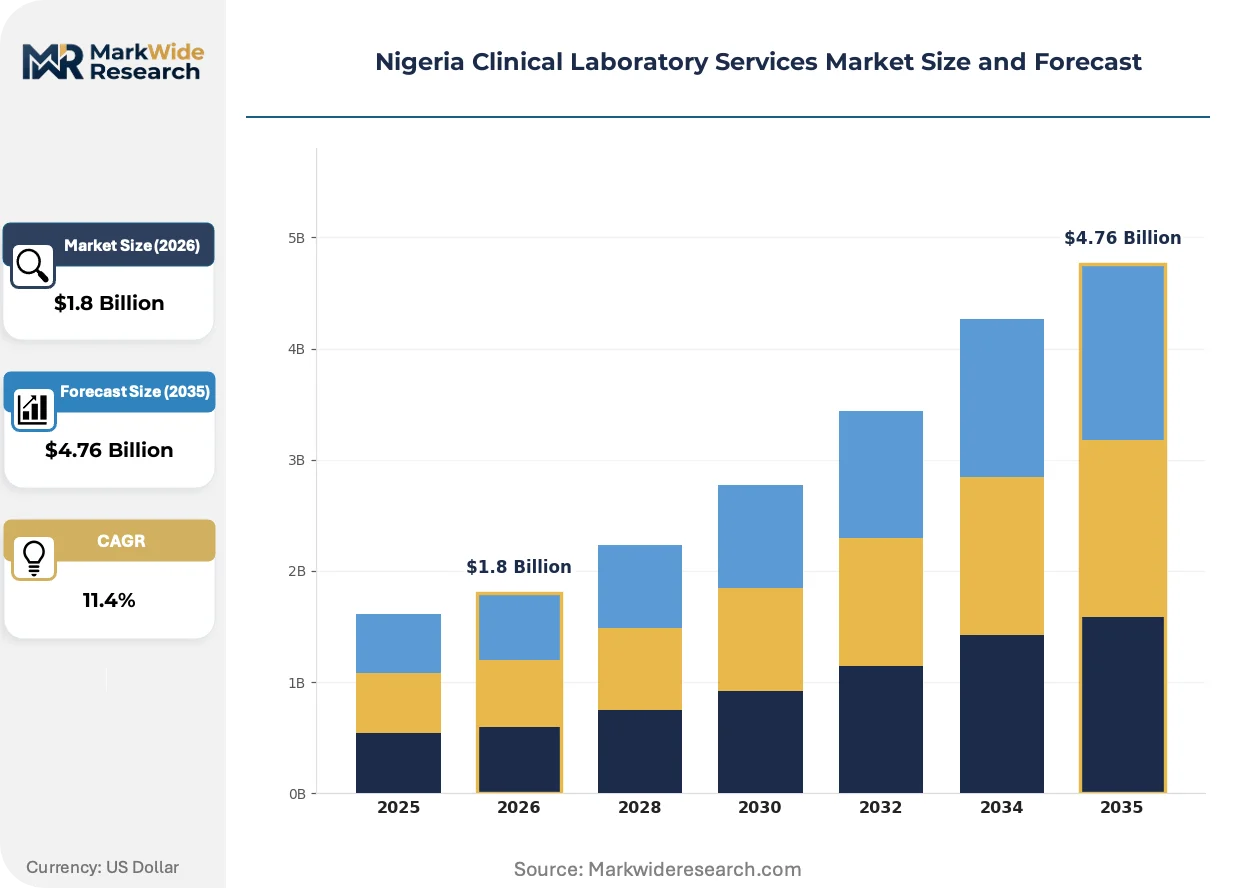
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pathology, Microbiology, Hematology, Biochemistry End User: Hospitals, Diagnostic Centers, Research Laboratories, Clinics Delivery Mode: In-Lab Testing, Point-of-Care Testing, At-Home Testing, Mobile Testing Technology: Molecular Diagnostics, Immunoassays, Automation, Workflow Management |
| Companies Covered | Mecure Healthcare, Union Diagnostic and Clinical Services PLC, Synlab Bondco PLC, PathCare Nigeria, Echo Lab (Integrated Diagnostic Holdings), Lancet Laboratories, Afriglobal Medicare, 54gene Diagnostics, LifeBridge Diagnostic Center, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Clinical Laboratory Services Market Shifts & Advancements
Automation and digital pathology are restructuring laboratory economics across Nigeria's diagnostic sector. These shifts compress manual processing costs while enabling service line expansion beyond traditional biochemistry and hematology.
Real-time PCR systems with integrated sample-to-result workflows are rendering obsolete batch-processed manual nucleic acid extraction methods. Large private laboratory networks in Lagos are deploying these platforms to capture tuberculosis and HIV viral load contracts from public health programs. The technology is rendering obsolete the previous model of centralized reference laboratory outsourcing for molecular testing.
The Medical Laboratory Science Council of Nigeria's 2023 revised facility inspection protocols now mandate documented quality management systems and external proficiency testing participation. These requirements are accelerating consolidation among smaller operators unable to absorb compliance documentation costs. Tier-2 cities including Port Harcourt and Ibadan are experiencing the fastest accreditation-driven filtering as local laboratories face upgrade-or-exit decisions.
Corporate wellness programs and health maintenance organizations are consolidating diagnostic procurement around preferred provider networks with guaranteed turnaround times. These buyers are displacing fragmented individual test ordering with annual panel contracts that specify service level agreements. Abuja's federal civil service and banking sector employee health schemes are exhibiting the most concentrated procurement rationalization.
Nigeria Clinical Laboratory Services Market Segmentation
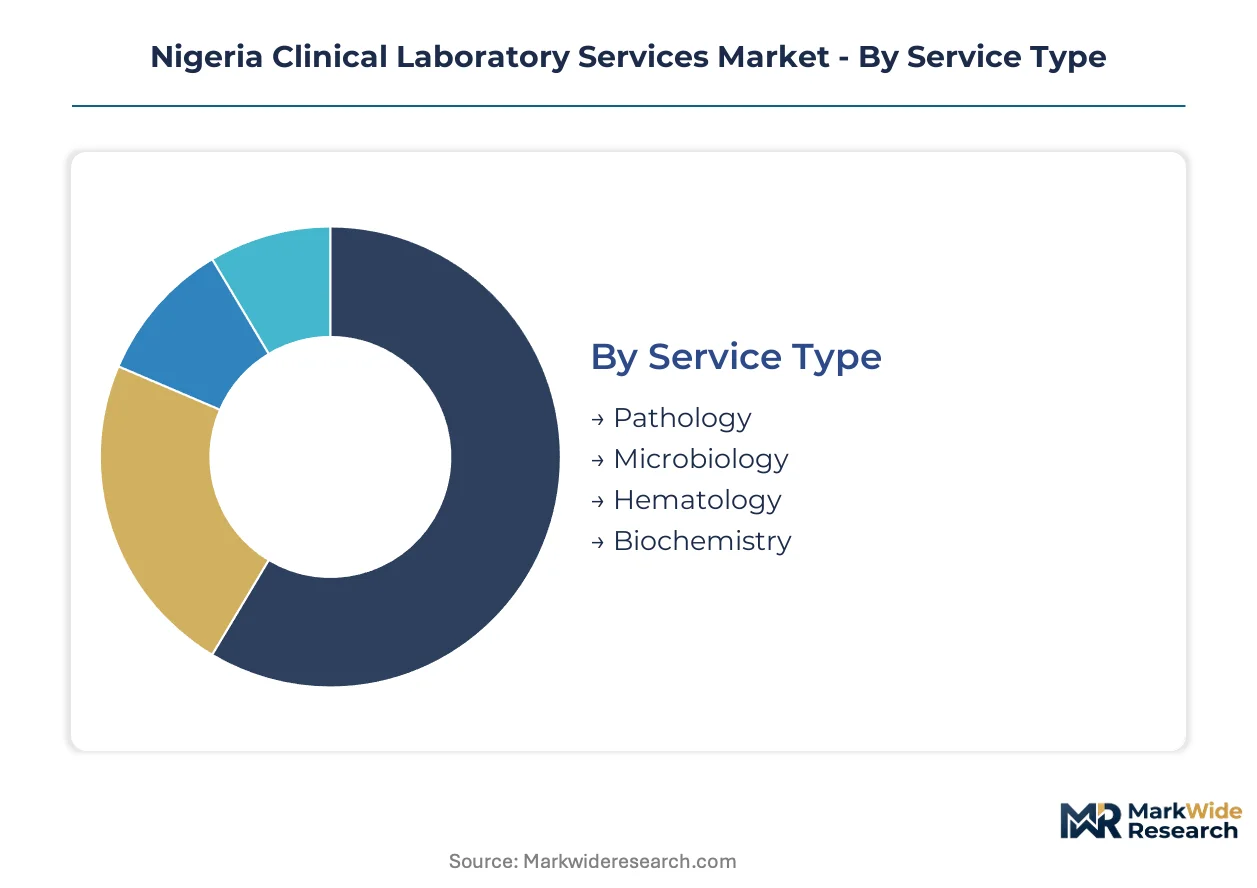
Service differentiation across Nigeria's clinical laboratory market determines equipment procurement patterns and margin structures. Each segmentation dimension reveals distinct competitive dynamics shaped by accreditation requirements and infrastructure constraints.
Service Type:
Application focus varies sharply across routine screening versus specialized disease detection, with capital intensity and reimbursement rates diverging accordingly.
- Pathology:Tissue-based diagnostic analysis encompasses histopathology and cytopathology for cancer detection. Demand clusters in Lagos private hospitals serving insured patient pools where oncology case volumes justify dedicated pathologist staffing.
- Microbiology:Culture-based and rapid diagnostic methods identify bacterial, viral, and fungal pathogens. Abuja tertiary hospitals and infectious disease reference centers drive specimen volumes for tuberculosis and antimicrobial resistance surveillance protocols.
- Hematology:Complete blood count and coagulation testing using automated cell counters. Port Harcourt diagnostic chains process high-throughput routine panels for pre-surgical screening and chronic disease monitoring.
- Biochemistry:Enzymatic and photometric analysis of metabolic markers including renal, liver, and lipid profiles. Kano private laboratories serve diabetic and hypertensive patient populations with standardized panel pricing.
Biochemistry commands the established base. The steepest expansion runs through Pathology as cancer diagnostic demand intensifies.
End User:
Customer type dictates contract structure, with institutional procurement favoring service level agreements over per-test pricing.
- Hospitals:In-house laboratory departments serving admitted patients and emergency diagnostics. Federal teaching hospitals in Lagos and Ibadan maintain the highest test volumes through captive patient flows.
- Diagnostic Centers:Standalone facilities specializing in outpatient testing and health screening. Standalone chains in Abuja's Central Business District compete through guaranteed turnaround times for corporate wellness contracts.
- Research Laboratories:Academic and clinical trial sites conducting specialized assays. University College Hospital Ibadan and Lagos University Teaching Hospital anchor genomic and biomarker research specimen processing.
- Clinics:Primary care facilities with limited on-site testing capability. General practice clinics in Kaduna and Enugu rely on courier networks to reference laboratories for panel completion.
Diagnostic Centers capture margin expansion fastest. Hospitals retain volume concentration through inpatient captive demand.
Delivery Mode:
Channel configuration determines cold chain requirements and technician deployment models across fixed and distributed networks.
- In-Lab Testing:Centralized processing with full automation and quality control infrastructure. Synlab Bondco PLC's multi-city hub model consolidates complex molecular diagnostics from satellite collection points.
- Point-of-Care Testing:Rapid diagnostic devices deployed at patient care locations. Emergency departments in Lagos trauma centers deploy cardiac marker and glucose meters for immediate clinical decision-making.
- At-Home Testing:Self-collection kits for chronic disease monitoring and infectious disease screening. Pharmacy retail chains in Abuja distribute HIV self-test and HbA1c mail-in kits to extend reach beyond facility networks.
- Mobile Testing:Vehicle-mounted laboratory units serving rural and event-based screening. Northern Nigeria health campaigns deploy mobile TB microscopy units to settlements beyond fixed laboratory coverage.
In-Lab Testing anchors revenue stability. Point-of-Care Testing gains share fastest through emergency and rural access priorities.
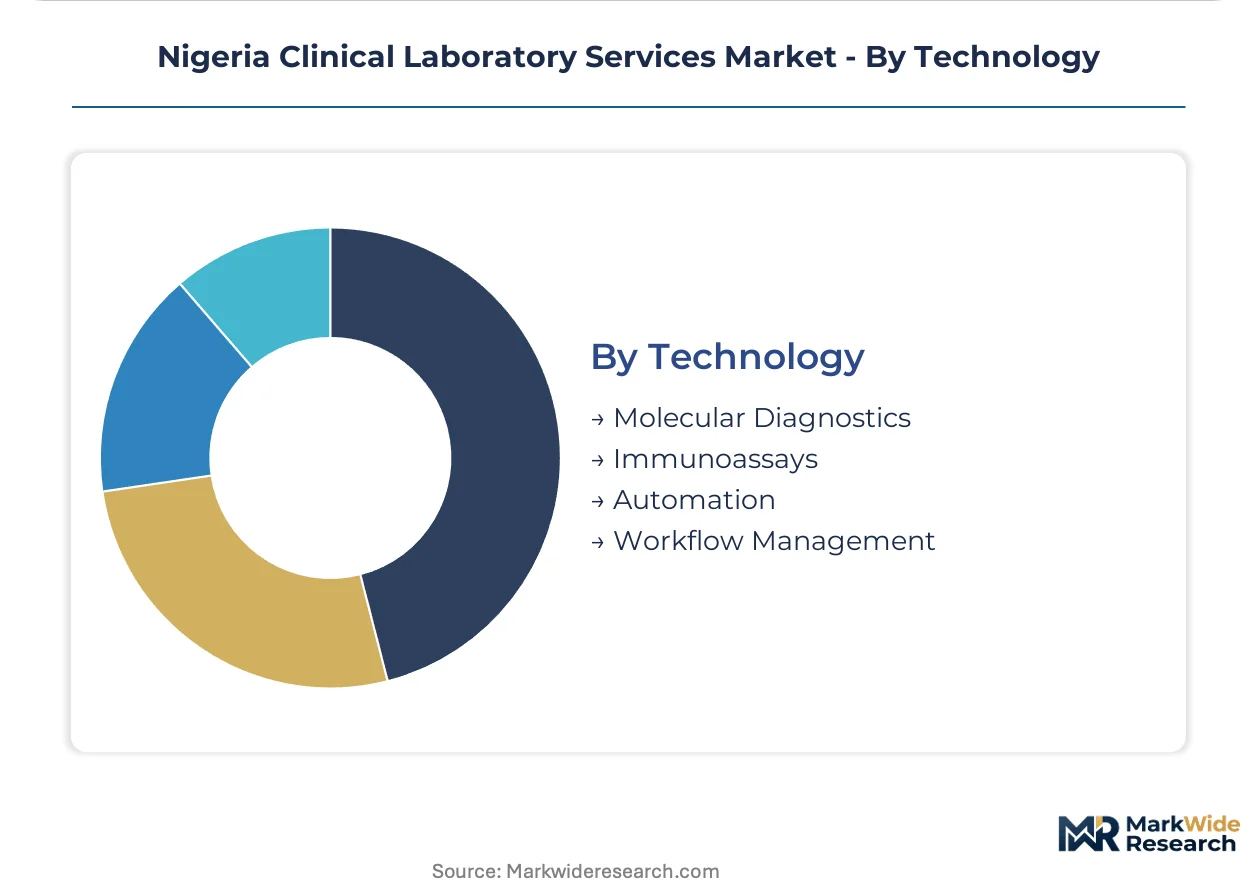
Technology:
Platform selection drives reagent supply chains and specialist staffing requirements, with automation levels determining throughput economics.
- Molecular Diagnostics:PCR and nucleic acid amplification methods for pathogen detection and genetic analysis. HIV viral load and tuberculosis testing protocols are mandating platform upgrades across MLSCN-accredited facilities.
- Immunoassays:Antibody and antigen detection using chemiluminescence and ELISA platforms. Hormone and tumor marker testing in Lagos premium diagnostic centers relies on automated immunoassay analyzers.
- Automation:Pre-analytical processing, robotic sample handling, and integrated analyzer systems. Large private laboratory networks deploy track-based automation to compress manual processing costs for high-volume biochemistry.
- Workflow Management:Laboratory information systems and digital pathology platforms for result reporting and quality tracking. MLSCN accreditation mandates are accelerating LIS adoption for documentation compliance.
Automation underpins current operational scale. Molecular Diagnostics climbs fastest as infectious disease protocols upgrade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Nigeria's urban corridors, with Lagos and Abuja buyers absorbing premium pricing for rapid turnaround while northern markets prioritize cost-minimized basic panels.
Lagos Metropolitan Corridor
Corporate wellness programs and private hospital networks drive sophisticated test demand. The Medical Laboratory Science Council of Nigeria enforces facility accreditation that filters substandard operators. Victoria Island and Ikeja clusters concentrate premium pathology services where Synlab Bondco PLC maintains multi-site processing hubs.
Federal Capital Territory Abuja
Federal civil service health schemes and diplomatic missions anchor high-volume contractual demand. NAFDAC in-vitro diagnostic registration requirements shape reagent procurement for equipped facilities. Central Business District diagnostic chains compete through guaranteed service level agreements for institutional buyers.
Port Harcourt Energy Hub
Oil sector employee health screening and expatriate medical requirements sustain premium pricing tolerance. The national health insurance scheme expansion creates reimbursable demand pools for accredited providers. Trans Amadi industrial zone laboratories process occupational health panels for energy company workforces.
Kano Northern Corridor
Chronic disease prevalence among underserved populations generates volume potential at price-sensitive tiers. Cold chain infrastructure deficits limit molecular diagnostics penetration outside major facilities. Sabon Gari district private laboratories serve diabetic and hypertensive patient populations with standardized economy pricing.
Ibadan Western Nigeria
Academic medical center research activity and teaching hospital referral networks anchor specialized assay demand. University College Hospital Ibadan maintains genomic and biomarker processing capabilities for clinical trial sponsors. Ring Road diagnostic chains extend collection networks into surrounding Oyo State settlements.
Nigeria Clinical Laboratory Services Market Competitive Landscape
Pan-African laboratory networks and domestic diagnostic chains split the market between standardized multi-city platforms and localized service specialization. Three archetypes dominate: West African hub operators with integrated logistics, premium pathology specialists concentrating oncology and histopathology, and emerging molecular diagnostics ventures capturing infectious disease protocol shifts. Consolidation pressure accelerates through MLSCN accreditation mandates that raise compliance costs for smaller facilities, while technology licensing partnerships enable rapid PCR platform deployment without captive R&D expenditure.
Within the West African hub tier, Synlab Bondco PLC exemplifies multi-city infrastructure leverage, while PathCare Nigeria and Lancet Laboratories occupy distinct positioning vectors in premium pathology and specialized oncology testing respectively. These three names illustrate how accreditation-compliant networks concentrate test volumes through compliant facility density, with each representing a strategic response to the same regulatory tightening—geographic scale, service depth, or clinical specialization as the primary competitive anchor.
| Leading Market Players |
|---|
| Mecure Healthcare |
| Union Diagnostic and Clinical Services PLC |
| Synlab Bondco PLC |
| PathCare Nigeria |
| Echo Lab (Integrated Diagnostic Holdings) |
| Lancet Laboratories |
| Afriglobal Medicare |
| 54gene Diagnostics |
| LifeBridge Diagnostic Center |
| Others |
Supply & Pricing Matrix
Apapa port clearance bottlenecks inflate landed costs for automated analyzers, concentrating supply-side leverage among distributors with bonded warehouse capacity while fragmenting downstream pricing power across MLSCN-accredited and non-accredited facility tiers. This logistics chokepoint forces capital-constrained laboratories toward reagent rental arrangements that embed equipment costs into per-test consumable pricing.
Pricing Analysis
Aftermarket service revenue from extended maintenance contracts drives lifetime value capture, with molecular diagnostics platforms commanding premium annual service agreements versus biochemistry analyzers. Three-tier pricing structure across premium, standard, and economy levels separates Synlab Bondco PLC's corporate wellness bundles from mid-tier diagnostic chains and Kano-based economy panel providers. Cost compression in economy-tier basic biochemistry is intensifying because MLSCN accreditation mandates raise fixed compliance overhead. Price-sensitive patient populations in northern Nigeria corridors absorb minimal out-of-pocket exposure, while Lagos insured corporate schemes tolerate premium turnaround guarantees.
Supply Chain Analysis
US Commerce Department export controls on advanced PCR thermal cycler technologies limit direct procurement channels, forcing Nigerian laboratories toward authorized distributor networks with documented end-user certifications. Automated analyzer supply concentrates in Germany, Japan, and the United States, while specialized molecular diagnostics reagents originate from Roche and Abbott manufacturing facilities in Singapore and Ireland. Cold chain logistics for temperature-sensitive PCR consumables rests on single-source freight forwarders with validated pharmaceutical handling credentials. Distribution runs through Lagos-based medical equipment importers holding NAFDAC establishment licenses, with satellite warehousing in Abuja and Port Harcourt serving regional laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigeria's clinical laboratory sector is approaching a platform-economics inflection as MLSCN-mandated laboratory information system interoperability forces consolidation around standardized data exchange protocols. This regulatory-driven ecosystem shift rewards accredited networks with multi-site integration capabilities.
For Market Incumbents: Insulate market position by accelerating backward integration into reagent cold chain logistics, capturing margin pools currently extracted by pharmaceutical distributors. Synlab Bondco PLC and PathCare Nigeria should preemptively acquire courier networks serving northern Nigeria corridors before accreditation mandates filter substandard competitors. Certification investment in ISO 15189 medical laboratory accreditation represents the priority defensive lever against MLSCN facility inspection tightening.
For New Entrants and Emerging Players: Northern Nigeria's Kano-Kaduna corridor presents underpenetrated laboratory density relative to chronic disease burden, offering first-mover positioning for accredited chains with economy-tier pricing. Mobile diagnostic units serving rural settlements beyond fixed facility networks capture reimbursable NHIS demand pools with minimal incumbent competition. Pharmacy-based sample collection partnerships with established retail chains provide the most penetrable go-to-market angle for capital-light market entry.
For Investors and Strategic Acquirers: Carve-out targets emerge from pan-African hospital groups divesting non-core laboratory assets to focus on clinical service delivery. Long-term viability in this sector hinges on molecular diagnostics platform scale and MLSCN accreditation compliance density rather than geographic footprint alone. The signal to watch is NHIS reimbursement rate negotiations for PCR-based tuberculosis and HIV viral load testing, which would validate premium service tier economics.
| Strategic Initiative | Industry Significance |
|---|---|
| MLSCN Accreditation Fast-Track | Accelerates facility approval timelines, enabling revenue commencement before competitors complete upgrade cycles. |
| PCR Platform Deployment Partnership | Roche and Abbott technology licensing agreements reduce captive R&D expenditure for molecular diagnostics expansion. |
| Corporate Wellness Contract Consolidation | Annual panel agreements with Abuja federal civil service schemes displace fragmented individual test ordering. |
| Cold Chain Logistics Integration | Bonded warehouse capacity at Apapa port insulates against reagent supply disruptions and currency volatility exposure. |
| Point-of-Care Testing Channel Development | Mobile diagnostic units extend reach into northern Nigeria settlements beyond fixed laboratory coverage. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laboratory managers at Synlab Bondco PLC and PathCare Nigeria, MLSCN accreditation officers, biomedical equipment distributors, and NHIS reimbursement specialists. Secondary validation drew from NAFDAC in-vitro diagnostic registration databases, MLSCN facility inspection reports, Nigerian Customs Service import records for automated analyzers, and hospital procurement contract registries. Bottom-up test volume modeling across Lagos, Abuja, Port Harcourt, Kano, and Ibadan corridors was triangulated against top-down healthcare expenditure projections.
Calibration against historical MLSCN accreditation timelines and equipment import duty structures anchored the analytical framework across the analysis window. Segmentation dimensions modeled include service type, end user category, delivery mode configuration, and technology platform. CAGRs were derived from infectious disease protocol shifts toward PCR-based methods and NHIS enrollment expansion patterns. Forecast inputs incorporated reagent supply concentration risks and power infrastructure reliability indices by urban corridor.
The forecast holds incumbent behavior within observed patterns; aggressive moves by international diagnostics conglomerates through direct subsidiary establishment would shift outcomes from distributor-dependent market structure assumptions. Material shifts in MLSCN accreditation cost trajectories or NAFDAC import registration timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Clinical Laboratory Services Market
Laboratory Services
Global Virology Specimen Collection Market
Laboratory Services
Central Lab Market
Laboratory Services
Autosampler Vials Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
Lab Mailers Market
Laboratory Services
Global Office Based Lab Market
Laboratory Services
LIMS Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
Middle East and Africa Clinical Laboratory Services Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
Laboratory Disposable Products Market
Laboratory Services
Global Clinical Reference Laboratory Market