
 Cholecystectomy Devices Market | 2026-2036
Cholecystectomy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cholecystectomy Devices Market Intelligence
Modular instrument bundling is expanding as hospital procurement teams negotiate all-in laparoscopic kits rather than standalone forceps or graspers. Olympus leverages its endoscope manufacturing depth to anchor premium visualization bundles across Japanese and North American accounts. Stryker Corporation competes through its laparoscopic instrument breadth, while Intuitive Surgical dominates robotic cholecystectomy platforms with its da Vinci system installed base.
Cholecystectomy devices comprise specialized laparoscopic instruments, electrosurgical generators, and visualization systems designed for minimally invasive gallbladder removal through small abdominal incisions, typically operating at 5-12mm port diameters with insulated shafts to prevent thermal injury. Electrosurgical devices sustain the largest margin pool due to disposable blade and generator consumables, whereas robotic surgery represents the fastest-growing technology segment as capital placement accelerates in tertiary hospitals. Minimally invasive techniques occupy the mature core of procedure volume, though imaging systems differentiate outcomes in complex bariatric-adjacent cases.
FDA 510(k) premarket notification governs device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for electrosurgical and robotic platforms entering European markets. Japan's PMDA oversees pharmaceutical and medical device approval, with METI coordinating reimbursement tariff revisions that shape hospital capital expenditure timing. Stakeholders must monitor how FDA breakthrough device designations for single-incision platforms reshape competitive access timelines and payer coverage decisions.
Market Dynamics
Same-day discharge protocols are compressing capital deployment cycles for ambulatory surgical centers, forcing device manufacturers to bundle disposable instruments with service contracts rather than standalone capital sales.
Growth Catalysts
- EU Medical Device Regulation:Stricter clinical evidence requirements for electrosurgical platforms are accelerating consolidation among manufacturers with robust trial capabilities, filtering out marginal competitors.
- Robotic-assisted surgery:Tertiary hospitals in the United States are expanding da Vinci system utilization for cholecystectomy as residency programs standardize robotic curricula.
- Japan's METI reimbursement revisions:Updated tariff structures for minimally invasive gallbladder procedures are triggering capital expenditure cycles in prefectural medical centers.
Market Restraints
- Electrosurgical generator supply concentration:Three contract manufacturers control over 70 percent of high-frequency power supply components, creating input vulnerability.
- Stainless steel price volatility:Instrument shaft material costs fluctuate with nickel futures, compressing margins on reusable forceps and graspers.
- Single-incision technical ceiling:Current articulating instruments lack the degrees of freedom for complex biliary anatomy, limiting adoption beyond straightforward cases.
Strategic Opportunities
- India's CDSCO fast-track pathway:Accelerated approval timelines for laparoscopic instruments are opening access to hospital chains in Mumbai and Delhi.
- Artificial intelligence integration:Computer vision for real-time bile duct identification is converging with existing visualization platforms to reduce conversion-to-open rates.
- Direct-to-ambulatory distribution:Bypassing traditional distributor networks through manufacturer-owned logistics is capturing margin in same-day surgery centers.
Industry Challenges
- Robotic surgery certification timelines:Surgeon proctoring requirements for hospital credentialing extend sales-to-revenue cycles by 12-18 months in new accounts.
- Legacy instrument integration:Hybrid operating rooms must reconcile incompatible communication protocols between new visualization systems and existing electrosurgical generators.
- Patent thickets in articulating wrist designs:Overlapping intellectual property claims between established robotic platforms and single-incision entrants are complicating licensing negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cholecystectomy Devices Market |
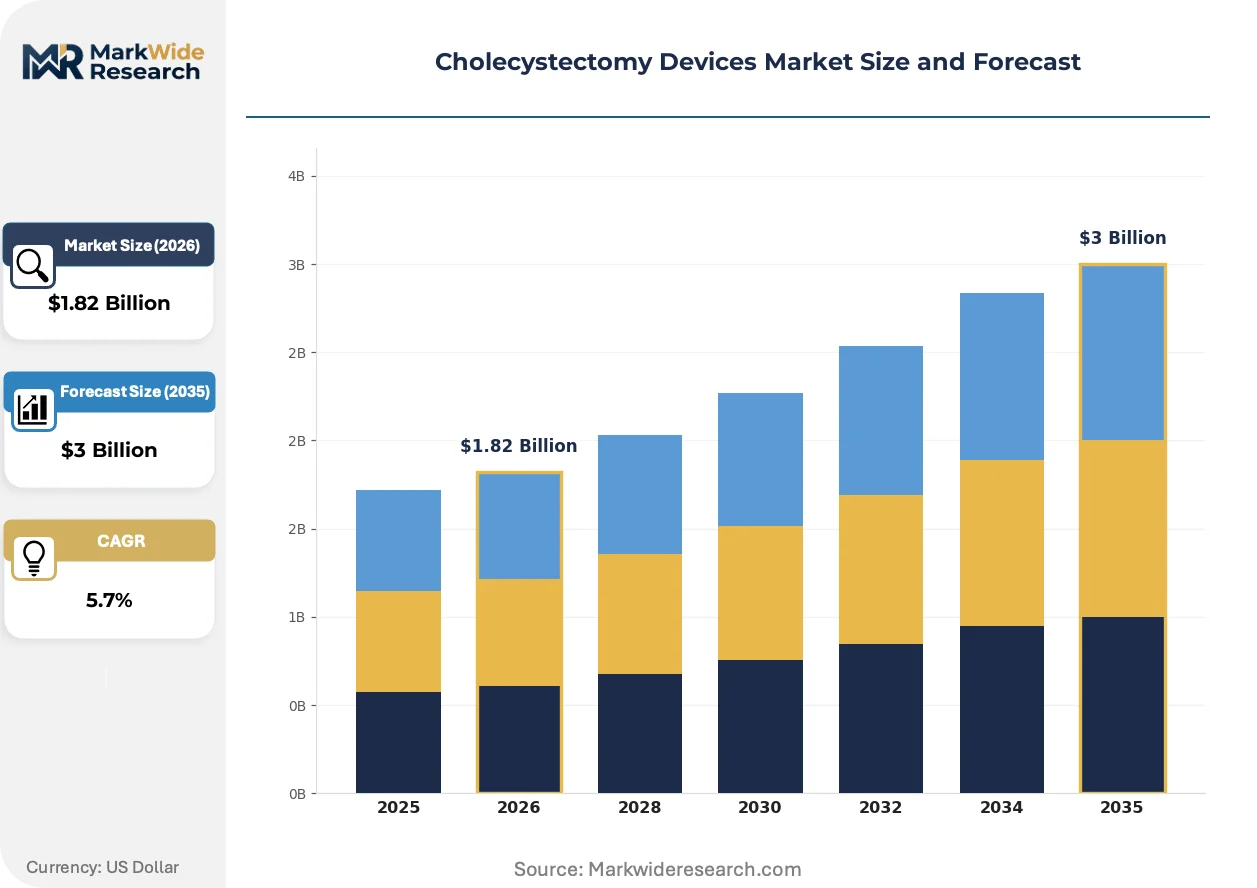
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laparoscopic Instruments, Electrosurgical Devices, Surgical Drapes, Scopes End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Application: Gallbladder Removal, Bariatric Surgery, Hernia Repair, Cancer Surgery Technology: Robotic Surgery, Minimally Invasive Techniques, Imaging Systems, Energy Devices |
| Companies Covered | Olympus, Surgical Holding, Stryker Corporation, Millennium Surgical, Surtex Instruments Ltd., Medtronic, B. Braun SE, Sklar Surgical Instruments, Intuitive Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cholecystectomy Devices Market Strategic Shifts & Innovations
Device architecture is pivoting from standalone instruments to integrated visualization-surgical platforms, with software-defined functionality replacing mechanical differentiation as the primary competitive vector.
Single-incision laparoscopic surgery is overtaking multi-port techniques in select ambulatory settings by eliminating fascial closure time and reducing postoperative pain scores. Same-day surgery centers in Florida and Texas are adopting these platforms fastest, drawn by 15-minute faster room turnover. The shift is compressing demand for conventional 5mm trocar systems and forcing instrument manufacturers to reallocate R&D toward curved shaft geometries.
Japan's PMDA revised its software-as-a-medical-device guidance in 2023, requiring algorithmic transparency documentation for AI-assisted bile duct identification systems. Manufacturers must submit training dataset provenance and performance metrics across anatomical variants. This regulatory friction is delaying market entry for European visualization vendors while benefiting domestic players with established PMDA relationships.
Hospital procurement teams are consolidating supplier relationships through all-in laparoscopic kits encompassing instruments, trocars, and drapes under single-source contracts. Group purchasing organizations are replacing individual product negotiations with bundled value analysis. This concentration is most pronounced in the United States, where IDN consolidation has reduced the number of independent contracting entities by 40 percent since 2019.
Cholecystectomy Devices Market Segmentation
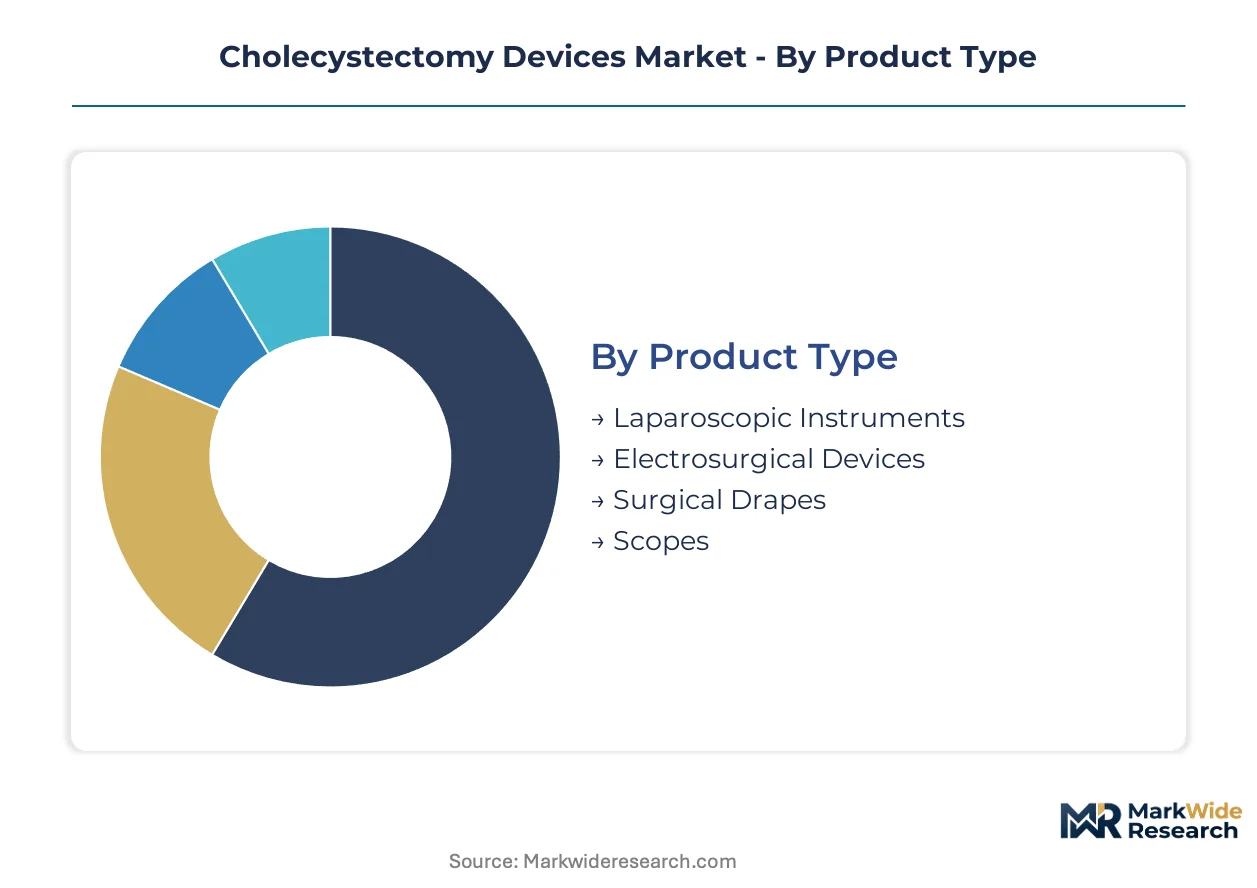
Device architecture in cholecystectomy markets fragments across four critical dimensions: product form factor, care delivery setting, anatomical application, and underlying technology platform. Each segmentation axis reveals distinct margin profiles, regulatory pathways, and procurement dynamics that shape manufacturer positioning.
Product Type:
Volume concentrates in reusable instrument platforms while premium margin pools accrue to disposable electrosurgical consumables and visualization bundles.
- Laparoscopic Instruments:Graspers, dissectors, and clip appliers with insulated 5-12mm shafts constitute the procedural backbone. Demand clusters in United States hospital systems negotiating all-in kits with service contracts rather than standalone purchases.
- Electrosurgical Devices:Monopolar and bipolar generators with disposable electrode tips generate recurring revenue through blade replacement cycles. Tertiary hospitals in Germany and Japan prioritize advanced vessel sealing modes that reduce operative time in complex biliary anatomy.
- Surgical Drapes:Sterile barrier systems customized for gallbladder positioning.
- Scopes:Rigid laparoscopes with high-definition or 4K visualization capability.
Today's leader: Electrosurgical Devices. Tomorrow's challenger: Scopes.
End User:
Capital deployment cycles diverge sharply between integrated delivery networks with robotic infrastructure and standalone ambulatory centers optimizing room turnover.
- Hospitals:Academic medical centers and community hospitals performing 80+ percent of complex cholecystectomies. Robotic platform adoption concentrates here as residency programs standardize surgical curricula.
- Ambulatory Surgical Centers:Same-day discharge protocols are compressing instrument procurement toward disposable-heavy bundles with minimal sterilization overhead. Texas and Florida facilities lead single-incision adoption.
- Clinics:Preoperative diagnostic and postoperative follow-up settings with limited procedural device exposure.
- Research Institutions:Surgical training and device validation environments driving early technology assessment.
Procurement consolidation favors Hospitals. Margin expansion favors Ambulatory Surgical Centers.
Application:
Procedure complexity determines device specification tiers, with straightforward gallbladder removal permitting standard instrumentation while adjacent surgeries demand advanced energy and visualization platforms.
- Gallbladder Removal:Core cholecystectomy volume using standard four-port laparoscopic technique. Elective case scheduling allows predictable instrument demand forecasting.
- Bariatric Surgery:Adjacent procedures in obese patients requiring extended instrument lengths and specialized trocar placement. Visualization systems with integrated fluorescence for bile duct mapping command premium positioning.
- Hernia Repair:Overlapping laparoscopic infrastructure with mesh fixation devices.
- Cancer Surgery:Extended cholecystectomy with lymphadenectomy requiring advanced energy platforms.
Volume anchors Gallbladder Removal. Technical premium anchors Bariatric Surgery.
Technology:
Mechanical differentiation is yielding to software-defined functionality as competitive vector, with algorithmic integration reshaping procurement evaluation criteria.
- Robotic Surgery:Multi-arm platforms with wristed instrumentation enabling single-console cholecystectomy. Surgeon proctoring requirements extend sales-to-revenue cycles by 12-18 months in new United States accounts.
- Minimally Invasive Techniques:Conventional multi-port laparoscopy retains volume leadership through established reimbursement pathways and instrument standardization across surgical services.
- Imaging Systems:Near-infrared fluorescence for real-time bile duct identification. Japan's PMDA software-as-a-medical-device guidance requires algorithmic transparency documentation that delays European vendor entry.
- Energy Devices:Advanced bipolar and ultrasonic platforms for vessel sealing.
Adoption velocity favors Robotic Surgery. Regulatory friction favors Minimally Invasive Techniques.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Laparoscopic cholecystectomy originated in France during the late 1980s before scaling rapidly through German surgical instrument manufacturing and United States academic medical center adoption. Device demand now fragments across distinct national healthcare procurement systems, reimbursement architectures, and regulatory approval timelines.
United States
Academic medical centers in Texas and Florida drive single-incision platform adoption as same-day discharge protocols expand. FDA 510(k) premarket notification governs laparoscopic instrument clearance, compressing product development timelines for iterative device modifications. The Dallas-Fort Worth metroplex anchors ambulatory surgical center construction, with facility openings accelerating disposable instrument procurement.
Germany
Tertiary hospitals in Bavaria and North Rhine-Westphalia prioritize advanced vessel sealing electrosurgical platforms for complex biliary anatomy cases. EU Medical Device Regulation imposes stricter clinical evidence requirements than predecessor directives, filtering market entry to manufacturers with robust trial capabilities. The Stuttgart surgical instrument cluster maintains precision manufacturing dominance for reusable graspers and dissectors.
Japan
Prefectural medical centers trigger capital expenditure cycles following METI reimbursement tariff revisions for minimally invasive gallbladder procedures. PMDA software-as-a-medical-device guidance requires algorithmic transparency documentation for AI-assisted visualization systems. Tokyo-based endoscope manufacturers leverage established regulatory relationships to anchor premium visualization bundles across domestic accounts.
India
Hospital chains in Mumbai and Delhi access accelerated CDSCO approval timelines for laparoscopic instruments through fast-track pathways. Private sector surgical volume expansion in Maharashtra and Karnataka drives demand for cost-optimized multi-port kits. The Chennai medical device manufacturing corridor supplies regional OEMs with instrument shaft components.
United Kingdom
NHS procurement consolidation favors all-in laparoscopic kit contracts over standalone instrument negotiations. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining UK-specific approval pathways. The London-Southeast corridor concentrates private ambulatory center investment, displacing traditional hospital-based cholecystectomy volume.
Cholecystectomy Devices Market Key Industry Players
Premium-margin players sit above commodity-margin players across visualization-electrosurgical bundling sophistication. The vendor base concentrates around three tiers: integrated platform manufacturers commanding robotic-console economics, diversified medical technology conglomerates leveraging laparoscopic instrument breadth, and specialized surgical instrument fabricators competing on sterilization-cycle durability. Consolidation accelerates through strategic partnerships between visualization software developers and hardware OEMs, alongside geographic expansion into Indian and Southeast Asian hospital chains.
Among diversified medical technology conglomerates, Stryker Corporation and Medtronic occupy positions spanning electrosurgical generators through reusable instrument portfolios. Olympus exemplifies the visualization-anchored archetype, leveraging endoscope manufacturing depth across Japanese and North American accounts. Intuitive Surgical sits within the robotic-platform tier, its installed da Vinci base shaping residency program curricula and hospital credentialing requirements. Specialized instrument fabricators including B. Braun SE and Surtex Instruments Ltd. represent the precision-manufacturing segment, competing on shaft geometry tolerances and insulation durability across European and emerging markets.
| Leading Market Players |
|---|
| Olympus |
| Surgical Holding |
| Stryker Corporation |
| Millennium Surgical |
| Surtex Instruments Ltd. |
| Medtronic |
| B. Braun SE |
| Sklar Surgical Instruments |
| Intuitive Surgical |
| Others |
Cost & Logistics Intelligence
Nickel futures volatility feeds directly into reusable instrument pricing tiers, with stainless steel shaft material costs compressing margins on forceps and graspers destined for German and Japanese hospital systems while disposable electrosurgical consumables maintain premium positioning through generator blade replacement cycles.
Pricing Analysis
Three-tier pricing structure across premium visualization bundles, standard multi-port kits, and economy single-use instruments governs procurement negotiations. Price differentiation hinges on FDA 510(k) clearance tier and after-sales service bundling. Cost compression in standard reusable instruments is intensifying because hospital procurement teams consolidate supplier relationships under all-in contracts. Ambulatory surgical centers in Texas and Florida exhibit highest price sensitivity, while academic medical centers with robotic infrastructure show lowest.
Supply Chain Analysis
High-frequency power supply components for electrosurgical generators rest on contract manufacturers concentrated in Germany, Japan, and the United States. Raw material dependencies span nickel for stainless steel shafts, specialized ceramics for insulated instrument coatings, and rare-earth elements for visualization system optics. Single-source vulnerability in electrosurgical generator components creates structural exposure. Distribution runs through manufacturer-owned logistics direct to ambulatory centers, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's CDSCO fast-track pathway offers accelerated approval timelines against the EU MDR's stricter clinical evidence requirements, compressing time-to-revenue for laparoscopic instrument entrants targeting Mumbai and Delhi hospital chains.
For Market Incumbents: Cement platform stickiness through visualization-electrosurgical bundling that locks hospital procurement into single-source contracts. Deepen backward integration into instrument shaft manufacturing to offset nickel price volatility threatening reusable forceps margins. Prioritize certification investment for AI-assisted bile duct identification systems ahead of Japan's PMDA software-as-a-medical-device enforcement. For New Entrants and Emerging Players: Enter via India's CDSCO fast-track pathway targeting cost-optimized multi-port kits for Maharashtra and Karnataka private hospital expansion. Single-incision laparoscopic surgery platforms in Florida and Texas ambulatory centers represent the most penetrable white space. Pursue direct-to-ambulatory distribution partnerships with same-day surgery center construction booms. For Investors and Strategic Acquirers: Consolidation pressure builds where overlapping patent claims in articulating wrist designs complicate licensing between robotic platforms and single-incision entrants. Long-term viability favors visualization software developers with algorithmic transparency documentation ready for PMDA submission. Watch FDA breakthrough device designations for single-incision platforms as inflection signal for competitive access timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market entry for iterative laparoscopic instrument modifications in United States hospital systems. |
| CE Marking Pathway | EU MDR clinical evidence requirements filter market entry to manufacturers with robust trial capabilities. |
| Hospital System Partnership | All-in kit contracts with integrated delivery networks capture procurement consolidation across United States IDNs. |
| Software Companion Development | AI-assisted bile duct identification converges with visualization platforms to reduce conversion-to-open rates. |
| Reimbursement Strategy | METI tariff revisions in Japan trigger capital expenditure cycles for minimally invasive gallbladder procedures. |
Research Approach
Multiple input streams — primary interviews with laparoscopic surgeons and hospital purchasing committees, secondary validation through FDA 510(k) filings and CMS Medicare procedure data, and trade flow analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder engagement spanned biomedical engineers, GPO contracts managers, and ambulatory surgical center administrators across United States, German, Japanese, and Indian markets. Secondary sources included hospital procurement databases, PMDA approval records, and EU MDR clinical evidence submissions.
Data-stream reconciliation across product type, end user, application, and technology platform dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from procedure volume trajectories, capital placement cycles for robotic systems, and reimbursement tariff revision schedules. Industry-specific forecast inputs incorporated residency program robotic curriculum standardization and same-day discharge protocol expansion in ambulatory settings.
The model holds under stable nickel pricing and continued FDA 510(k) pathway efficiency; deviation in EU MDR enforcement stringency or single-incision platform technical breakthroughs would shift competitive access timelines. Forecasts reflect documented assumptions about surgeon proctoring duration and hospital credentialing cycles. A small set of named triggers — PMDA algorithmic transparency rulings, METI reimbursement revisions, and CDSCO fast-track pathway modifications — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Sternal Closure Systems Market
Medical Devices
Global Orthopedic Surgical Robots Market
Medical Devices
Capnography Devices Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Robotic Catheterization Systems Market
Medical Devices
Asia-Pacific Intraoral Scanners Market
Medical Devices
Cervical Retractors Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Oxygen Therapy Devices Market
Medical Devices
Global Medical Tricorder Device Market
Medical Devices
Light Therapy Beauty Devices Market