
 US Contact Lenses Market | 2026-2036
US Contact Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
US Contact Lenses Market Insights
Subscription-based lens replacement programs is consolidating recurring revenue models across the US contact lens value chain. Johnson & Johnson Vision Care, Inc. leverages direct-to-consumer auto-ship platforms to sustain high patient retention rates. Alcon Inc. anchors its market position through extensive optometrist rebate programs. The Cooper Companies, Inc. differentiates via specialty toric and multifocal portfolios that command premium positioning.
US contact lenses are thin, curved polymer discs—typically 8.0–14.5 mm in diameter and 0.05–0.30 mm center thickness—designed to refract light directly onto the retina for vision correction or therapeutic corneal reshaping. Silicone hydrogel materials now dominate soft lens formulations due to superior oxygen permeability exceeding 100 Dk/t units, reducing hypoxia-related complications during extended wear. Soft contact lenses generate the highest volume flows through retail channels, while scleral lenses capture concentrated margin pools in therapeutic applications for irregular corneas. Silicone hydrogel leads material substitution trends as practitioners phase out conventional hydrogel for daily wear prescriptions.
FDA 510(k) premarket notification requirements govern all new contact lens introductions, with the agency enforcing ISO 18369 biocompatibility standards for ocular surface safety. The FTC Contact Lens Rule mandates prescription release to patients, enabling channel competition between optometry clinics and online retail platforms. State-level optometry practice acts in California, Texas, and New York further shape dispensing authority and telehealth fitting permissions. Stakeholders must monitor evolving FDA guidance on myopia control device classifications and state legislative pushes to expand online prescription verification requirements.
Market Dynamics
Silicone hydrogel material substitution is compressing legacy hydrogel manufacturing capacity while FDA 510(k) clearance pathways accelerate optical design innovation cycles, forcing incumbent suppliers to retool production lines or cede daily disposable segments.
Growth Catalysts
- FTC Contact Lens Rule prescription portability:The mandate enables online retail platforms to compete directly with optometry clinics, expanding patient access to replacement lenses through direct-to-consumer channels.
- Myopia control device classifications:FDA guidance on optical designs for pediatric populations is opening therapeutic indications beyond refractive correction into axial length management.
- California-Texas-Florida demand concentration:Large clinic networks and aging demographics in these states sustain high replacement volumes for toric and multifocal prescriptions.
Market Restraints
- Silicone hydrogel raw material concentration:Specialty monomer supply chains concentrate among limited chemical suppliers, creating input cost volatility for lens manufacturers.
- State-level optometry practice act fragmentation:California, New York, and Texas maintain divergent telehealth fitting permissions, complicating national distribution strategies.
- Refractive surgery substitution:LASIK and SMILE procedures continue capturing younger myopic patients who would otherwise convert to long-term contact lens wearers.
Strategic Opportunities
- Subscription auto-ship penetration:Direct-to-consumer platforms in Texas and Florida demonstrate patient retention advantages over traditional clinic dispensing models.
- Scleral lens therapeutic expansion:Irregular cornea applications including keratoconus and post-surgical ectasia represent underpenetrated margin pools beyond standard refractive correction.
- ISO 18369 biocompatibility convergence:Harmonized international safety standards are reducing regulatory duplication costs for manufacturers pursuing multi-market registrations.
Industry Challenges
- Optometrist fitting skill specialization:Scleral and orthokeratology lens modalities require advanced corneal topography interpretation capabilities that general practitioners often lack.
- 510(k) submission timeline compression:Novel optical geometries demand extensive clinical validation to satisfy FDA substantial equivalence determinations, stretching R&D cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Contact Lenses Market |
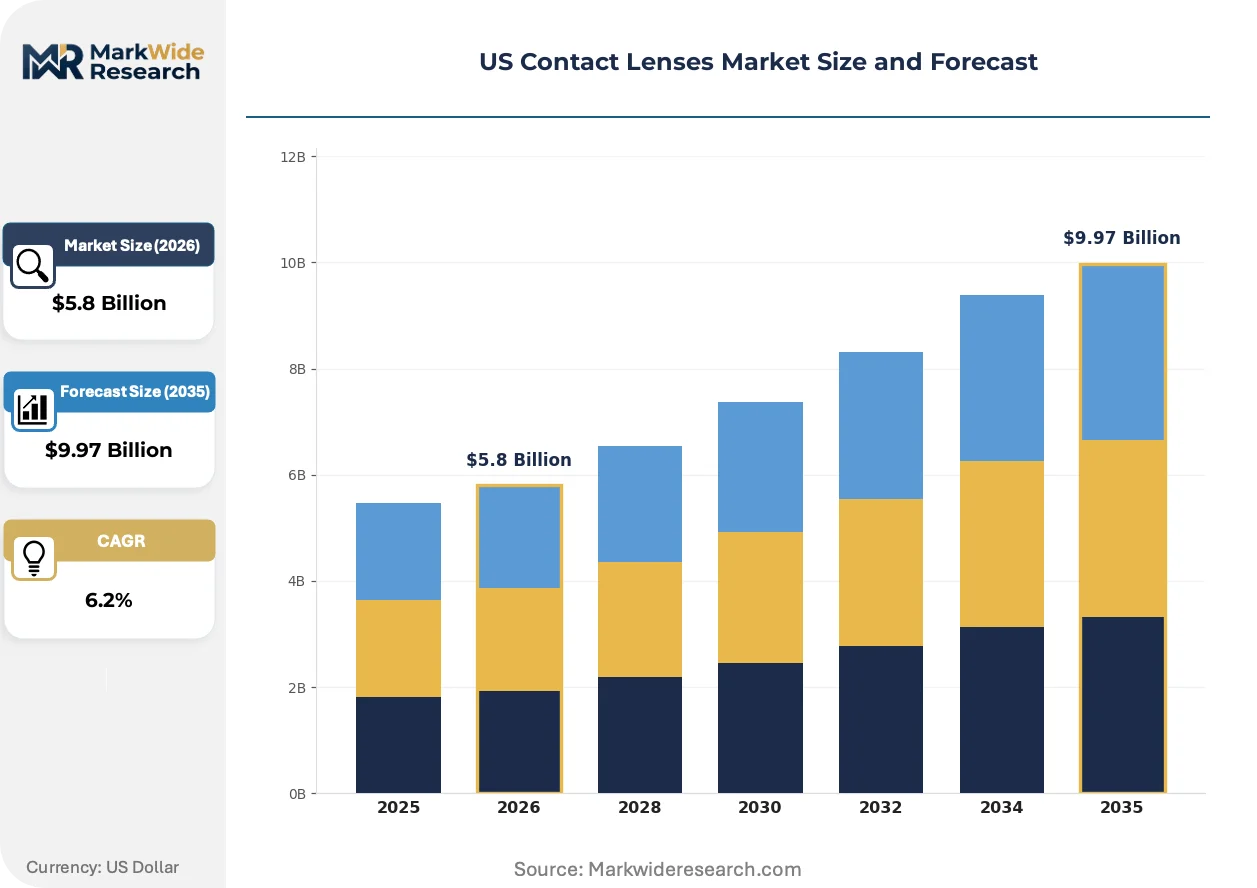
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.97 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Contact Lenses, Rigid Gas Permeable, Hybrid Lenses, Scleral Lenses, Cosmetic Lenses Material: Hydrogel, Silicone Hydrogel, PMMA, Fluorosilicone Acrylate, Silicone Acrylate Application: Myopia Correction, Hyperopia Correction, Astigmatism Correction, Presbyopia, Therapeutic Use End User: Optometry Clinics, Optical Retailers, Eye Hospitals, Ophthalmology Centers, Online Retail Platforms |
| Companies Covered | The Cooper Companies, Inc., Carl Zeiss Meditec AG, Johnson & Johnson Vision Care, Inc., Menicon Co., Ltd., HOYA Corporation, Bausch & Lomb Incorporated, EssilorLuxottica, SynergEyes Inc., Alcon Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Contact Lenses Market Trends and Innovations
Electronics integration into ocular surface devices is electrifying competitive boundaries between traditional optics and digital health monitoring, forcing material scientists to reconcile biocompatibility with sensor conductivity requirements.
Silicone hydrogel formulations with embedded tear film biosensors are electrifying the preventive eye care segment. Early adopters in diabetes management and glaucoma monitoring programs pilot these platforms for continuous intraocular pressure tracking. The convergence is electrifying partnerships between lens manufacturers and digital health platforms previously outside the optical value chain.
FDA draft guidance on myopia control device classifications is reshaping pediatric prescription protocols. The framework distinguishes optical designs with axial length modification claims from standard refractive correction, triggering separate clinical trial requirements. Manufacturers targeting the under-18 segment are responding with dedicated juvenile safety databases.
Younger demographics in California and Texas compress replacement cycles toward daily disposable modalities. Online retailers capture this shift through subscription platforms that bypass traditional clinic dispensing economics. The behavioral pivot is most visible among 18-34 year-old myopes who prioritize convenience over per-unit cost optimization.
US Contact Lenses Market Segmentation
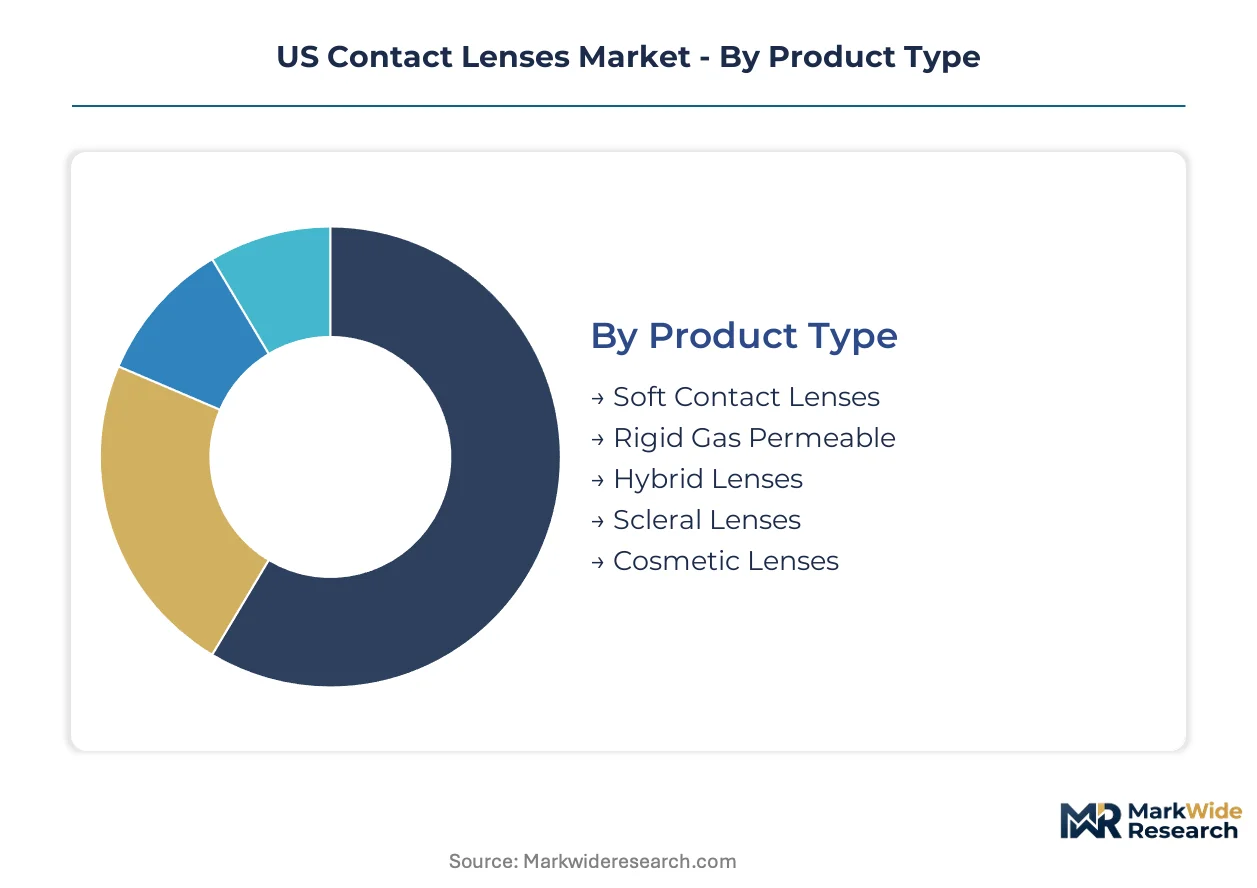
Contact lens segmentation reveals distinct procurement patterns across vision correction modalities. Material chemistry and replacement frequency drive margin stratification, while channel economics reshape patient access pathways.
Product Type:
Patient tolerance and wear duration separate buyers across lens construction categories.
- Soft Contact Lenses:Silicone hydrogel formulations dominate daily disposable prescriptions in California and Texas, where younger demographics prioritize convenience over per-unit economics. Extended wear variants sustain volume in aging populations requiring multifocal correction.
- Scleral Lenses:Large-diameter designs vault over irregular corneas for keratoconus and post-surgical ectasia patients. Texas and Florida eye hospitals generate concentrated margin pools as fitting complexity limits general practitioner participation.
- Rigid Gas Permeable:High-oxygen permeability suits overnight orthokeratology protocols for pediatric myopia management.
- Hybrid Lenses:Rigid center with soft skirt combines visual acuity with comfort for astigmatic prescriptions.
- Cosmetic Lenses:Plano and corrective tinted options circulate through online retail platforms with minimal professional oversight.
Volume sits with soft lenses; growth tilts toward scleral modalities.
Material:
Biocompatibility certification and oxygen transmission rates stratify supplier positioning.
- Silicone Hydrogel:Dk/t values exceeding 100 units reduce hypoxia-related complications during extended wear. FDA 510(k) clearances for novel silicone hydrogel geometries accelerate replacement of legacy hydrogel platforms in daily disposable segments.
- Hydrogel:Conventional poly-HEMA formulations retain cost-sensitive weekly and monthly replacement prescriptions. California Medicaid programs and discount optical retailers sustain residual demand as manufacturers phase production toward silicone hydrogel capacity.
- Fluorosilicone Acrylate:High Dk rigid materials suit overnight orthokeratology and extended wear rigid lens designs.
- Silicone Acrylate:Moderate Dk rigid formulations balance oxygen permeability with deposit resistance for conventional RGP wearers.
- PMMA:Legacy polymethyl methacrylate persists in specialty therapeutic applications with limited oxygen requirements.
Manufacturing capacity concentrates on silicone hydrogel; hydrogel contracts toward price-sensitive channels.
Application:
Clinical outcome metrics and reimbursement pathways differentiate prescriber selection.
- Myopia Correction:Axial length management claims trigger FDA myopia control device classifications distinct from standard refractive correction. California pediatric practices pilot optical designs with juvenile safety databases for under-18 populations.
- Presbyopia:Multifocal and monovision approaches command premium positioning in Florida's aging demographic clusters. Online subscription platforms capture replacement volume as patients bypass traditional clinic dispensing economics.
- Astigmatism Correction:Toric lens geometries with stabilization zones address corneal curvature asymmetry.
- Hyperopia Correction:Plus-powered spherical designs serve farsighted prescriptions across age demographics.
- Therapeutic Use:Bandage lenses and drug delivery platforms address corneal healing and ocular surface disease.
Refractive correction holds volume; myopia control climbs fastest on regulatory pathway expansion.
End User:
Prescription authority and fitting reimbursement rates structure channel economics.
- Optometry Clinics:Comprehensive eye examinations with corneal topography sustain specialty toric and multifocal fitting revenue. Texas and California practice acts govern telehealth permissions that constrain or enable remote prescription verification.
- Online Retail Platforms:FTC Contact Lens Rule prescription portability enables direct-to-consumer auto-ship models. Younger demographics in Florida and Texas compress replacement cycles through subscription bypass of clinic dispensing markups.
- Optical Retailers:Big-box and independent chains leverage volume purchasing for standard spherical prescriptions.
- Eye Hospitals:Scleral and therapeutic lens fitting concentrates in academic medical centers with corneal specialist access.
- Ophthalmology Centers:Post-surgical and disease-related therapeutic applications align with surgical practice referrals.
Clinic dispensing anchors volume; online platforms gain share on convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing capacity concentrates in the Northeast and Midwest, while patient consumption clusters in Sun Belt states with aging demographics and large optometry networks. This geographic mismatch shapes distribution economics and regulatory compliance burdens across state lines.
California
Silicone hydrogel daily disposables dominate prescriptions among younger demographics in Los Angeles and San Francisco Bay Area metro clusters. The state's Board of Optometry enforces telehealth fitting restrictions that complicate online prescription verification. Stanford and UCLA eye hospitals anchor scleral lens fitting specialization for irregular cornea cases.
Texas
Houston and Dallas-Fort Worth sustain high toric and multifocal replacement volumes through large clinic networks and aging suburban populations. The Texas Optometry Board maintains distinct telehealth permissions that enable hybrid dispensing models. Austin's technology corridor incubates direct-to-consumer subscription platforms bypassing traditional clinic economics.
Florida
Miami and Tampa Bay retirement communities drive presbyopia correction demand with premium multifocal positioning. The Florida Board of Optometry regulates prescription release timelines under FTC Contact Lens Rule implementation. Bascom Palmer Eye Institute in Miami anchors therapeutic scleral fitting for post-surgical ectasia patients.
New York
Manhattan and Long Island optometry practices concentrate specialty fitting revenue for complex astigmatism and multifocal prescriptions. The state's professional regulation diverges from Texas and California on remote prescription verification, constraining online platform penetration. Columbia and NYU eye centers drive orthokeratology adoption for pediatric myopia management.
Illinois
Chicago metro area manufacturing plants supply hydrogel and silicone hydrogel raw materials to domestic lens fabricators. The Illinois Department of Financial and Professional Regulation enforces optometry practice acts affecting telehealth dispensing authority. Midwest distribution hubs in Rockford and Peoria serve replacement lens logistics for surrounding states.
US Contact Lenses Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the US contact lens value chain. Four multinational conglomerates control material formulation and optical design IP, while regional distributors and online platforms capture patient-facing revenue. The market structures around three archetypes: integrated material-to-lens manufacturers, specialty therapeutic designers, and direct-to-consumer subscription operators. Competitive moves concentrate on auto-ship platform expansion and optometrist rebate program intensification.
Among integrated manufacturers, Johnson & Johnson Vision Care, Inc. and Alcon Inc. anchor the daily disposable silicone hydrogel segment through distinct channel strategies. The Cooper Companies, Inc. occupies a position within specialty toric and multifocal portfolios. These three entities exemplify the capital-intensive archetype that dominates FDA 510(k) clearance activity and material science R&D.
| Leading Market Players |
|---|
| The Cooper Companies, Inc. |
| Carl Zeiss Meditec AG |
| Johnson & Johnson Vision Care, Inc. |
| Menicon Co., Ltd. |
| HOYA Corporation |
| Bausch & Lomb Incorporated |
| EssilorLuxottica |
| SynergEyes Inc. |
| Alcon Inc. |
| Others |
Pricing and Supply Chain Analysis
Specialty silicone monomer feedstock costs cascade through three pricing tiers as manufacturers allocate limited chemical supplier capacity between premium daily disposable formulations and residual hydrogel production for Medicaid programs.
Pricing Analysis
Margin tightening in the daily disposable tier reflects silicone hydrogel raw material concentration among limited chemical suppliers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared silicone hydrogel dailies from conventional hydrogel monthlies and unbranded discount alternatives. Cost compression accelerates as Johnson & Johnson Vision Care and Alcon intensify rebate programs for optometrist dispensing. Online retail platforms serving younger demographics exhibit lowest price sensitivity; Medicaid-sustained hydrogel channels face acute cost pressure.
Supply Chain Analysis
Freight cost volatility from Southeast Asian specialty monomer suppliers compounds input cost uncertainty for domestic lens fabricators. Manufacturing capacity concentrates in Ireland, Singapore, and the US Northeast, with silicone hydrogel polymerization dependent on Japanese and German chemical intermediates. Single-source vulnerability in fluorosilicone acrylate precursors threatens rigid gas permeable lens production. Distribution runs through optometry clinic networks, online subscription platforms, and big-box optical retailers in descending volume share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone hydrogel material substitution is forcing consolidation as legacy hydrogel manufacturers face stranded capacity and margin compression.
For Market Incumbents: Deepen backward integration into specialty monomer supply through captive chemical partnerships or toll manufacturing agreements. Secure FDA 510(k) clearance pipelines for myopia control device classifications before pediatric protocol standardization locks in design winners. Alcon and Johnson & Johnson Vision Care must defend toric and multifocal positioning against Cooper Companies' specialty portfolio expansion.
For New Entrants and Emerging Players: Irregular cornea patients in Texas and Florida eye hospitals represent an underserved buyer archetype with concentrated margin pools and limited general practitioner competition. Scleral lens fitting specialization offers white-space entry with premium pricing power. Target telehealth-enabled subscription models in states with permissive optometry practice acts.
For Investors and Strategic Acquirers: FDA draft guidance finalization on myopia control device classifications is the leading indicator that pediatric optical design IP will command acquisition premiums. Five-to-ten year viability favors platform players with auto-ship infrastructure and optometrist rebate scale. Monitor state legislative pushes expanding online prescription verification as signal for direct-to-consumer channel acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Hydrogel Capacity Expansion | Retools stranded hydrogel lines to capture daily disposable volume in California and Texas. |
| Myopia Control Device FDA Submission | Opens pediatric axial length management claims distinct from standard refractive correction. |
| Direct-to-Consumer Subscription Launch | Bypasses clinic dispensing markups to capture 18-34 year-old convenience-prioritizing demographics. |
| Optometrist Rebate Program Intensification | Locks in specialty toric and multifocal fitting revenue against online platform erosion. |
| Scleral Lens Fitting Training Partnership | Addresses optometrist skill gaps to expand therapeutic irregular cornea penetration. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, silicone hydrogel material substitution rates, and state-level telehealth regulation changes anchored the trend analysis, supplemented by interviews with optometry clinic owners, contact lens manufacturing executives, GPO contracts managers, and online retail platform operators. Secondary validation drew from FDA premarket notification databases, FTC Contact Lens Rule enforcement records, state optometry board filings, and ISO 18369 biocompatibility certification registries. Bottom-up patient volume modeling triangulated against top-down manufacturer revenue estimates.
Segment-weighting across material chemistry, replacement frequency, application type, and channel structure informed volume and value outputs across the analysis window. CAGRs derived from fitted trend lines incorporating silicone hydrogel adoption curves and myopia control device regulatory pathway progression. Forecast inputs included pediatric population myopia prevalence trajectories and optometrist telehealth permission expansion scenarios.
Revisions become necessary when FDA myopia control guidance finalization, state telehealth legislative shifts, or silicone monomer supply disruptions materialize outside modeled assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pressotherapy Systems Market
Medical Devices
Medical Bionic Implants and Exoskeletons Market
Medical Devices
North America Intraocular Lens Market
Medical Devices
Telehealth Device Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Ocular Implants Market
Medical Devices
Central Venous Catheter Market
Medical Devices
Arthroscopic Shaver Market
Medical Devices
Global Peripheral IV Catheters Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Cervical Spine System Market
Medical Devices
Global Radial Artery Compression Devices Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
Europe Invisible Orthodontics Market