
 Electric Massage Equipment Market | 2026-2036
Electric Massage Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Massage Equipment Market Insights
Silicone-based cushioning is broadening the durability and cost profile of massage chair upholstery across mid-tier and premium lines. Panasonic Corporation leverages vertical integration in motor and sensor manufacturing to sustain quality control across its therapeutic device portfolio. OSIM International anchors its competitive stance through brand strength in Asian retail channels and flagship store networks. HoMedics competes aggressively in North American mass-market distribution through big-box retail partnerships and direct-to-consumer online positioning.
Electric massage equipment encompasses motorized devices designed to deliver mechanical stimulation, thermal therapy, or percussive force to soft tissue, typically operating at frequencies between 20–60 Hz with power draws of 20–150 watts depending on application scale. These systems serve therapeutic relaxation, sports recovery, and clinical rehabilitation purposes across consumer and professional settings. Massage chairs command the largest revenue pool within product type segmentation due to high unit values and recurring replacement cycles in commercial wellness environments. Handheld massagers represent the fastest-expanding category as portability and lower price points attract younger home users seeking post-workout recovery tools. Percussion technology within the technology dimension captures disproportionate margin attention from athletic and physiotherapy buyers prioritizing deep-tissue efficacy.
FDA 510(k) clearance requirements for therapeutic electrical devices shape product development timelines and clinical validation investments for manufacturers targeting the United States. EU MDR conformity assessment and CE marking obligations govern market access across European member states, while China's NMPA registration rules apply to imported and domestically produced therapeutic equipment. Japan's PMDA and METI standards further segment compliance burdens for companies pursuing premium positioning in aging-care markets. Stakeholders must monitor evolving electrical safety harmonization between IEC 60601 regional adoptions and emerging battery-powered portable standards that could reshape certification costs and competitive barriers.
Market Dynamics
Silicone-based cushioning materials are compressing upholstery replacement cycles while FDA 510(k) clearance timelines reshape product development budgets for therapeutic electrical devices targeting clinical channels.
Growth Catalysts
- EU MDR Conformity Assessment:Tighter CE marking obligations for therapeutic electrical equipment are filtering substandard imports and elevating quality premiums for compliant manufacturers across European distribution networks.
- Aging-Care Infrastructure:Japan's METI standards for home medical devices are accelerating institutional procurement of massage chairs in assisted-living facilities and rehabilitation centers.
- Percussion Technology:Deep-tissue efficacy gains in handheld devices are displacing basic vibration units among athletic recovery buyers seeking portable physiotherapy alternatives.
Market Restraints
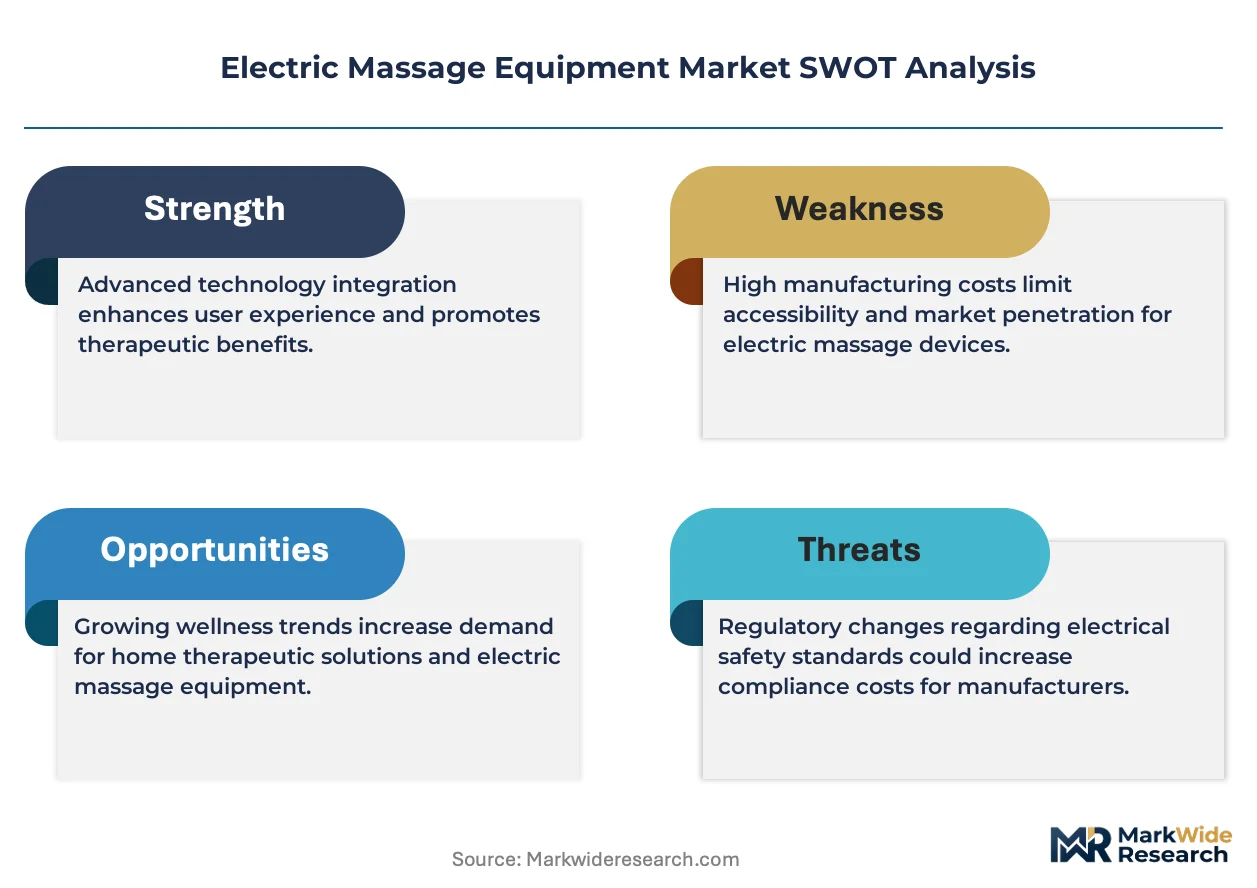
- Copper and Rare-Earth Magnet Costs:Motor winding materials face volatile commodity pricing that compresses margins on mid-tier massage chair production lines.
- Shenzhen Component Concentration:PCB and sensor module supply clusters in China's Pearl River Delta create single-point vulnerability for battery-powered portable device assemblers.
- Battery Safety Certification:IEC 60601-1 third edition amendments for lithium-ion powered therapeutic devices extend validation timelines by eight to fourteen months.
Strategic Opportunities
- German Clinical Rehabilitation:Post-operative recovery protocols in orthopedic centers are integrating motorized massage as standard physiotherapy adjunct, opening institutional sales channels.
- Telehealth Integration:Remote patient monitoring platforms are converging with connected massage devices to enable prescription-driven home therapy programs reimbursable under evolving digital health frameworks.
- India's PLI Scheme:Production-linked incentives for electronic manufacturing are attracting component localization investments that reduce landed costs for therapeutic device imports.
Industry Challenges
- Biomedical Engineer Shortage:Therapeutic device firms struggle to recruit professionals fluent in both IEC 60601 electrical safety and human biomechanics for product validation teams.
- Legacy Upholstery Supplier Integration:Shifting from PVC to silicone-based cushioning requires renegotiating multi-year contracts with established furniture component vendors resistant to retooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Massage Equipment Market |
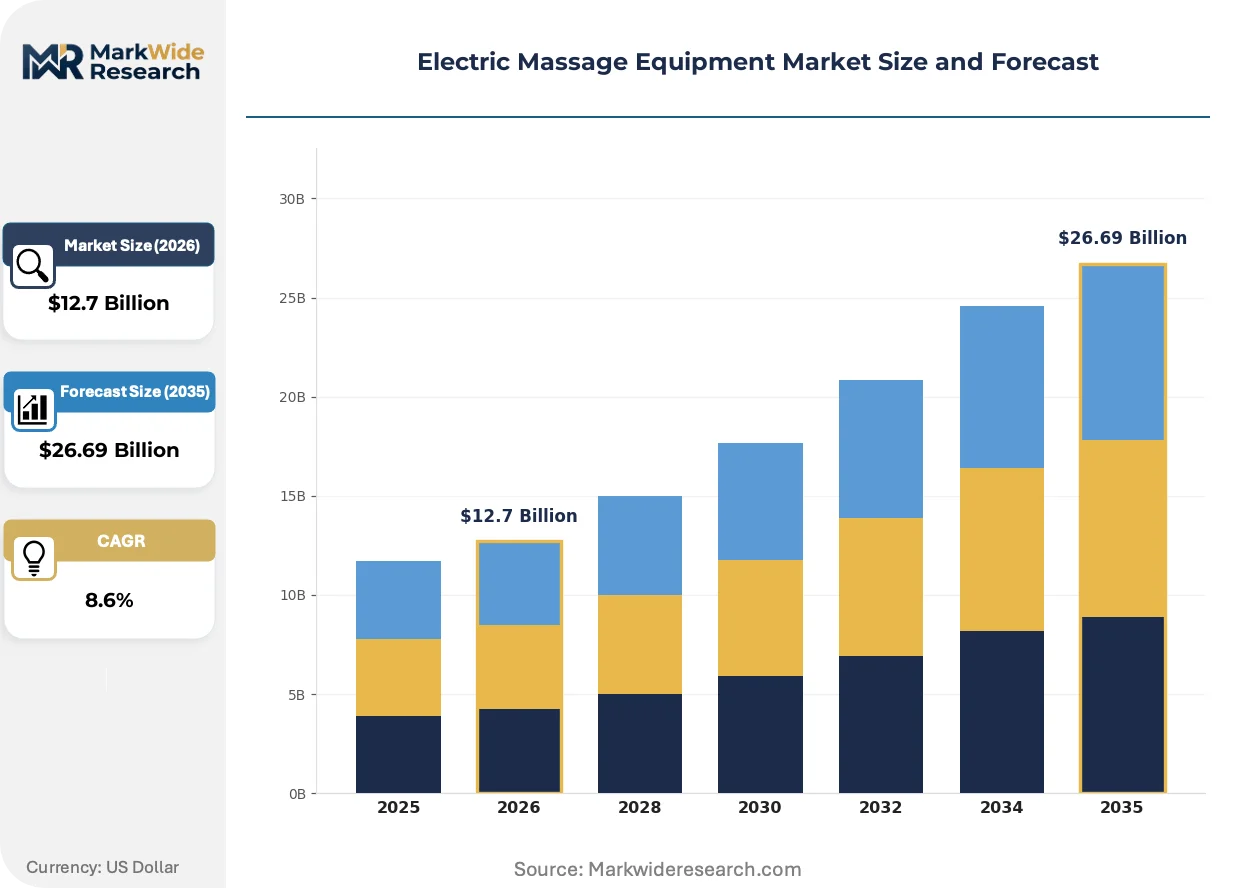
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.69 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Massage Chairs, Handheld Massagers, Foot Massagers, Massage Tables Technology: Vibration, Heat Therapy, Percussion, Infrared End User: Home Users, Professional Massage Therapists, Rehabilitation Centers, Wellness Spas Distribution Channel: Online Retail, Specialty Stores, Medical Supply Stores, Supermarkets |
| Companies Covered | Panasonic Corporation, OSIM International, Omron Corporation, MedMassager, HoMedics, Beurer, LURACO Technologies Corporation, JSB Healthcare, Shenzhen Relcare Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Massage Equipment Market Trends and Innovations
Sensor fusion and material science advances are compressing the feature gap between clinical-grade and consumer massage equipment while regulatory harmonization efforts reshape certification economics.
AI-driven pressure mapping is unifying real-time body contour detection with adaptive motor response in premium massage chairs. Physical therapy clinics in the United States are adopting these systems at replacement-cycle intervals of four to five years. This convergence is compressing the historical segmentation between institutional and home-use therapeutic equipment.
China's NMPA registration rules for imported therapeutic electrical devices now mandate in-country clinical trials for Class II medical equipment classifications. Domestic manufacturers gain six-to-twelve month speed-to-market advantages over foreign competitors. Multinational firms are responding through joint venture structures with licensed domestic distributors.
Direct-to-consumer subscription models for handheld percussive devices are displacing traditional big-box retail stocking arrangements among buyers under age forty. Athletic recovery brands are unbundling hardware from content platforms that prescribe usage protocols. This channel rotation is most visible in United States metropolitan markets where fitness studio partnerships drive trial conversion.
Electric Massage Equipment Market Segmentation
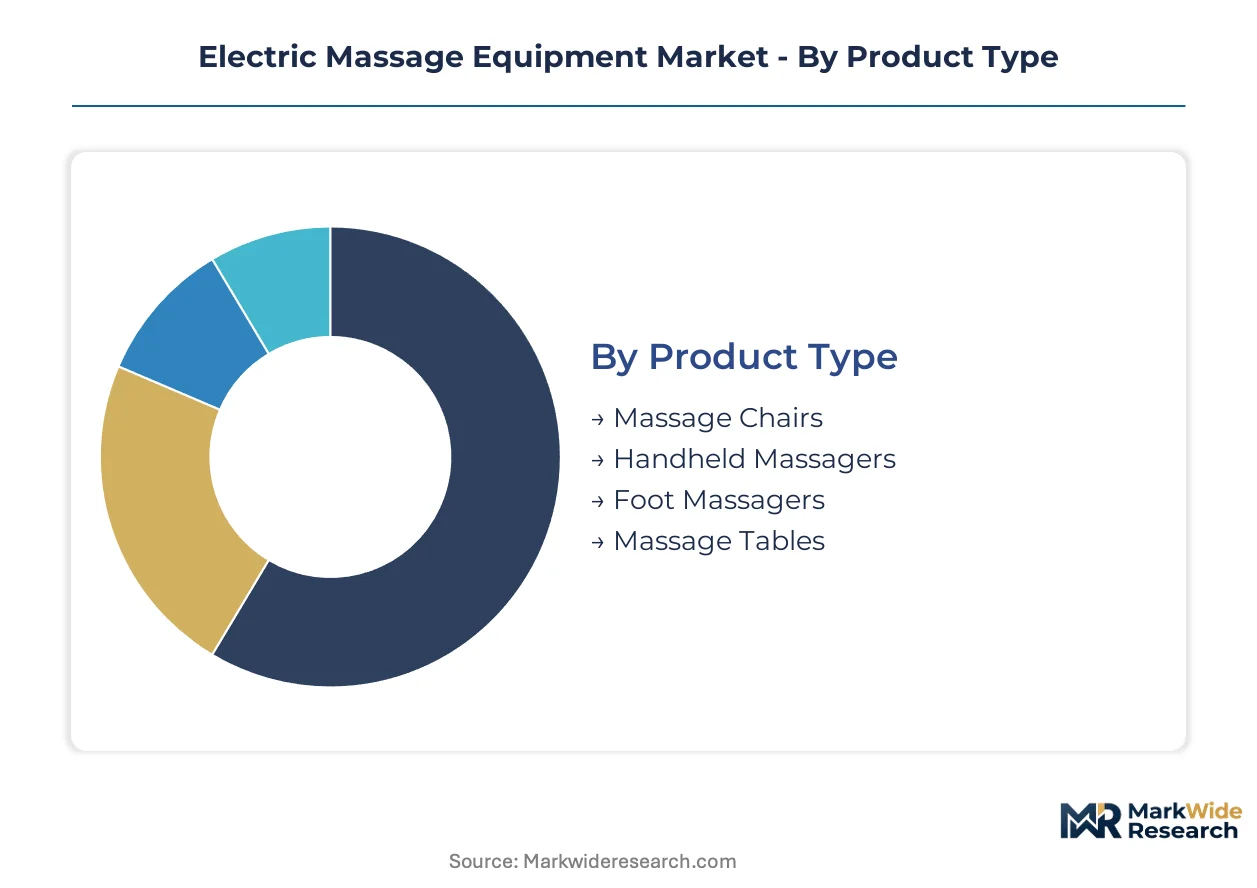
Electric massage equipment segments diverge sharply by price tolerance, usage intensity, and regulatory exposure. Manufacturers must align motor specifications, upholstery durability, and certification pathways to distinct buyer profiles across these four dimensions.
Product Type:
Unit economics and replacement cycles separate buyers most dramatically in this category.
- Massage Chairs:Full-body systems integrate quad-roller mechanisms, zero-gravity positioning, and embedded heating elements at 150-watt power draws. Demand concentrates in United States suburban households and Japan's assisted-living facilities where METI standards for home medical devices accelerate institutional procurement.
- Handheld Massagers:Portable percussive units operate at 20–60 Hz with lithium-ion battery packs enabling 90–150 minute runtime. Younger athletic recovery buyers in United States metropolitan markets drive fastest expansion through direct-to-consumer subscription models displacing big-box retail.
- Foot Massagers:Shiatsu-based units with heat therapy target circulation improvement for diabetic and elderly home users.
- Massage Tables:Motorized height-adjustment systems serve professional therapists requiring 500-pound dynamic load capacity.
Volume sits with Massage Chairs; growth tilts toward Handheld Massagers.
Technology:
Clinical efficacy claims and FDA clearance requirements segment buyers by intended use environment.
- Percussion:Rapid-fire piston mechanisms deliver 40–60 Hz deep-tissue stimulation with amplitude up to 16mm. Physiotherapy clinics in Germany's orthopedic centers integrate these systems into post-operative recovery protocols as standard adjuncts.
- Vibration:Oscillating motor platforms provide surface-level muscle relaxation at lower cost points for casual home users.
- Heat Therapy:Carbon-fiber heating elements sustain 40–45°C surface temperatures for vasodilation and pain relief.
- Infrared:Far-infrared emitters penetrate 2–3 inches subcutaneously for chronic pain management in clinical settings.
Percussion commands premium pricing; Vibration holds volume leadership in mass-market channels.
End User:
Reimbursement eligibility and purchase authority split this category between consumer discretion and institutional procurement.
- Home Users:Individual purchasers prioritize space efficiency and multi-user programming with price sensitivity varying by age cohort. Aging populations in Germany and China accelerate replacement cycles as home wellness infrastructure expands.
- Professional Massage Therapists:Licensed practitioners demand commercial-grade durability with 8–10 hour daily duty cycles and portable table configurations.
- Rehabilitation Centers:Institutional buyers require FDA 510(k) clearance or EU MDR conformity for therapeutic electrical device classification to qualify for facility reimbursement.
- Wellness Spas:Hospitality-oriented purchasers prioritize aesthetic customization and synchronized multi-unit control for service differentiation.
Rehabilitation Centers anchor institutional volume; Home Users represent the steepest expansion trajectory.
Distribution Channel:
Buyer age and urgency preferences determine channel selection more than geography.
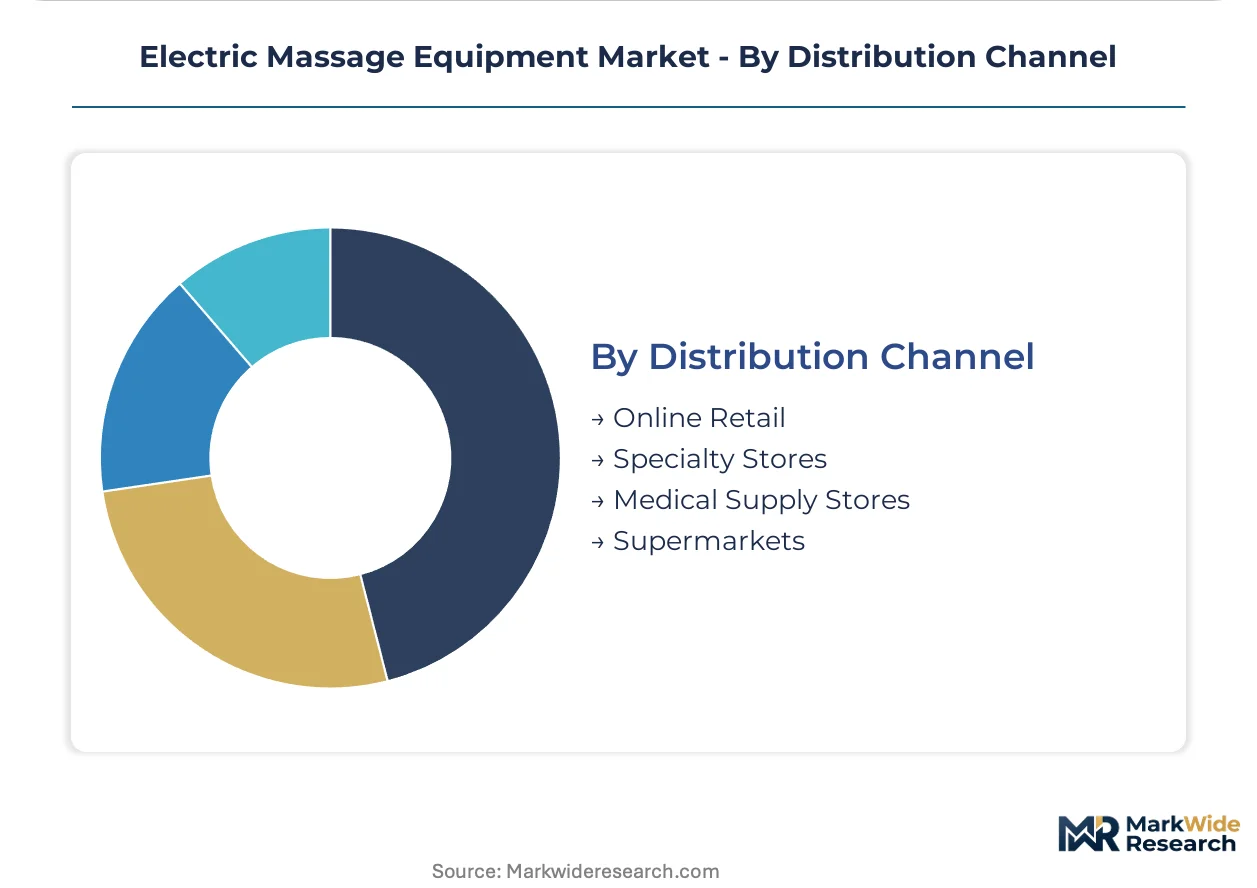
- Online Retail:Direct-to-consumer platforms enable subscription bundling with fitness content and usage protocol apps. Athletic recovery brands in United States markets leverage this channel for buyers under forty through fitness studio partnership trials.
- Specialty Stores:Flagship networks allow tactile evaluation of upholstery feel and motor noise profiles for premium massage chair purchases.
- Medical Supply Stores:Clinical-grade distribution requires staff training on FDA clearance documentation and insurance pre-authorization assistance.
- Supermarkets:Impulse-accessible placement drives entry-level handheld and foot massager volume with minimal sales support.
Specialty Stores dominate Massage Chair transactions; Online Retail gains fastest in handheld percussive categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for electric massage equipment concentrates in aging economies with established home wellness infrastructure and clinical reimbursement pathways. The United States, China, Germany, and Japan absorb the majority of premium massage chair and handheld device shipments. Regulatory frameworks and component supply clusters further reinforce these geographic concentrations.
United States
Suburban household penetration of full-body massage chairs and post-workout recovery culture among younger demographics sustain dual demand streams. FDA 510(k) clearance requirements for therapeutic electrical devices filter import competition and elevate compliance costs for clinical-channel entrants. Chicago and Dallas-Fort Worth retail corridors host flagship showroom networks where tactile evaluation drives premium conversion.
China
Domestic manufacturers leverage six-to-twelve month speed-to-market advantages under NMPA registration rules for Class II therapeutic equipment. Aging urban populations in Shanghai and Beijing accelerate replacement cycles as residential wellness infrastructure expands. The Pearl River Delta component cluster around Shenzhen supplies PCB and sensor modules for battery-powered portable device assemblers serving export markets.
Germany
Orthopedic centers in Munich and Hamburg integrate motorized massage systems into post-operative rehabilitation protocols as standard physiotherapy adjuncts. EU MDR conformity assessment and CE marking obligations for therapeutic electrical equipment elevate quality premiums for compliant manufacturers. Stuttgart's precision engineering base supports motor and control system fabrication for mid-tier and premium equipment lines.
Japan
METI standards for home medical devices accelerate institutional procurement of massage chairs in Tokyo and Osaka assisted-living facilities. PMDA registration requirements segment compliance burdens for premium positioning in aging-care markets. Nagoya's industrial machinery heritage feeds therapeutic equipment component supply chains with precision motor and actuator fabrication.
India
Production-linked incentives for electronic manufacturing under the PLI scheme attract component localization investments that reduce landed costs for therapeutic device imports. Mumbai and Delhi-NCR urban households show rising appetite for entry-level handheld massagers as fitness culture penetrates metropolitan centers. Gujarat component fabricators are retooling for silicone-based cushioning and small-motor assembly to serve domestic OEM demand.
Electric Massage Equipment Market Competitive Landscape
Strategic partnerships dominate the current landscape as therapeutic equipment specialists seek regulatory expertise and distribution scale. The vendor base stratifies across three tiers: diversified electronics conglomerates with captive component supply, dedicated wellness equipment brands with flagship retail networks, and contract manufacturers serving private-label mass-market distributors. Two archetypes anchor competitive positioning: vertically integrated motor and sensor producers, and brand-centric lifestyle marketers with content-platform ecosystems. M&A activity and geographic licensing agreements represent the dominant competitive moves as firms seek FDA and EU MDR compliance capabilities without internal buildout.
Among Asia-Pacific-based diversified manufacturers, Panasonic Corporation and Omron Corporation occupy positions that exemplify captive supply chain control over motor and sensing subsystems. OSIM International anchors the brand-centric archetype through Asian flagship store networks and lifestyle positioning. In the North American mass-market tier, HoMedics represents distribution-scale players competing through big-box retail partnerships and direct-to-consumer online channels. These three company groupings illustrate how regulatory compliance burdens and channel access requirements stratify competitive positioning across price-performance tiers.
| Leading Market Players |
|---|
| Panasonic Corporation |
| OSIM International |
| Omron Corporation |
| MedMassager |
| HoMedics |
| Beurer |
| LURACO Technologies Corporation |
| JSB Healthcare |
| Shenzhen Relcare Electronics |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between FDA 510(k) cleared clinical units and uncertified consumer devices manifests in both pricing power and supply chain sourcing strategies across the electric massage equipment sector. Premium clinical-grade manufacturers command pricing premiums through validated therapeutic claims while absorbing extended compliance timelines, whereas mass-market assemblers compete on landed cost optimization from Shenzhen component clusters.
Pricing Analysis
Volume-mass-market handheld units trade at thin margins while premium massage chairs retain substantial pricing power through embedded heating arrays and AI-driven pressure mapping. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared rehabilitation equipment from big-box retail SKUs and direct-to-consumer subscription bundles. Cost compression in mid-tier massage chair production intensifies because copper winding and rare-earth magnet inputs face commodity volatility. Home users under age forty show highest price sensitivity through subscription model uptake, whereas institutional rehabilitation centers prioritize clinical validation over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle component demand from diversified electronics conglomerates with captive motor fabrication, while contract manufacturers serve private-label distributors through Shenzhen PCB and sensor module clusters. China, Japan, and Germany anchor therapeutic equipment production through precision motor engineering and upholstery fabrication capabilities. Raw material dependencies center on lithium-ion battery cells, silicone-based cushioning polymers, and copper motor windings. Single-source vulnerability concentrates in Pearl River Delta sensor module supply for battery-powered portable device assemblers. Distribution runs through medical supply stores requiring staff training on FDA clearance documentation alongside flagship showroom networks for tactile premium evaluation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA 510(k) clearance requirements for therapeutic electrical devices erect substantial barrier-to-entry moats favoring incumbent players with established clinical validation infrastructure and regulatory affairs capabilities.
For Market Incumbents: Deepen backward integration into motor and sensor subsystem production to insulate margins from rare-earth magnet price volatility and Shenzhen component concentration risks. Expand EU MDR conformity assessment capabilities ahead of tightening CE marking obligations to capture quality premiums filtering substandard imports. Prioritize biomedical engineer recruitment for IEC 60601 electrical safety and human biomechanics fluency to accelerate product validation timelines. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting United States metropolitan fitness studio partnerships where athletic recovery buyers under age forty show lowest brand loyalty and highest trial conversion. Exploit India's PLI scheme for electronic manufacturing component localization to reduce landed costs for therapeutic device imports serving price-sensitive entry-level demand. Bypass saturated big-box retail channels entirely through fitness content platform bundling that prescribes usage protocols. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists possessing captive motor supply and existing FDA 510(k) clearances given accelerating institutional procurement in Japan's METI-regulated assisted-living facilities. Target acquisition archetypes include Asian flagship store networks with lifestyle brand positioning and EU MDR compliance capabilities. Watch for inflection signals in telehealth integration momentum where remote patient monitoring platforms converge with connected massage devices for prescription-driven home therapy reimbursement eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Clinical channel access hinges on therapeutic electrical device clearance timelines averaging fourteen to eighteen months. |
| EU MDR Conformity Pathway Investment | CE marking obligations filter substandard imports and elevate quality premiums for compliant manufacturers. |
| Silicone Upholstery Supplier Retooling | Material science advances compress replacement cycles while requiring multi-year contract renegotiation with legacy vendors. |
| Fitness Studio Partnership Network | Direct-to-consumer trial conversion in United States metropolitan markets displaces traditional big-box retail stocking. |
| Telehealth Platform Integration | Remote patient monitoring convergence enables prescription-driven home therapy programs under evolving digital health frameworks. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, NMPA registration databases, and METI home medical device standards, complemented by interviews with biomedical engineers, rehabilitation center procurement directors, therapeutic equipment brand managers, and GPO contracts managers. Secondary validation drew from customs trade data, SEC 10-K therapeutic device segment disclosures, and hospital procurement database extracts. Bottom-up unit shipment modeling and top-down market value triangulation anchored segmentation outputs.
Segmentation outputs across product type, technology, end user, and distribution channel dimensions were projected over the analysis window using elasticity-adjusted demand curves and replacement cycle assumptions. CAGRs derived from weighted average of historical trajectory analysis and forward-looking regulatory impact assessment. Industry-specific forecast inputs included lithium-ion battery cost curves and IEC 60601-1 third edition amendment adoption timelines.
Regulatory harmonization delays, commodity price spikes in copper and rare-earth magnets, and biomedical engineer talent scarcity are the dominant revision risks warranting scenario sensitivity testing. Forecasts reflect documented assumptions on certification pathway durations and institutional reimbursement evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Airway Management Devices Market
Medical Devices
Sacroiliac Joint Fusion Market
Medical Devices
Indonesia Devices Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Anesthesia Vaporizers Market
Medical Devices
Organoids Kits Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Global Mucosal Atomization Devices Market
Medical Devices
Asia-Pacific Medical Aesthetic Devices Market
Medical Devices
Asia-Pacific Ostomy Care and Accessories Market
Medical Devices
Rectal Catheters Market
Medical Devices
Spinal Needles Market
Medical Devices
Pneumatic Nebulizers Market
Medical Devices
Ostomy Drainage Systems Market
Medical Devices
Global Stroke Assistive Devices Market