
 Bone Anchored Hearing Aids Market | 2026-2036
Bone Anchored Hearing Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Anchored Hearing Aids Market Intelligence
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries for bone anchored hearing aid manufacturers. Cochlear Limited leverages its vertically integrated manufacturing footprint across multiple continents to sustain supply continuity. Oticon Medical anchors its position through deep specialization in bone conduction transducer engineering. MED-EL Medical Electronics competes on the strength of its broad ENT implant portfolio and established surgeon training networks.
Bone anchored hearing aids are surgically implanted devices that transmit sound vibrations directly to the cochlea via an osseointegrated titanium abutment or magnetic coupling, bypassing damaged outer or middle ear structures to achieve functional hearing restoration in patients with conductive or mixed hearing loss. The fully implantable product type commands premium positioning due to its cosmetic appeal and reduced infection risk, while single-sided deafness represents the fastest-growing indication as awareness spreads among adult patients and referring audiologists. Margin pools concentrate in the surgical aid and external processor categories where recurring component sales and software upgrade cycles generate sustained aftermarket revenue.
FDA premarket notification and EU MDR conformity assessment shape product development timelines and commercial launch sequencing for manufacturers seeking multi-region approval. Health Canada and the Therapeutic Goods Administration in Australia enforce parallel but divergent clinical evidence requirements that fragment regulatory strategy. Stakeholders must monitor evolving reimbursement coding decisions by national health technology assessment bodies to anticipate volume shifts between hospital-based and outpatient surgical delivery settings.
Market Dynamics
Osseointegrated titanium abutment miniaturization and magnetic coupling refinements are compressing surgical complexity while expanding candidate eligibility for bone anchored hearing systems. Manufacturers must align R&D roadmaps with tightening FDA premarket notification requirements and EU MDR conformity assessment timelines.
Growth Catalysts
- Single-sided deafness awareness campaigns:Adult patients and referring audiologists in tertiary ENT centers are expanding diagnostic pipelines for bone conduction solutions.
- EU MDR quality benchmarks:CE marking under tightened Medical Device Regulation protocols is filtering substandard implantable hearing devices from European distribution channels.
- Pediatric ENT program expansion:Tertiary hospitals in the United States, Germany, and Japan are building dedicated bone anchored hearing aid surgical units.
Market Restraints
- Titanium supply concentration:Medical-grade titanium billet sourcing clusters with limited aerospace-qualified suppliers create input vulnerability.
- Surgical skill bottlenecks:Otologic surgeons trained in percutaneous abutment placement remain scarce outside major metropolitan academic centers.
- Reimbursement coding fragmentation:Divergent health technology assessment decisions across national bodies delay commercial rollout sequencing.
Strategic Opportunities
- Fully implantable cosmetic appeal:Subcutaneous magnetic coupling systems eliminate percutaneous wound care and expand addressable patient pools.
- Software upgrade monetization:External processor firmware and sound processing algorithm refreshes generate recurring aftermarket revenue streams.
- Outpatient surgical migration:Ambulatory surgery center reimbursement approvals in select US states are shifting volume from inpatient settings.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing protocols for novel transducer materials extend regulatory submission preparation by 18-24 months.
- Surgeon training network scaling:Proctoring requirements for safe osseointegration drilling techniques limit commercial expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Anchored Hearing Aids Market |
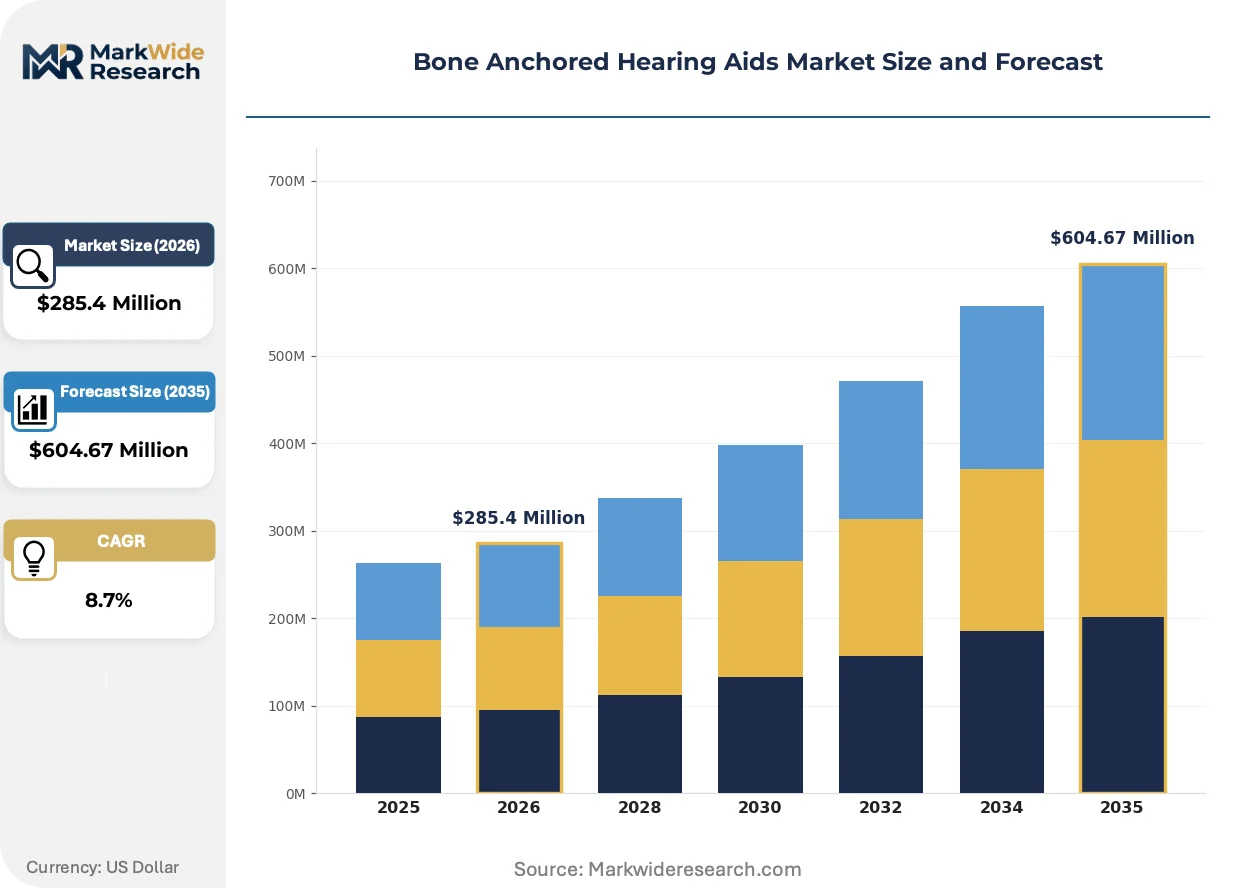
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Implantable, Partially Implantable, External Processor, Surgical Aid Indication: Conductive Hearing Loss, Mixed Hearing Loss, Single-Sided Deafness, Chronic Otitis Media End User: Pediatrics, Adults, Geriatrics, Military Personnel Distribution Channel: Online Stores, Hospitals, Audiology Clinics, Medical Supply Stores |
| Companies Covered | Cochlear Limited, Oticon Medical, Sonova Holding AG, Demant, MED-EL Medical Electronics, WS Audiology, Nurotron Biotechnology, Amplifon SpA, Starkey Hearing Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Anchored Hearing Aids Market Strategic Shifts & Innovations
Active transducer engineering and digital signal processing convergence are redefining performance benchmarks for bone conduction hearing restoration. Competitive positioning now hinges on firmware differentiation and surgical technique simplification.
Magnetic coupling systems with transcutaneous energy transfer are supplanting percutaneous abutment designs in premium product tiers. Pediatric and cosmetic-sensitive adult segments are adopting these configurations fastest. Surgical infection rates and wound management burdens are compressing demand for traditional abutment-based systems.
EU MDR Article 10 post-market surveillance obligations are forcing manufacturers to rebuild clinical follow-up infrastructure across European Economic Area markets. Legacy notified body relationships no longer suffice for sustained market access. Smaller implantable hearing device portfolios face disproportionate compliance cost absorption.
Hospital procurement committees are consolidating vendor relationships around full ENT implant ecosystem suppliers. Standalone bone anchored hearing aid manufacturers face exclusion from integrated tender processes. Germany and Japan exhibit this concentration most acutely where university hospital networks dominate volume allocation.
Bone Anchored Hearing Aids Market Segmentation
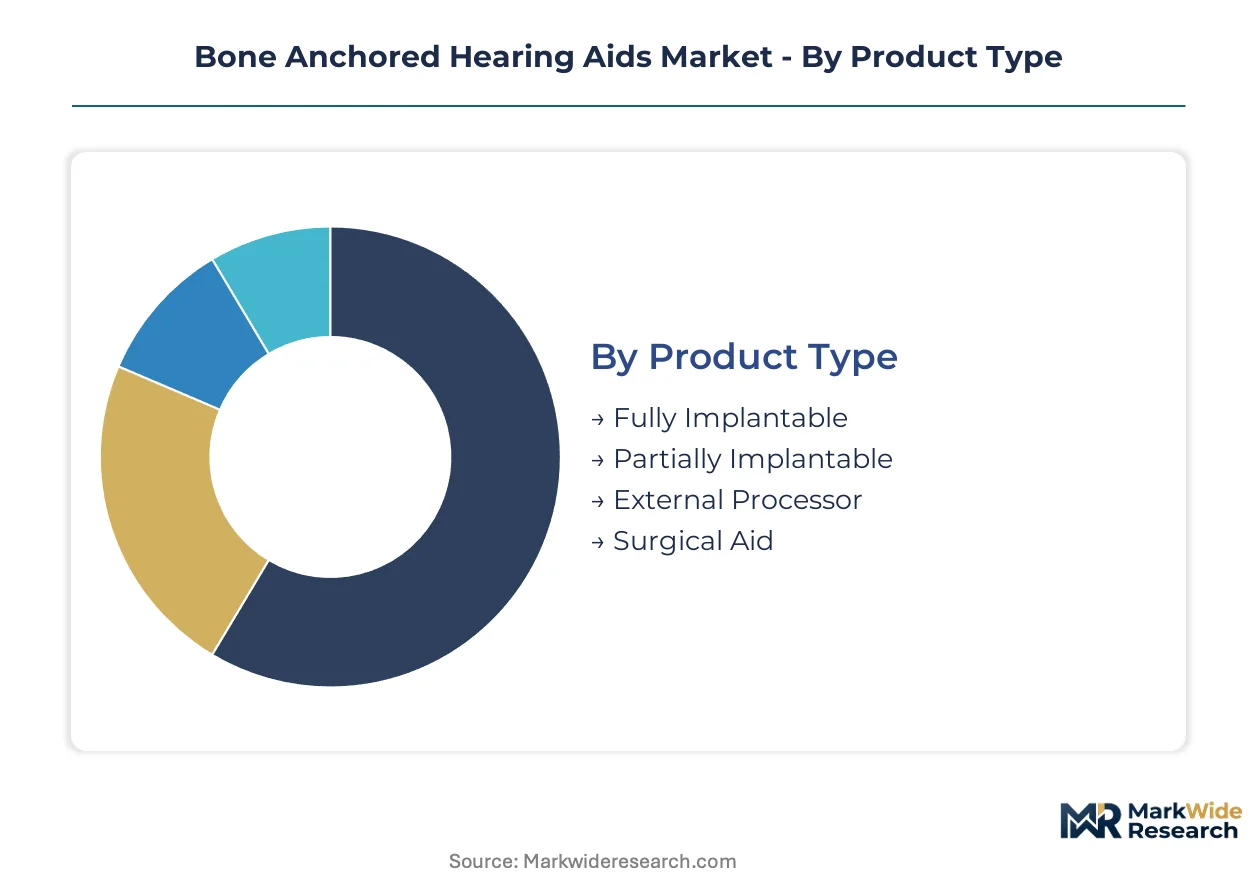
Segmentation in bone anchored hearing aids reveals distinct procurement patterns across implantable versus external systems, with reimbursement pathways and surgical infrastructure dictating regional penetration rates. Manufacturers calibrate portfolio depth against hospital purchasing consolidation and ambulatory surgery center expansion.
Product Type:
Fully implantable systems concentrate demand in Germany and Japan where cosmetic sensitivity and established reimbursement codes accelerate adoption, while external processors dominate volume in US outpatient settings.
- Fully Implantable:Subcutaneous magnetic coupling eliminates percutaneous abutment exposure, reducing infection risk and wound care burden. Demand clusters in tertiary ENT centers across Germany and Japan where aesthetic outcomes command premium positioning.
- Partially Implantable:Combines osseointegrated fixture with detachable external sound processor, balancing surgical permanence with upgrade flexibility. US hospital procurement committees favor this configuration for pediatric programs seeking processor replacement pathways without revision surgery.
- External Processor:Detachable sound processing unit with firmware upgrade cycles generating recurring aftermarket revenue.
- Surgical Aid:Titanium abutment and fixture assembly requiring otologic surgeon placement in operating room settings.
Fully implantable systems hold the largest share; momentum sits with external processors as ambulatory surgery center reimbursement expands.
Indication:
Cost tier stratification separates premium magnetic coupling deployments for single-sided deafness from standard abutment-based solutions for conductive loss.
- Single-Sided Deafness:CROS-style bone conduction routing restores spatial hearing awareness in unilateral cochlear function loss. Adult patients in US metropolitan markets drive fastest expansion as audiologist referral networks mature.
- Conductive Hearing Loss:Bypasses damaged outer or middle ear structures through direct osseointegrated vibration transmission. Pediatric cases across US and German academic medical centers constitute stable procedural volume.
- Mixed Hearing Loss:Combines conductive and sensorineural deficits requiring bone conduction amplification with residual cochlear function.
- Chronic Otitis Media:Recurrent infection history contraindicates conventional air-conduction hearing aids, favoring percutaneous or transcutaneous bone anchored alternatives.
Conductive hearing loss holds the largest share; single-sided deafness is climbing the fastest as awareness campaigns penetrate adult populations.
End User:
Volume concentration varies sharply across age cohorts, with pediatric programs requiring specialized anesthesia protocols and geriatric cases presenting comorbid surgical risk profiles.
- Pediatrics:Craniofacial development considerations mandate delayed implantation timing and specialized fixture sizing. Tertiary children's hospitals in the United States and Germany anchor global procedural volume through dedicated multidisciplinary teams.
- Adults:Cosmetic motivation and occupational hearing demands drive self-referral patterns. Japanese working-age adults exhibit strongest magnetic coupling preference for professional appearance preservation.
- Geriatrics:Age-related surgical risk stratification and comorbidity burden constrain candidacy expansion.
- Military Personnel:Blast-induced conductive trauma creates specialized rehabilitation pathways through Veterans Health Administration and parallel national defense medical systems.
Adults hold the largest share; pediatrics is gaining share fastest through academic medical center program expansion.
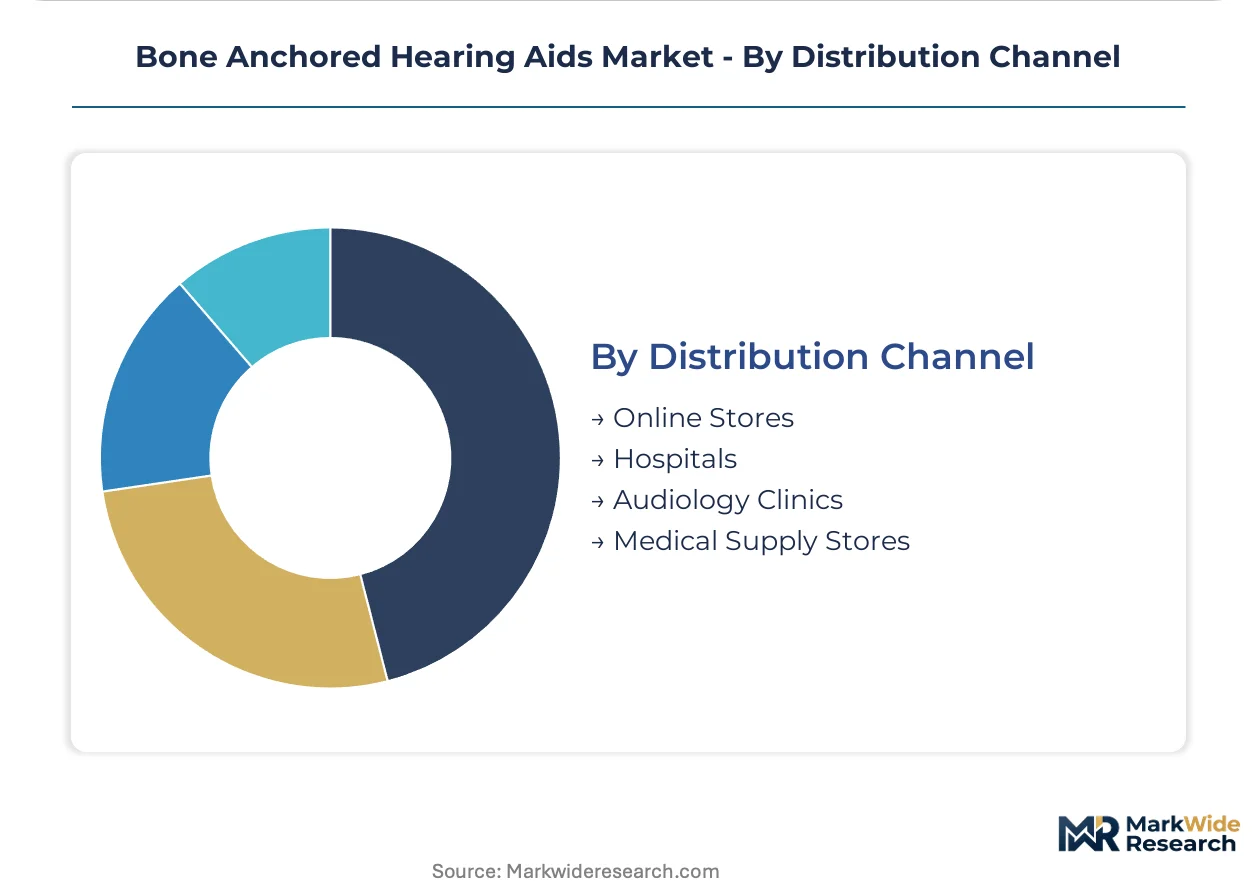
Distribution Channel:
Supply concentration favors hospital-based procurement in implantable categories, while external processor replacement channels fragment toward audiology clinics and direct manufacturer portals.
- Hospitals:Surgical implant procurement flows through integrated delivery network contracts and ENT implant ecosystem vendor consolidation. German university hospital networks and Japanese national hospital organizations exercise dominant purchasing leverage.
- Audiology Clinics:External processor fitting, programming, and maintenance services concentrate in independent practice settings. US Medicare reimbursement for diagnostic audiology supports clinic-based processor upgrade cycles.
- Online Stores:Direct-to-consumer accessories and replacement components bypass traditional distribution markup.
- Medical Supply Stores:Regional durable medical equipment suppliers service post-surgical wound care and processor retention accessories.
Hospitals hold the largest share; audiology clinics show steepest expansion trajectory as processor upgrade cycles shift toward outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket approval pathways and established reimbursement frameworks for osseointegrated hearing solutions concentrate procedural volume in select advanced economies. National health technology assessment bodies shape commercial rollout sequencing through divergent coding decisions.
United States
Pediatric ENT program expansion in tertiary academic centers drives procedural growth, with dedicated bone anchored hearing aid surgical units multiplying across major metropolitan hospitals. CMS reimbursement coding for outpatient ambulatory surgery centers is shifting volume from inpatient settings. The Veterans Health Administration maintains specialized rehabilitation pathways for blast-induced conductive trauma in military personnel.
Germany
University hospital networks exercise dominant purchasing leverage through consolidated vendor relationships around full ENT implant ecosystem suppliers. CE marking under tightened EU MDR protocols filters substandard devices from distribution channels. Tertiary children's hospitals in Bavaria and North Rhine-Westphalia anchor European pediatric procedural volume through multidisciplinary craniofacial teams.
Japan
Working-age adults exhibit strongest preference for magnetic coupling systems to preserve professional appearance, accelerating fully implantable adoption. METI oversight of medical device quality benchmarks aligns with PMDA premarket certification timelines. National hospital organizations in Tokyo and Osaka concentrate surgical expertise and procurement decision-making for osseointegrated hearing solutions.
United Kingdom
NHS England specialized commissioning frameworks determine patient access to bone conduction implantation outside private pay channels. NICE health technology assessment decisions influence coding and reimbursement for single-sided deafness indications. London and Manchester academic medical centers host the principal surgeon training networks for percutaneous abutment placement techniques.
Australia
Therapeutic Goods Administration clinical evidence requirements for implantable hearing devices run parallel but divergent from FDA and EU pathways, fragmenting regulatory strategy. The Royal Victorian Eye and Ear Hospital in Melbourne and Sydney's Westmead Hospital anchor southern hemisphere surgical training and volume concentration. Private health insurance penetration determines access to premium magnetic coupling configurations outside public hospital queues.
Bone Anchored Hearing Aids Market Key Industry Players
Player mix skews toward diversified ENT implant conglomerates with captive audiology distribution. Market structure concentrates around vertically integrated manufacturers sustaining supply continuity across multiple continents. Two strategic archetypes dominate: full ENT ecosystem suppliers leveraging hospital procurement consolidation, and specialized bone conduction engineering houses competing on transducer performance. Competitive moves center on surgeon training network scaling and software upgrade monetization through external processor firmware cycles.
Within the diversified implant conglomerate tier, Cochlear Limited and MED-EL Medical Electronics exemplify vertically integrated manufacturing footprints spanning surgical fixture production through external sound processor distribution. Oticon Medical occupies a position as the specialized bone conduction engineering archetype, anchoring competitive positioning through deep technical focus on transducer and magnetic coupling systems. These three entities collectively represent the concentration of surgical aid and external processor revenue pools where recurring component sales generate sustained aftermarket income.
| Leading Market Players |
|---|
| Cochlear Limited |
| Oticon Medical |
| Sonova Holding AG |
| Demant |
| MED-EL Medical Electronics |
| WS Audiology |
| Nurotron Biotechnology |
| Amplifon SpA |
| Starkey Hearing Technologies |
| Others |
Cost & Logistics Intelligence
Magnetic coupling miniaturization replacing percutaneous abutment designs is redrawing supply geography toward precision-machining hubs in Switzerland and Germany while compressing premium-tier pricing premiums through reduced surgical complexity and infection management costs.
Pricing Analysis
Certification level (FDA PMA versus 510(k) versus CE MDR Class III) creates the primary spread between premium magnetic coupling systems and standard abutment-based configurations. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 biocompatibility testing depth and notified body audit stringency. Cost compression in economy-tier external processors is intensifying because hospital procurement committees consolidate vendor relationships around full ENT implant ecosystem suppliers. Pediatric ENT programs exhibit highest price sensitivity due to fixture sizing complexity and revision surgery risks, while working-age adults in Japan show lowest sensitivity for cosmetic-preserving fully implantable systems.
Supply Chain Analysis
Switzerland and Germany anchor precision titanium machining for osseointegrated fixtures, while the United States and Japan concentrate active transducer and digital signal processor fabrication. Medical-grade titanium billet sourcing draws from aerospace-qualified suppliers in the US and Russia, with transducer magnets and biocompatible polymers sourced from Japanese and German specialty chemical producers. Single-source vulnerability concentrates in medical-grade titanium feedstock qualified to ASTM F136 standards. Distribution runs through integrated delivery network contracts in German university hospital systems and GPO-negotiated agreements in US academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where CE MDR and FDA PMA entrenchment creates switching costs that lock hospital procurement committees into validated supplier relationships.
For Market Incumbents: Fortify surgeon training network scaling through proctored osseointegration drilling programs in tertiary academic centers, countering emerging entrant archetypes with streamlined magnetic coupling engineering. Deepen backward integration into medical-grade titanium billet sourcing to offset aerospace supplier concentration risk, while accelerating software upgrade monetization through external processor firmware refresh cycles. For New Entrants and Emerging Players: Differentiate on pediatric fixture miniaturization and craniofacial development timing protocols, where established players maintain weaker specialized positioning. White-space opportunity concentrates in ambulatory surgery center reimbursement pathways across select US states, with go-to-market execution anchored through audiology clinic processor fitting partnerships bypassing hospital procurement consolidation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed audiology distribution platforms seeking implantable hearing device manufacturing integration to escape standalone processor margin compression. Long-term viability framing centers on regulatory entrenchment durability and software recurring revenue attachment rates. Signal to monitor: EU MDR notified body capacity constraints extending conformity assessment timelines and filtering subscale competitors from market access.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 post-market surveillance obligations force clinical follow-up infrastructure rebuilds across European Economic Area markets. |
| Hospital System Partnership | Integrated delivery network contracts in German university hospital networks and US academic medical centers concentrate volume allocation. |
| Software Companion Development | External processor firmware and sound processing algorithm refreshes generate recurring aftermarket revenue streams beyond initial implant sales. |
| Reimbursement Strategy | Coding decisions by national health technology assessment bodies determine volume shifts between hospital-based and outpatient surgical settings. |
| FDA Submission | Premarket approval pathway selection shapes product development timelines and commercial launch sequencing for multi-region manufacturers. |
Research Approach
A spread of perspectives from otologic surgeons, hospital purchasing committee directors, biomedical engineers specializing in implantable devices, and GPO contracts managers converged on the working assumptions through structured primary interviews. Secondary validation drew from FDA PMA and 510(k) filings, EUDAMED CE marking databases, CMS Medicare reimbursement coding decisions, and hospital procurement contract disclosures. Bottom-up procedural volume estimates triangulated against top-down manufacturer revenue segmentation across the analysis window.
Segmentation dimensions modeled span product type architecture, indication severity tier, end-user age cohort, and distribution channel structure throughout the forecast period. CAGRs were derived from procedure volume trajectories weighted by reimbursement pathway maturity and surgical infrastructure expansion rates. Industry-specific forecast inputs incorporated EU MDR transition timeline impacts and ambulatory surgery center coding approval patterns.
Material uncertainties — regulatory submission delays, titanium supply disruptions, and reimbursement coding reversals — sit outside the modeled envelope. Forecasts reflect assumptions about surgeon training network scaling velocity and magnetic coupling adoption curves. Recalibration cycles align with material shifts in EU MDR enforcement stringency and CMS outpatient procedural payment determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Monitors Market
Medical Devices
GCC Biopsy Devices Market
Medical Devices
Global Robotic Endoscopy Devices Market
Medical Devices
Global Medical Tricorder Device Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Global Nebuliser Market
Medical Devices
Percutaneous Nephrostomy Catheters Market
Medical Devices
Pneumology Digital Stethoscope Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
Australia Clear Aligner Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Italy Artificial Organs and Bionic Implants Market
Medical Devices
Gastric Electrical Stimulators Market
Medical Devices
Intravenous Transportation System Market