
 Sleeve Gastrectomy Devices Market | 2026-2036
Sleeve Gastrectomy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Sleeve Gastrectomy Devices Market Analytics
China is tilting toward expanded domestic production capacity for laparoscopic stapling systems and endoluminal platforms. Medtronic plc anchors its position through captive supply of surgical staplers with integrated reload technology. Johnson & Johnson competes across the full procedural workflow from access ports to reinforcement materials. Intuitive Surgical Inc specializes in robotic-assisted sleeve gastrectomy protocols that reduce operative variability.
Sleeve gastrectomy devices encompass stapling instruments, calibration tubes, and reinforcement materials designed to transect and seal the gastric fundus along a predetermined sleeve geometry, typically achieving a residual stomach volume of 60–150 mL to restrict caloric intake and modulate hunger hormone secretion. These devices serve the primary commercial purpose of enabling standardized, reproducible gastric reduction in metabolic and bariatric surgical settings. The sutures and clips segments lead procedural volume due to staple-line reinforcement requirements, while biodegradable plastics within the material dimension represent the fastest-growing category as hospitals prioritize absorbable reinforcement over permanent mesh. Stainless steel stapler cartridges remain the mature margin pool where scale economies and reprocessing protocols defend incumbent positions.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for manufacturers seeking commercial distribution. The EU AI Act and FDA software-as-medical-device guidance increasingly scrutinize algorithmic features in robotic and image-guided platforms. Stakeholders must monitor evolving reimbursement coding for endoluminal sleeve procedures versus conventional laparoscopic approaches.
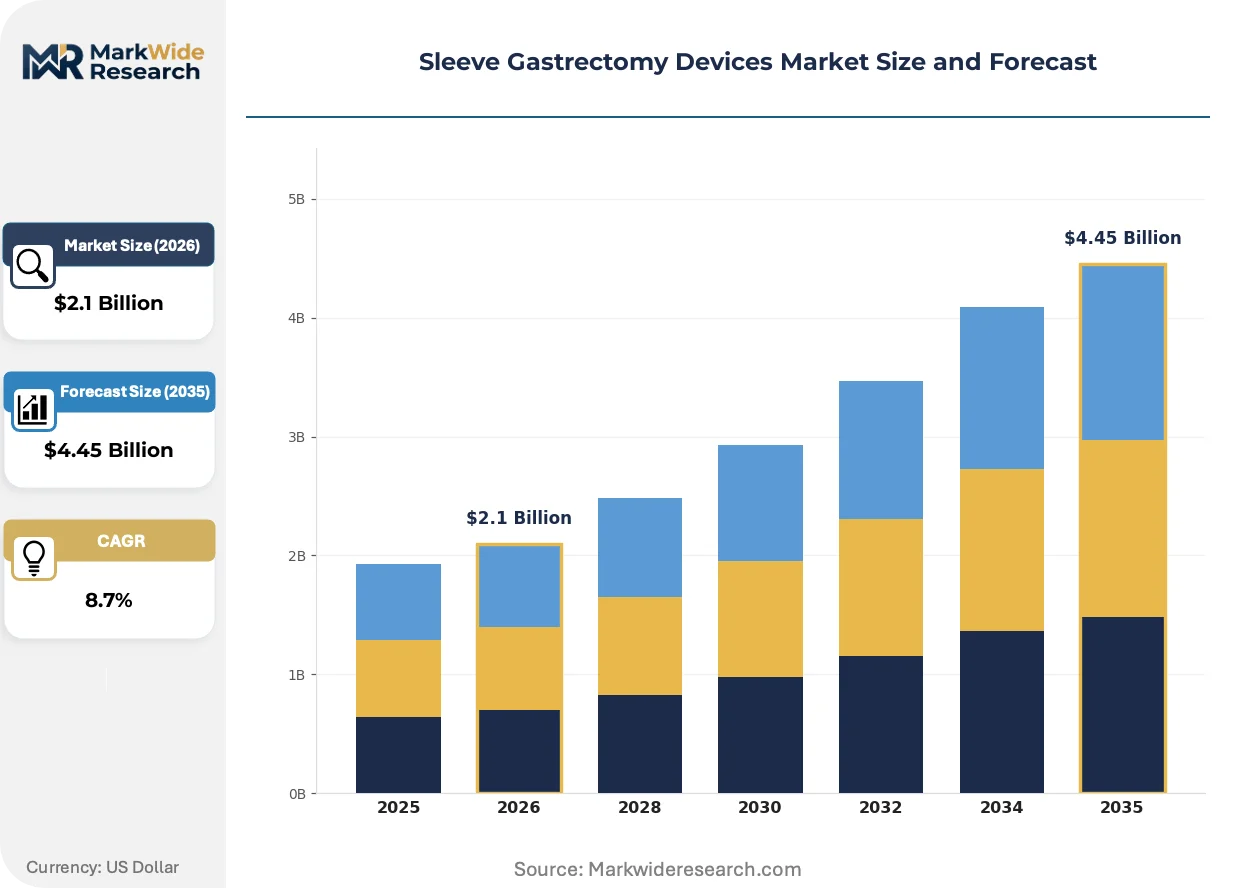
Market Dynamics
Reimbursement coding compression for metabolic surgery is forcing device manufacturers to demonstrate superior cost-per-procedure outcomes against competing bariatric interventions. Payers in the United States, Germany, and Japan are tightening prior authorization requirements while expanding coverage for endoluminal alternatives.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for stapler reload innovations reduce commercialization lag for manufacturers targeting bariatric clinic networks.
- Biodegradable polymer advancement:Absorbable staple-line reinforcement materials eliminate permanent mesh complications, driving hospital procurement preference shifts in tertiary care centers.
- Japan metabolic surgery expansion:METI-supported obesity treatment protocols increase sleeve gastrectomy procedure volumes in Tokyo and Osaka metropolitan clusters.
Market Restraints
- Stainless steel input volatility:Surgical stapler cartridge production faces margin pressure from fluctuating nickel and chromium commodity prices.
- EU MDR technical documentation burden:Conformity assessment timelines for robotic-assisted platforms extend market access costs by twelve to eighteen months.
- Endoluminal sleeve substitution:Non-surgical gastric restriction procedures capture pre-diabetic patient segments previously routed to laparoscopic surgery.
Strategic Opportunities
- China domestic production incentives:NMPA localization requirements create captive supply opportunities for laparoscopic stapling system manufacturers establishing Shanghai or Shenzhen manufacturing.
- Robotic-image guidance convergence:Integration of intraoperative fluorescence imaging with robotic stapling protocols reduces operative variability and supports premium pricing.
- Ambulatory surgical center channel expansion:Outpatient bariatric protocols in the United States open device procurement relationships outside traditional hospital supply chains.
Industry Challenges
- Specialized bariatric surgeon scarcity:Fellowship-trained metabolic surgery capacity constraints limit procedure volume expansion in secondary markets.
- EU AI Act algorithmic validation:Robotic platform manufacturers face documentation requirements for machine learning components in preoperative planning modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleeve Gastrectomy Devices Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bands, Stents, Sutures, Clips Material: Silicone, Polypropylene, Stainless Steel, Biodegradable Plastics End User: Hospitals, Bariatric Clinics, Outpatient Surgery Centers, Research Institutions Application: Weight Loss, Diabetes Management, Metabolic Disorders, Gastroesophageal Reflux |
| Companies Covered | Intuitive Surgical Inc, Johnson & Johnson, Medtronic plc, Stryker, Apollo Endosurgery Inc, Olympus Corporation, Standard Bariatrics Inc, NuVasive Inc, Smith+Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleeve Gastrectomy Devices Market Evolving Landscape
Device architecture is pivoting toward disposable-single-use configurations that eliminate reprocessing liability while capturing procedure economics previously lost to sterilization services. This shift reconfigures supply chain relationships between manufacturers and hospital materials management.
Staple-line reinforcement technology is migrating from permanent polymer mesh to absorbable synthetic matrices that degrade within ninety days post-implantation. Tertiary care hospitals in the United States and Germany are adopting these materials at accelerated procurement cycles. This transition compresses margin pools for incumbent mesh suppliers while opening premium positioning for biodegradable platform developers.
The EU AI Act and FDA software-as-medical-device guidance are imposing validation documentation requirements on algorithmic components within robotic-assisted platforms. Manufacturers must submit clinical evidence for machine learning modules that adjust stapling parameters based on tissue thickness feedback. Robotic system developers with integrated image guidance capabilities face the steepest compliance burden as they retrofit existing platforms for premarket submission.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, forcing device manufacturers to compete on standalone technical support pricing. Bariatric clinics in Japan and the United States are leading this disintermediation, sourcing maintenance from third-party biomedical engineering firms. This compression is most visible in metropolitan clusters where surgical volume justifies dedicated in-house device servicing teams.
Sleeve Gastrectomy Devices Market Segmentation
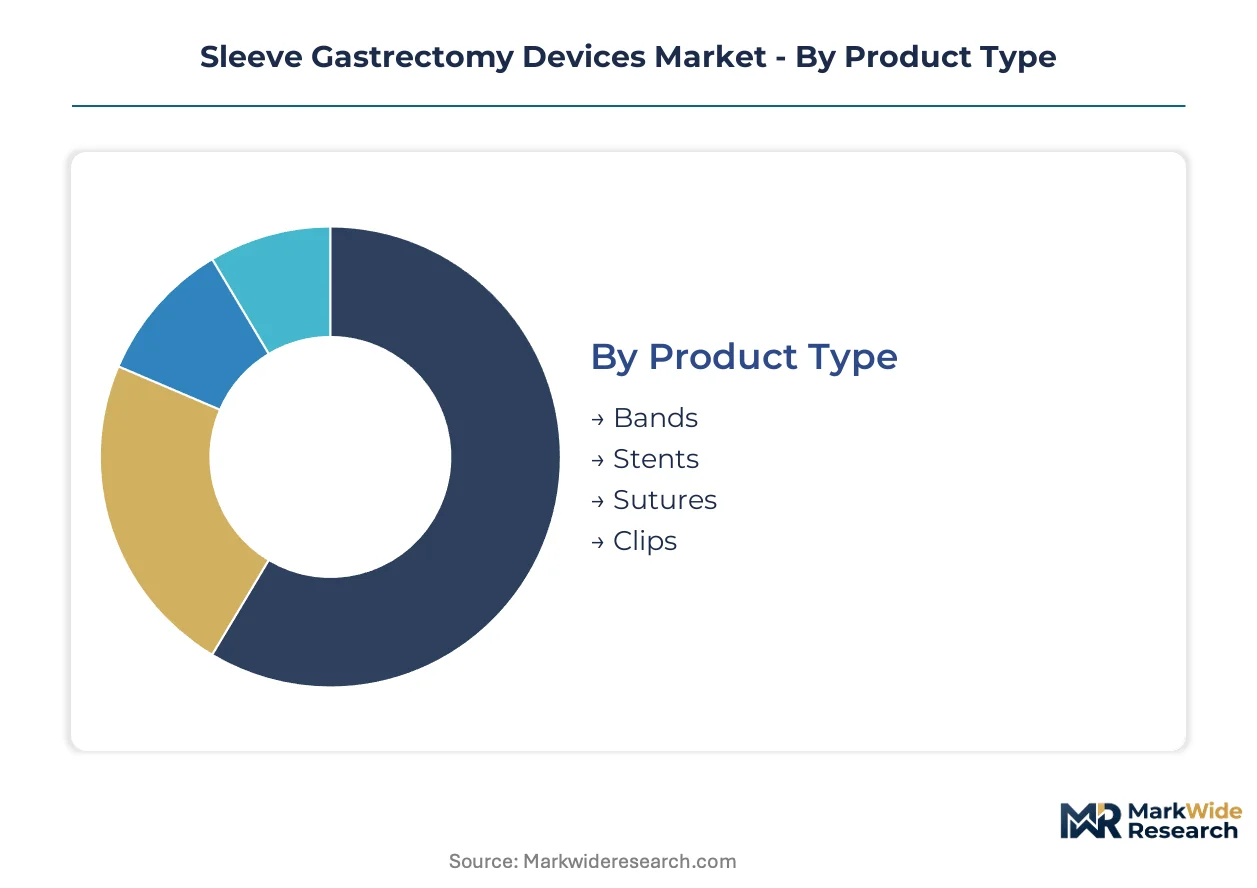
Segmentation in sleeve gastrectomy devices reveals distinct procurement cycles and clinical utility patterns across product categories. Hospitals and bariatric clinics prioritize staple-line integrity and operative efficiency when selecting device configurations for metabolic surgery workflows.
Product Type:
Replacement cycles vary sharply across this category, with consumable reloads turning over monthly while capital equipment persists for seven to ten years.
- Sutures:Absorbable and non-absorbable configurations reinforce staple lines against leakage and bleeding complications. Demand concentrates in tertiary hospitals across the United States and Germany where staple-line reinforcement protocols are mandatory. Biodegradable polymer advancement is shifting procurement preference toward absorbable synthetic matrices.
- Clips:Titanium and polymer variants secure tissue approximation and vascular control during gastric transection. Bariatric clinics in Tokyo and Osaka metropolitan clusters are expanding clip utilization as METI-supported obesity treatment protocols increase sleeve procedure volumes. Prior authorization tightening from payers is forcing demonstration of superior cost-per-procedure outcomes.
- Bands:Adjustable gastric restriction devices for revisional procedures.
- Stents:Endoluminal platforms for non-surgical gastric volume reduction.
Sutures anchor the volume base while clips gain share at the steepest rate.
Material:
Cost tiers separate premium absorbable synthetics from commodity stainless steel, with procurement committees weighing complication avoidance against per-procedure economics.
- Biodegradable Plastics:Polylactic acid and polyglycolic acid matrices degrade within ninety days post-implantation, eliminating permanent mesh complications. Tertiary care centers in the United States and Germany are adopting these materials at accelerated procurement cycles. This transition compresses margin pools for incumbent mesh suppliers.
- Stainless Steel:Surgical stapler cartridges and clip appliers rely on nickel-chromium alloys for structural integrity and corrosion resistance. Fluctuating commodity prices for nickel and chromium inputs are pressuring manufacturer margins. Scale economies and reprocessing protocols defend incumbent positions in high-volume bariatric centers.
- Silicone:Biocompatible elastomer for adjustable band systems.
- Polypropylene:Permanent mesh for staple-line reinforcement in cost-constrained settings.
Stainless steel dominates installed base value while biodegradable plastics are expanding most quickly in new procurement.
End User:
Customer type determines channel strategy, with hospital supply chains demanding bundled service contracts and ambulatory centers pursuing unbundled technical support.
- Hospitals:Integrated health systems with dedicated metabolic surgery programs generate the highest per-procedure device utilization. Procurement committees in the United States and Germany are unbundling after-sales service contracts from capital equipment purchases. Third-party biomedical engineering firms are capturing maintenance relationships.
- Bariatric Clinics:Specialized facilities focus exclusively on metabolic and bariatric surgical volume. Fellowship-trained surgeon scarcity limits procedure expansion in secondary markets. FDA 510(k) pathway streamlining is accelerating adoption of stapler reload innovations.
- Outpatient Surgery Centers:Ambulatory bariatric protocols are opening device procurement outside traditional hospital supply chains.
- Research Institutions:Academic medical centers evaluate novel endoluminal and robotic-assisted platforms.
Hospitals anchor the volume base while outpatient surgery centers are climbing the fastest as reimbursement shifts toward ambulatory settings.
Application:
Clinical indication shapes device selection, with diabetes management protocols demanding precision stapling and metabolic disorder cases prioritizing operative speed.
- Weight Loss:Primary bariatric indication drives stapling instrument and calibration tube utilization. Robotic-assisted sleeve gastrectomy protocols reduce operative variability in high-volume centers. EU MDR technical documentation requirements are extending market access timelines for robotic platform manufacturers.
- Diabetes Management:Metabolic surgery for type 2 diabetes remission requires standardized gastric sleeve geometry to modulate hunger hormone secretion. Japan's METI-supported treatment protocols are expanding sleeve volumes in Tokyo and Osaka. Endoluminal sleeve substitution is capturing pre-diabetic patient segments.
- Metabolic Disorders:Dyslipidemia and hypertension comorbidities.
- Gastroesophageal Reflux:Revisional procedures for post-sleeve reflux complications.
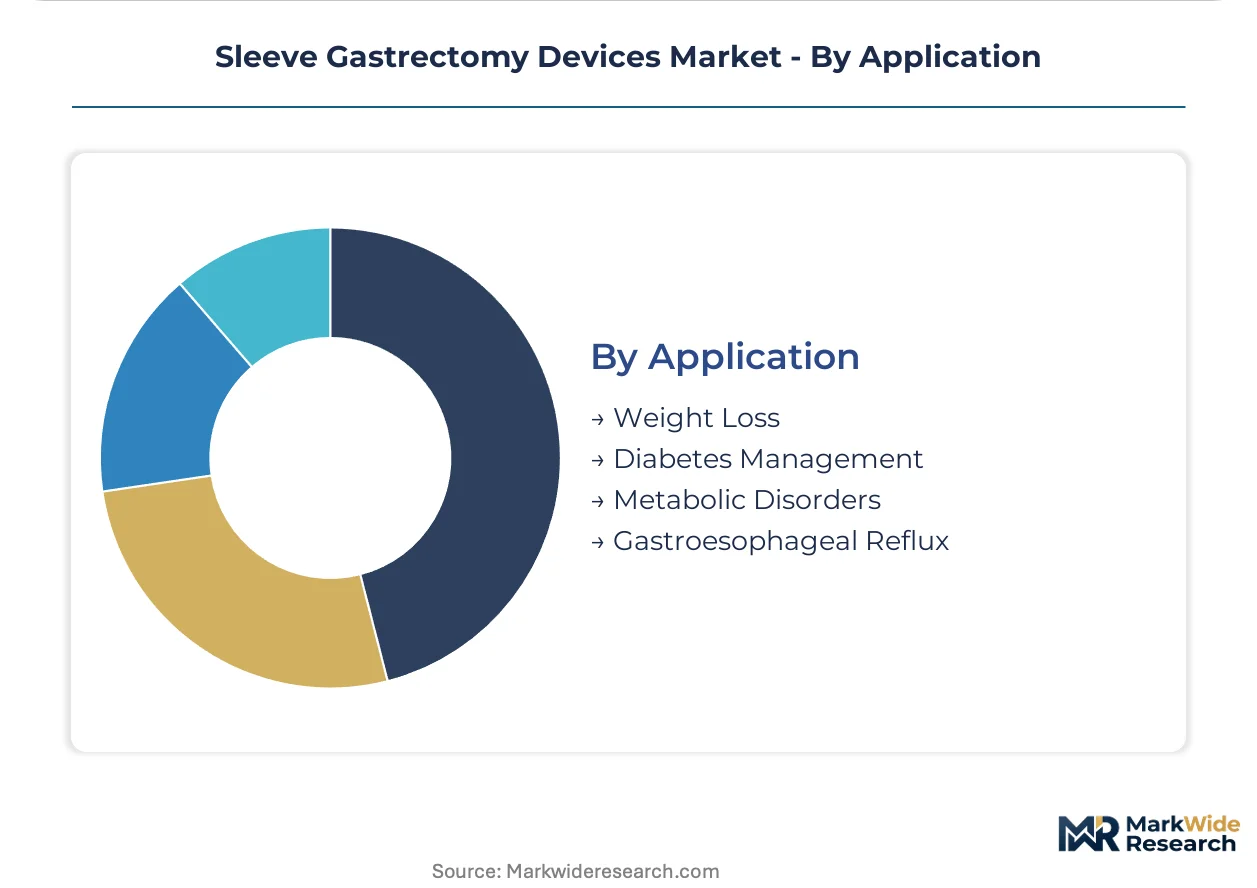
Weight loss anchors the volume base while diabetes management is gaining share fastest as reimbursement frameworks expand metabolic surgery access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics infrastructure underwrites Europe's distribution capacity for laparoscopic stapling systems, while Shanghai Pudong International Airport's cold-chain cargo terminals anchor Asia-Pacific supply velocity for temperature-sensitive reinforcement materials.
United States
CMS reimbursement coding for metabolic surgery and ambulatory surgical center expansion drive device procurement. FDA 510(k) pathway streamlining accelerates stapler reload commercialization timelines. The Cleveland Clinic and Mayo Clinic surgical networks in Ohio and Minnesota generate concentrated demand for robotic-assisted platforms.
Germany
EU MDR conformity assessment requirements and statutory health insurance coverage for bariatric procedures shape market access. The country's national pharmaceutical regulator enforces technical documentation standards for robotic platforms. Tertiary care clusters in Berlin and Munich are unbundling after-sales service contracts from capital equipment purchases.
Japan
METI-supported obesity treatment protocols and aging-related metabolic disorder prevalence expand sleeve procedure volumes. The Pharmaceuticals and Medical Devices Agency scrutinizes software-as-medical-device components in robotic systems. Tokyo and Osaka metropolitan clusters are adopting clip-based reinforcement technologies at accelerated procurement cycles.
China
NMPA localization requirements and domestic production incentives for laparoscopic systems reshape supply chains. The national medical products administration mandates conformity assessment for imported stapling platforms. Manufacturing concentration in Shanghai and Shenzhen is capturing assembly operations for multinational device manufacturers.
United Kingdom
NHS England commissioning frameworks for tier-three weight management services route patients toward surgical intervention. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with EU MDR standards. London and Manchester academic medical centers are evaluating endoluminal sleeve alternatives to conventional laparoscopic approaches.
Sleeve Gastrectomy Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The market structure consolidates around diversified surgical technology conglomerates with captive stapling portfolios, while mid-scale reinforcement material developers occupy niche positions. Two strategic archetypes dominate: full-procedure-workflow providers spanning access to closure, and focused robotics developers targeting operative variability reduction. Competitive moves concentrate on M&A for staple-line reinforcement technology and strategic partnerships for ambulatory surgical center channel access.
Among diversified surgical technology conglomerates, Johnson & Johnson and Medtronic plc exemplify full-workflow platform developers with integrated reload and reinforcement portfolios. Intuitive Surgical Inc occupies a specialized position within robotic-assisted protocol development. These three entities anchor the competitive structure through differentiated approaches to operative standardization and channel reach.
| Leading Market Players |
|---|
| Intuitive Surgical Inc |
| Johnson & Johnson |
| Medtronic plc |
| Stryker |
| Apollo Endosurgery Inc |
| Olympus Corporation |
| Standard Bariatrics Inc |
| NuVasive Inc |
| Smith+Nephew |
| Others |
Value Network & Pricing Analysis
Commodity volatility in nickel-chromium alloys determines both margin compression in stainless steel stapler cartridges and the geographic clustering of component forging operations. Manufacturers with captive supply of surgical-grade metals command pricing power across premium tier configurations, while procurement committees in cost-constrained settings force substitution toward reprocessable standard-tier alternatives.
Pricing Analysis
Volume-discount tiering separates bundled capital-plus-service contracts from unbundled consumable-only procurement. Premium robotic-assisted platforms capture pricing power through integrated fluorescence imaging capabilities, while standard laparoscopic stapling systems face cost compression from third-party reload competitors. Hospital materials management committees in Germany and the United States demonstrate highest price sensitivity, whereas academic medical centers prioritize operative standardization over per-procedure economics.
Supply Chain Analysis
Export-control regimes on precision laser-welding equipment limit flows of advanced stapler cartridge manufacturing technology to certain jurisdictions. Component forging concentrates in Germany, Japan, and the United States, with nickel-chromium alloy feedstock drawing from Russian and Indonesian mining operations. Single-source vulnerability sits with specialized calibration tube suppliers serving robotic platform integrators. Distribution runs through hospital purchasing organizations and group procurement networks in metropolitan surgical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device architecture fragmentation creates entry niches as ambulatory surgical centers disintermediate traditional hospital supply relationships and demand unbundled technical support pricing.
For Market Incumbents: Insulate staple-line reinforcement portfolios through backward integration into biodegradable polymer synthesis and captive supply of absorbable matrix production. Lock in ambulatory surgical center channel control through standalone technical service contracts that preempt third-party biomedical engineering capture. Defend against endoluminal sleeve substitution by embedding robotic-assisted protocols in metabolic surgery training curricula. For New Entrants and Emerging Players: Build out clip-based reinforcement technology for the Japan metropolitan clusters where METI-supported obesity protocols are accelerating sleeve procedure volumes. Target outpatient surgery centers in the United States with disposable-single-use stapling configurations that eliminate reprocessing liability. Establish go-to-market positioning through GPO contract penetration rather than capital equipment direct sales. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors biodegradable material specialists over permanent mesh incumbents. Long-term viability across the next decade hinges on regulatory navigation capabilities for EU AI Act algorithmic validation requirements. Acquisition targets with integrated fluorescence imaging modules and stapler reload innovation pipelines offer defensive positioning. Watch FDA 510(k) clearance velocity for robotic-assisted platforms as the inflection signal for competitive reordering.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation for robotic platforms extends market access timelines twelve to eighteen months. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic networks generate concentrated demand for operative standardization protocols. |
| Software Companion Development | FDA software-as-medical-device guidance imposes validation requirements on machine learning stapling modules. |
| Reimbursement Strategy | CMS coding compression for metabolic surgery forces demonstration of superior cost-per-procedure outcomes. |
| Backward Integration | Captive supply of biodegradable polymer matrices defends margin pools against commodity stainless steel volatility. |
Research Methodology
Operator-level perspectives from bariatric surgeons, hospital purchasing committee chairs, biomedical engineering directors, and GPO contracts managers anchored the qualitative base. Primary interview data combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS reimbursement coding records, and hospital procurement system disclosures. Bottom-up procedure volume estimates and top-down device revenue triangulation cross-checked segmentation outputs.
Scenario-bracketing around regulatory pathway delays and commodity price volatility informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material composition, end-user facility category, and application indication. CAGRs derived from procedure volume trajectories, device replacement cycles, and pricing tier evolution. Forecast inputs incorporated METI-supported obesity protocol expansion in Japan and NMPA localization requirements in China.
Stress conditions across nickel-chromium commodity volatility, EU MDR conformity assessment timeline extension, and endoluminal sleeve substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding reimbursement stability and surgeon training pipeline capacity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
Eye Socket Implants Market
Medical Devices
Urodynamic Devices Market
Medical Devices
Intravenous Access Devices Market
Medical Devices
Global Oxygen Conservation Devices Market
Medical Devices
Implant Handpiece Market
Medical Devices
Global Disposable Medical Sensors Market
Medical Devices
Endoscope Flushing Pumps Market
Medical Devices
Medical Smart Wearable Devices Market
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Therapeutic Contact Lenses Market
Medical Devices
Global Electronic Drug Delivery Systems Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Drug and Gene Delivery Devices Market
Medical Devices
High Tibial Osteotomy (HTO) Plates Market
Medical Devices
Esophageal Stethoscopes Market