
 Colorectal Cancer Molecular Diagnostics Market | 2026-2036
Colorectal Cancer Molecular Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Colorectal Cancer Molecular Diagnostics Market Outlook
The EU Green Deal's healthcare decarbonization targets is realigning procurement criteria for molecular diagnostics across European hospital networks. Exact Sciences Corporation leverages its specialized expertise in non-invasive colorectal screening to sustain laboratory partnerships across North America. F. Hoffmann-La Roche Ltd anchors its competitive position through integrated workflow solutions spanning sequencing platforms and companion diagnostics. Qiagen differentiates its portfolio with sample preparation technologies that control upstream quality in PCR-based colorectal mutation detection.
Colorectal cancer molecular diagnostics encompasses nucleic acid-based assays, protein biomarker detection systems, and genomic profiling platforms designed to identify oncogenic mutations, microsatellite instability, and epigenetic alterations in tissue or liquid biopsy specimens. These technologies employ polymerase chain reaction amplification, fluorescence in situ hybridization probe hybridization, and next-generation sequencing readouts to detect KRAS, NRAS, BRAF, and PIK3CA mutations that guide targeted therapy selection and monitor minimal residual disease. Next-generation sequencing occupies the premium tier of technology segmentation, capturing complex mutational signatures and expanding indication scope beyond single-gene hotspot analysis. Diagnostic kits represent the mature revenue base within product type segmentation, while assay systems command higher margins through recurring consumable pull-through and automated workflow integration.
The FDA's oversight of companion diagnostics through the Center for Devices and Radiological Health shapes premarket approval pathways and clinical validation requirements for colorectal cancer biomarker tests. EMA's In Vitro Diagnostic Regulation mandates post-market performance surveillance and notified body certification, elevating compliance costs for manufacturers seeking European market access. WHO classification frameworks for tumor pathology influence standardization of molecular testing protocols across national health systems. Stakeholders must monitor evolving payer coverage determinations for multi-cancer early detection assays and assess whether liquid biopsy platforms will displace tissue-based testing in adjuvant monitoring settings.
Market Dynamics
Non-invasive stool DNA testing is compressing tissue biopsy volumes while expanding screening eligibility to asymptomatic populations, fundamentally restructuring laboratory workflows and reimbursement patterns across health systems.
Growth Catalysts
- Medicare coverage expansion:CMS reimbursement codes for multi-target stool DNA assays eliminate out-of-pocket barriers for Medicare beneficiaries aged 45-75, accelerating adoption in community oncology settings.
- PCR-based mutation detection:Real-time polymerase chain reaction platforms deliver same-day KRAS/NRAS/BRAF results, enabling immediate therapy selection in metastatic colorectal cancer management.
- Liquid biopsy validation:Circulating tumor DNA assays for minimal residual disease monitoring create recurring revenue streams in adjuvant surveillance protocols.
Market Restraints
- EU In Vitro Diagnostic Regulation compliance:EMA-mandated notified body certification and post-market performance surveillance elevate entry costs for biomarker test manufacturers seeking European market access.
- Sequencing reagent supply concentration:Dependence on single-source polymerase enzymes and fluorescent probe chemistries from specialized suppliers creates input cost volatility and allocation risk.
- Formalin-fixed paraffin-embedded tissue degradation:Pre-analytical variability in sample fixation compromises nucleic acid yield, limiting assay sensitivity in archival specimens.
Strategic Opportunities
- Multi-cancer early detection integration:Blood-based methylation panels that include colorectal signatures alongside other malignancies capture screening budget consolidation in employer-sponsored health plans.
- Pharmacogenomic co-development:Companion diagnostic partnerships for emerging HER2-directed and KRAS G12C inhibitors secure exclusive assay placement in pivotal clinical trials.
- Decentralized point-of-care testing:Cartridge-based PCR systems deploy to community gastroenterology clinics, reducing sample transport logistics and time-to-result in rural health networks.
Industry Challenges
- Bioinformatics pipeline standardization:Variant interpretation discordance between laboratories necessitates investment in curated knowledge bases and cross-platform harmonization initiatives.
- Laboratory-developed test validation:FDA premarket approval pathways for in-house assays demand extensive analytical and clinical studies, compressing margins for hospital-based molecular pathology programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colorectal Cancer Molecular Diagnostics Market |
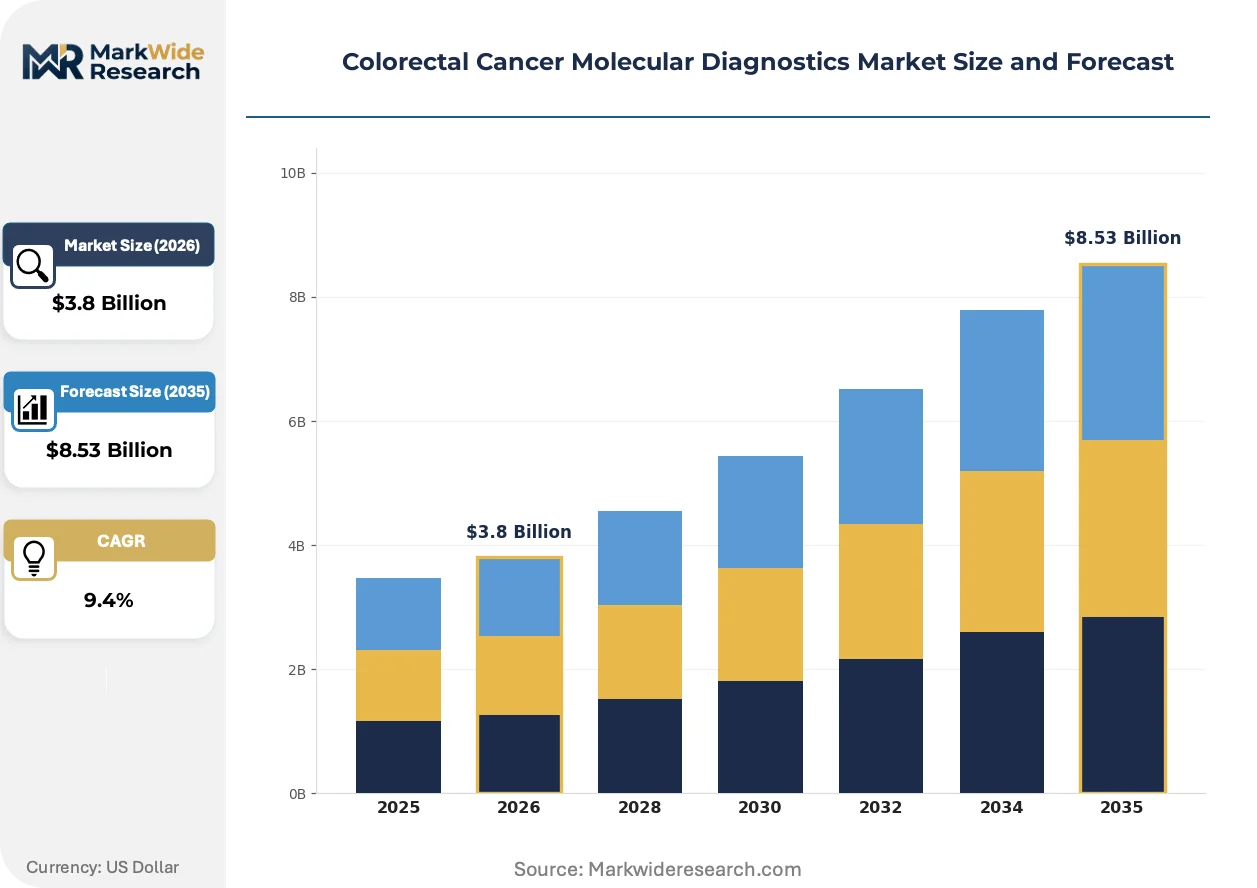
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Biomarkers, Reagents, Assay Systems Technology: Next-Generation Sequencing, PCR, FISH, IHC End User: Hospitals, Diagnostic Laboratories, Research Institutions, Oncology Clinics Delivery Mode: Laboratory Services, Point-of-Care, Home Testing, Telehealth |
| Companies Covered | F. Hoffmann-La Roche Ltd, Exact Sciences Corporation, Guardant Health, Qiagen, Danaher Corporation, Abbott Laboratories, Agilent Technologies, Hologic, Cepheid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colorectal Cancer Molecular Diagnostics Market Strategic Shifts
Workflow automation and artificial intelligence-assisted variant classification are compressing turnaround times while expanding testing capacity without proportional staffing expansion. These shifts favor integrated platform vendors over fragmented reagent suppliers.
Next-generation sequencing is absorbing complex mutational signature analysis previously requiring sequential single-gene assays, consolidating testing menus into unified panels. Major cancer centers in the United States and Germany are adopting comprehensive genomic profiling as front-line diagnostic standard. This technology is absorbing market share from fluorescence in situ hybridization for microsatellite instability detection, compressing reimbursement codes into broader sequencing categories.
EMA's In Vitro Diagnostic Regulation mandates performance surveillance and notified body involvement for all biomarker-based colorectal cancer tests, elevating documentation burdens for manufacturers. European hospital procurement departments now require CE-marked companion diagnostics with post-market clinical evidence packages. Smaller assay developers are responding through notified body pre-submission programs and quality management system overhauls to maintain market access.
Oncology clinics are unbundling histopathology from molecular testing, contracting directly with specialized reference laboratories for genomic profiling. This disintermediation bypasses traditional hospital laboratory networks and concentrates volume with high-throughput sequencing centers. The pattern is most visible in United States metropolitan markets where independent gastroenterology groups negotiate preferred pricing for stool DNA screening and reflex mutation testing.
Colorectal Cancer Molecular Diagnostics Market Segmentation
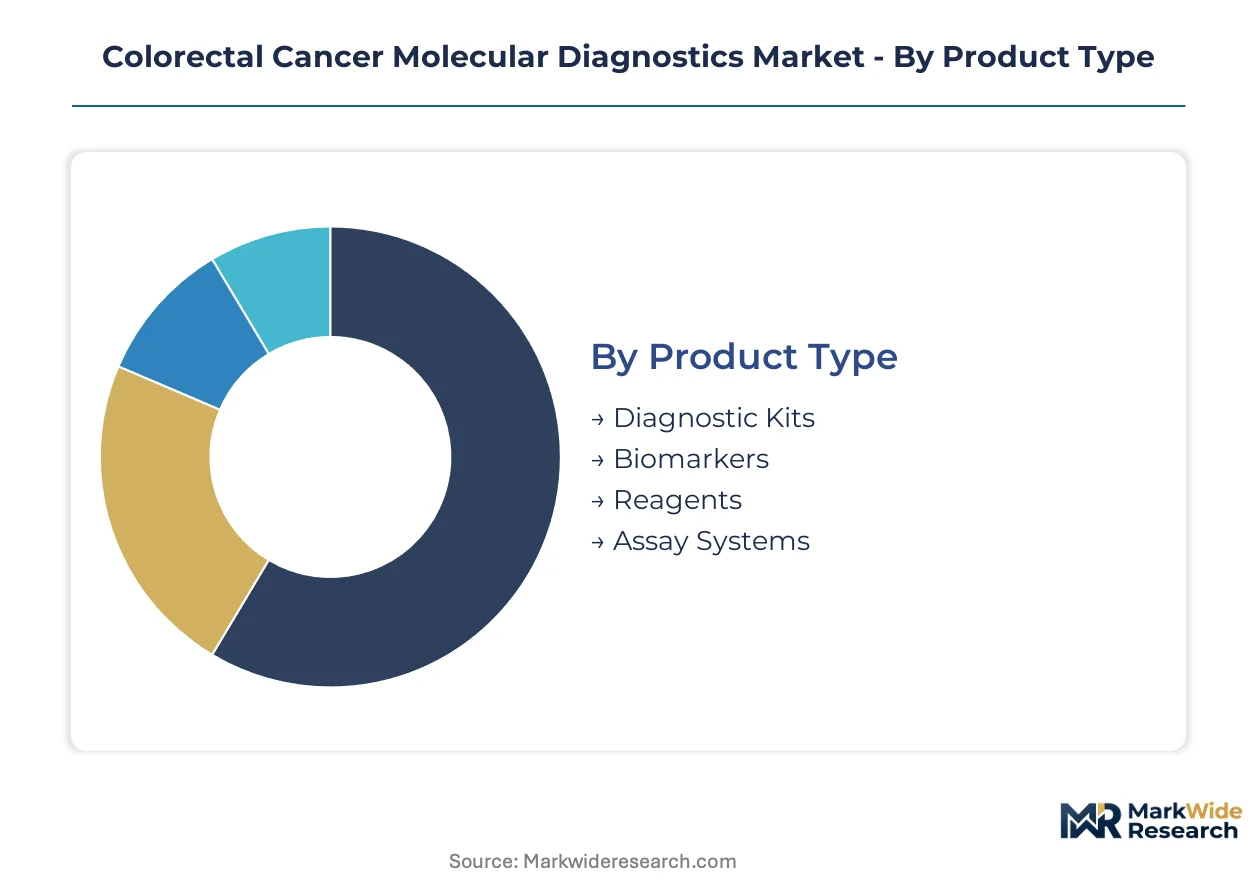
Segmentation in colorectal cancer molecular diagnostics reveals how technology integration depth shapes procurement decisions across health systems. Standalone platforms command premium positioning in centralized laboratories, while embedded workflows penetrate decentralized care settings.
Product Type:
Integration depth separates standalone consumables from fully automated systems that embed sample-to-result workflows.
- Diagnostic Kits:Pre-configured reagent panels for KRAS, NRAS, BRAF, and PIK3CA mutation detection ship in lyophilized or liquid formats with standardized protocols. Demand concentrates in United States community oncology clinics where Medicare reimbursement favors kit-based testing over send-out laboratory services.
- Assay Systems:Integrated platforms combine nucleic acid extraction, amplification, and detection modules with automated liquid handling. Germany's university hospital networks favor these systems for high-throughput microsatellite instability screening, absorbing workflow consolidation pressures from EU Green Deal procurement criteria.
- Biomarkers:Purified protein and nucleic acid reference standards calibrate assay performance across laboratories.
- Reagents:Polymerase enzymes, fluorescent probes, and buffer formulations supply open-architecture PCR and sequencing workflows.
Volume placements concentrate in Diagnostic Kits; the faster expansion belongs to Assay Systems.
Technology:
Cost tier stratification positions sequencing at premium price points while PCR dominates routine mutation screening.
- Next-Generation Sequencing:Massively parallel readout platforms detect complex mutational signatures, tumor mutational burden, and microsatellite instability from single biopsy specimens. Major cancer centers in Boston and Heidelberg adopt these as front-line standards, displacing sequential single-gene assays.
- PCR:Real-time amplification delivers same-day KRAS/NRAS/BRAF results with lower capital requirements. United States diagnostic laboratories deploy PCR for immediate therapy selection in metastatic cases where turnaround time drives clinical utility.
- FISH:Fluorescence in situ hybridization probes detect gene amplification and chromosomal rearrangements in tissue sections.
- IHC:Immunohistochemistry antibodies visualize protein expression of mismatch repair proteins and HER2 status.
PCR maintains the largest installed base; next-generation sequencing is climbing the fastest as panel consolidation accelerates.
End User:
Customer type determines whether testing occurs within institutional networks or bypasses traditional laboratory hierarchies.
- Diagnostic Laboratories:Centralized reference facilities process high-volume genomic profiling with CAP/CLIA accreditation. United States independent gastroenterology groups contract directly with these laboratories, disintermediating hospital networks for stool DNA screening and reflex mutation testing.
- Oncology Clinics:Community and academic cancer centers integrate molecular testing into treatment planning workflows. Germany's outpatient oncology practices are expanding in-house PCR capacity to reduce sample transport delays.
- Hospitals:Integrated health systems maintain molecular pathology departments for tissue-based diagnostics.
- Research Institutions:Academic medical centers validate novel biomarkers and develop laboratory-developed tests for investigational use.
Diagnostic Laboratories capture the highest test volumes; Oncology Clinics are expanding most quickly as point-of-care models proliferate.
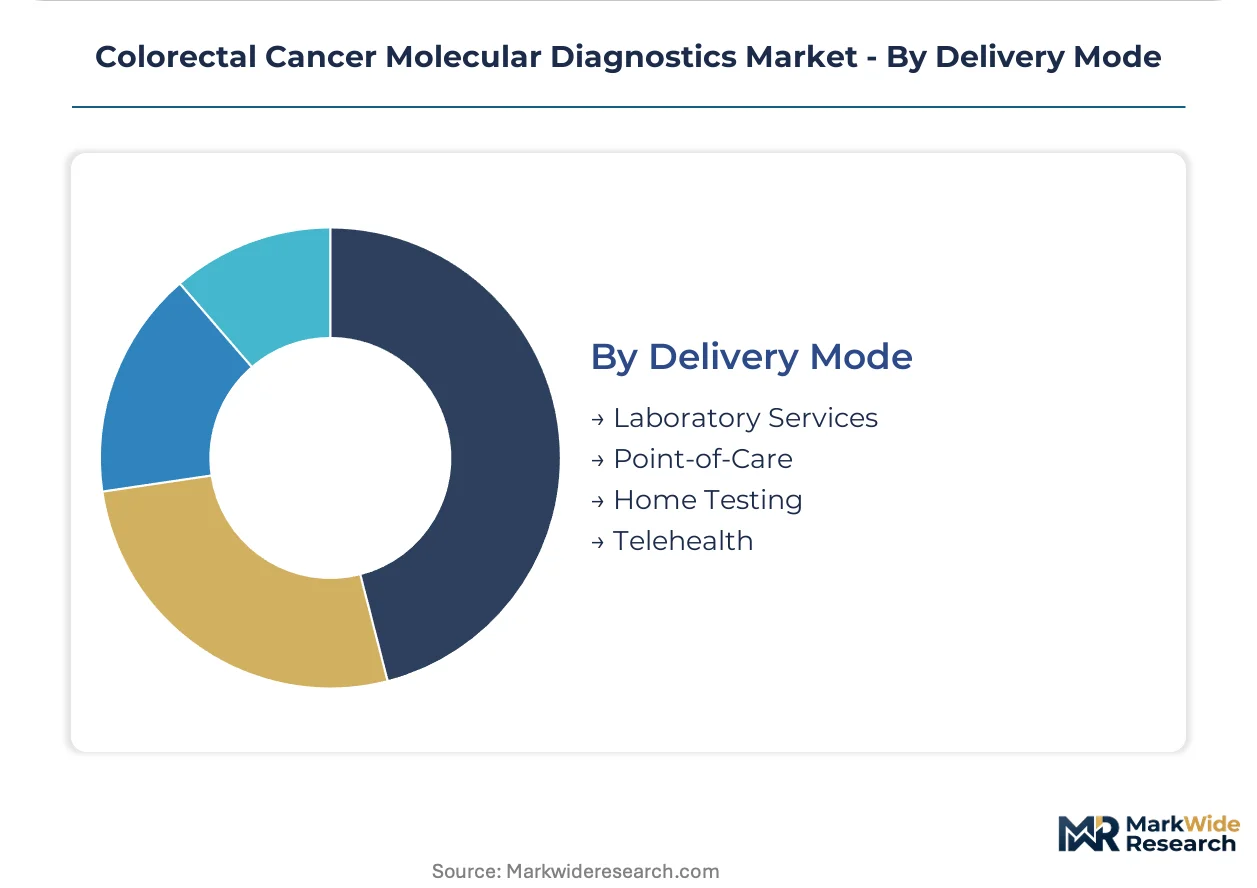
Delivery Mode:
Geography shapes whether specimens travel to centralized hubs or testing decentralizes to patient proximity.
- Laboratory Services:Send-out models ship specimens to specialized reference facilities with comprehensive profiling capabilities. Rural United States health networks rely on these services for access to next-generation sequencing beyond local capacity.
- Point-of-Care:Cartridge-based systems deploy to community gastroenterology clinics for same-day mutation results. Germany's ambulatory care expansion is driving placement in metropolitan outpatient centers.
- Home Testing:Patient-collected stool specimens for DNA-based screening bypass clinical encounters entirely.
- Telehealth:Remote consultation platforms integrate molecular test ordering and result delivery for geographically dispersed populations.
Laboratory Services dominate current revenue; Point-of-Care is gaining share fastest as cartridge technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's concentration of cancer research institutions and genomic medicine centers anchors North American demand for comprehensive colorectal cancer molecular diagnostics, while Heidelberg and Munich drive comparable adoption patterns across German university hospital networks.
United States
Medicare reimbursement codes for multi-target stool DNA assays eliminate cost barriers for beneficiaries aged 45-75, accelerating community oncology adoption. FDA oversight through the Center for Devices and Radiological Health shapes premarket approval pathways for companion diagnostics. The Boston-Cambridge corridor concentrates next-generation sequencing deployment at Dana-Farber Cancer Institute and Massachusetts General Hospital, displacing sequential single-gene testing.
Germany
University hospital networks favor integrated assay systems for high-throughput microsatellite instability screening, absorbing workflow consolidation pressures. EU Green Deal healthcare decarbonization targets realign procurement criteria across European hospital networks. Heidelberg's National Center for Tumor Diseases anchors comprehensive genomic profiling adoption alongside Munich's Ludwig-Maximilians-Universität Klinikum.
China
Domestic biotech clusters scale liquid biopsy platforms for minimal residual disease monitoring in adjuvant surveillance protocols. NMPA regulatory pathways for innovative diagnostic devices accelerate market entry for locally developed assays. Shanghai's Zhangjiang Hi-Tech Park concentrates cartridge-based PCR manufacturing for decentralized point-of-care deployment in community gastroenterology clinics.
Japan
PMDA harmonization with FDA companion diagnostic guidelines streamlines approval for KRAS-directed therapy selection assays. METI industrial policy supports domestic sequencing platform development to reduce import dependence. Tokyo's Cancer Institute Hospital and Osaka's National Hospital Organization anchor comprehensive genomic profiling adoption in metastatic colorectal cancer management.
United Kingdom
NHS England's genomic medicine service contracts consolidate molecular testing volume with designated high-throughput sequencing centers. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for innovative biomarker tests. London's Royal Marsden NHS Foundation Trust and Manchester's Christie NHS Foundation Trust anchor regional genomic profiling networks for colorectal cancer stratification.
Colorectal Cancer Molecular Diagnostics Market Competitive Environment
The competitive structure tilts toward integrated platform vendors over fragmented reagent suppliers, with workflow automation and artificial intelligence-assisted variant classification compressing turnaround times. Three archetypes dominate: multinational conglomerates with sequencing-to-diagnostic vertical integration, specialized oncology-focused developers with companion diagnostic partnerships, and sample preparation technology specialists controlling upstream quality. M&A activity concentrates on liquid biopsy platform acquisitions and strategic partnerships for pharmacogenomic co-development.
Among Swiss-based pharmaceutical-diagnostics conglomerates, F. Hoffmann-La Roche Ltd exemplifies integrated workflow solutions spanning sequencing platforms and companion diagnostics. Exact Sciences Corporation represents the specialized non-invasive screening archetype with laboratory partnership networks across North America. Qiagen occupies a position within sample preparation technology, anchoring upstream quality control in PCR-based mutation detection workflows.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Exact Sciences Corporation |
| Guardant Health |
| Qiagen |
| Danaher Corporation |
| Abbott Laboratories |
| Agilent Technologies |
| Hologic |
| Cepheid |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up diagnostic platform specialists have consolidated fragmented PCR reagent suppliers across North America and Europe, translating procurement scale into pricing discipline that squeezes standalone assay developers on both input costs and end-product margins.
Pricing Analysis
Value-based pricing anchored to clinical outcome metrics—specifically time-to-treatment decision and minimal residual disease detection sensitivity—commands premiums from United States oncology clinics seeking Medicare reimbursement optimization. Pricing stratifies across premium, standard, and economy tiers differentiated by automation level and companion diagnostic certification status. Cost compression in economy-tier PCR kits is intensifying because of Chinese cartridge manufacturers scaling point-of-care production. Community gastroenterology practices exhibit highest price sensitivity; major cancer centers prioritize throughput guarantees over per-test economics.
Supply Chain Analysis
Workforce-availability constraints in precision manufacturing hubs around Boston and San Diego have pushed reagent formulation and lyophilization capacity toward Germany's Rhine-Neckar biotechnology corridor and Singapore's Tuas biomedical park. Polymerase enzymes, fluorescent probe chemistries, and synthetic oligonucleotides draw from single-source suppliers concentrated in Switzerland and California. Single-source vulnerability in thermostable DNA polymerase production creates allocation risk during demand surges. Distribution runs through specialized cold-chain logistics networks serving CAP/CLIA-accredited reference laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
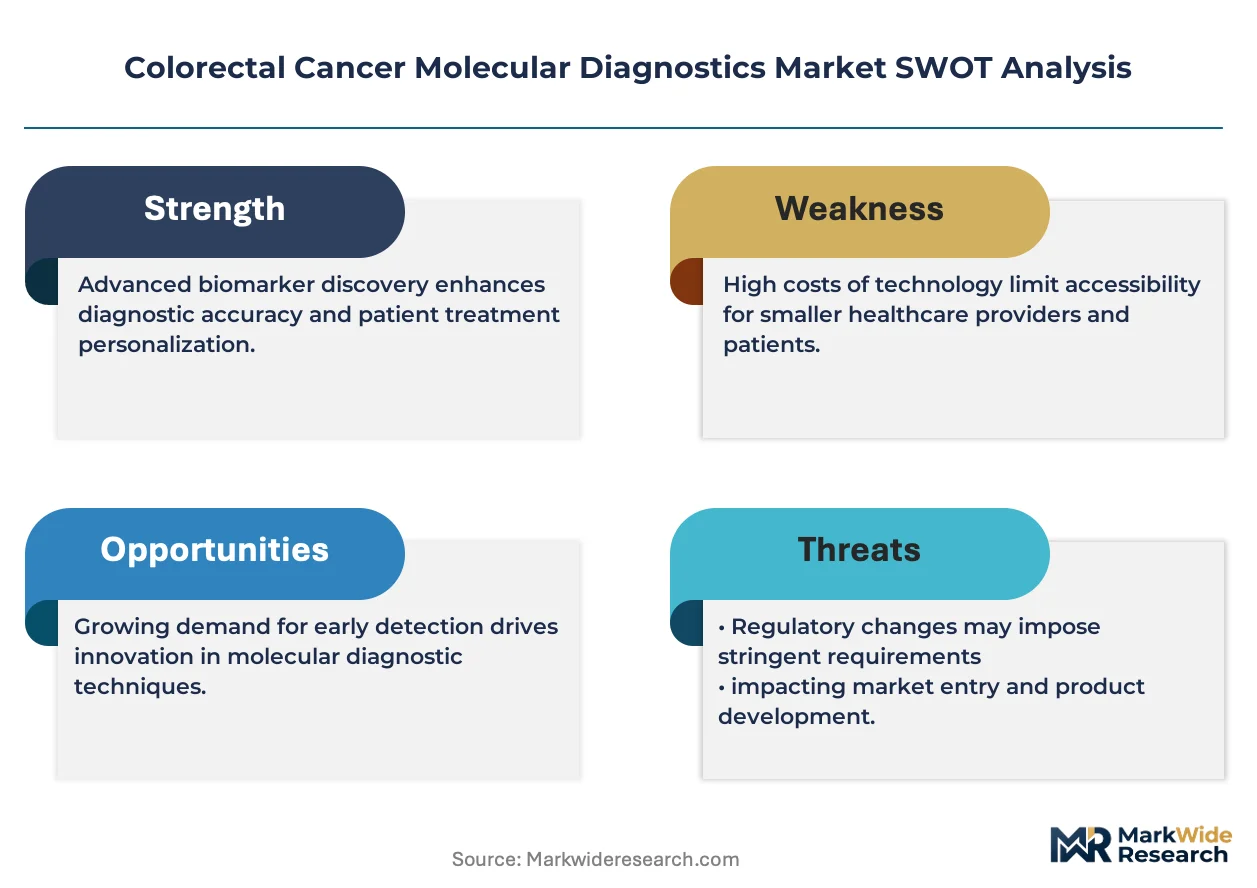
This market reads as a cost-of-compliance story where EMA's In Vitro Diagnostic Regulation erects a barrier-to-entry moat that rewards manufacturers with notified body certification infrastructure and post-market surveillance capabilities.
For Market Incumbents: To counter liquid biopsy platform entrants displacing tissue-based testing in adjuvant monitoring, secure exclusive companion diagnostic partnerships for emerging KRAS G12C and HER2-directed inhibitors while expanding backward integration into proprietary polymerase enzyme production to neutralize input cost volatility. For New Entrants and Emerging Players: Capture white-space opportunity in decentralized point-of-care cartridge systems for Germany's ambulatory gastroenterology expansion and India's tier-2 city oncology networks. Community clinics in rural United States health networks represent the most penetrable segment; pursue direct-to-clinic distribution bypassing hospital laboratory hierarchies. For Investors and Strategic Acquirers: Distressed-cycle entries favor sample preparation technology specialists with CE-marked quality control systems in European geographies where EU Green Deal procurement criteria favor workflow consolidation. Five-to-ten-year viability hinges on multi-cancer early detection assay integration. Signal to watch: CMS coverage determinations for blood-based methylation panels including colorectal signatures.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Secures exclusive assay placement in pivotal FDA-tracked clinical trials for emerging targeted therapies. |
| CE Marking Pathway | Unlocks European hospital procurement under EMA In Vitro Diagnostic Regulation post-market surveillance requirements. |
| Hospital System Partnership | Concentrates volume with high-throughput sequencing centers bypassing traditional laboratory networks. |
| Software Companion Development | Integrates AI-assisted variant classification compressing turnaround times without proportional staffing expansion. |
| Reimbursement Strategy | Aligns test menu design with CMS Medicare coverage codes for stool DNA screening in beneficiaries aged 45-75. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced with primary interviews involving clinical laboratory directors, hospital procurement managers, companion diagnostic regulatory leads, and gastroenterology practice administrators. FDA 510(k) submissions, EMA notified body certification databases, CMS Medicare reimbursement determinations, and hospital GPO contract repositories supplied quantitative anchors. Bottom-up test volume modeling and top-down market sizing triangulated across these sources.
Granularity-level modeling tracked technology platform, product type integration depth, end-user institutional category, and delivery mode geography across the projection horizon. CAGRs were derived from segmented growth rate analysis applied to baseline volume and value estimates. Forecast inputs incorporated Medicare coverage expansion trajectories, EU In Vitro Diagnostic Regulation implementation timelines, and liquid biopsy platform validation progress in minimal residual disease applications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS multi-cancer early detection coverage decisions and sequencing reagent supply concentration disruptions. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
Angiogenesis Assays Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Food Allergy Diagnosis and Treatment Market
Clinical Diagnostics
Global Cervical Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Herpes Marker Testing Market
Clinical Diagnostics
Osteoporosis Testing Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Antenatal Screening Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Pediatric Cardiac Tumor Diagnostics Market