
 Global Companion Animal Health Market | 2026-2036
Global Companion Animal Health Market Size, Share, and Industry Trends Forecast 2026-2036
Global Companion Animal Health Market Foresight
Prescription-grade biologics is bifurcating the companion animal health landscape into premium validated therapies and commodity-grade alternatives. Zoetis leverages its vertically integrated biological manufacturing network to dominate the canine vaccine segment. Boehringer Ingelheim anchors its position through sustained R&D intensity in feline respiratory disease portfolios.
Companion animal health encompasses the prevention, diagnosis, and treatment of disease in domesticated pets, comprising chemically synthesized small-molecule drugs, recombinant biologicals, and in-vitro diagnostic assays with specificity thresholds exceeding ninety-five percent. Its primary commercial purpose is to extend productive lifespan and reduce zoonotic transmission risk in human-animal cohabitation environments. Pharmaceuticals and vaccines together command the deepest margin pools, while diagnostics is the fastest-expanding category as point-of-care polymerase chain reaction platforms displace reference-lab workflows. Nutraceuticals occupies a maturing niche where regulatory ambiguity constrains premium pricing power.
The FDA Center for Veterinary Medicine enforces pharmacovigilance reporting that elevates compliance costs for novel therapeutic entrants, while the EU Green Deal's veterinary pharmaceutical residue limits are forcing reformulation of long-acting parasiticides. The USDA Animal and Plant Health Inspection Service coordinates interstate movement rules that shape distribution channel economics for live-attenuated vaccines. Stakeholders must monitor how Brazil's national agricultural regulator tightens import equivalency standards for biological products.
Market Dynamics
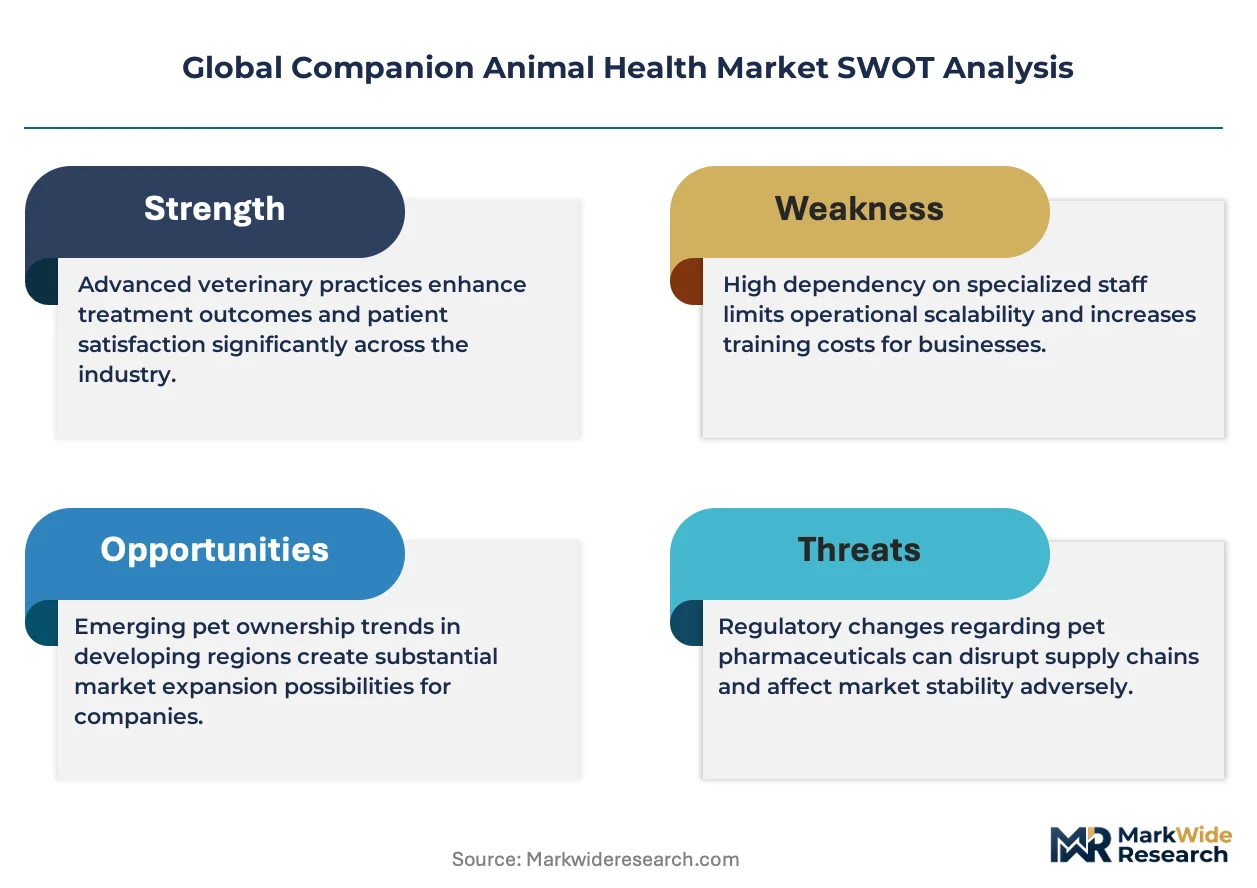
The FDA Center for Veterinary Medicine's pharmacovigilance expansion is restructuring competitive economics by elevating compliance thresholds for novel therapeutic entrants and compressing margin pools for mid-tier manufacturers lacking dedicated regulatory infrastructure.
Growth Catalysts
- Point-of-care PCR platforms:Veterinary clinics in the United States are adopting rapid molecular diagnostics that reduce turnaround times from days to hours, expanding service revenue per patient visit.
- EU Green Deal residue limits:Reformulation mandates for long-acting parasiticides are accelerating R&D investment in biodegradable active ingredient delivery systems.
- Brazil's import equivalency tightening:ANVISA's biological product standards are forcing foreign manufacturers to establish local manufacturing partnerships, deepening market penetration.
Market Restraints
- Active pharmaceutical ingredient concentration:Contract manufacturing for veterinary biologics concentrates in a limited supplier base, creating single-source vulnerability for recombinant protein production.
- Cold chain infrastructure gaps:Live-attenuated vaccine distribution faces temperature excursion risks in tropical climates, limiting rural veterinary service expansion.
- Nutraceutical regulatory ambiguity:Divergent national classification standards for pet supplements create formulation compliance costs that constrain cross-border product launches.
Strategic Opportunities
- Germany's veterinary digital health reimbursement:Emerging telemedicine coverage frameworks for remote consultations create channel expansion potential for diagnostic platform vendors.
- Feline respiratory disease portfolios:Underdeveloped therapeutic categories relative to canine offerings present white space for species-specific biologic development.
- Subscription-based preventive care:Monthly wellness plan models are displacing transactional veterinary visits in urban United States markets, locking in recurring revenue streams.
Industry Challenges
- Veterinary pathologist scarcity:Specialized diagnostic interpretation skills face supply constraints as diagnostic volume expands faster than training program output.
- Multi-jurisdiction pharmacovigilance reporting:Fragmented adverse event submission requirements across the United States, European Union, and Brazil strain regulatory affairs team capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Companion Animal Health Market |
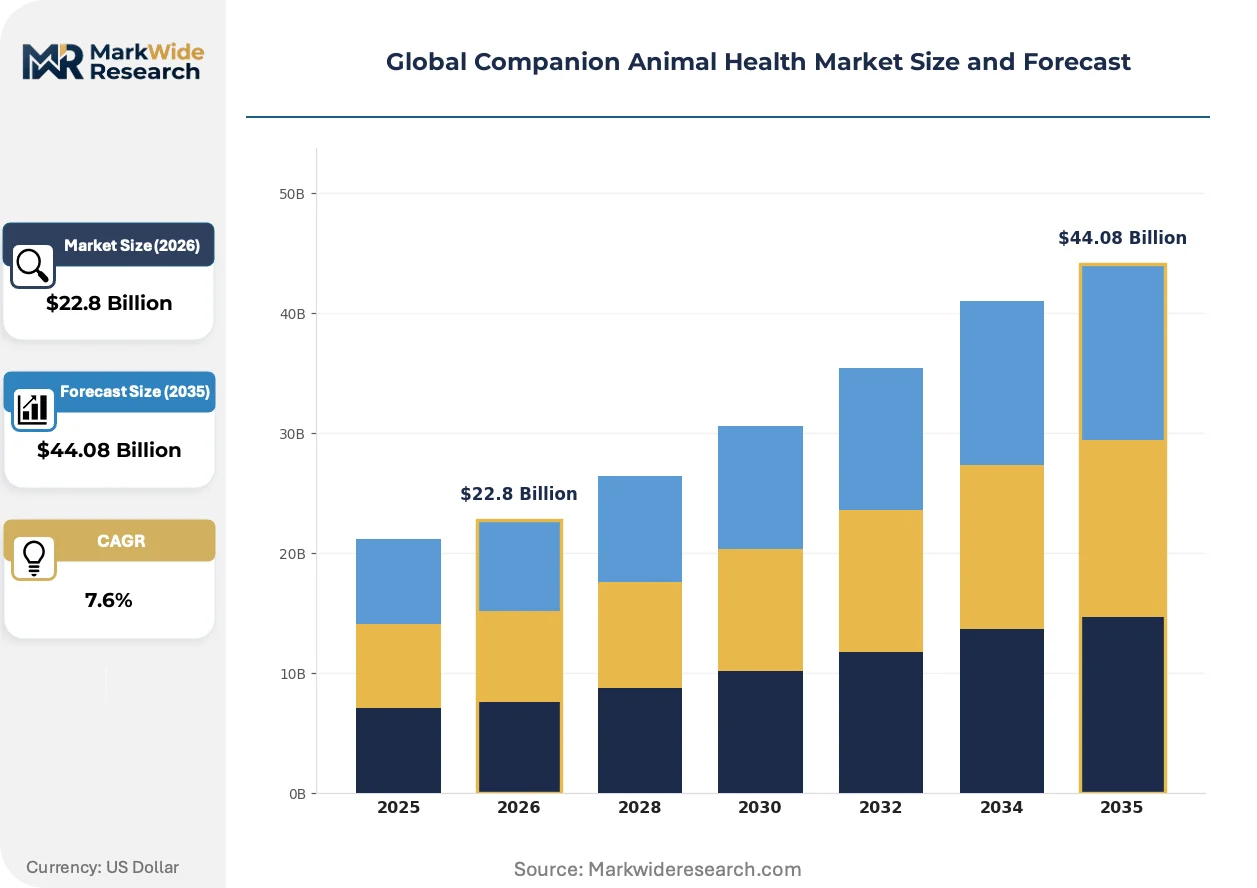
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $44.08 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Pharmaceuticals, Diagnostics, Feed Additives, Nutraceuticals, Devices Animal Type: Canine, Feline, Equine, Avian, Exotic Pets, Small Mammals End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Pharmacies Distribution Channel: Direct Sales, Wholesalers, Online Retail, Veterinary Distribution, Specialty Stores |
| Companies Covered | Zoetis, Boehringer Ingelheim, Elanco Animal Health, Merck Animal Health, Virbac, Ceva Santé Animale, Vetoquinol, Dechra Pharmaceuticals, IDEXX Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Companion Animal Health Market Shifts & Advancements
Companion animal health is experiencing simultaneous technology convergence and regulatory compression, with diagnostic decentralization and sustainability mandates rewriting product development priorities across pharmaceuticals, biologics, and nutraceuticals.
Portable polymerase chain reaction instruments are fragmenting diagnostic service delivery by enabling same-day pathogen identification in clinic settings. Small animal veterinary practices in Germany and the United States are deploying these systems to capture revenue previously directed to reference laboratories. The technology is fragmenting the traditional lab-clinic relationship and compressing price points for routine infectious disease panels.
The EU Green Deal's veterinary pharmaceutical residue limits are forcing reformulation of long-acting parasiticides used in companion animals. Manufacturers must redesign active ingredient release kinetics to meet biodegradability thresholds without compromising efficacy duration. European Union markets are responding with accelerated investment in lipid nanoparticle and implantable depot delivery technologies.
Pet owner purchasing patterns are rotating toward subscription-based preventive care bundles that combine vaccines, diagnostics, and parasiticides into monthly payment structures. United States veterinary clinic chains are displacing transactional visit models with membership programs that improve client retention metrics. This behavioral shift is most visible in metropolitan markets where millennial and Generation Z pet ownership concentrates.
Global Companion Animal Health Market Segmentation
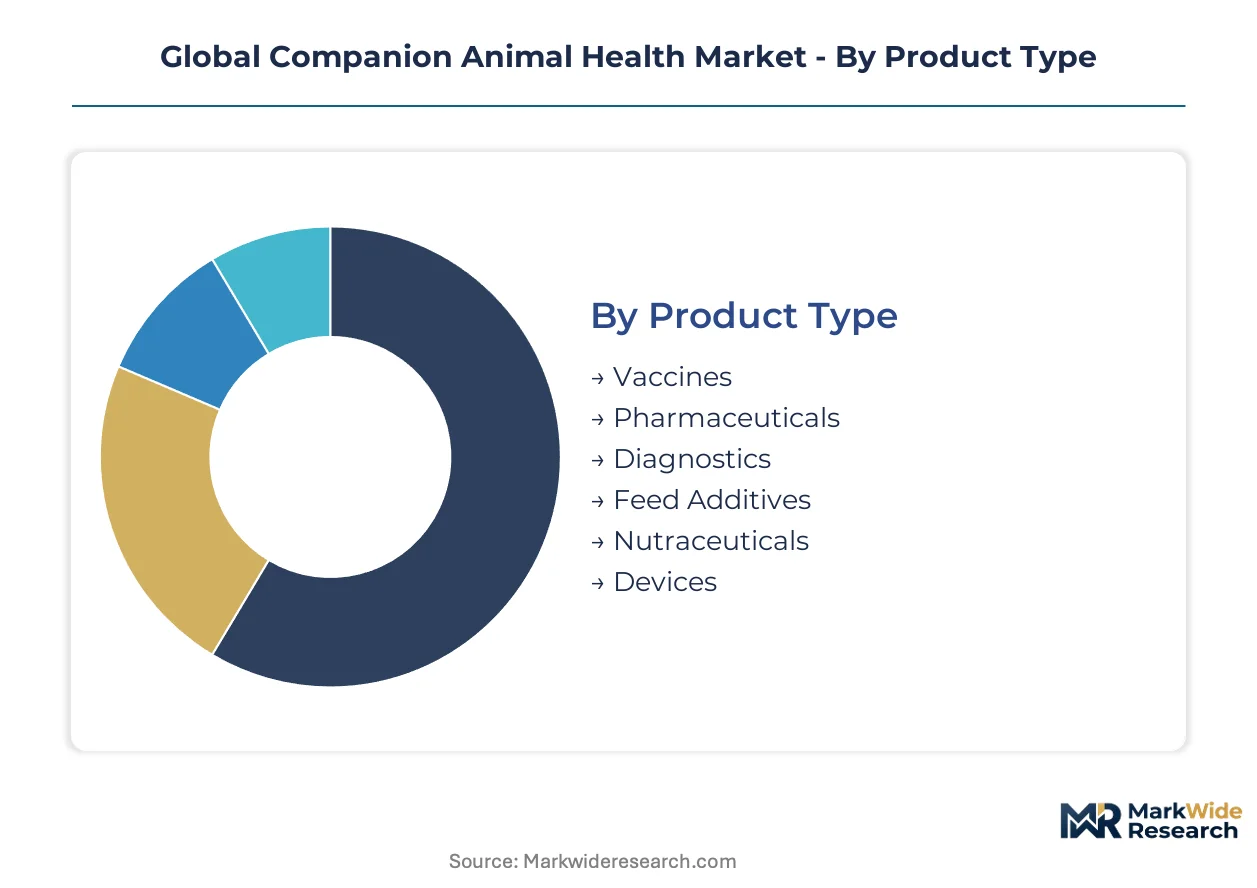
Product differentiation in companion animal health creates distinct margin architectures across therapeutic modalities. Segment-specific regulatory pathways and reimbursement dynamics determine where manufacturers concentrate R&D investment.
Product Type:
Pharmaceuticals and vaccines capture the deepest margin pools, while diagnostics commands accelerating revenue growth through platform upgrades.
- Vaccines:Live-attenuated and recombinant formulations generate recurring annual demand through booster protocols. Canine core vaccines dominate United States veterinary clinic procurement, with USDA APHIS interstate movement rules shaping distribution economics.
- Pharmaceuticals:Chemically synthesized small-molecule drugs address chronic conditions including osteoarthritis and dermatitis. FDA Center for Veterinary Medicine pharmacovigilance requirements elevate compliance costs for novel therapeutic entrants, compressing margins for mid-tier manufacturers.
- Diagnostics:Point-of-care PCR platforms displace reference-lab workflows in United States and German clinics.
- Feed Additives:Palatability enhancers and digestive enzymes target premium pet food formulations.
- Nutraceuticals:Regulatory ambiguity across Brazil and European Union markets constrains premium pricing power for supplements.
- Devices:Surgical instruments and infusion pumps serve specialized veterinary procedures.
Pharmaceuticals hold the dominant share, while diagnostics is gaining share fastest through technology substitution.
Animal Type:
Species-specific disease burdens and owner willingness-to-pay create tiered addressable markets across companion animal categories.
- Canine:Large breed orthopedic disease and vaccine protocols drive sustained pharmaceutical demand. United States urban markets concentrate spending on preventive care bundles.
- Feline:Respiratory disease portfolios remain underdeveloped relative to canine offerings, presenting white space for species-specific biologic development in German and Brazilian markets.
- Equine:Performance animal therapeutics command premium pricing through specialized veterinary channels.
- Avian:Exotic pet ownership in metropolitan United States sustains niche diagnostic demand.
- Exotic Pets:Reptile and amphibian therapeutics face limited validated treatment protocols.
- Small Mammals:Rabbit and rodent oncology services expand in European specialty clinics.
Canine segments generate the largest revenue base, though feline spending per animal is climbing the fastest as diagnostic penetration deepens.
End User:
Channel concentration shapes pricing power and service bundling opportunities across institutional buyer types.
- Veterinary Clinics:Independent and corporate practice groups in the United States are adopting subscription-based preventive care models. Monthly wellness plans displace transactional visits, locking in recurring revenue for vaccine and parasiticide portfolios.
- Animal Hospitals:24-hour emergency and specialty referral centers concentrate advanced surgical and oncology caseloads. Germany's emerging telemedicine reimbursement frameworks create channel expansion potential for remote diagnostic interpretation.
- Research Laboratories:Contract research organizations support preclinical safety studies for novel biologics.
- Pharmacies:Retail and compounding channels serve maintenance medication refills.
Veterinary clinics command the dominant procurement volume, while animal hospitals show the steepest expansion trajectory through specialty service migration.
Distribution Channel:
Channel configuration determines cold chain integrity requirements and customer access economics across geographic markets.
- Direct Sales:Manufacturer field forces serve high-volume corporate clinic chains with consolidated procurement. ANVISA's import equivalency tightening in Brazil forces foreign manufacturers toward local manufacturing partnerships, deepening direct engagement.
- Wholesalers:Full-line distributors manage inventory and credit risk for independent veterinary practices. Temperature excursion risks in tropical climates limit live-attenuated vaccine distribution reach.
- Online Retail:E-commerce penetration accelerates for nutraceuticals and non-prescription devices.
- Veterinary Distribution:Specialized logistics providers handle controlled substance and biological product cold chains.
- Specialty Stores:Pet retail chains capture over-the-counter parasiticide and supplement sales.
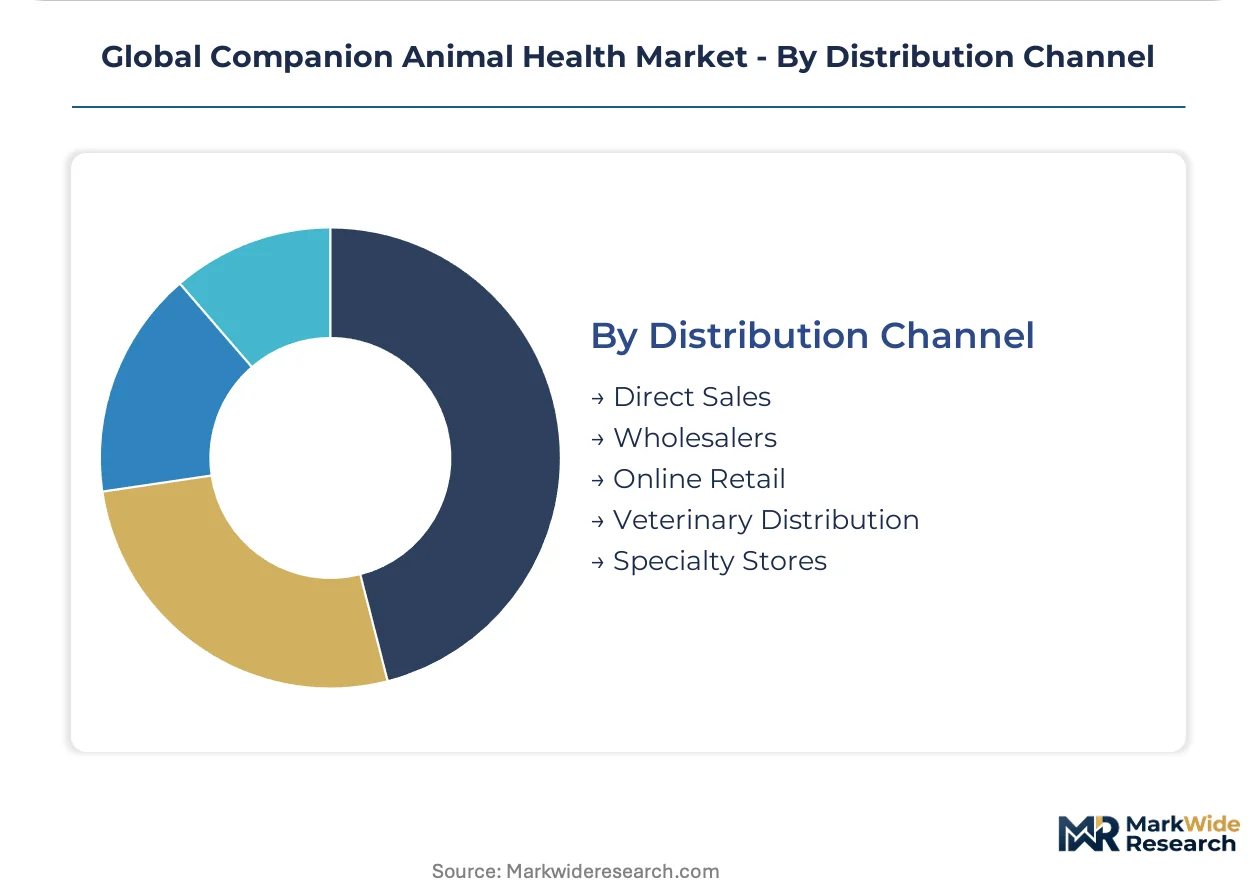
Direct sales maintains the largest share, with veterinary distribution expanding most quickly through cold chain specialization requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in biological products and active pharmaceutical ingredients concentrate manufacturing investment in markets with established regulatory infrastructure. The United States maintains a net exporter position in recombinant vaccines, while Brazil and Germany absorb substantial import volumes to meet domestic veterinary service expansion.
United States
Corporate veterinary clinic chains in metropolitan markets drive procurement consolidation for point-of-care diagnostics and preventive care bundles. FDA Center for Veterinary Medicine pharmacovigilance rules elevate compliance costs for novel therapeutic entrants, compressing margins for mid-tier manufacturers. Kansas and Iowa host concentrated biological production facilities serving North American distribution networks.
Germany
Specialty veterinary hospitals and university-affiliated referral centers generate premium demand for advanced surgical devices and oncology therapeutics. Emerging telemedicine reimbursement frameworks under national health policy discussions create channel expansion potential for remote diagnostic interpretation. Bavaria's Munich-Stuttgart corridor anchors pharmaceutical R&D clusters focused on feline respiratory disease biologics.
Brazil
Rapid urban pet ownership growth in São Paulo and Rio de Janeiro sustains import demand for vaccines and parasiticides despite local manufacturing expansion. ANVISA's tightening biological product import equivalency standards force foreign manufacturers toward domestic partnership structures. São Paulo state hosts the principal veterinary pharmaceutical formulation facilities serving Latin American export markets.
China
Domestic companion animal spending concentrates in tier-one cities where pet hospital chains proliferate diagnostic service menus. NMPA veterinary pharmaceutical registration pathways are converging toward international standards, accelerating multinational market entry timelines. Shanghai and Suzhou industrial parks attract biological manufacturing investment targeting Asia-Pacific regional supply.
United Kingdom
Independent veterinary practice networks maintain fragmented procurement patterns resistant to corporate consolidation seen in other developed markets. Post-EU regulatory divergence creates parallel compliance obligations for products accessing both UK and continental European markets. London's specialist referral hospitals concentrate demand for advanced oncology and orthopedic therapeutic modalities.
Global Companion Animal Health Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory infrastructure dimensions. The market exhibits tiered concentration where vertically integrated biological manufacturers command premium positioning against commodity pharmaceutical suppliers. Two dominant archetypes emerge: diversified human-animal health conglomerates leveraging cross-species R&D platforms, and focused veterinary specialists concentrating species-specific therapeutic depth. Competitive dynamics center on M&A activity to acquire molecular diagnostic capabilities and strategic partnerships to secure cold chain distribution in tropical markets.
Within the diversified conglomerate tier, Zoetis and Boehringer Ingelheim exemplify archetypes built upon vertically integrated biological manufacturing networks and sustained R&D intensity in species-specific portfolios. Elanco Animal Health occupies a position representing the agricultural-to-companion transition strategy through portfolio rebalancing. These entities anchor competitive positioning through captive vaccine production capacity and direct field force engagement with corporate clinic chains across the United States and Germany.
| Leading Market Players |
|---|
| Zoetis |
| Boehringer Ingelheim |
| Elanco Animal Health |
| Merck Animal Health |
| Virbac |
| Ceva Santé Animale |
| Vetoquinol |
| Dechra Pharmaceuticals |
| IDEXX Laboratories |
| Others |
Supply & Pricing Matrix
Captive biological manufacturing capacity in Kansas and Iowa anchors price floors for recombinant vaccines by limiting supplier entry and sustaining premium positioning against commodity alternatives. Scale advantages in cold-chain infrastructure compress logistics costs for incumbents while elevating barriers for mid-tier entrants lacking dedicated regulatory compliance teams.
Pricing Analysis
Corporate veterinary clinic chains anchor subscription-based pricing structures across preventive care bundles in United States metropolitan markets. Price differentiation rests on USDA APHIS certification tiers for interstate vaccine movement and brand equity in species-specific biologics. Cost compression in commodity parasiticides intensifies as Brazilian import equivalency standards force reformulation investments. Independent rural practices exhibit highest price sensitivity; specialty emergency hospitals show lowest.
Supply Chain Analysis
Active pharmaceutical ingredient synthesis concentrates in India and China, creating single-source vulnerability for recombinant protein precursors used in feline respiratory biologics. Cold chain integrity for live-attenuated vaccines draws from specialized logistics providers with tropical climate monitoring capabilities. Tariff exposure on biological imports into Brazil strains distribution economics. Downstream channels run through direct manufacturer field forces serving consolidated corporate clinic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary pathologist scarcity constrains diagnostic platform expansion faster than training program output, creating persistent capability gaps in infectious disease interpretation across United States and German markets.
For Market Incumbents: Consolidate molecular diagnostic capabilities through targeted acquisition of point-of-care PCR platform developers to defend against reference-lab workflow displacement. Deepen captive vaccine production capacity in Brazil through ANVISA-compliant local manufacturing partnerships, neutralizing import equivalency tightening as a competitive wedge. For New Entrants and Emerging Players: Differentiate on feline respiratory disease biologics where species-specific portfolios remain underdeveloped relative to canine offerings. Target German specialty veterinary hospitals through telemedicine-integrated diagnostic interpretation services, exploiting emerging reimbursement frameworks as a channel expansion angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated biological manufacturers with captive cold chain infrastructure over commodity pharmaceutical suppliers exposed to API concentration risk. Long-term viability accrues to entities controlling both manufacturing and distribution in tropical climate markets. Watch FDA pharmacovigilance enforcement intensity as an inflection indicator for compliance cost trajectories affecting mid-tier manufacturer margins.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care PCR Platform Acquisition | Captures diagnostic revenue previously directed to IDEXX Laboratories reference lab networks. |
| Brazil Local Manufacturing Partnership | Neutralizes ANVISA import equivalency barriers while deepening Latin American market penetration. |
| Feline Respiratory Biologic Development | Addresses white space in species-specific portfolios where canine offerings dominate R&D investment. |
| Subscription Preventive Care Rollout | Locks recurring revenue streams in United States urban markets displacing transactional visit models. |
| Cold Chain Infrastructure Expansion | Mitigates temperature excursion risks limiting live-attenuated vaccine distribution in tropical climates. |
Research Methodology
The analysis maps vaccines, pharmaceuticals, diagnostics, and nutraceuticals segments, each validated through veterinary clinic procurement directors, regulatory affairs specialists at biological manufacturers, and specialty hospital pathologists. Primary fieldwork combined with secondary sources including FDA Center for Veterinary Medicine pharmacovigilance filings, USDA APHIS interstate movement records, ANVISA biological product registrations, and EU Green Deal veterinary residue guidelines. Bottom-up patient visit volume estimates triangulate against top-down manufacturer revenue disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product modality, animal species, end-user channel type, and regional regulatory cluster. CAGRs derive from fitted growth curves incorporating point-of-care diagnostic adoption rates, subscription plan penetration in United States metropolitan markets, and Brazil import equivalency compliance timelines.
Material uncertainties — regulatory enforcement intensity shifts, zoonotic disease outbreak frequency, and telemedicine reimbursement policy reversals — sit outside the modeled envelope. Forecasts reflect assumptions about sustained pet ownership growth in tier-one cities and continued FDA pharmacovigilance expansion. Revision becomes warranted when FDA adverse event reporting thresholds cross enforcement intensity levels triggering manufacturer compliance cost step-functions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Zoonotic Disease Treatment Market
Animal Health
Companion Animal Ear Infection Treatment Market
Animal Health
Cattle Health Market
Animal Health
Canada Animal Health Care Market
Animal Health
Equine Healthcare Market
Animal Health
Animal Health Market
Animal Health
Rat Model Market
Animal Health
Companion Animal Healthcare Market
Animal Health
Canine Influenza Treatment Market
Animal Health
Equine Fluid Therapy Market
Animal Health
Swine Healthcare Market
Animal Health
Companion Animal Medicine Market
Animal Health
Swine Health Market
Animal Health
Global Poultry Healthcare Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
African Horse Sickness Treatment Market