
 Single-Lead ECG Monitors Market | 2026-2036
Single-Lead ECG Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Lead ECG Monitors Market Analytics
The capability gap between FDA-cleared platforms and uncertified consumer wearables is unwinding competitive boundaries in single-lead ECG monitoring. AliveCor Inc. leverages its KardiaMobile portfolio to dominate direct-to-consumer channels with prescription-grade algorithms. GE HealthCare anchors hospital procurement networks through embedded ECG workflows in enterprise imaging systems. Koninklijke Philips N.V. extends its Sleep and Respiratory Care division into ambulatory cardiac monitoring, competing on integrated diagnostic platforms rather than standalone hardware.
Single-lead ECG monitors capture electrical cardiac activity through one bipolar electrode pair, typically sampling at 300–500 Hz with bandwidth filtered to 0.05–40 Hz for diagnostic clarity; these devices transmit rhythm strips to clinicians for atrial fibrillation detection and post-ablation surveillance. Smartphone ECG Monitors occupy the fastest-expanding margin pool as patients seek medical-grade tracings without clinic visits, while Patch Monitors sustain premium pricing through multi-day adhesive wear and automated arrhythmia burden quantification. Wearable Devices face commoditization pressure from fitness-tracker incumbents lacking 510(k) clearance, concentrating profitability in regulated clinical segments.
FDA 510(k) premarket notification and CE marking under the EU MDR impose clinical validation requirements that filter out consumer-electronics entrants, while HIPAA and GDPR frameworks constrain cloud-based telemetry architectures across North American and European deployments. Japan's PMDA enforces QMS ministerial ordinances that extend approval timelines for Bluetooth-enabled devices, favoring domestic partnerships with METI-registered distributors. Stakeholders must monitor evolving FDA guidance on artificial-intelligence-enabled ECG interpretation, as algorithm-based diagnostic claims trigger de novo classification pathways that reshape product development roadmaps and competitive moats.
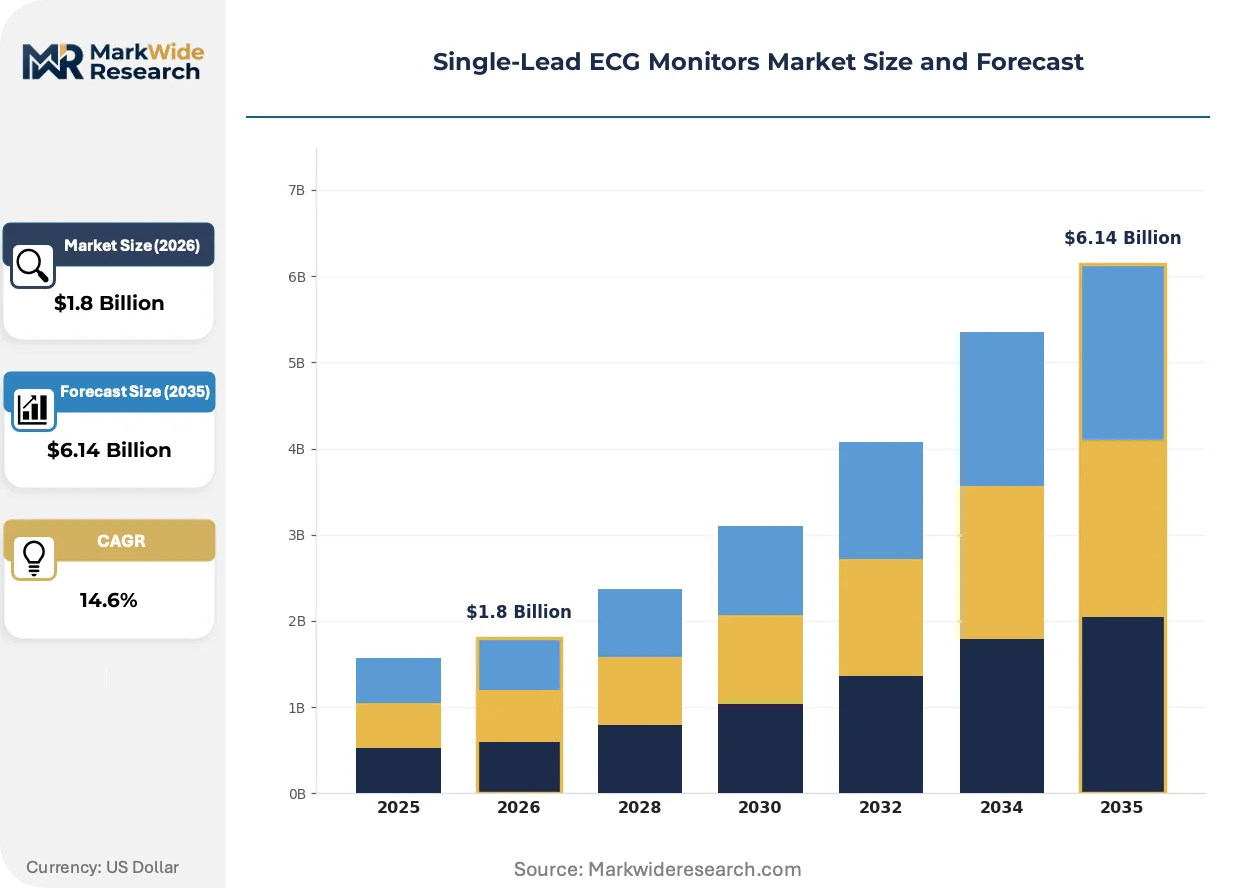
Market Dynamics
Prescription-grade algorithm deployment through smartphone-connected hardware is collapsing the historical separation between consumer wellness devices and reimbursable cardiac diagnostics, forcing reimbursement authorities to rewrite coverage determinations for remote physiologic monitoring.
Growth Catalysts
- Remote patient monitoring reimbursement:Medicare's CPT 99457-99458 codes in the United States now compensate clinicians for asynchronous ECG review, converting home monitoring from patient-paid expense to billable service line.
- Ambulatory arrhythmia detection:Post-ablation surveillance protocols at electrophysiology centers increasingly mandate 30-day patch monitoring, creating recurring hardware consumption tied to procedural volumes.
- EU MDR Class IIa pathway alignment:Harmonized clinical evidence requirements across notified bodies accelerate multi-country market entry for validated algorithm platforms.
Market Restraints
- Silver-zinc battery supply concentration:Multi-day patch monitors depend on thin-film cell manufacturing dominated by South Korean and Japanese chemical suppliers, exposing margins to raw material price volatility.
- FDA 510(k) predicate device erosion:Narrowing pools of acceptable predicate devices for novel form factors force more entrants toward de novo classification, extending timelines by 12-18 months.
- Consumer wearable substitution:Apple Watch irregular rhythm notifications capture low-risk screening demand without clinical workflow integration, compressing addressable volume for prescription-only entrants.
Strategic Opportunities
- Japan's PMDA QMS ministerial ordinance partnerships:Bluetooth-enabled device approvals favor METI-registered distributor relationships, creating defensive positioning for early entrants in Tokyo and Osaka healthcare networks.
- Artificial intelligence-enabled ECG interpretation:Algorithm-based diagnostic claims trigger FDA de novo pathways that reshape competitive moats for cloud-native telemetry architectures.
- Pharmacy channel direct distribution:CVS and Walgreens retail health clinics represent untapped points of care for same-day ECG acquisition with embedded telemedicine referral loops.
Industry Challenges
- Biomedical signal processing talent scarcity:Firmware engineers with combined expertise in analog front-end design and FDA software-as-medical-device documentation command premium compensation, constraining R&D velocity at mid-scale manufacturers.
- HIPAA-GDPR cloud architecture bifurcation:Dual-compliant telemetry infrastructure requires regionally isolated data residency, doubling hosting expenditure for vendors serving transatlantic health systems.
- Legacy EMR integration friction:HL7 FHIR connectivity gaps at community hospitals force manual rhythm strip upload workflows, degrading clinical adoption despite hardware performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Lead ECG Monitors Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smartphone ECG Monitors, Handheld ECG Monitors, Patch Monitors End User: Home Users, Hospitals, Clinics, Telemedicine Providers Technology: Wireless Technology, Smartphone Integration, Bluetooth Connectivity, Cloud-Based Platforms Distribution Channel: Online Retail, Medical Supply Stores, Direct Sales, Third-Party Distributors |
| Companies Covered | AliveCor Inc., Dimetek Digital Medical Technologies Ltd., OMRON Corporation, Zenicor Medical Systems, Tianjin Chase Sun Pharmaceutical Group, Ambisea Technology Corp., Perlong Medical Equipment Co., GE HealthCare, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Lead ECG Monitors Market Evolving Landscape
Algorithmic diagnostic autonomy is redrawing the boundary between hardware manufacturers and clinical decision-support vendors, compressing value capture toward the software layer while commoditizing electrode and analog front-end components.
Photoplethysmography-enhanced single-lead ECG fusion is displacing pure electrical signal acquisition in ambulatory monitors. Consumer electronics suppliers integrate PPG arrays with bipolar electrodes to capture pulse transit time alongside rhythm strips. Hospital procurement committees now evaluate combined optical-electrical platforms for sleep apnea and atrial fibrillation comorbidity screening, collapsing separate device categories into unified diagnostic hardware.
FDA's evolving guidance on artificial intelligence-enabled ECG interpretation is forcing algorithm developers toward locked-model premarket submissions rather than continuous learning architectures. The industrial consequence is a freeze in cloud-based model updates that previously improved sensitivity through real-world data feedback. Electrophysiology practices in the United States are responding by demanding contractual algorithm version guarantees from vendors, treating software as fixed-function hardware components.
Cardiology group purchasing organizations are consolidating remote monitoring vendor panels from twelve to three contracted suppliers, compressing switching flexibility for individual physicians. Independent electrophysiology practices in Texas and Florida are responding by forming regional buying cooperatives to retain negotiation leverage against health system aggregators. This concentration is most visible in Medicare Advantage networks where capitated cardiac care bundles incentivize standardized device deployment across employed physician networks.
Single-Lead ECG Monitors Market Segmentation
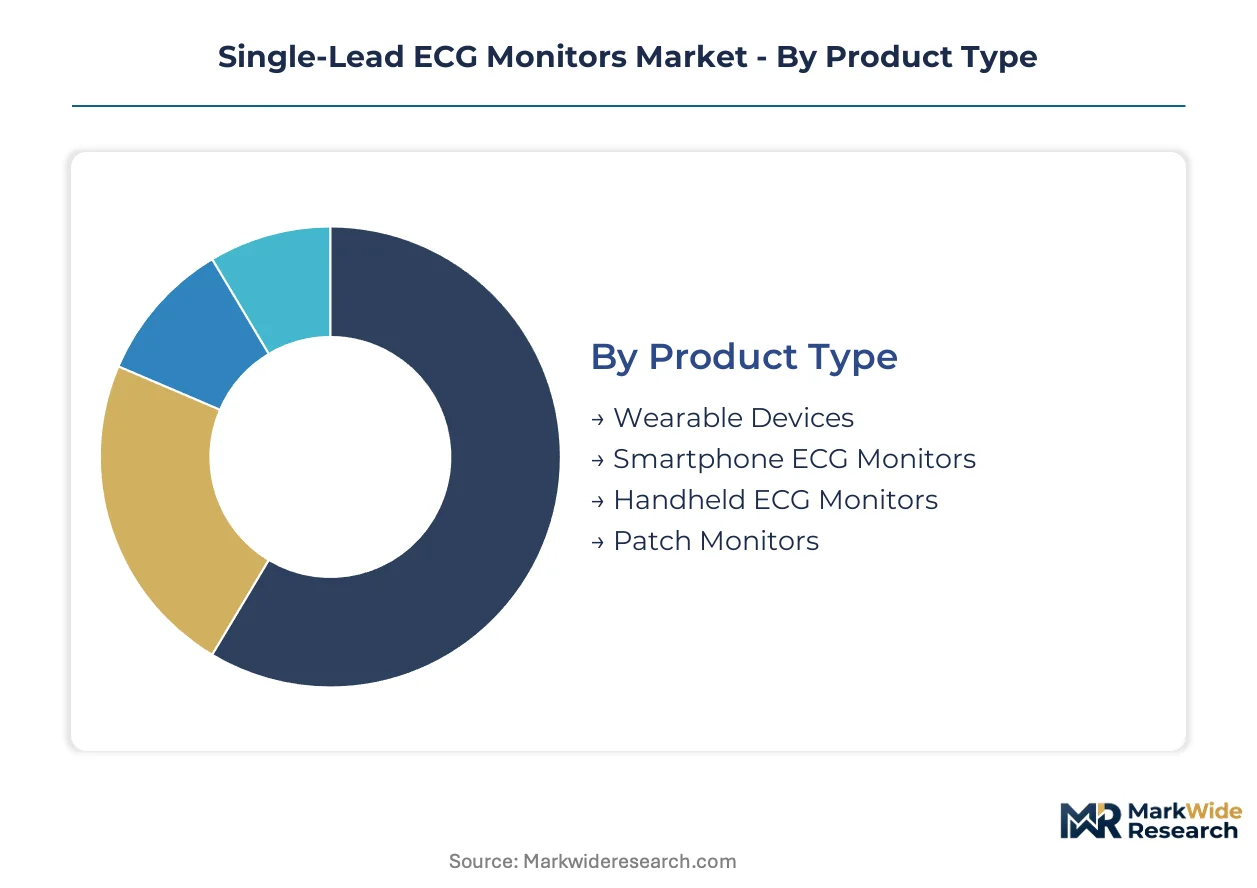
Segmentation in single-lead ECG monitoring reveals how hardware form factors, clinical workflows, and reimbursement pathways fragment addressable demand. Each dimension carries distinct margin profiles and regulatory burdens that reshape competitive positioning across direct-to-consumer and institutional channels.
Product Type:
Channel mix varies sharply: smartphone-connected hardware dominates direct-to-consumer e-commerce, while patch monitors flow through electrophysiology clinic procurement and hospital GPO contracts.
- Smartphone ECG Monitors:Compact bipolar electrode assemblies interface with iOS and Android devices via acoustic or electrical coupling, sampling at 300 Hz with FDA-cleared atrial fibrillation detection algorithms. Demand concentrates among Medicare beneficiaries in the United States seeking reimbursable home monitoring under CPT 99457-99458, though algorithm version lock-in under FDA guidance constrains continuous model improvement.
- Patch Monitors:Adhesive-integrated electrodes with silver-zinc thin-film cells enable 7-14 day continuous wear with automated arrhythmia burden quantification. Electrophysiology centers in Germany and Japan mandate 30-day post-ablation surveillance, creating recurring hardware consumption tied to procedural volumes and exposing margins to South Korean battery supply concentration.
- Wearable Devices:Wrist-worn or chest-strap form factors with photoplethysmography-electrical fusion face commoditization pressure from fitness trackers lacking 510(k) clearance.
- Handheld ECG Monitors:Standalone devices with integrated displays serve clinic-based point-of-care diagnostics where immediate rhythm interpretation outweighs smartphone dependency.
By volume, Wearable Devices leads. By growth pace, Smartphone ECG Monitors is expanding most quickly.
End User:
Cost tier separation is pronounced: home users pay out-of-pocket or through remote monitoring reimbursement, while hospitals absorb capital equipment through enterprise imaging budgets.
- Home Users:Elderly populations and chronic atrial fibrillation patients drive demand for prescription-grade hardware with embedded telemedicine referral loops. United States Medicare Advantage networks increasingly capitate cardiac care bundles, incentivizing standardized device deployment across member populations.
- Hospitals:Enterprise procurement committees evaluate ECG platforms for HL7 FHIR EMR integration, with connectivity gaps at community hospitals forcing manual workflow workarounds that degrade adoption despite hardware performance.
- Clinics:Independent electrophysiology practices in Texas and Florida form regional buying cooperatives to retain negotiation leverage against health system aggregators consolidating vendor panels.
- Telemedicine Providers:Asynchronous ECG review platforms require HIPAA-compliant cloud architectures with regionally isolated data residency, doubling hosting expenditure for transatlantic deployments.
By revenue concentration, Hospitals dominates. By margin expansion, Telemedicine Providers is climbing the fastest.
Technology:
Application context determines architecture: acute monitoring demands low-latency wireless transmission, while longitudinal surveillance prioritizes cloud storage and algorithm versioning.
- Smartphone Integration:Acoustic or electrical signal transmission to mobile devices collapses hardware cost structures but triggers FDA software-as-medical-device documentation requirements that constrain R&D velocity at mid-scale manufacturers.
- Cloud-Based Platforms:Centralized rhythm strip storage and AI-enabled interpretation face GDPR data residency mandates in Europe and HIPAA constraints in North America, fragmenting vendor infrastructure into regionally isolated deployments.
- Wireless Technology:Proprietary RF protocols in legacy hospital systems compete with Bluetooth Low Energy for ambulatory monitoring dominance.
- Bluetooth Connectivity:Japan's PMDA QMS ministerial ordinances extend approval timelines for Bluetooth-enabled devices, favoring METI-registered distributor partnerships for market entry.
By installed base, Wireless Technology leads. By strategic investment, Cloud-Based Platforms is gaining share fastest.
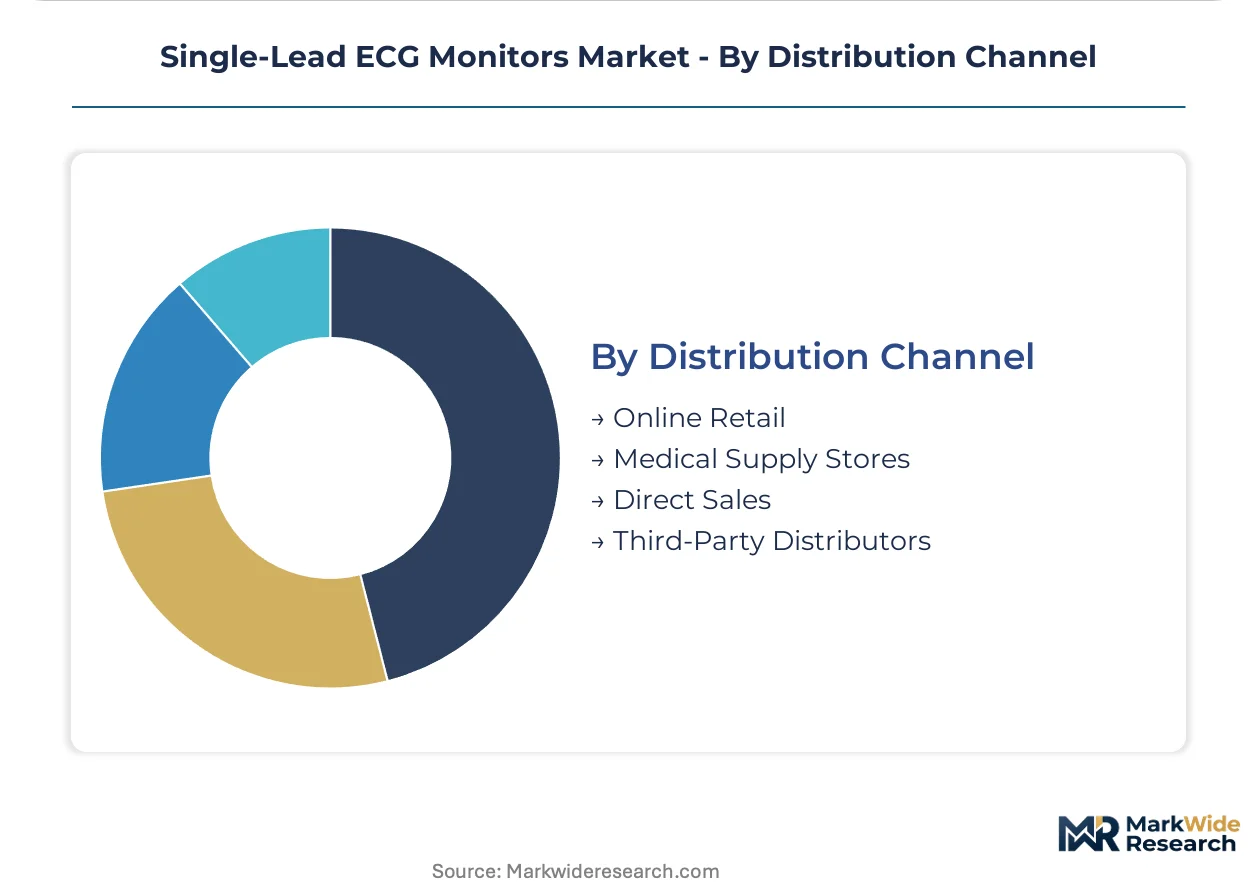
Distribution Channel:
Customer type and purchase urgency shape channel selection: acute clinical need favors medical supply stores, while planned home monitoring migrates to online retail.
- Direct Sales:Vendor field forces target electrophysiology practices and hospital cardiology departments with embedded workflow integration services, capturing premium pricing through clinical validation and algorithm version guarantees.
- Online Retail:Amazon and direct-to-consumer brand sites serve price-sensitive home users seeking same-day delivery, though FDA 510(k) clearance remains a discriminator against uncertified consumer electronics entrants.
- Medical Supply Stores:Regional distributors stock handheld and patch monitors for clinic same-day acquisition, with CVS and Walgreens retail health clinics representing untapped points of care for embedded telemedicine referral loops.
- Third-Party Distributors:METI-registered partners in Japan and specialized cardiac device distributors in Germany navigate PMDA and EU MDR compliance on behalf of foreign manufacturers.
By transaction volume, Online Retail leads. By margin retention, Direct Sales shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany, where Medicare and statutory health insurance reimbursement frameworks convert prescription-grade hardware into billable service lines, while Japanese and South Korean markets absorb premium markups through extended PMDA approval timelines and domestic distributor gatekeeping.
United States
Medicare Advantage networks capitate cardiac care bundles, incentivizing standardized device deployment across member populations in Florida and Texas. FDA 510(k) clearance requirements filter consumer electronics entrants, preserving margin pools for prescription-grade platforms. Electrophysiology practices in Houston and Miami form regional buying cooperatives to retain leverage against health system vendor panel consolidation.
Germany
Statutory health insurance funds reimburse ambulatory arrhythmia monitoring under integrated care contracts, driving patch monitor consumption in Berlin and Munich electrophysiology centers. EU MDR Class IIa harmonized requirements accelerate multi-country entry for validated algorithm platforms. Bavarian medical device clusters around Nuremberg supply silver-zinc thin-film cells to patch manufacturers, exposing margins to raw material volatility.
Japan
PMDA QMS ministerial ordinances extend Bluetooth-enabled device approval timelines, favoring METI-registered distributor partnerships for Tokyo and Osaka healthcare network entry. Aging demographics accelerate home-based cardiac monitoring adoption among chronic atrial fibrillation patients. Kansai region electrophysiology centers mandate 30-day post-ablation surveillance protocols, creating recurring hardware consumption.
South Korea
MFDS medical device regulations align with international standards while domestic chemical suppliers dominate silver-zinc battery manufacturing for multi-day patch monitors. Seoul-based health technology clusters develop photoplethysmography-enhanced ECG fusion platforms for sleep apnea comorbidity screening. National health insurance coverage for remote patient monitoring remains limited, compressing addressable volume to private pay segments.
United Kingdom
NHS long-term plan targets atrial fibrillation early detection through primary care networks, creating procurement demand in London and Manchester. MHRA post-Brexit regulatory divergence from EU MDR extends dual compliance burdens for vendors serving continental and British markets. Telemedicine providers in the Southeast require HIPAA-GDPR bifurcated cloud architectures, doubling hosting expenditure.
Single-Lead ECG Monitors Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates and prescription-grade algorithm specialists. The vendor base stratifies across three tiers: hospital procurement network anchors with embedded ECG workflows, direct-to-consumer platforms with FDA-cleared diagnostic claims, and component suppliers for electrophysiology clinic patch monitors. Strategic moves center on algorithm version lock-in under evolving FDA guidance and regional distributor partnerships for PMDA compliance.
Among diversified health technology conglomerates, GE HealthCare and Koninklijke Philips N.V. occupy positions anchoring hospital enterprise imaging procurement networks. AliveCor Inc. exemplifies the direct-to-consumer prescription-grade archetype, leveraging smartphone-connected hardware to capture reimbursable home monitoring demand. These three companies represent the dominant competitive positioning vectors: enterprise workflow integration, regulatory-cleared algorithm deployment, and ambulatory diagnostic platform extension.
| Leading Market Players |
|---|
| AliveCor Inc. |
| Dimetek Digital Medical Technologies Ltd. |
| OMRON Corporation |
| Zenicor Medical Systems |
| Tianjin Chase Sun Pharmaceutical Group |
| Ambisea Technology Corp. |
| Perlong Medical Equipment Co. |
| GE HealthCare |
| Koninklijke Philips N.V. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for silver-zinc thin-film cells lock in both electrode supply security and predictable input costs for patch monitor manufacturers serving German and Japanese electrophysiology networks. These arrangements insulate margins from Korean chemical supplier price volatility while constraining flexibility to pivot toward alternative battery chemistries.
Pricing Analysis
Customization-premium spreads separate configured-to-order patch monitors with embedded algorithm version guarantees from standard smartphone-connected hardware sold through online retail. Three-tier pricing structure across prescription-grade, clinical-validated, and consumer wellness tiers reflects FDA 510(k) clearance status and HL7 FHIR integration depth. Cost compression in the consumer wellness tier intensifies because Apple Watch irregular rhythm notifications capture low-risk screening demand without clinical workflow integration. Telemedicine providers exhibit lowest price sensitivity due to reimbursable CPT code coverage, while direct-to-consumer home users face highest out-of-pocket price elasticity.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for silicon MEMS foundries supplying analog front-end components to US-based device assemblers. Manufacturing concentration centers on South Korea and Japan for silver-zinc battery cells, Taiwan for semiconductor fabrication, and Germany for medical-grade electrode substrates. Raw material dependencies rest on lithium carbonate for battery electrolytes, high-purity silicon for signal processing chips, and conductive polymers for adhesive electrodes. Single-source vulnerability in South Korean chemical supply exposes patch monitor margins to export restriction risk. Distribution runs through METI-registered partners in Japan, specialized cardiac device distributors in Germany, and GPO-contracted channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-lead ECG monitoring is approaching a platform-economics inflection as algorithm developers and hardware manufacturers contest value capture through HL7 FHIR interoperability standards that determine EMR integration depth.
For Market Incumbents: Compound defensive positioning through algorithm version lock-in under evolving FDA guidance on AI-enabled ECG interpretation, while securing backward integration into silver-zinc battery cell supply through Korean chemical partnerships. Consumer wearable substitution from uncertified fitness trackers threatens prescription-grade volume; counter this by embedding telemedicine referral loops into retail pharmacy distribution at CVS and Walgreens. For New Entrants and Emerging Players: Lead with pharmacy channel direct distribution as the most penetrable go-to-market angle, targeting same-day ECG acquisition workflows at retail health clinics in Texas and Florida. Independent electrophysiology practices forming regional buying cooperatives represent underserved white-space demand. Cloud-native telemetry architectures with HIPAA-GDPR bifurcated compliance offer differentiation against legacy hospital procurement network anchors. For Investors and Strategic Acquirers: Firmware engineering boutiques with combined analog front-end design and FDA software-as-medical-device documentation expertise represent the highest-conviction acquisition target archetype. Long-term viability hinges on regulatory-cleared algorithm deployment rather than hardware commoditization. Signal to watch: FDA de novo classification volume for novel AI-enabled diagnostic claims as inflection indicator for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Classification Pathway | Accelerates market entry for AI-enabled ECG interpretation algorithms beyond predicate device constraints. |
| Hospital System Partnership | Secures GPO panel positioning against vendor consolidation from twelve to three contracted suppliers. |
| Software Companion Development | Enables locked-model premarket submissions that satisfy evolving FDA guidance on continuous learning architectures. |
| CE Marking Pathway | Unlocks EU MDR Class IIa harmonized entry for multi-country algorithm platform deployment. |
| Reimbursement Strategy | Converts Medicare CPT 99457-99458 codes into sustainable revenue streams for asynchronous ECG review. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EU MDR notified body guidance documents, and CMS Medicare reimbursement schedules preceded structured interviews with electrophysiology practice administrators, hospital GPO contracts managers, biomedical firmware engineers, and METI-registered medical device distributors. Primary fieldwork combined with secondary validation from PMDA ministerial ordinance filings and silver-zinc battery supply chain disclosures. Bottom-up demand modeling across product type, end user, and technology segments triangulated against top-down market sizing from regulatory filing revenue proxies.
Variance decomposition across the projection horizon isolates volume drivers from price mix effects within smartphone ECG monitor, patch monitor, and wearable device categories. Segmentation dimensions modeled include hardware form factor, clinical workflow integration depth, reimbursement pathway eligibility, and regional regulatory cluster. CAGRs derive from procedural volume forecasts at electrophysiology centers, Medicare Advantage capitation trends, and algorithm platform adoption curves. Industry-specific inputs incorporate post-ablation surveillance protocol mandates and Bluetooth-enabled device approval timeline differentials by notified body.
Forecasts assume regulatory continuity in FDA 510(k) predicate device acceptability and EU MDR Class IIa harmonized requirements; material policy shifts toward de novo classification expansion or MDR clinical evidence escalation would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asthma Spacers Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market
Medical Devices
Global Cardiopulmonary Resuscitation Device Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Global Medical Device Security Market
Medical Devices
Global Angiographic Catheters Market
Medical Devices
South Korea Ophthalmic Devices Market
Medical Devices
Spine Bone Stimulators Market
Medical Devices
Pectus Bar System Market
Medical Devices
Microscope Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
Syndesmosis Repair System Market