
 Bio Filter Market | 2026-2036
Bio Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Bio Filter Market Intelligence
The increasing focus on industrial effluent treatment, particularly from chemical manufacturing units and food processing plants, is rebalancing the market away from its traditional municipal-only focus. Suez SA leverages its extensive portfolio to serve both municipal and industrial clients. Veolia Water Technologies differentiates through its specialized solutions for complex industrial wastewater, while Biorem Inc. occupies a specific niche with its focus on air pollution control biofilters.
A bio filter is a pollution control device using a biological medium to treat contaminated air or water. It operates by passing the contaminant stream through a bed of material, such as compost or plastic media, where microorganisms metabolize the pollutants. Wastewater treatment applications continue to dominate volume, but air purification is a high-margin growth area. Submerged biofilters represent a mature product type, while hybrid biofilters are gaining traction for their operational flexibility and efficiency in varied load conditions.
Regulations from bodies like the US EPA and compliance with Europe's REACH directive set stringent performance criteria for bio filter media and discharged effluents. In China, national GB standards for water and air quality are compelling industrial facilities to upgrade their treatment systems. Future competitive advantage will hinge on developing systems that meet evolving contaminant removal targets with lower energy and maintenance costs.
Market Dynamics
The convergence of stringent environmental regulations and the diversification of applications beyond municipal wastewater is the central force acting on the bio filter market. Mandates like China's GB standards and Europe's Urban Waste Water Treatment Directive create a non-negotiable demand floor for compliance-driven investments.
Growth Catalysts
- Regulatory Enforcement:The push for compliance with regulations such as the EU's Urban Waste Water Treatment Directive compels municipalities to upgrade or install advanced biological treatment systems, directly stimulating demand for new bio filter units.
- Industrial Effluent Control:A heightened focus on treating wastewater from chemical manufacturing and food processing industries creates a significant demand stream, as these sectors face pressure to reduce their environmental impact and comply with discharge limits.
- National Policy Initiatives:China's national water quality improvement plans and its dual carbon goals are creating a concentrated wave of investment in water treatment infrastructure, making it a pivotal geography for bio filter deployment.
Market Restraints
- High Capital Outlay:The substantial upfront investment required for the construction and installation of large-scale bio filter systems, particularly submerged configurations, can be a significant barrier for smaller municipalities and industrial operators.
- Process Sensitivity:The biological nature of the filtration process makes it susceptible to performance degradation from sudden changes in temperature, pH, or contaminant loads, requiring stable operating conditions to maintain efficiency.
- Alternative Technologies:The availability of competing water treatment technologies, such as membrane bioreactors (MBRs), presents a substitution threat in applications where higher purification standards or smaller physical footprints are prioritized.
Strategic Opportunities
- Air Pollution Control:Expanding into high-margin air purification applications, especially for the treatment of volatile organic compounds (VOCs) and odors from industrial facilities, represents a key avenue for market diversification and value creation.
- Hybrid System Development:Innovating with hybrid biofilters, which combine different media types and operational principles, offers a path to capture demand for more flexible and efficient systems capable of handling variable load conditions. *Emerging Market Infrastructure: Targeting infrastructure projects in rapidly industrializing economies in Southeast Asia and Latin America, where environmental regulations are tightening, provides new geographic growth frontiers for established vendors.
Industry Challenges
- Operational Skill Gaps:The effective management of a bio filter's microbial ecosystem requires specialized knowledge, and a shortage of trained operators can lead to suboptimal performance, system downtime, and increased long-term operational costs.
- Certification and Compliance Timelines:Navigating the complex and often lengthy process of achieving performance certification for new filter media and systems against standards set by bodies like the US EPA can delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio Filter Market |
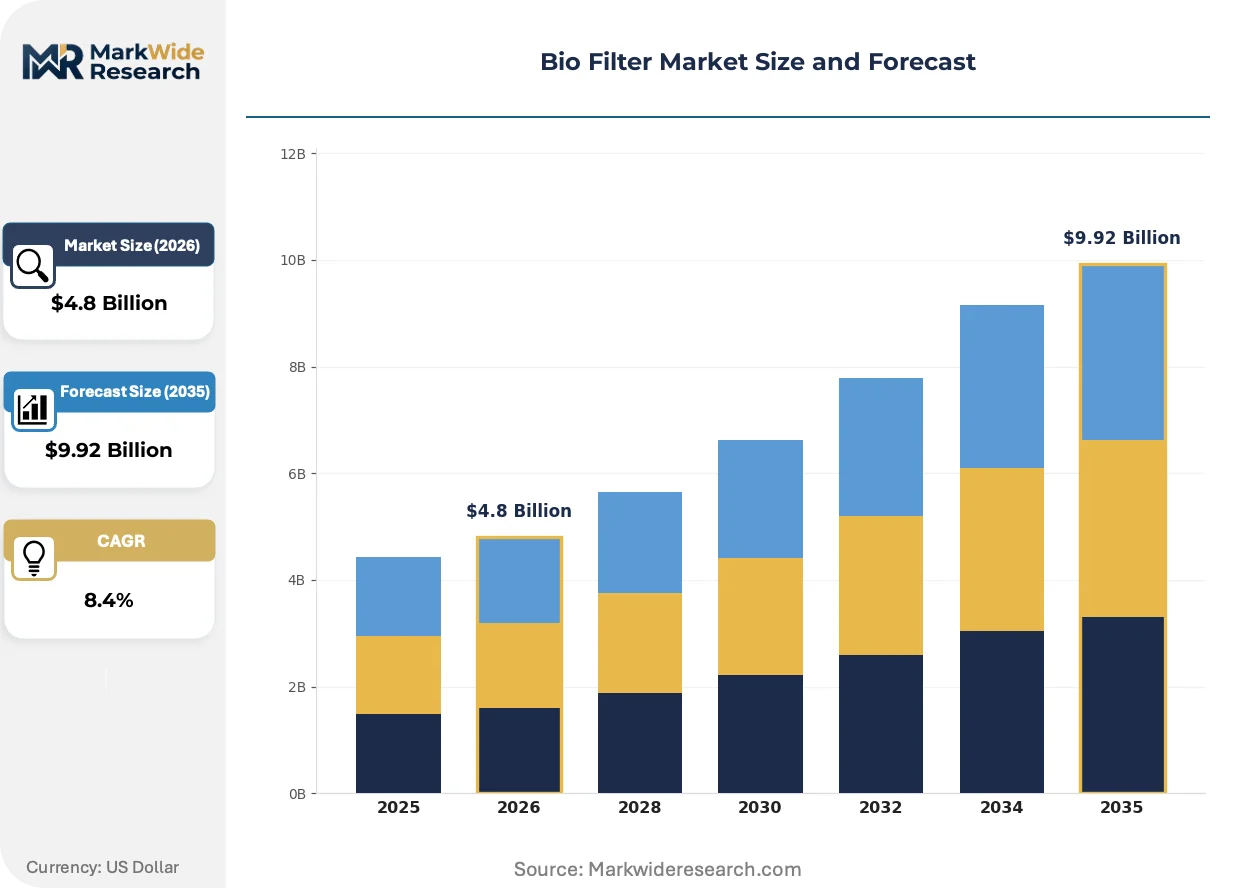
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trickling Biofilter, Submerged Biofilter, Floating Biofilter, Hybrid Biofilter Technology: Activated Carbon, Membrane, Biodegradation, Adsorption, Bio-oxidation Application: Wastewater Treatment, Air Purification, Industrial Effluents, Agricultural Runoff End User: Municipal Authorities, Food Processing Plants, Chemical Manufacturing Units, Textile Facilities |
| Companies Covered | Biorem Inc., Suez SA, Veolia Water Technologies, BioAir Solutions, LLC, Dürr AG, Pentair plc, Evoqua Water Technologies LLC, Pentair Aquatic Eco-Systems, Xylem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio Filter Market Strategic Shifts & Innovations
The development of specialized media and intelligent process controls is reshaping the market. This evolution moves beyond basic contaminant removal, focusing on energy efficiency, operational autonomy, and targeted pollutant degradation to meet more demanding regulatory and economic requirements.
Hybrid biofilters combine elements from different biological treatment processes, such as submerged and trickling filters, into a single unit. Industrial and municipal operators with highly variable influent loads are driving adoption. The superior adaptability of these systems is consolidating their role as the technology of choice for facilities needing to treat complex, fluctuating waste streams with greater efficiency.
China's stringent GB standards for water and air quality are a powerful regulatory driver. This policy directly compels industrial facilities, particularly in the chemical, textile, and pharmaceutical sectors, to invest in advanced treatment technologies. The segment most affected is older manufacturing plants, which are now forced to retrofit their systems with modern biofilters capable of meeting new contaminant removal targets.
A notable behavioral shift is occurring as buyers move from a pure capital expenditure focus to evaluating the total cost of ownership. The traditional equipment-sale model is being challenged by a preference for systems that guarantee lower energy consumption and reduced maintenance over the asset's lifecycle. This trend is most pronounced in Europe, where high energy costs and policy frameworks like the EU Green Deal make long-term operational efficiency a primary procurement consideration.
Bio Filter Market Segmentation
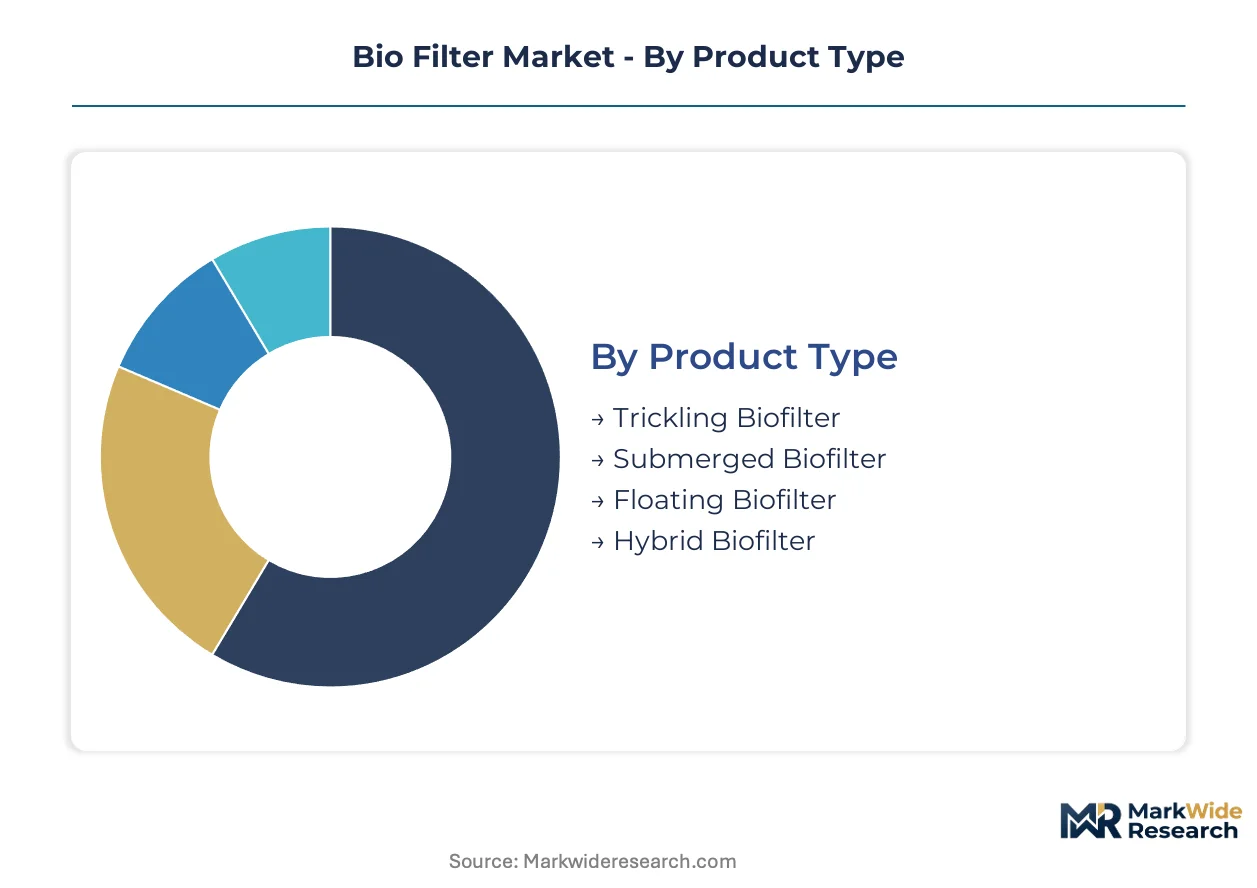
The bio filter market exhibits diverse segmentation driven by evolving treatment requirements and technological advancements. Understanding these distinct categories provides clarity on where investment flows and innovation concentrates. This analysis highlights the varying capital expenditures and operational complexities across different bio filter solutions.
Product Type:
Submerged biofilters require substantial upfront investment due to the civil engineering work and tank construction involved.
- Trickling Biofilter:These systems utilize a fixed media bed, with wastewater trickling over it to enable biofilm formation for pollutant degradation.
- Submerged Biofilter:These filters fully immerse the media in the wastewater stream, fostering high biological activity for efficient contaminant removal. Demand concentrates in larger municipal facilities and industrial applications requiring compact footprints, driven by stringent discharge limits in Europe.
- Floating Biofilter:These systems feature buoyant media that float on the water surface, primarily used for nutrient removal in ponds or lakes.
- Hybrid Biofilter:These advanced systems integrate elements from different biological treatment processes, like submerged and trickling filters, to optimize operational flexibility. Their superior adaptability to variable load conditions drives adoption in industrial facilities in China with fluctuating effluent quality.
Most installed capacity flows through Submerged Biofilter. Expansion is steepest in Hybrid Biofilter.
Technology:
Bio filter technologies are increasingly tailored to specific contaminant profiles and regulatory requirements.
- Activated Carbon:This technology uses activated carbon media to adsorb organic pollutants and odors, often in conjunction with biological treatment for enhanced removal. It is frequently employed in air purification applications targeting volatile organic compounds (VOCs).
- Membrane:Membrane filtration technologies are often integrated with biological processes to achieve higher effluent quality, particularly for nutrient removal and pathogen inactivation. These systems are gaining traction in advanced wastewater treatment plants requiring ultrapure water for reuse.
- Biodegradation:This core biological process involves microorganisms metabolizing organic pollutants present in air or water streams.
- Adsorption:Adsorption involves pollutants physically adhering to the surface of a solid medium, a process often preceding or complementing biological degradation.
- Bio-oxidation:This technology uses microorganisms to oxidize specific inorganic or organic compounds, transforming them into less harmful substances.
Biodegradation forms the foundational mechanism for most bio filter systems. Activated Carbon technology secures a significant share in air purification segments.
Application:
Regulatory mandates from bodies like the US EPA and Europe's REACH directive drive demand across various bio filter applications.
- Wastewater Treatment:This application segment dominates the bio filter market, addressing pollutants from municipal and industrial sources to meet discharge standards. Significant investment flows into upgrading municipal wastewater infrastructure in line with the EU's Urban Waste Water Treatment Directive.
- Air Purification:This high-margin application focuses on removing volatile organic compounds (VOCs), odors, and hazardous air pollutants from industrial emissions. Demand is particularly strong in chemical manufacturing units in China, driven by national GB standards.
- Industrial Effluents:This category specifically targets complex and often toxic wastewater discharged from manufacturing processes, requiring specialized bio filter designs.
- Agricultural Runoff:Bio filters in this application mitigate nutrient pollution and pesticides from agricultural drainage before they enter natural water bodies.
Wastewater Treatment commands the largest volume of bio filter deployments. Air Purification applications are expanding most quickly due to stringent industrial emission controls.
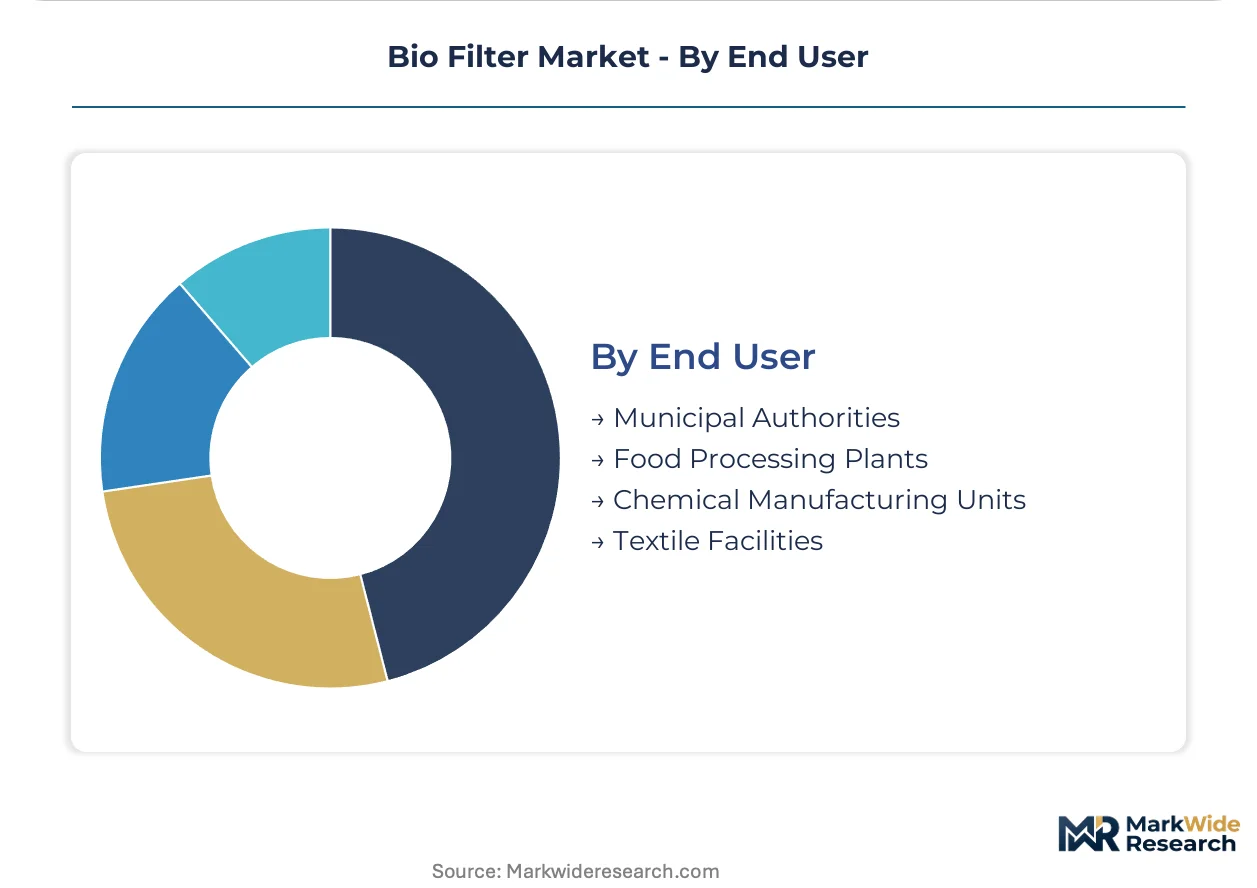
End User:
The diversity of end-user requirements necessitates specialized bio filter solutions tailored to specific contaminant types and volumes.
- Municipal Authorities:These entities represent the largest end-user segment, deploying bio filters for treating urban sewage and ensuring compliance with public health and environmental regulations. Upgrades are ongoing in many European cities to enhance treatment capacity.
- Food Processing Plants:Bio filters manage organic-rich wastewater and odor emissions from operations like dairies, breweries, and meat processing facilities.
- Chemical Manufacturing Units:These facilities require robust bio filter systems to treat complex and often hazardous industrial effluents, including VOCs and specific organic compounds. Demand is intensifying in China due to its national water quality improvement initiatives and dual carbon goals.
- Textile Facilities:Bio filters address colored wastewater and chemical pollutants generated during dyeing and finishing processes in textile manufacturing.
Municipal Authorities consistently drive the largest volume of bio filter installations. Chemical Manufacturing Units are increasingly investing in advanced bio filter systems to meet tightening discharge regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial facilities in China anchor significant bio filter demand, driven by national water quality improvement plans and stringent GB standards. Europe also mandates substantial investments for municipal wastewater treatment system upgrades. This global push for environmental compliance shapes regional market dynamics.
China
China's national water quality improvement plans and dual carbon goals drive substantial bio filter investments. GB standards compel industrial facilities to upgrade systems. Chemical manufacturing units in the Yangtze River Delta are retrofitting with modern biofilters. This ensures compliance with new contaminant removal targets.
Germany
Germany mandates significant bio filter investments for municipal wastewater treatment, aligning with the EU's Urban Waste Water Treatment Directive. Industrial facilities face pressure to reduce environmental impact under the EU Green Deal. North Rhine-Westphalia cities are upgrading treatment capacity to meet stringent discharge limits. This addresses high energy costs through efficient systems.
United States
United States environmental regulations from the US EPA compel demand for advanced bio filter systems. Industrial effluent treatment, especially for chemical manufacturing, drives significant investment. California, with its stringent environmental laws, leads in adopting air purification biofilters. Northeast municipalities are also upgrading wastewater infrastructure.
India
India's rapid industrialization and tightening environmental regulations create new growth frontiers for bio filter deployment. National policies encourage advanced treatment technologies in industrial zones. Infrastructure projects in Maharashtra and Gujarat are integrating modern biofilter systems. This addresses growing industrial and municipal wastewater challenges.
France
France prioritizes municipal wastewater treatment upgrades to comply with the EU's Urban Waste Water Treatment Directive. Industrial clients also leverage biofilters for effluent control. Suez SA, headquartered in France, serves both municipal and industrial sectors. Cities within the Île-de-France region are enhancing treatment capacity.
Bio Filter Market Key Industry Players
Portfolio diversification dominates the current landscape, as companies expand their offerings beyond traditional municipal applications. The market exhibits a tiered structure, with large diversified players, specialized solution providers, and niche technology firms. Large entities leverage extensive portfolios to serve varied client bases. Mid-sized specialists differentiate through targeted solutions for complex industrial wastewater. Technology innovation and geographic expansion into emerging markets are also prevalent competitive moves.
Specialists focusing on specific market segments include Biorem Inc., which occupies a niche in air pollution control biofilters. Large European-based conglomerates, such as Suez SA and Veolia Water Technologies, exemplify diversified players. Suez SA leverages its extensive portfolio to serve both municipal and industrial clients. Veolia Water Technologies differentiates through specialized solutions for complex industrial wastewater applications. These firms anchor strategies for both broad market coverage and targeted problem-solving.
| Leading Market Players |
|---|
| Biorem Inc. |
| Suez SA |
| Veolia Water Technologies |
| BioAir Solutions, LLC |
| Dürr AG |
| Pentair plc |
| Evoqua Water Technologies LLC |
| Pentair Aquatic Eco-Systems |
| Xylem Inc. |
| Others |
Cost & Logistics Intelligence
Hybrid biofilter development, integrating diverse treatment processes, simultaneously reshapes cost economics and concentrates specialized media suppliers. This evolution impacts project-based pricing and global material sourcing.
Pricing Analysis
Input-cost pass-through remains a critical factor for bio filter system integrators, influencing project-based pricing models. Price differentiation stems from the level of customization required for complex industrial effluents and the performance certification against standards like US EPA or China's GB. Pricing softness affects standard submerged biofilters due to competing technologies, while hybrid systems command a premium for their flexibility. Smaller municipalities and industrial operators exhibit higher price sensitivity, contrasting with large chemical manufacturing units prioritizing long-term operational efficiency.
Supply Chain Analysis
Dual-sourcing requirements are emerging for specialized bio filter media, driven by demand for performance consistency across diverse applications. Geographic supply concentration for advanced media and control components centers on China and European manufacturers. Raw material dependencies include specialized plastic media for hybrid systems and activated carbon for air purification applications. Single-source vulnerability for proprietary microbial cultures poses a supply chain risk for niche providers. Distribution runs through a mix of direct sales from large conglomerates and specialized engineering firms for complex industrial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bio filter market functions as a regulatory compounder, with demand significantly amplified by mandates like the EU's Urban Waste Water Treatment Directive. This directive compels extensive municipal infrastructure upgrades, ensuring sustained market expansion.
For Market Incumbents: Cement existing market leadership by diversifying portfolios to serve both municipal and complex industrial clients, leveraging extensive technical expertise. Invest in R&D for advanced hybrid biofilters and specialized media to counter the threat from alternative technologies like MBRs. Prioritize certification investments against stringent performance criteria from bodies like the US EPA and China's GB standards. Expand geographic reach into rapidly industrializing economies, securing long-term contracts for municipal infrastructure projects.
For New Entrants and Emerging Players: Hybrid system development offers a technology-first wedge into the bio filter market, targeting industrial facilities with variable load conditions. Focus on high-margin air purification applications, particularly for VOCs from chemical manufacturing units. The most penetrable segment remains older manufacturing plants in China, compelled to retrofit systems by GB standards. Go-to-market strategies should emphasize systems guaranteeing lower energy consumption and reduced maintenance over the asset's lifecycle.
For Investors and Strategic Acquirers: Roll-up economics work for specialized bio filter technology providers because of fragmented expertise across niche applications and geographies. The long-term viability of this market is anchored in sustained global regulatory enforcement and industrial expansion in emerging economies. Acquisition targets include mid-sized firms with proprietary media or specialized solutions for complex industrial wastewater. The signal to watch is the accelerated implementation of stringent water and air quality standards in Southeast Asia and Latin America.
| Strategic Initiative | Industry Significance |
|---|---|
| Specialized Media R&D | Enhances contaminant removal efficiency for complex industrial effluents, meeting evolving US EPA and REACH criteria. |
| Hybrid System Integration | Provides operational flexibility for industrial facilities with fluctuating waste streams, reducing energy costs. |
| Geographic Expansion (China/SEA) | Captures demand from national water quality improvement plans and tightening environmental regulations. |
| Full-Service O&M Contracts | Addresses operational skill gaps for municipal authorities, ensuring optimal bio filter performance. |
| Digital Process Control Development | Improves system autonomy and reduces maintenance costs for end-users, aligning with TCO focus. |
Research Approach
Direct dialogue with municipal water treatment managers, industrial plant engineers, bio filter system manufacturers, and environmental consultants informed the qualitative grounding. This primary research was validated against extensive secondary data, including US EPA reports, EU Urban Waste Water Treatment Directive documents, and China's GB standards. The analysis employed both bottom-up market sizing and top-down validation, integrating corporate sustainability reports for comprehensive insight.
The quantitative model produced granular volume and value projections across the analysis window, segmented by product type, technology, application, end-user, and regional regulatory stringency. Compound annual growth rates were derived from historical data and projected growth drivers, including anticipated industrial expansion. Key forecast inputs included projected municipal wastewater volumes and evolving industrial emission targets under national policies.
The model holds under current regulatory and technological trajectories; deviation in environmental policy enforcement or rapid adoption of disruptive alternative technologies would shift projections. Forecasts reflect documented assumptions regarding market dynamics and technological evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Tertiary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
Agricultural Wastewater Treatment Market
Water and Wastewater Treatment
Latin America Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Mobile Wastewater Treatment Plant Market
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
Water Testing Meter Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Ecological Wastewater Treatment Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Global Vertical Sewage Pumps Market
Water and Wastewater Treatment
Backwash Pre-Filters Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Wastewater Clarifier Market