
 Backwash Pre-Filters Market | 2026-2036
Backwash Pre-Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Backwash Pre-Filters Market Insights
Skilled filtration technician availability is rotating toward electronic and hydraulic system competencies, constraining deployment timelines for legacy manual installations. Pentair plc leverages its captive supply of pleated media to sustain margin pools in municipal contracts. Eaton Corporation plc anchors North American industrial demand through specialized high-pressure screen configurations. Amiad Water Systems Ltd. competes aggressively in agricultural irrigation with disc technology optimized for variable water quality.
Backwash pre-filters are self-cleaning separation devices that remove suspended solids from fluid streams using screen, disc, or media elements rated from 10 to 1500 microns, with cleaning cycles triggered by differential pressure or timed intervals. Their primary purpose is protecting downstream membranes, pumps, and process equipment in water-intensive operations while minimizing consumable waste. Screen and disc configurations dominate municipal and agricultural installations where debris loads are predictable and backwash frequency remains moderate. Electronic technology represents the fastest-expanding segment as facilities prioritize remote monitoring and reduced labor intervention. Pleated and deep bed systems occupy premium positions in chemical plants and power generation where sub-micron retention and extended service intervals justify higher capital outlay.
The EPA enforces Maximum Contaminant Level standards that compel US water treatment facilities to upgrade pre-filtration stages ahead of membrane bioreactor expansions. China's MEE implements increasingly stringent GB standards for industrial wastewater reuse, forcing steel and textile manufacturers toward automatic backwash architectures. ISO 9001 and NSF/ANSI 61 certifications function as baseline market access requirements across European and North American procurement frameworks. Stakeholders must monitor regulatory divergence between electronic actuation mandates in developed markets and cost-driven manual system persistence in emerging economies.
Market Dynamics
The transition from manual to electronic actuation systems constitutes the dominant structural force reshaping competitive positioning, as facilities prioritize remote monitoring capabilities and labor reduction over legacy mechanical architectures.
Growth Catalysts
- EPA Maximum Contaminant Level enforcement:US water treatment facilities must upgrade pre-filtration stages ahead of membrane bioreactor expansions, mandating automatic backwash architectures in municipal procurement.
- Steel and chemical plant retrofits:China's industrial corridor cities are retrofitting existing filtration infrastructure to comply with tightening MEE GB standards for wastewater reuse.
- Variable frequency drive integration:Pump protection requirements in agricultural irrigation are accelerating specification of screen and disc configurations with differential pressure triggers.
Market Restraints
- Stainless steel screen cost volatility:Raw material price swings for 316L and 904L alloys compress margin pools for manufacturers serving price-sensitive municipal segments.
- Skilled technician scarcity:The rotation toward electronic and hydraulic system competencies constrains deployment timelines for legacy manual installations in emerging economies.
- Membrane bioreactor pre-treatment standardization:Divergent specifications between membrane OEMs create procurement friction and extend engineering review cycles.
Strategic Opportunities
- IoT-enabled predictive maintenance:Convergence of electronic actuation with cloud analytics creates white space for service revenue models in industrial water treatment.
- Brazilian agricultural expansion:Variable water quality conditions in center-pivot irrigation districts favor disc technology optimized for high debris loads.
- EU Green Deal water reuse targets:Circular economy mandates for industrial process water recovery favor automatic backwash systems with minimal consumable waste.
Industry Challenges
- ISO 9001 and NSF/ANSI 61 certification timelines:Multi-month validation processes delay market access for new entrants in North American and European procurement frameworks.
- Legacy mechanical system integration:Retrofit projects require custom engineering to interface electronic actuation with existing PLC architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Backwash Pre-Filters Market |
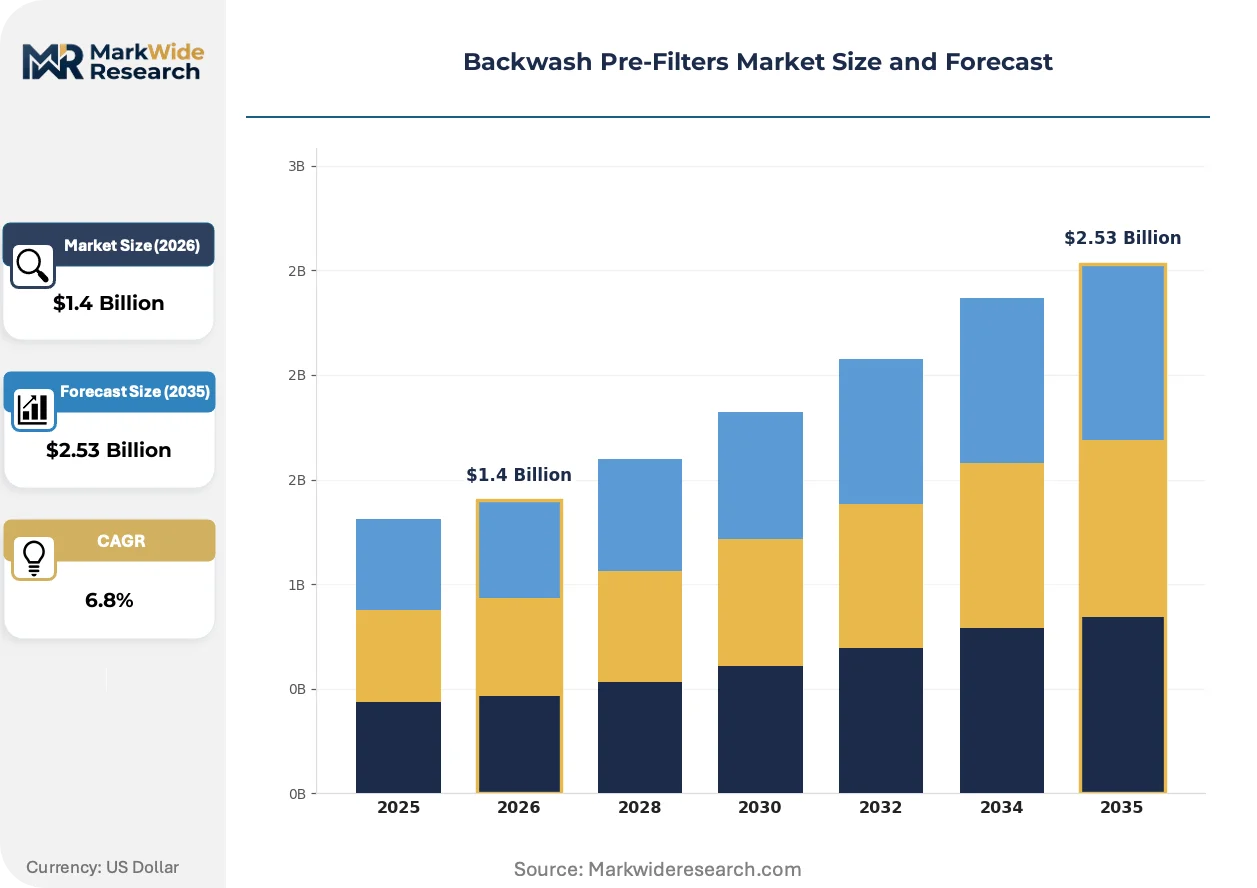
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
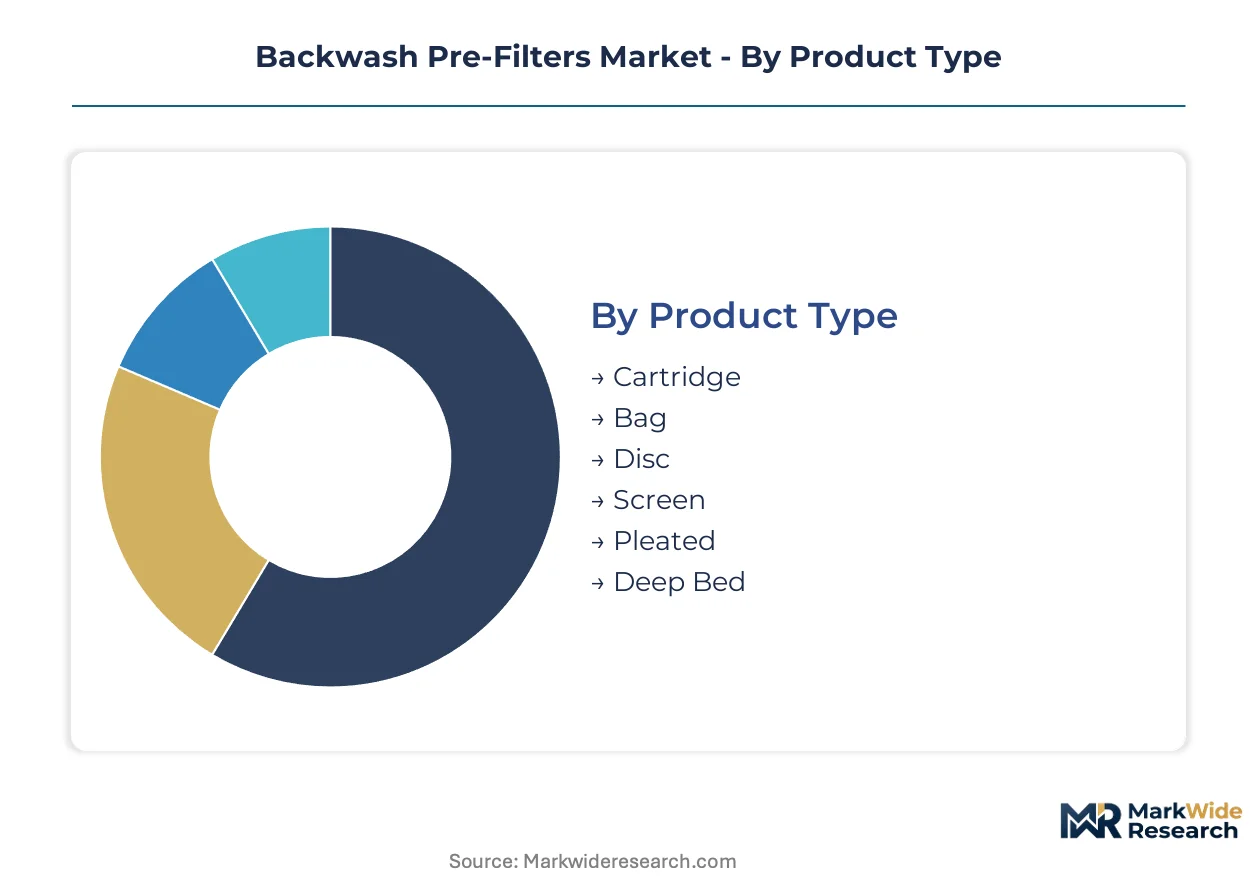
| Segmentation | Product Type: Cartridge, Bag, Disc, Screen, Pleated, Deep Bed Technology: Automatic, Manual, Semi-Automatic, Electronic, Hydraulic Application: Municipal Water Treatment, Industrial Effluent, Agricultural Irrigation, Mining Operations, Power Generation End User: Water Treatment Facilities, Chemical Plants, Food Processing Units, Textile Manufacturing, Metal Finishing |
| Companies Covered | Pall Corporation, Eaton Corporation plc, Amiad Water Systems Ltd., Pentair plc, US Water Systems, Honeywell, Hans Sasserath, SPX FLOW, WesTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Backwash Pre-Filters Market Trends and Innovations
Electronic actuation architectures are displacing manual systems across municipal and industrial installations, while regulatory tightening in major economies forces specification upgrades and remote monitoring integration.
Electronic differential pressure sensors paired with motorized valve actuators are displacing spring-loaded mechanical triggers in municipal water treatment facilities. German and Indian utilities now specify these systems to comply with tightening discharge standards and reduce operator rounds. This displacement is compressing demand for legacy manual units and concentrating procurement among suppliers with captive electronics integration capabilities.
China's MEE implements increasingly stringent GB standards for industrial wastewater reuse, forcing steel and textile manufacturers toward automatic backwash architectures with documented cleaning cycle logs. The regulatory consequence is a specification upgrade cycle across Shandong and Jiangsu province industrial clusters. Affected facilities are prioritizing systems with integrated flow meters and pressure transducers to demonstrate compliance during environmental audits.
Facility operators now unbundle after-sales service contracts from initial equipment procurement, favoring third-party maintenance providers with multi-brand expertise. This behavior shift disrupts traditional OEM service revenue models in North American industrial markets. The trend is most visible in power generation and chemical processing verticals where specialized filtration technicians command premium labor rates.
Backwash Pre-Filters Market Segmentation
Backwash pre-filter procurement patterns diverge sharply across product architectures and actuation methods, with margin capture shifting toward electronically controlled systems and specialized media configurations. Understanding these segment boundaries clarifies where specification upgrades concentrate and which technology transitions reshape supplier economics.
Product Type:
Margin pools concentrate in pleated and deep bed configurations where extended service intervals and sub-micron retention justify premium positioning against commodity screen alternatives.
- Screen:Stainless steel or synthetic mesh elements rated 50-1500 microns dominate municipal installations in Germany and India where debris loads remain predictable and backwash frequency stays moderate. Procurement volumes here are compressing as utilities upgrade toward electronic actuation systems with integrated differential pressure monitoring.
- Disc:Stacked polypropylene or nylon discs with calibrated groove geometry excel in agricultural irrigation across Brazil's center-pivot districts where variable water quality demands self-cleaning flexibility. The technology captures expanding share in mining operations where high solids loading would blind conventional screen elements.
- Cartridge:Replaceable depth filters serve point-of-use protection in food processing units with moderate suspended solids.
- Bag:Felt or mesh sock configurations occupy economy tier positions in metal finishing pre-treatment stages.
- Pleated:High-surface-area media deliver sub-10 micron retention for chemical plant membrane protection.
- Deep Bed:Granular media systems with extended backwash cycles anchor power generation cooling water intakes.
The dominant share belongs to Screen configurations, while Disc is closing the gap fastest in water-stressed agricultural regions.
Technology:
Specification velocity runs highest in actuation architectures that reduce labor intervention and enable remote monitoring compliance.
- Electronic:Motorized valve actuators paired with programmable logic controllers and cloud-connected sensors now anchor municipal procurement in the US and EU. China's steel and textile manufacturers specify these systems to satisfy MEE audit requirements for documented cleaning cycle logs.
- Automatic:Spring-loaded or timer-based triggers without full electronic integration persist in price-sensitive emerging economy installations where skilled technician scarcity constrains deployment.
- Manual:Hand-operated valve systems retreat to small-scale agricultural and legacy industrial sites with minimal regulatory oversight.
- Semi-Automatic:Hybrid configurations blend manual override with pressure-triggered cleaning in mid-tier food processing applications.
- Hydraulic:Fluid-power actuation serves high-pressure industrial environments in chemical plants where electrical hazard classification complicates electronic alternatives.
Electronic systems command the steepest expansion trajectory, while Automatic retains volume leadership in transitional procurement cycles.
Application:
End-use concentration patterns reflect regulatory enforcement intensity and capital availability for infrastructure retrofit programs.
- Municipal Water Treatment:EPA Maximum Contaminant Level enforcement drives pre-filtration upgrades ahead of membrane bioreactor expansions across US utilities. Procurement here prioritizes NSF/ANSI 61 certified systems with minimal operator intervention.
- Industrial Effluent:China's MEE GB standards for wastewater reuse force retrofit cycles across Shandong and Jiangsu province steel and textile clusters. Specifications demand integrated flow meters and pressure transducers for compliance documentation.
- Agricultural Irrigation:Variable frequency drive pump protection requirements accelerate screen and disc adoption with differential pressure triggers in Brazil and India.
- Mining Operations:High-solids process water recovery favors disc technology optimized for abrasive debris loads.
- Power Generation:Cooling water intake protection specifies deep bed configurations with extended backwash intervals.
Municipal Water Treatment holds the largest installed base, though Industrial Effluent is gaining share fastest under tightening discharge regimes.
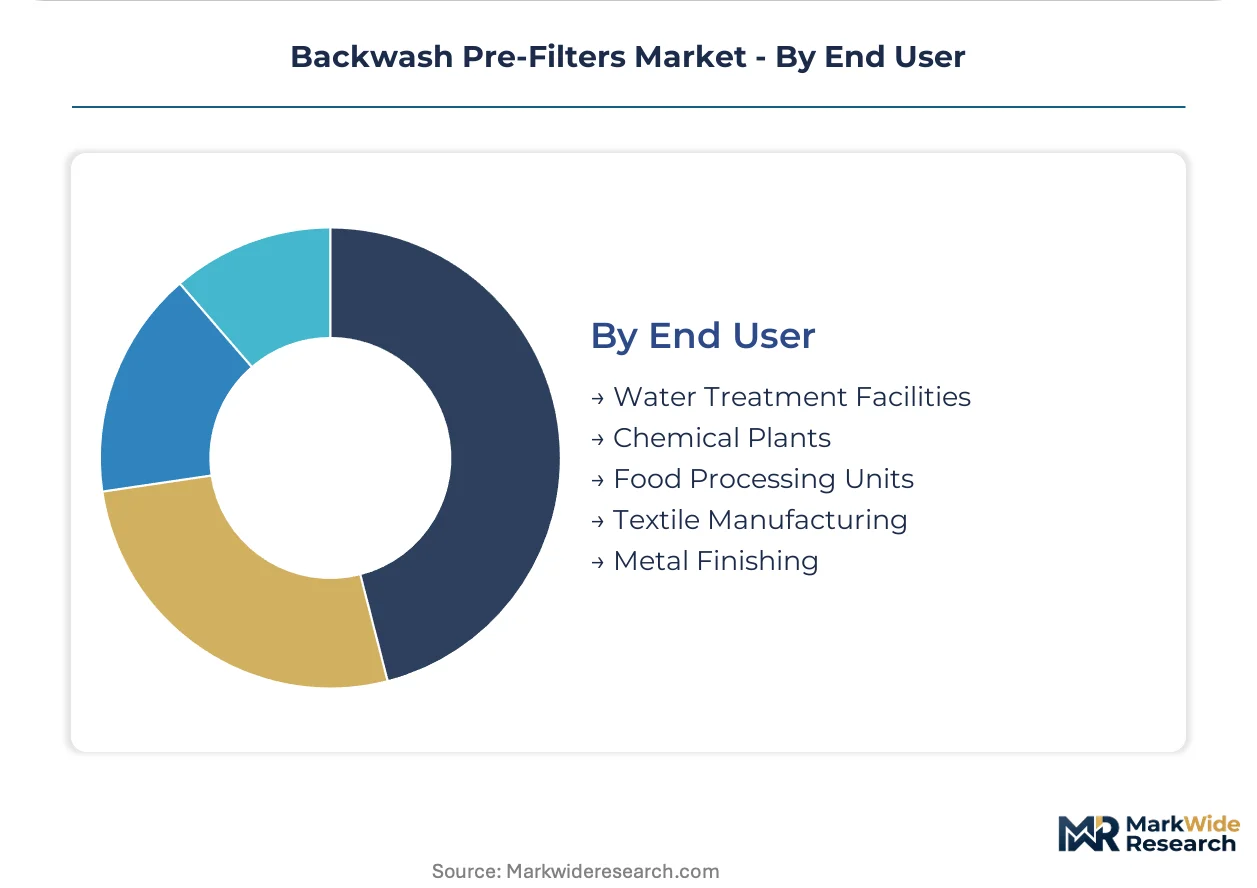
End User:
Customer segmentation reveals divergent procurement behaviors between regulated utilities and industrial operators with varying compliance exposure.
- Water Treatment Facilities:Municipal and industrial water utilities in Germany, India, and Brazil anchor automatic backwash demand as discharge standards tighten. These buyers unbundle service contracts from equipment procurement, favoring third-party maintenance providers.
- Chemical Plants:Process water recovery and membrane protection requirements in China's industrial corridors specify pleated and electronic systems with predictive maintenance integration.
- Food Processing Units:Hygienic design constraints and moderate solids loading favor cartridge and screen configurations with quick-change accessibility.
- Textile Manufacturing:India's dyeing and finishing operations retrofit filtration infrastructure to comply with zero liquid discharge mandates.
- Metal Finishing:Pre-treatment bath protection employs bag and screen systems with economy-tier pricing.
Water Treatment Facilities command the dominant procurement volume, while Chemical Plants are expanding specification fastest under environmental audit pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Germany and the United States prioritize electronic actuation for municipal compliance, while India and Brazil balance cost constraints against regulatory pressure. China's industrial corridor cities drive specification upgrades ahead of wastewater reuse mandates.
Germany
Municipal utilities specify automatic backwash systems to meet tightening EU discharge standards under the EU Green Deal water reuse targets. The country's environmental regulator enforces strict pre-treatment requirements ahead of membrane bioreactor expansions. Industrial clusters in North Rhine-Westphalia retrofit cooling water intakes with deep bed configurations.
United States
EPA Maximum Contaminant Level enforcement compels water treatment facilities to upgrade pre-filtration stages. The agency mandates automatic architectures in municipal procurement frameworks. Utilities across the Great Lakes region prioritize NSF/ANSI 61 certified systems with minimal operator intervention.
China
Steel and textile manufacturers retrofit filtration infrastructure to comply with MEE GB standards for industrial wastewater reuse. The Ministry of Ecology and Environment implements increasingly stringent audit requirements for documented cleaning cycle logs. Shandong and Jiangsu province industrial clusters specify integrated flow meters and pressure transducers.
India
Textile dyeing and finishing operations retrofit filtration systems to comply with zero liquid discharge mandates. The Central Pollution Control Board tightens enforcement of pre-treatment standards for industrial effluent. Municipal water treatment facilities in Maharashtra and Gujarat expand procurement of screen configurations with differential pressure triggers.
Brazil
Agricultural irrigation districts favor disc technology optimized for variable water quality conditions in center-pivot systems. ANVISA and environmental agencies coordinate standards for process water recovery in food processing units. São Paulo state industrial operators specify electronic actuation to reduce labor costs amid technician scarcity.
Backwash Pre-Filters Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with mid-scale regional fabricators occupying price-sensitive segments. The upper tier commands municipal and industrial contracts through captive electronics integration and certified media supply. Three archetypes dominate: diversified filtration conglomerates with captive component production, specialized water technology pure-plays, and regional system integrators serving emerging economy price points. Competitive moves concentrate on backward integration into sensor and actuator manufacturing, plus geographic expansion through distribution partnerships in water-stressed regions.
Among diversified filtration conglomerates, Eaton Corporation plc and Pentair plc occupy positions exemplifying the integrated leader archetype through their captive supply chains and multi-vertical reach. Amiad Water Systems Ltd. represents the specialized pure-play model with concentrated expertise in agricultural and industrial applications. These three anchors illustrate how competitive positioning splits between scale-driven diversification and focused technology depth.
| Leading Market Players |
|---|
| Pall Corporation |
| Eaton Corporation plc |
| Amiad Water Systems Ltd. |
| Pentair plc |
| US Water Systems |
| Honeywell |
| Hans Sasserath |
| SPX FLOW |
| WesTech |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at stainless steel mesh producers in Germany and China directly shapes margin pools for screen-based configurations, concentrating supply-side pricing power among integrated manufacturers with captive 316L alloy sourcing while compressing floors for commodity assemblers dependent on spot metal markets.
Pricing Analysis
Long-term municipal offtake agreements dominate procurement in Germany and the United States, anchoring volume commitments that insulate premium suppliers from spot-price volatility in stainless steel feedstocks. Price differentiation rests on NSF/ANSI 61 certification tier and after-sales service bundling, with unbundled third-party maintenance contracts eroding traditional OEM service revenue. Cost compression in manual system tiers is intensifying because Brazilian and Indian buyers prioritize capital expenditure minimization over lifecycle operating cost. Municipal water treatment facilities in developed markets exhibit lowest price sensitivity, while small-scale agricultural operators in emerging economies drive aggressive tender competition.
Supply Chain Analysis
China and Germany anchor stainless steel screen fabrication, with India expanding woven mesh capacity to serve domestic irrigation demand. Raw material dependencies center on 316L and 904L alloy feedstocks, polypropylene disc media, and electronic actuator components sourced from East Asian semiconductor foundries. Single-source vulnerability concentrates in high-precision differential pressure sensors for electronic actuation systems. Distribution runs through specialized water technology distributors in North America and Europe, direct OEM sales forces in China, and agricultural equipment dealers in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The backwash pre-filters market is recovering from a cyclical trough driven by delayed municipal infrastructure spending during rate-tightening periods, with procurement velocity now accelerating as EPA and EU Green Deal enforcement timelines harden.
For Market Incumbents: Consolidate backward integration into pleated media manufacturing to defend margin pools against specialty chemical plant demand, while acquiring regional service capabilities in Brazil and India to counter third-party maintenance disruption. Lock in multi-year municipal offtake agreements ahead of membrane bioreactor expansion cycles to secure capacity utilization. For New Entrants and Emerging Players: NSF/ANSI 61 certification fast-track programs open procurement access in North American municipal segments where incumbent lead times extend six to nine months. Target Brazilian agricultural irrigation with disc technology optimized for variable water quality, leveraging local equipment dealer networks rather than direct sales infrastructure to minimize customer acquisition cost. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electronic actuation specialists with integrated predictive maintenance platforms, suggesting superior cash flow quality versus commodity screen manufacturers. Focus acquisition screening on mid-scale European firms with captive sensor integration capabilities and established MEE compliance documentation in China. Monitor EPA enforcement action intensity as the inflection signal for municipal upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pleated Media | Captive supply of high-surface-area filtration media secures margin pools in chemical plant membrane protection contracts. |
| Electronic Actuator Manufacturing Scale-Up | In-house production of motorized valve systems reduces dependency on East Asian sensor suppliers and accelerates municipal compliance timelines. |
| IoT Platform Partnership | Cloud analytics integration creates service revenue streams as facilities unbundle maintenance from initial equipment procurement. |
| Brazilian Distribution Channel Expansion | Agricultural equipment dealer partnerships capture center-pivot irrigation demand without direct sales infrastructure investment. |
| MEE Compliance Documentation Investment | Integrated flow meter and pressure transducer systems satisfy Shandong and Jiangsu province audit requirements for steel manufacturers. |
Research Methodology
Operator-level perspectives from municipal water utility engineers, chemical plant maintenance directors, agricultural irrigation district managers, and filtration OEM product managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA enforcement databases, MEE GB standard publications, EU Green Deal implementation reports, and municipal procurement records from Maharashtra and São Paulo state agencies. Bottom-up unit economics for screen, disc, and pleated configurations were triangulated against top-down market sizing from trade customs data and industry association capacity surveys.
Sensitivity analysis tested forecast outputs against regulatory enforcement intensity scenarios, stainless steel price volatility bands, and electronic actuation adoption curve variations across the projection horizon. Segmentation dimensions modeled include product architecture, actuation technology, application vertical, and end-user procurement behavior. CAGRs were derived from regression analysis of historical procurement volumes against regulatory milestone timing, with specific inputs for membrane bioreactor pre-treatment penetration rates and zero liquid discharge mandate compliance deadlines in Indian textile clusters.
Underlying assumptions cover EPA Maximum Contaminant Level enforcement timelines, MEE audit documentation requirements, and skilled technician availability curves, with deviation risk concentrated in regulatory delay scenarios and raw material supply disruptions. Recalibration cycles align with material shifts in municipal capital appropriation patterns and GB standard revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Global Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Global Biological Wastewater Treatment Market
Water and Wastewater Treatment
Commercial Atmospheric Water Generator Market
Water and Wastewater Treatment
Javelle Water Market
Water and Wastewater Treatment
Tertiary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Water Aeration System Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Water Testing Meter Market
Water and Wastewater Treatment
Global Vertical Sewage Pumps Market
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Latin America Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market