
 Mobile Wastewater Treatment Plant Market | 2026-2036
Mobile Wastewater Treatment Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Wastewater Treatment Plant Market Foresight
Construction sites and emergency response teams is broadening the addressable base for mobile wastewater systems. Xylem Inc. leverages its pump and treatment integration capabilities to serve remote industrial deployments. Evoqua Water Technologies LLC sustains technology leadership in membrane bioreactor packages for temporary municipal bypass projects. SUEZ SA anchors European municipal emergency frameworks with rapid-deployment containerized plants.
A mobile wastewater treatment plant comprises self-contained, transportable systems—typically skid-mounted or containerized—integrating screening, biological oxidation, clarification, and disinfection stages within throughput capacities ranging from 10,000 to over 1 million gallons per day. These units process raw sewage or industrial effluent at locations lacking permanent infrastructure, serving construction dewatering, municipal bypass, and disaster relief scenarios. Containerized plants dominate current procurement volumes due to their plug-and-play logistics and reduced site preparation. Membrane bioreactor technology commands premium positioning as discharge standards tighten and water reuse expands. Skid-mounted solutions occupy the economy tier where rapid mobilization and short deployment cycles matter more than effluent quality.
The EPA enforces effluent limitations under the Clean Water Act, while state-level environmental agencies impose supplementary permitting for temporary discharge points. OSHA mandates worker exposure controls around mobile biological treatment units handling raw municipal waste. Stakeholders must monitor regulatory divergence between federal baseline standards and emerging state-level reuse mandates that could reshape equipment specification requirements.
Market Dynamics
Containerized membrane bioreactor technology is compressing deployment timelines from months to days, forcing incumbent equipment suppliers to reconfigure service models around rapid mobilization rather than permanent infrastructure sales.
Growth Catalysts
- Hurricane Response Protocols:Emergency management agencies in Florida, Texas, and Louisiana now mandate pre-positioned mobile treatment capacity. FEMA's updated disaster water infrastructure guidelines accelerate procurement cycles for containerized units.
- Construction Dewatering Regulations:EPA effluent limitation guidelines for construction site discharge are tightening suspended solids and nutrient thresholds. Contractors face penalties for non-compliance, driving rental demand for compliant mobile systems.
- Membrane Bioreactor Maturation:Packaged MBR systems achieve reuse-grade effluent without secondary clarification. Municipal bypass projects in California increasingly specify this technology for temporary capacity during plant upgrades.
Market Restraints
- Stainless Steel Input Volatility:Containerized plant fabrication depends heavily on 316L stainless steel for corrosion resistance. Price swings in nickel and molybdenum feed directly into unit production costs with limited pass-through flexibility.
- Skilled Technician Concentration:Commissioning and operation of mobile biological systems requires certified wastewater operators. The pool of licensed personnel concentrates in established municipal markets, constraining rapid deployment to remote locations.
- Permitting Fragmentation:State environmental agencies impose divergent temporary discharge standards. California's Title 22 reuse requirements exceed federal baselines, forcing equipment specification changes that raise unit costs and extend sales cycles.
Strategic Opportunities
- Mining Camp Water Loops:Remote extraction operations in Nevada, Arizona, and Colorado seek closed-loop wastewater systems for workforce housing. Mobile units enabling potable reuse reduce freshwater hauling costs and environmental liability exposure.
- CSRD-Driven European Demand:Corporate Sustainability Reporting Directive requirements are pushing industrial site operators toward documented water stewardship. Rapid-deployment containerized plants allow temporary compliance during permanent facility construction.
- IoT-Enabled Predictive Maintenance:Sensor networks monitoring biological process parameters and membrane fouling are converging with cloud analytics platforms. Equipment suppliers can capture recurring revenue through performance-guaranteed service contracts.
Industry Challenges
- Cross-State Operator Certification:Wastewater operator licenses rarely transfer between state jurisdictions. Deployment teams must maintain redundant certified staff or absorb retraining costs, complicating national rental fleet operations.
- Legacy System Integration:Mobile plants connecting to existing municipal collection systems face incompatible inlet configurations and control protocols. Each connection requires custom engineering, eroding the plug-and-play value proposition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Wastewater Treatment Plant Market |
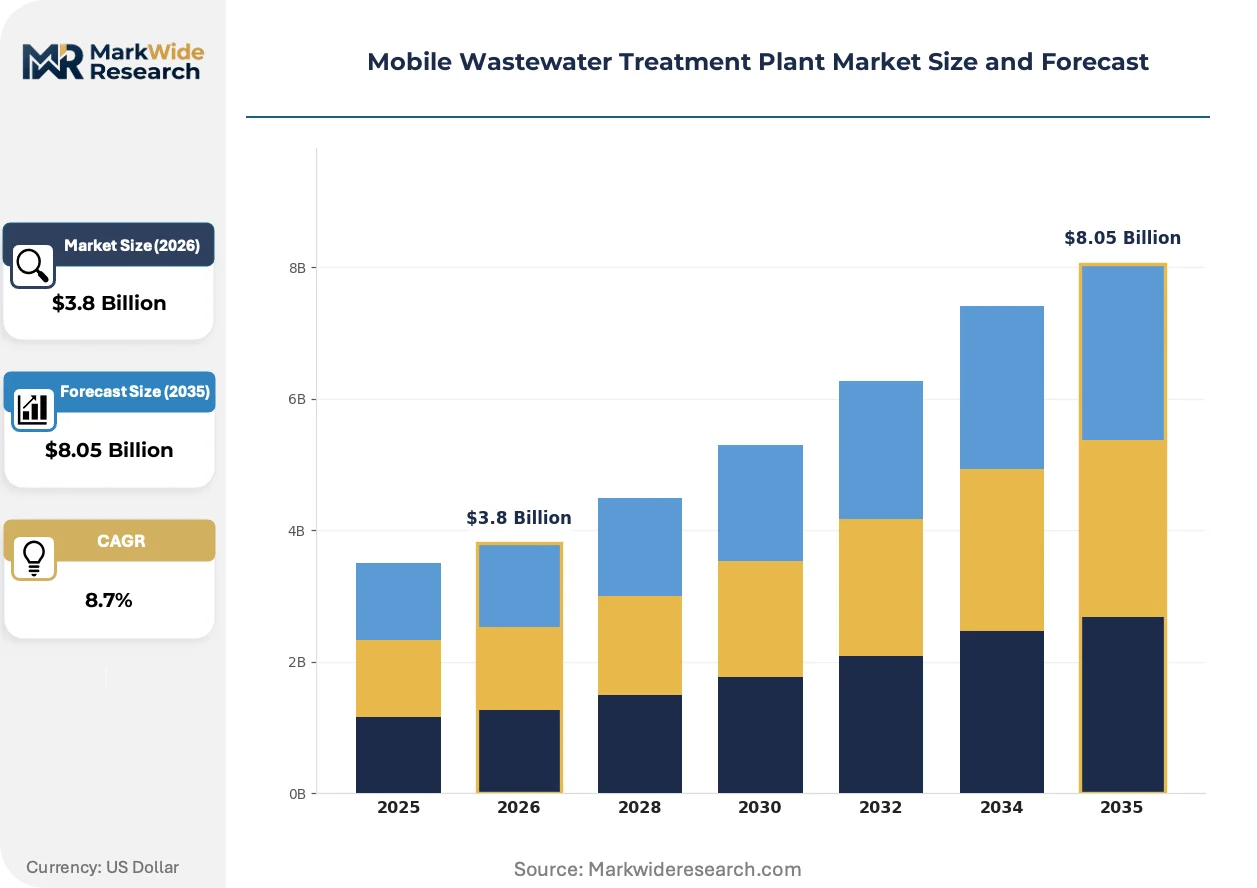
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Systems, Containerized Plants, Mobile Units, Skid-mounted Solutions Technology: Membrane Bioreactor, Reverse Osmosis, Biological Treatment, Chemical Treatment End User: Municipalities, Construction Sites, Industrial Facilities, Emergency Response Teams Application: Wastewater Treatment, Water Recycling, Disaster Recovery, Temporary Camps |
| Companies Covered | Xylem Inc., Pentair plc, Veolia Water Technologies & Solutions SA, General Electric Company, Danaher Corporation, Evoqua Water Technologies LLC, SUEZ SA, WesTech Engineering LLC, Aquatech International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Wastewater Treatment Plant Market Shifts & Advancements
Digital process control and modular membrane technology are compressing the trade-off between deployment speed and effluent quality that has historically segmented the mobile treatment market into economy and premium tiers.
Containerized membrane bioreactor packages are unifying biological treatment and membrane filtration within single shipping-container footprints. Mining operators and military base contractors are adopting these systems for 90-day deployment cycles. The technology is unifying what were previously separate procurement decisions for temporary capacity and water reuse compliance.
EPA's updated effluent limitation guidelines for construction and development point sources are mandating numeric nutrient limits where qualitative standards previously applied. Equipment suppliers must now certify total nitrogen and phosphorus removal capabilities to bid federally funded projects. California and Florida environmental agencies are mirroring these standards, compressing the addressable market for basic screening-and-disinfection units.
Rental and service-based contracting are displacing capital purchase for temporary wastewater needs. Municipal utilities managing plant upgrades now favor 12-24 month operating leases with guaranteed effluent quality over equipment ownership. The model is most visible in Texas and North Carolina, where rapid population growth creates recurring bypass treatment requirements.
Mobile Wastewater Treatment Plant Market Segmentation
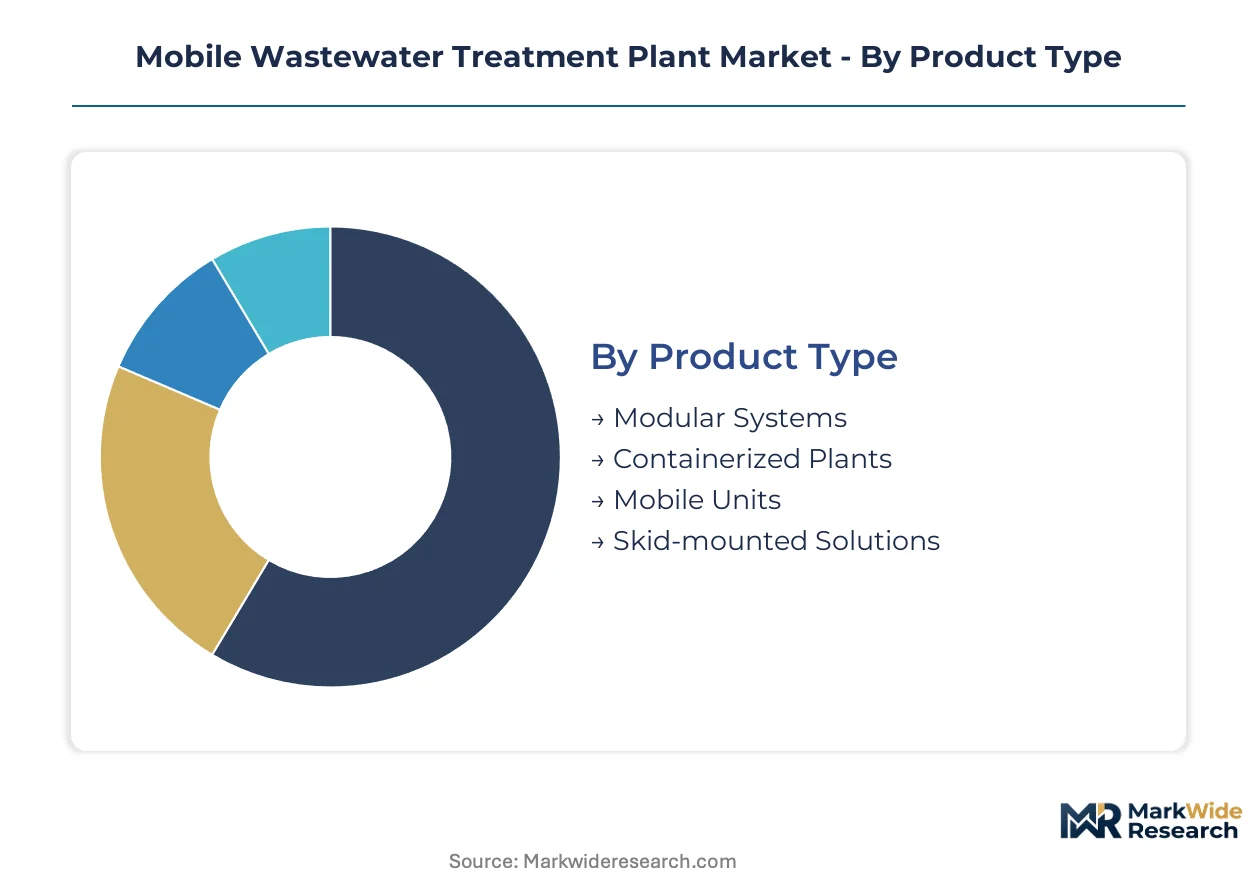
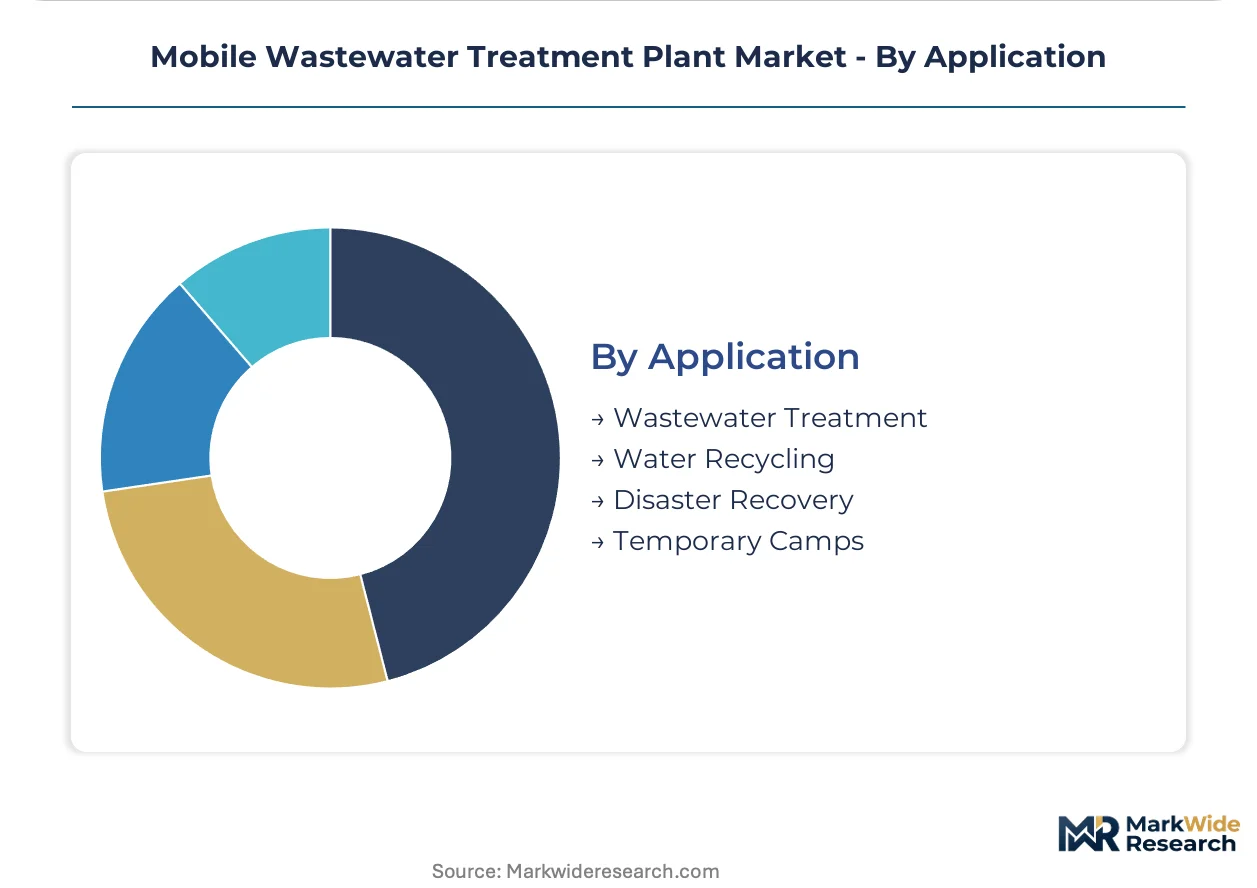
Equipment specification varies sharply across deployment scenarios. Municipal bypass projects demand reuse-grade effluent while construction dewatering prioritizes rapid mobilization. Understanding these segment boundaries clarifies procurement patterns and technology positioning.
Product Type:
Replacement cycles differ dramatically by mounting configuration. Containerized plants with standardized dimensions refresh every 8-12 years as membrane technology advances. Skid-mounted systems turn over faster at 4-6 years due to harsher field conditions and lower capital commitment.
- Containerized Plants:Self-contained systems housed in modified shipping containers integrate screening, biological treatment, and disinfection within a single transportable footprint. Demand concentrates in Florida, Texas, and Louisiana where FEMA protocols mandate pre-positioned emergency capacity and hurricane response timelines compress deployment windows to under 72 hours.
- Skid-mounted Solutions:Steel-frame mounted equipment packages prioritize rapid field installation over effluent quality, typically serving construction dewatering and short-term industrial needs. Texas and California contractors drive procurement as EPA construction effluent guidelines tighten suspended solids thresholds and penalties for non-compliance escalate.
- Modular Systems:Interchangeable process units allow capacity scaling through parallel installation.
- Mobile Units:Trailer-mounted configurations serve rapid-response scenarios requiring highway transport without specialized hauling permits.
Volume placements concentrate in Containerized Plants; the faster expansion belongs to Skid-mounted Solutions.
Technology:
Cost tiers separate clearly by treatment sophistication. Membrane bioreactor systems command 3-4x capital cost premiums over biological treatment alternatives. Reverse osmosis layers additional energy and pretreatment expenses, restricting adoption to water-stressed geographies with reuse mandates.
- Membrane Bioreactor:Combined biological oxidation and membrane filtration achieves Title 22 reuse-grade effluent without secondary clarification. California municipalities specify this technology for plant upgrade bypasses where discharge to sensitive watersheds demands nitrogen and phosphorus removal below federal baselines.
- Biological Treatment:Conventional activated sludge or fixed-film processes occupy the economy tier where regulatory thresholds remain less stringent. Construction dewatering applications in Texas and Florida favor these systems for 90-180 day deployments where suspended solids compliance suffices.
- Reverse Osmosis:Pressure-driven membrane separation targets dissolved solids removal for industrial process water recycling.
- Chemical Treatment:Coagulation, flocculation, and disinfection systems serve specialized industrial effluent with targeted contaminant profiles.
Procurement volumes favor Biological Treatment; Membrane Bioreactor is gaining share fastest where reuse regulations tighten.
End User:
Customer type determines contracting structure and service intensity. Municipalities favor operating leases with guaranteed effluent quality. Construction sites prioritize rental flexibility with rapid mobilization clauses.
- Municipalities:Utilities managing plant upgrades or emergency capacity shortfalls require 12-24 month deployments with certified operators and compliance documentation. Texas and North Carolina municipalities lead this segment as population growth outpaces permanent infrastructure construction.
- Emergency Response Teams:FEMA and state emergency management agencies procure containerized units under pre-positioned contracts with 24-hour activation requirements. Florida and Louisiana agencies expanded fleet commitments following recent hurricane seasons that overwhelmed permanent treatment capacity.
- Construction Sites:General contractors rent systems for dewatering and workforce sanitation during infrastructure projects.
- Industrial Facilities:Mining, oil and gas, and manufacturing operators deploy mobile systems for remote workforce housing and process water management.
Contract volume concentrates in Municipalities; Emergency Response Teams show the steepest expansion trajectory as climate adaptation protocols harden.
Application:
Deployment duration and effluent standards segment this category sharply. Disaster recovery demands immediate activation with variable influent quality. Water recycling applications require consistent performance for potable or process reuse.
- Disaster Recovery:Post-hurricane and flood response scenarios require treatment of highly variable raw sewage and debris-laden influent. FEMA guidelines now specify containerized membrane bioreactor units for sustained deployment beyond 30 days where permanent system restoration lags.
- Wastewater Treatment:Standard sewage processing for municipal bypass and construction camp sanitation represents the baseline application with established equipment specifications and operator certification pathways.
- Water Recycling:Closed-loop systems enabling potable or process water reuse serve mining camps in Nevada and Arizona where freshwater hauling costs exceed mobile treatment premiums.
- Temporary Camps:Workforce housing for infrastructure and extraction projects requires sanitary sewage treatment with minimal site preparation.
Deployment frequency clusters in Wastewater Treatment; Water Recycling climbs fastest as western states deepen reuse mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile wastewater treatment plant production concentrates in Germany and the United States, while consumption clusters in hurricane-prone coastal zones and water-stressed mining regions. Equipment fabricators leverage established industrial bases to serve dispersed deployment sites.
United States
Texas, California, and Florida drive procurement as municipal infrastructure gaps intersect with disaster response mandates. The EPA enforces updated effluent limitation guidelines under the Clean Water Act, tightening numeric nutrient limits for construction site discharge. Houston-area emergency management agencies pre-position containerized membrane bioreactor units for 72-hour hurricane activation protocols.
Germany
Industrial site operators deploy rapid-deployment systems to satisfy Corporate Sustainability Reporting Directive documentation requirements during permanent facility construction. ECHA chemical safety standards influence equipment material specifications for corrosion resistance. The Ruhr industrial cluster hosts fabrication facilities supplying containerized plants across European municipal emergency frameworks.
China
Western mining provinces seek closed-loop wastewater systems for remote extraction workforce housing under tightening environmental compliance. The Ministry of Ecology and Environment enforces discharge standards that elevate membrane bioreactor adoption for temporary camp sanitation. Sichuan-Chongqing infrastructure contractors rent skid-mounted units for tunneling and dam construction dewatering.
Australia
Queensland and Western Australia mining camps adopt mobile treatment to reduce freshwater hauling costs across vast distances. The country's national environmental regulator imposes site-specific discharge permits that favor reuse-grade effluent systems. Pilbara iron ore operations specify containerized membrane packages for 90-day workforce housing rotations.
Canada
Alberta oil sands and remote northern extraction sites require seasonal workforce sanitation without permanent infrastructure. Health Canada guidelines influence potable reuse system specifications for isolated camp deployments. Fort McMurray contractors source skid-mounted biological treatment for construction dewatering during expansion cycles.
Mobile Wastewater Treatment Plant Market Competitive Landscape
Top-tier vendors anchor premium membrane bioreactor integration, while mid-tier fabricators compete on rapid mobilization speed and rental flexibility. The vendor base stratifies across three tiers: integrated water technology conglomerates, specialized mobile equipment fabricators, and regional rental service operators. Two strategic archetypes dominate: technology licensors leveraging pump and treatment integration capabilities, and rental fleet operators capturing recurring revenue through performance-guaranteed service contracts. Competitive moves center on backward integration into membrane manufacturing and geographic expansion of certified operator networks.
Within the integrated technology tier, Xylem Inc. and Evoqua Water Technologies LLC occupy positions exemplifying pump-treatment integration and packaged membrane system specialization respectively. SUEZ SA anchors European municipal emergency frameworks with rapid-deployment containerized plants. These three entities represent contrasting archetypes: Xylem exemplifies vertical equipment integration, Evoqua occupies membrane bioreactor technology leadership, and SUEZ embodies geographic anchoring through pre-positioned fleet contracts. Their collective positioning illustrates how technology depth, service network density, and regulatory relationship intensity separate premium-tier competitors from rental-focused challengers.
| Leading Market Players |
|---|
| Xylem Inc. |
| Pentair plc |
| Veolia Water Technologies & Solutions SA |
| General Electric Company |
| Danaher Corporation |
| Evoqua Water Technologies LLC |
| SUEZ SA |
| WesTech Engineering LLC |
| Aquatech International LLC |
| Others |
Supply & Pricing Matrix
Containerized membrane bioreactor maturation is compressing fabrication economics while concentrating supply among German and United States fabricators with captive membrane sourcing. This technology transition rewards scale players with backward integration into membrane manufacturing while marginalizing skid-mounted assemblers dependent on spot stainless steel markets.
Pricing Analysis
Short lead-time premiums dominate contract structures, with FEMA-mandated 72-hour activation commands commanding 40-60 percent markups over standard 30-day delivery windows. Three-tier pricing structure across premium, standard, and economy levels separates membrane bioreactor packages with Title 22 certification from biological treatment units and basic screening systems. Cost compression in economy-tier skid-mounted units is intensifying because nickel and molybdenum volatility erodes pass-through flexibility. Construction contractors exhibit highest price sensitivity, while emergency response agencies prioritize guaranteed activation over unit cost.
Supply Chain Analysis
Regional distribution centers in Houston, Ruhr, and Shanghai anchor hub-and-spoke patterns serving dispersed deployment sites. Manufacturing concentrates in Germany, the United States, and China, with fabrication drawing from 316L stainless steel mills in North Rhine-Westphalia and specialty membrane suppliers in Japan and South Korea. Single-source vulnerability concentrates in hollow-fiber membrane modules, where two Japanese suppliers control premium ultrafiltration grades. Distribution runs through rental fleet operators with certified operator networks rather than direct equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane bioreactor technology consolidation is forcing skid-mounted specialists toward acquisition or exit as EPA nutrient limits eliminate their core construction dewatering market.
For Market Incumbents: Extend certified operator networks into secondary state markets before regulatory reciprocity agreements harden competitive moats. Acquire distressed skid-mounted rental fleets at cyclical lows to convert containerized membrane capacity. Backward integration into membrane manufacturing protects margin structure against Japanese supplier pricing power.
For New Entrants and Emerging Players: Begin with mining camp water recycling in Nevada and Arizona, where freshwater hauling economics justify mobile treatment premiums and incumbent coverage remains thin. Target 90-day workforce housing rotations with IoT-enabled performance contracts that displace capital purchase. Lead with guaranteed effluent quality rather than equipment specifications to bypass operator certification barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated water technology conglomerates seeking membrane bioreactor deployment capabilities. Long-term viability favors operators with captive membrane supply and multi-state operator certification infrastructure. Watch California Title 22 enforcement intensity as inflection indicator for reuse-grade equipment demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | Captive ultrafiltration supply insulates margin structure against Japanese supplier concentration. |
| Multi-State Operator Certification Infrastructure | Cross-jurisdiction deployment capability unlocks FEMA pre-positioned contract eligibility. |
| IoT-Enabled Performance Contracting | Sensor networks monitoring membrane fouling enable recurring revenue substitution of capital sales. |
| Mining Camp Water Loop Specialization | Potable reuse compliance in Nevada and Arizona commands 3-4x rental premiums over construction dewatering. |
| European CSRD Compliance Documentation | Rapid-deployment containerized plants satisfy Corporate Sustainability Reporting Directive water stewardship requirements. |
Research Methodology
Document review covered EPA effluent limitation guidelines, FEMA disaster water infrastructure protocols, and state environmental agency permitting databases, complemented by interviews with municipal utility directors, emergency management procurement officers, and containerized plant fabricators. Secondary validation drew from equipment rental fleet disclosures, stainless steel commodity price indices, and membrane technology patent filings. Bottom-up unit deployment estimates triangulated against top-down infrastructure spending projections across the analysis window.
Segment-level outputs reflect modeled deployment frequencies by mounting configuration, technology tier, and end-user contracting structure throughout the forecast period. CAGRs were derived from regression analysis of historical procurement cycles against regulatory enforcement intensity and hurricane season severity indices. Forecast inputs incorporated FEMA fleet expansion commitments, EPA construction effluent guideline implementation timelines, and membrane replacement cycle assumptions.
Underlying measurement precision varies by segment; containerized membrane bioreactor deployments carry tighter precision than skid-mounted construction rentals due to visible municipal procurement pipelines. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and nickel price stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Agricultural Wastewater Treatment Market
Water and Wastewater Treatment
Global Wastewater Treatment Services Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Global Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Tertiary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Water Testing Meter Market
Water and Wastewater Treatment
Packaged Wastewater Treatment Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
Commercial Atmospheric Water Generator Market
Water and Wastewater Treatment
Global Vertical Sewage Pumps Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market
Water and Wastewater Treatment
Javelle Water Market