
 Plant Based Water Filter Market | 2026-2036
Plant Based Water Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Water Filter Market Analytics
NSF/ANSI 42 and 53 certification timelines for organic filter media is collapsing from eighteen months to under ten months, squeezing smaller suppliers out of qualification pipelines. Pentair PLC leverages its captive testing laboratories to compress certification cycles for coconut-shell carbon blocks. A.O. Smith Corporation anchors its position through backward integration into activated carbon sourcing from Sri Lankan cooperatives. The 3M Company differentiates via proprietary pleated plant-fiber geometries that exceed NSF flow-rate benchmarks without chemical binders.
A plant based water filter employs lignocellulosic, activated carbon, or bio-ceramic media derived from renewable botanical sources to reduce chlorine, sediment, volatile organic compounds, and microbial contaminants from potable water streams, typically operating at flow rates between two and ten gallons per minute depending on housing configuration. Activated carbon segments dominate value capture due to established supply chains for coconut-shell and bamboo precursors, while nanofiltration technology leads growth velocity as plant-derived membrane substrates displace petroleum-based polyamides in select applications. Gravity-fed systems occupy the premium residential tier where consumers prioritize zero-energy operation, though electrolysis integration for mineral retention is gaining traction in Korean and Japanese household segments.
EPA Office of Water guidelines under the Safe Drinking Water Act directly shape permissible contaminant reduction claims for filters sold in the United States, while REACH compliance in Europe restricts synthetic resin binders traditionally used in carbon block manufacturing. BIS IS 10500 standards in India mandate specific turbidity and bacterial removal thresholds that plant-based systems must demonstrate through third-party laboratory validation. Stakeholders must monitor evolving PFAS maximum contaminant levels across multiple jurisdictions, as these emerging standards will determine which bio-adsorbent formulations qualify for municipal and institutional procurement.
Market Dynamics
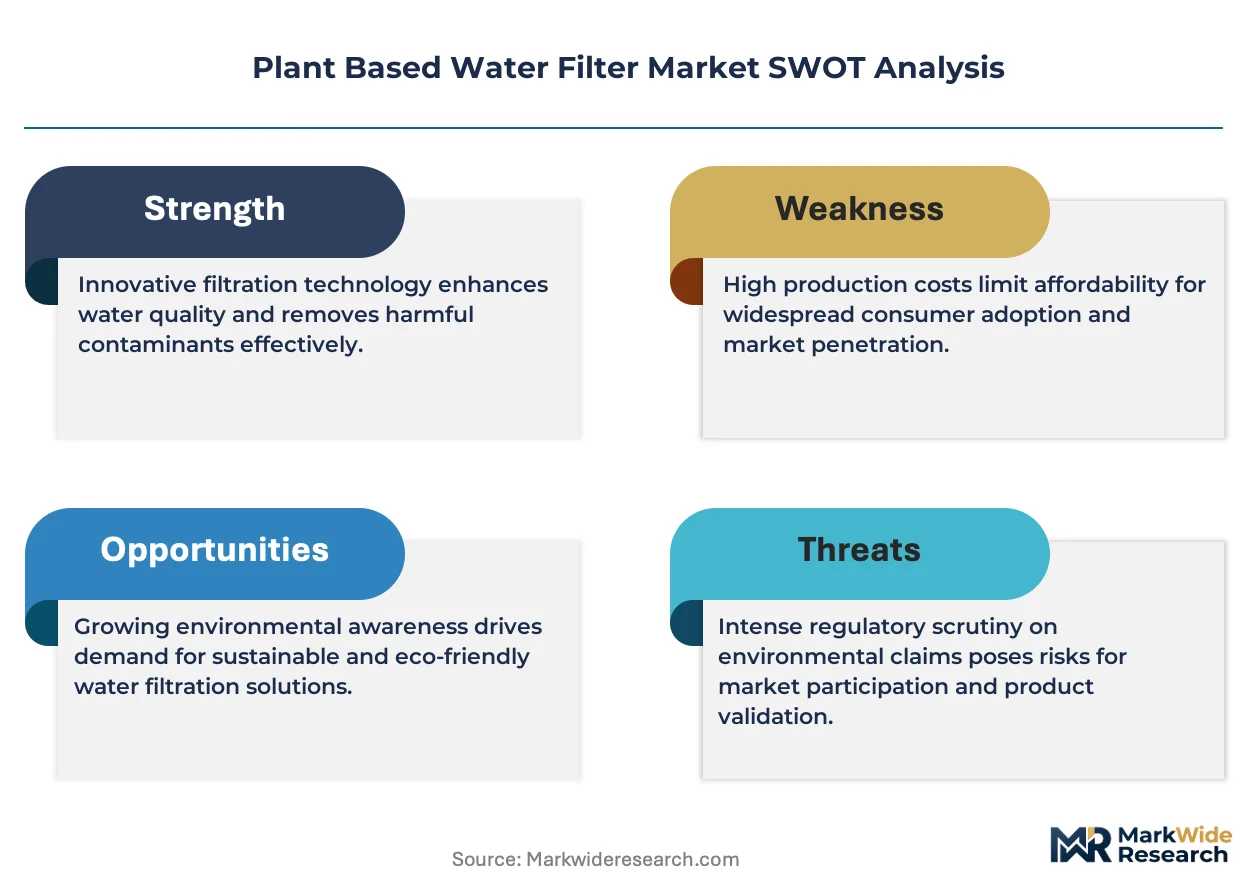
EU Green Deal water quality directives are tightening permissible contaminant thresholds, forcing municipal facilities across Germany to upgrade from synthetic resin binders to lignocellulosic media. This regulatory compression is accelerating qualification timelines and reshaping supplier competitive positions.
Growth Catalysts
- REACH compliance deadlines:European restrictions on synthetic resin binders in carbon block manufacturing are pulling demand toward bio-ceramic alternatives. Municipal procurement teams in Germany are specifying plant-derived media to meet 2027 phase-out timelines.
- BIS IS 10500 certification intensity:India's Bureau of Indian Standards is mandating third-party laboratory validation for turbidity and bacterial removal. Tier-one city utilities in Mumbai and Delhi are retrofitting legacy systems with activated carbon blocks.
- Coconut-shell precursor availability:Established supply chains for lignocellulosic feedstock from Sri Lankan cooperatives are stabilizing input costs for activated carbon production. This material security is enabling capacity expansion across South Asian manufacturing clusters.
Market Restraints
- NSF/ANSI certification compression:Qualification timelines for organic filter media have collapsed from eighteen months to under ten months. Smaller suppliers lack captive testing laboratory infrastructure to match Pentair PLC's cycle compression.
- Activated carbon supply concentration:Premium coconut-shell precursor sourcing clusters in Sri Lanka and Indonesia create geographic concentration risk. Climate volatility in these regions threatens feedstock security for carbon block manufacturers.
- PFAS adsorption performance gaps:Current bio-adsorbent formulations struggle to meet emerging maximum contaminant levels for per- and polyfluoroalkyl substances. This technical limitation is disqualifying plant-based systems from municipal procurement in jurisdictions with stringent PFAS standards.
Strategic Opportunities
- Korean and Japanese household mineral retention:Electrolysis integration for mineral retention is gaining traction in East Asian residential segments. Manufacturers can capture premium positioning by bundling zero-energy gravity-fed housings with mineralization modules.
- Nanofiltration membrane substrates:Plant-derived membrane materials are displacing petroleum-based polyamides in select industrial pre-treatment applications. This technology convergence opens pharmaceutical and semiconductor end-uses previously closed to botanical media.
- EPA PFAS rulemaking tailwind:The EPA Office of Water is establishing enforceable maximum contaminant levels for per- and polyfluoroalkyl substances. Bio-adsorbent formulations that demonstrate compliance will qualify for municipal and institutional procurement previously reserved for synthetic systems.
Industry Challenges
- NSF/ANSI 42 and 53 testing bottlenecks:Third-party laboratory capacity constraints are extending validation queues. Manufacturers face working capital pressure from elongated certification cycles.
- Legacy housing compatibility:Plant-based carbon blocks must retrofit existing polypropylene housings without compromising flow-rate benchmarks. Engineering teams are resolving dimensional tolerance mismatches between botanical media and petroleum-based legacy infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Water Filter Market |
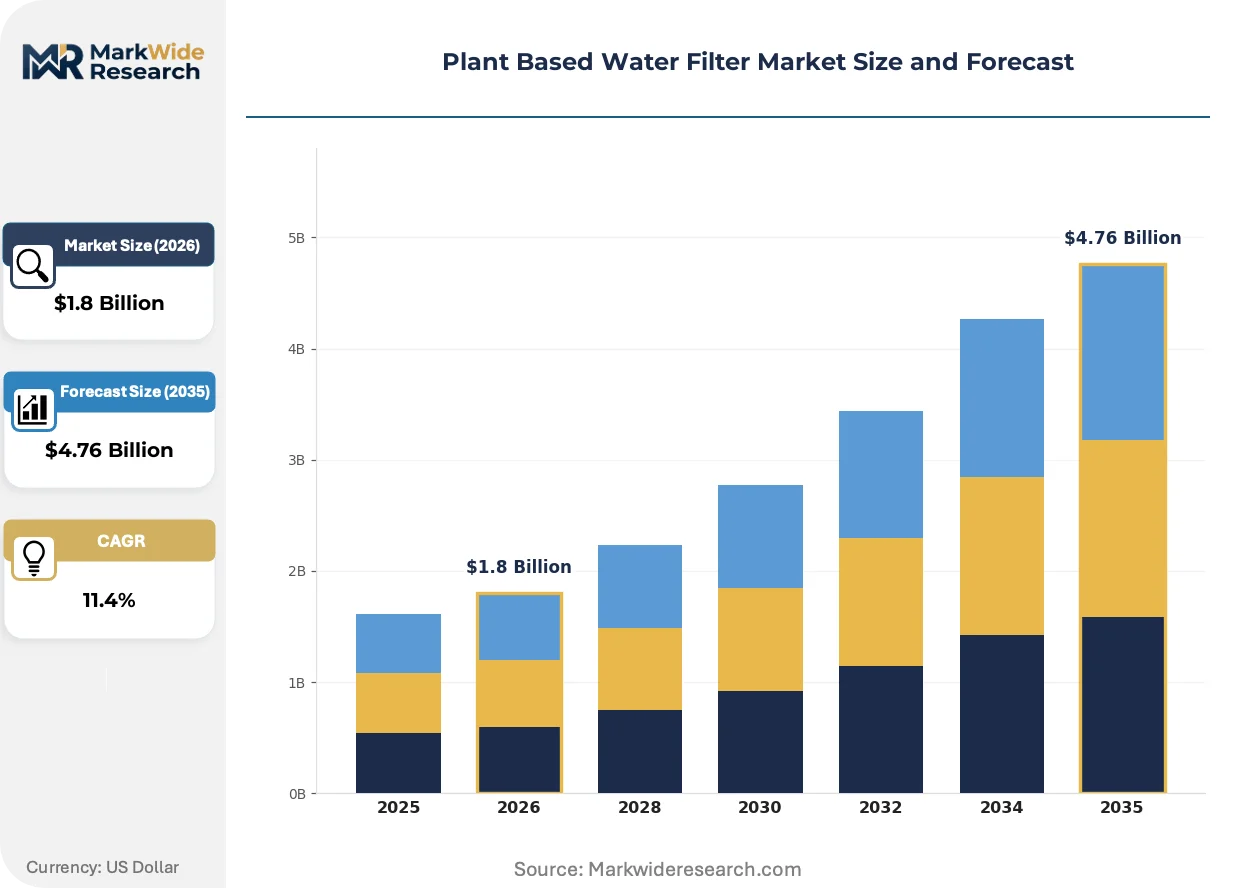
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon, Reverse Osmosis, UV Filter, Ceramic Application: Residential Use, Commercial Use, Industrial Use, Recreational Technology: Filtration, Electrolysis, Nanofiltration, Gravity-fed End User: Households, Restaurants, Hospitals, Schools |
| Companies Covered | Pentair PLC, A.O. Smith Corporation, The 3M Company, Culligan International, Veolia Environnement, Eaton Corporation, Panasonic Corporation, Coway Co., Ltd., MANN+HUMMEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Water Filter Market Evolving Landscape
Plant-based water filtration is experiencing rapid media formulation evolution as regulatory thresholds tighten and end-users prioritize zero-energy operation. Three distinct developments are reshaping competitive positioning.
Nanofiltration technology employing plant-derived membrane substrates is bifurcating the industrial pre-treatment segment. Pharmaceutical manufacturers in Switzerland are adopting these bio-polyamide alternatives for API purification processes. This substrate shift is compressing incumbent petroleum-based membrane suppliers into commodity pricing tiers.
REACH restrictions on synthetic resin binders are forcing carbon block manufacturers to reformulate with lignocellulosic binding agents. European producers are retooling production lines to eliminate petroleum-derived adhesives ahead of 2027 compliance deadlines. Municipal procurement specifications in Germany and France now explicitly disqualify synthetic binder systems from tender eligibility.
Residential buyer preferences are rotating toward zero-energy gravity-fed configurations. Korean and Japanese households are prioritizing mineral retention through integrated electrolysis modules over conventional pressure-driven systems. This consumption-pattern shift is fragmenting demand between premium gravity-fed tiers and standard pressure-driven alternatives.
Plant Based Water Filter Market Segmentation
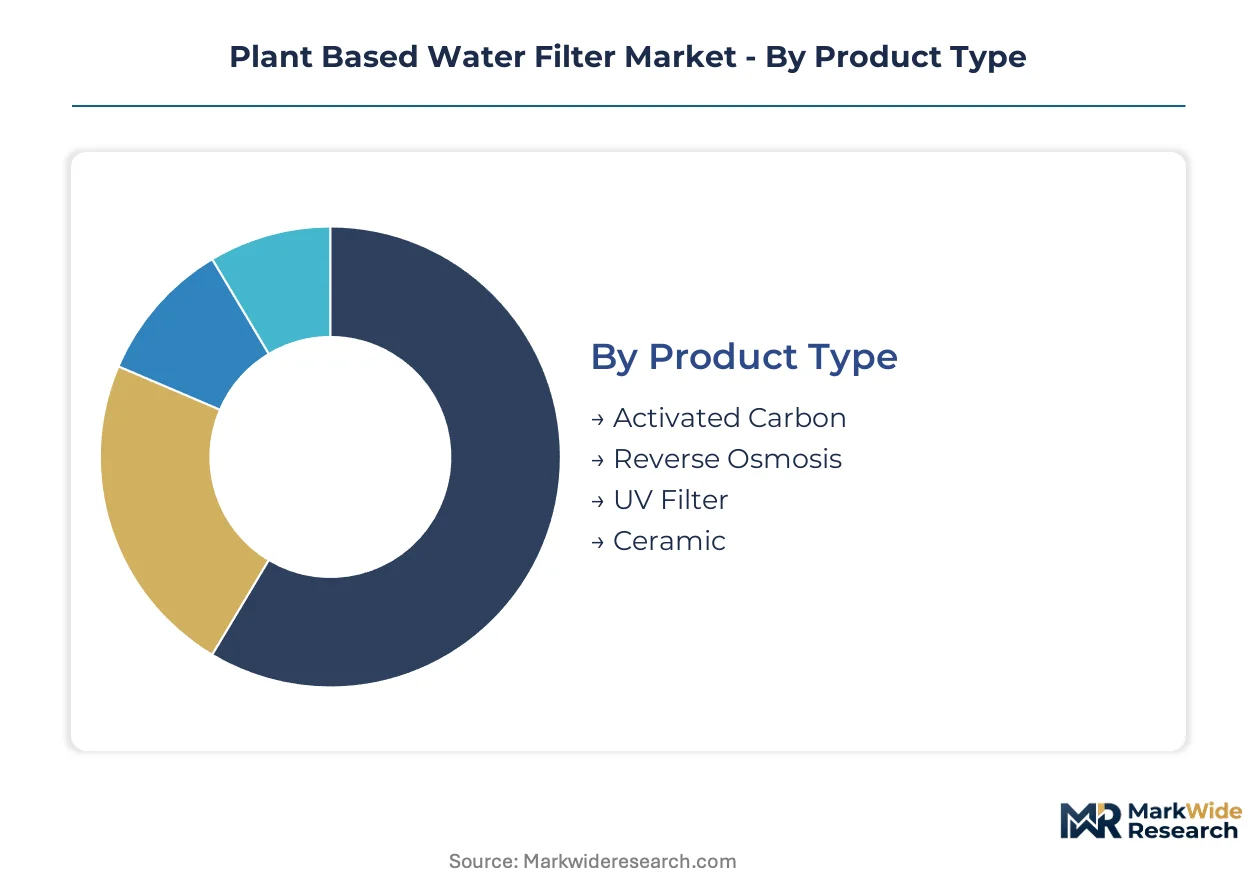
Margin capture in plant-based filtration diverges sharply by media chemistry and certification burden. Suppliers must map segment-specific qualification timelines against end-use pricing power to optimize portfolio allocation.
Product Type:
Activated carbon blocks command the widest margin pools due to established coconut-shell supply chains and NSF certification density. Ceramic and membrane alternatives face steeper cost curves but escape resin binder regulatory exposure.
- Activated Carbon:Derived from lignocellulosic precursors—coconut shell, bamboo, and hardwood—this media reduces chlorine, VOCs, and sediment through adsorption. Municipal procurement teams in Germany specify carbon blocks to meet EU Green Deal phase-out timelines for synthetic binders.
- Reverse Osmosis:Semi-permeable membranes fabricated from plant-derived substrates displace petroleum-based polyamides in select pre-treatment stages. Pharmaceutical manufacturers in Switzerland adopt these bio-polyamide alternatives for API purification, though flow-rate benchmarks lag conventional membranes.
- UV Filter:Ultraviolet sterilization modules paired with botanical pre-filtration media address bacterial compliance without chemical disinfection byproducts.
- Ceramic:Porous bio-ceramic elements fabricated from diatomaceous earth and clay mineral composites target gravity-fed residential tiers.
Activated Carbon holds installed capacity. Reverse Osmosis is rotating up the share rankings.
Application:
Volume concentration tilts toward residential replacement cycles, while commercial and industrial segments concentrate qualification value through multi-year procurement contracts.
- Residential Use:Gravity-fed housings dominate premium tiers where Korean and Japanese households prioritize zero-energy operation with integrated electrolysis mineralization. Tier-one city utilities in Mumbai retrofit legacy systems with certified carbon blocks to satisfy BIS IS 10500 turbidity mandates.
- Commercial Use:Restaurants, cafeterias, and food service operations deploy under-sink and countertop configurations with high-throughput carbon block cartridges. REACH compliance deadlines in Europe pull demand toward bio-ceramic alternatives ahead of synthetic binder phase-outs.
- Industrial Use:Pre-treatment for pharmaceutical and semiconductor manufacturing employs nanofiltration membranes with plant-derived substrates.
- Recreational:Portable and camping filtration systems utilize lightweight gravity-fed ceramic elements for backcountry water sourcing.
Residential Use anchors volume throughput. Industrial Use is climbing the fastest as membrane substrates penetrate process water applications.
Technology:
Certification intensity varies by mechanism—pressure-driven systems face tighter NSF flow-rate validation, while gravity-fed configurations escape energy compliance but confront mineral retention benchmarks.
- Filtration:Pressure-driven particulate and adsorptive separation through pleated plant-fiber geometries and carbon block cartridges. Pentair PLC compresses certification cycles through captive laboratory infrastructure.
- Electrolysis:Mineral retention modules integrated post-filtration restore ionic content for taste and health positioning. Korean and Japanese household segments drive specification of these add-on units.
- Nanofiltration:Plant-derived membrane substrates displace synthetic polyamides in selective ion rejection applications.
- Gravity-fed:Zero-energy operation through ceramic candle and carbon block configurations housed in countertop vessels.
Filtration maintains installed base dominance. Nanofiltration is gaining share fastest as bio-polyamide formulations mature.
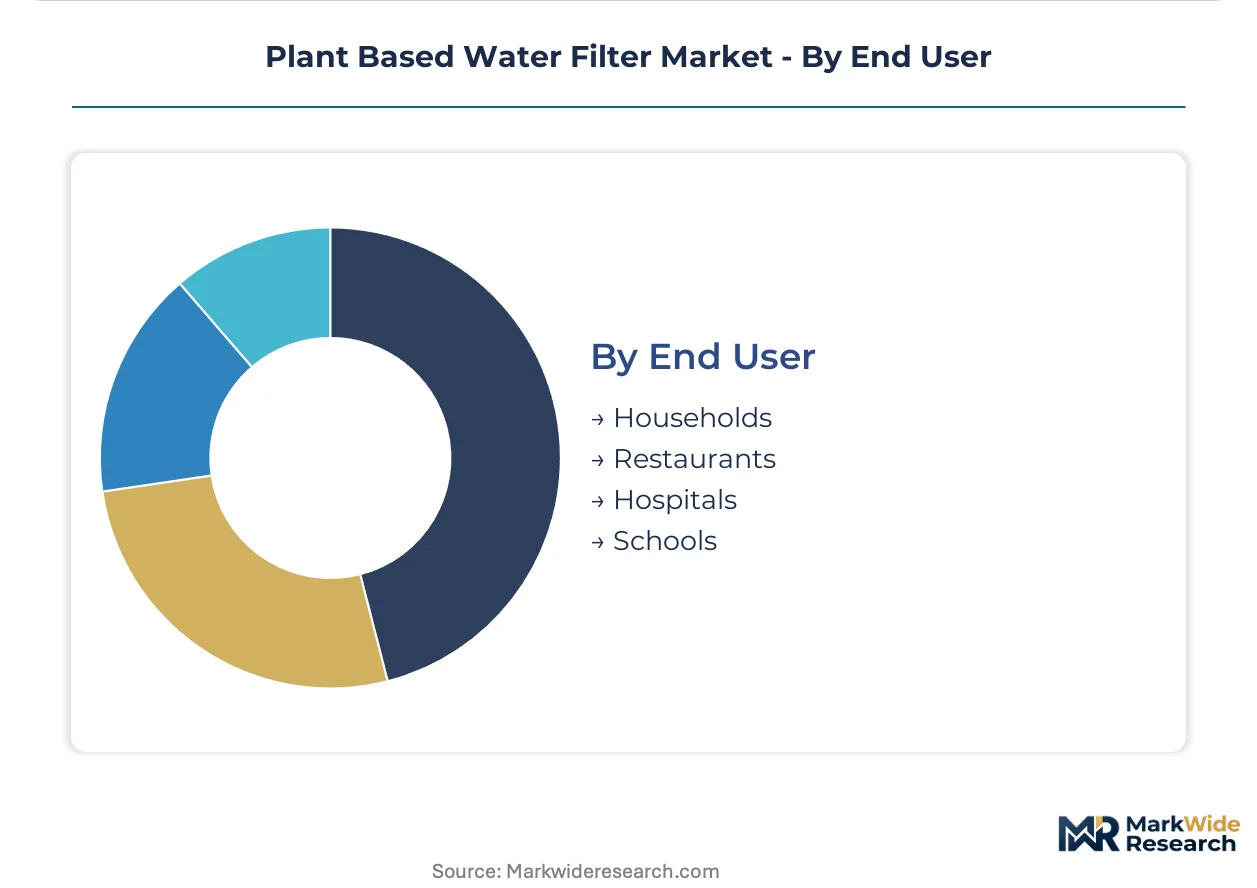
End User:
Purchasing authority fragments across facility managers, procurement committees, and individual consumers, each imposing distinct validation requirements.
- Households:Individual consumers select countertop and under-sink systems based on NSF certification badges and zero-energy claims. Japanese households prioritize mineral retention through electrolysis bundling.
- Restaurants:Food service operators specify high-capacity carbon block systems with bacterial removal validation under BIS IS 10500 or equivalent hygiene codes.
- Hospitals:Healthcare facilities demand multi-stage configurations with documented Legionella and bacterial reduction through third-party laboratory validation.
- Schools:Educational institutions retrofit drinking fountains with activated carbon blocks to meet tightening municipal water quality directives.
Households concentrate unit volume. Hospitals are ascending the value-per-installation rankings through multi-stage specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal water quality directives are tightening permissible contaminant thresholds, forcing municipal facilities to upgrade filtration infrastructure. Germany anchors European deployment volume. India's BIS certification requirements are intensifying demand in tier-one cities. East Asian households prioritize mineral retention through electrolysis integration.
Germany
Municipal water treatment facilities across North Rhine-Westphalia and Bavaria are retrofitting legacy systems with lignocellulosic media. REACH compliance deadlines for synthetic resin binder phase-outs by 2027 are pulling procurement specifications toward bio-ceramic alternatives. The Rhine-Ruhr industrial cluster is seeing expanded deployment of activated carbon blocks in municipal facilities.
India
Tier-one city utilities in Mumbai and Delhi are retrofitting legacy systems to satisfy BIS IS 10500 turbidity and bacterial removal mandates. The Bureau of Indian Standards now requires third-party laboratory validation for potable water systems. Manufacturing clusters in Maharashtra and Gujarat are expanding activated carbon block capacity to serve municipal procurement.
United States
The EPA Office of Water is establishing enforceable maximum contaminant levels for per- and polyfluoroalkyl substances under the Safe Drinking Water Act. Municipal procurement teams are evaluating bio-adsorbent formulations for PFAS compliance. Industrial pre-treatment facilities in the Great Lakes region are piloting plant-derived membrane substrates.
Japan
Household segments in the Kanto and Kansai regions are prioritizing zero-energy gravity-fed configurations with integrated electrolysis mineralization. Consumer preferences are rotating toward mineral retention modules over conventional pressure-driven systems. Tokyo-Osaka corridor retailers are bundling gravity-fed housings with mineralization add-ons.
South Korea
Residential buyers in the Seoul Capital Area are driving specification of electrolysis-integrated filtration systems for taste and health positioning. MFDS-aligned quality benchmarks are shaping product development priorities. Gyeonggi Province manufacturing clusters are scaling production of mineral retention modules for domestic and export markets.
Plant Based Water Filter Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive laboratory infrastructure and specialty filtration pure-plays with regional supply chain control. Market structure concentrates around three tiers: multinational water technology groups, integrated component suppliers, and regional membrane specialists. Dominant competitive moves include backward integration into lignocellulosic precursor sourcing and compression of NSF/ANSI certification cycles through in-house testing capacity.
Within the multinational tier, Pentair PLC and A.O. Smith Corporation exemplify divergent sourcing strategies—Pentair leverages captive testing laboratories for cycle compression while A.O. Smith anchors position through upstream control over Sri Lankan cooperative supply chains. The 3M Company occupies a distinct position among diversified technology groups, differentiating via proprietary pleated geometries that exceed flow-rate benchmarks without chemical binders.
| Leading Market Players |
|---|
| Pentair PLC |
| A.O. Smith Corporation |
| The 3M Company |
| Culligan International |
| Veolia Environnement |
| Eaton Corporation |
| Panasonic Corporation |
| Coway Co., Ltd. |
| MANN+HUMMEL |
| Others |
Value Network & Pricing Analysis
Coconut-shell carbon displacing synthetic resin binders simultaneously concentrates precursor sourcing in Sri Lankan and Indonesian cooperatives while compressing margin structures for European manufacturers facing REACH compliance deadlines. This substitution dynamic tethers pricing power to feedstock security and certification velocity rather than manufacturing scale alone.
Pricing Analysis
Certification level (NSF/ANSI 42 and 53 tier) creates the primary spread between premium and standard positioning. Three-tier pricing structure across premium, standard, and economy levels reflects validation burden, with municipal procurement teams in Germany paying premiums for accelerated qualification cycles. Cost compression in standard tiers is intensifying because smaller suppliers lack captive laboratory infrastructure to match cycle compression. Household segments in East Asia demonstrate lowest price sensitivity due to mineral retention bundling, while Indian tier-one city utilities exhibit highest sensitivity to per-unit cartridge economics.
Supply Chain Analysis
Strategic stockpiling of lignocellulosic precursors dominates inventory strategy among carbon block manufacturers confronting climate volatility in feedstock regions. Geographic supply concentration centers on Sri Lanka, Indonesia, and India for coconut-shell and bamboo precursors. Raw material dependencies rest on activated carbon feedstock, bio-ceramic mineral composites, and plant-derived membrane substrates. Single-source vulnerability from concentrated precursor harvesting regions threatens feedstock security. Distribution runs through municipal procurement committees, industrial pre-treatment facility managers, and retail channel partners serving residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, REACH, and BIS jurisdictions creates niche positioning opportunities for suppliers with jurisdiction-specific certification depth. This demand-side shift rewards specialized qualification capabilities over undifferentiated scale.
For Market Incumbents: Fortify positions through backward integration into Sri Lankan cooperative supply chains and captive NSF/ANSI testing infrastructure. Pentair PLC's laboratory compression advantage and A.O. Smith Corporation's precursor sourcing control exemplify defensible moats against emerging membrane substrate competitors. Capacity addition in South Asian manufacturing clusters anchors cost position. For New Entrants and Emerging Players: Differentiate on PFAS-compliant bio-adsorbent formulations targeting municipal procurement in US Great Lakes jurisdictions. The most penetrable white-space sits in pharmaceutical nanofiltration pre-treatment where plant-derived membrane substrates displace petroleum-based polyamides. Go-to-market angle: laboratory validation partnerships with Swiss and German pharmaceutical manufacturers. For Investors and Strategic Acquirers: The market sits at a certification-intensification phase that favors vertically integrated specialists with captive testing capacity. Long-term viability hinges on qualification pipeline ownership rather than manufacturing scale alone. Acquisition target archetype: regional membrane specialists with BIS or NSF validation depth. Signal to watch: EPA PFAS maximum contaminant level enforcement triggering municipal procurement specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Sourcing | Sri Lankan cooperative partnerships stabilize feedstock costs against climate volatility. |
| Captive NSF/ANSI Laboratory Investment | In-house testing infrastructure compresses qualification cycles below ten months. |
| PFAS-Compliant Bio-Adsorbent Development | EPA rulemaking creates municipal procurement eligibility for compliant formulations. |
| Electrolysis Module Bundling | Korean and Japanese households drive premium positioning through mineral retention. |
| Nanofiltration Membrane Substrate Scale-Up | Pharmaceutical manufacturers in Switzerland adopt plant-derived alternatives. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and municipal procurement databases. Interviews with carbon block manufacturing executives, municipal water treatment procurement officers, BIS laboratory validation specialists, and activated carbon feedstock cooperatives informed demand-side and supply-side dynamics. Secondary validation drew from EPA Office of Water guidance documents, ECHA REACH restriction timelines, BIS IS 10500 certification records, and SEC 10-K disclosures from listed water technology groups. Bottom-up unit economics triangulated against top-down market sizing across product type, application, technology, and end user segmentation.
Segmentation dimensions modeled include media chemistry (activated carbon, ceramic, membrane), application tier (residential, commercial, industrial), technology mechanism (filtration, electrolysis, nanofiltration, gravity-fed), and end user purchasing authority (households, restaurants, hospitals, schools). CAGRs were derived through regression analysis of historical certification velocity, regulatory phase-in schedules, and replacement cycle patterns. Industry-specific forecast inputs incorporated NSF/ANSI pipeline queue lengths and REACH synthetic binder phase-out compliance timelines.
Material uncertainties — regulatory acceleration in PFAS standards, climate disruption in coconut-shell harvesting regions, and third-party laboratory capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline compression and feedstock price stability. Revision becomes warranted when EPA enforcement intensity or BIS validation requirements cross thresholds that alter procurement specification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Home Water Softener System Market
Water Treatment Systems
MENA Point of Use Water Purifiers Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Solar Aerators Market
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market
Water Treatment Systems
Global Solar Water Desalination Plants Market
Water Treatment Systems
US Water Purifier Market
Water Treatment Systems
Water Treatment Ozone Generator Market
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
Global RO Water Purifier Market
Water Treatment Systems
Smart Water Softeners Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Point of Entry Water Treatment Systems Market