
 United States Membrane Bioreactor (MBR) Market | 2026-2036
United States Membrane Bioreactor (MBR) Market Size, Share, and Industry Trends Forecast 2026-2036
United States Membrane Bioreactor (MBR) Market Intelligence
Market Context
Modular skid-mounted MBR packages are repositioning how municipal buyers evaluate capital projects against conventional activated sludge upgrades. Evoqua Water Technologies leverages its integrated service network to sustain long-term operating contracts across the Midwest. Koch Membrane Systems anchors its position through captive hollow fiber manufacturing and direct membrane replacement programs. Veolia Water Technologies competes on design-build-operate frameworks that reduce upfront public expenditure.
Technical Definition and Segments
Membrane Bioreactor (MBR) systems combine suspended growth biological treatment with membrane filtration, typically operating at mixed liquor suspended solids concentrations of 8-12 g/L and producing effluent with turbidity below 0.2 NTU for direct reuse or discharge. Hollow fiber configurations lead installed capacity due to packing density advantages and air scour energy efficiency, while flat sheet membranes occupy niche applications requiring minimal pretreatment and simplified cleaning protocols. Ultrafiltration technology dominates the municipal segment where pathogen rejection governs specification, whereas reverse osmosis integration is expanding in industrial process water loops requiring dissolved solids removal beyond biological treatment.
Regulatory Outlook
EPA effluent limitation guidelines and state-level water reuse frameworks in California, Texas, and Florida shape membrane specification, testing protocols, and operator certification requirements. The Clean Water Act's evolving nutrient criteria and emerging contaminant monitoring lists are forcing utilities toward advanced treatment trains that privilege MBR's consistent effluent quality. Stakeholders must monitor pending EPA per- and polyfluoroalkyl substances rules and state direct potable reuse authorizations that will determine the next wave of membrane upgrade cycles.
Market Dynamics
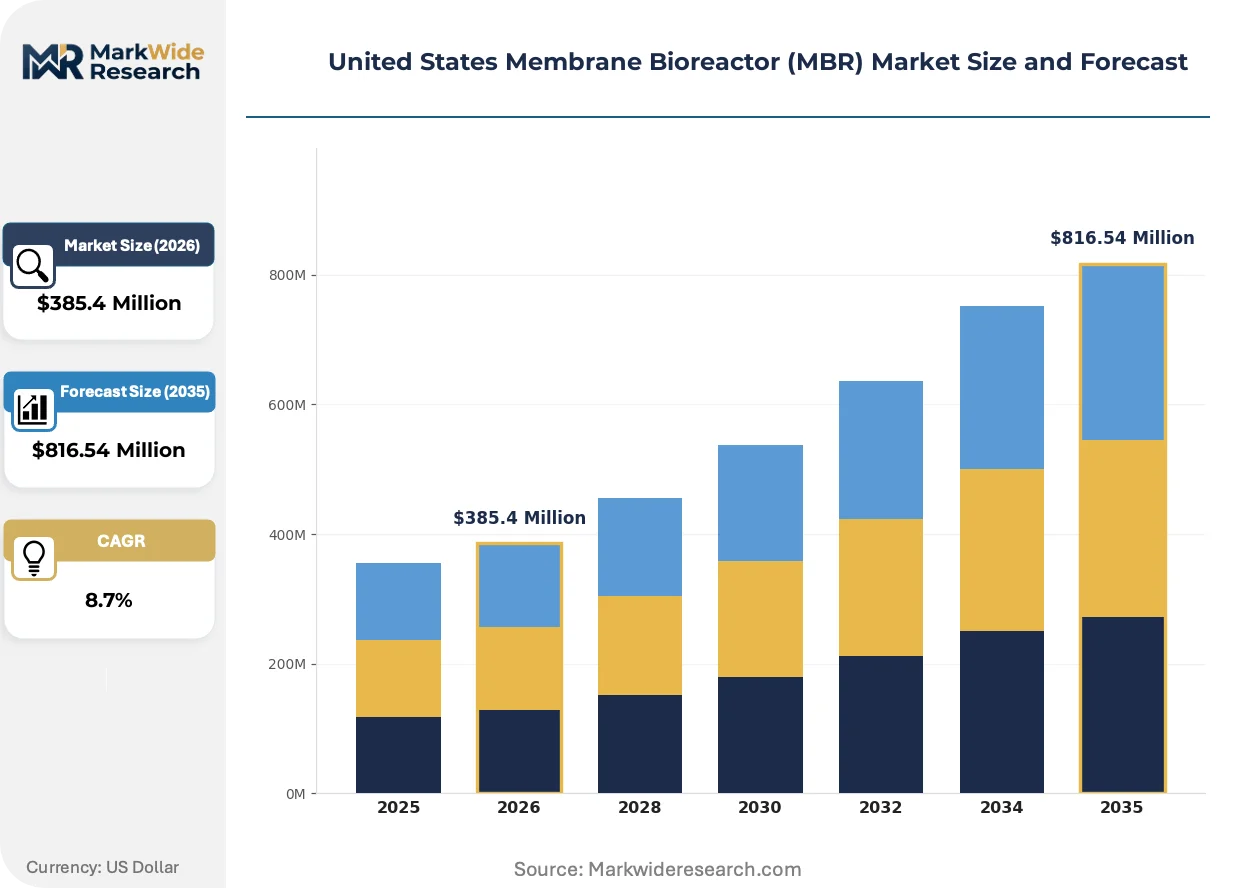
EPA effluent limitation guidelines and state-level water reuse mandates are compressing upgrade cycles for municipal wastewater infrastructure, forcing utilities toward membrane-based treatment trains that deliver consistent pathogen rejection and nutrient removal.
Growth Catalysts
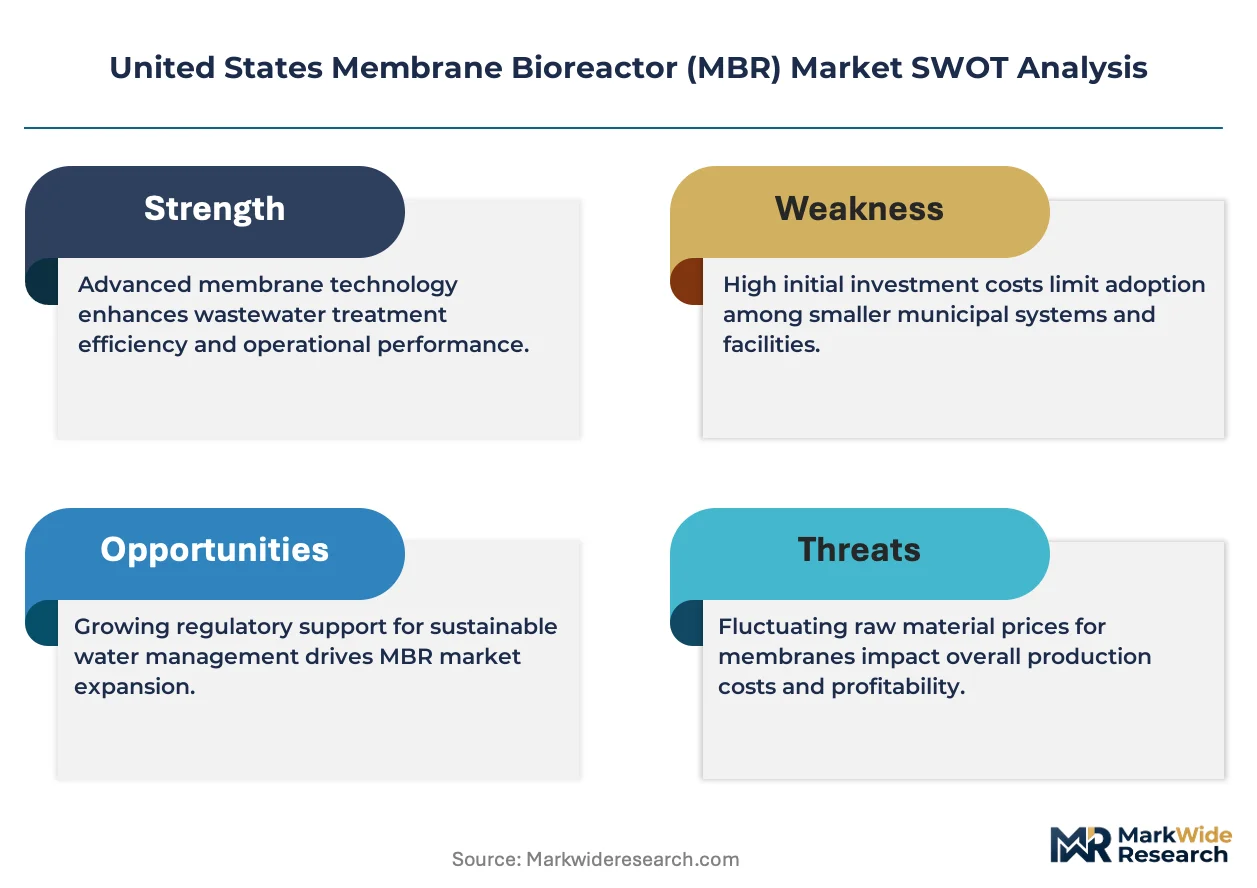
- California Title 22 Reuse Standards:Direct potable reuse authorizations in Los Angeles and San Diego counties are accelerating MBR procurement for advanced treatment trains.
- Hollow Fiber Energy Efficiency:Air scour optimization and reduced transmembrane pressure requirements are lowering lifecycle operating costs for Southwest utilities facing electricity price volatility.
- Texas Water Development Board Financing:State revolving fund allocations for non-potable reuse projects are concentrating MBR installations in the Colorado River basin.
Market Restraints
- Membrane Replacement Cost Concentration:Hollow fiber module procurement depends on limited domestic PVDF supply chains subject to petrochemical feedstock volatility.
- Technical Limitation:Fouling-resistant ceramic membranes remain cost-prohibitive for municipal scale, constraining options for high-strength industrial wastewater applications.
- Regulatory Friction:EPA's pending PFAS monitoring rules create specification uncertainty, delaying capital commitments until testing protocols stabilize.
Strategic Opportunities
- Great Plains Underpenetration:Nebraska and Kansas municipal utilities lack advanced treatment infrastructure, presenting first-mover advantages for design-build-operate frameworks.
- Industrial Process Water Convergence:MBR-RO integration for semiconductor and pharmaceutical manufacturing is expanding beyond municipal effluent reuse into captive process loops.
- Rural Package Plant Channel:Modular skid-mounted systems below 1 MGD capacity are penetrating unsewered communities through USDA Rural Development financing mechanisms.
Industry Challenges
- Membrane Operator Certification Gap:State-level wastewater operator licensing programs lack MBR-specific coursework, creating staffing bottlenecks for utilities expanding advanced treatment.
- Legacy SCADA Integration Complexity:Municipal buyers face protocol mismatches between membrane control systems and existing plant automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Membrane Bioreactor (MBR) Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hollow Fiber, Flat Sheet, Multi-tubular, Spiral Wound End User: Municipal Wastewater Treatment, Industrial Wastewater Treatment, Water Reclamation, Aquaculture Application: Wastewater Treatment, Drinking Water Treatment, Agricultural Reuse, Process Water Treatment Technology: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis |
| Companies Covered | Evoqua Water Technologies, Mitsubishi Chemical Corporation, Veolia Water Technologies, Koch Membrane Systems, TORAY INDUSTRIES, INC., Xylem Inc., SUEZ Water Technologies & Solutions, DuPont Water Solutions, Kubota Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Membrane Bioreactor (MBR) Market Strategic Shifts & Innovations
Membrane technology evolution is compressing the performance gap between biological treatment and tertiary filtration, enabling single-process solutions where multi-stage trains previously dominated.
Advanced oxidation processes are integrating with MBR effluent polishing to address emerging contaminant monitoring requirements. Pharmaceutical and personal care product rejection is becoming a specification priority for utilities in the Great Lakes region. This convergence is integrating chemical oxidation with membrane barrier functions, collapsing what were separate capital projects into unified procurement decisions.
EPA's evolving Clean Water Act nutrient criteria are mandating total nitrogen and phosphorus limits that conventional activated sludge cannot reliably achieve. The agency's forthcoming effluent limitation guidelines for municipal separate storm sewer systems are extending membrane treatment requirements to wet-weather flows. California's State Water Resources Control Board is responding with accelerated permitting pathways for MBR-based direct potable reuse, compressing project development timelines.
Design-build-operate contracting is displacing traditional engineer-procure-construct arrangements for municipal buyers seeking to transfer operational risk. Florida utilities are leading this shift, with Tampa Bay Water and Miami-Dade adopting long-term service agreements that bundle membrane replacement and energy optimization. This restructuring concentrates vendor relationships around integrated service networks rather than equipment supply alone.
United States Membrane Bioreactor (MBR) Market Segmentation
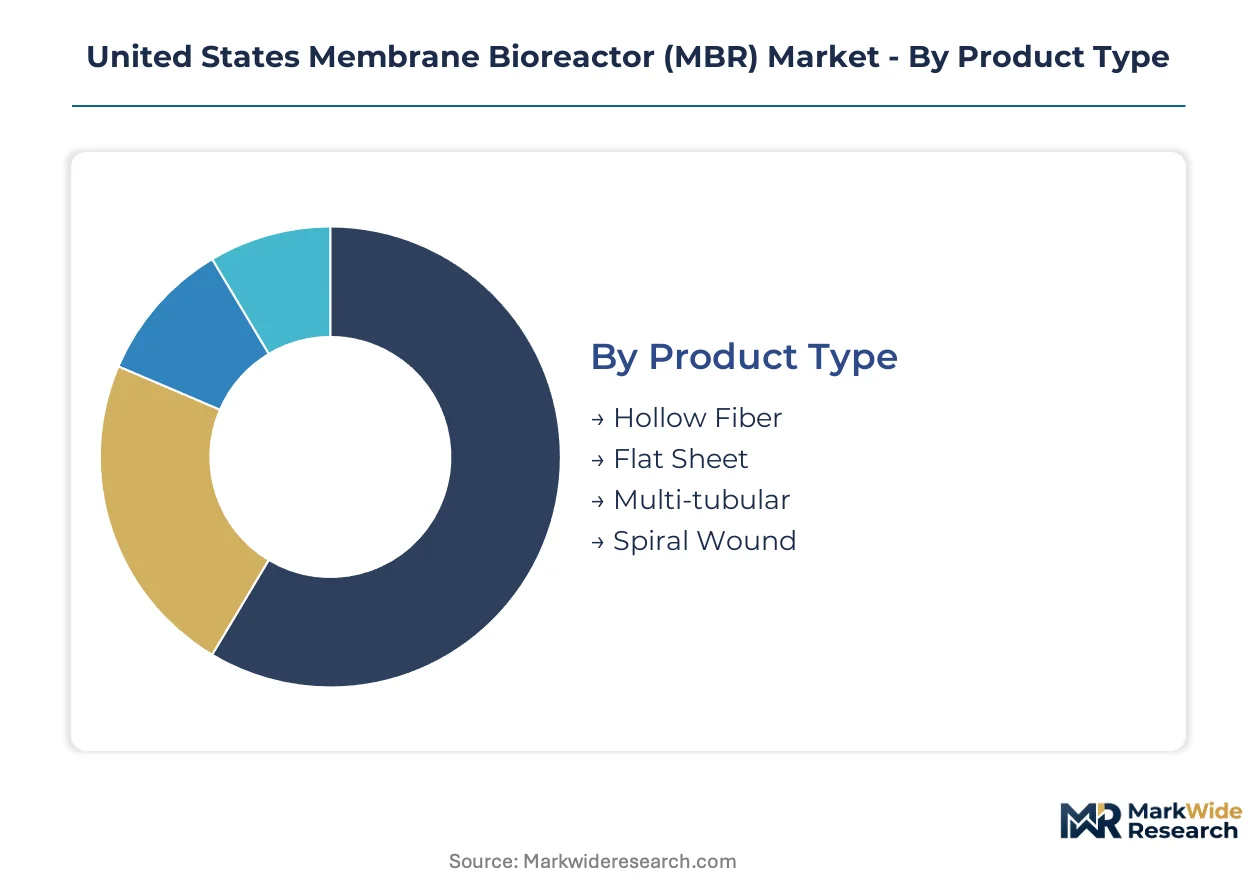
MBR procurement decisions fragment across membrane geometry, end-use requirements, and filtration specifications. Each dimension carries distinct capital intensity and operational complexity profiles that reshape vendor positioning and utility specification priorities.
Product Type:
Standalone membrane configurations dominate municipal procurement, while embedded systems integrate into compact industrial skids.
- Hollow Fiber:Dense PVDF fiber bundles operate at high packing density with air scour energy requirements below competing geometries. California and Texas municipal utilities specify hollow fiber for Title 22 reuse compliance, prioritizing footprint reduction and lifecycle electricity cost control.
- Flat Sheet:Rigid plate-and-frame assemblies tolerate higher suspended solids loading with minimal pretreatment infrastructure. Food and beverage processors in the Midwest deploy flat sheet MBRs for high-strength organic waste streams where chemical cleaning frequency must stay low.
- Multi-tubular:Ceramic or polymeric tubes handle abrasive industrial effluents with aggressive backwash protocols.
- Spiral Wound:Compact spiral configurations concentrate in space-constrained retrofit applications and mobile treatment units.
Volume placements concentrate in Hollow Fiber; the faster expansion belongs to Flat Sheet.
End User:
Cost tier stratification separates capital-intensive municipal projects from operational-expense-focused industrial adopters.
- Municipal Wastewater Treatment:City and county utilities deploy MBR to meet EPA effluent limitation guidelines and state nutrient criteria. The Southwest and Great Plains regions drive procurement as water scarcity intensifies reuse mandates.
- Industrial Wastewater Treatment:Manufacturing facilities face pretreatment standards and zero-liquid-discharge requirements. Semiconductor fabs and pharmaceutical plants specify MBR-RO trains for process water recovery.
- Water Reclamation:Direct potable reuse pilots in Los Angeles and San Diego counties accelerate advanced treatment procurement.
- Aquaculture:Recirculating aquaculture systems in Florida and coastal regions deploy compact MBR for biofloc management and effluent polishing.
Municipal Wastewater Treatment anchors procurement volume; Water Reclamation climbs the fastest as direct potable reuse frameworks mature.
Application:
Application scope spans discharge compliance through resource recovery, with specification intensity varying by effluent destination.
- Wastewater Treatment:Biological nutrient removal combined with membrane barrier delivers consistent effluent for surface water discharge. EPA Clean Water Act enforcement and evolving total nitrogen limits force conventional plant upgrades toward MBR trains.
- Drinking Water Treatment:Direct potable reuse and indirect potable reuse applications demand multi-barrier treatment with advanced oxidation. California State Water Resources Control Board permitting pathways compress project timelines for utilities pursuing groundwater replenishment.
- Agricultural Reuse:Irrigation-quality effluent production concentrates in Central Valley districts facing groundwater sustainability mandates.
- Process Water Treatment:Captive industrial loops in power generation and data centers require ultrapure feedwater with minimal dissolved organic carbon.
Wastewater Treatment dominates installed base; Drinking Water Treatment gains share fastest under state direct potable reuse authorizations.
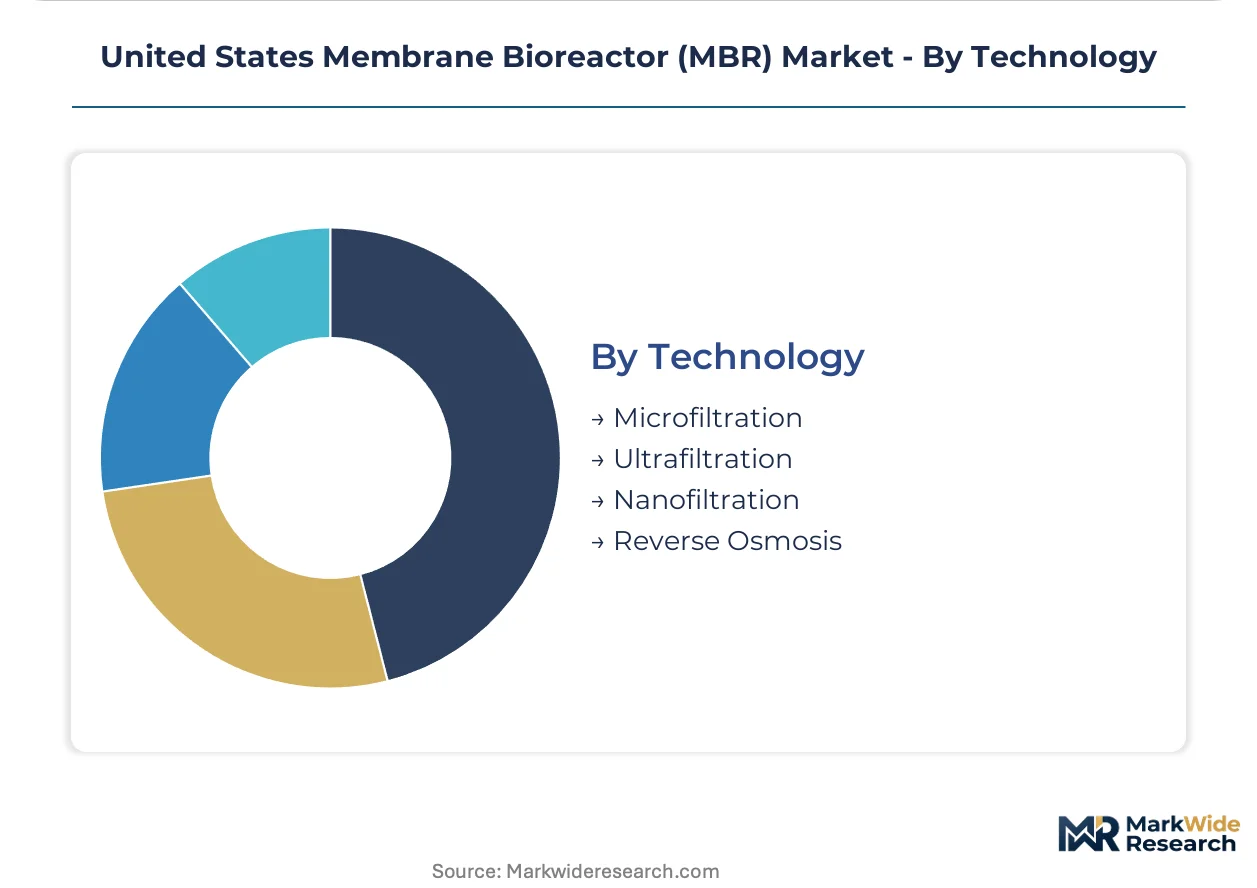
Technology:
Technology selection follows pore size requirements from solids separation through dissolved contaminant rejection.
- Ultrafiltration:Nominal 0.01-0.1 micron pore structures reject bacteria, viruses, and colloidal material without chemical disinfection. Municipal MBR specifications default to ultrafiltration for pathogen barrier compliance and direct reuse eligibility.
- Microfiltration:Larger 0.1-10 micron pores target suspended solids and protozoa removal at lower transmembrane pressure. Pretreatment-heavy industrial applications specify microfiltration MBR where downstream reverse osmosis handles dissolved constituents.
- Nanofiltration:Divalent ion and organic molecule rejection suits softening and micropollutant control in specialized reuse schemes.
- Reverse Osmosis:Desalination-grade membranes integrate downstream of biological treatment for dissolved solids removal in process water and potable reuse trains.
Ultrafiltration captures the largest deployment share; Reverse Osmosis integration expands most quickly for industrial process loops and advanced potable reuse.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in distressed census tracts are concentrating MBR manufacturing and service facilities near municipal anchor customers across the Southwest and Great Plains, accelerating capital deployment into water-stressed regions.
Southwest
California and Arizona utilities drive procurement for direct potable reuse compliance. EPA Clean Water Act enforcement and California State Water Resources Control Board permitting compress project timelines. Los Angeles and San Diego counties host the nation's most advanced MBR-based groundwater replenishment installations.
Texas and the Colorado River Basin
State revolving fund allocations from the Texas Water Development Board finance non-potable reuse infrastructure. Municipal utilities in Austin, San Antonio, and El Paso specify hollow fiber configurations for Title 22 compliance. The basin's agricultural districts face groundwater sustainability mandates requiring advanced treatment.
Great Plains
Nebraska and Kansas municipal utilities lack advanced treatment infrastructure, creating first-mover advantages for design-build-operate frameworks. USDA Rural Development financing mechanisms enable modular skid-mounted systems below 1 MGD capacity. Unsewered communities in Oklahoma and Kansas represent underpenetrated demand.
Florida and the Southeast
Tampa Bay Water and Miami-Dade anchor long-term service agreements bundling membrane replacement and energy optimization. Florida utilities lead the shift from engineer-procure-construct to design-build-operate contracting. The state's aquaculture operations deploy compact MBR for recirculating systems and effluent polishing.
Pacific Northwest
Semiconductor fabs and data centers in Oregon and Washington specify MBR-RO trains for ultrapure process water. Industrial zero-liquid-discharge requirements concentrate demand in Portland and Seattle metro areas. The region's hydropower pricing advantages reduce lifecycle electricity cost sensitivity.
United States Membrane Bioreactor (MBR) Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across membrane supply and system integration tiers. The market exhibits moderate consolidation around integrated service networks and captive membrane manufacturing. Three archetypes dominate: diversified water technology conglomerates with global service footprints, specialized membrane manufacturers with direct replacement programs, and regional system integrators pursuing design-build-operate contracts. M&A activity targets service network density, while technology licensing agreements expand geographic coverage without capital-intensive manufacturing investment.
Among diversified water technology conglomerates, Evoqua Water Technologies and Veolia Water Technologies exemplify the integrated service network archetype, anchoring long-term operating contracts across municipal and industrial segments. Koch Membrane Systems occupies a position within the specialized membrane manufacturing tier, representing captive hollow fiber production capabilities. These three companies illustrate the competitive tension between equipment supply margins and recurring service revenue streams.
| Leading Market Players |
|---|
| Evoqua Water Technologies |
| Mitsubishi Chemical Corporation |
| Veolia Water Technologies |
| Koch Membrane Systems |
| TORAY INDUSTRIES, INC. |
| Xylem Inc. |
| SUEZ Water Technologies & Solutions |
| DuPont Water Solutions |
| Kubota Corporation |
| Others |
Cost & Logistics Intelligence
PVDF resin feedstock volatility propagates through hollow fiber membrane manufacturing into municipal procurement tiers, with Southwest utilities bearing electricity-indexed operating cost premiums that reshape lifecycle evaluation frameworks against conventional activated sludge alternatives.
Pricing Analysis
Margin tightening in municipal project bidding reflects compressed capital cycles driven by EPA effluent limitation guideline enforcement. Three-tier pricing structure across integrated design-build-operate bundles, standalone equipment procurement, and aftermarket membrane replacement programs separates vendor relationships by contract duration and service depth. Hollow fiber configurations command premiums over flat sheet alternatives due to packing density advantages and air scour efficiency, though ceramic membrane alternatives remain cost-prohibitive for scale. Industrial semiconductor and pharmaceutical adopters exhibit lowest price sensitivity, prioritizing process water reliability over capital expenditure minimization.
Supply Chain Analysis
NSF/ANSI 61 and Title 22 certification requirements gate domestic membrane module supply, concentrating qualified manufacturing in Japan, Germany, and the United States for hollow fiber PVDF production. Raw material dependencies center on petrochemical-derived fluoropolymers, specialized epoxy potting compounds, and precision extrusion equipment. Single-source vulnerability persists in high-purity PVDF resin supply from limited domestic chemical producers. Distribution runs through direct OEM channels for large municipal projects and regional system integrators for sub-1 MGD package plant deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States MBR market functions as a cost-of-compliance arena where EPA Clean Water Act nutrient criteria and emerging PFAS monitoring rules erect regulatory moats favoring incumbent players with established testing protocols and operator certification programs.
For Market Incumbents: Cement service network density across the Great Plains through design-build-operate frameworks that transfer operational risk from municipal buyers. Lock in long-term membrane replacement contracts with Southwest utilities facing electricity price volatility, while investing in ceramic membrane R&D to preempt fouling-resistant alternatives. Threat substitution from advanced oxidation process integration demands defensive positioning in emerging contaminant treatment trains. For New Entrants and Emerging Players: California's direct potable reuse authorization pathway opens a window for specialized advanced oxidation-MBR integration specialists in Los Angeles and San Diego counties. Target unsewered rural communities in Nebraska and Kansas through USDA Rural Development financing mechanisms for modular skid-mounted systems below 1 MGD. White-space concentration in Great Plains municipal infrastructure lacks incumbent service coverage, enabling first-mover design-build-operate positioning without direct competitive confrontation. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional system integrators with captive membrane replacement revenue streams in Texas and Florida municipal markets. Long-term viability hinges on exposure to state revolving fund allocation trajectories and direct potable reuse regulatory maturation. Watch EPA PFAS effluent limitation guideline finalization as the signal triggering accelerated membrane upgrade procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build-Operate Contract Expansion | Florida utilities lead long-term service agreements bundling membrane replacement with energy optimization. |
| Ceramic Membrane R&D Investment | Fouling-resistant alternatives address high-strength industrial wastewater applications currently cost-prohibitive for scale. |
| Great Plains Service Network Buildout | Nebraska and Kansas municipal infrastructure gaps create first-mover advantages without incumbent competition. |
| Advanced Oxidation Process Integration | California's emerging contaminant requirements collapse separate capital projects into unified MBR procurement decisions. |
| Rural Package Plant Channel Development | USDA Rural Development financing mechanisms enable sub-1 MGD modular system penetration in unsewered communities. |
Research Approach
Independent corroboration across EPA enforcement action databases, state water reuse permit filings, and municipal procurement records underwrites the qualitative findings. Primary interviews with wastewater utility directors, membrane system operators, state revolving fund administrators, and design-build-operate contract managers combined with secondary validation from SEC 10-K filings of publicly traded water technology conglomerates, Texas Water Development Board financing disclosures, and California State Water Resources Control Board permitting data. Bottom-up installation tracking and top-down market sizing triangulate volume estimates.
Historical reference periods anchor the projection horizon to documented upgrade cycle compression following EPA effluent limitation guideline revisions. Segmentation modeling spans membrane geometry, end-use category, application scope, and filtration technology across the analysis window. CAGRs derive from utility capital expenditure trajectories, state financing allocation patterns, and regulatory compliance deadline clustering. Forecast inputs incorporate electricity price volatility indices for Southwest markets and petrochemical feedstock cost movements affecting PVDF resin pricing.
The model assumes a particular technology adoption path; alternative pathways for ceramic membrane cost reduction would alter the outlook. Forecasts reflect assumptions regarding EPA PFAS rule finalization timing and state direct potable reuse authorization velocity. A model refresh is warranted upon material change in federal infrastructure spending allocation or hollow fiber membrane import tariff structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Commercial Atmospheric Water Generator Market
Water and Wastewater Treatment
Wastewater Clarifier Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
Water Testing Meter Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Mobile Wastewater Treatment Plant Market
Water and Wastewater Treatment
Global Biological Wastewater Treatment Market
Water and Wastewater Treatment
Backwash Pre-Filters Market
Water and Wastewater Treatment
US Wastewater Secondary Treatment Equipment Market
Water and Wastewater Treatment
Global Wastewater Treatment Services Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market
Water and Wastewater Treatment
Packaged Wastewater Treatment Market
Water and Wastewater Treatment
Sludge Dewatering Equipment Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Aeration Pads Market