
 Wastewater Clarifier Market | 2026-2036
Wastewater Clarifier Market Size, Share, and Industry Trends Forecast 2026-2036
Wastewater Clarifier Market Insights
European equipment manufacturers is recalibrating output schedules after supply chain disruptions in specialty steel and polymer feedstocks. Veolia Water Technologies leverages its integrated service model across municipal and industrial contracts. SUEZ sustains competitive positioning through geographic dominance in France and extended Middle Eastern operations. Evoqua Water Technologies differentiates via technology leadership in high-rate clarification systems for power and microelectronics end users.
A wastewater clarifier separates suspended solids from liquid effluent through gravity settling, flotation, or inclined plate separation, typically achieving overflow rates of 0.5 to 1.5 gallons per minute per square foot in conventional designs. The unit serves as the primary solids-liquid separation stage upstream of biological or tertiary treatment processes. Lamella clarifiers and plate settlers command margin pools in retrofit applications where footprint constraints dominate project economics. Dissolved air flotation systems represent the fastest-growing product category in oil and gas and food processing effluent streams where low-density solids resist gravity settling.
EPA effluent limitation guidelines and the EU Urban Wastewater Treatment Directive shape equipment specifications and upgrade cycles across municipal and industrial installations. China's MEE enforcement of Class A discharge standards and India's CPCB mandates for zero liquid discharge in textile and tannery clusters are redirecting procurement toward hybrid biological-chemical clarification trains. Stakeholders must monitor regulatory divergence between jurisdictions to align product certification roadmaps with divergent compliance timelines.
Market Dynamics
Clarifier procurement is tightening around footprint-constrained retrofits as municipal utilities face EPA consent decrees mandating phosphorus removal without expanding plant boundaries. Equipment vendors now compete on hydraulic capacity per square meter rather than unit cost alone.
Growth Catalysts
- EU Urban Wastewater Treatment Directive:Germany and France enforce tertiary nutrient removal mandates that force lamella clarifier upgrades at aging facilities.
- China's MEE Class A standards:Industrial zones in Jiangsu and Zhejiang provinces must achieve near-zero suspended solids discharge, accelerating dissolved air flotation deployments.
- Oil and gas produced water volumes:Permian Basin operators require high-rate clarification for reuse in hydraulic fracturing operations.
Market Restraints
- Specialty steel input volatility:Stainless steel plate packs for lamella systems face price swings tied to nickel supply from Indonesian smelters.
- Polymer feedstock concentration:Coagulant and flocculant supply chains cluster in Gulf Coast petrochemical corridors, exposing buyers to hurricane disruption.
- Gravity settling velocity limits:Conventional circular clarifiers cannot capture oil droplets below specific gravity differentials, forcing capital-intensive DAF substitutions.
Strategic Opportunities
- India's CPCB zero liquid discharge clusters:Tiruppur textile and Kanpur tannery districts mandate closed-loop water systems, opening hybrid biological-chemical clarification markets.
- Power plant cooling tower blowdown reuse:High-rate ballasted sedimentation systems enable zero-discharge compliance at combined-cycle gas facilities.
- Remote monitoring integration:IoT sludge level sensors and predictive rake torque analytics create aftermarket service revenue streams.
Industry Challenges
- Process control engineering scarcity:Municipal utilities lack personnel trained in dissolved oxygen and solids flux modeling for optimized clarifier operation.
- Legacy SCADA integration:Brownfield installations require protocol bridging between proprietary DAF controls and existing plant automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wastewater Clarifier Market |
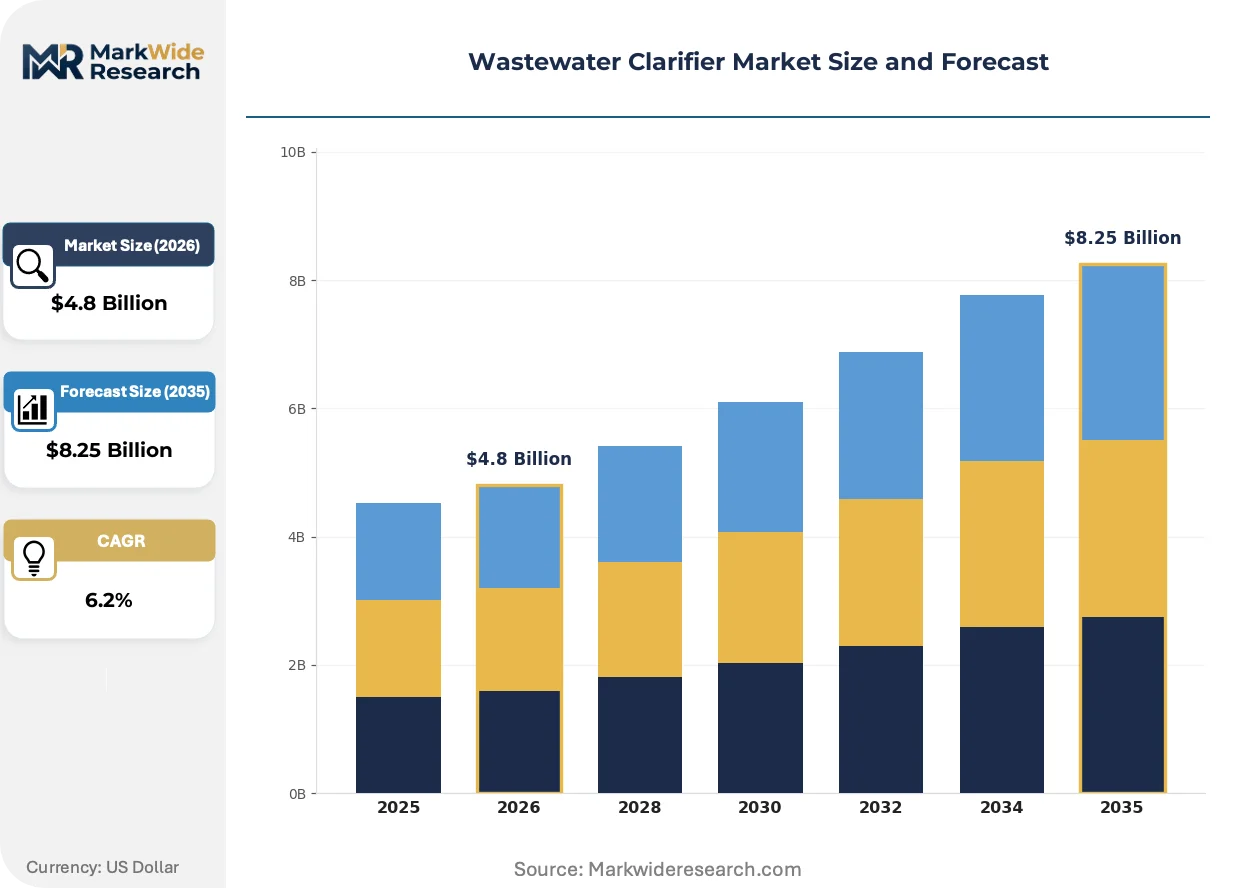
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Settling Tanks, Dissolved Air Flotation, Lamella Clarifiers, Plate Settlers Application: Industrial Wastewater, Municipal Applications, Oil & Gas Industry, Agricultural Runoff Technology: Biological Treatment, Chemical Treatment, Physical Treatment, Hybrid Systems End User: Manufacturing Plants, Water Treatment Facilities, Food & Beverage Industry, Pharmaceutical Companies |
| Companies Covered | Veolia Water Technologies, SUEZ, Evoqua Water Technologies, BASF SE, Ecolab Inc., Xylem Inc., Kurita Water Industries Ltd., Kemira Oyj, SNF Floerger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wastewater Clarifier Market Trends and Innovations
Digital twin modeling and advanced materials are compressing clarifier design cycles while regulatory tightening forces convergence between biological and physical treatment stages. Vendors now bundle real-time performance guarantees with equipment supply.
Membrane bioreactor pretreatment clarification is decentralizing solids handling from centralized gravity thickeners to satellite high-rate units. Food and beverage processors in California adopt compact inclined plate settlers to protect downstream ultrafiltration membranes from fouling. This distributed architecture reduces polymer consumption by isolating high-strength waste streams at source.
EPA effluent limitation guidelines for steam electric power generation are forcing coal ash pond closures and direct discharge elimination. Utilities in Ohio and Pennsylvania retrofit existing basins with tube settlers and ballasted flocculation to meet selenium and nitrate limits. Equipment suppliers now engineer for seasonal temperature swings that alter settling velocities.
Microelectronics fabs in Taiwan and South Korea are unbundling clarifier maintenance from capital purchase contracts. Foundry operators demand guaranteed suspended solids performance with penalty clauses, transferring operational risk to Veolia and SUEZ service divisions. This performance-based contracting compresses vendor margins while locking in decade-long replacement part revenue.
Wastewater Clarifier Market Segmentation
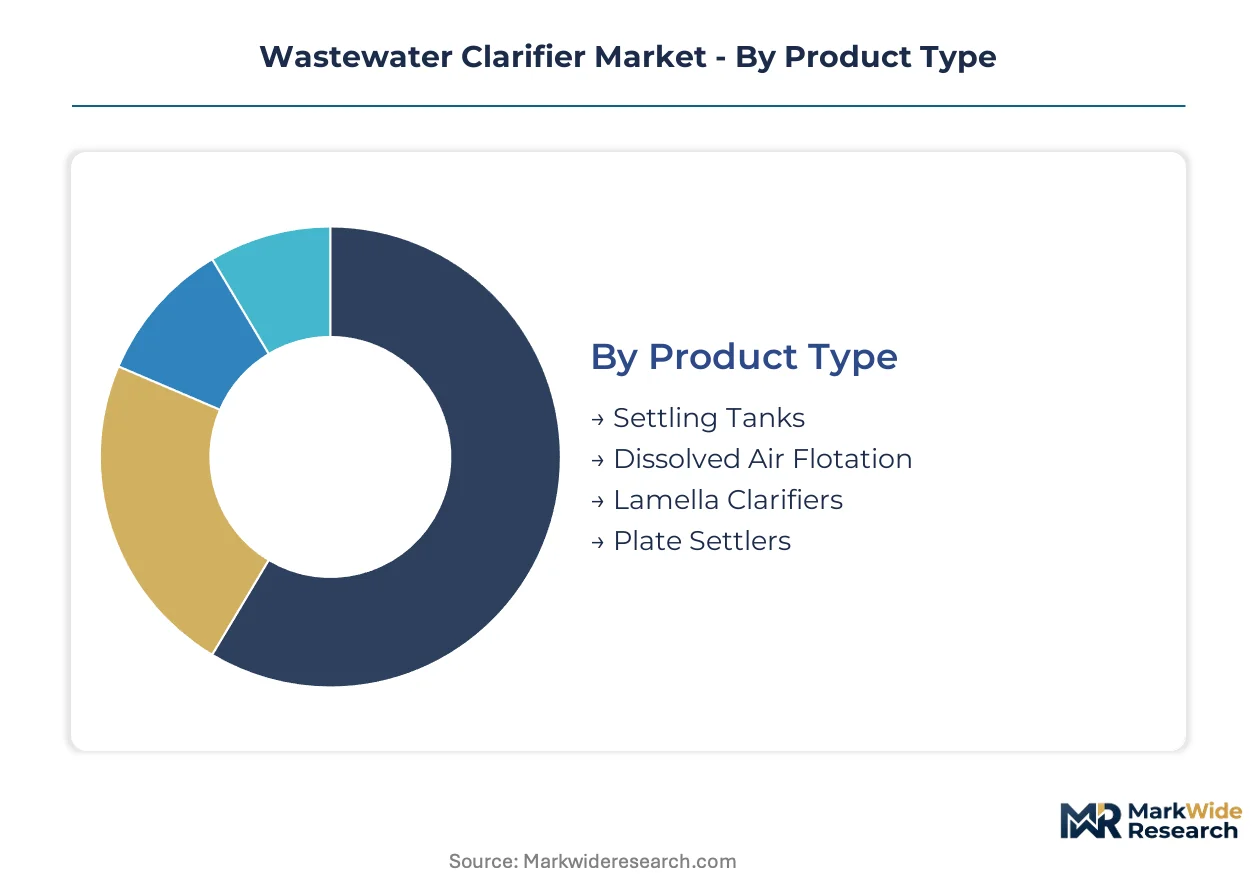
Clarifier procurement diverges sharply across product architectures and end-use chemistry. Equipment specification hinges on suspended solids density, hydraulic loading rates, and regulatory discharge limits rather than unit cost alone.
Product Type:
Specialty steel fabricators concentrate lamella plate production in German and Japanese industrial corridors, creating geographic supply dependencies for high-specification units.
- Dissolved Air Flotation:Pressurized air injection generates micro-bubbles that attach to low-density solids, achieving separation velocities impossible in gravity systems. Oil and gas produced water treatment in the Permian Basin and food processing effluent in California's Central Valley are concentrating procurement as EPA discharge limits tighten for fats, oils, and grease.
- Lamella Clarifiers:Inclined plate packs multiply effective settling area within compact footprints, enabling retrofit installations where municipal plants face consent decree deadlines without boundary expansion. German municipalities facing EU Urban Wastewater Treatment Directive nutrient mandates represent the densest installed base of aging units requiring upgrade.
- Settling Tanks:Conventional circular and rectangular gravity settlers dominate municipal primary treatment stages across legacy infrastructure in the United States and India.
- Plate Settlers:Tube and plate configurations protect downstream membrane systems in high-purity industrial water recycling loops.
Today's leader: Lamella Clarifiers. Tomorrow's challenger: Dissolved Air Flotation.
Application:
Cost tier stratification separates capital-intensive industrial installations from municipal procurement cycles governed by EPA consent decree timelines.
- Industrial Wastewater:Heavy metals, chemical oxygen demand, and temperature extremes demand corrosion-resistant materials and automated sludge removal. China's Jiangsu and Zhejiang province industrial clusters under MEE Class A enforcement are expanding dissolved air flotation capacity fastest.
- Municipal Applications:Phosphorus removal mandates without plant expansion are forcing high-rate clarification retrofits. United States utilities in Ohio and Pennsylvania retrofit existing basins with tube settlers to meet selenium and nitrate limits from coal ash pond closures.
- Oil & Gas Industry:Produced water volumes in Texas and New Mexico require clarification for hydraulic fracturing reuse, with suspended solids specifications below 25 mg/L.
- Agricultural Runoff:Nutrient recovery from dairy and poultry operations concentrates demand in the Chesapeake Bay watershed and Netherlands dairy regions.
Industrial Wastewater commands premium pricing. Municipal Applications drive volume scale.
Technology:
Customer type bifurcation separates engineering-procurement-construction firms specifying hybrid trains from municipal operators defaulting to physical separation.
- Hybrid Systems:Biological-chemical-physical process integration achieves zero liquid discharge in India's Tiruppur textile and Kanpur tannery clusters under CPCB mandates. Ballasted flocculation combined with high-rate sedimentation enables power plant cooling tower blowdown reuse.
- Physical Treatment:Gravity settling and flotation remain the default for primary solids separation where downstream biological treatment handles dissolved organics.
- Chemical Treatment:Coagulation and flocculation upstream of clarification targets phosphorus precipitation and heavy metals removal.
- Biological Treatment:Activated sludge clarification integrates return activated sludge management with solids-liquid separation.
Hybrid Systems are climbing the fastest. Physical Treatment retains installed base dominance.
End User:
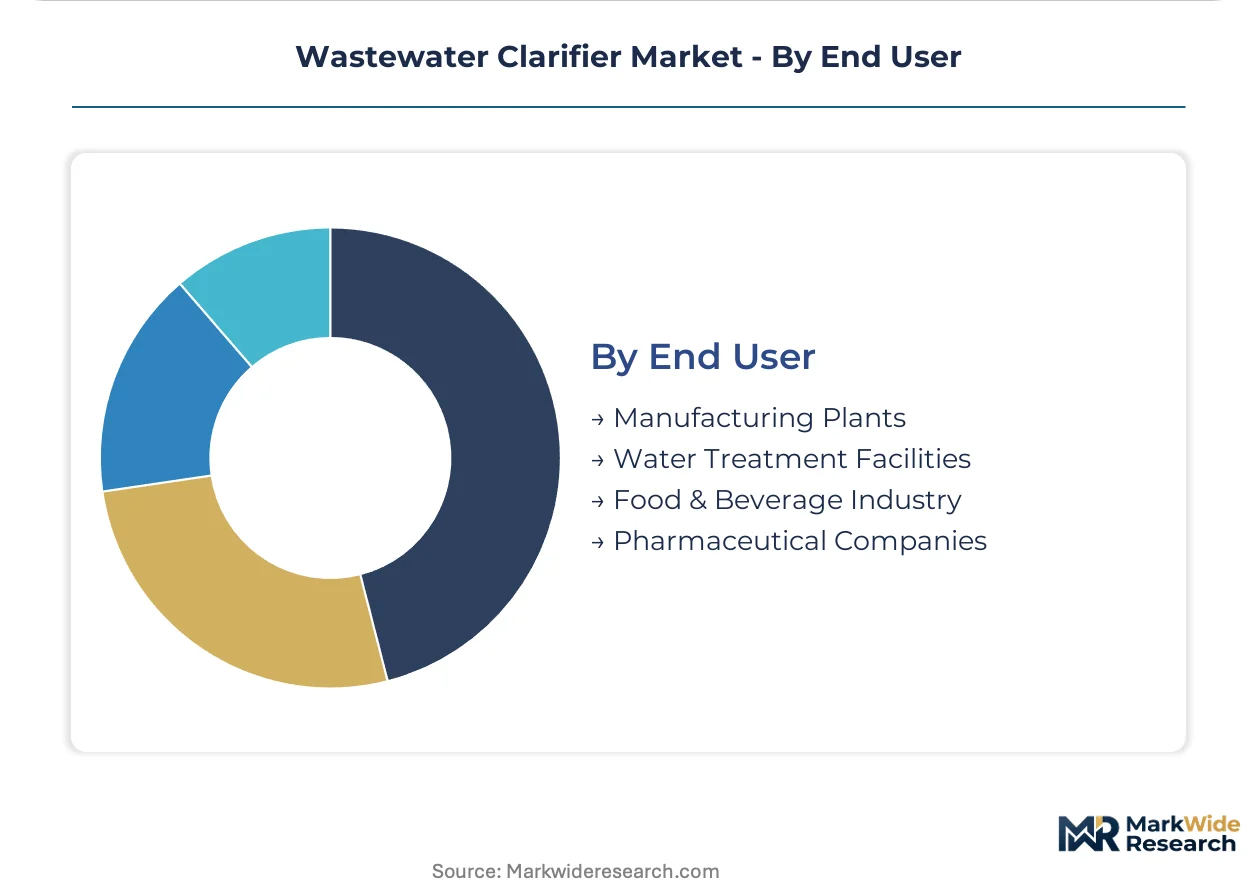
Margin concentration pools in pharmaceutical and microelectronics specifications demanding guaranteed performance contracting with penalty clauses.
- Water Treatment Facilities:Municipal utilities in France, Germany, and the United States represent the largest installed base with cyclical upgrade demand tied to regulatory enforcement waves.
- Pharmaceutical Companies:Active pharmaceutical ingredient manufacturing in Ireland and Switzerland requires validated clarification systems with complete documentation for FDA and EMA compliance.
- Manufacturing Plants:Automotive and electronics fabrication in Taiwan and South Korea specify compact footprint systems for process water recycling.
- Food & Beverage Industry:California processors adopt inclined plate settlers to protect ultrafiltration membranes from high-strength organic fouling.
Water Treatment Facilities anchor volume. Pharmaceutical Companies extract premium margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE enforcement drives faster upgrade cycles than Germany's EU-mandated retrofits, while US utilities face consent decree deadlines without boundary expansion options. Each geography shapes procurement through distinct regulatory mechanisms and industrial cluster concentrations.
United States
Ohio and Pennsylvania utilities retrofit existing basins with tube settlers to meet selenium and nitrate limits from coal ash pond closures. EPA effluent limitation guidelines for steam electric power generation force direct discharge elimination. Municipal plants in the Chesapeake Bay watershed deploy high-rate clarification for phosphorus removal without expanding plant boundaries.
Germany
Municipalities face EU Urban Wastewater Treatment Directive nutrient mandates requiring lamella clarifier upgrades at aging facilities. Specialty steel fabricators concentrate plate production in industrial corridors, creating supply dependencies for high-specification units. The Ruhr region's legacy infrastructure drives cyclical replacement demand tied to enforcement waves.
China
Jiangsu and Zhejiang province industrial clusters under MEE Class A enforcement expand dissolved air flotation capacity fastest. The Ministry of Ecology and Environment enforces stricter wastewater reuse targets across industrial zones. Near-zero suspended solids discharge requirements accelerate hybrid biological-chemical clarification train procurement.
India
Tiruppur textile and Kanpur tannery districts under CPCB mandates mandate closed-loop water systems, opening hybrid biological-chemical clarification markets. Zero liquid discharge requirements redirect procurement toward integrated process trains. Maharashtra's pharmaceutical manufacturing corridor generates secondary demand for validated clarification systems.
France
SUEZ sustains competitive positioning through geographic dominance in municipal contracts and extended Middle Eastern operations. Tightening nutrient removal regulations force upgrades to lamella and dissolved air flotation systems. The country's integrated service model influences procurement patterns across adjacent jurisdictions.
Wastewater Clarifier Market Competitive Landscape
German and French producers anchor one tier; US specialists hold another through technology differentiation in high-rate systems. The market structures around integrated service providers, chemical-technology hybrids, and pure-play equipment fabricators. Three archetypes dominate: full-service water management conglomerates, specialty chemical-technology integrators, and regional stainless steel fabricators. Consolidation pressures favor M&A among mid-cap fabricators while technology licensing agreements proliferate between chemical suppliers and equipment vendors.
Within the full-service tier, Veolia Water Technologies and SUEZ exemplify geographic anchoring strategies, with the former leveraging integrated service models across municipal and industrial contracts. Evoqua Water Technologies occupies a position emphasizing technology leadership in high-rate clarification. BASF SE and Ecolab Inc. represent the chemical-technology hybrid archetype, bundling coagulant supply with process design expertise. Xylem Inc. and Kurita Water Industries Ltd. anchor the equipment-chemical convergence segment.
| Leading Market Players |
|---|
| Veolia Water Technologies |
| SUEZ |
| Evoqua Water Technologies |
| BASF SE |
| Ecolab Inc. |
| Xylem Inc. |
| Kurita Water Industries Ltd. |
| Kemira Oyj |
| SNF Floerger |
| Others |
Pricing and Supply Chain Analysis
Municipal utilities under EPA consent decree deadlines concentrate procurement around guaranteed performance contracts rather than capital expenditure minimization, compressing vendor margins while extending service revenue lock-in periods. Equipment suppliers respond with tiered pricing structures that separate premium lamella systems with real-time monitoring from standard gravity settlers.
Pricing Analysis
Capacity additions in China's Jiangsu and Zhejiang provinces are reshaping price floors for dissolved air flotation systems as domestic fabricators achieve scale in stainless steel plate pack production. Three-tier pricing structure across premium, standard, and economy levels separates guaranteed-performance contracts with penalty clauses from basic equipment supply. Cost compression in municipal retrofit segments is intensifying because footprint-constrained sites limit competitive bidding pools. Industrial end users in oil and gas and microelectronics exhibit least price sensitivity due to operational risk transfer requirements.
Supply Chain Analysis
Refurbishment flows for legacy circular clarifiers create secondary parts markets in the United States and Germany as municipal utilities extend asset life rather than greenfield replacement. Specialty steel fabrication concentrates in Germany, Japan, and South Korea, while polymer coagulant production clusters in United States Gulf Coast corridors. Stainless steel plate packs draw from Indonesian nickel smelters, exposing buyers to commodity volatility. Single-source vulnerability in specialty steel feedstocks dominates risk profiles. Distribution runs through engineering-procurement-construction firms and direct municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as zero liquid discharge mandates in India's textile clusters and power plant cooling tower blowdown reuse specifications shift procurement toward hybrid biological-chemical trains with guaranteed performance terms.
For Market Incumbents: Acquire predictive analytics capabilities for sludge level monitoring and rake torque optimization to capture aftermarket service revenue streams. Defensive consolidation around specialty steel fabrication capacity in German industrial corridors mitigates nickel supply volatility from Indonesian smelters. Threat substitution from membrane bioreactor pretreatment clarification demands vertical integration into polymer chemistry for coagulant-flocculant bundling. For New Entrants and Emerging Players: Remote monitoring platforms offer the lowest barrier to entry for aftermarket service penetration in municipal utilities lacking process control engineering personnel. India's CPCB-mandated zero liquid discharge clusters in Tiruppur and Kanpur present the most penetrable geographic window. Food and beverage processors in California seeking membrane protection through compact inclined plate settlers provide a second white-space target. Go-to-market positioning should emphasize IoT sensor integration with penalty-backed performance guarantees. For Investors and Strategic Acquirers: Integrated water management conglomerates are the most active acquirer in this space, consolidating mid-cap stainless steel fabricators to secure plate pack supply. Long-term viability hinges on service revenue share expansion over equipment sales across the projection horizon. Acquisition target archetype: regional fabricators with installed base relationships in consent decree-driven municipal markets. Signal to watch: EPA enforcement acceleration in phosphorus removal without boundary expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel | Captive plate pack production insulates German fabricators from Indonesian nickel volatility. |
| Performance-Based Contracting Expansion | Guaranteed suspended solids outcomes transfer operational risk to Veolia and SUEZ service divisions. |
| Remote Monitoring Platform Deployment | IoT sludge level sensors create decade-long replacement part revenue in municipal utilities. |
| Hybrid System Process Integration | Biological-chemical-physical trains achieve CPCB zero liquid discharge in Indian textile clusters. |
| Geographic Expansion into Middle Eastern Operations | SUEZ leverages French municipal expertise across adjacent jurisdictions with tightening nutrient standards. |
Research Methodology
Direct dialogue with municipal plant engineers, EPC contractors, aftermarket service heads, and polymer procurement leads grounded qualitative assessment in operational realities. Secondary validation drew from EPA effluent limitation guidelines, EU Urban Wastewater Treatment Directive filings, MEE Class A enforcement records, and customs data on stainless steel plate imports. Bottom-up and top-down triangulation cross-checked equipment shipment volumes against regulatory-driven replacement cycle modeling.
Bottom-up segmentation modeling tracked product architectures, application chemistry, and end-user specifications across the projection horizon. Analytical dimensions included clarifier type, treatment train configuration, and regional regulatory cluster intensity. CAGRs derived from replacement cycle timing, consent decree deadlines, and industrial cluster expansion rates. Forecast inputs incorporated MEE enforcement acceleration trajectories and specialty steel price elasticity assumptions.
The model assumes a particular technology adoption path; alternative pathways for membrane bioreactor pretreatment would alter the outlook if distributed clarification architectures displace centralized gravity thickeners. Forecasts reflect enforcement wave timing assumptions; delayed EPA consent decree implementation or relaxed MEE Class A standards would compress upgrade demand. Practitioners should monitor nickel price volatility from Indonesian smelters and municipal bond issuance rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Global Wastewater Diffused Aerator Market
Water and Wastewater Treatment
Global Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
Javelle Water Market
Water and Wastewater Treatment
Tertiary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Latin America Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Global Biological Wastewater Treatment Market
Water and Wastewater Treatment
Global Wastewater Treatment Services Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
Global Vertical Sewage Pumps Market
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Water Aeration System Market