
 Air Pollution Control Systems Market | 2026-2036
Air Pollution Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Air Pollution Control Systems Market Intelligence
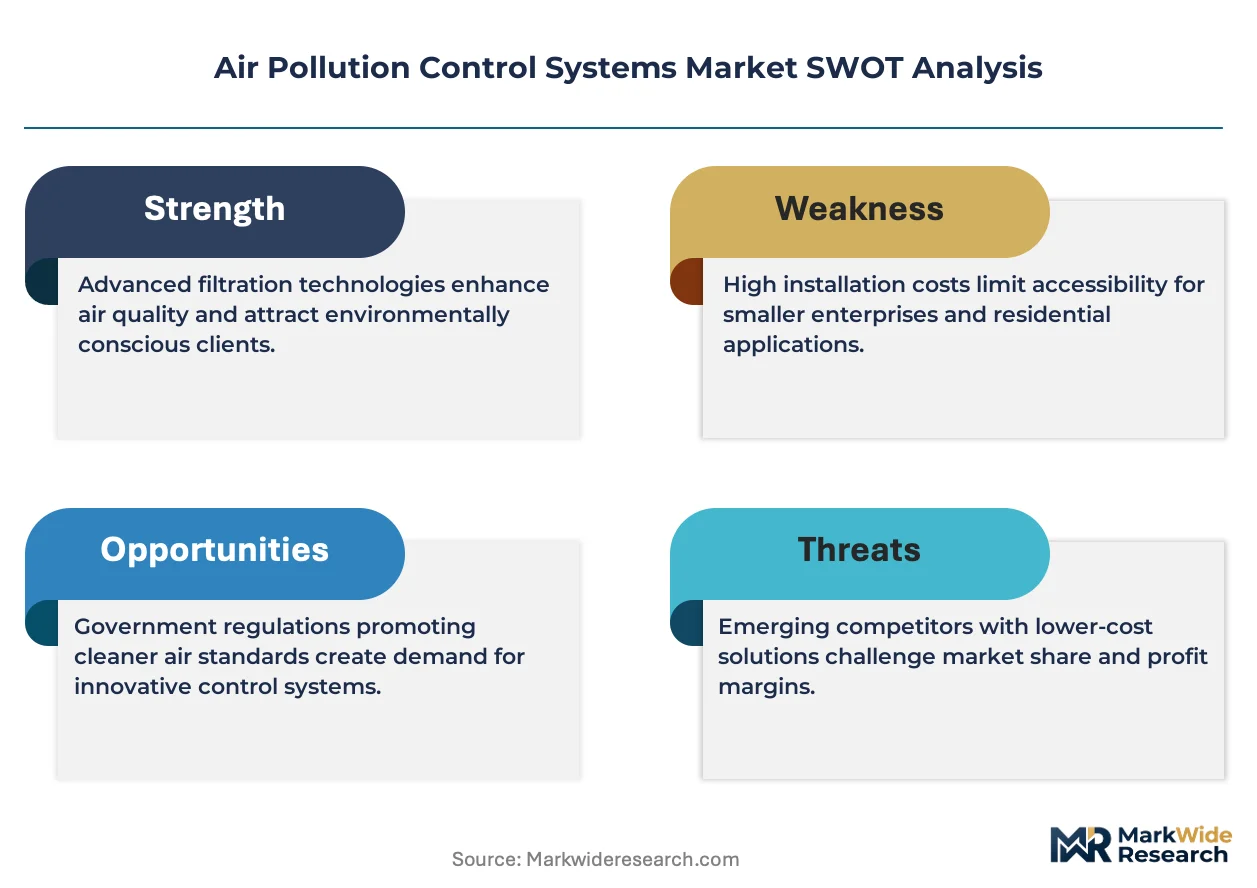
Project finance and equipment leasing is narrowing the competitive field for air pollution control systems, allowing mid-sized industrial operators to access scrubber and filtration technologies without heavy capital outlay. Thermax Limited leverages its integrated engineering capabilities across boiler and environmental solutions to sustain repeat utility contracts. GEA Group Aktiengesellschaft anchors its position through specialized wet scrubbing systems for chemical manufacturing clients. Mitsubishi Heavy Industries, Ltd. dominates large-scale electrostatic precipitator installations for coal-fired power generation in Asia.
Air pollution control systems comprise engineered equipment designed to remove particulate matter, sulfur oxides, nitrogen oxides, and volatile organic compounds from industrial exhaust streams, typically achieving removal efficiencies exceeding 99 percent for fine particulates through electrostatic precipitation or fabric filtration. These systems serve the essential commercial purpose of enabling industrial facilities to operate within legally mandated emission limits while protecting worker health and surrounding communities. Electrostatic precipitators retain the largest installed base across power generation applications due to their proven handling of high-temperature, high-volume flue gases, while wet scrubbing technologies capture the fastest growth in chemical manufacturing where multi-pollutant control requirements intensify. Selective catalytic reduction systems command premium margins in cement plants and metal processing facilities facing stringent nitrogen oxide regulations.
The US EPA enforces Maximum Achievable Control Technology standards that compel foundries and chemical manufacturers to upgrade or replace aging control equipment, while China's MEE implements progressively tighter emission concentration limits for particulate matter and sulfur dioxide across industrial sectors. India's Central Pollution Control Board mandates continuous emission monitoring systems that create recurring demand for instrumentation-integrated scrubber and filter packages. Stakeholders must evaluate whether their technology portfolios can adapt as regulatory thresholds tighten and carbon border adjustments begin to penalize imports from jurisdictions with weaker enforcement.
Market Dynamics
Retrofitting mandates for coal-fired power plants in China are compressing equipment replacement cycles and concentrating procurement among integrated engineering firms capable of turnkey electrostatic precipitator overhauls.
Growth Catalysts
- MEE Emission Standards:China's Ministry of Ecology and Environment mandates wet scrubbing upgrades for steel and cement producers, forcing capital deployment into multi-pollutant control systems.
- Industrial Corridors:India's concentrated manufacturing zones along the Delhi-Mumbai Industrial Corridor generate clustered demand for continuous emission monitoring integrated with baghouse filtration.
- Dual Carbon Goals:China's national carbon neutrality targets accelerate selective catalytic reduction retrofits in coal power to align nitrogen oxide control with decarbonization timelines.
Market Restraints
- Specialized Alloy Costs:Hastelloy and titanium components for corrosive wet scrubbing environments face price volatility tied to nickel mining concentration in Indonesia and the Philippines.
- Fabric Filter Supply:High-temperature filter media production concentrates among German and Japanese specialty textile manufacturers, creating single-source vulnerability for large utility contracts.
- Baghouse Footprint Constraints:Physical space limitations at aging industrial sites in the US Northeast prevent straightforward fabric filtration retrofits, favoring compact electrostatic precipitator alternatives.
Strategic Opportunities
- Indonesian Smelter Expansion:Nickel processing capacity growth in Sulawesi and Halmahera creates demand for acid gas scrubbing systems absent established local equipment suppliers.
- Carbon Border Adjustment Mechanism:The EU's CBAM incentivizes Indian and Chinese exporters to install certified emission control systems to avoid import tariffs on carbon-intensive goods.
- Digital Twin Integration:Predictive maintenance platforms combining sensor networks with scrubber performance modeling enable service-contract revenue streams beyond equipment sales.
Industry Challenges
- Corrosion Engineering Talent:Wet scrubber design for high-sulfur flue gas applications requires specialized materials expertise concentrated among retiring specialists in Germany and Japan.
- CE Certification Timelines:European conformity assessment for novel catalytic reduction systems extends 14-18 months, delaying commercial deployment against faster domestic Chinese approval pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Pollution Control Systems Market |
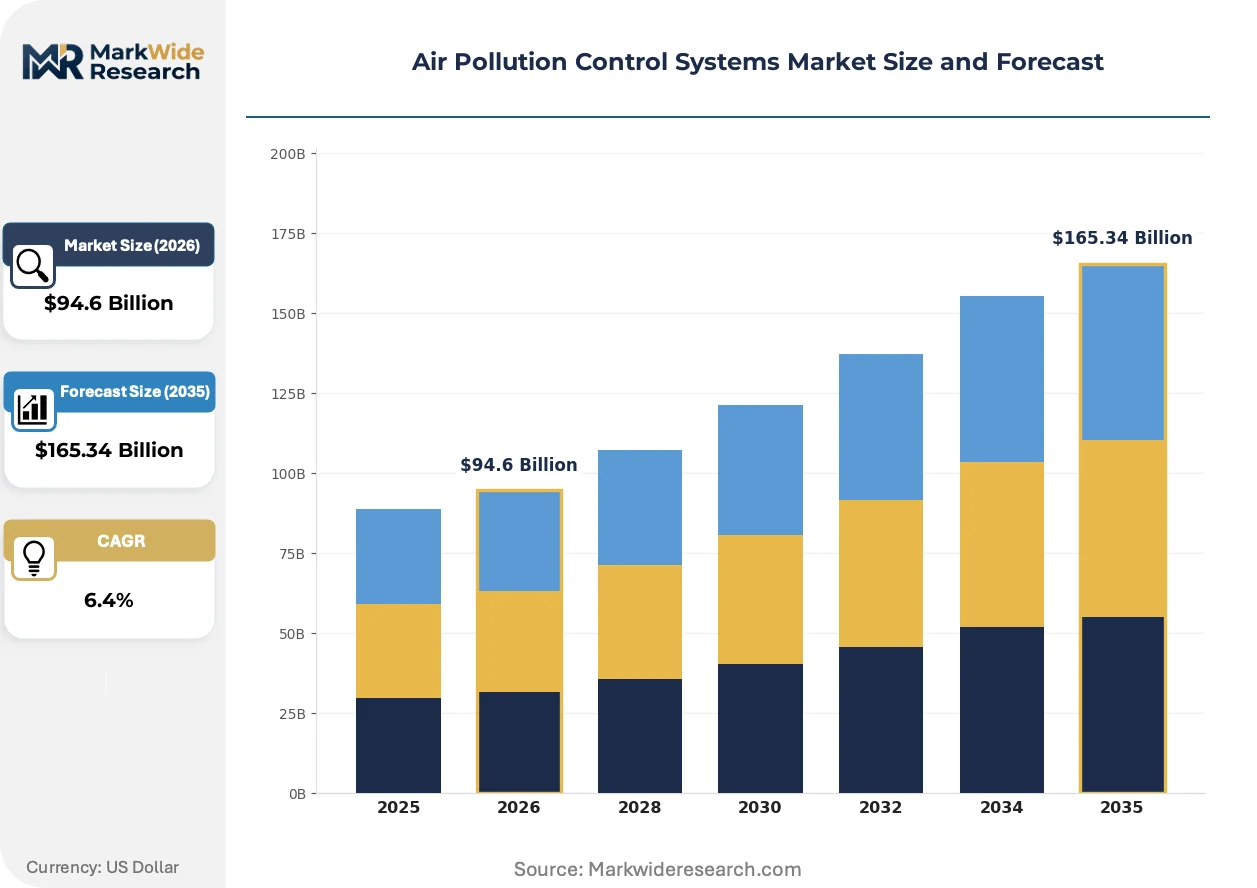
| Market Size in 2026 | $94.6 Billion |
| Market Size in 2035 | $165.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straight Flow Scrubbers, Electrostatic Precipitators, Fabric Filters, Cyclones, Absorbers Technology: Wet Scrubbing, Dry Scrubbing, Selective Catalytic Reduction, Biofiltration, Adsorption Application: Power Generation, Cement Plants, Chemical Manufacturing, Metal Processing, Food Production End User: Utilities, Chemical Manufacturers, Foundries, Food Processors, Power Producers |
| Companies Covered | Thermax Limited, GEA Group Aktiengesellschaft, Mitsubishi Heavy Industries, Ltd., Fujian Longking Co., Ltd., Donaldson Company, Inc., Babcock & Wilcox Enterprises, Inc., Siemens AG, Ducon Technologies Inc., General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Pollution Control Systems Market Strategic Shifts & Innovations
Equipment intelligence and modular system architecture are compressing project delivery timelines and enabling performance-based contracting models that shift operational risk from plant operators to technology suppliers.
Dry sorbent injection systems paired with compact fabric filters are rendering obsolete conventional wet limestone scrubbers at smaller coal units and industrial boilers below 300 MW capacity. Cement producers in Southeast Asia are adopting these configurations to avoid wastewater treatment infrastructure. The technology is rendering obsolete the historical preference for wet scrubbing in sulfur dioxide control outside power generation.
The US EPA's pending updates to Maximum Achievable Control Technology standards for ferrous foundries will mandate particulate matter capture efficiencies exceeding 99.9 percent. This forces cupola furnace operators to replace mechanical collectors with baghouse or hybrid electrostatic-filtration systems. Midwestern foundry clusters are responding by consolidating procurement through regional equipment cooperatives to share engineering validation costs.
Performance guarantees are displacing traditional equipment purchase contracts in chemical manufacturing, with scrubber vendors assuming operational risk for emission compliance. This transfers maintenance burden and catalyst replacement scheduling to suppliers. The shift is most visible in German and Dutch petrochemical corridors where environmental liability regulations tighten operator accountability.
Air Pollution Control Systems Market Segmentation
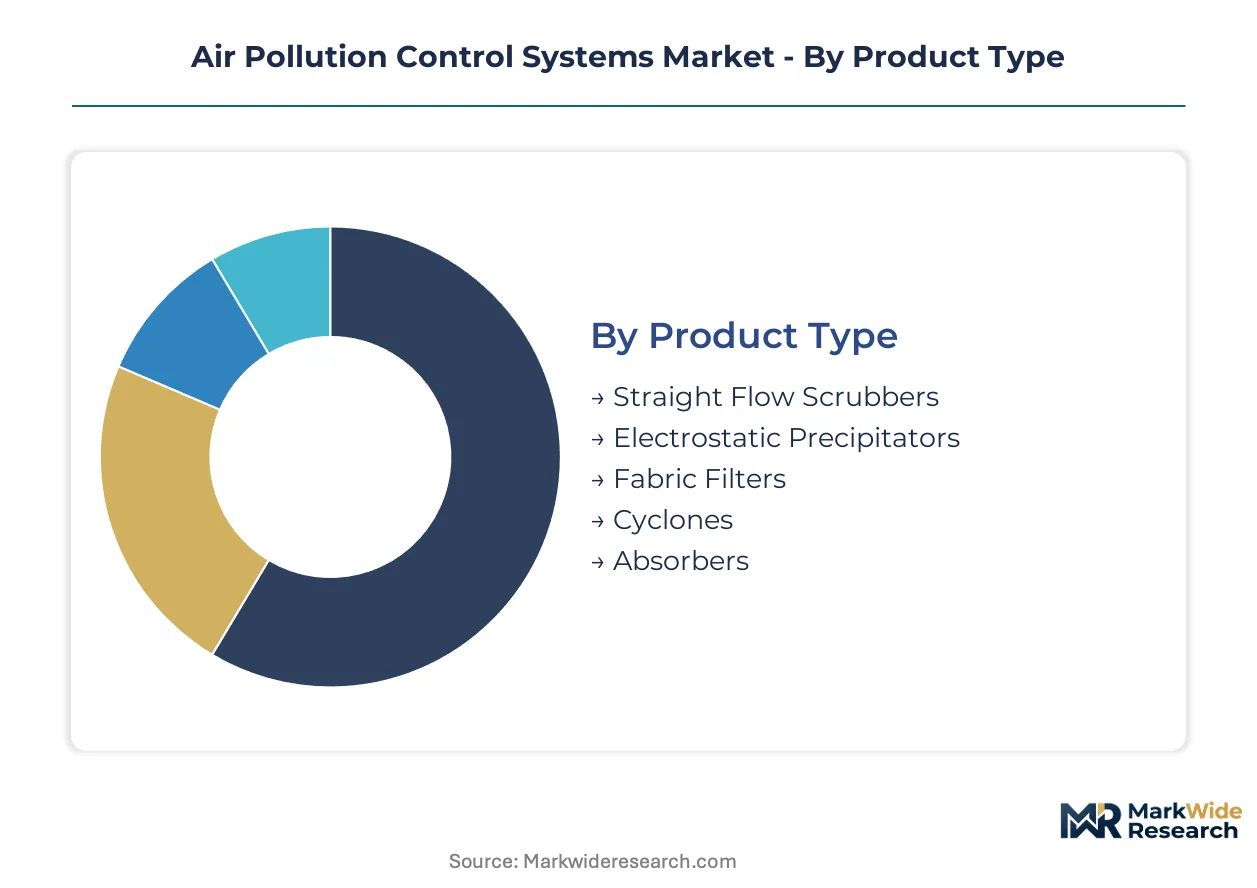
Segmentation reveals how procurement patterns diverge across equipment types and user profiles. After-sales service intensity varies dramatically between electrostatic precipitator retrofits requiring continuous electrode maintenance versus disposable filter media replacements.
Product Type:
Service intensity correlates directly with component complexity and replacement frequency across equipment categories.
- Straight Flow Scrubbers:Vertical vessel designs with counter-current gas-liquid contact achieve acid gas removal efficiencies above 95 percent. Chemical manufacturers in Germany's Rhine-Ruhr corridor favor these for chlorine derivative production, driven by ECHA enforcement of industrial emissions directives.
- Electrostatic Precipitators:High-voltage electrode systems ionize particulate matter for collection on grounded plates, handling flue gas volumes exceeding 5 million cubic meters per hour. Coal-fired utilities in China's Shandong and Shanxi provinces dominate replacement demand as MEE standards force electrode rapping system upgrades.
- Fabric Filters:Woven or felt media capture sub-micron particles through surface and depth filtration mechanisms. Cement plants along India's Delhi-Mumbai Industrial Corridor specify PTFE membrane bags for kiln exhaust applications.
- Cyclones:Centrifugal separation removes coarse particulates above 10 microns without moving parts. Foundries in the US Midwest deploy these as pre-cleaners upstream of final filtration stages.
- Absorbers:Packed column designs dissolve gaseous pollutants into liquid reagents for chemical neutralization. Sulfuric acid producers in Spain's Huelva chemical complex require titanium-clad absorbers for SO3 handling.
By volume, Fabric Filters lead. By growth pace, Straight Flow Scrubbers are ahead.
Technology:
Capital deployment patterns reflect divergent operating cost structures and regulatory compliance timelines.
- Wet Scrubbing:Liquid reagent systems capture acid gases and particulates simultaneously through gas-liquid contact. Nickel smelters in Indonesia's Sulawesi belt adopt venturi scrubbers for SO2 control absent local wastewater treatment infrastructure.
- Dry Scrubbing:Powdered sorbent injection neutralizes acid gases without liquid waste generation. Cement kilns in Vietnam's Hon Chong district favor dry systems to avoid effluent discharge permitting.
- Selective Catalytic Reduction:Vanadium or zeolite catalysts reduce nitrogen oxides to nitrogen and water at 300-400°C operating temperatures. Coal power operators in Poland's Silesia region retrofit SCR systems to meet EU Industrial Emissions Directive NOx limits.
- Biofiltration:Microbial oxidation degrades volatile organic compounds in compost-based filter beds. Food processors in the Netherlands' Noord-Brabant province deploy these for ethanol and acetaldehyde emissions from baking operations.
- Adsorption:Activated carbon or zeolite media capture VOCs and mercury through physical surface binding. Hazardous waste incinerators in Japan's Chiba prefecture specify activated carbon injection for dioxin control.
By installed base, Wet Scrubbing dominates. By expansion trajectory, Selective Catalytic Reduction is climbing the fastest.
Application:
End-use concentration determines equipment specification standards and supplier qualification requirements.
- Power Generation:High-volume flue gas conditioning demands equipment redundancy and continuous emission monitoring integration. Coal plants in South Africa's Mpumalanga province retrofit fabric filters alongside existing electrostatic precipitators for PM2.5 compliance.
- Cement Plants:Alkaline dust and high moisture content necessitate corrosion-resistant materials and thermal insulation. Producers in Egypt's Suez Canal Economic Zone install hybrid electrostatic-baghouse systems for kiln and clinker cooler exhaust.
- Chemical Manufacturing:Variable pollutant loads and toxic compound handling require modular scrubber configurations with automated pH control. Petrochemical complexes in Thailand's Map Ta Phut industrial estate deploy multi-stage wet scrubbing for olefin production emissions.
- Metal Processing:High-temperature exhaust and metallic particulate loads demand refractory-lined ductwork and spark-resistant construction. Aluminum smelters in Iceland's Reyðarfjörður utilize dry scrubbing with alumina adsorption for fluoride recovery.
- Food Production:Organic particulate and odor control priorities favor low-pressure-drop filtration and bio-oxidation systems. Rendering facilities in Brazil's São Paulo state install regenerative thermal oxidizers for protein processing emissions.
Power Generation commands the largest equipment footprint. Chemical Manufacturing shows the steepest contract value growth.
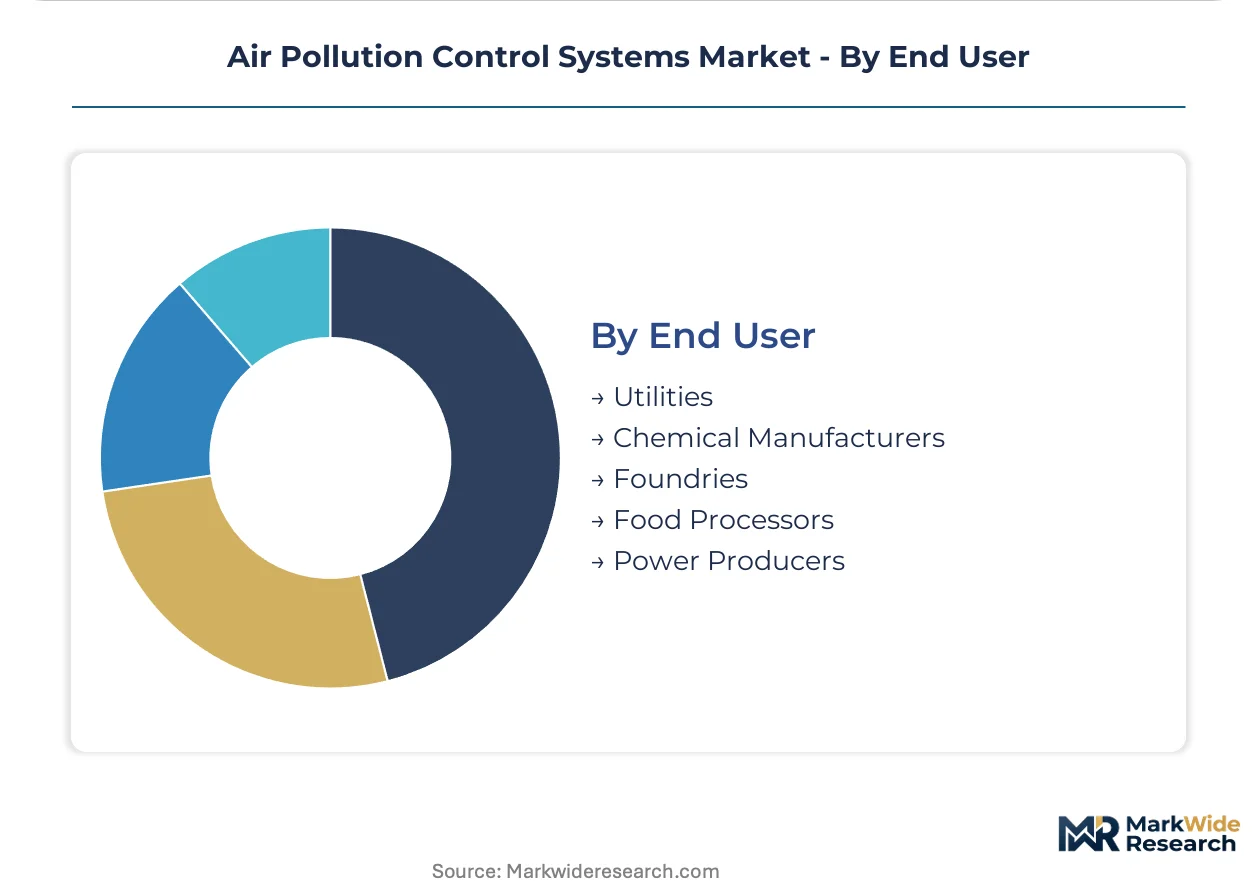
End User:
Procurement sophistication and lifecycle cost evaluation maturity distinguish buyer categories.
- Utilities:Centralized engineering departments specify equipment with 25-year design life and guaranteed availability clauses. State Power Investment Corporation in China bundles electrostatic precipitator procurement across multiple provincial generation assets.
- Chemical Manufacturers:Process-integrated environmental systems require vendor assumption of operational risk through performance contracting. BASF's Ludwigshafen complex negotiates scrubber availability guarantees tied to emission compliance liability transfer.
- Foundries:Capital constraints and limited in-house technical staff drive preference for turnkey installation and operator training packages. Cupola furnace operators in Italy's Brescia region consolidate procurement through regional foundry associations.
- Food Processors:Hygiene standards and product contamination risks mandate stainless steel construction and clean-in-place capability. Dairy cooperatives in New Zealand's Waikato region specify food-grade filtration for spray dryer exhaust.
- Power Producers:Independent generators lacking integrated engineering resources rely on OEM service contracts for catalyst replacement and baghouse maintenance. IPPs in Turkey's Afşin-Elbistan lignite district outsource SCR catalyst management to technology suppliers.
Utilities represent the deepest retrofit backlog. Chemical Manufacturers are shifting fastest toward performance-based contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's engineering corridors where specialty alloy fabricators command premiums, while Chinese domestic suppliers compete on retrofit bundling for MEE-mandated upgrades. This asymmetry shapes procurement patterns across industrial clusters.
China
Shandong and Shanxi provinces drive electrostatic precipitator replacement cycles as coal-fired utilities retrofit for MEE emission standards. The Ministry of Ecology and Environment mandates wet scrubbing upgrades across steel and cement sectors. Procurement concentrates among State Power Investment Corporation's bundled provincial contracts.
India
The Delhi-Mumbai Industrial Corridor generates clustered demand for baghouse filtration with continuous emission monitoring integration. BIS norms and the PLI scheme for clean technology manufacturing accelerate local equipment procurement. Cement plants in Gujarat and Maharashtra specify PTFE membrane bags for kiln exhaust applications.
Germany
Rhine-Ruhr chemical manufacturers favor straight flow scrubbers for chlorine derivative production under ECHA industrial emissions directives. Corrosion engineering expertise for high-sulfur flue gas applications concentrates among retiring specialists. BASF's Ludwigshafen complex negotiates performance-based scrubber contracts with liability transfer.
United States
Midwestern foundry clusters consolidate procurement through regional equipment cooperatives to share engineering validation costs for EPA Maximum Achievable Control Technology compliance. Cupola furnace operators replace mechanical collectors with hybrid electrostatic-filtration systems. Physical space constraints at aging Northeast sites favor compact precipitator alternatives over baghouse retrofits.
Indonesia
Nickel processing capacity expansion in Sulawesi and Halmahera creates demand for acid gas scrubbing systems absent established local equipment suppliers. Venturi scrubber installations address SO2 control without local wastewater treatment infrastructure. Smelter operators source from foreign engineering firms with regional service partnerships.
Air Pollution Control Systems Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in materials and catalyst supply. The vendor base organizes around three tiers: diversified engineering conglomerates with turnkey capabilities, focused environmental equipment fabricators, and niche materials suppliers for corrosive service conditions. Competitive moves center on performance contracting models that transfer operational risk to suppliers, and geographic expansion into nickel smelter corridors lacking established local players.
Within the diversified engineering tier, Thermax Limited and Mitsubishi Heavy Industries, Ltd. occupy positions spanning boiler integration through environmental retrofits. GEA Group Aktiengesellschaft exemplifies the specialized wet scrubbing archetype for chemical manufacturing clients. These three anchors illustrate how procurement sophistication varies: conglomerates bundle multi-asset contracts, while specialists capture premium margins through process-integrated designs.
| Leading Market Players |
|---|
| Thermax Limited |
| GEA Group Aktiengesellschaft |
| Mitsubishi Heavy Industries, Ltd. |
| Fujian Longking Co., Ltd. |
| Donaldson Company, Inc. |
| Babcock & Wilcox Enterprises, Inc. |
| Siemens AG |
| Ducon Technologies Inc. |
| General Electric Company |
| Others |
Cost & Logistics Intelligence
Indonesian nickel mining concentration anchors titanium and Hastelloy alloy pricing for wet scrubber components, compressing margins for fabricators downstream while concentrating premium pricing power with German and Japanese specialty metal suppliers. Project finance structures and extended equipment leasing terms redistribute capital risk across the value chain, allowing mid-sized operators to access advanced filtration technologies without absorbing full upfront costs.
Pricing Analysis
Configured-to-order electrostatic precipitator retrofits command 40-60 percent premiums over standardized baghouse packages due to site-specific engineering and continuous emission monitoring integration. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE-marked and MEE-compliant systems capturing margin premiums against unverified alternatives. Cost compression in standard filtration tiers is intensifying because Chinese domestic suppliers bundle retrofit packages for provincial utility contracts. Chemical manufacturers demonstrate lowest price sensitivity due to performance-guarantee contracting models that transfer operational risk, while foundry cooperatives in capital-constrained Midwestern clusters negotiate aggressively on upfront capital outlay.
Supply Chain Analysis
Supplier-financing facilities from German engineering conglomerates and Japanese trading houses extend payment terms to 180 days for nickel smelter projects in Indonesia, easing working capital pressure for EPC contractors. High-temperature filter media production concentrates in Germany and Japan, while titanium alloy fabrication anchors in China and specialty steel production centers in South Korea. Wet scrubber assembly draws from Hastelloy sheet, ceramic tower packing, and ceramic filter elements, exposing fabricators to nickel price volatility and single-source vulnerability for PTFE membrane media. Distribution runs through regional engineering subsidiaries with localized service partnerships, particularly for MEE-mandated retrofit corridors in Shandong and Shanxi provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air pollution control systems represent a high-growth disruption as carbon border adjustments and dual carbon goals force capital deployment into certified multi-pollutant control infrastructure. The regulatory inflection at China's MEE and the EU's CBAM creates structural demand for integrated emission monitoring and scrubber retrofits.
For Market Incumbents: Insulate service revenue streams by embedding predictive maintenance platforms and digital twin integration into long-term performance contracts, locking out competitors from catalyst replacement and electrode maintenance cycles. Deepen backward integration into high-temperature filter media production to reduce dependency on German and Japanese textile suppliers, while expanding corrosion engineering talent pipelines to offset retiring specialist concentration. For New Entrants and Emerging Players: Establish a beachhead in Indonesian nickel smelter corridors where acid gas scrubbing demand outpaces established local equipment suppliers, leveraging foreign engineering partnerships to bypass capital-intensive fabrication infrastructure. Target dry sorbent injection retrofits for sub-300 MW industrial boilers in Southeast Asian cement plants, positioning compact systems as wastewater-free alternatives to conventional limestone scrubbers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-sized wet scrubbing specialists with proven chemical manufacturing track records and existing performance-contracting capabilities, as liability transfer models concentrate procurement among qualified vendors. Watch for inflection signals in CE certification timeline compression or MEE approval pathway acceleration, which would shift competitive advantage toward faster-deployment domestic Chinese suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Performance Contracting Expansion | Scrubber vendors assume emission compliance liability at BASF's Ludwigshafen complex and comparable chemical corridors. |
| Backward Integration into Filter Media | Fabricators reduce single-source exposure to German and Japanese PTFE membrane suppliers for cement kiln applications. |
| Digital Twin Platform Deployment | Predictive maintenance networks enable recurring service revenue beyond equipment sales at coal-fired utilities. |
| Indonesian Smelter Market Entry | Foreign engineering firms capture acid gas scrubbing demand in Sulawesi and Halmahera nickel processing corridors. |
| Dry Sorbent Injection Scale-Up | Cement producers in Vietnam's Hon Chong district avoid effluent permitting through compact SO2 control systems. |
Research Approach
A standing panel of plant engineers at coal-fired utilities, procurement leads at chemical manufacturing complexes, EPC contractors specializing in environmental retrofits, and aftermarket service directors provided ongoing calibration across primary interview rounds. Secondary validation drew from EPA Maximum Achievable Control Technology filings, MEE emission standard updates, BIS certification databases, and customs records for specialty alloy imports. Bottom-up equipment shipment tallies and top-down utility capital expenditure tracking were triangulated to anchor market sizing.
Scenario bracketing around regulatory enforcement intensity and nickel price volatility shaped projection ranges across the analysis window. Segmentation dimensions modeled include equipment type, technology category, application sector, and end-user procurement sophistication, with regional regulatory cluster differentiation for MEE, EPA, and ECHA jurisdictions. CAGRs were derived from installed base replacement cycles and greenfield capacity additions, incorporating catalyst replacement scheduling and electrode rapping system upgrade intervals as industry-specific demand drivers.
Stress conditions across nickel alloy price bands, CE certification timeline variance, and MEE enforcement intensity gradients were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory trajectory and commodity input stability. Macroeconomic contraction, abrupt tariff restructuring, or breakthrough dry scrubbing technology maturation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
North America Industrial Air Quality Control Systems Market
Air Quality Control Systems
Singapore Air Purifier Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
Anti-Pollution Toner Market
Air Quality Control Systems
Oxygen Filters Market
Air Quality Control Systems
Anti-Pollution Mask Market
Air Quality Control Systems
Environmental Control System (ECS) Market
Air Quality Control Systems
Global Mist Eliminator Market
Air Quality Control Systems
Europe Industrial Air Quality Control Systems Market
Air Quality Control Systems
Green Emissions Analyzers Market
Air Quality Control Systems
Southeast Asia Air Purifier Market
Air Quality Control Systems
Nitrogen Oxide Control Systems Market
Air Quality Control Systems
UV Air Purifiers Market
Air Quality Control Systems
Air Quality Monitoring Software Market
Air Quality Control Systems
Air Quality Control Systems Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market