
 Wastewater Screening Equipment Market | 2026-2036
Wastewater Screening Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Wastewater Screening Equipment Market Analytics
Germany is reconfiguring its manufacturing footprint for wastewater screening systems through dedicated engineering corridors in Bavaria and North Rhine-Westphalia. Evoqua Water Technologies leverages its membrane-integrated screening portfolio to anchor premium municipal contracts across North American utilities. Veolia Water Technologies & Solutions competes through in-house production of high-capacity drum screens for European industrial clients. Xylem Inc. differentiates via IoT-enabled condition monitoring bundled with its traveling water screen installations.
Wastewater screening equipment encompasses mechanical and automated bar, fine, and rotary screen assemblies engineered to remove solids, debris, and particulate matter from influent streams prior to biological or chemical treatment stages, with aperture specifications typically ranging from 0.5 mm to 150 mm depending on downstream process sensitivity. Fine Screens lead product type demand due to their critical role in protecting membrane bioreactor installations, while Rotary Screens represent the fastest-expanding category driven by continuous-operation requirements in high-volume municipal plants. Automatic technology commands the dominant technology share as labor cost escalation and remote monitoring capabilities render manual configurations structurally marginal, though Hybrid systems are gaining traction where seasonal flow variability demands operational flexibility.
The EPA enforces Clean Water Act effluent limitations that mandate preliminary treatment standards, while the EU Urban Wastewater Treatment Directive sets nutrient removal benchmarks that intensify screening reliability requirements. ISO 9001 and EN 12255-1 product conformity frameworks govern equipment certification pathways in Europe, with India's CPCB notifying revised sewage treatment plant standards under the Water (Prevention and Control of Pollution) Act. Stakeholders must monitor regulatory tightening around microplastic capture mandates and assess technology migration timelines from mechanical to sensor-driven automatic configurations.
Market Dynamics
Automatic screening configurations are compressing the addressable base for manual and semi-mechanical systems as municipal utilities prioritize remote operability and labor cost containment across treatment infrastructure procurement cycles.
Growth Catalysts
- EU Urban Wastewater Treatment Directive revisions:Germany's municipal utilities are accelerating fine-screen procurement ahead of stricter nutrient removal benchmarks and preliminary treatment standards enforcement.
- Membrane bioreactor proliferation:Industrial food processing and pharmaceutical effluent treatment facilities demand finer aperture specifications to protect downstream membrane assets from particulate damage.
- IoT-enabled condition monitoring:North American utilities bundle predictive maintenance capabilities with screening equipment tenders, reducing unplanned downtime in high-volume coastal plants.
Market Restraints
- Stainless steel and specialty alloy input volatility:Drum screen and fine-screen manufacturers face margin compression from nickel and molybdenum price swings in European and Asian metal exchanges.
- Technical limitation in microplastic capture:Conventional aperture specifications above 0.5 mm fail to intercept synthetic fibers and microbeads, creating compliance exposure ahead of anticipated capture mandates.
- Regulatory friction from divergent certification timelines:India's CPCB sewage treatment plant standards and ISO 9001 conformity pathways impose overlapping compliance burdens on multinational equipment suppliers.
Strategic Opportunities
- Hybrid system deployment:Australian and Indian coastal treatment plants with seasonal flow variability present demand for configurations blending automatic and manual override capabilities.
- Microplastic capture technology convergence:Integration of advanced filtration media with rotary drum architectures addresses emerging regulatory tailwinds in European wastewater directives.
- Performance-based service contracting:Municipal utilities in Bavaria and North Rhine-Westphalia are piloting outcome-based maintenance agreements that shift capital expenditure to operational expenditure structures.
Industry Challenges
- Electromechanical technician scarcity:Automated screening system deployment outpaces qualified field service capacity in secondary Indian and Australian municipal markets.
- Legacy control system integration:SCADA retrofit requirements in aging North American treatment plants extend commissioning timelines and escalate project risk for automatic technology rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wastewater Screening Equipment Market |
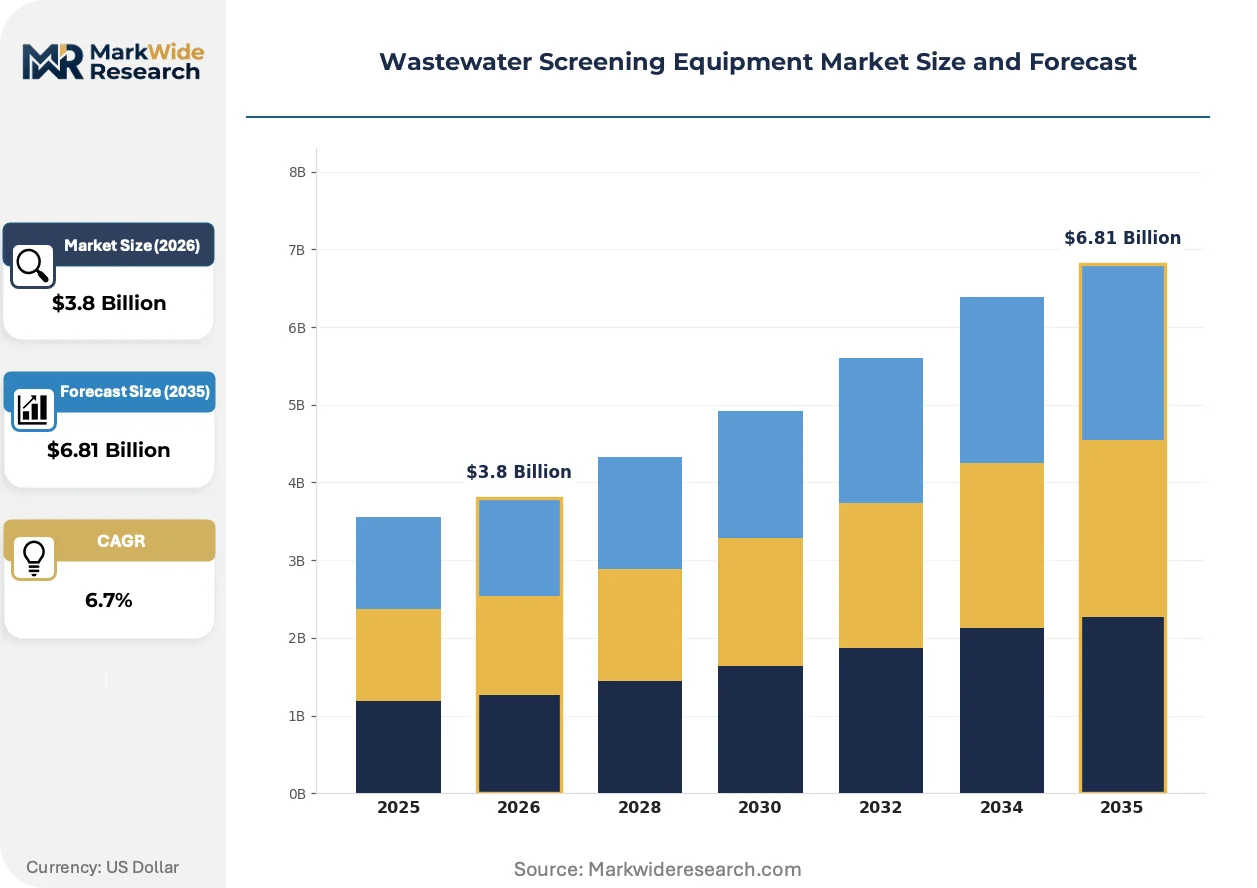
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bar Screens, Fine Screens, Course Screens, Rotary Screens Technology: Mechanical, Manual, Automatic, Hybrid End User: Municipal, Industrial, Commercial, Agricultural Application: Wastewater Treatment, Stormwater Management, Industrial Process, Reuse |
| Companies Covered | Evoqua Water Technologies, Kurita Water Industries Ltd., Veolia Water Technologies & Solutions, Ovivo Inc., Aquatech International, SUEZ, Pentair plc, Ecolab Inc., Xylem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wastewater Screening Equipment Market Evolving Landscape
Sensor-driven automatic configurations are compressing the operational envelope for manual screening systems while regulatory tightening around effluent quality forces aperture specification upgrades across municipal procurement cycles.
Ultrasonic level sensors coupled with variable-frequency drive motors enable real-time flow-adjusted screen operation without operator intervention. Coastal treatment plants in Australia and India are deploying these packages at replacement cycle acceleration, bypassing semi-automatic intermediaries entirely. Continuous-operation rotary architectures with embedded condition monitoring is rendering obsolete batch-cleaned bar screen installations in high-volume municipal settings.
The EPA enforces Clean Water Act effluent limitations that mandate preliminary treatment standards with escalating reliability requirements for screening upstream of biological stages. Industrial discharge permits in food processing and chemical manufacturing now specify maximum allowable solids loading that forces aperture migration toward fine-screen specifications. North American utilities are responding by bundling membrane protection guarantees into screening equipment procurement tenders.
Performance-based contracting is displacing traditional capital purchase models in German municipal markets, with operators transferring operational risk to equipment suppliers through uptime guarantee structures. Bavarian engineering corridors are configuring service-forward business models that capture recurring revenue from remote diagnostics and predictive parts replacement. This shift concentrates supplier relationships around integrated technology-service portfolios rather than discrete equipment transactions.
Wastewater Screening Equipment Market Segmentation
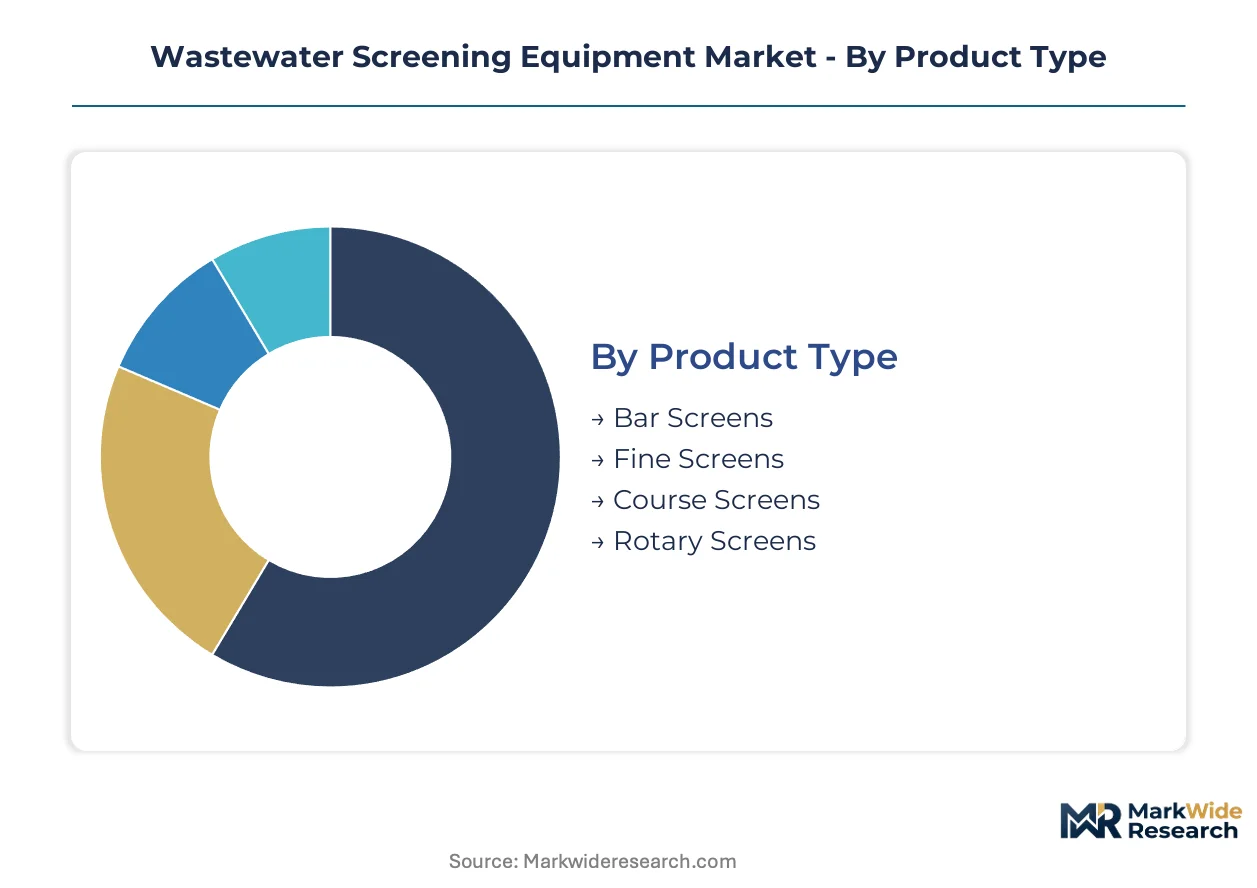
Wastewater screening equipment segmentation reveals how technology maturity, regulatory pressure, and end-use economics create distinct procurement patterns across municipal and industrial buyers. Equipment specification choices cascade through downstream biological treatment performance and membrane asset protection.
Product Type:
Cost tier differentiation separates high-precision fine-screen systems from robust coarse configurations, with aperture specification driving material selection and manufacturing complexity.
- Fine Screens:Aperture specifications ranging from 0.5 mm to 6 mm protect membrane bioreactor installations in pharmaceutical and food processing effluent treatment. German municipal utilities under EU Urban Wastewater Treatment Directive revisions are accelerating procurement of these systems ahead of stricter nutrient removal benchmarks.
- Rotary Screens:Continuous-operation drum architectures with automated cleaning mechanisms serve high-volume coastal treatment plants in India and Australia. Seasonal flow variability in these markets is compressing replacement cycles for batch-cleaned alternatives.
- Bar Screens:Coarse-interception systems with 25 mm to 150 mm spacing handle heavy debris loads in preliminary treatment stages.
- Coarse Screens:Ruggedized designs intercept large solids and protect downstream fine-screen assets from damage.
Fine Screens command the established base. The steepest expansion runs through Rotary Screens.
Technology:
Application intensity varies sharply between labor-dependent manual configurations and sensor-driven automatic systems, with hybrid architectures emerging where operational flexibility outweighs pure automation economics.
- Automatic:Ultrasonic level sensors coupled with variable-frequency drive motors enable real-time flow adjustment without operator presence. North American utilities bundle predictive maintenance capabilities into tenders, reducing unplanned downtime in high-volume coastal facilities.
- Hybrid:Configurations blending automatic operation with manual override address seasonal flow variability in Australian and Indian treatment infrastructure. These systems gain traction where capital constraints limit full automation deployment.
- Mechanical:Timer-actuated or differential-level-triggered systems occupy mid-tier municipal procurement.
- Manual:Operator-dependent configurations retreat to small-scale agricultural and remote commercial installations.
Automatic technology commands the established base. The steepest expansion runs through Hybrid systems.
End User:
Customer type determines specification stringency, with municipal buyers prioritizing remote operability and industrial purchasers focusing on membrane protection guarantees.
- Municipal:City and regional utilities deploy large-capacity installations with IoT-enabled condition monitoring across treatment infrastructure. Procurement cycles in Germany are accelerating ahead of EU directive revisions, while Indian and Australian coastal plants displace manual configurations.
- Industrial:Food processing and pharmaceutical effluent treatment facilities demand finer aperture specifications to protect downstream membrane assets from particulate damage.
- Commercial:Shopping centers, hotels, and office complexes require compact footprint systems for on-site pretreatment.
- Agricultural:Livestock operations and food processing plants utilize coarse-interception systems for solids-laden wastewater streams.
Municipal end users command the established base. The steepest expansion runs through Industrial facilities.
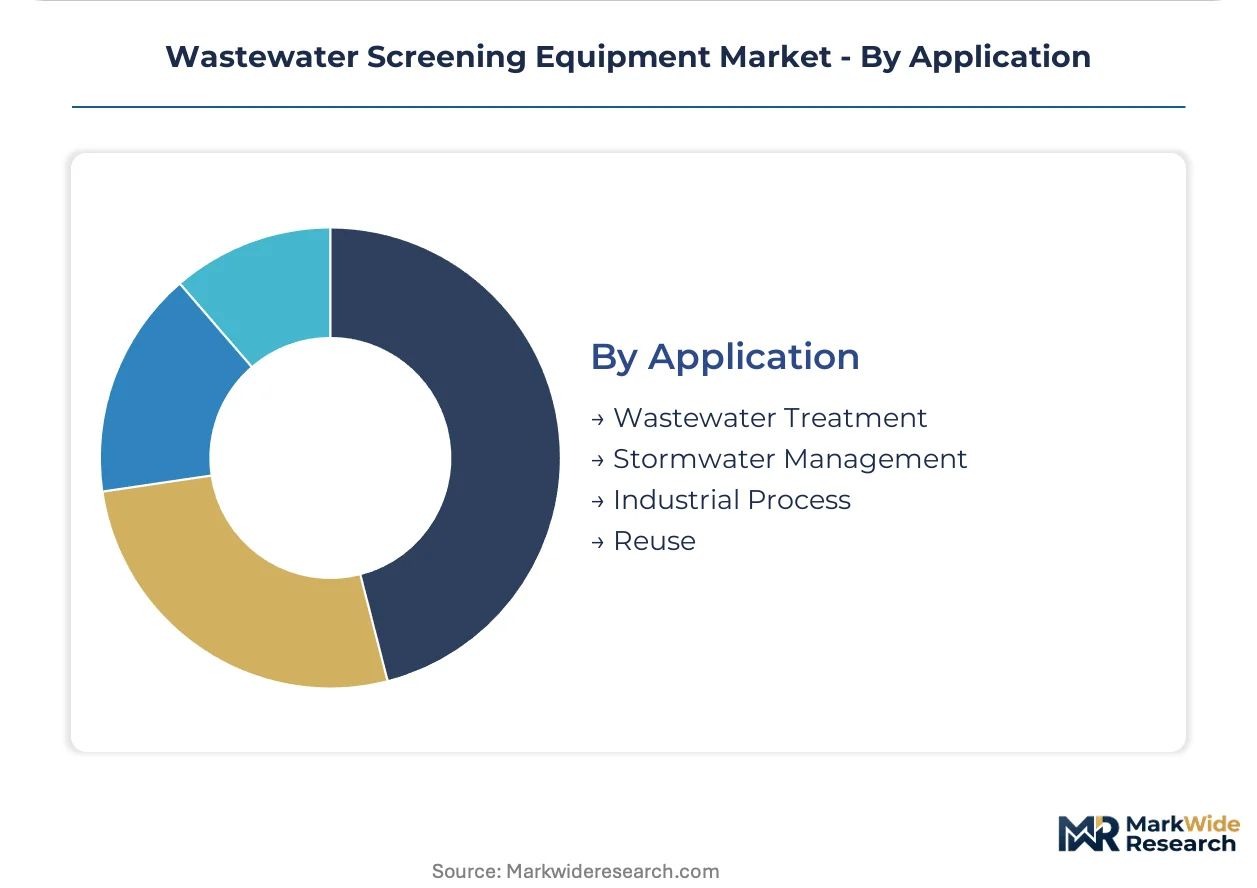
Application:
Volume concentration clusters in wastewater treatment proper, with reuse applications commanding premium specifications as water scarcity intensifies recovery economics.
- Wastewater Treatment:Preliminary and primary stage installations across municipal and industrial facilities constitute the core demand base. EPA Clean Water Act effluent limitations mandate reliable screening upstream of biological treatment stages.
- Reuse:Water recovery applications impose stringent solids removal requirements to meet potable and non-potable quality standards. These specifications drive aperture migration toward fine-screen and advanced filtration convergence.
- Stormwater Management:Debris interception in urban runoff systems protects downstream infrastructure from clogging.
- Industrial Process:In-plant recycling loops require continuous-operation screening to maintain production continuity.
Wastewater Treatment commands the established base. The steepest expansion runs through Reuse applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering corridors in Bavaria and North Rhine-Westphalia concentrate manufacturing capacity for membrane-integrated and drum-screen systems. Municipal procurement cycles across multiple geographies now synchronize with regulatory revision timelines rather than traditional replacement schedules.
Germany
Municipal utilities accelerate fine-screen procurement ahead of EU Urban Wastewater Treatment Directive revisions. The country's engineering corridors in Bavaria and North Rhine-Westphalia reconfigure production footprints for advanced screening assemblies. Stricter nutrient removal benchmarks intensify reliability requirements for preliminary treatment stages.
United States
North American utilities bundle IoT-enabled condition monitoring into screening equipment tenders. EPA Clean Water Act effluent limitations mandate escalating reliability for upstream biological protection. Coastal treatment facilities in California and Florida displace manual configurations with automatic systems.
India
Coastal treatment plants in Gujarat and Maharashtra deploy automatic screening technology to bypass semi-automatic intermediaries entirely. The CPCB notifies revised sewage treatment plant standards under the Water Act. Seasonal flow variability compresses replacement cycles for batch-cleaned alternatives.
Australia
High-volume coastal plants in New South Wales and Queensland prioritize continuous-operation rotary architectures. The country's treatment infrastructure procurement emphasizes remote operability and labor cost containment. Hybrid configurations gain traction where capital constraints limit full automation deployment.
Japan
Industrial food processing and pharmaceutical effluent facilities demand finer aperture specifications for membrane asset protection. METI guidelines on resource circulation intensify screening requirements for water reuse applications. Manufacturing clusters around Osaka and Nagoya integrate predictive maintenance capabilities into equipment specifications.
Wastewater Screening Equipment Market Competitive Landscape
Integrated technology-service providers and specialized equipment fabricators split the market along the capital-versus-outcome contracting divide. Consolidation pressure concentrates relationships around suppliers capable of bundling remote diagnostics with hardware procurement. Two archetypes dominate: multinational water technology conglomerates with captive service networks, and regional engineering specialists with deep integration into municipal procurement channels. Competitive moves center on performance-based contracting pilots and geographic expansion through engineering corridor partnerships.
Among conglomerate-tier operators, Evoqua Water Technologies and Veolia Water Technologies & Solutions exemplify the integrated service model, while Xylem Inc. represents the IoT-enabled condition monitoring vector. These entities anchor premium municipal contracts through technology bundling rather than discrete equipment transactions. Regional specialists occupy mid-tier procurement where capital constraints favor hybrid system deployment.
| Leading Market Players |
|---|
| Evoqua Water Technologies |
| Kurita Water Industries Ltd. |
| Veolia Water Technologies & Solutions |
| Ovivo Inc. |
| Aquatech International |
| SUEZ |
| Pentair plc |
| Ecolab Inc. |
| Xylem Inc. |
| Others |
Value Network & Pricing Analysis
Stainless steel and specialty alloy concentration in German and Chinese metallurgical corridors anchors margin distribution across drum screen and fine-screen manufacturing tiers, with nickel and molybdenum price volatility compressing equipment suppliers while membrane-integrated system bundling captures premium value pools downstream.
Pricing Analysis
The EU Urban Wastewater Treatment Directive dictates the pricing tier structure across municipal procurement cycles, separating membrane-integrated premium configurations from standard mechanical assemblies. Three-tier pricing structure across premium, standard, and economy levels reflects aperture specification precision, ISO 9001 certification status, and predictive maintenance bundling. Cost compression in mid-tier mechanical systems is intensifying because stainless steel input volatility erodes fabricator margins. Municipal utilities in Germany and North America exhibit lowest price sensitivity due to outcome-based contracting pilots, while Indian and Australian coastal plants face acute capital constraints driving economy-tier procurement.
Supply Chain Analysis
Contract manufacturing for precision screen apertures and automated cleaning assemblies concentrates in Bavarian engineering corridors and North Rhine-Westphalia production clusters, with secondary capacity in Japanese Nagoya-Osaka manufacturing zones. Raw material sourcing draws from Chinese nickel processing, South Korean specialty steel production, and German precision machining inputs. Single-source vulnerability in molybdenum supply from limited global extractive operations creates exposure for fine-screen fabricators. Distribution runs through direct municipal utility procurement channels in developed markets and regional equipment distributors in emerging coastal infrastructure deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wastewater screening equipment fragmentation creates multiple entry niches as regulatory tightening around microplastic capture and membrane protection forces specification upgrades across municipal and industrial buyer archetypes.
For Market Incumbents: Insulate premium municipal relationships through predictive maintenance service bundling and remote diagnostics integration, countering margin pressure from stainless steel cost volatility by anchoring long-term outcome-based contracts in Bavarian and North Rhine-Westphalia engineering corridors. Backward integration into specialty alloy sourcing secures input cost stability for drum screen manufacturing. For New Entrants and Emerging Players: Build out hybrid system deployment capabilities targeting Australian and Indian coastal treatment plants where seasonal flow variability and capital constraints create white-space demand below full automation tiers. Microplastic capture technology convergence with rotary drum architectures offers the most penetrable application segment for differentiated entry. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automatic screening technology as IoT-enabled condition monitoring and sensor integration raise R&D thresholds. Target acquisition archetypes include regional engineering specialists with deep municipal procurement channel integration in German engineering corridors. The signal to watch is EU directive implementation timelines accelerating replacement cycles ahead of statutory deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Service Contracting | Bavarian utilities pilot outcome-based agreements shifting capital expenditure to operational expenditure structures with uptime guarantees. |
| Microplastic Capture Technology Integration | Advanced filtration media convergence with rotary drum architectures addresses emerging EU regulatory tailwinds on synthetic fiber interception. |
| IoT-Enabled Condition Monitoring Deployment | North American utilities bundle predictive maintenance capabilities reducing unplanned downtime in high-volume coastal treatment facilities. |
| Hybrid System Configuration Development | Australian and Indian coastal plants with seasonal flow variability demand automatic-manual override blending operational flexibility. |
| Engineering Corridor Partnership Expansion | German manufacturing clusters in Bavaria and North Rhine-Westphalia reconfigure production footprints for membrane-integrated screening assemblies. |
Research Methodology
The analysis maps fine-screen, rotary screen, bar screen, and coarse screen sub-sectors, each validated through municipal utility procurement officers, industrial plant engineers, equipment maintenance directors, and aftermarket service heads. Primary interviews combined with secondary validation from EPA enforcement databases, EU Urban Wastewater Treatment Directive revision documents, ISO certification registries, and India CPCB sewage treatment plant standards. Bottom-up equipment shipment triangulation with top-down municipal capital expenditure patterns anchored volume estimates.
Forecast assumptions held regulatory implementation timelines and stainless steel price volatility bands fixed while varying membrane bioreactor penetration rates and automatic technology displacement speed across municipal procurement cycles. Segmentation dimensions modeled include product type aperture specification, technology automation level, end-user procurement scale, and regional regulatory framework cluster. CAGRs derived from equipment replacement cycle acceleration patterns and infrastructure investment intensity indices.
Practitioners should monitor EU directive revision enforcement calendars, nickel and molybdenum exchange price movements, and microplastic capture mandate legislative progress for early signals of forecast revision triggers. Quarterly review of municipal tender issuance rates, membrane bioreactor installation permits, and automatic screening system commissioning data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Agricultural Wastewater Treatment Market
Water and Wastewater Treatment
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market
Water and Wastewater Treatment
Bio Filter Market
Water and Wastewater Treatment
Sewage Pump Market
Water and Wastewater Treatment
Javelle Water Market
Water and Wastewater Treatment
Wastewater Clarifier Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Global Wastewater Treatment Services Market
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
US Wastewater Secondary Treatment Equipment Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Mobile Wastewater Treatment Plant Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Global Vertical Sewage Pumps Market