
 Electrocoagulation Market | 2026-2036
Electrocoagulation Market Size, Share, and Industry Trends Forecast 2026-2036
Electrocoagulation Market Foresight
Performance-based service contracts for electrode replacement and sludge handling is decoupling capital equipment from recurring revenue streams. Ecolab leverages its chemical-services infrastructure to bundle electrocoagulation with coagulant supply, sustaining integrated account control across North American food-processing clients. Veolia dominates European municipal tenders through long-term operating contracts that embed electrode maintenance within broader water-management concessions. Genesis Water Technologies specializes in mobile unit deployment for oil-field brine treatment, competing on rapid mobilization rather than permanent installation scale.
Electrocoagulation employs sacrificial aluminum or iron anodes that release metallic ions under applied current, destabilizing colloidal pollutants and enabling subsequent separation by flotation or sedimentation; typical systems operate at current densities of 20-200 A/m² with contact times of 15-45 minutes for heavy metal reduction. Direct current configurations anchor existing installed base in mature industrial markets where simplicity outweighs efficiency gains, while pulsed current segments capture fastest expansion in dye-intensive textile clusters seeking reduced electrode consumption and energy recovery. Modular installations lead volume in remote mining and oil-field contexts where rapid redeployment offsets higher unit costs against stranded asset risk.
EPA effluent limitation guidelines under the Clean Water Act shape product design for US-bound systems, while EU REACH restrictions on hexavalent chromium discharge and the F-Gas Regulation's indirect pressure on energy-intensive alternatives reinforce electrocoagulation's competitive position against chemical precipitation in European metal-finishing applications. China's MEE enforces Class I discharge standards across Yangtze River Economic Belt provinces, compelling retrofit adoption in legacy electroplating facilities. Stakeholders must monitor electrode material cost trajectories and emerging sludge valorization pathways as these operational variables increasingly determine project economics against membrane and advanced oxidation alternatives.
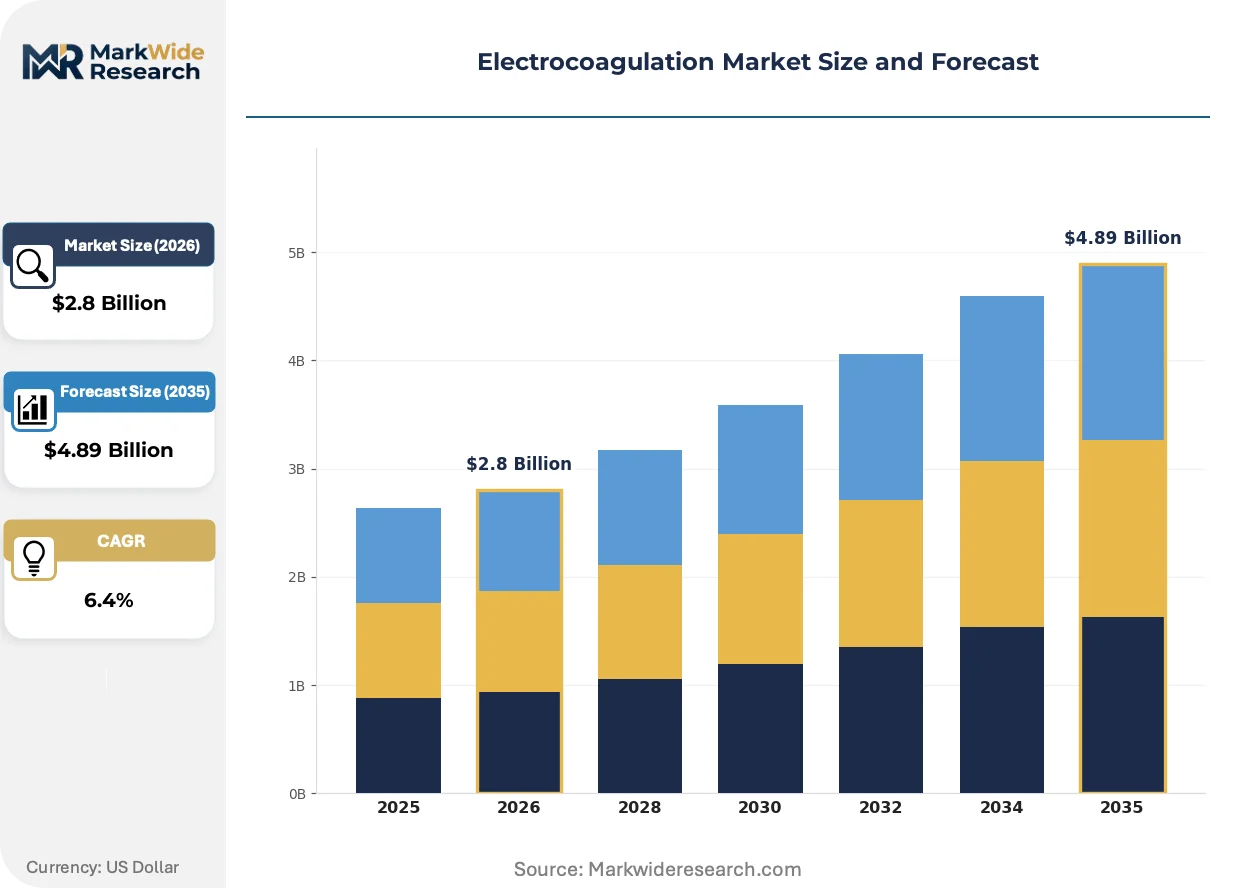
Market Dynamics
Pulsed current technology is compressing electrode consumption rates while EU wastewater directives force municipal facility retrofits across Germany and Scandinavia, restructuring competitive advantage toward energy efficiency rather than capital scale.
Growth Catalysts
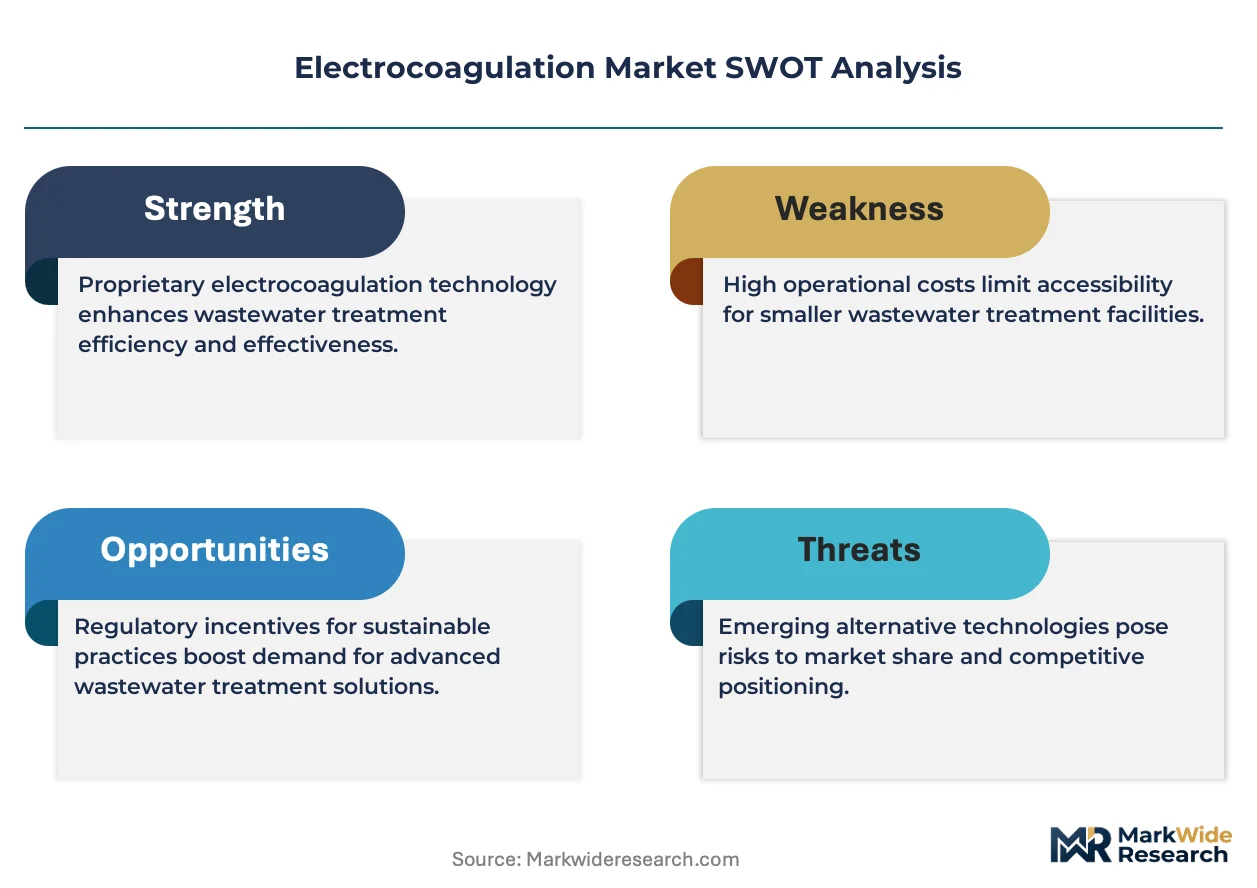
- MEE Class I Standards:China's Ministry of Ecology and Environment enforces discharge limits across Yangtze River Economic Belt provinces, compelling electroplating facility retrofits.
- Pulsed Current Systems:Dye-intensive textile clusters in Bangladesh and Vietnam adopt pulse-modulated power supplies to reduce aluminum anode dissolution rates.
- Oil-Field Brine Volumes:Permian Basin produced water treatment demand concentrates in Texas and New Mexico, where mobile electrocoagulation units displace chemical precipitation.
Market Restraints
- Aluminum Price Volatility:LME aluminum ingot fluctuations compress project IRRs for fixed-price electrode supply contracts in Indian metal-finishing clusters.
- Sludge Disposal Concentration:Hazardous waste landfill capacity constraints in Germany and the Netherlands inflate operating costs for high-solid-load electrocoagulation operations.
- Membrane Bioreactor Substitution:MBR technology captures pharmaceutical wastewater volumes where ultralow effluent phosphorus limits exceed electrocoagulation's single-stage capability.
Strategic Opportunities
- Indonesian Nickel Processing:Laterite ore refining expansion in Sulawesi and Halmahera creates untreated acid mine drainage treatment demand exceeding local chemical supply infrastructure.
- EU Critical Raw Materials Act:Domestic electrode manufacturing incentives for aluminum and iron anode production reduce import dependency for European system integrators.
- Photovoltaic Manufacturing:Silicon wafer cutting fluid recovery in Malaysia and Thailand integrates electrocoagulation with membrane filtration for closed-loop water reuse.
Industry Challenges
- Electrochemical Engineering Talent:Shortage of process designers capable of optimizing current density profiles for variable wastewater chemistries delays commissioning timelines.
- Legacy PLC Integration:Brownfield industrial sites in the US Rust Belt require custom control system bridges to connect pulsed current controllers with existing SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrocoagulation Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Direct Current, Pulsed Current, Alternating Current, Innovative Methods End User: Industrial Wastewater Treatment, Municipal Wastewater Treatment, Oil & Gas, Research Laboratories Application: Water Purification, Sludge Management, Heavy Metal Removal, Dye Removal Installation: Modular Systems, Custom-Built Systems, Mobile Units, Permanent Installations |
| Companies Covered | Ecolab, Veolia, SUEZ, Evoqua Water Technologies, Aqua-Aerobic Systems, H2O Innovation, Genesis Water Technologies, WaterTectonics, Nijhuis Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrocoagulation Market Shifts & Advancements
Electrode material science and power electronics convergence is compressing energy intensity benchmarks while regulatory discharge limits tighten across multiple industrial jurisdictions simultaneously.
Automated electrode wear monitoring using conductivity-based anode thickness sensors is automating replacement scheduling in continuous-flow municipal installations. German wastewater utilities pilot these systems to eliminate manual inspection cycles. Predictive algorithms reduce unplanned downtime by triggering maintenance before passivation layers degrade treatment efficiency.
REACH restrictions on hexavalent chromium discharge from metal-finishing operations tighten effluent thresholds across EU member states. Electrocoagulation captures plating shop volumes where chemical reduction processes face substitution pressure from F-Gas Regulation energy-intensity scrutiny. Italian and Polish surface treatment clusters accelerate system procurement to meet 2025 compliance deadlines.
Equipment-as-a-service contracting is displacing capital purchase models in North American food-processing plants. Ecolab and regional integrators bundle electrode replacement with chemical supply, compressing customer switching costs. California and Wisconsin dairy operations lead adoption where balance-sheet treatment favors operating expense classification over depreciation schedules.
Electrocoagulation Market Segmentation
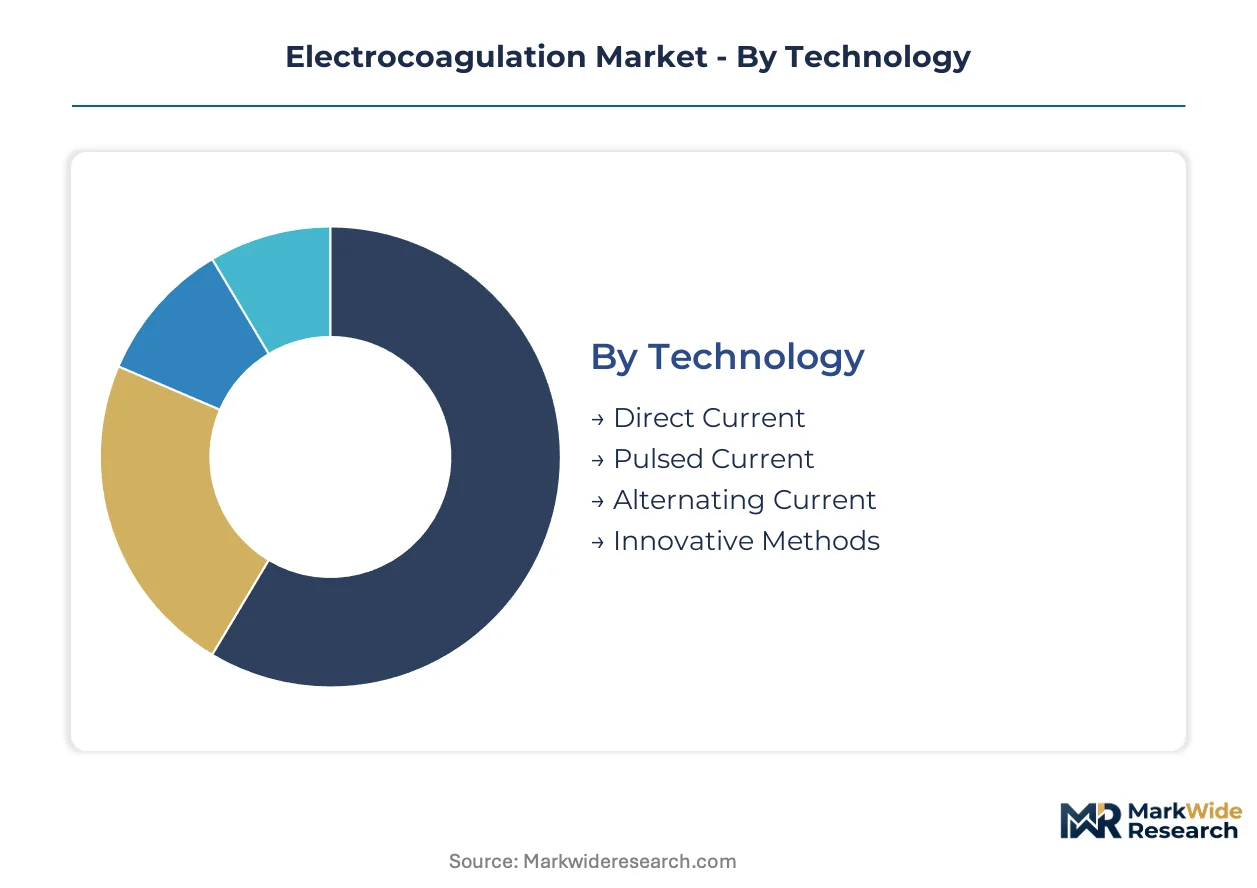
Technology choice determines electrode consumption rates and energy efficiency benchmarks, while installation type shapes capital deployment patterns across remote mining clusters versus urban municipal networks. End-user concentration in industrial wastewater versus municipal systems drives divergent service contract structures and equipment lifecycle expectations.
Technology:
Capital efficiency versus operational flexibility trade-offs dominate procurement decisions across power-intensive textile clusters and energy-constrained remote sites.
- Direct Current:Conventional DC configurations apply steady-state current densities of 20-200 A/m² through sacrificial aluminum or iron anodes. Mature industrial markets in the US Rust Belt favor this simplicity where maintenance familiarity outweighs efficiency premiums.
- Pulsed Current:Pulse-modulated power supplies interrupt current flow to reduce electrode dissolution rates and enable partial energy recovery. Dye-intensive textile clusters in Bangladesh and Vietnam adopt this technology fastest where aluminum anode costs dominate project economics.
- Alternating Current:AC systems minimize electrode polarization and extend operational cycles between replacement events. Research laboratories and pilot-scale installations employ AC configurations for variable wastewater chemistry testing.
- Innovative Methods:Hybrid electrochemical-photocatalytic approaches and bipolar electrode arrays target emerging contaminant classes including per- and polyfluoroalkyl substances.
Direct Current leads on scale; Pulsed Current leads on momentum.
End User:
Discharge permit stringency and sludge disposal infrastructure availability segment buyer priorities across compliance-driven versus cost-driven procurement contexts.
- Industrial Wastewater Treatment:Metal-finishing, textile dyeing, and food-processing facilities deploy electrocoagulation for heavy metal and suspended solids reduction. China's Yangtze River Economic Belt electroplating retrofits concentrate demand where MEE Class I standards compel technology substitution.
- Municipal Wastewater Treatment:Urban utilities integrate electrocoagulation as tertiary polishing for phosphorus removal and microplastic capture. German municipal tenders under revised EU Urban Wastewater Treatment Directive revisions expand adoption for nutrient recovery applications.
- Oil & Gas:Produced water treatment in Texas and New Mexico Permian Basin operations favors mobile electrocoagulation units over fixed chemical precipitation infrastructure. Rapid redeployment between well pads offsets higher unit capital costs.
- Research Laboratories:Academic and government testing facilities employ bench-scale and pilot systems for process optimization studies and emerging contaminant treatability assessments.
Industrial Wastewater Treatment commands installed base volume; Oil & Gas shows steepest expansion trajectory.
Application:
Contaminant class and target effluent quality determine electrode material selection and current density programming requirements.
- Water Purification:Suspended solids and colloidal destabilization for potable water pretreatment and process water recycling. Semiconductor fabrication facilities in Malaysia and Thailand integrate electrocoagulation with membrane filtration for closed-loop ultrapure water systems.
- Sludge Management:Electrocoagulation reduces sludge volume and improves dewaterability compared to chemical precipitation, though hazardous waste landfill constraints in Germany and the Netherlands inflate disposal costs for high-solid-load operations.
- Heavy Metal Removal:Hexavalent chromium, cadmium, and nickel reduction for metal-finishing effluent compliance. EU REACH restrictions and F-Gas Regulation energy-intensity scrutiny displace chemical reduction processes in Italian and Polish surface treatment clusters.
- Dye Removal:Color and COD reduction for textile wastewater where azo dye breakdown requires optimized current density profiles. Bangladesh and Vietnam dye houses adopt pulsed current systems specifically for this application.
Heavy Metal Removal anchors regulatory-driven procurement; Dye Removal is gaining share fastest in Asian textile manufacturing zones.
Installation:
Asset mobility requirements and site infrastructure permanence dictate equipment configuration and financing structure preferences.
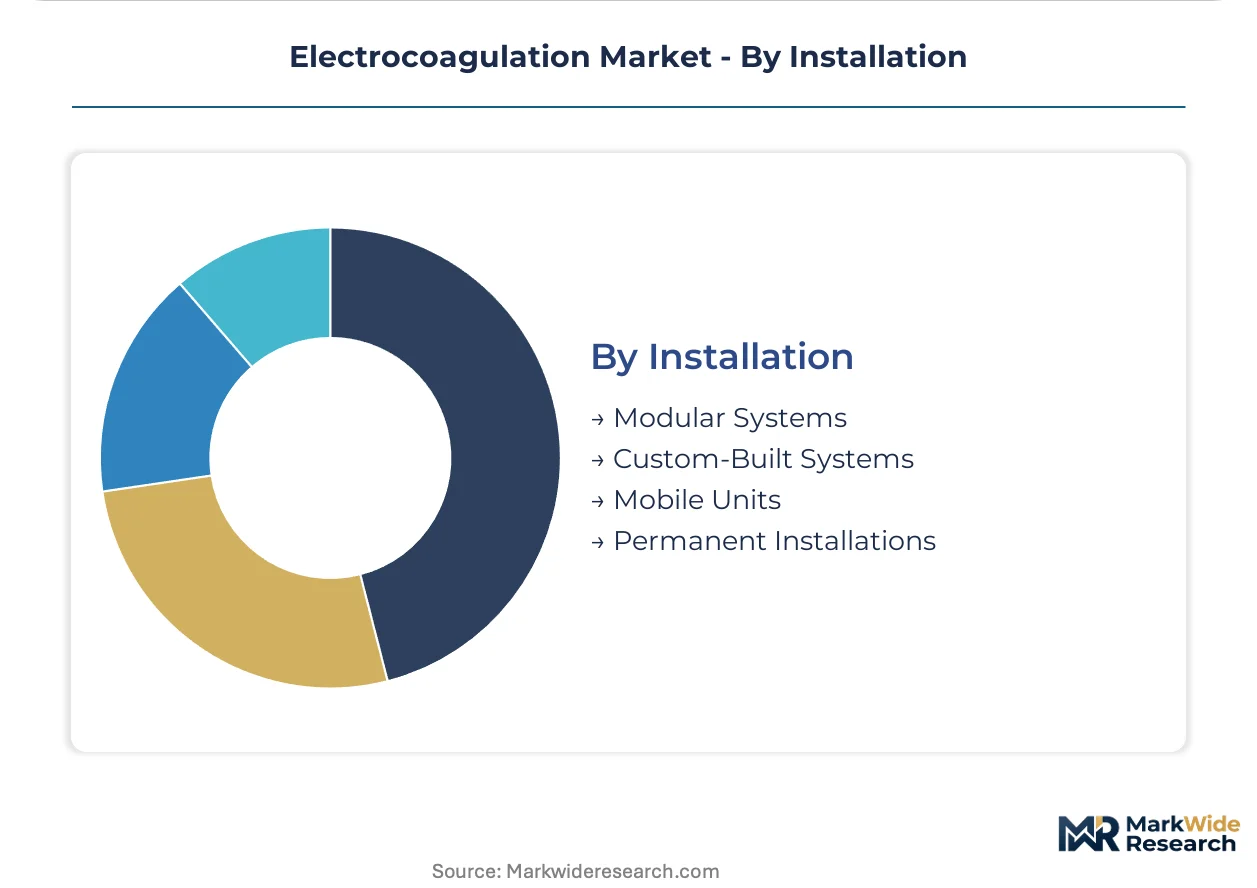
- Modular Systems:Containerized or skid-mounted units enable rapid deployment and capacity scaling. Remote mining operations in Indonesian nickel processing zones favor modular configurations where ore body exhaustion timelines create stranded asset risk.
- Custom-Built Systems:Engineered installations for high-flow municipal or industrial facilities with site-specific hydraulic and electrical integration requirements. German wastewater utilities specify custom configurations for automated electrode wear monitoring integration.
- Mobile Units:Truck-mounted or trailer-based systems for temporary or emergency treatment needs. Oil-field service providers in Texas deploy mobile electrocoagulation for produced water treatment with rapid well-to-well relocation.
- Permanent Installations:Fixed civil works with integrated power distribution and sludge handling infrastructure. European municipal concessions under long-term operating contracts favor permanent installations for lifecycle cost optimization.
Permanent Installations dominate cumulative capacity; Modular Systems show strongest growth in resource extraction frontiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrocoagulation system procurement patterns track regulatory-arbitrage dynamics, with capital migrating toward jurisdictions where discharge enforcement creates cost-of-compliance premiums against legacy chemical treatment alternatives.
Germany
Municipal wastewater utilities in North Rhine-Westphalia and Bavaria accelerate electrocoagulation adoption under revised EU Urban Wastewater Treatment Directive revisions targeting nutrient recovery. The F-Gas Regulation's energy-intensity scrutiny reinforces competitive positioning against chemical precipitation in metal-finishing applications. Stuttgart and Munich industrial clusters drive demand for automated electrode wear monitoring systems.
China
MEE Class I discharge standards across Yangtze River Economic Belt provinces compel electroplating facility retrofits in Jiangsu and Zhejiang provinces. Tightening enforcement of discharge limits concentrates demand in coastal manufacturing zones where legacy facilities face technology substitution pressure. Shanghai and Suzhou industrial parks anchor the regional installed base expansion.
United States
EPA effluent limitation guidelines under the Clean Water Act shape product design for Permian Basin oil-field brine treatment applications in Texas and New Mexico. Mobile electrocoagulation units displace fixed chemical precipitation infrastructure where rapid well-to-well redeployment offsets higher unit capital costs. Houston and Midland service providers dominate equipment deployment.
Bangladesh
Dye-intensive textile clusters in Dhaka and Chittagong adopt pulsed current systems to reduce aluminum anode dissolution rates and compress operating expenditures. Garment export compliance requirements from EU buyers drive technology substitution in wastewater treatment infrastructure. Narayanganj and Gazipur industrial zones concentrate procurement activity.
Indonesia
Laterite ore refining expansion in Sulawesi and Halmahera creates untreated acid mine drainage treatment demand exceeding local chemical supply infrastructure. Nickel processing facility commissioning timelines accelerate electrocoagulation adoption where modular configurations address stranded asset risk from ore body exhaustion. Morowali Industrial Park anchors regional demand concentration.
Electrocoagulation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated water-management conglomerates dominating European municipal concessions while regional fabricators capture mobile unit deployment in resource extraction frontiers. The competitive structure tiered across three archetypes: full-service water utilities bundling electrocoagulation within long-term operating contracts, specialized equipment fabricators competing on rapid mobilization and customization, and chemical-services providers leveraging existing account relationships to cross-sell electrochemical systems. Dominant competitive moves include strategic partnerships between power electronics suppliers and system integrators, plus geographic expansion through equipment-as-a-service contracting models that compress customer switching costs.
Within the integrated utilities tier, Ecolab and Veolia exemplify divergent regional strategies, with the former leveraging North American chemical-services infrastructure and the latter dominating European municipal tenders through concession-based operating contracts. Genesis Water Technologies occupies a position among specialized fabricators, competing on mobile unit deployment for oil-field applications rather than permanent installation scale. These three anchors illustrate how competitive positioning fragments across service-model archetypes rather than consolidating around technology leadership alone.
| Leading Market Players |
|---|
| Ecolab |
| Veolia |
| SUEZ |
| Evoqua Water Technologies |
| Aqua-Aerobic Systems |
| H2O Innovation |
| Genesis Water Technologies |
| WaterTectonics |
| Nijhuis Industries |
| Others |
Supply & Pricing Matrix
EU Urban Wastewater Treatment Directive revisions are compelling German municipal utilities to specify automated electrode wear monitoring systems, forcing suppliers to absorb certification costs for predictive maintenance integration and compressing margins on standardized DC configurations.
Pricing Analysis
Distributor margins of 12-18 percent on modular systems widen to 25-30 percent for custom municipal installations with embedded service contracts. Three-tier pricing structure across premium pulsed-current systems, standard DC configurations, and economy-grade mobile units segments buyer access by capital availability and operating expense classification. Pricing pressure stems from aluminum ingot volatility transmitted through fixed-price electrode supply agreements in Indian metal-finishing clusters. Municipal wastewater utilities exhibit lowest price sensitivity due to concession-based financing, while remote mining operators prioritize lowest capital outlay despite higher lifecycle costs.
Supply Chain Analysis
Freight costs for containerized modular systems from Chinese coastal manufacturing zones to Indonesian nickel processing sites in Sulawesi and Halmahera add 8-12 percent to delivered equipment costs, incentivizing regional fabrication partnerships. Aluminum anode supply concentrates in China, India, and Russia, with power electronics sourcing anchored in Germany, Japan, and Taiwan. The supply chain draws from LME-linked commodity exposure for sacrificial electrodes and semiconductor-grade components for pulse-modulated controllers. Single-source vulnerability sits with high-frequency power supply modules from specialized German and Japanese fabricators. Distribution runs through water-management conglomerates in European municipal markets and oil-field service integrators in North American resource extraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where MEE Class I discharge standards across China's Yangtze River Economic Belt provinces create sustained retrofit demand independent of industrial capital cycles.
For Market Incumbents: Deepen backward integration into aluminum electrode casting to offset LME price volatility exposure in fixed-price municipal contracts. Expand automated wear monitoring R&D partnerships with German wastewater utilities to lock in specification advantages against pulsed-current challengers. Membrane bioreactor substitution in pharmaceutical wastewater applications threatens single-stage electrocoagulation positioning, requiring phosphorus-removal performance upgrades or hybrid system development. For New Entrants and Emerging Players: Launch via equipment-as-a-service contracting in North American food-processing plants where Ecolab's chemical-services bundling has proven the model but left mid-tier dairy and meat-processing accounts underserved. Target Indonesian nickel processing acid mine drainage treatment where laterite ore refining expansion outpaces local chemical supply infrastructure. Photovoltaic manufacturing silicon wafer cutting fluid recovery in Malaysia and Thailand offers white-space entry with closed-loop water reuse integration. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized fabricators holding mobile unit deployment capabilities for oil-field brine treatment, where Permian Basin produced water volumes concentrate demand and rapid well-to-well relocation creates service stickiness. Five-to-ten year viability hinges on sludge valorization pathway maturation reversing hazardous waste landfill cost inflation in European operations. Watch for electrode material science breakthroughs targeting PFAS degradation as inflection indicators for technology leadership repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Electrode Material Science Partnership | Collaboration with German research institutes accelerates PFAS-targeting bipolar electrode array commercialization. |
| Equipment-as-a-Service Expansion | California and Wisconsin dairy operations favor operating expense classification over capital depreciation schedules. |
| Mobile Unit Fleet Scaling | Texas Permian Basin service providers capture produced water treatment demand through rapid well-to-well redeployment. |
| Automated Wear Monitoring Integration | North Rhine-Westphalia utilities pilot conductivity-based anode thickness sensors to eliminate manual inspection cycles. |
| Regional Fabrication Localization | Indonesian nickel processing demand in Morowali Industrial Park rewards Sulawesi-based modular assembly partnerships. |
Research Methodology
Coverage spans Germany, China, the United States, Bangladesh, and Indonesia, with primary inputs from each market's wastewater utility planning officers, electroplating facility maintenance directors, oil-field service procurement teams, textile dye house operations managers, and nickel processing plant engineers. Secondary validation drew from EPA effluent limitation guidelines, EU Urban Wastewater Treatment Directive revision documents, MEE discharge standard enforcement records, LME aluminum price series, and SEC filings from publicly traded water-management conglomerates. Bottom-up project pipeline assessment triangulated against top-down regulatory mandate quantification.
Rate-of-change decomposition separated volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include technology type, end-user category, application focus, and installation configuration, with regional regulatory enforcement intensity as an overlay variable. CAGRs were derived from fitted trend extrapolation moderated by electrode material cost trajectory scenarios and sludge disposal capacity constraints in key European markets. Industry-specific inputs incorporated pulsed-current adoption curves in Bangladeshi textile clusters and mobile unit deployment rates in Permian Basin oil-field operations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum price spike conditions or accelerated membrane bioreactor cost reductions in pharmaceutical applications. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
Latin America Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Wastewater Clarifier Market
Water and Wastewater Treatment
Commercial Atmospheric Water Generator Market
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
Global Wastewater Treatment Services Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Mobile Wastewater Treatment Plant Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
US Wastewater Secondary Treatment Equipment Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Sewage Treatment Service Market
Water and Wastewater Treatment
Ecological Wastewater Treatment Market
Water and Wastewater Treatment
Aeration Pads Market