
 Borehole Yield Testing Market | 2026-2036
Borehole Yield Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Borehole Yield Testing Market Outlook
Direct-to-municipality contracting channels is reshaping how borehole yield testing services reach public water utilities, bypassing traditional generalist distributors. Schlumberger Limited leverages its deep subsurface diagnostics heritage to anchor premium testing portfolios across Middle Eastern and North African markets. Halliburton Company sustains competitive positioning through integrated well-construction-to-testing workflows that reduce mobilization costs for clients. Baker Hughes Company differentiates via digital monitoring platforms that embed yield data directly into long-term aquifer management dashboards.
Borehole yield testing measures the sustainable water discharge rate from drilled wells through controlled pumping protocols, typically recording drawdown recovery curves over 24–72 hour test cycles to determine transmissivity and storativity coefficients. The primary commercial purpose is to certify aquifer productivity for water rights allocation, irrigation design, and municipal supply engineering. Pumping tests dominate methodology revenue due to regulatory mandates for extended-duration certification across most jurisdictions, while digital monitoring technology captures expanding margin pools as utilities shift from manual data logging to continuous telemetry-based aquifer surveillance. Environmental studies applications are gaining traction fastest where contaminated site remediation requires precise plume capture rate verification before pump-and-treat system design.
The EPA enforces Underground Injection Control standards that influence yield testing scope when boreholes intersect potential drinking water aquifers, while ISO 14686 provides international methodological benchmarks for pumping test execution and reporting. India's Central Ground Water Authority mandates yield certification under its groundwater regulation framework, creating compliance-driven demand spikes in states with critical overextraction notifications. Stakeholders must monitor how fragmented national groundwater laws evolve toward harmonized transboundary aquifer protocols, as this will determine whether testing providers invest in portable multi-standard equipment platforms or region-specific certification specializations.
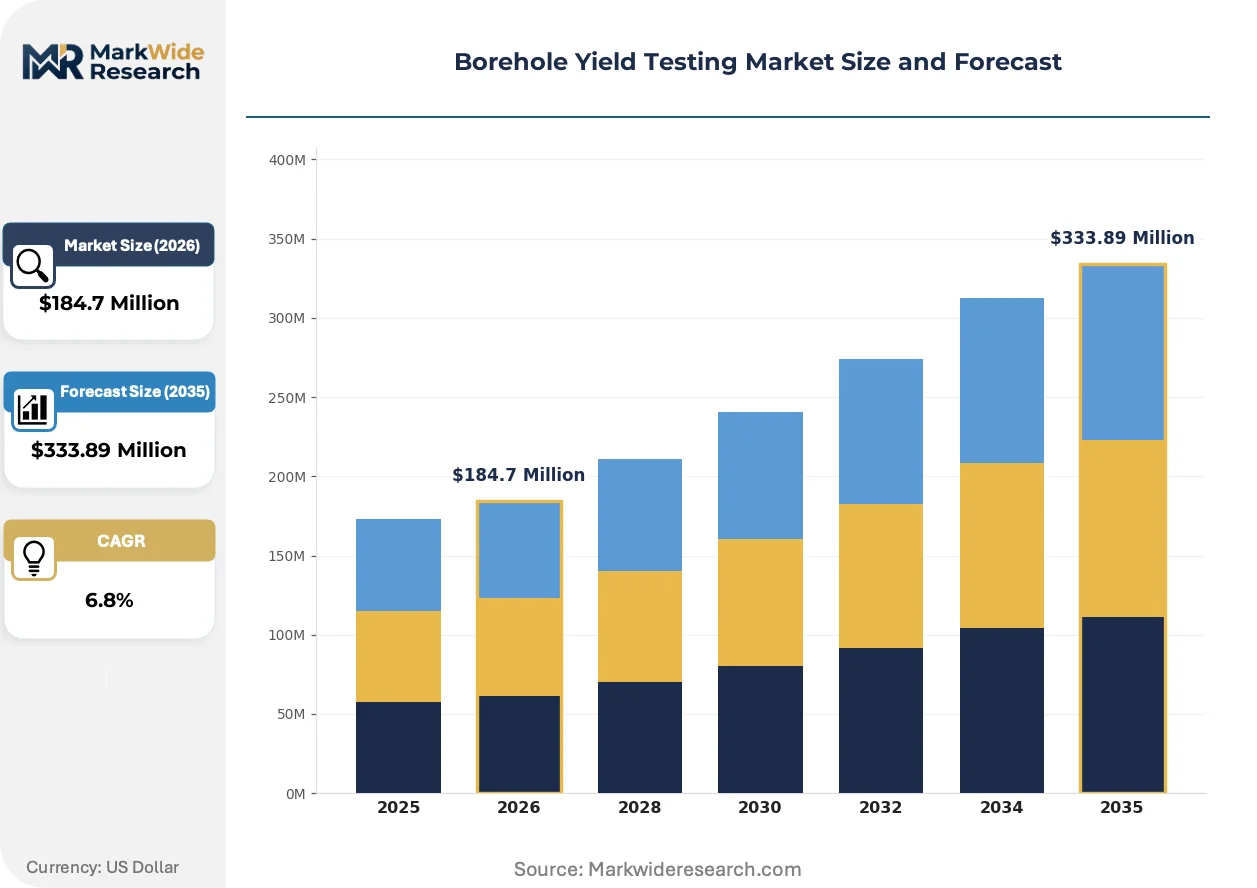
Market Dynamics
Groundwater extraction permits are tightening across jurisdictions, forcing agricultural cooperatives and municipal utilities to document sustainable yield before pump installation. This regulatory compression is accelerating certification demand and reshaping how testing services contract with end-users.
Growth Catalysts
- EU Water Framework Directive:Stricter aquifer protection mandates across member states require extended-duration pumping tests for all new boreholes intersecting designated groundwater bodies.
- Irrigation cooperatives:Agricultural water security programs in water-stressed regions are embedding yield certification into collective infrastructure financing packages.
- Digital telemetry:Continuous aquifer monitoring platforms are creating recurring revenue streams beyond one-time certification events.
Market Restraints
- Diesel price volatility:Pumping test mobilization depends on generator fuel, with cost spikes compressing field margins for fixed-price contracts.
- Equipment supply concentration:Precision transducers and data loggers source primarily from German and Swiss sensor manufacturers, creating import dependency for testing firms in emerging markets.
- Transmissivity estimation uncertainty:Heterogeneous fractured rock aquifers defy standard analytical solutions, limiting test reliability in crystalline basement regions.
Strategic Opportunities
- Contaminated site remediation:Pump-and-treat system design requires precise plume capture rate verification, opening environmental consulting channels.
- India's state groundwater authorities:Mandated yield certification before agricultural electrical connections creates compliance-driven demand concentration.
- Cloud-based aquifer management dashboards:Integration of yield data with long-term water balance modeling is virtualizing client relationships beyond test execution.
Industry Challenges
- Hydrogeologist talent scarcity:Specialized expertise in pumping test design and analytical solution selection constrains service expansion.
- Multi-standard equipment platforms:Fragmented national groundwater laws force capital allocation toward portable systems capable of ISO 14686, EPA Underground Injection Control, and jurisdiction-specific protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Borehole Yield Testing Market |
| Market Size in 2026 | $184.7 Million |
| Market Size in 2035 | $333.89 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Methodology: Pumping Tests, Slug Tests, Swabbing, Borehole Camera Surveys Application Type: Agricultural Uses, Industrial Supplies, Municipal Water, Environmental Studies Technology: Electromagnetic, Hydraulic, Mechanical, Digital Monitoring End User: Water Utilities, Agricultural Sector, Environmental Agencies, Drilling Contractors |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, GEOSS, Midland Pumps, Marines Well Services Limited, Bhoojal Survey and Recharging, Geotech Solutions Inc., Fugro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Borehole Yield Testing Market Strategic Shifts
Digital instrumentation is compressing test cycles while expanding data granularity. Automation and remote telemetry are shifting value capture from field labor to software-enabled aquifer intelligence.
Continuous drawdown monitoring via satellite-linked pressure transducers is virtualizing traditional manual observation well networks. Municipal utilities in Australia and the southwestern United States are deploying these systems to replace 24-hour technician presence during extended pumping tests. The technology is virtualizing labor-intensive data collection into automated anomaly detection and predictive storativity modeling.
India's Central Ground Water Authority enforcement actions against overextraction are mandating real-time telemetry for agricultural boreholes in critical notification areas. State-level regulators in Gujarat and Punjab now require digital flow meters with cellular backhaul before electrical pump connections are authorized. Equipment providers are responding with solar-powered, tamper-evident monitoring packages priced for smallholder cooperative budgets.
Direct contracting between testing specialists and public water utilities is displacing generalist environmental consultants as the primary procurement channel. Municipal engineering departments in Saudi Arabia, South Africa, and Chile are establishing framework agreements with borehole yield testing firms for multi-year aquifer monitoring programs. This pattern concentrates procurement authority with technical buyers who prioritize ISO 14686 methodological rigor over lowest-bid compliance documentation.
Borehole Yield Testing Market Segmentation
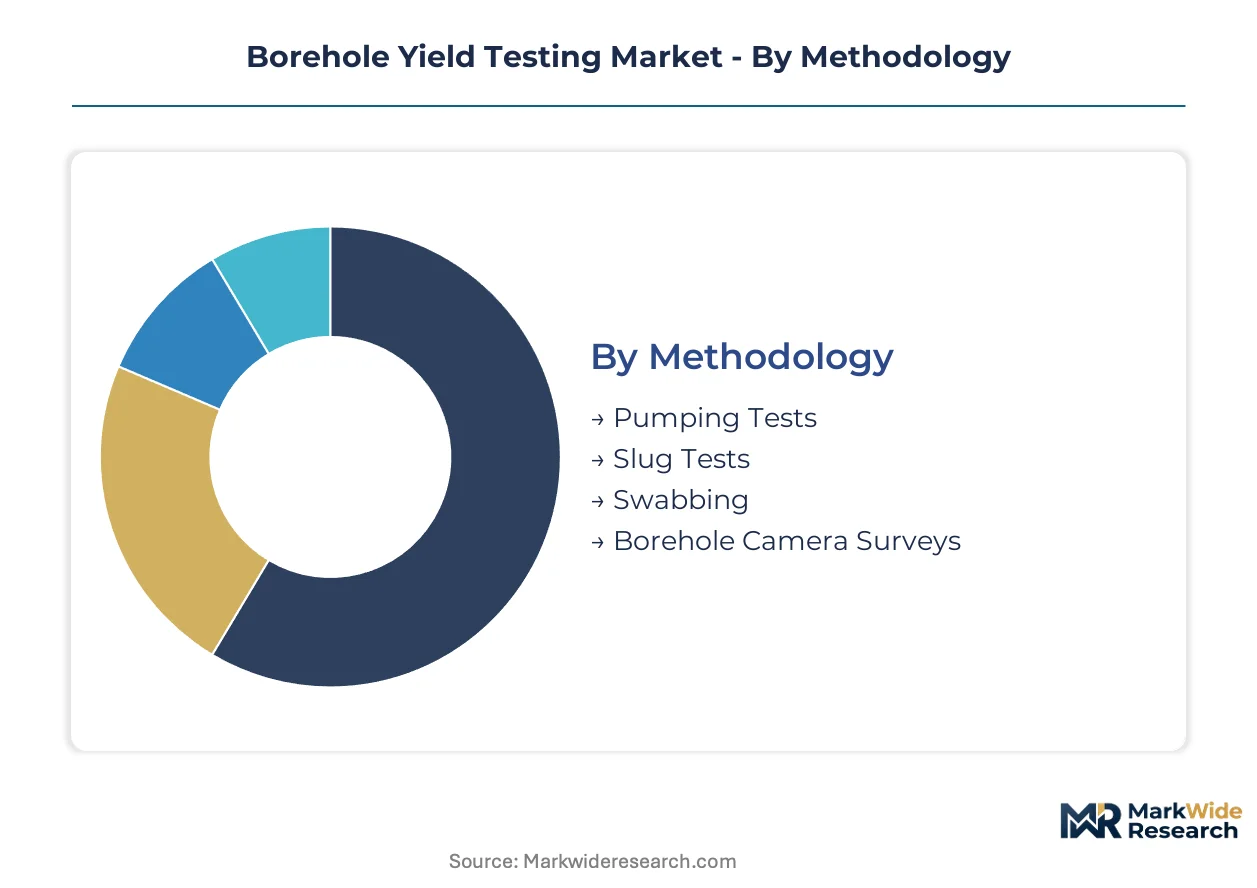
Borehole yield testing services fragment across methodological traditions, application domains, and technology generations. Procurement patterns differ sharply between compliance-driven agricultural certification and predictive municipal aquifer management.
Methodology:
Mature pumping protocols dominate revenue while emerging rapid-assessment techniques gain traction in preliminary screening applications.
- Pumping Tests:Extended-duration drawdown-recovery protocols lasting 24–72 hours establish transmissivity and storativity coefficients for regulatory certification. India's Central Ground Water Authority mandates these tests before agricultural electrical connections, concentrating demand in Gujarat and Punjab irrigation districts.
- Slug Tests:Rapid water-level displacement methods using instantaneous injection or withdrawal provide transmissivity estimates without sustained pumping. Environmental consultants in contaminated site remediation deploy these for plume capture feasibility screening where full pumping tests prove cost-prohibitive.
- Swabbing:Mechanical borehole cleaning and yield stimulation through repeated surging operations.
- Borehole Camera Surveys:Downhole visual inspection for fracture identification and casing integrity verification.
Pumping Tests retain volume leadership; Slug Tests hold the steepest expansion curve.
Application Type:
Cost tiers separate capital-intensive municipal infrastructure from dispersed agricultural compliance spending.
- Agricultural Uses:Irrigation cooperatives and large-scale farming operations require yield certification for groundwater extraction permits. State-level authorities in water-stressed regions embed testing into collective infrastructure financing, with India's notification system driving concentrated procurement.
- Municipal Water:Public utilities commission extended-duration tests for wellfield design and water rights allocation. Saudi Arabian and Chilean municipalities are establishing multi-year framework agreements with testing specialists, displacing generalist environmental consultants.
- Industrial Supplies:Manufacturing and mining operations verify sustainable extraction rates for process water security.
- Environmental Studies:Contaminated site remediation demands precise plume capture rate verification before pump-and-treat system design, with this channel gaining share fastest among application categories.
Agricultural Uses command the largest addressable base; Environmental Studies are expanding most quickly.
Technology:
Customer type divides the market between legacy hydraulic instrumentation and digitally native monitoring platforms.
- Digital Monitoring:Satellite-linked pressure transducers and cellular-enabled flow meters enable continuous aquifer surveillance beyond one-time certification events. Australian and southwestern US utilities deploy these systems to replace 24-hour technician presence, virtualizing labor into predictive storativity modeling.
- Hydraulic:Conventional pump-and-measure systems using manometer-based drawdown recording remain standard for regulatory compliance documentation.
- Electromagnetic:Borehole logging tools for aquifer boundary delineation and fracture trace mapping.
- Mechanical:Manual depth sounding and bailer-based sampling equipment for basic yield estimation.
Hydraulic technology retains installed-base dominance; Digital Monitoring is climbing the fastest.
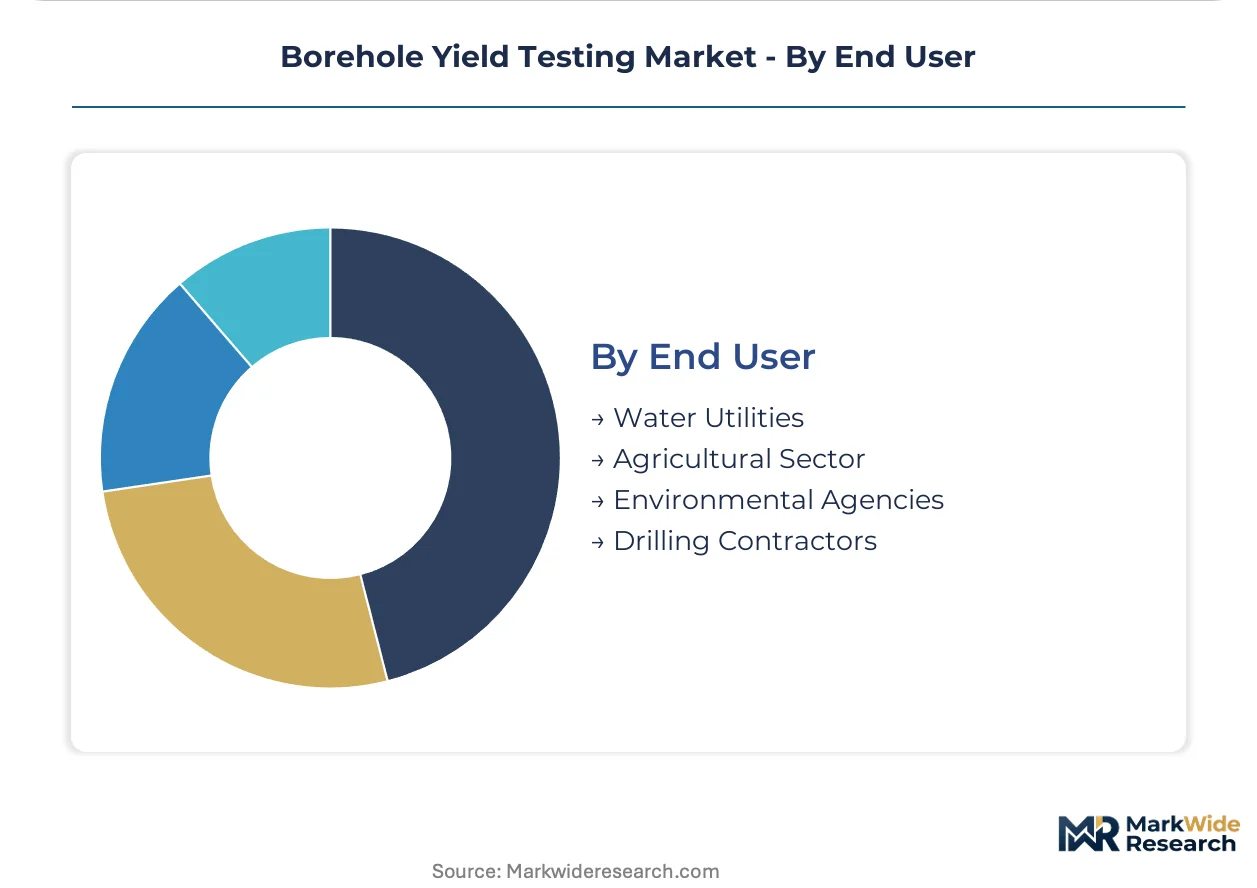
End User:
Supply concentration among specialized hydrogeology firms shapes how each buyer category accesses testing services.
- Water Utilities:Municipal engineering departments prioritize ISO 14686 methodological rigor in direct framework agreements with testing specialists. Procurement authority concentrates with technical buyers who value long-term aquifer management dashboards over lowest-bid documentation.
- Drilling Contractors:Well construction firms integrate yield testing into integrated well-completion workflows to reduce client mobilization costs. Halliburton Company anchors this channel through construction-to-testing bundling.
- Agricultural Sector:Irrigation cooperatives and individual farmers respond to state-mandated certification requirements before pump installation authorization.
- Environmental Agencies:Regulators and remediation consultants commission testing for contaminated site oversight and enforcement documentation.
Water Utilities represent the highest-value contracting channel; Agricultural Sector covers the broadest geographic dispersion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-African Water Pipeline corridor and India's National Water Grid interconnects anchor regional demand concentration for borehole yield certification services.
United States
Southwestern aquifer systems in Arizona and California drive municipal utility procurement of extended-duration pumping tests. EPA Underground Injection Control standards tighten testing scope where boreholes intersect drinking water aquifers. Phoenix and Los Angeles water departments deploy satellite-linked pressure transducers to virtualize technician presence during 72-hour certification cycles.
India
Gujarat and Punjab irrigation districts concentrate agricultural compliance demand for state-mandated yield certification. The Central Ground Water Authority mandates real-time telemetry with cellular backhaul before electrical pump connections in critical overextraction notification areas. State groundwater authorities in Haryana and Rajasthan are expanding digital flow meter requirements to smallholder cooperative budgets.
Saudi Arabia
NEOM and Riyadh municipal engineering departments establish multi-year framework agreements with testing specialists for wellfield design. The national water regulator requires ISO 14686 methodological rigor for all new boreholes intersecting designated groundwater bodies. Eastern Province utilities prioritize continuous aquifer monitoring platforms over one-time certification events.
Australia
Murray-Darling Basin irrigation cooperatives embed yield certification into collective infrastructure financing packages. State-level environmental protection agencies mandate extended-duration tests for groundwater extraction permits in water-stressed catchments. Queensland and New South Wales utilities deploy automated anomaly detection systems to replace manual observation well networks.
Germany
EU Water Framework Directive implementation tightens aquifer protection mandates across Baden-Württemberg and Bavaria industrial clusters. Federal state environmental agencies require 24–72 hour pumping tests for all new boreholes intersecting designated groundwater bodies. Precision transducer supply from German sensor manufacturers creates equipment concentration for testing firms serving Central European markets.
Borehole Yield Testing Market Competitive Environment
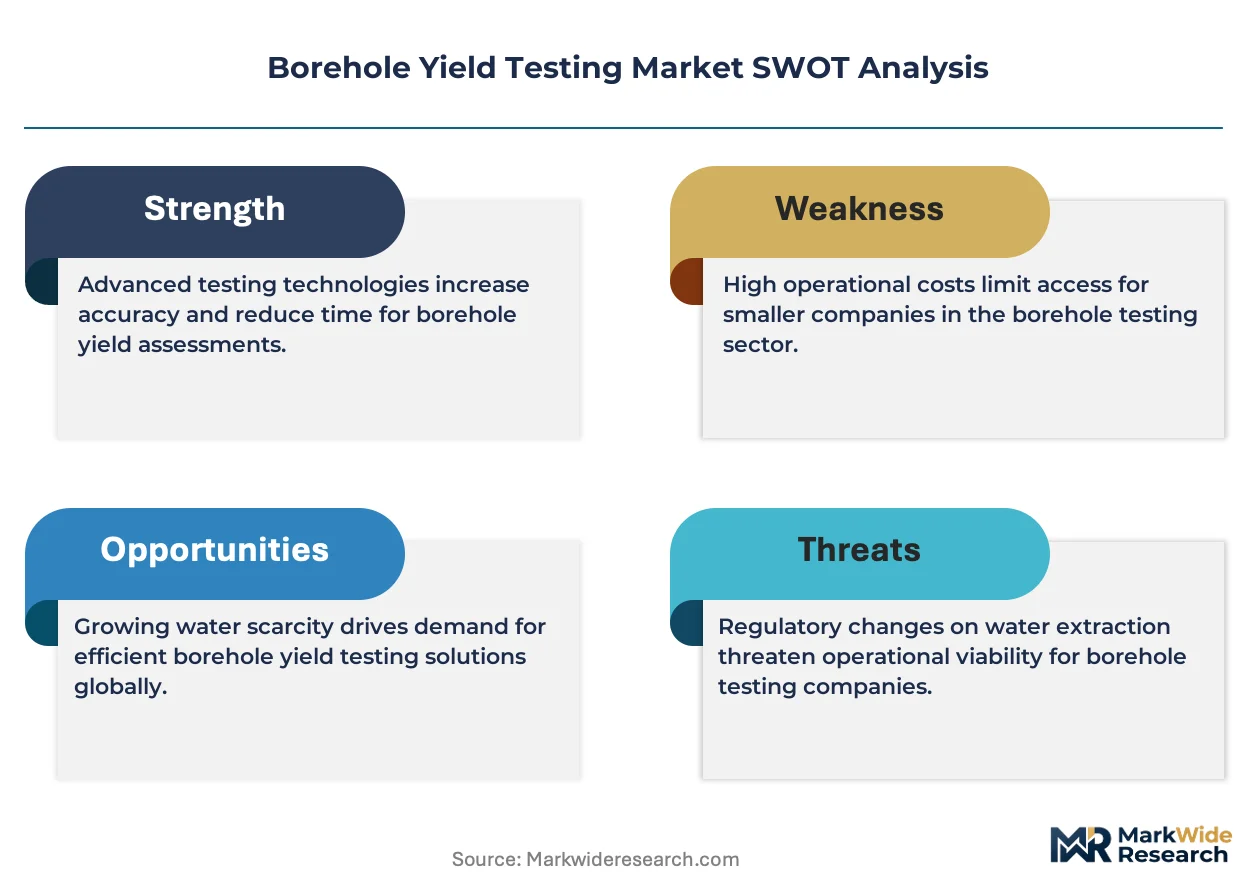
On the supply side, the industry is consolidating around integrated well-construction-to-testing workflows and digital monitoring platforms. Tiered competition separates premium aquifer management specialists from compliance-focused regional operators. Three archetypes dominate: oilfield services heritage firms with subsurface diagnostics capabilities, dedicated hydrogeology consultancies with ISO 14686 certification authority, and equipment manufacturers bundling sensor hardware with field service contracts. M&A activity concentrates on digital telemetry capabilities, while strategic partnerships lock in municipal framework agreements.
Among oilfield services heritage firms, Schlumberger Limited, Halliburton Company, and Baker Hughes Company anchor premium testing portfolios across Middle Eastern and North African markets. These entities exemplify the integrated workflow archetype, reducing client mobilization costs through construction-to-testing bundling. Their positioning sits within the high-value municipal and industrial supply segments where methodological rigor commands procurement priority over lowest-bid documentation.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| GEOSS |
| Midland Pumps |
| Marines Well Services Limited |
| Bhoojal Survey and Recharging |
| Geotech Solutions Inc. |
| Fugro |
| Others |
Value Chain & Pricing Dynamics
Idle pumping test capacity across South African and Australian hydrogeology consultancies is compressing project margins and forcing equipment-heavy firms toward multi-year municipal framework agreements that lock in utilization. Diesel generator fuel costs and German-sourced precision transducer procurement dominate supplier behavior, with pricing posture shifting from fixed-rate certification toward telemetry-enabled recurring revenue models.
Pricing Analysis
Volume-discount tiering separates ISO 14686-certified premium specialists from compliance-focused regional operators and economy-grade manual testing providers. Price differentiation rests on certification authority depth and after-sales telemetry bundling, with premium tiers capturing multi-year aquifer management dashboards. Pricing pressure stems from diesel price volatility eroding fixed-contract field margins. Agricultural cooperatives in Gujarat and Punjab exhibit highest price sensitivity, while Saudi Arabian municipal engineering departments prioritize methodological rigor over lowest-bid procurement.
Supply Chain Analysis
Upstream feedstock for precision pressure transducers and data loggers draws from German and Swiss sensor manufacturers, creating import dependency for testing firms in India and South Africa. Raw material dependencies center on piezoelectric ceramics, titanium alloy casings, and cellular telemetry modules. Supply chain risk concentrates in single-source vulnerability for ISO-calibrated instrumentation. Distribution runs through direct-to-municipality contracting channels that displace generalist environmental consultants, with drilling contractors integrating testing into bundled well-completion workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized hydrogeologist expertise constrains service expansion across all major demand clusters, with pumping test design and analytical solution selection capabilities determining competitive viability. This scarcity dynamic rewards early certification investment and talent pipeline development.
For Market Incumbents: Harden defensive positioning through backward integration into precision transducer calibration facilities and captive hydrogeologist training programs. Digital telemetry platform consolidation threatens standalone testing providers; anchor client relationships via cloud-based aquifer management dashboards that virtualize one-time certification into recurring surveillance contracts. Capacity addition in Gujarat and Punjab irrigation districts captures India's compliance-driven demand concentration. For New Entrants and Emerging Players: Build out contaminated site remediation channels where plume capture verification requirements outstrip specialist supply. Environmental consulting white space in fractured rock aquifer regions offers penetrable entry points given standard analytical solution limitations. Target agricultural electrical connection compliance in Rajasthan and Haryana as state groundwater authorities expand digital flow meter mandates. Go-to-market leverage rests on solar-powered, tamper-evident monitoring packages priced for smallholder cooperative budgets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital telemetry-enabled aquifer surveillance providers with municipal framework agreement lock-in. Long-term viability over the projection horizon favors acquisition targets combining ISO 14686 certification authority with satellite-linked pressure transducer deployment capabilities. Watch India's Central Ground Water Authority enforcement actions against overextraction as inflection indicators for telemetry mandate expansion into additional state notification areas.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Telemetry Platform Deployment | Virtualizes labor-intensive manual observation into predictive storativity modeling for Australian and southwestern US utilities. |
| ISO 14686 Certification Investment | Unlocks premium municipal procurement in Saudi Arabia where national water regulators mandate methodological rigor. |
| Backward Integration into Sensor Calibration | Reduces import dependency on German manufacturers for emerging market testing firms. |
| Contaminated Site Remediation Channel Entry | Captures fastest-expanding application segment through plume capture rate verification services. |
| Agricultural Cooperative Financing Partnership | Embeds yield certification into collective infrastructure packages across Murray-Darling Basin irrigation districts. |
Study Parameters
A spread of perspectives from hydrogeology consultants, municipal water utility engineering directors, agricultural cooperative managers, and precision sensor procurement leads converged on the working assumptions. Primary interviews with drilling contractors and environmental remediation specialists combined with secondary validation from EPA Underground Injection Control filings, EU Water Framework Directive implementation reports, India's Central Ground Water Authority notifications, and ISO 14686 methodological documentation. Bottom-up project pipeline assessment and top-down regulatory mandate analysis triangulated volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by methodology, application type, technology generation, and end-user procurement authority. CAGRs derived from installed base replacement cycles and regulatory compliance deadline clustering. Industry-specific forecast inputs included state-level groundwater authority notification expansion timelines and diesel price volatility bands affecting field margin compression.
Stress conditions across diesel generator fuel cost spikes, German sensor export restriction scenarios, and hydrogeologist wage inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization velocity and telemetry adoption curves. Cross-checking against India's state groundwater authority electrical connection authorization data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Water Testing Meter Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
Ecological Wastewater Treatment Market
Water and Wastewater Treatment
Global Wastewater Diffused Aerator Market
Water and Wastewater Treatment
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Agricultural Wastewater Treatment Market
Water and Wastewater Treatment
Sludge Dewatering Equipment Market
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
Backwash Pre-Filters Market
Water and Wastewater Treatment
Global Vertical Sewage Pumps Market