
 Global Water and Wastewater Treatment Equipment Market | 2026-2036
Global Water and Wastewater Treatment Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Water and Wastewater Treatment Equipment Market Intelligence
Specialist membrane system producers are pivoting production capacity towards high-rejection reverse osmosis elements for industrial water reuse. DuPont leverages its materials science expertise in polymer-based filtration media. Veolia Environnement S.A. competes by offering integrated design, build, and operate services for large municipal projects. Xylem Inc. specializes in intelligent pumping and transport systems that optimize water management cycles.
Water and wastewater treatment equipment comprises engineered systems designed to remove physical, chemical, and biological contaminants from water sources. These systems often achieve specific purification targets, such as reducing total dissolved solids (TDS) below 500 parts per million for drinking water applications. Membrane systems, particularly reverse osmosis, represent the fastest-growing treatment technology segment due to their versatility. While the municipal sector remains the largest end-use market by volume, the industrial manufacturing sector provides higher-margin opportunities for specialized solutions.
Regulations such as the US EPA's National Pollutant Discharge Elimination System (NPDES) and the EU's Urban Wastewater Treatment Directive set stringent effluent limits, mandating equipment upgrades. In China, the Ministry of Ecology and Environment (MEE) enforces GB standards for industrial discharge, creating a large compliance-driven market. Navigating these varied and evolving regional standards for contaminant removal is the central challenge for equipment manufacturers seeking market access.
Market Dynamics
The central dynamic shaping the market is the global enforcement of stricter water quality standards. This regulatory pressure compels both municipal and industrial end-users to upgrade from basic treatment methods to more advanced, and often more expensive, purification technologies.
Growth Catalysts
- Regulatory Mandates:The EU's Urban Wastewater Treatment Directive forces municipalities to enhance nutrient removal capabilities, directly spurring investment in biological treatment and tertiary filtration equipment to meet new effluent standards.
- Industrial Purity Requirements:Demand from the semiconductor fabrication sector for ultrapure water systems, which require near-total removal of ionic and organic contaminants, creates a high-value catalyst for advanced membrane and ion exchange technologies.
- Infrastructure Development:New industrial zones and urban expansion in countries like India and Vietnam necessitate the construction of greenfield water and wastewater treatment facilities, representing a significant volume of new equipment projects.
Market Restraints
- High Capital Costs:The significant upfront investment required for advanced treatment systems, such as reverse osmosis or membrane bioreactors, can be a substantial barrier for smaller municipalities and price-sensitive industrial users.
- Technical Limitations:Persistent issues with membrane fouling and scaling increase operational expenditures through higher energy consumption, chemical cleaning requirements, and reduced membrane lifespan, constraining overall system efficiency.
- Regulatory Fragmentation:The need for equipment manufacturers to navigate and comply with a complex web of disparate national standards, from the US EPA to China's MEE, increases product development costs and time-to-market.
Strategic Opportunities
- Circular Economy Models:Developing systems for direct potable reuse or industrial water recycling in water-stressed regions offers a major growth avenue, turning wastewater from a liability into a valuable resource.
- Emerging Contaminant Treatment:Growing regulatory focus on micropollutants like PFAS and pharmaceuticals creates an opportunity for specialized equipment combining advanced oxidation processes (AOPs) with high-rejection membranes.
- Modular & Decentralized Systems:Offering containerized, pre-engineered treatment plants provides a flexible and scalable solution for remote communities, construction sites, and smaller industrial facilities in regions like sub-Saharan Africa.
Industry Challenges
- Legacy System Integration:Integrating modern, digitally-controlled treatment equipment with aging and often poorly documented municipal pipeline networks presents significant technical and logistical hurdles for upgrade projects.
- Skilled Operator Shortage:A widening skills gap exists for technicians qualified to operate and maintain sophisticated, automated treatment plants, particularly those involving complex membrane systems and digital controls.
- Material Cost Volatility:Fluctuations in the price of essential raw materials, including specialty polymers for membranes and corrosion-resistant alloys for pumps and vessels, complicate project bidding and threaten manufacturer margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Water and Wastewater Treatment Equipment Market |
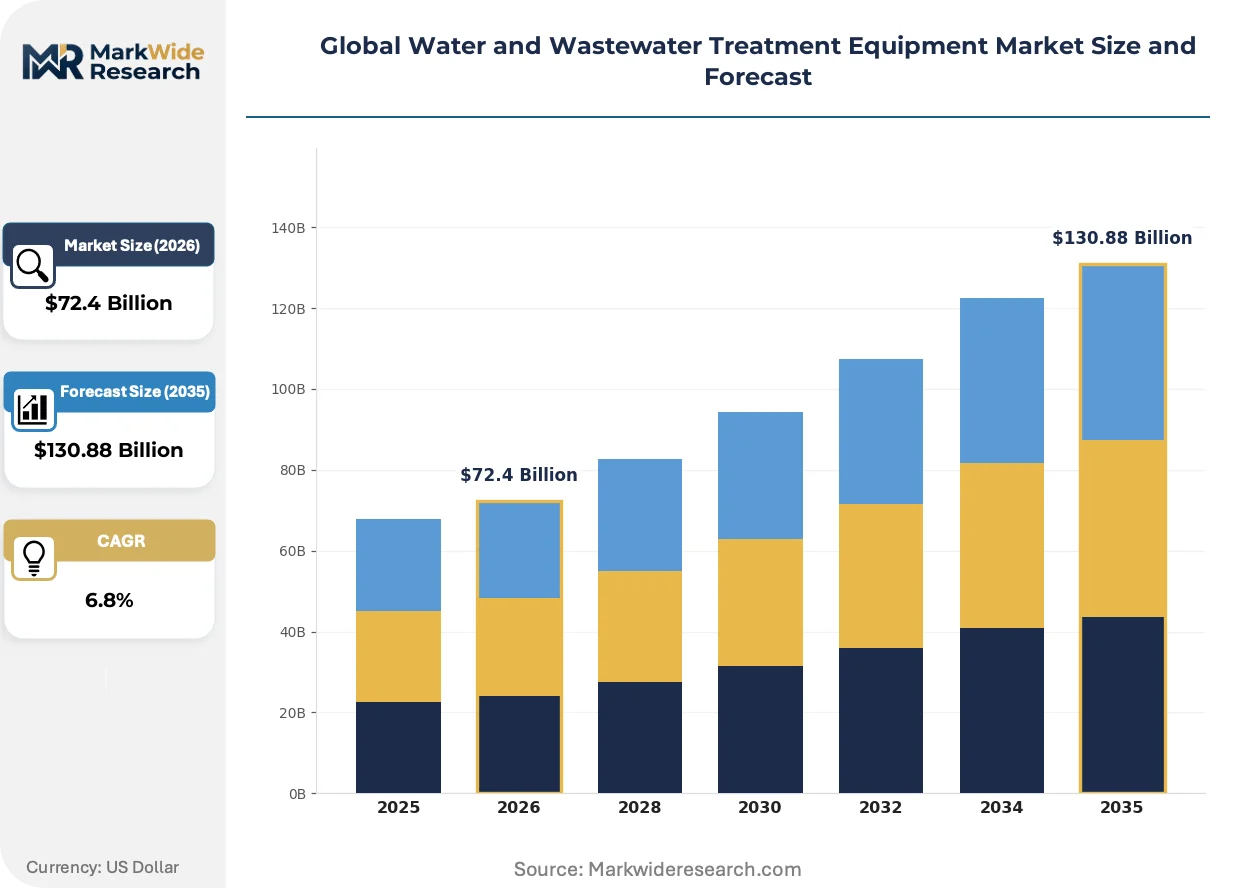
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $130.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Pumps, Filters, Clarifiers, Disinfection Units, Aerators, Membrane Systems Treatment Technology: Reverse Osmosis, Ultraviolet, Activated Carbon, Ion Exchange, Coagulation, Sedimentation End Use Sector: Municipal, Industrial Manufacturing, Agriculture, Commercial Facilities, Power Generation, Food Processing Installation Environment: Onsite Plants, Mobile Units, Remote Facilities, Modular Systems, Prefabricated Units, Custom Installations |
| Companies Covered | Veolia Environnement S.A., Xylem Inc., Ecolab Inc., SUEZ Group, Pentair plc, DuPont, Aquatech International, 3M, Evoqua Water Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Water and Wastewater Treatment Equipment Market Strategic Shifts & Innovations
System intelligence and resource recovery are transforming the equipment landscape. The focus is shifting from simple compliance with discharge limits toward optimizing the entire water cycle, extracting value from waste streams, and using data to drive operational efficiency.
Digital twin technology creates dynamic virtual models of physical water treatment plants to simulate and forecast operational performance. Large municipal utilities and complex industrial facilities are the primary adopters, seeking to optimize chemical usage, predict maintenance needs, and reduce energy consumption. This technology is integrating real-time sensor data with process models, enabling a proactive approach to plant management.
The US EPA's formal establishment of maximum contaminant levels for PFAS chemicals in drinking water is a landmark regulatory action. This move compels public water systems nationwide to assess their source water and implement effective treatment solutions. As a result, demand is surging for equipment based on granular activated carbon, ion exchange resins, and high-pressure reverse osmosis membranes.
A distinct behavioral shift is occurring away from traditional equipment purchasing toward the adoption of long-term service agreements. This Water-as-a-Service (WaaS) model transfers the responsibility for capital investment and operational performance from the end-user to the technology provider. The trend is most visible within water-intensive industries in Latin America, where companies seek to secure water quality and availability without major balance sheet impacts.
Global Water and Wastewater Treatment Equipment Market Segmentation
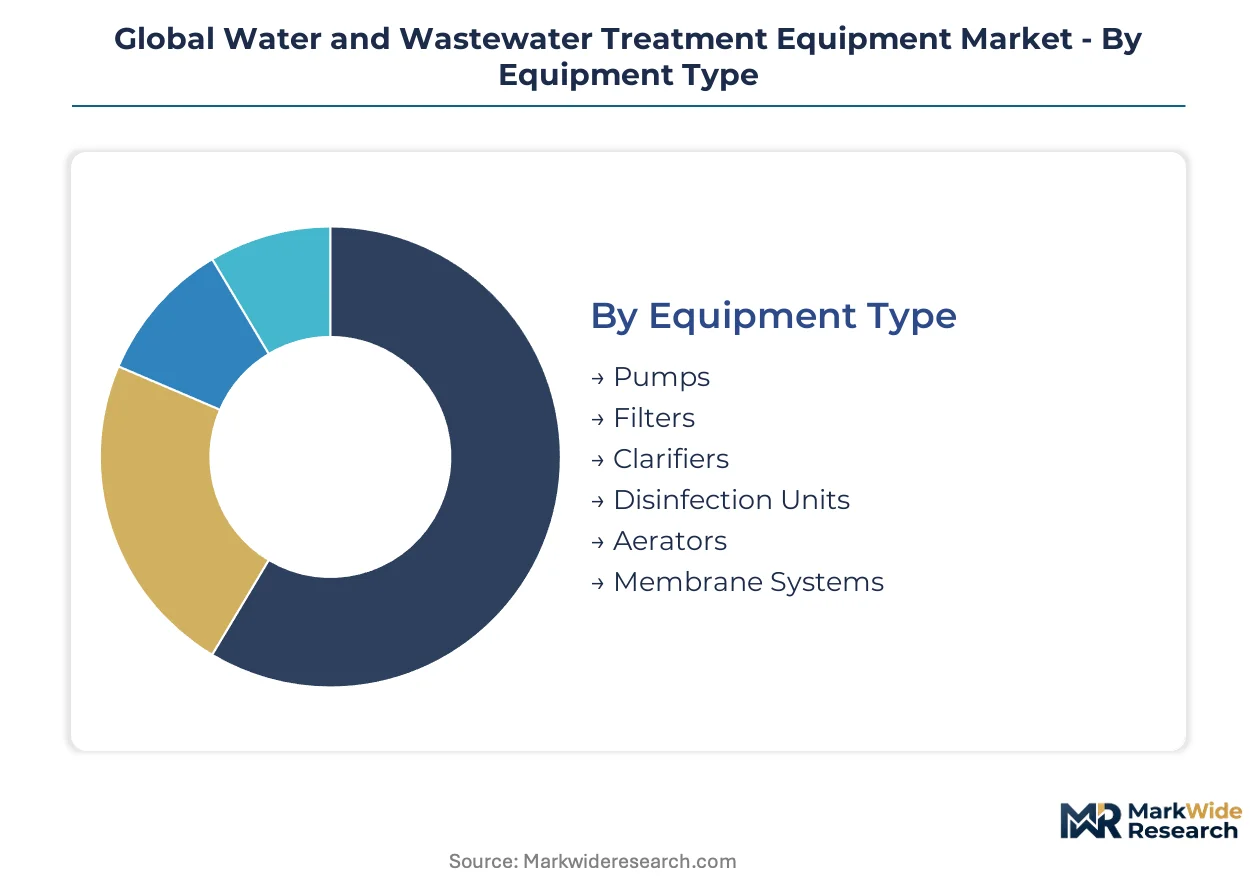
The Global Water and Wastewater Treatment Equipment Market is highly diversified, reflecting the varied requirements for water quality, scale of operation, and regulatory compliance across different applications. Understanding these distinct segments illuminates where investment is flowing and which technologies are gaining traction for specific purification challenges.
Equipment Type:
The capital outlay for water and wastewater treatment equipment varies significantly, with advanced membrane systems typically requiring the largest initial investment due to specialized materials and precision engineering.
- Membrane Systems:These engineered barriers selectively remove dissolved solids, colloids, and microorganisms from water, often utilizing reverse osmosis or ultrafiltration principles. Demand from the semiconductor fabrication sector for ultrapure water systems drives innovation and adoption of these high-rejection technologies.
- Pumps:Essential mechanical devices that move water or wastewater through treatment processes, ranging from raw water intake to treated effluent discharge. Their continuous operation in municipal infrastructure and industrial cooling systems underscores their foundational role in water management cycles.
- Filters:Components that physically remove suspended solids and particulate matter from water using media like sand, activated carbon, or specialized cartridges. Industrial facilities use various filters to protect downstream equipment and ensure process water quality.
- Clarifiers:Large sedimentation tanks designed to remove suspended solids from water or wastewater through gravity settling, a common primary treatment step.
- Disinfection Units:Systems employing chemical (e.g., chlorine) or physical (e.g., UV light) methods to eliminate pathogenic microorganisms from treated water.
- Aerators:Equipment that introduces air into water to increase dissolved oxygen levels, crucial for biological treatment processes and odor control in wastewater.
Membrane Systems absorbs the bulk of installed capacity; Pumps is expanding most quickly.
Treatment Technology:
The cost tier for treatment technologies ranges from conventional coagulation and sedimentation, which are relatively low-cost, to advanced reverse osmosis and specialized activated carbon systems designed for micropollutant removal, which command higher prices.
- Reverse Osmosis:A pressure-driven membrane process that removes ions, molecules, and larger particles from drinking water and industrial process streams. Its high contaminant removal rates make it critical for industrial water reuse and desalination projects in water-stressed regions.
- Activated Carbon:A porous material used to adsorb organic compounds, chlorine, and emerging contaminants like PFAS from water through physical adsorption. Municipal water treatment plants increasingly deploy granular activated carbon to comply with stricter drinking water standards.
- Ultraviolet:A non-chemical disinfection method that uses UV light to inactivate bacteria, viruses, and protozoa by damaging their DNA. It serves as a primary disinfection barrier for drinking water and tertiary treatment for wastewater effluent.
- Ion Exchange:A reversible chemical process where undesirable ions in water are exchanged for more desirable ions held by a resin. This technology is vital for softening hard water and producing demineralized water for industrial boilers.
- Coagulation:A chemical process involving the addition of coagulants to destabilize suspended particles in water, allowing them to clump together. It is a fundamental step in conventional water treatment to remove turbidity and color.
- Sedimentation:A physical process where gravity causes suspended solids to settle out of water, typically following coagulation and flocculation.
The shift towards advanced purification drives demand for Reverse Osmosis and Activated Carbon.
End Use Sector:
Application diversity drives market dynamics, with each sector presenting unique water quality challenges and regulatory compliance requirements for equipment manufacturers.
- Municipal:Public utilities responsible for treating drinking water for urban populations and managing wastewater discharge from residential and commercial sources. This sector represents the largest volume market, driven by population growth and aging infrastructure upgrades.
- Industrial Manufacturing:Encompasses diverse industries requiring process water for production, cooling, and boiler feed, alongside managing complex industrial wastewater streams. Specialized solutions in this sector often command higher margins due to stringent purity demands and complex effluent regulations.
- Power Generation:Requires high-purity water for boiler feed and cooling towers to prevent scaling and corrosion, while also managing large volumes of cooling water discharge. Water treatment equipment ensures efficient plant operation and environmental compliance.
- Food Processing:Mandates strict hygiene standards and specific water quality for product washing, ingredient preparation, and sanitation within food and beverage production. Regulatory bodies enforce rigorous standards for water used in food contact applications.
- Agriculture:Primarily involves irrigation water treatment to remove suspended solids, pathogens, and algae, enhancing crop yield and preventing drip emitter clogging. Demand for efficient water use is rising in water-scarce agricultural regions.
- Commercial Facilities:Includes water treatment for hotels, hospitals, office buildings, and institutional campuses, focusing on potable water, HVAC systems, and on-site wastewater management.
Regulatory compliance and process water needs define the procurement patterns across these sectors.
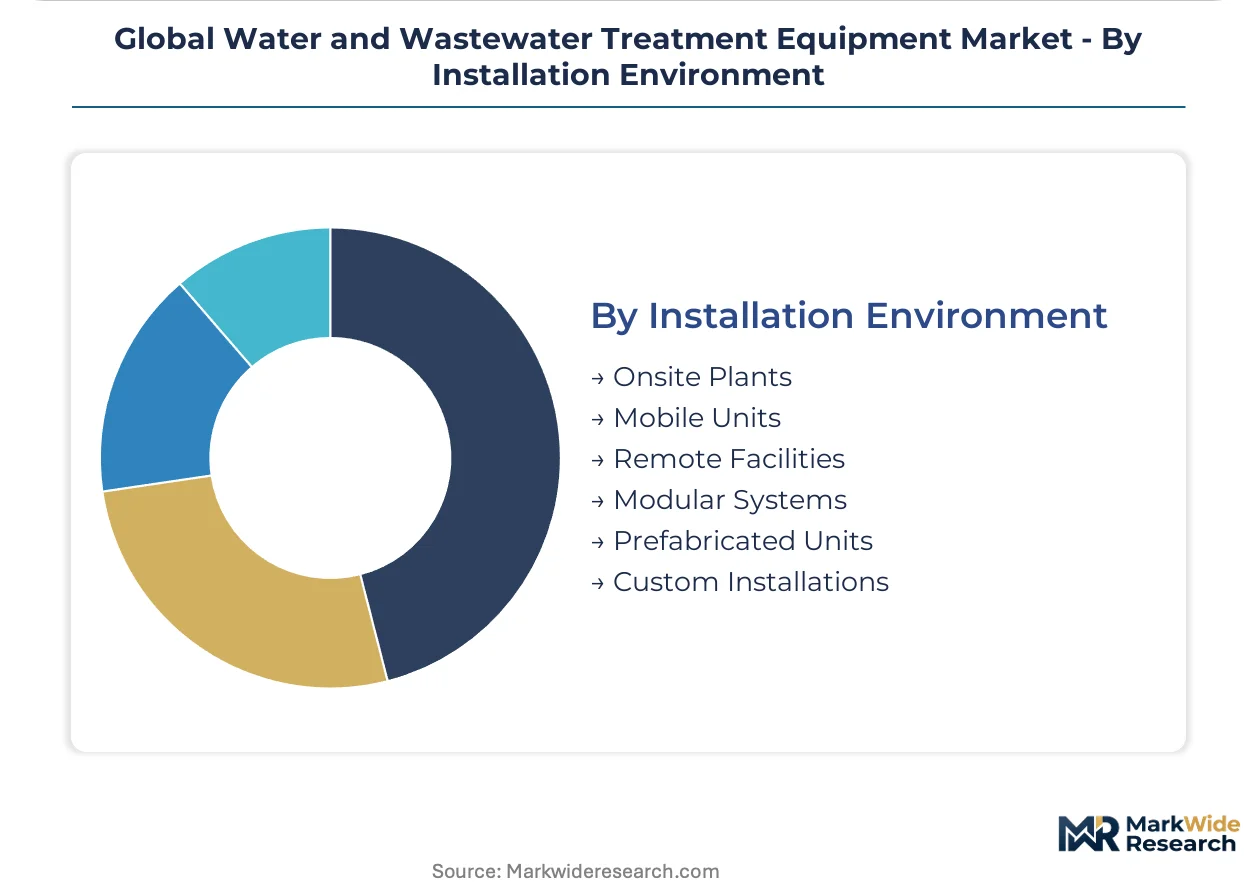
Installation Environment:
Customer type influences the choice of installation environment, with large municipal entities favoring permanent onsite plants, while remote or temporary needs drive demand for modular or mobile units.
- Onsite Plants:Large-scale, permanent treatment facilities constructed directly at the point of water intake or wastewater discharge, common for municipal and major industrial operations. These installations offer maximum capacity and customization.
- Modular Systems:Pre-engineered and factory-assembled treatment units that can be rapidly deployed and scaled up or down as needed. Their flexibility makes them suitable for remote communities, temporary construction sites, or rapid industrial expansion.
- Mobile Units:Self-contained treatment systems mounted on trailers or skids, capable of being transported to different locations for emergency response, temporary water supply, or pilot testing. These units provide immediate solutions for unforeseen water challenges.
- Remote Facilities:Treatment systems designed for isolated locations lacking extensive infrastructure, often requiring robust, low-maintenance designs and remote monitoring capabilities.
- Prefabricated Units:Entire treatment blocks manufactured off-site and then transported for assembly, reducing on-site construction time and costs for various applications.
- Custom Installations:Uniquely designed and built systems tailored to meet highly specific water quality requirements or challenging site conditions, common for complex industrial processes.
Scalability and deployment speed are critical considerations across these diverse installation types.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's vast industrial base and urban expansion drive significant demand for water and wastewater treatment equipment. Regulatory enforcement and infrastructure development across diverse geographies shape regional market dynamics. Each region presents unique challenges and opportunities for equipment manufacturers.
United States
Aging water infrastructure upgrades and emerging contaminant treatment drive equipment demand across the United States. The US EPA's establishment of maximum contaminant levels for PFAS chemicals mandates new purification solutions. California's Silicon Valley continues to require advanced ultrapure water systems for its semiconductor fabrication facilities.
Germany
German industrial sectors demand high purity water for manufacturing processes, alongside a strong focus on water reuse. The EU's Urban Wastewater Treatment Directive forces municipalities to enhance nutrient removal capabilities. Bavaria's advanced manufacturing hubs integrate sophisticated treatment technologies for industrial water recycling.
India
Rapid urbanization and new industrial zones necessitate significant investment in greenfield water and wastewater treatment facilities in India. The Central Pollution Control Board (CPCB) sets standards for industrial discharge, creating a compliance-driven market. Gujarat's chemical industry concentrates demand for specialized wastewater management solutions.
China
China's stringent environmental regulations and industrial growth fuel demand for advanced contaminant removal technologies. The Ministry of Ecology and Environment (MEE) enforces GB standards for industrial discharge, compelling equipment upgrades. The Yangtze River Delta's manufacturing centers adopt high-rejection membrane systems for process water and effluent treatment.
Vietnam
Vietnam's infrastructure development and expanding manufacturing sector create new project opportunities for water treatment equipment. National technical regulations on wastewater quality guide investments in modern treatment plants. Ho Chi Minh City's industrial parks require scalable and efficient solutions for managing process water and discharge.
Global Water and Wastewater Treatment Equipment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized solutions for complex industrial purity requirements. The market structure features large, integrated service providers alongside niche technology specialists and component manufacturers. Strategic archetypes include comprehensive solution providers, advanced membrane specialists, and intelligent system integrators. Capacity expansion and strategic partnerships remain dominant competitive moves across the sector.
Within the integrated solutions tier, Veolia Environnement S.A. represents a major player in large municipal projects, offering comprehensive design, build, and operate services that span the entire water cycle. Xylem Inc. occupies a position among specialists in intelligent pumping and transport systems, optimizing water management cycles for diverse applications with advanced digital controls. DuPont exemplifies materials science expertise, anchoring its offerings in polymer-based filtration media crucial for advanced membrane systems and high-rejection reverse osmosis elements. These companies collectively illustrate the varied approaches to market engagement, from broad service provision to highly specialized component manufacturing and system integration, catering to distinct segments of the global market.
| Leading Market Players |
|---|
| Veolia Environnement S.A. |
| Xylem Inc. |
| Ecolab Inc. |
| SUEZ Group |
| Pentair plc |
| DuPont |
| Aquatech International |
| 3M |
| Evoqua Water Technologies |
Cost & Logistics Intelligence
Skilled technicians for advanced purification systems, particularly those in developed economies, introduce labor-cost differentials that contribute to pricing-tier spreads across complex equipment installations. These cost variations influence the final project bids for municipal and industrial clients.
Pricing Analysis
Warranty and long-term service agreements often define the true cost of advanced water treatment equipment, unbundling capital expenditure from operational performance. The market primarily operates on a project-based pricing model for large installations, complemented by contract-based agreements for Water-as-a-Service offerings. Price differentiation stems from the high customization required for complex industrial applications and the extent of after-sales support provided. Pricing pressure stems from material cost volatility for polymers and corrosion-resistant alloys. Smaller municipalities and price-sensitive industrial users exhibit the highest price sensitivity, often seeking more economical standard solutions.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks facilitate the global movement of water treatment components and systems to diverse project sites. Supply concentration for advanced membrane materials and precision-engineered pumps primarily resides in countries like China, Germany, and the United States. The industry relies heavily on specialty polymers for membranes and corrosion-resistant alloys for pumps and vessels. Commodity price volatility for these raw materials represents a structural supply chain risk. Distribution runs through a mix of direct sales channels for large, custom installations and established distributor networks for standard equipment and aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global water and wastewater treatment equipment market is navigating a significant technology-transition phase. Advanced membrane systems, particularly reverse osmosis, are steadily displacing conventional treatment methods due to their superior contaminant removal capabilities.
For Market Incumbents:Extend integrated design, build, and operate services to capture the full lifecycle value of municipal projects, leveraging existing client relationships. Incumbents should strategically acquire niche technology specialists in advanced oxidation processes to address emerging contaminant regulations like PFAS. Deepening vertical integration into specialized polymer-based filtration media manufacturing can mitigate material cost volatility. Investing in R&D for next-generation membrane fouling resistance is crucial to counter operational expenditure concerns.
For New Entrants and Emerging Players:Price-point gaps between premium, custom-engineered solutions and basic conventional systems create opportunities for new entrants. Target modular and decentralized treatment systems for remote communities and smaller industrial facilities in regions like sub-Saharan Africa. Offering specialized equipment for emerging contaminants such as PFAS, combining advanced oxidation processes with high-rejection membranes, provides a high-value niche. A Water-as-a-Service (WaaS) model, emphasizing operational performance and predictable costs, can attract price-sensitive industrial users.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized technology providers and intelligent system integrators given the accelerating shift towards advanced purification and circular economy models. The market offers long-term viability, anchored by essential infrastructure needs, tightening regulations, and global water scarcity. Investors should prioritize acquisition targets with strong intellectual property in next-gen membrane materials or advanced digital controls for plant optimization. The signal to watch is the increasing number of large-scale direct potable reuse project approvals in water-stressed regions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding production of high-rejection reverse osmosis elements addresses semiconductor industry demand for ultrapure water. |
| Technology Licensing | Licensing advanced oxidation processes enables broader deployment of solutions for micropollutants like PFAS. |
| Strategic Partnership | Partnering with digital twin providers optimizes operational efficiency and predictive maintenance for municipal utilities. |
| Green Manufacturing Transition | Developing energy-efficient pumping and membrane systems reduces operational expenditures for industrial end-users. |
| Acquisition of Specialist Firm | Acquiring firms with expertise in ion exchange resins strengthens offerings for PFAS removal from drinking water. |
Research Approach
US EPA reports, EU Urban Wastewater Treatment Directives, and China MEE GB standards formed the secondary backbone for initial market scoping and data validation. This was complemented by primary interviews with municipal utility managers, industrial plant engineers, and equipment R&D directors. Insights were triangulated using both bottom-up market sizing and top-down validation against macroeconomic indicators and regulatory frameworks.
Historical trendline analysis and econometric modeling underpinned the quantitative forecast framework across the analysis window. Segmentation dimensions included equipment type, treatment technology, end-use sector, installation environment, and regional regulatory compliance. Compound annual growth rates were derived from a detailed assessment of market drivers, restraints, and historical growth patterns. Key industry-specific forecast inputs included global population growth projections and industrial infrastructure development plans in emerging economies.
Inputs from regulatory bodies and industry associations were available through the study window; gaps in granular project-level investment data introduce uncertainty bands. Forecasts reflect documented assumptions regarding economic stability, regulatory enforcement, and technological progression. Geopolitical events or unforeseen rapid technological disruptions could revise these projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Tertiary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Water Testing Meter Market
Water and Wastewater Treatment
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market
Water and Wastewater Treatment
Global Biological Wastewater Treatment Market
Water and Wastewater Treatment
Mobile Wastewater Treatment Plant Market
Water and Wastewater Treatment
Latin America Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Backwash Pre-Filters Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Global Vertical Sewage Pumps Market