
 China Water and Wastewater Treatment (WWT) Technology Market | 2026-2036
China Water and Wastewater Treatment (WWT) Technology Market Size, Share, and Industry Trends Forecast 2026-2036
China Water and Wastewater Treatment (WWT) Technology Market Outlook
Municipal buyers are collapsing historical procurement preferences for conventional activated sludge systems as industrial end users scale zero-liquid-discharge investments. Beijing OriginWater Technology Co., Ltd. leverages membrane bioreactor expertise to dominate high-specification municipal retrofits in northern China. Beijing Enterprises Water Group Limited anchors its position through backward integration into operations and maintenance contracts across the Yangtze basin. DuPont competes on film composite membrane chemistry leadership for brackish water and tertiary treatment applications.
Water and wastewater treatment technology encompasses physical, chemical, and biological processes engineered to remove contaminants from water streams to meet specified effluent or potable water quality parameters, typically operating across turbidity thresholds below 0.1 NTU for membrane-based potable systems and biochemical oxygen demand reduction exceeding 90 percent for biological secondary treatment. Membrane filtration occupies the fastest-expanding margin pool as polymeric and ceramic membrane costs decline against thermal desalination alternatives, while activated sludge sustains volume leadership in municipal baseload capacity despite energy intensity disadvantages. Clarifiers and filtration systems concentrate demand from industrial end users facing MEE discharge enforcement, whereas aerators face replacement pressure from more efficient fine-bubble diffusion technologies.
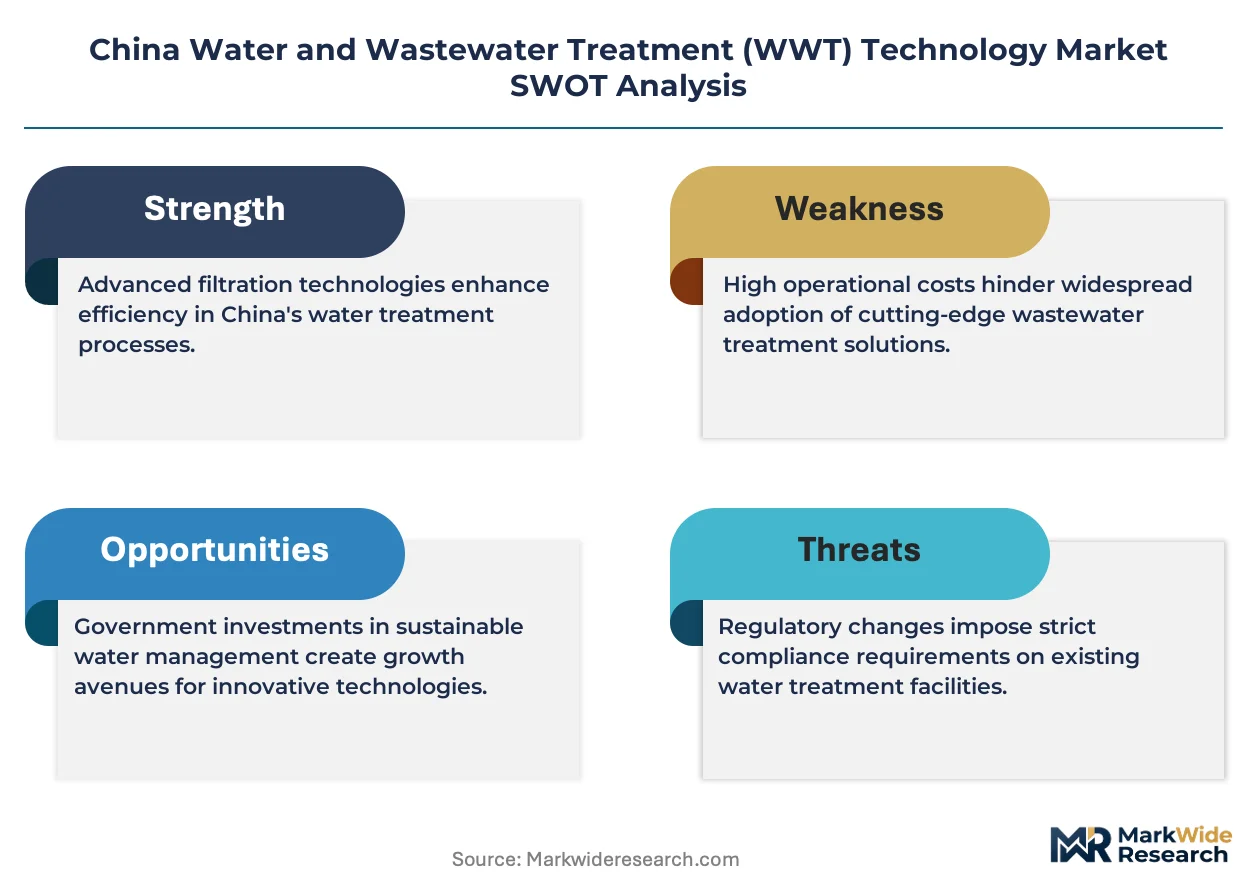
China's Ministry of Ecology and Environment enforces GB 3838 surface water quality standards and GB 18918 municipal discharge limits that directly determine technology selection and retrofit timelines for treatment facilities. The National Development and Reform Commission dual carbon goals compound these requirements by embedding energy efficiency benchmarks into project approvals and subsidy eligibility. Stakeholders must monitor how provincial MEE bureaus interpret evolving standards for emerging contaminants and carbon accounting in facility design.
Market Dynamics
Membrane-based zero-liquid-discharge mandates from China's Ministry of Ecology and Environment are collapsing conventional activated sludge procurement preferences across industrial clusters in the Yangtze and Pearl River deltas.
Growth Catalysts
- MEE discharge standard tightening:GB 18918 municipal limits and emerging contaminant protocols force technology replacement cycles at treatment facilities nationwide.
- Industrial cluster concentration:Chemical and electronics manufacturers in Jiangsu and Guangdong provinces scale advanced treatment investments to meet zero-liquid-discharge requirements.
- Membrane cost decline:Polymeric and ceramic membrane production scaling reduces unit economics against thermal desalination alternatives.
Market Restraints
- Energy input volatility:Fine-bubble aeration and membrane bioreactor operations face margin pressure from electricity price fluctuations in carbon-intensive grid regions.
- Core membrane chemistry concentration:Film composite reverse osmosis element supply concentrates among specialty chemical producers with limited qualified alternatives.
- Legacy asset stranding:Existing activated sludge basins carry sunk capital that delays full-system replacement despite efficiency disadvantages.
Strategic Opportunities
- Central and western province penetration:Sichuan and Shaanxi industrial zones face accelerating discharge enforcement with limited installed advanced treatment capacity.
- Operations and maintenance contract expansion:Municipal utilities seek performance-guaranteed service structures that transfer operational risk to technology providers.
- Dual carbon goal alignment:National Development and Reform Commission energy efficiency benchmarks embed subsidy eligibility criteria that favor low-carbon treatment process selection.
Industry Challenges
- Membrane specialist talent scarcity:Ceramic and polymeric module design expertise concentrates among engineers with cross-training in chemical engineering and materials science.
- Retrofit integration complexity:Existing clarifier and aeration infrastructure requires staged commissioning that extends project timelines and disrupts continuous operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Water and Wastewater Treatment (WWT) Technology Market |
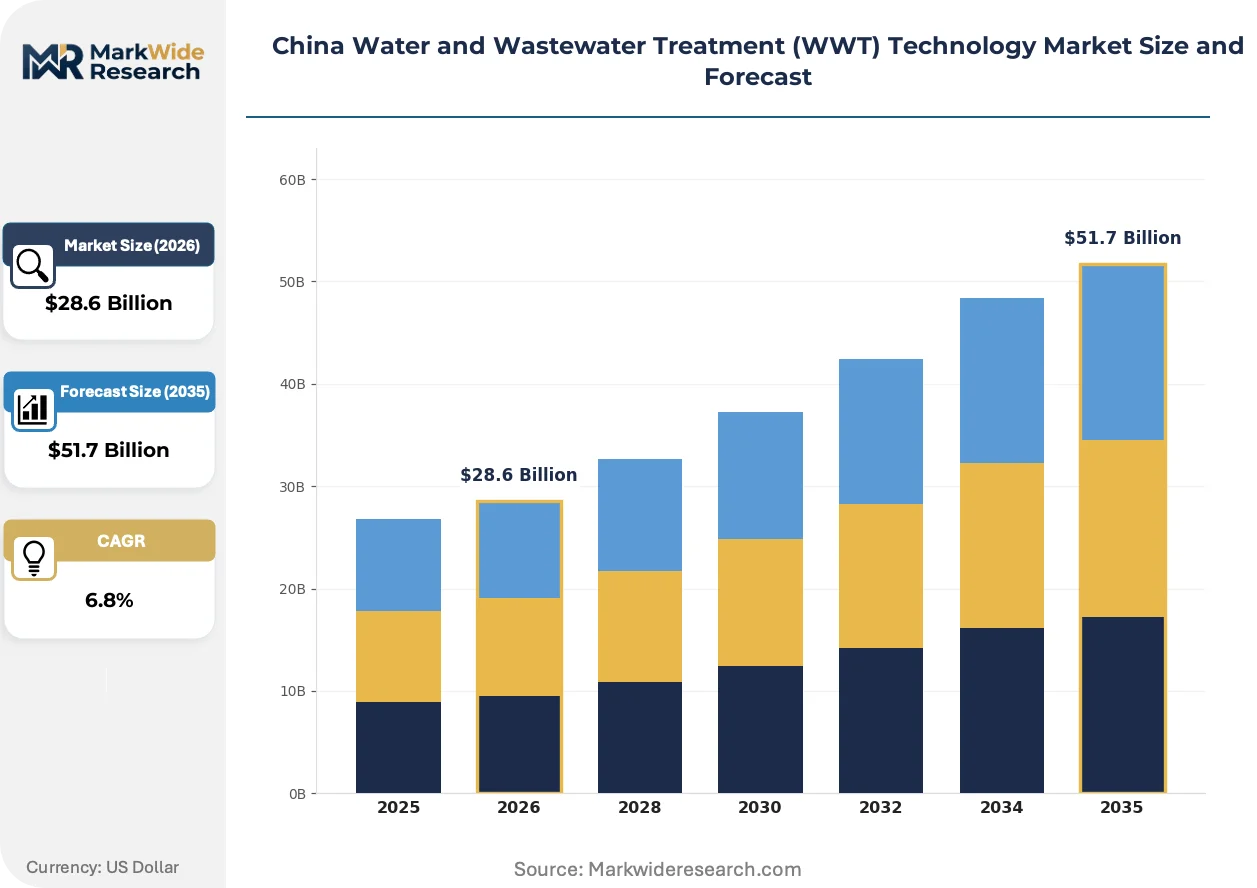
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Membrane Filtration, Activated Sludge, UV Treatment, Chemical Coagulation Product Type: Clarifiers, Pumps, Aerators, Filtration Systems End User: Municipal, Industrial, Agricultural, Residential Application: Desalination, Industrial Water Treatment, Wastewater Reuse, Sludge Treatment |
| Companies Covered | CECEP Guozhen Environmental Protection Technology Co., Ltd., Chongqing Water Group Co., Ltd., Beijing Enterprises Water Group Limited, SafBon Water Service (Holding) Inc., Ecolab Inc., Beijing OriginWater Technology Co., Ltd., China Water Affairs Group, DuPont, Veolia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Water and Wastewater Treatment (WWT) Technology Market Strategic Shifts
Technology substitution patterns and procurement model evolution are compressing equipment replacement cycles while elevating performance-guaranteed service structures over capital-sale transactions.
Ceramic membrane filtration is fragmenting conventional polymeric dominance in high-temperature industrial wastewater applications. Steel and petrochemical facilities in Hebei province adopt silicon carbide and alumina substrates for thermal and chemical resistance. This durability premium is fragmenting procurement specifications between commodity municipal projects and severe-duty industrial retrofits.
China's Ministry of Ecology and Environment interprets GB 3838 surface water quality standards with escalating strictness for emerging contaminants including pharmaceuticals and perfluorinated substances. Industrial discharge permits now require tertiary treatment capability that exceeds conventional biological oxidation. Chemical manufacturers in the Yangtze River Delta respond by embedding advanced oxidation processes upstream of membrane filtration trains.
Buyers are consolidating vendor relationships around full-lifecycle accountability rather than discrete equipment procurement. Municipal water bureaus in northern China bundle membrane bioreactor supply with decade-long operations contracts. This performance-risk transfer concentrates contract awards among vertically integrated providers with captive service networks.
China Water and Wastewater Treatment (WWT) Technology Market Segmentation
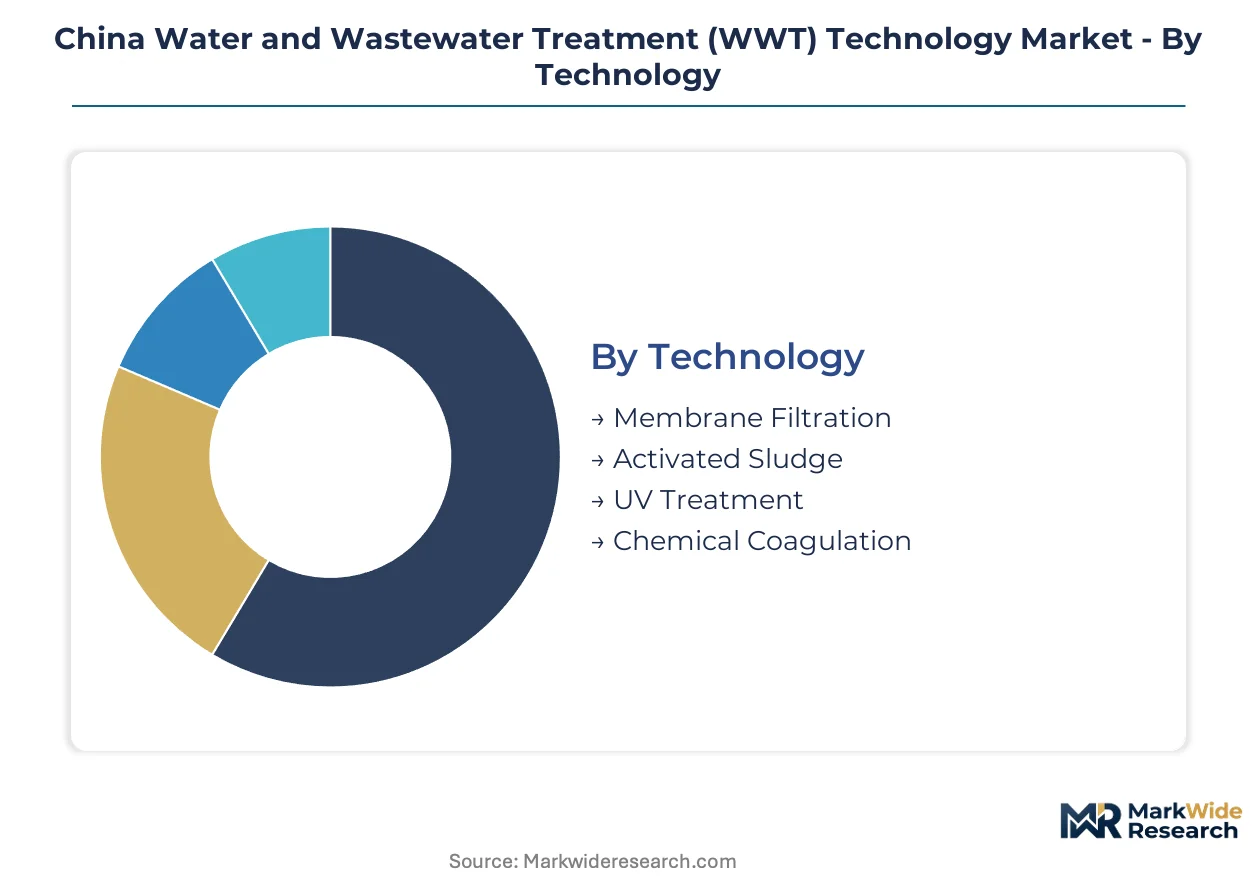
Technology selection in China's WWT market hinges on discharge standard stringency and energy efficiency mandates. Procurement patterns diverge sharply between municipal baseload retrofits and industrial zero-liquid-discharge installations.
Technology:
MEE's GB 18918 discharge limits and emerging contaminant protocols create tiered compliance thresholds that reshape technology deployment across facility types.
- Membrane Filtration:Polymeric and ceramic membranes achieve turbidity below 0.1 NTU for potable systems and enable zero-liquid-discharge compliance in Jiangsu and Guangdong industrial clusters. MEE's tightening standards for perfluorinated substances accelerate membrane bioreactor adoption in chemical manufacturing zones.
- Activated Sludge:Conventional biological oxidation retains volume leadership in municipal baseload capacity despite energy intensity disadvantages. Sunk capital in existing basins delays full-system replacement across northern China utilities facing carbon accounting pressures.
- UV Treatment:Tertiary disinfection systems address pharmaceutical and personal care product residuals in Yangtze River Delta municipal effluent.
- Chemical Coagulation:Aluminum and ferric-based precipitation systems serve high-turbidity industrial influent in Shanxi mining corridors.
Established volume favors Activated Sludge; emerging adoption favors Membrane Filtration.
Product Type:
Capital equipment procurement concentrates where MEE enforcement is strictest, with margin pools shifting toward integrated system suppliers.
- Clarifiers:Sedimentation infrastructure faces replacement pressure from membrane-based alternatives in zero-liquid-discharge retrofits. Steel and petrochemical facilities in Hebei province retain clarifier trains for primary solids separation ahead of advanced treatment.
- Filtration Systems:Multimedia and membrane filtration trains command premium pricing in tertiary treatment configurations. Electronics manufacturers in the Pearl River Delta embed these systems to meet semiconductor-grade water specifications.
- Pumps:High-efficiency variable frequency drives dominate newbuild specifications under NDRC dual carbon energy benchmarks.
- Aerators:Fine-bubble diffusion technologies displace coarse bubble systems in municipal energy retrofit programs.
Clarifiers retain installed base dominance; Filtration Systems capture expanding margin share.
End User:
Customer procurement authority fragments across state-owned utilities, private industrial operators, and fragmented agricultural collectives.
- Industrial:Chemical, electronics, and steel manufacturers scale advanced treatment investments to meet zero-liquid-discharge mandates in Jiangsu and Guangdong. Performance-guaranteed service contracts transfer operational risk to technology providers.
- Municipal:Provincial water bureaus bundle membrane bioreactor supply with decade-long operations contracts in Beijing and Tianjin. GB 18918 compliance deadlines accelerate retrofit timelines across northern China.
- Agricultural:Livebrate operations in Sichuan basin face emerging nutrient discharge enforcement with limited treatment infrastructure.
- Residential:Point-of-use filtration concentrates in high-income urban districts of Shanghai and Shenzhen.
Municipal procurement anchors volume; Industrial contracts expand most quickly.
Application:
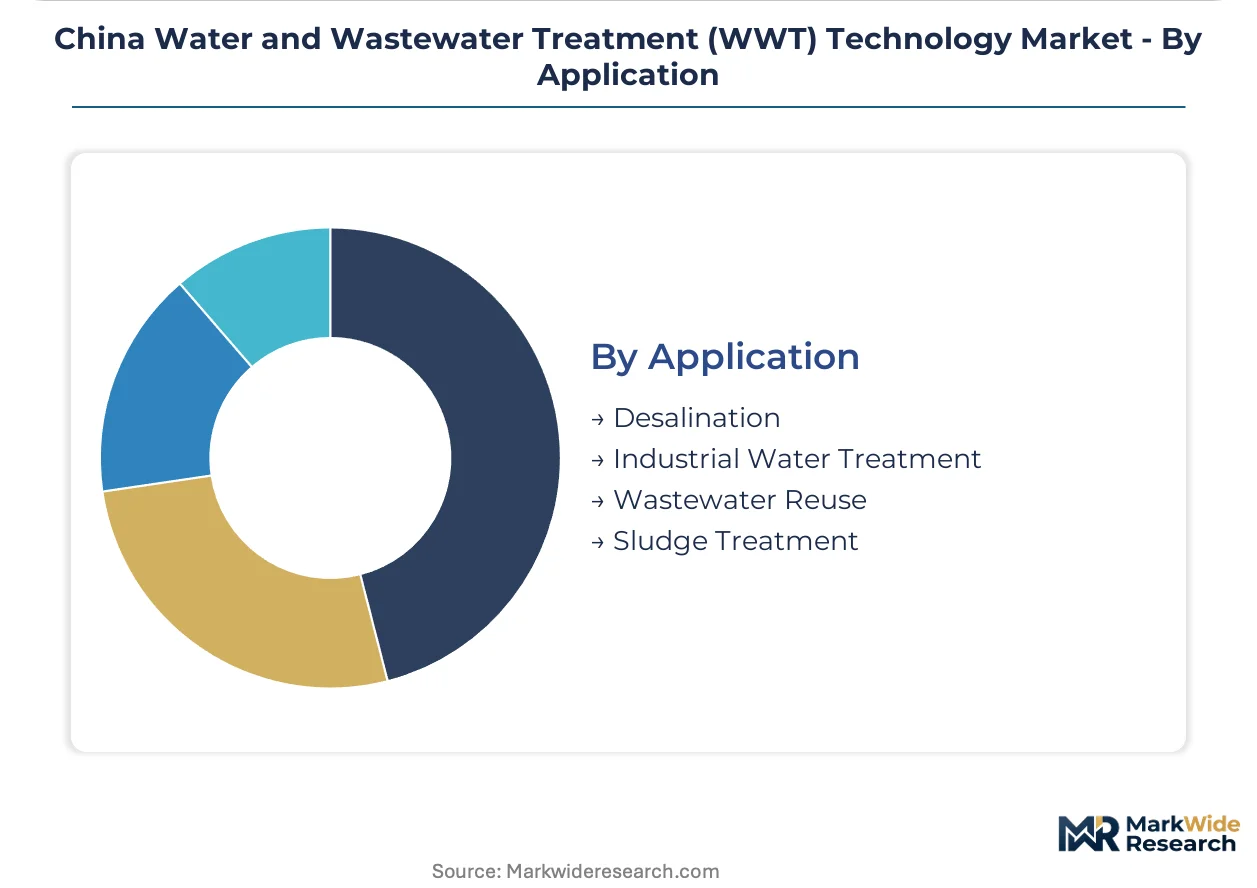
Use-case segmentation reflects water stress geography and industrial cluster specialization.
- Industrial Water Treatment:Process water purification for semiconductor and pharmaceutical manufacturing commands highest specification thresholds. Yangtze River Delta facilities integrate advanced oxidation with membrane trains for emerging contaminant removal.
- Wastewater Reuse:Tertiary treatment for cooling tower makeup and irrigation expands in Beijing-Tianjin-Hebei water-stressed corridor. MEE reuse guidelines tighten quality parameters for non-potable applications.
- Desalination:Reverse osmosis concentrates in coastal Shandong and Liaoning industrial zones with limited freshwater access.
- Sludge Treatment:Anaerobic digestion and thermal drying capacity lags behind liquid treatment infrastructure across central provinces.
Wastewater Reuse scales fastest in water-stressed regions; Industrial Water Treatment commands premium specification tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German membrane technology exports flow into Chinese industrial retrofits as domestic fabricators scale ceramic substrate production for high-temperature applications.
Yangtze River Delta
Jiangsu chemical manufacturers deploy advanced oxidation trains to meet MEE perfluorinated substance limits. Provincial discharge permits now mandate tertiary membrane filtration for electronics process water. Suzhou and Wuxi industrial parks concentrate zero-liquid-discharge retrofits.
Pearl River Delta
Guangdong semiconductor fabs drive ultrapure water specification escalation. MEE reuse guidelines tighten cooling tower makeup quality thresholds. Shenzhen and Dongguan facilities integrate reverse osmosis with electrodeionization for semiconductor-grade output.
Beijing-Tianjin-Hebei
Water stress in the Jing-Jin-Ji corridor accelerates wastewater reuse infrastructure. NDRC dual carbon benchmarks embed energy efficiency into municipal project approvals. Tianjin membrane bioreactor retrofits bundle decade-long operations contracts.
Sichuan-Chongqing
Western industrial zones face accelerating MEE enforcement with limited installed advanced treatment capacity. Livestock operations confront emerging nutrient discharge rules. Chengdu electronics manufacturers import membrane filtration trains from coastal fabricators.
Shandong Peninsula
Coastal desalination concentrates in Qingdao and Yantai industrial zones with constrained freshwater access. Petrochemical clusters adopt ceramic membranes for thermal resistance. Provincial standards exceed national GB 18918 limits for heavy industrial discharge.
China Water and Wastewater Treatment (WWT) Technology Market Competitive Environment
Listed leaders compete with private specialists across state-contract access and technology licensing dimensions. Market structure tilts toward consolidation around vertically integrated providers with captive service networks. Three archetypes dominate: state-owned utilities with operations scale, membrane technology specialists with process expertise, and international chemical conglomerates with materials science depth. Competitive moves center on performance-guaranteed service contracts and backward integration into membrane module manufacturing.
Among state-backed operators, Beijing Enterprises Water Group Limited and Chongqing Water Group Co., Ltd. exemplify the utility-scale archetype with basin-spanning operations contracts. Beijing OriginWater Technology Co., Ltd. occupies a position within the membrane specialist tier, representing domestic technology capability in high-specification retrofits. These three entities anchor competitive dynamics across municipal and industrial procurement channels.
| Leading Market Players |
|---|
| CECEP Guozhen Environmental Protection Technology Co., Ltd. |
| Chongqing Water Group Co., Ltd. |
| Beijing Enterprises Water Group Limited |
| SafBon Water Service (Holding) Inc. |
| Ecolab Inc. |
| Beijing OriginWater Technology Co., Ltd. |
| China Water Affairs Group |
| DuPont |
| Veolia |
| Others |
Value Chain & Pricing Dynamics
MEE's GB 18918 discharge standards and emerging contaminant protocols gate both supplier qualification and price differentiation simultaneously, forcing membrane module vendors to recertify chemistry formulations while municipal buyers pay premiums for compliance-guaranteed performance tiers.
Pricing Analysis
Membrane bioreactor systems command a 40-60% premium over conventional activated sludge retrofits, while ceramic membrane trains for high-temperature industrial applications price at a further elevation above polymeric alternatives. Pricing stratifies across premium, standard, and economy tiers based on membrane chemistry certification grade and bundled operations contract length. Cost compression in standard-tier polymeric membranes is intensifying because domestic Chinese fabricators are scaling silicon carbide substrate production. Municipal utilities in northern China exhibit highest price sensitivity due to budget constraints under carbon accounting pressures, whereas semiconductor manufacturers in the Pearl River Delta demonstrate lowest sensitivity given ultrapure water specification requirements.
Supply Chain Analysis
Inventory cycles for film composite reverse osmosis elements have extended from 8-12 weeks to 16-20 weeks as specialty chemical producers in Germany, Japan, and the United States throttle output expansion. Membrane module assembly draws from polyethersulfone resin feedstocks anchored in China, polysulfone chemistry from German BASF production, and silicon carbide powders from Saint-Gobain's Norwegian operations. Single-source vulnerability concentrates in proprietary interfacial polymerization chemistry for high-rejection seawater membranes. Distribution runs through state-owned utility procurement platforms in northern China and direct OEM relationships with electronics manufacturers in Jiangsu and Guangdong.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: MEE discharge permits create decade-long technology lock-in periods that compound switching costs across municipal and industrial buyer bases.
For Market Incumbents: Secure backward integration into ceramic membrane substrate manufacturing to defend margin position against emerging domestic Chinese fabricators. Expand operations and maintenance contract coverage in Sichuan-Chongqing industrial zones before MEE enforcement accelerates. Prioritize certification investment for perfluorinated substance removal protocols to maintain technology leadership against substitute advanced oxidation processes.
For New Entrants and Emerging Players: Anchor in livestock wastewater treatment in Sichuan basin, where nutrient discharge enforcement is emerging with limited installed advanced treatment capacity. Target small and mid-scale chemical manufacturers in Shandong Peninsula seeking ceramic membrane alternatives to German imports. Pursue a technology licensing go-to-market angle with provincial state-owned enterprises lacking in-house membrane design expertise.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across membrane bioreactor retrofit segments as modular skid-mounted designs reduce field installation labor. Long-term viability favors vertically integrated providers with captive service networks over pure equipment vendors. Acquisition target archetype: regional membrane specialists with MEE certification track records and existing municipal operations contracts. Monitor MEE interpretations of carbon accounting in facility design as the inflection signal for subsidy eligibility shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Substrate Manufacturing | Captures margin pool from German and Japanese specialty chemical suppliers while securing supply continuity. |
| Performance-Guaranteed Operations Contract Expansion | Locks in decade-long revenue streams with Beijing and Tianjin municipal utilities seeking risk transfer. |
| Ceramic Membrane Product Line Extension | Addresses Hebei steel and petrochemical demand for thermal and chemical resistance beyond polymeric limits. |
| Advanced Oxidation Process Licensing Agreement | Enables Yangtze River Delta chemical manufacturers to meet MEE perfluorinated substance discharge thresholds. |
| Central and Western Province Geographic Expansion | Positions ahead of MEE enforcement acceleration in Sichuan and Shaanxi with limited competitor presence. |
Study Parameters
Desk research of MEE regulatory filings, NDRC dual carbon policy documents, and provincial discharge permit databases preceded structured interviews with municipal water bureau procurement directors, membrane technology R&D leads at domestic fabricators, industrial facility environmental compliance officers, and operations managers at state-owned utilities. Primary fieldwork combined with secondary validation against customs trade data for membrane module imports, SEC 10-K disclosures from listed water treatment groups, and project finance databases for municipal retrofit programs. Bottom-up facility-level capacity assessments triangulated against top-down provincial infrastructure spending plans.
Variance decomposition across technology substitution rates, membrane cost decline curves, and MEE enforcement intensity shaped the analytical framework throughout the forecast period. Segmentation dimensions modeled include technology type, product category, end-user archetype, and application use-case, with regional water stress geography as an industry-specific overlay. CAGRs derived from fitted adoption curves for membrane bioreactor retrofits and zero-liquid-discharge mandates in industrial clusters. Forecast inputs incorporated electricity price trajectory assumptions for carbon-intensive grid regions and ceramic membrane production scaling timelines from domestic Chinese fabricators.
Decision-makers should treat outputs as directional under base assumptions of sustained MEE discharge standard tightening and NDRC dual carbon benchmark enforcement; material deviation in regulatory interpretation timelines or membrane cost decline rates would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market
Water and Wastewater Treatment
Latin America Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Mobile Wastewater Treatment Plant Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market
Water and Wastewater Treatment
US Wastewater Secondary Treatment Equipment Market
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Global Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Bio Filter Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Agricultural Wastewater Treatment Market
Water and Wastewater Treatment
Tertiary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
Global Biological Wastewater Treatment Market