
 Middle-East and Africa Industrial Air Quality Control Systems Market | 2026-2036
Middle-East and Africa Industrial Air Quality Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Industrial Air Quality Control Systems Market Foresight
Aftermarket service revenue is reshaping margin distribution across the Middle-East and Africa Industrial Air Quality Control Systems landscape. Dürr AG leverages its regional service footprint to capture recurring maintenance contracts from cement and steel producers. Alfa Laval AB anchors its position through heat-recovery-integrated scrubber systems that reduce total cost of ownership for Gulf petrochemical operators. Donaldson Company Inc competes on filtration media replacement cycles, sustaining long-term client relationships in mining-intensive economies.
Industrial air quality control systems encompass engineered equipment designed to capture, filter, monitor, or neutralize particulate matter, gaseous pollutants, and volatile organic compounds from industrial exhaust streams, typically operating at temperatures ranging from ambient to 400°C depending on process integration. These systems serve the primary purpose of ensuring occupational safety, environmental compliance, and process efficiency across heavy manufacturing environments. Electrostatic precipitators dominate capital expenditure in power generation and cement sectors due to their handling capacity for high-volume flue gases. HEPA filtration segments are gaining traction in pharmaceutical cleanrooms and food processing facilities across the Gulf Cooperation Council states. Gas analyzers represent the fastest-growing technology category as real-time emissions monitoring becomes mandatory under tightening national environmental standards.
Saudi Arabia's General Authority for Meteorology and Environmental Protection and South Africa's Department of Forestry, Fisheries and the Environment enforce emissions thresholds that directly shape equipment procurement specifications and retrofit timelines. The UAE's Ministry of Climate Change and Environment has introduced industrial permitting requirements that mandate continuous emissions monitoring systems for major pollutant categories. Stakeholders must track how national carbon-neutrality commitments across Gulf monarchies and South Africa's Just Energy Transition Partnership reshape capital allocation between end-of-pipe treatment and process-integrated pollution prevention.
Market Dynamics
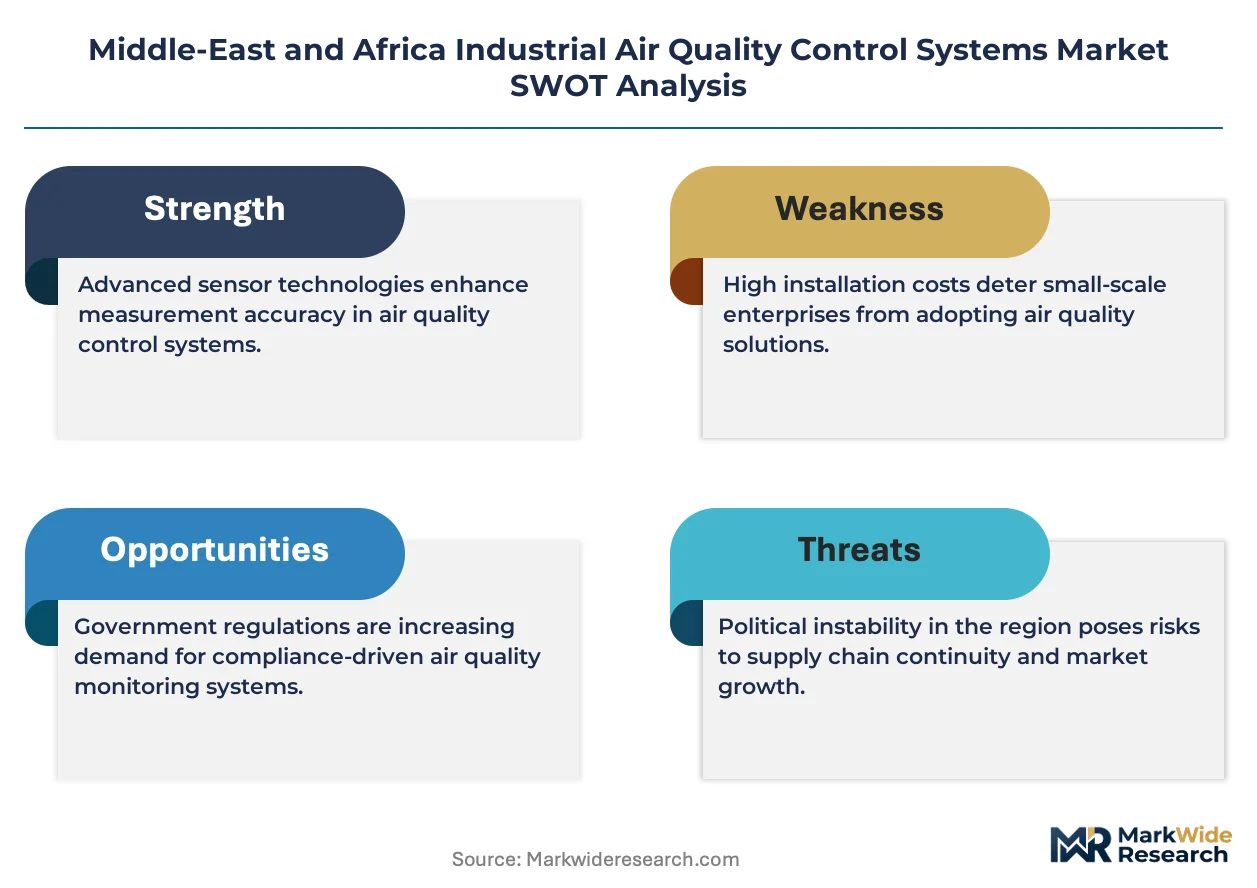
Tightening emissions enforcement across Gulf petrochemical corridors and South African mining belts is compressing equipment replacement cycles while elevating aftermarket service intensity.
Growth Catalysts
- SFDA Industrial Emissions Standards:Saudi Arabia's environmental regulator mandates continuous monitoring for sulfur oxides and particulate matter, forcing cement and steel facilities to retrofit electrostatic precipitators with integrated gas analyzer arrays.
- Petrochemical capacity expansion:Gulf Cooperation Council states are commissioning integrated refining-chemical complexes that require multi-stage scrubber trains and regenerative thermal oxidizers as standard process equipment.
- Johannesburg mining cluster:Dust suppression system deployments are accelerating around South Africa's platinum and gold extraction operations as occupational exposure limits tighten.
Market Restraints
- Stainless steel input volatility:Scrubber vessel fabrication depends on nickel-chromium alloy pricing, which fluctuates with Indonesian ore export policies and LME inventory cycles.
- Specialized contractor concentration:Installation and commissioning expertise for high-temperature flue gas treatment concentrates among engineering firms with Gulf project track records, creating bottleneck risk during peak construction windows.
- Legacy baghouse compatibility:Existing pulse-jet filtration infrastructure in North African cement plants cannot accommodate HEPA-grade media without structural reinforcement, delaying upgrade timelines.
Strategic Opportunities
- UAE carbon neutrality pathway:Abu Dhabi and Dubai industrial free zones offer accelerated permitting for facilities deploying heat-recovery-integrated scrubbers, creating first-mover positioning for technology providers.
- Pharmaceutical cleanroom filtration:Vaccine manufacturing investments in Saudi Arabia and Egypt require ISO 14644-1 compliant HEPA and ULPA installations with real-time particle monitoring.
- Remote diagnostics convergence:Cloud-connected gas analyzers combined with predictive maintenance algorithms enable service revenue models that displace traditional break-fix contracts.
Industry Challenges
- Certification timeline compression:South Africa's Department of Forestry, Fisheries and the Environment has shortened equipment type-approval windows for continuous emissions monitoring systems, straining testing laboratory capacity.
- Retrofit integration complexity:Brownfield petrochemical facilities must synchronize scrubber upgrades with scheduled turnaround windows, requiring modular skid-mounted designs that minimize process downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Industrial Air Quality Control Systems Market |
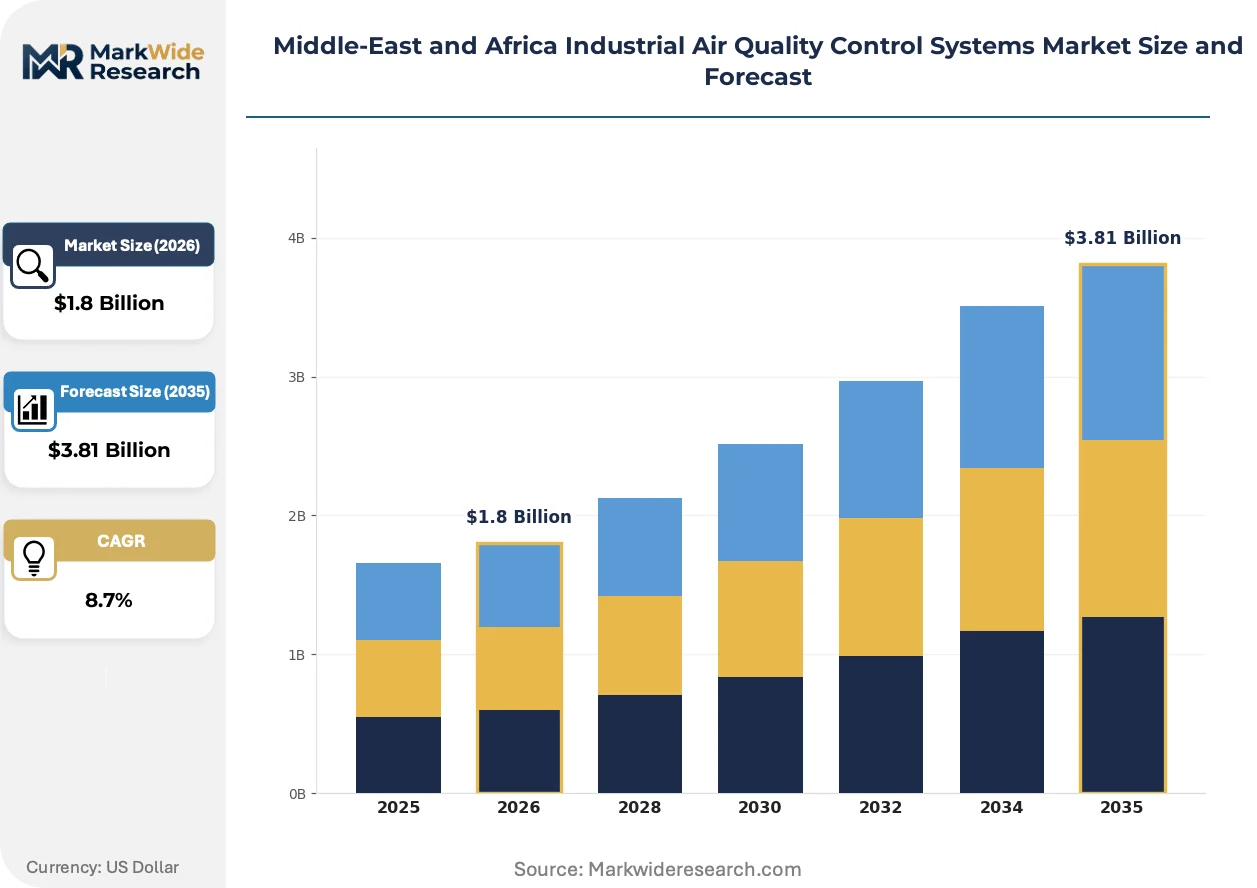
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filtration Systems, Monitoring Devices, Control Units, Purification Equipment Technology: Electrostatic Precipitators, Activated Carbon, HEPA Filters, Gas Analyzers Application: Manufacturing Facilities, Mining Operations, Chemical Processing, Power Plants End User: Aerospace, Pharmaceuticals, Food & Beverage, Construction |
| Companies Covered | Pure Air Solutions, Redecam Group SpA, Alfa Laval AB, Dürr AG, Donaldson Company Inc, Aircure, The ERG Group, FLSmidth & Co A/S, CFW Environmental, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Industrial Air Quality Control Systems Market Shifts & Advancements
Wet scrubber architectures are yielding to dry sorbent injection systems in specific temperature regimes, while real-time emissions data becomes a contractual currency between industrial operators and regulators.
Membrane filtration technology is migrating from ambient-temperature process water applications into high-temperature flue gas polishing roles. Saudi Aramco downstream affiliates are piloting ceramic membrane modules for particulate capture upstream of selective catalytic reduction units. This technology is migrating from water treatment into air quality applications, compressing the traditional wet scrubber market in sulfur recovery contexts.
South Africa's carbon tax regime, administered by the National Treasury, imposes direct levies on stationary combustion emissions above verified thresholds. Mining and metals processors face stepped liability calculations that favor continuous monitoring investments over periodic stack testing. The Johannesburg-Pretoria industrial corridor exhibits the most aggressive compliance technology procurement as facilities restructure fuel mixes and install verification-grade analyzer networks.
Service unbundling is fragmenting traditional equipment-supply contracts into separate hardware, installation, and multi-year maintenance components. Cement producers in Egypt and Morocco now solicit standalone aftermarket proposals from third-party specialists rather than accepting bundled OEM service terms. This pattern is most pronounced in markets where local technical labor pools support independent maintenance operations.
Middle-East and Africa Industrial Air Quality Control Systems Market Segmentation
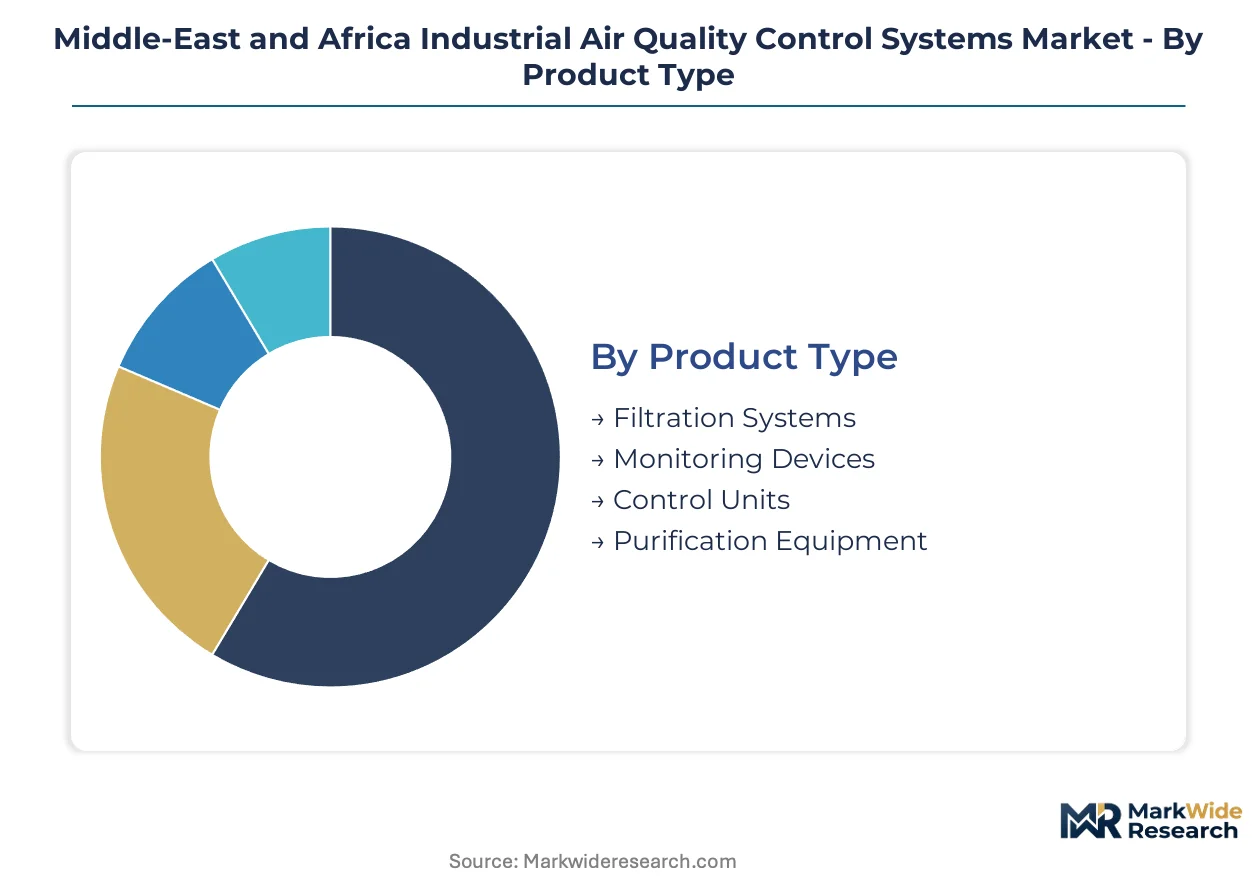
Equipment heterogeneity across the Middle-East and Africa Industrial Air Quality Control Systems landscape demands granular segmentation. Procurement patterns diverge sharply between heavy process industries requiring continuous emissions monitoring and discrete manufacturing seeking modular filtration upgrades.
Product Type:
Cost tier stratification separates capital-intensive scrubber systems from consumable media and instrumentation packages.
- Filtration Systems:Baghouse collectors and cartridge filters capture particulate loads in cement kiln exhaust and mining ventilation networks. Johannesburg platinum belt operations drive replacement cycles for high-temperature filter media as occupational exposure limits tighten.
- Monitoring Devices:Continuous emissions monitoring systems integrate gas analyzers, opacity meters, and data acquisition hardware for regulatory reporting. SFDA mandates in Saudi Arabia and UAE Ministry of Climate Change permitting requirements force real-time stack monitoring across petrochemical corridors.
- Control Units:Programmable logic controllers and distributed control systems automate damper positioning and scrubber liquid flow rates.
- Purification Equipment:Regenerative thermal oxidizers and catalytic converters destroy volatile organic compounds in coating and solvent recovery operations.
Filtration Systems command the established base. The steepest expansion runs through Monitoring Devices.
Technology:
Application temperature regimes and pollutant chemistry determine technology selection across Gulf refining and South African mining clusters.
- Electrostatic Precipitators:High-voltage ionization fields remove fine particulate from high-volume flue gas streams above 150°C. Saudi cement and power generation facilities deploy these for sulfur-laden exhaust handling where baghouse media would degrade.
- Gas Analyzers:Fourier-transform infrared and chemiluminescence detectors measure SOx, NOx, and CO concentrations for regulatory compliance. South Africa's carbon tax administration and stepped liability calculations favor verification-grade analyzer networks in the Johannesburg-Pretoria corridor.
- Activated Carbon:Adsorption beds capture mercury vapor and dioxin fractions in medical waste and hazardous material incineration.
- HEPA Filters:High-efficiency particulate air media achieve 99.97% retention at 0.3 microns for pharmaceutical cleanrooms and food processing environments.
Electrostatic Precipitators anchor heavy industrial deployment. Gas Analyzers are climbing the fastest as mandatory monitoring spreads.
Application:
Volume concentration and emissions intensity shape procurement specifications across extraction and processing verticals.
- Power Plants:Coal and natural gas combustion generates massive flue gas volumes requiring multi-stage treatment trains. Egyptian and Moroccan facilities retrofit electrostatic precipitators and wet scrubbers to meet tightened particulate and sulfur oxide thresholds.
- Chemical Processing:Petrochemical crackers and aromatics units emit complex organic and acid gas mixtures. Gulf Cooperation Council integrated refining-chemical complexes mandate regenerative thermal oxidizers and acid gas scrubbers as standard process equipment.
- Manufacturing Facilities:Metal fabrication and automotive painting operations deploy localized extraction and thermal oxidation for solvent vapors.
- Mining Operations:Underground and open-pit extraction sites suppress respirable silica and diesel particulate through ventilation and filtration systems.
Power Plants retain the largest installed base. Chemical Processing shows the steepest trajectory as Gulf capacity expands.
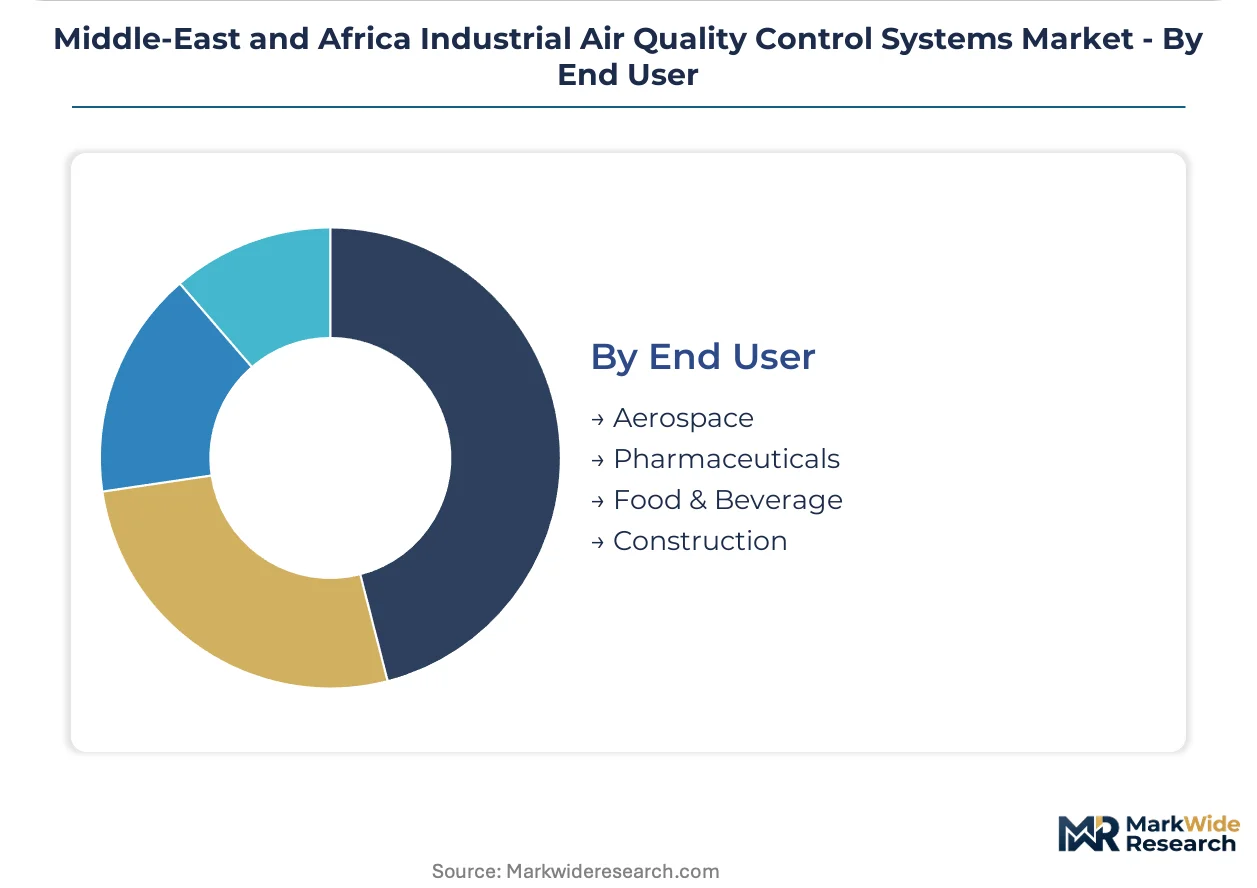
End User:
Customer type differentiation separates regulated heavy industry from quality-critical cleanroom environments.
- Pharmaceuticals:Vaccine manufacturing and sterile formulation require ISO 14644-1 compliant cleanrooms with HEPA and ULPA filtration plus real-time particle monitoring. Saudi Arabia and Egypt investments in biological production capacity drive demand for validated filtration systems.
- Food & Beverage:Dairy powder drying and edible oil processing control microbial and cross-contamination risks through hygienic air handling.
- Aerospace:Composite manufacturing and surface treatment facilities manage volatile organic compound emissions from resin systems and solvent degreasing.
- Construction:Cement batching and asphalt production sites deploy dust suppression for regulatory compliance and community relations.
Pharmaceuticals concentrate premium specification demand. Food & Beverage is expanding most quickly as Gulf processing investments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Middle-East and Africa diverge sharply: Gulf states deploy multi-stage scrubber trains for petrochemical compliance, while South African mining belts prioritize dust suppression and occupational exposure controls.
Saudi Arabia
Petrochemical capacity expansion along the Gulf coast drives demand for regenerative thermal oxidizers and acid gas scrubbers. The General Authority for Meteorology and Environmental Protection mandates continuous emissions monitoring for sulfur oxides, forcing cement and steel retrofits. The Jubail industrial city cluster anchors scrubber deployments for integrated refining-chemical complexes.
United Arab Emirates
Abu Dhabi and Dubai industrial free zones accelerate permitting for heat-recovery-integrated scrubber installations. The Ministry of Climate Change and Environment requires continuous emissions monitoring systems for major pollutant categories across petrochemical corridors. The Ruwais refining complex exemplifies multi-stage treatment train deployment.
South Africa
Platinum and gold extraction operations around Johannesburg drive dust suppression system procurement as occupational exposure limits tighten. The Department of Forestry, Fisheries and the Environment enforces stepped carbon tax liability calculations favoring verification-grade analyzer networks. The Johannesburg-Pretoria industrial corridor concentrates compliance technology procurement.
Egypt
Cement kiln exhaust treatment retrofits dominate equipment demand as particulate and sulfur oxide thresholds tighten. The national environmental regulator shapes procurement specifications for electrostatic precipitator upgrades. The Suez Canal Economic Zone attracts filtration system investments for new industrial capacity.
Morocco
Cement plant baghouse infrastructure faces HEPA-grade upgrade delays due to structural reinforcement requirements. National industrial emissions standards force pulse-jet filtration retrofits across North African facilities. The Casablanca-Settat region concentrates cement production and associated air quality control demand.
Middle-East and Africa Industrial Air Quality Control Systems Market Competitive Landscape
Capability concentration sits with European engineering specialists; scale advantage sits with diversified industrial conglomerates. The vendor base separates into three tiers: integrated technology providers owning full scrubber-to-analyzer portfolios, regional fabricators capturing installation and commissioning contracts, and aftermarket service specialists unbundling maintenance from hardware supply. Dominant competitive moves include modular skid-mounted system design for brownfield retrofit synchronization and predictive maintenance algorithm development for recurring revenue capture.
Among European-based engineering groups, Dürr AG and Alfa Laval AB exemplify the integrated technology tier, while Donaldson Company Inc represents the filtration-focused specialist archetype. These anchors illustrate divergent strategic positioning: full-system capability versus component depth. Regional procurement patterns favor vendors with established Gulf project track records for high-temperature flue gas treatment, creating concentration risk during peak construction windows. Service unbundling trends fragment traditional equipment-supply contracts, opening positioning for independent maintenance operators in markets with sufficient technical labor pools.
| Leading Market Players |
|---|
| Pure Air Solutions |
| Redecam Group SpA |
| Alfa Laval AB |
| Dürr AG |
| Donaldson Company Inc |
| Aircure |
| The ERG Group |
| FLSmidth & Co A/S |
| CFW Environmental |
| Others |
Supply & Pricing Matrix
Jubail Industrial City's fabrication capacity for nickel-chromium alloy scrubber vessels shapes downstream pricing power across Gulf petrochemical corridors. Concentration of specialized welding and pressure-vessel certification expertise in this Saudi Arabian cluster creates asymmetric leverage when project timelines compress.
Pricing Analysis
Long-term service contracts with multi-year maintenance attachments dominate equipment procurement, displacing pure hardware transactions. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated systems from regional fabricator builds and refurbished legacy units. Cost compression in the economy tier intensifies because Egyptian and Moroccan cement producers now unbundle aftermarket services to independent specialists. Mining operators in South Africa's platinum belt exhibit highest price sensitivity due to carbon tax liability pressures, while pharmaceutical cleanroom projects in Saudi Arabia and the UAE show lowest sensitivity given validation requirements.
Supply Chain Analysis
Tariff exposure between Indonesia and Gulf fabrication hubs dominates raw material cost volatility for stainless steel alloy inputs. Scrubber vessel production draws from Germany, South Korea, and domestic Saudi facilities for specialized pressure equipment. Nickel-chromium alloy pricing hinges on Indonesian ore export policy fluctuations and LME inventory cycles. Single-source vulnerability concentrates in high-temperature ceramic membrane modules piloted by Saudi Aramco affiliates. Distribution runs through EPC contractors with established Gulf project track records, creating bottleneck risk during peak construction windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue layers expand faster than hardware sales as predictive maintenance algorithms and remote diagnostics displace traditional break-fix contracts. Cloud-connected gas analyzer networks generate recurring revenue streams that reshape margin distribution.
For Market Incumbents: Entrench service attach rates by embedding predictive maintenance algorithms into gas analyzer deployments, capturing recurring revenue from cement and steel producers. Expand regional certification capacity for continuous emissions monitoring systems ahead of South Africa's compressed type-approval timelines. Counter independent maintenance specialists through proprietary spare parts ecosystems and remote diagnostics platforms that reduce client switching.
For New Entrants and Emerging Players: Build out modular skid-mounted scrubber designs targeting brownfield petrochemical retrofit windows in the Jubail and Ruwais corridors, where turnaround synchronization creates procurement urgency. Pharmaceutical cleanroom filtration in Saudi Arabia and Egypt offers the most penetrable segment given vaccine manufacturing investments and ISO 14644-1 validation requirements. Establish partnerships with regional engineering firms possessing Gulf project track records for installation and commissioning credibility.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aftermarket service specialists with predictive maintenance platforms over pure hardware fabricators. The five-to-ten year viability window rewards vendors with recurring revenue models and regulatory compliance data assets. Acquisition targets should demonstrate installed base density in mining-intensive economies or petrochemical corridors. Monitor South Africa's carbon tax administration enforcement intensity as inflection indicator for continuous monitoring system procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Cloud-connected gas analyzers enable recurring revenue capture from SFDA-mandated monitoring systems. |
| Modular Skid-Mounted System Design | Brownfield petrochemical retrofits in Jubail and Ruwais require minimized process downtime during turnaround windows. |
| Regional Certification Capacity Expansion | South Africa's shortened equipment type-approval windows strain testing laboratory capacity and create first-mover advantage. |
| Heat-Recovery-Integrated Scrubber Deployment | UAE industrial free zones offer accelerated permitting for facilities with energy-efficient multi-stage treatment trains. |
| Independent Aftermarket Service Unbundling | Egyptian and Moroccan cement producers now solicit standalone maintenance proposals separate from OEM hardware contracts. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, EPC procurement leads, and aftermarket service heads anchored the qualitative base. Primary interviews across these stakeholder categories combined with secondary validation from customs and trade data, SEC filings of listed engineering groups, and national environmental regulator enforcement disclosures. Bottom-up equipment deployment tracking and top-down industrial capacity expansion analysis provided triangulation across the Middle-East and Africa region.
Scenario-bracketing around regulatory enforcement intensity, nickel alloy price volatility, and petrochemical construction cycle timing shaped the analytical framework. Segmentation dimensions modeled include product type, technology category, application vertical, and end-user industry across the projection horizon. CAGRs derived from equipment replacement cycle compression rates and aftermarket service penetration curves. Industry-specific inputs incorporated SFDA mandate implementation timelines and South African carbon tax liability calculations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology-integrated challengers or state-backed fabrication capacity would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Indoor Air Purification Market
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
Environment Controllers Market
Air Quality Control Systems
Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Sustainable Air Filter Market
Air Quality Control Systems
Air Quality Control Systems Market
Air Quality Control Systems
Asia-Pacific Air Quality Control System Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
Air Quality Monitoring Software Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Air Pollution Control Systems Market
Air Quality Control Systems
Emission Management Software Market
Air Quality Control Systems
Desiccant Air Breather Market
Air Quality Control Systems
UV Air Purifiers Market
Air Quality Control Systems
Ozone Generation Market
Air Quality Control Systems
Anti-Pollution Mask Market