
 Global Vertical Sewage Pumps Market | 2026-2036
Global Vertical Sewage Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vertical Sewage Pumps Market Outlook
Predictive maintenance subscriptions is decoupling pump hardware from recurring revenue streams, forcing OEMs to restructure go-to-market economics. Grundfos leverages its digital service platform to lock in long-term municipal contracts. KSB SE & Co. KGaA anchors its position through captive foundry capacity for high-chrome impellers. Xylem Inc. differentiates via embedded sensor arrays that feed cloud-based degradation models.
Vertical sewage pumps are centrifugal or positive-displacement units configured with elongated drive shafts to immerse the hydraulic end below fluid level while keeping motors dry, typically handling solids up to 80 mm and heads exceeding 100 meters for raw sewage lift stations. Their primary purpose is reliable elevation of untreated wastewater against gravity in constrained urban infrastructure footprints. Submersible designs dominate municipal procurement due to flood-proof sealing and reduced station footprint, while grinder configurations command premium positioning in industrial pretreatment applications where fibrous waste abounds. Non-submersible architectures retain share in temporary installations for disaster-response and construction dewatering where rapid redeployment matters more than energy efficiency.
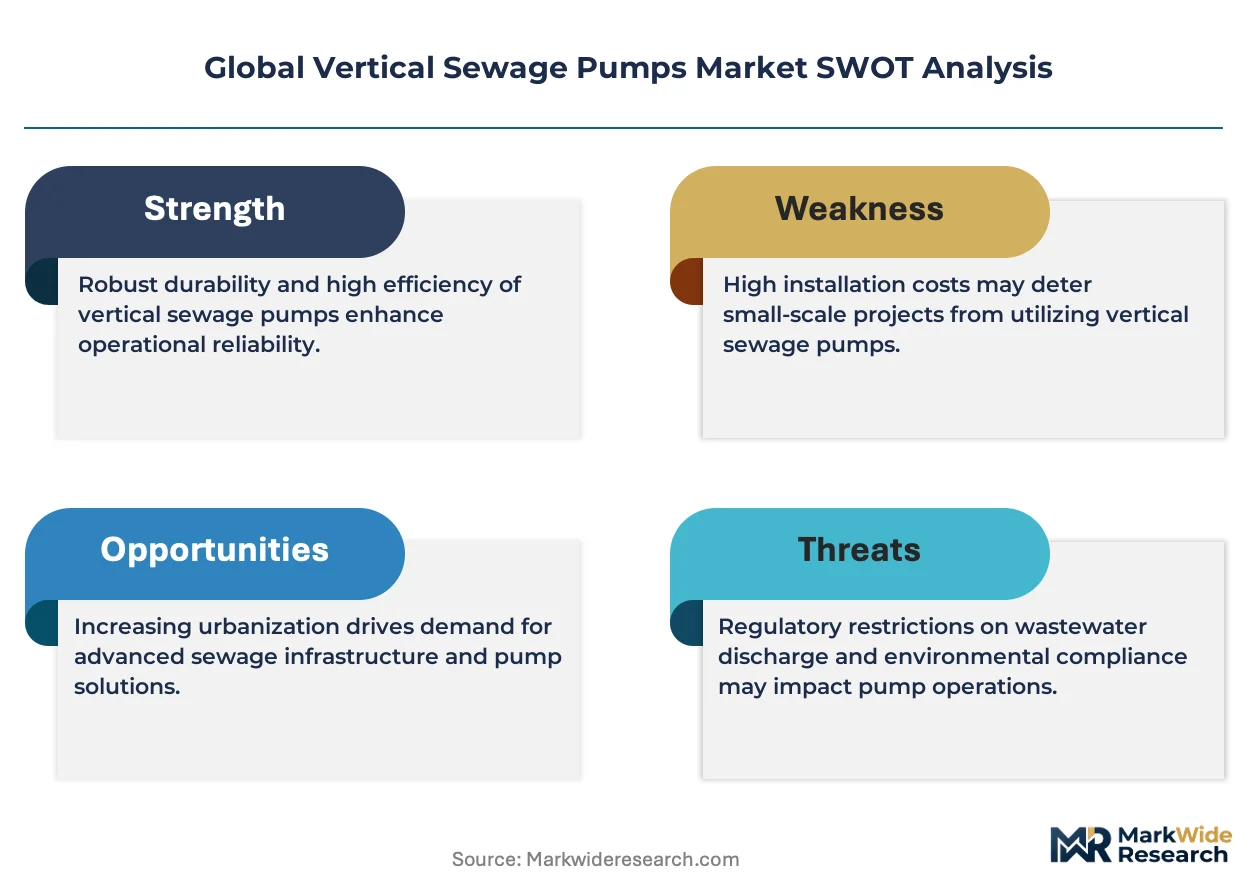
EPA effluent guidelines under the Clean Water Act, EU Urban Wastewater Treatment Directive enforcement by the European Commission, and China's MEE discharge standards for municipal pollutants collectively tighten allowable particulate loads and energy intensity benchmarks. These frameworks compel pump upgrades toward higher-efficiency hydraulics and variable-frequency drive integration. Stakeholders must weigh capex recovery timelines against accelerating regulatory compliance deadlines and carbon-border adjustment exposure on imported cast components.
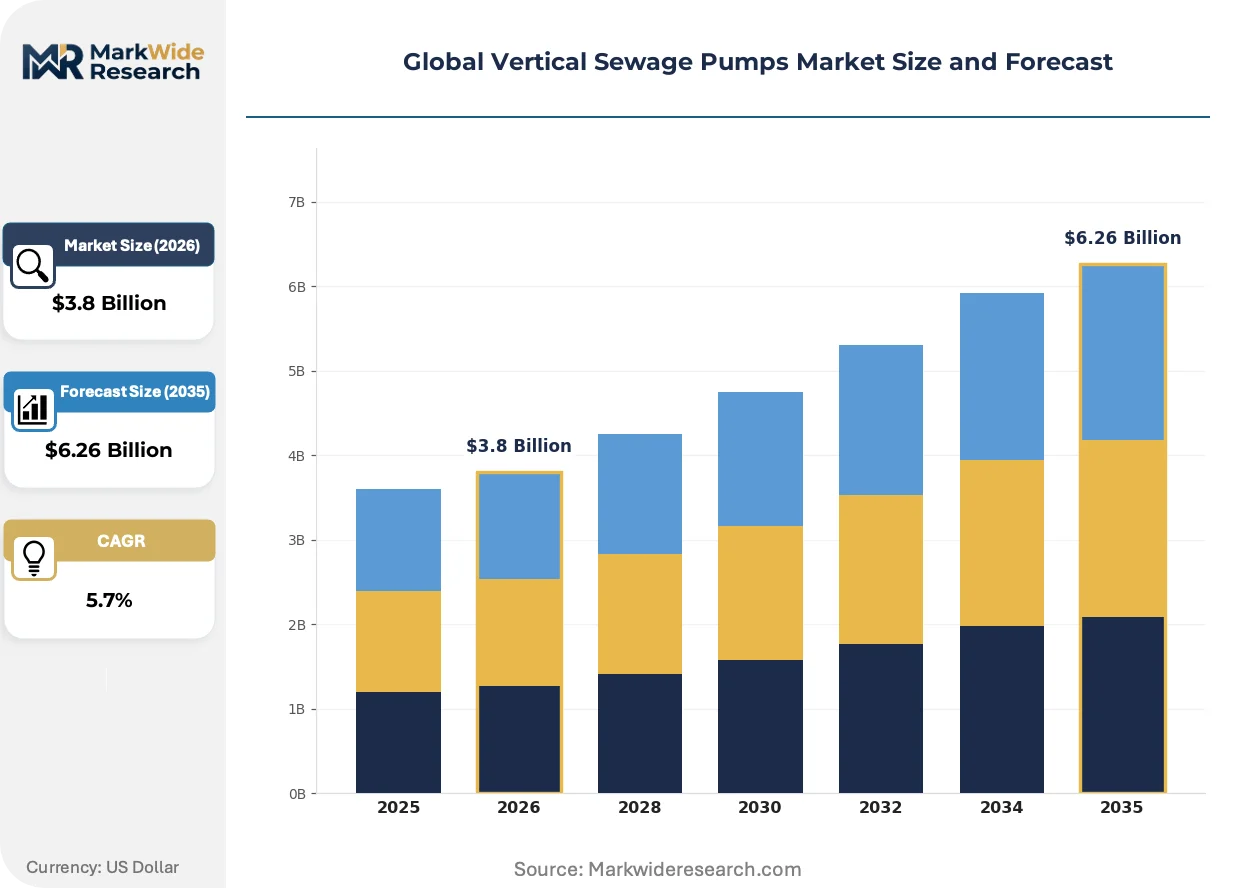
Market Dynamics
Submersible motor sealing technology and EU Urban Wastewater Treatment Directive enforcement are compressing replacement cycles while elevating specification thresholds for municipal procurement teams.
Growth Catalysts
- EU Urban Wastewater Treatment Directive revisions:Germany's municipal utilities face mandatory nutrient removal upgrades, triggering bulk tender releases for high-head submersible units with integrated variable-frequency drives.
- Yangtze River Delta combined sewer overflow programs:Shanghai and Nanjing retrofit timelines are accelerating lift station densification, concentrating demand for compact vertical configurations with 80 mm solids passage.
- Stainless steel impeller casting:Foundry capacity expansion for duplex grades is reducing lead times for corrosion-resistant hydraulics specified in coastal wastewater infrastructure.
Market Restraints
- High-chrome iron ore price volatility:Abrasion-resistant impeller alloys depend on concentrated South African and Kazakh ferrochrome supply, exposing OEM margins to commodity swings.
- Submersible seal manufacturing concentration:Mechanical face seal production clusters in Germany and Japan, creating single-source vulnerability for flood-proof motor protection systems.
- Temporary dewatering substitution:Construction and disaster-response segments favor rapid-deploy portable units over permanent vertical installations, capping efficiency-driven upgrade potential.
Strategic Opportunities
- India's AMRUT 2.0 urban mission:Sewer network expansion in 500 cities lacks established pump procurement protocols, opening specification-influence windows for efficiency-rated vertical designs.
- IoT sensor-to-cloud convergence:Embedded vibration and temperature monitoring fused with predictive algorithms enables subscription revenue models detached from hardware margins.
- Brazil's ANVISA industrial effluent enforcement:Food processing and pulp sectors face first-time pretreatment mandates, creating grinder pump demand in greenfield industrial parks.
Industry Challenges
- Foundry metallurgist scarcity:Duplex stainless casting expertise concentrates in aging workforce pools across Northern Italy and Lower Saxony, constraining quality output scaling.
- MEE discharge standard compliance timelines:China's municipal operators face compressed certification deadlines for ammonia and total nitrogen limits, forcing parallel pump and biological process upgrades.
- Legacy SCADA integration friction:Brownfield lift stations with 1990s control architectures require costly protocol bridging to accept digital pump diagnostics, delaying smart retrofit adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vertical Sewage Pumps Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible, Non-Submersible, Grinder, Diaphragm End User: Municipal, Industrial, Commercial, Residential Application: Wastewater Treatment, Stormwater Management, Process Water, Sewage Transport Installation Type: Fixed, Portable, Temporary, Permanent |
| Companies Covered | KSB SE & Co. KGaA, Wilo SE, Grundfos, Flowserve Corporation, Pentair plc, Xylem Inc., Ebara Corporation, ITT Inc., Sulzer Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vertical Sewage Pumps Market Strategic Shifts
Wet-end hydraulics, motor thermal management, and service delivery architectures are undergoing simultaneous reinvention as efficiency mandates and labor constraints rewrite procurement economics.
Permanent magnet synchronous motors paired with integrated variable-frequency drives are modularizing powertrain architecture for submersible sewage pumps. Dutch and Danish water authorities specify these packages for 15% energy reduction guarantees. The technology is modularizing supplier ecosystems, allowing motor specialists to displace traditional pump OEMs in electrical specification decisions.
REACH restrictions on hexavalent chromium surface treatments are eliminating traditional hard-chrome coating options for wear rings and shafts. Pump manufacturers pivot to tungsten carbide spray or ceramic plasma coatings for abrasion resistance. German KBA industrial equipment guidelines and Dutch drinking water sector procurement rules now explicitly favor chromium-free surface engineering, accelerating coating supplier consolidation.
Performance-based service agreements are displacing traditional break-fix maintenance in Scandinavian municipal markets. Copenhagen and Stockholm utilities now contract guaranteed availability levels rather than discrete repair events. Dutch waterboards pilot similar outcome structures, transferring operational risk to OEM service arms and compressing in-house technical staffing requirements.
Global Vertical Sewage Pumps Market Segmentation
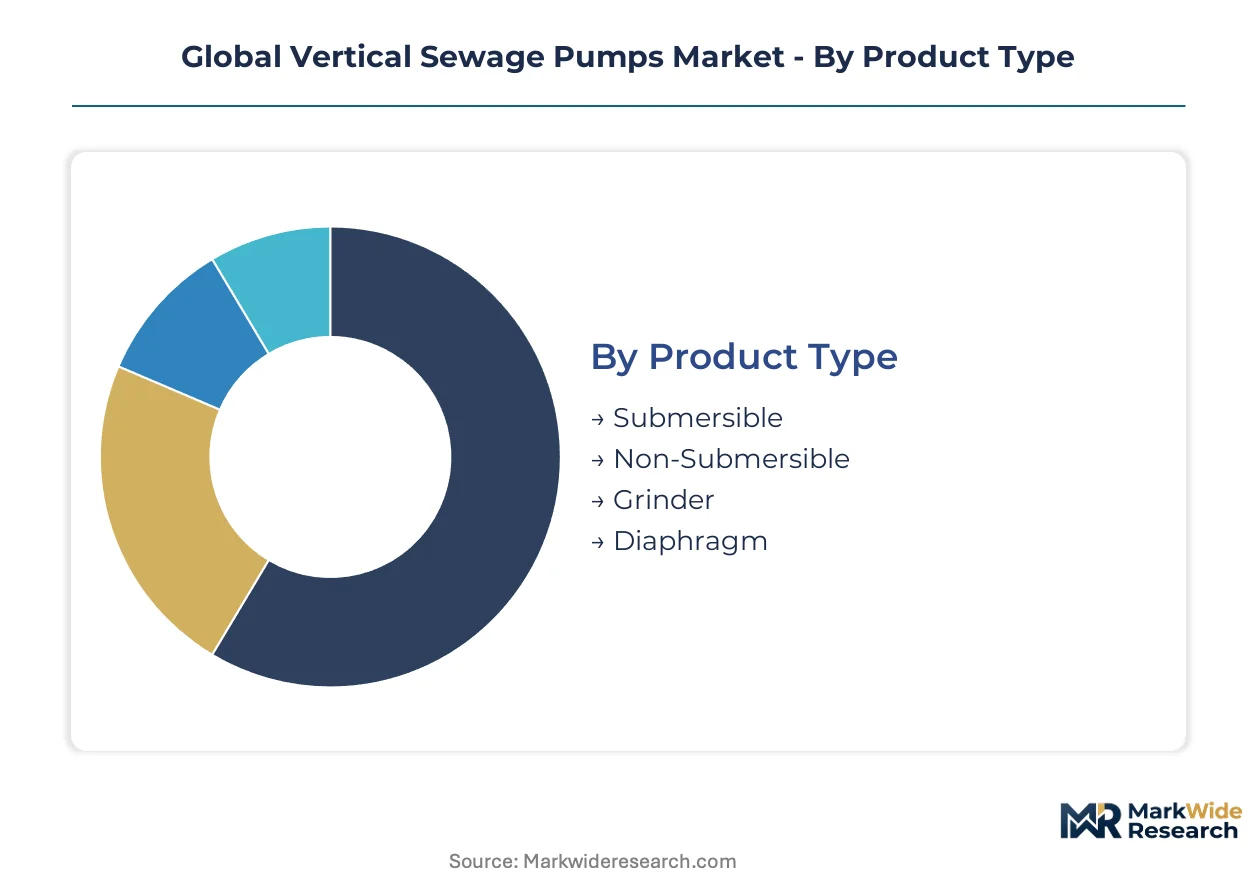
Procurement specifications for vertical sewage pumps diverge sharply across end-use contexts, with municipal utilities prioritizing lifecycle efficiency guarantees while industrial buyers emphasize solids-handling capacity and chemical compatibility.
Product Type:
Buyers differentiate primarily by flood-risk exposure and station footprint constraints rather than upfront capital outlay.
- Submersible:Motors operate fully immersed with double mechanical seal systems rated for continuous submersion at depths exceeding 20 meters. German municipal utilities under EU Urban Wastewater Treatment Directive enforcement specify these for nutrient removal retrofits requiring minimal civil works.
- Grinder:Integrate macerating mechanisms upstream of impeller stages to reduce fibrous solids to sub-5mm particles. Demand clusters in Brazil's food processing and pulp sectors facing ANVISA industrial effluent mandates for first-time pretreatment compliance.
- Non-Submersible:Extended drive shafts maintain dry motor positioning above fluid level for temporary installations.
- Diaphragm:Positive-displacement action handles viscous sludge with high solids concentration in small-scale residential and commercial lift stations.
Volume sits with Submersible configurations; growth tilts toward Grinder designs as industrial pretreatment regulations expand.
End User:
Contracting authority sophistication determines specification complexity and service attachment rates.
- Municipal:Public wastewater utilities operate under regulatory compliance deadlines with 15-25 year asset replacement cycles. China's Yangtze River Delta megacity cluster accelerates combined sewer overflow retrofits, concentrating tender releases for high-head units with integrated variable-frequency drives.
- Industrial:Private operators prioritize uptime guarantees and chemical resistance for process-integrated effluent handling. Scandinavian pulp and paper producers adopt performance-based service agreements transferring operational risk to OEM service arms.
- Commercial:Shopping centers and hospitality complexes specify compact submersible packages for basement-level sewage elevation.
- Residential:Individual property owners select cost-optimized grinder pumps for remote connections to municipal gravity mains.
Municipal procurement dominates absolute unit volume; Industrial segments show steepest expansion trajectory as effluent enforcement tightens.
Application:
Fluid characteristics and peak flow variability shape hydraulic design priorities across use cases.
- Wastewater Treatment:Raw sewage lift stations require 80mm solids passage and abrasion-resistant impeller alloys. India's AMRUT 2.0 urban mission in 500 cities lacks established procurement protocols, opening specification-influence windows for efficiency-rated designs.
- Stormwater Management:Intermittent high-volume, low-solids events demand rapid-start capabilities and debris-resistant intakes. Shanghai's combined sewer overflow retrofit programs accelerate lift station densification for flash flood mitigation.
- Process Water:Industrial circulation systems prioritize corrosion resistance and precise flow control.
- Sewage Transport:Long-distance force mains emphasize energy efficiency and pressure stability over solids-handling extremes.
Wastewater Treatment anchors current installed base; Stormwater Management climbs fastest as climate adaptation infrastructure scales.
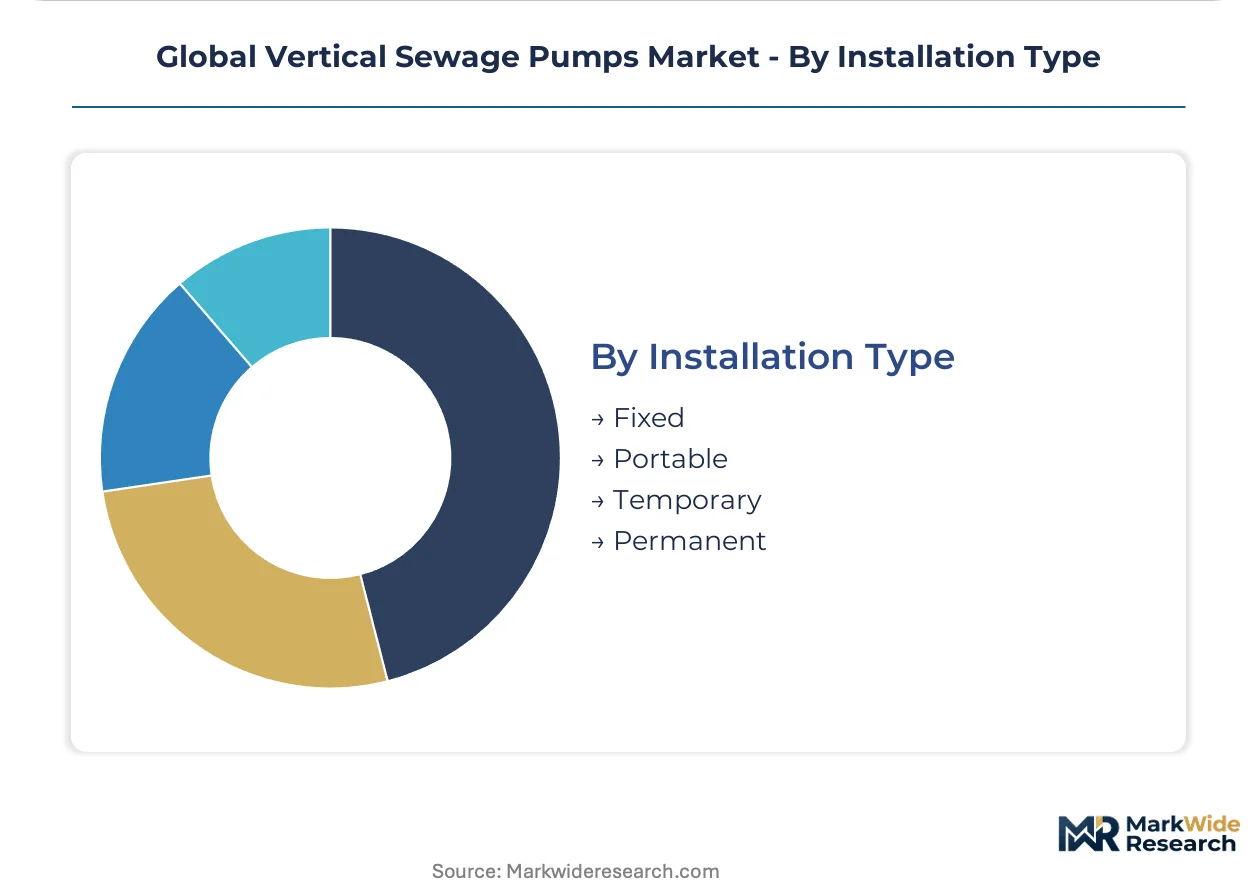
Installation Type:
Asset mobility requirements and project duration dictate capital recovery calculations and maintenance responsibility allocation.
- Fixed:Permanent concrete wet-well installations with dedicated electrical infrastructure serve core municipal networks. Dutch water authorities specify permanent magnet synchronous motor packages for guaranteed energy reduction commitments.
- Portable:Skid-mounted or trailer-deployed units enable rapid response to infrastructure failures and seasonal demand spikes. Disaster-response agencies in flood-prone regions maintain standby fleets for emergency dewatering operations.
- Temporary:Construction site dewatering favors rapid-deploy units over permanent vertical installations where project timelines under five years preclude efficiency-driven upgrade economics.
- Permanent:Engineered station designs with 30-year structural lifespans integrate predictive maintenance sensor arrays and cloud-based degradation monitoring.
Fixed installations command revenue concentration; Portable configurations expand most quickly as climate resilience procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German foundries and Japanese seal manufacturers concentrate critical component supply, while municipal procurement clusters in China's coastal megacities and India's emerging urban corridors absorb volume. This production-consumption divide shapes lead times and specification influence across the value chain.
Germany
Frankfurt am Main utilities tender for nutrient removal retrofits under EU Urban Wastewater Treatment Directive enforcement. KBA industrial equipment guidelines now mandate chromium-free surface engineering for wear components. Lower Saxony foundries expand duplex stainless casting capacity to shorten lead times for corrosion-resistant impellers.
China
Shanghai and Nanjing accelerate combined sewer overflow retrofit programs, concentrating demand for compact vertical configurations with 80 mm solids passage. MEE discharge standards impose compressed certification deadlines for ammonia and total nitrogen limits. Yangtze River Delta megacity clusters drive lift station densification for flash flood mitigation.
United States
EPA effluent guidelines under the Clean Water Act tighten allowable particulate loads for municipal wastewater utilities. Chicago and Houston metropolitan utilities specify permanent magnet synchronous motor packages for energy reduction commitments. Southeast coastal cities prioritize stainless steel hydraulics for saltwater intrusion resilience.
India
AMRUT 2.0 urban mission targets sewer network expansion across 500 cities lacking established pump procurement protocols. Central Electricity Authority efficiency ratings influence specification windows for variable-frequency drive integration. Maharashtra and Gujarat municipal corporations release bulk tenders for high-head submersible units.
Brazil
ANVISA industrial effluent enforcement creates first-time pretreatment mandates for food processing and pulp sectors. São Paulo and Rio de Janeiro industrial parks specify grinder pumps for fibrous waste maceration. Greenfield manufacturing zones in Minas Gerais adopt performance-based service agreements for operational risk transfer.
Global Vertical Sewage Pumps Market Competitive Environment
Top-tier vendors anchor municipal specification influence through digital service platforms, while mid-scale specialists compete on foundry proximity and coating technology. European and Japanese incumbents control mechanical seal supply chains through concentrated manufacturing footprints. Strategic archetypes include integrated pump-and-service providers, captive foundry operators, and sensor-embedded system architects. Competitive moves center on predictive maintenance subscription models and backward integration into high-chrome impeller alloys.
Among German-based industrial groups, KSB SE & Co. KGaA and Wilo SE exemplify the captive manufacturing archetype through in-house foundry and motor production capabilities. Grundfos anchors the digital service tier with cloud-connected degradation monitoring platforms. These three entities represent contrasting approaches to decoupling recurring revenue from hardware margins across European and Asian municipal procurement channels.
| Leading Market Players |
|---|
| KSB SE & Co. KGaA |
| Wilo SE |
| Grundfos |
| Flowserve Corporation |
| Pentair plc |
| Xylem Inc. |
| Ebara Corporation |
| ITT Inc. |
| Sulzer Ltd. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between EU Urban Wastewater Treatment Directive-compliant submersible units and temporary dewatering configurations manifests in both procurement premiums and foundry allocation priorities. German municipal utilities pay substantial uplifts for KBA-compliant chromium-free surface engineering while construction contractors source portable non-submersible architectures through spot-market channels with minimal specification overhead.
Pricing Analysis
Margin tightening in standard-grade submersible configurations reflects ferrochrome ore volatility from South African and Kazakh supply corridors. Three-tier pricing structure across premium, standard, and economy levels tracks impeller alloy grades and seal redundancy specifications. Municipal utilities in the Yangtze River Delta show lowest price sensitivity due to compliance-driven replacement urgency, while Indian AMRUT 2.0 contractors negotiate aggressively on upfront capital outlay.
Supply Chain Analysis
Dual-sourcing requirements for mechanical face seals now mandate qualified suppliers in both Germany and Japan after flood-related production disruptions. Duplex stainless casting concentrates in Northern Italy and Lower Saxony, while high-chrome iron ore draws from concentrated Southern African deposits. Single-source vulnerability for submersible motor protection systems creates tariff exposure on precision-machined seal faces. Distribution runs through OEM-direct municipal contracts and specialized wastewater equipment distributors serving industrial retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet synchronous motor technology is displacing conventional induction architectures across Dutch and Danish water authority specifications, compressing incumbent pump OEM margins while opening specification influence windows for electrical specialists.
For Market Incumbents: Extend predictive maintenance subscription attach rates to lock in municipal contract renewals ahead of grinder pump specialists entering Brazil's ANVISA enforcement markets. Deepen captive foundry capacity for duplex stainless impellers to offset metallurgist scarcity in Northern Italy. Reinforce specification influence through embedded sensor arrays that feed cloud-based degradation models, countering modular motor suppliers displacing traditional hydraulics decisions. For New Entrants and Emerging Players: IoT-enabled vibration monitoring fused with predictive algorithms offers specification entry into India's AMRUT 2.0 cities lacking established procurement protocols. Target grinder pump demand in Brazil's food processing and pulp sectors facing first-time ANVISA pretreatment mandates. Lead with performance-based service agreements transferring operational risk to OEM service arms, mirroring Scandinavian municipal contracting evolution. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated pump-and-service providers with established municipal subscription revenue streams. Five-to-ten year viability hinges on backward integration into high-chrome impeller alloys and captive foundry capacity. Watch for consolidation signals when ferrochrome price volatility exceeds OEM hedging capacity, forcing distressed asset availability in precision casting segments.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Grundfos leverages digital service architecture to secure long-term municipal contracts with guaranteed availability commitments. |
| Captive Foundry Capacity Expansion | KSB SE anchors impeller supply security through in-house duplex stainless casting in Lower Saxony. |
| Sensor-Embedded System Architecture | Xylem differentiates via embedded arrays feeding cloud-based degradation models for subscription revenue. |
| Chromium-Free Surface Engineering Pivot | German KBA guidelines now mandate REACH-compliant coatings, accelerating tungsten carbide supplier consolidation. |
| Performance-Based Service Agreements | Copenhagen and Stockholm utilities now contract outcome structures transferring operational risk to OEM service arms. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with municipal wastewater utility procurement directors, industrial plant maintenance managers, OEM aftermarket service heads, and foundry operations specialists. EPA effluent guideline databases, EU Urban Wastewater Treatment Directive enforcement records, China's MEE discharge standard certifications, and Indian AMRUT 2.0 tender releases provided regulatory validation. Bottom-up unit shipment estimates triangulated against top-down infrastructure investment flows from national statistics bureaus.
Data-stream reconciliation across product type, end user, application, and installation type dimensions generated volume and value outputs over the projection horizon. CAGRs derived from regression analysis against municipal capital expenditure cycles and industrial effluent enforcement timelines. Forecast inputs incorporated permanent magnet motor adoption curves, ferrochrome price elasticity coefficients, and predictive maintenance subscription penetration rates.
Several conditions sit outside the modeled scope, including force majeure disruptions to South African ferrochrome supply, abrupt EU Urban Wastewater Treatment Directive deadline acceleration, and breakthrough solid-state pumping technologies. Deviation in China's MEE compliance certification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Sewage Treatment Service Market
Water and Wastewater Treatment
Commercial Atmospheric Water Generator Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Agricultural Wastewater Treatment Market
Water and Wastewater Treatment
Sewage Pump Market
Water and Wastewater Treatment
Backwash Pre-Filters Market
Water and Wastewater Treatment
Water Aeration System Market
Water and Wastewater Treatment
Global Biological Wastewater Treatment Market
Water and Wastewater Treatment
Latin America Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Wastewater Clarifier Market